
 Adenovirus Diagnostic Testing Market | 2026-2036
Adenovirus Diagnostic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Adenovirus Diagnostic Testing Market Outlook
Aftermarket assay service revenue is reshaping profitability models for diagnostic platforms. Abbott Laboratories leverages broad installed-base coverage across hospital core labs to sustain recurring consumable pull-through. Thermo Fisher Scientific anchors its position through integrated qPCR workflow systems that span extraction through analysis. BioMérieux competes on rapid turnaround time specifications for immunocompromised patient populations.
Adenovirus diagnostic testing encompasses molecular, serological, and culture-based methods for detecting human adenovirus nucleic acid, antigen, or antibodies in clinical specimens, with qPCR assays achieving analytical sensitivity thresholds of 10-100 copies per reaction for quantitative viral load monitoring. The primary commercial purpose centers on differentiating adenoviral respiratory, ocular, or gastrointestinal infections from clinically similar presentations caused by influenza, RSV, or SARS-CoV-2. PCR Tests command the dominant share of molecular confirmation workflows due to established reimbursement pathways and laboratory familiarity, while Rapid Antigen Tests occupy point-of-care settings where fifteen-minute turnaround overrides sensitivity limitations. Next-Generation Sequencing represents the fastest-expanding technology dimension as reference laboratories deploy pan-viral panels for untargeted outbreak investigation.
FDA oversight of in vitro diagnostic devices under 21 CFR Part 820 quality system regulations shapes premarket validation requirements for adenovirus assay developers, while the EU In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for CE-marked products entering European Economic Area markets. The Clinical Laboratory Improvement Amendments framework governs US laboratory-developed test complexity classifications, directly affecting where adenovirus testing can be performed. Stakeholders must monitor evolving FDA template guidance for multiplex respiratory panels to anticipate validation burden shifts that will determine competitive entry costs.
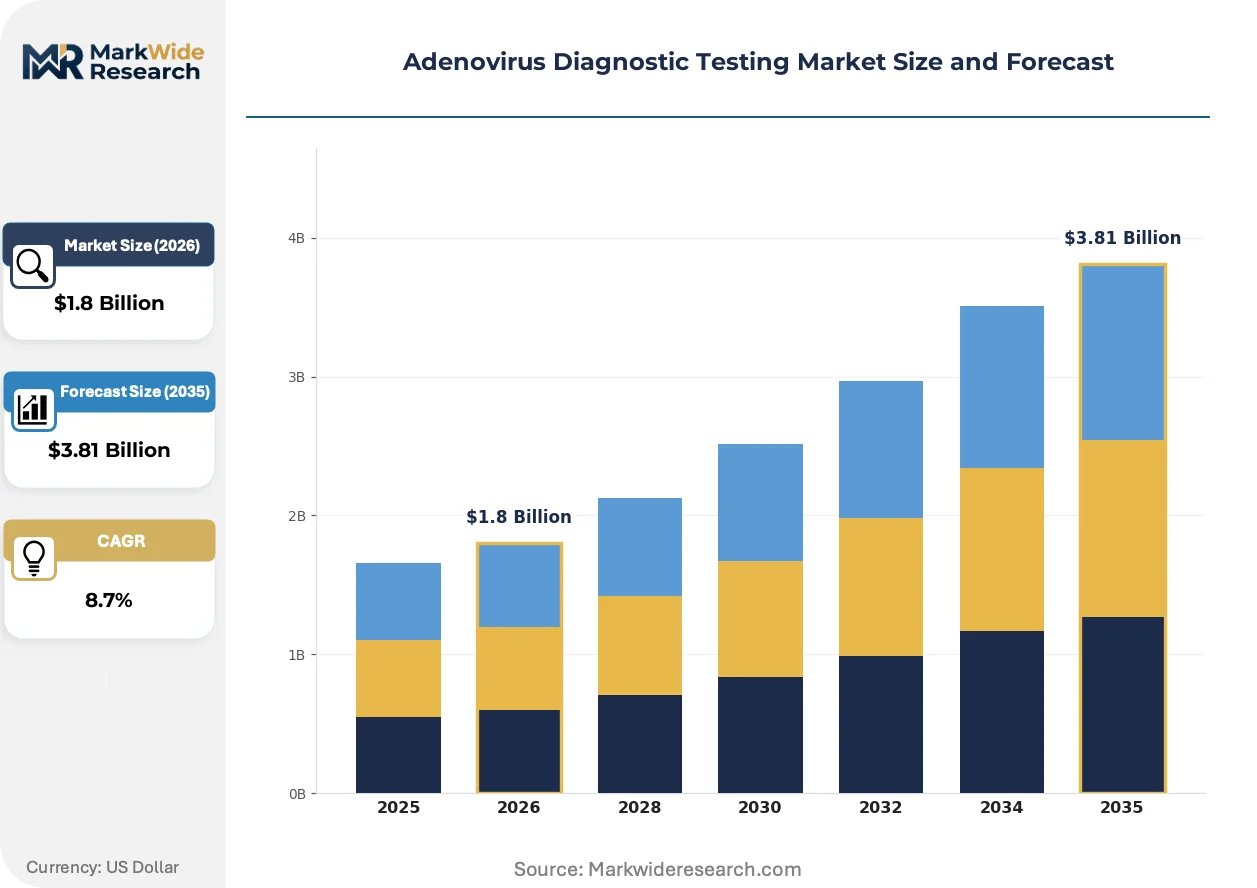
Market Dynamics
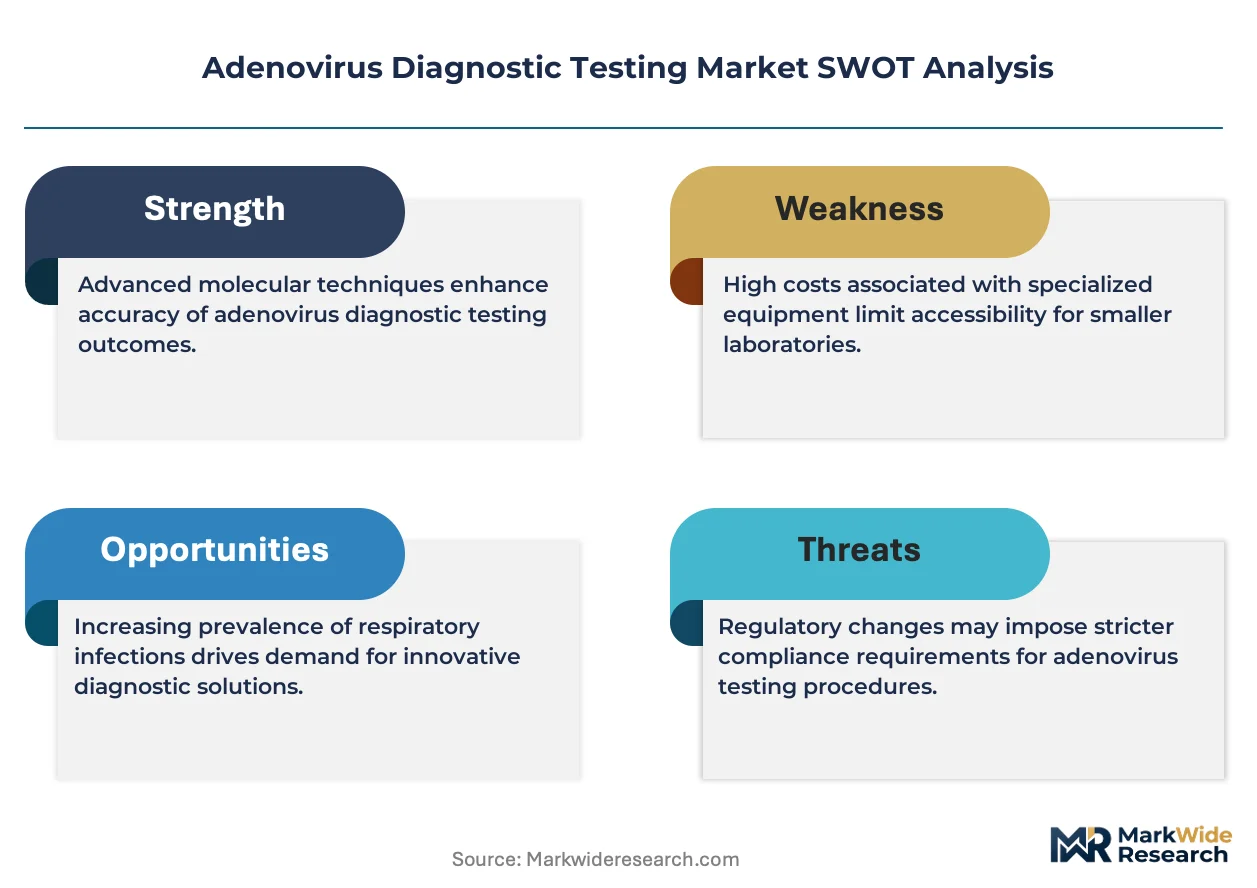
Multiplex respiratory panel complexity is forcing assay developers to recalibrate validation timelines against FDA's evolving template guidance, compressing competitive entry windows while expanding menu breadth requirements for hospital laboratory customers.
Growth Catalysts
- CLIA Complexity Waivers:The Clinical Laboratory Improvement Amendments framework enables moderate-complexity molecular testing in physician office laboratories, expanding point-of-care access beyond centralized reference sites.
- Immunocompromised Patient Surveillance:Hematology-oncology units require quantitative viral load monitoring for stem cell transplant recipients, creating dedicated demand for qPCR-based adenovirus quantification.
- Pan-Viral Outbreak Investigation:Next-Generation Sequencing deployment in public health laboratories enables untargeted pathogen discovery during unexplained respiratory clusters.
Market Restraints
- Extraction Reagent Volatility:Magnetic bead chemistry supply concentration in Chinese manufacturing creates input cost instability and batch-to-batch performance variation.
- Reimbursement Compression:Medicare's Clinical Laboratory Fee Schedule annual reductions constrain assay profitability, particularly for standalone adenovirus targets outside bundled respiratory panels.
- Antigen Test Sensitivity Floor:Rapid immunochromatographic methods exhibit analytical limits tenfold higher than molecular alternatives, restricting clinical utility to high-titer specimens.
Strategic Opportunities
- Home-Based Specimen Collection:Microsampling devices and dried matrix spots enable patient-collected nasopharyngeal specimens shipped to reference laboratories, bypassing clinic visit requirements.
- Digital PCR Differentiation:Absolute quantification without standard curves addresses precision medicine needs in pediatric transplant centers requiring trace-level viral load detection.
- Japan's PMDA Streamlined Review:The Pharmaceuticals and Medical Devices Agency's Sakigake designation system accelerates market access for novel infectious disease diagnostics in Asia-Pacific's highest-value reference laboratory market.
Industry Challenges
- Bioinformatics Pipeline Validation:Next-Generation Sequencing assay developers face non-standardized reference materials for adenovirus serotype discrimination, complicating analytical specificity claims.
- Cross-Reactivity Mitigation:Primer-probe design teams must navigate sequence homology between human adenovirus species and enteric adenoviruses to prevent gastrointestinal specimen interference.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adenovirus Diagnostic Testing Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR Tests, ELISA Kits, Rapid Antigen Tests, Viral Culture End User: Hospitals, Diagnostic Labs, Research Institutions, Home Testing Technology: qPCR, Next-Generation Sequencing, Microfluidics, LAMP Application: Infectious Disease Diagnosis, Clinical Research, Epidemic Outbreak Tracking, Vaccine Development |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche, Danaher Corporation, BioMérieux, QIAGEN, Thermo Fisher Scientific, Bio-Rad Laboratories, Becton, Dickinson and Company, DiaSorin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adenovirus Diagnostic Testing Market Strategic Shifts
Cloud-connected instrument architectures are collapsing the traditional boundaries between assay execution and result interpretation, enabling real-time quality monitoring and remote technical support that reshape service delivery economics.
Random access molecular analyzers are virtualizing the batch-processing paradigm that historically constrained laboratory workflow efficiency. Hospital core laboratories in Germany and Japan deploy these systems to interleave adenovirus requests with STAT infectious disease testing, eliminating minimum batch size requirements that previously delayed individual specimen reporting.
The EU In Vitro Diagnostic Regulation's clinical evidence requirements are compressing the CE-marking timeline for multiplex respiratory panels. Assay developers must now generate prospective diagnostic accuracy data across intended-use populations, favoring established manufacturers with existing clinical trial infrastructure over emerging entrants lacking European investigator networks.
Consolidated procurement by integrated delivery networks is displacing decentralized laboratory purchasing autonomy. United States health systems now mandate standardized respiratory pathogen menus across affiliated hospitals, forcing reference laboratories to negotiate enterprise-wide contracts that sacrifice menu customization for volume pricing advantages.
Adenovirus Diagnostic Testing Market Segmentation
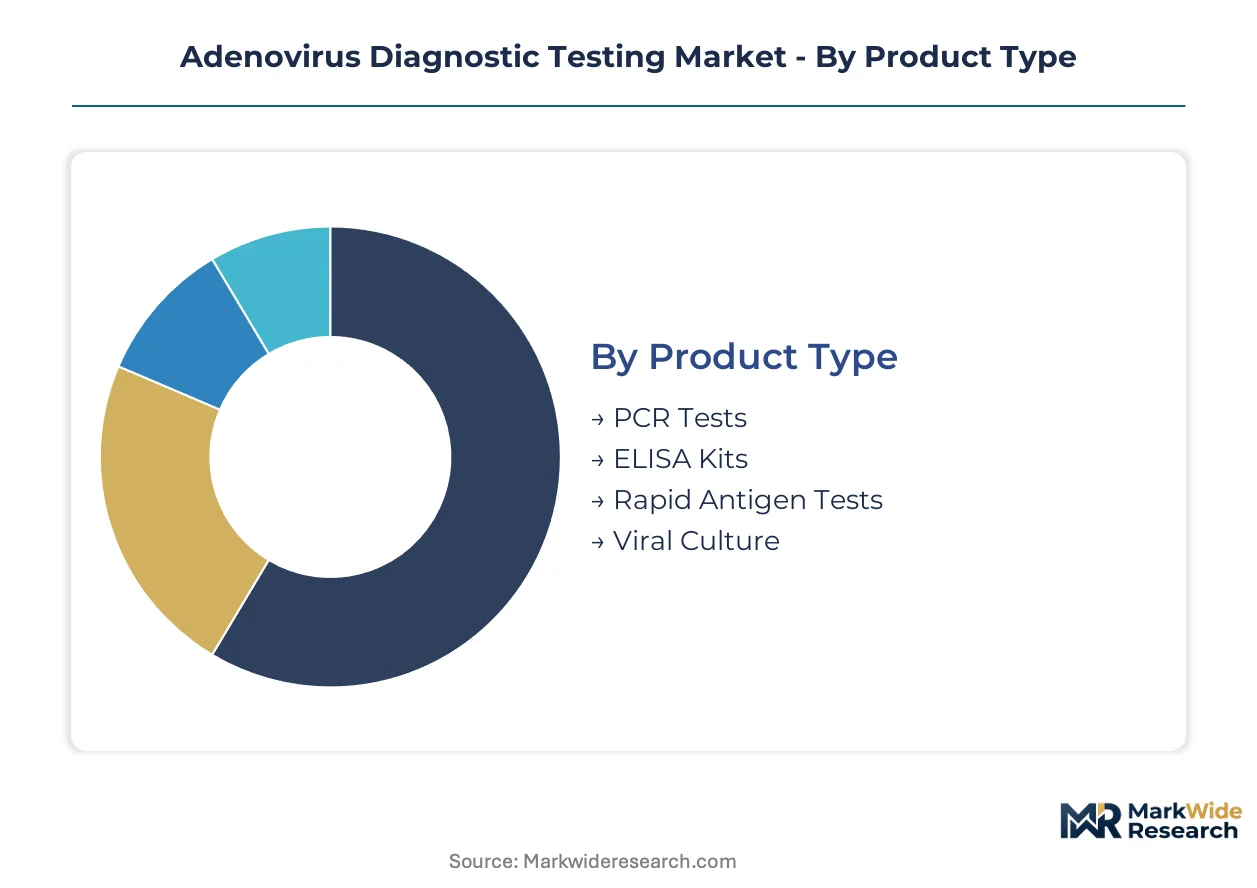
Segmentation in adenovirus diagnostics reveals how technology maturity, care setting economics, and specimen routing requirements fragment commercial opportunities. Each dimension carries distinct margin profiles, regulatory pathways, and competitive intensity that shape platform investment decisions.
Product Type:
Mature molecular platforms coexist with emerging rapid formats as reimbursement and sensitivity requirements diverge across care settings.
- PCR Tests:Nucleic acid amplification assays deliver analytical sensitivity thresholds of 10-100 copies per reaction for quantitative viral load monitoring. Centralized hospital laboratories in the United States and Germany anchor demand as bundled respiratory panel reimbursement solidifies molecular confirmation workflows.
- Rapid Antigen Tests:Immunochromatographic lateral flow devices generate results within fifteen minutes at point-of-care sites. Physician office laboratories across Japan leverage CLIA complexity waivers to deploy these where turnaround time overrides sensitivity constraints for high-titer specimens.
- ELISA Kits:Enzyme-linked immunosorbent assays detect adenovirus-specific IgM and IgG antibodies in serological surveillance programs.
- Viral Culture:Cell-based isolation methods retain niche utility in reference laboratories for serotype characterization and antiviral susceptibility testing.
PCR Tests retain volume leadership; Rapid Antigen Tests hold the steepest expansion curve.
End User:
Customer type determines pricing power, menu breadth requirements, and service attachment rates for diagnostic platforms.
- Hospitals:Acute care institutions require STAT turnaround capabilities and integrated electronic medical record connectivity. Core laboratories in the United States deploy random access molecular analyzers to interleave adenovirus requests with urgent infectious disease testing, eliminating batch-processing delays.
- Diagnostic Labs:Independent reference laboratories and hospital outreach programs concentrate specimen volume for economies of scale. Germany's centralized laboratory networks dominate routing for complex molecular panels.
- Research Institutions:Academic medical centers and public health laboratories drive adoption of untargeted detection methods.
- Home Testing:Patient-collected specimen models using microsampling devices bypass clinic visits for shipped laboratory analysis.
Hospitals command the highest per-test revenue; Home Testing is climbing the fastest as consumer-directed care expands.
Technology:
Platform selection hinges on throughput requirements, capital constraints, and bioinformatics infrastructure availability.
- qPCR:Quantitative real-time PCR dominates commercial menus with established reagent supply chains and laboratory familiarity. Thermo Fisher Scientific anchors market position through integrated workflow systems spanning extraction through analysis for transplant center surveillance protocols.
- Next-Generation Sequencing:Massively parallel sequencing enables pan-viral panel deployment for untargeted outbreak investigation. Public health laboratories in Japan and the United States drive adoption as bioinformatics pipelines mature for adenovirus serotype discrimination.
- Microfluidics:Lab-on-chip architectures miniaturize reaction volumes for near-patient testing applications.
- LAMP:Loop-mediated isothermal amplification operates without thermal cycling equipment for resource-limited settings.
qPCR maintains installed-base dominance; Next-Generation Sequencing is gaining share fastest in reference laboratory networks.
Application:
Use case differentiation separates high-volume routine screening from premium-priced specialized surveillance.
- Infectious Disease Diagnosis:Differentiation of adenoviral respiratory, ocular, or gastrointestinal infections from clinically similar presentations caused by influenza, RSV, or SARS-CoV-2. Hospital emergency departments in the United States drive volume for syndromic respiratory panels.
- Clinical Research:Quantitative viral load monitoring supports hematology-oncology units managing stem cell transplant recipients. BioMérieux competes on rapid turnaround specifications for immunocompromised patient populations requiring trace-level detection.
- Epidemic Outbreak Tracking:Untargeted pathogen discovery during unexplained respiratory clusters.
- Vaccine Development:Immunogenicity assessment and viral titer quantification in clinical trial protocols.
Infectious Disease Diagnosis captures routine volume; Clinical Research carries the steepest pricing premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity for adenovirus diagnostics varies sharply across healthcare systems. Germany and Japan absorb premium molecular pricing for transplant surveillance, while India and Brazil face acute cost constraints that favor antigen-based screening protocols.
United States
Hospital laboratory consolidation and IDN procurement standardization concentrate demand for multiplex respiratory panels. FDA's evolving template guidance for multiplex infectious disease assays compresses validation timelines for assay developers. Reference laboratory networks in Boston and the Research Triangle anchor specimen routing for complex molecular testing.
Germany
Centralized laboratory networks dominate specimen volume for hematology-oncology surveillance protocols. EU In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for CE-marked products entering European Economic Area markets. The Rhine-Ruhr metropolitan region hosts dense clusters of hospital core laboratories deploying random access molecular analyzers.
Japan
Stem cell transplant centers generate dedicated demand for quantitative viral load monitoring in immunocompromised populations. PMDA's Sakigake designation system accelerates market access for novel infectious disease diagnostics. Tokyo-Osaka corridor reference laboratories drive adoption of next-generation sequencing for untargeted outbreak investigation.
India
Point-of-care expansion in tier-2 cities creates volume for rapid antigen formats where sensitivity constraints are tolerated. CDSCO oversight of in vitro diagnostic devices shapes import and manufacturing compliance requirements. Bangalore and Hyderabad clusters concentrate diagnostic reagent manufacturing and distribution infrastructure.
Adenovirus Diagnostic Testing Market Competitive Environment
Capability concentration sits with integrated platform specialists; scale advantage sits with broad installed-base incumbents. The vendor landscape organizes around three archetypes: multinational conglomerates with full workflow integration, mid-sized specialists competing on turnaround specifications, and emerging entrants targeting home-based specimen collection models. Dominant competitive moves include strategic partnerships for bioinformatics pipeline development and geographic licensing agreements to access Japan's streamlined regulatory pathway.
Among US-based conglomerates, Abbott Laboratories and Thermo Fisher Scientific occupy positions spanning extraction through analysis workflows. BioMérieux represents the European specialist archetype competing on rapid turnaround specifications. These three entities exemplify how platform breadth, geographic footprint, and clinical evidence infrastructure separate sustainable competitors from emerging challengers facing EU IVDR compliance burdens.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche |
| Danaher Corporation |
| BioMérieux |
| QIAGEN |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Becton, Dickinson and Company |
| DiaSorin |
| Others |
Value Chain & Pricing Dynamics
Shanghai-to-Rotterdam container freight corridors transmit cost volatility from magnetic bead chemistry manufacturing clusters directly into assay pricing tiers, concentrating margin pressure on mid-tier PCR kit suppliers while enabling premium-tier vendors to sustain value-based contracts with hospital laboratory networks.
Pricing Analysis
Aftermarket consumable and service contract revenue streams drive lifetime value capture for installed-base incumbents. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared multiplex panels from moderate-complexity LDT workflows and unregulated research-use-only formats. Pricing pressure stems from Medicare Clinical Laboratory Fee Schedule compression, particularly for standalone adenovirus targets outside bundled respiratory reimbursement. Reference laboratories exhibit lowest price sensitivity due to transplant surveillance protocol stickiness; physician office laboratories face acute cost constraints favoring rapid antigen formats.
Supply Chain Analysis
Tariff exposure between China and the United States dominates input cost instability for magnetic bead extraction reagents. Manufacturing concentrates in China, Germany, and the United States for thermal cycler instruments; reagent production clusters in China and Ireland. Raw material dependencies span oligonucleotide synthesis chemistries, fluorescent probe dyes, and polymerase enzymes. Single-source vulnerability in Chinese magnetic bead supply creates batch-to-batch performance variation risks. Distribution runs through consolidated procurement by integrated delivery networks and centralized reference laboratory contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network procurement standardization, as United States health systems mandate uniform respiratory pathogen menus across affiliated hospitals.
For Market Incumbents: Build switching-cost moats through electronic medical record integration and random access analyzer installed-base expansion. Defend against emerging digital PCR specialists by deepening CLIA-waived assay menus for point-of-care sites. Pursue backward integration into oligonucleotide synthesis to secure probe supply chains against Chinese manufacturing volatility. For New Entrants and Emerging Players: India's tier-2 city physician office laboratories represent underpenetrated white space where rapid antigen CLIA waivers bypass molecular infrastructure requirements. Japan's PMDA Sakigake pathway offers accelerated regulatory entry for novel serotype discrimination assays. Target home-based microsampling models through direct-to-consumer partnerships with telehealth platforms. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate diagnostic divisions lacking EU IVDR clinical evidence infrastructure for multiplex panel compliance. Long-term viability hinges on pan-viral NGS assay developers with validated bioinformatics pipelines for public health laboratory networks. Monitor FDA template guidance publication timing as inflection signal for validation burden shifts affecting competitive entry costs.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU IVDR clinical evidence requirements favor manufacturers with existing European investigator networks for multiplex respiratory panels. |
| Hospital System Partnership | Integrated delivery network enterprise contracts sacrifice menu customization for volume pricing advantages across affiliated laboratories. |
| Software Companion Development | Cloud-connected instrument architectures enable real-time quality monitoring that collapses boundaries between assay execution and remote interpretation. |
| Reimbursement Strategy | Medicare Clinical Laboratory Fee Schedule navigation determines profitability for standalone adenovirus targets outside bundled panels. |
| FDA Submission | Multiplex respiratory panel template guidance compliance compresses validation timelines while expanding menu breadth requirements. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU IVDR technical documentation, CMS Medicare claims data, and hospital procurement databases. Primary interviews span clinical laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs leads at assay developers. Secondary validation draws from Clinical Laboratory Improvement Amendments complexity classification records, PMDA Sakigake designation announcements, and reference laboratory service menus. Bottom-up assay volume modeling triangulates against top-down market sizing from installed-base estimates and consumable pull-through rates.
Forecast inputs include qPCR platform replacement cycles, NGS bioinformatics pipeline deployment trajectories, and CLIA waiver expansion patterns across physician office laboratories. Segmentation dimensions span product type, end user, technology platform, and application use case. CAGRs derive from instrument placement velocity, reagent annuity per installed unit, and reimbursement pathway stability across the projection horizon. Industry-specific inputs incorporate transplant center surveillance protocol adoption and pan-viral outbreak investigation funding allocations.
Practitioners should monitor FDA template guidance revisions, EU IVDR notified body capacity constraints, and magnetic bead supply chain disruptions for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Middle East and Africa Syndromic Multiplex Diagnostic Market
Diagnostics
Semen Analysis Market
Diagnostics
Fructosamine Test Market
Diagnostics
At-Home Cancer Testing Market
Diagnostics
Global Lyme Disease Diagnostic Market
Diagnostics
Anatomic Pathology Market
Diagnostics
Acute Ischemic Stroke Diagnosis Market
Diagnostics
Global Tissue Diagnostics Market
Diagnostics
Global Cervical Cancer Diagnostics Market
Diagnostics
DNA Probes - Based Diagnostics Market
Diagnostics
Diagnostic Testing of Stds Market
Diagnostics
Pancreatic Cyst Diagnostics Market
Diagnostics
Global Alzheimers Disease Diagnostic Market
Diagnostics
Livestock Diagnostics Market
Diagnostics
Global Liver Disease Diagnostics Market
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market