
 Global Chemiluminescence Immunoassay (CLIA) Market | 2026-2036
Global Chemiluminescence Immunoassay (CLIA) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chemiluminescence Immunoassay (CLIA) Market Foresight
The EU In Vitro Diagnostic Regulation is realigning procurement priorities across European hospital networks, compelling manufacturers to rebuild clinical evidence portfolios for legacy assays. F. Hoffmann-La Roche AG leverages its deep reagent installed base to sustain recurring revenue streams while navigating the new conformity burden. Abbott Laboratories anchors its competitive position through instrument-reagent bundling that locks diagnostic laboratories into long-term supply contracts. Siemens Healthineers differentiates via modular analyzer architectures that allow mid-volume sites to scale throughput without full platform replacement.
Chemiluminescence immunoassay denotes a detection method where antibody-antigen binding triggers a light-emitting chemical reaction, typically employing acridinium ester or alkaline phosphatase substrates to quantify analytes at picomolar sensitivity for endocrine, infectious disease, and tumor marker panels. Magnetic separation technology dominates high-throughput installations due to its wash efficiency and reproducibility, while electrochemiluminescence commands premium positioning in reference laboratories seeking the broadest dynamic range. Reagent consumables capture the majority of lifetime value per installed instrument, with oncology and infectious disease applications driving the fastest menu expansion as multiplexed cancer panels and respiratory pathogen screens deepen test utilization.
The FDA maintains stringent premarket review pathways for novel CLIA analytes under its IVD classification system, while China's NMPA accelerates domestic innovation through streamlined green-channel approvals for priority diagnostic devices. ISO 13485 quality management certification has become a baseline market-access requirement for suppliers targeting institutional procurement tenders across Japan, Germany, and Brazil. Stakeholders must monitor how decentralized point-of-care CLIA platforms reshape volume economics between centralized laboratories and distributed specialty clinics.
Market Dynamics
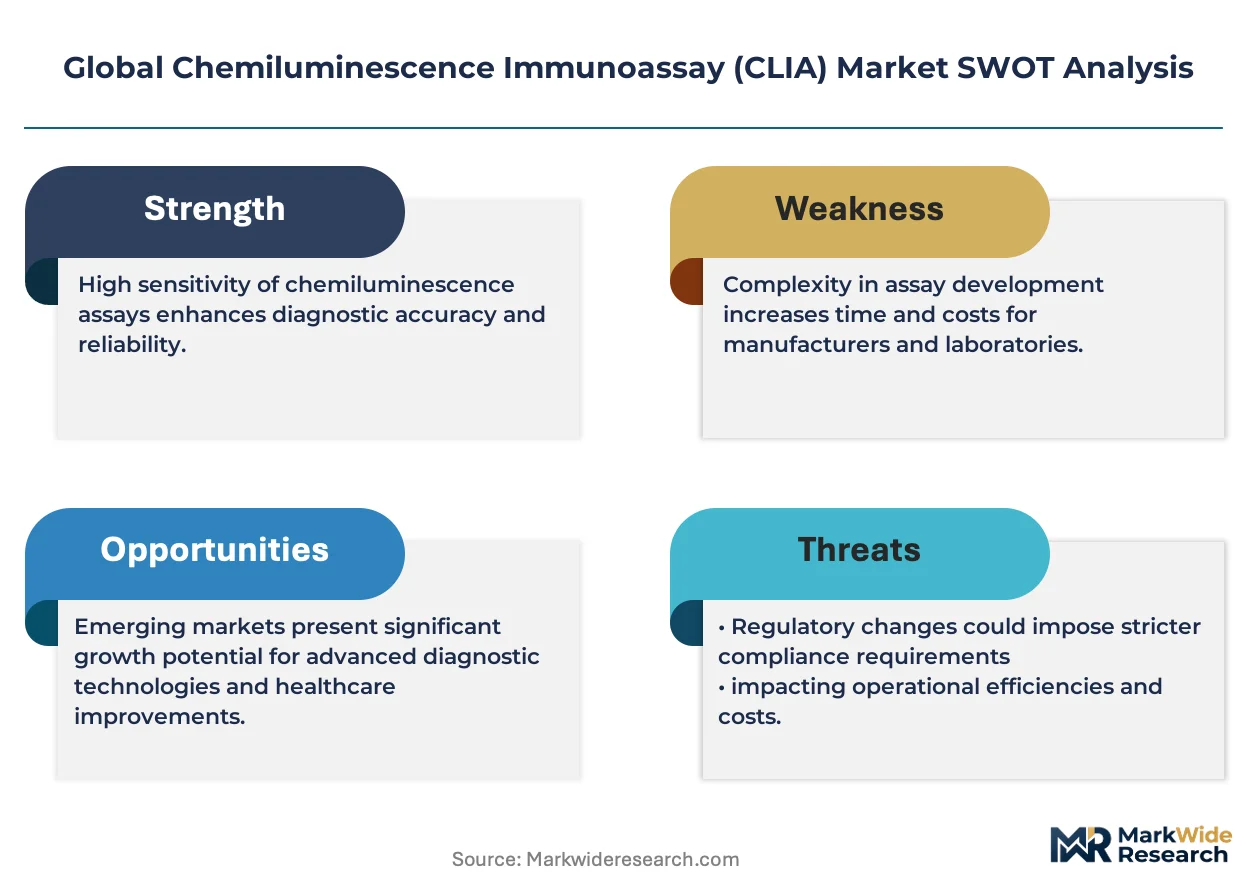
Reagent kit cost-engineering by Chinese domestic manufacturers is compressing instrument margins and forcing global incumbents to unbundle hardware from consumable contracts. This structural pressure cascades through procurement offices in hospital laboratories and diagnostic chains worldwide.
Growth Catalysts
- Oncology test menu expansion:Multiplexed cancer biomarker panels are deepening utilization rates in tertiary hospital laboratories across Germany and Japan. Payer reimbursement frameworks in both markets now cover serial tumor marker monitoring.
- EU MDR compliance timelines:The Medical Device Regulation's 2026 enforcement deadline compels European diagnostic networks to replace legacy enzyme-linked immunosorbent assay workflows with validated CLIA alternatives.
- Magnetic microparticle separation:This wash technology reduces assay variability in high-throughput infectious disease screening, driving replacement demand in Brazilian and Indian reference laboratories.
Market Restraints
- Acridinium ester supply concentration:Three specialty chemical manufacturers in Switzerland and Germany control global substrate production, exposing assay makers to input cost volatility and allocation risk.
- ISO 13485 certification timelines:Quality management system audits for new market entrants now stretch 14-18 months in Japan and Brazil, delaying commercial launch windows.
- Fluorescence polarization immunoassay substitution:This alternative detection method competes for thyroid and fertility testing volumes in mid-volume laboratories seeking lower capital commitments.
Strategic Opportunities
- Decentralized point-of-care deployment:Compact CLIA analyzers are penetrating specialty clinics and urgent care networks in Texas, Florida, and California, fragmenting volume from centralized hospital laboratories.
- Respiratory pathogen panel demand:Multiplexed viral and bacterial detection menus are expanding beyond influenza and COVID-19 into routine respiratory syndrome workups in South Korean and Australian diagnostic chains.
- China NMPA green-channel approvals:Priority review pathways for domestic innovation accelerate time-to-market for novel infectious disease assays targeting tuberculosis and hepatitis C.
Industry Challenges
- Assay validation workforce scarcity:Clinical laboratories in France and Italy face acute shortages of medical laboratory scientists trained in chemiluminescence method verification and quality control protocol design.
- Legacy LIS integration complexity:Middleware compatibility gaps between new-generation CLIA analyzers and entrenched laboratory information systems in British National Health Service trusts extend deployment timelines and inflate implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chemiluminescence Immunoassay (CLIA) Market |
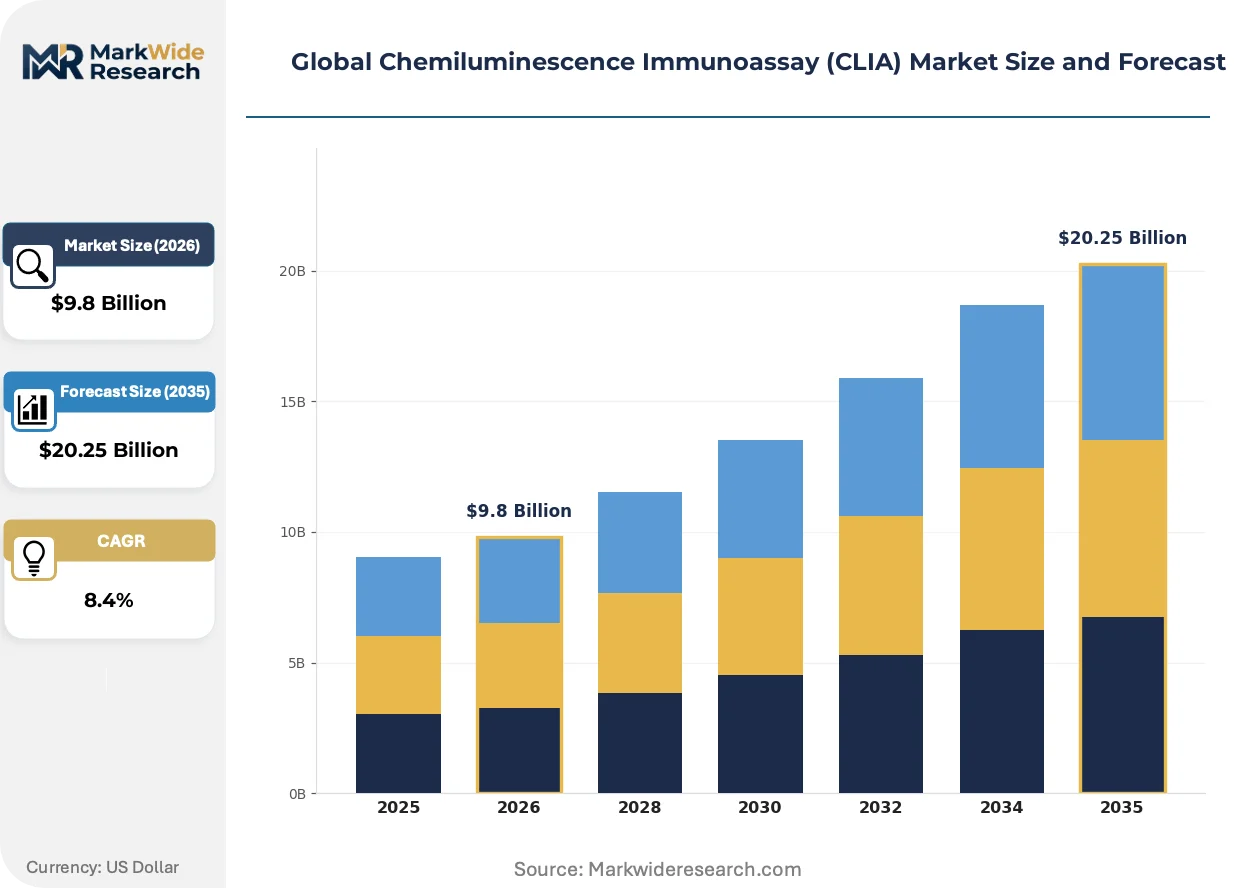
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instruments, Reagents, Software, Consumables Technology: Magnetic Separation, Enzyme Labeling, Electrochemiluminescence, Chemiluminescent Substrates Application: Oncology, Infectious Diseases, Endocrinology, Cardiology, Autoimmune Disorders End User: Diagnostic Laboratories, Research Institutes, Academic Centers, Specialty Clinics |
| Companies Covered | DiaSorin S.p.A., Shenzhen New Industries Biomedical Engineering Co., Ltd., F. Hoffmann-La Roche AG, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Sysmex Corporation, Siemens Healthineers AG, Abbott Laboratories, QuidelOrtho Corporation, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chemiluminescence Immunoassay (CLIA) Market Shifts & Advancements
Digital integration and miniaturization are reconfiguring how chemiluminescence assays are deployed, validated, and monetized across the diagnostic value chain. Three developments merit particular attention.
Electrochemiluminescence detection is expanding into mid-volume hospital laboratories previously served by conventional acridinium ester platforms. Siemens Healthineers and domestic Chinese instrument makers are shipping modular architectures that scale from 80 to 400 tests per hour without full platform replacement. This flexibility is compressing the traditional segmentation between reference laboratories and general hospital sites.
China's NMPA streamlined approval pathways for priority diagnostic devices are accelerating domestic assay innovation. Local manufacturers now secure market authorization for novel infectious disease panels in 12-18 months versus 36-48 months for imported alternatives. European and Japanese instrument makers are responding by establishing joint ventures with Chinese reagent developers to access these accelerated timelines.
Diagnostic procurement offices are unbundling instrument placement from long-term consumable commitments. Hospital networks in Germany and the Netherlands now negotiate reagent supply contracts separately from analyzer leases, compressing supplier margins and shortening contract renewal cycles. This shift is most visible in laboratory consortia serving multiple regional hospitals.
Global Chemiluminescence Immunoassay (CLIA) Market Segmentation
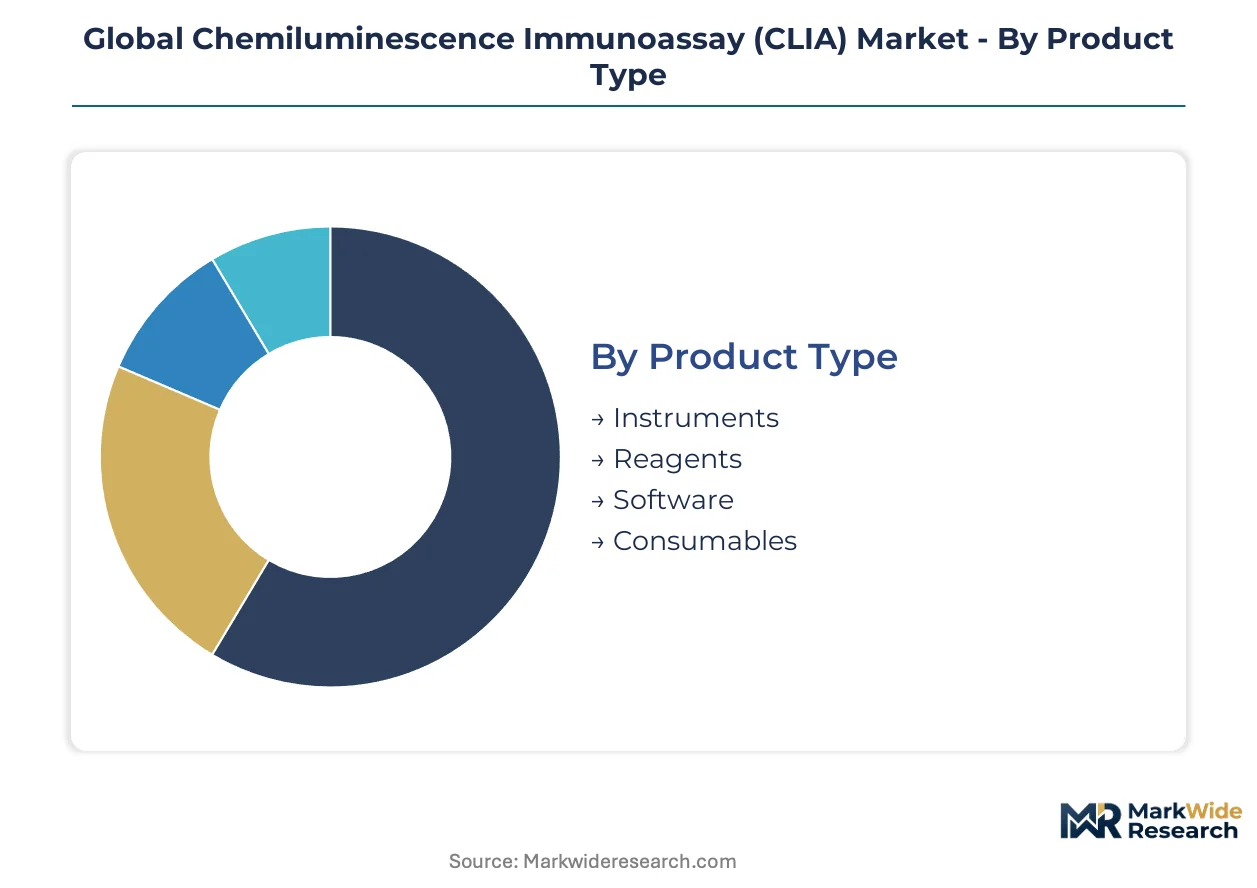
CLIA market segmentation reveals how regulatory pathways, cost structures, and clinical workflows fragment purchasing decisions across hospital procurement offices. Each dimension carries distinct certification burdens and margin profiles that reshape competitive positioning.
Product Type:
ISO 13485 certification applies differentially across this category, with instruments requiring full quality system audits while consumables face streamlined conformity routes in Japan and Brazil.
- Instruments:Modular analyzer architectures span 80 to 400 tests per hour, accommodating magnetic microparticle or electrochemiluminescence detection heads. Demand concentrates in Chinese tertiary hospitals where domestic makers displace imported platforms through aggressive placement terms.
- Reagents:Acridinium ester and alkaline phosphatase substrate kits generate recurring revenue streams that exceed instrument lifetime value. Oncology and infectious disease panels in German and Japanese reference laboratories drive the fastest menu expansion.
- Software:Middleware platforms bridge analyzer output to entrenched laboratory information systems, with NHS trusts in Britain demanding HL7 FHIR compatibility.
- Consumables:Pipette tips, reaction vessels, and wash buffers face cost-engineering pressure from Chinese domestic suppliers compressing procurement budgets.
Leading the category by volume: Reagents. Growing fastest: Software.
Technology:
Detection chemistry determines capital intensity, throughput ceiling, and dynamic range sensitivity across laboratory tiers.
- Magnetic Separation:Microparticle wash technology reduces assay variability in high-throughput infectious disease screening. Brazilian and Indian reference laboratories drive replacement demand for legacy open-tube systems.
- Enzyme Labeling:Alkaline phosphatase conjugates offer cost-efficient detection for mid-volume sites in France and Italy facing capital constraints.
- Electrochemiluminescence:Ru(bpy)3²⁺ chemistry delivers the broadest dynamic range for tumor marker quantification. Siemens Healthineers anchors this tier in German university hospitals seeking picomolar sensitivity.
- Chemiluminescent Substrates:Acridinium ester production concentrates in Swiss and German specialty chemical manufacturers, exposing assay makers to allocation risk.
Electrochemiluminescence commands premium positioning. Magnetic separation expands most quickly into mid-volume sites.
Application:
Clinical indication determines reimbursement eligibility, test frequency, and panel multiplexing depth in payer negotiations.
- Oncology:Multiplexed cancer biomarker panels enable serial tumor marker monitoring now covered by German and Japanese reimbursement frameworks. Tertiary hospital laboratories deepen utilization rates fastest.
- Infectious Diseases:Respiratory pathogen screens beyond influenza and COVID-19 penetrate South Korean and Australian diagnostic chains. China's NMPA green-channel accelerates tuberculosis and hepatitis C assay approvals.
- Endocrinology:Thyroid and fertility testing faces substitution pressure from fluorescence polarization immunoassay in mid-volume laboratories.
- Cardiology:Cardiac troponin protocols demand rapid turnaround times that favor centralized laboratory workflows over point-of-care alternatives.
- Autoimmune Disorders:ANA and ENA panels require high specificity to minimize false-positive referrals in rheumatology clinics.
Oncology generates the steepest expansion trajectory. Autoimmune testing matures slowest.
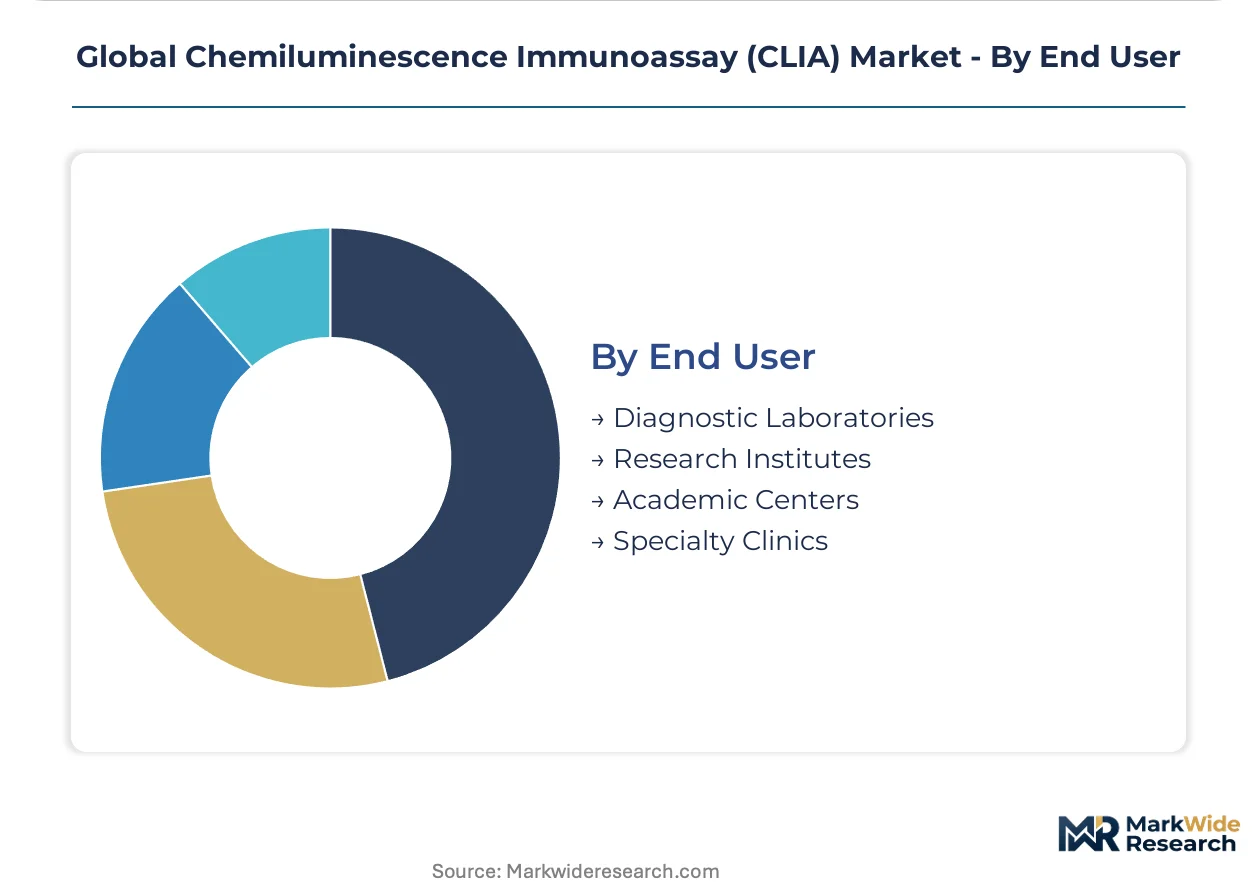
End User:
Site type dictates throughput requirements, staffing expertise, and integration complexity with existing health information infrastructure.
- Diagnostic Laboratories:Hospital networks in Germany and the Netherlands unbundle instrument leases from reagent contracts, compressing supplier margins. Magnetic separation platforms dominate high-throughput screening.
- Research Institutes:Custom assay development for novel biomarkers requires flexible substrate chemistries and open-architecture detection systems.
- Academic Centers:Training pipelines for medical laboratory scientists in France and Italy face acute scarcity, extending validation timelines.
- Specialty Clinics:Compact CLIA analyzers fragment volume from centralized laboratories in Texas, Florida, and California urgent care networks.
Diagnostic laboratories anchor procurement volume. Specialty clinics gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the most concentrated CLIA manufacturing corridor, where domestic instrument makers exploit cost-engineered reagent kits to displace imported platforms across Chinese tertiary hospitals.
China
Domestic manufacturers in the Yangtze River Delta and Pearl River Delta exploit NMPA green-channel approvals to compress time-to-market for tuberculosis and hepatitis C assays to 12-18 months. The regulator's priority review pathways accelerate domestic innovation while forcing European joint ventures to localize reagent development. Shanghai and Beijing hospital networks now source over half of new analyzer placements from domestic suppliers.
Germany
German university hospitals in Bavaria and North Rhine-Westphalia drive demand for electrochemiluminescence systems delivering picomolar sensitivity for tumor marker quantification. The EU MDR's 2026 enforcement deadline compels diagnostic networks to replace legacy ELISA workflows with validated CLIA alternatives. Berlin and Munich laboratory consortia now unbundle instrument leases from reagent contracts, compressing supplier margins.
United States
Texas, Florida, and California urgent care networks fragment volume from centralized laboratories through compact CLIA analyzer deployment in specialty clinics. The FDA maintains stringent premarket review pathways for novel analytes under its IVD classification system. The Greater Boston and San Francisco Bay Area clusters concentrate research institute demand for custom assay development on open-architecture detection systems.
Japan
Tokyo and Osaka tertiary hospitals deepen utilization rates for multiplexed cancer biomarker panels now covered by national reimbursement frameworks. PMDA quality management system audits stretch 14-18 months for new market entrants, delaying commercial launch windows. The Kanto region faces acute shortages of medical laboratory scientists trained in chemiluminescence method verification.
Brazil
São Paulo and Rio de Janeiro reference laboratories drive replacement demand for magnetic microparticle separation platforms in high-throughput infectious disease screening. ANVISA's alignment with ISO 13485 certification requirements creates baseline market-access barriers for international suppliers. The Southeast region concentrates procurement decisions for hospital network laboratory consortia serving multiple regional facilities.
Global Chemiluminescence Immunoassay (CLIA) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across detection chemistry tiers, with electrochemiluminescence systems commanding price multiples over conventional acridinium ester platforms. The vendor base stratifies into three archetypes: diversified diagnostics conglomerates with deep reagent installed bases, mid-scale instrument specialists leveraging modular architectures, and cost-engineered domestic challengers from China. Consolidation pressure intensifies as procurement offices unbundle hardware from consumable contracts, while technology licensing agreements proliferate to access NMPA accelerated approval pathways.
Within the diversified conglomerate tier, F. Hoffmann-La Roche AG and Abbott Laboratories exemplify players sustaining recurring revenue through instrument-reagent bundling strategies. Siemens Healthineers occupies a position among modular architecture specialists, while Shenzhen New Industries Biomedical Engineering Co., Ltd. represents the cost-engineered domestic challenger archetype exploiting China's regulatory green channels.
| Leading Market Players |
|---|
| DiaSorin S.p.A. |
| Shenzhen New Industries Biomedical Engineering Co., Ltd. |
| F. Hoffmann-La Roche AG |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Sysmex Corporation |
| Siemens Healthineers AG |
| Abbott Laboratories |
| QuidelOrtho Corporation |
| Danaher Corporation |
| Others |
Supply & Pricing Matrix
Medical laboratory scientist shortages in the Kanto region of Japan widen labor-cost differentials between electrochemiluminescence reference laboratories and mid-volume hospital sites, compressing pricing-tier spreads as automation investments substitute for scarce technical expertise.
Pricing Analysis
Throughput-based pricing anchors the dominant model, with per-test fees scaling from economy-tier magnetic separation platforms to premium electrochemiluminescence systems delivering picomolar sensitivity. Price differentiation rests on ISO 13485 certification grade and analyzer uptime guarantees, with German university hospitals paying brand premiums for Siemens Healthineers while Chinese tertiary hospitals prioritize domestic cost-engineered alternatives. Pricing pressure stems from procurement offices unbundling instrument leases from reagent contracts in Dutch and German laboratory consortia. Mid-volume French and Italian laboratories exhibit highest price sensitivity due to capital constraints, whereas Japanese reference laboratories show lowest sensitivity given national reimbursement coverage for multiplexed cancer panels.
Supply Chain Analysis
China's NMPA green-channel domestic-content requirements reshape sourcing patterns, compelling European instrument makers to localize reagent development through joint ventures with Shenzhen and Shanghai developers. Acridinium ester substrate production concentrates in Switzerland and Germany, while magnetic microparticle manufacturing centers on Chinese Yangtze River Delta suppliers. Raw material dependencies span specialty chemical substrates, precision-engineered reaction vessels, and rare-earth magnetic beads. Single-source vulnerability in Swiss-German acridinium ester supply exposes assay makers to allocation risk. Distribution runs through hospital procurement offices and diagnostic laboratory consortia serving regional network facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU MDR's 2026 enforcement deadline elevates cost-of-compliance barriers, creating a regulatory moat favoring manufacturers with pre-existing clinical evidence portfolios and ISO 13485 quality system infrastructure.
For Market Incumbents: Deepen instrument-reagent bundling defenses by locking German and Dutch laboratory consortia into long-term service contracts with embedded uptime guarantees. Accelerate backward integration into acridinium ester substrate production to mitigate Swiss-German supply concentration risk. Expand modular analyzer architectures that scale throughput without full platform replacement, countering Chinese domestic displacement in mid-volume segments.
For New Entrants and Emerging Players: Urgent care networks in Texas, Florida, and California offer the most penetrable white-space channel, with compact CLIA analyzers fragmenting volume from centralized hospital laboratories. Target respiratory pathogen panel demand in South Korean and Australian diagnostic chains as the fastest-expanding application segment. Pursue NMPA joint venture structures to access China's 12-18 month green-channel approval timelines for tuberculosis and hepatitis C assays.
For Investors and Strategic Acquirers: Re-rating potential sits with modular architecture specialists given procurement unbundling trends compressing pure reagent-stream margins. Long-term viability across the analysis window favors manufacturers with electrochemiluminescence detection chemistry and established hospital system partnerships. Watch NMPA approval velocity for domestic Chinese manufacturers as the inflection indicator for global pricing-tier compression.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Joint Venture Formation | European instrument makers access China's 12-18 month priority review pathways through localized reagent partnerships. |
| Modular Analyzer Architecture Deployment | Siemens Healthineers enables mid-volume sites to scale from 80 to 400 tests per hour without platform replacement. |
| EU MDR Clinical Evidence Portfolio Rebuild | F. Hoffmann-La Roche AG sustains recurring revenue by validating legacy assays ahead of 2026 enforcement deadlines. |
| Point-of-Care Compact Analyzer Launch | Abbott Laboratories fragments centralized laboratory volume through specialty clinic penetration in Texas and Florida. |
| Backward Integration into Substrate Production | Assay manufacturers mitigate Swiss-German acridinium ester supply concentration through captive chemical synthesis. |
Research Methodology
Multi-period observation of NMPA approval timelines, EU MDR compliance expenditures, and hospital procurement contract structures anchored the trend analysis, supplemented by interviews with diagnostic laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs leads at IVD manufacturers. Secondary validation drew from FDA 510(k) filings, NMPA priority review databases, hospital procurement tender records, and ISO 13485 audit disclosure patterns. Bottom-up instrument placement and reagent consumption estimates triangulated against top-down market sizing derived from payer reimbursement code analysis.
Segment-weighting approaches modeled technology tier, application indication, end-user site type, and regional regulatory cluster across the projection horizon. CAGRs were derived from installed base expansion rates, test menu utilization depth, and pricing trajectory assumptions. Industry-specific forecast inputs incorporated magnetic microparticle separation adoption curves and electrochemiluminescence platform replacement cycles.
Several conditions sit outside the modeled scope, including unforeseen regulatory timeline extensions, raw material supply disruptions, and fluorescence polarization immunoassay substitution acceleration. Forecasts reflect documented assumptions regarding reimbursement stability and certification audit duration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Alanine Aminotransferase Reagent Market
Diagnostics
Urinary Protein Reagents Market
Diagnostics
Global Diagnostic Radiopharmaceuticals and Contrast Media Market
Diagnostics
Pancreatic Cyst Diagnostics Market
Diagnostics
Middle East and Africa Syndromic Multiplex Diagnostic Market
Diagnostics
Global Paper Diagnostics Market
Diagnostics
Swine Disease Diagnostic Kit Market
Diagnostics
Glucose Biosensors Market
Diagnostics
Global Serological Testing Market
Diagnostics
Latent Tuberculosis Infection Detection Market
Diagnostics
Global STD Diagnostics Market
Diagnostics
Global Coagulation Analyzers Market
Diagnostics
Equine Diagnostic Services Market
Diagnostics
Meningitis Diagnosis and Treatment Market
Diagnostics
North America Non-Hodgkin Lymphoma Diagnostics Market
Diagnostics
In Vitro Diagnostics Test Kit Market