
 Steel Powder Market | 2026-2036
Steel Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Powder Market Analytics
The gap between premium atomized grades and commodity reduced iron powder is realigning procurement strategies across the value chain. Höganäs AB leverages its integrated atomization network to dominate high-purity segments for additive manufacturing. Sandvik AB specializes in gas-atomized stainless grades that command premium positioning in medical and aerospace supply chains.
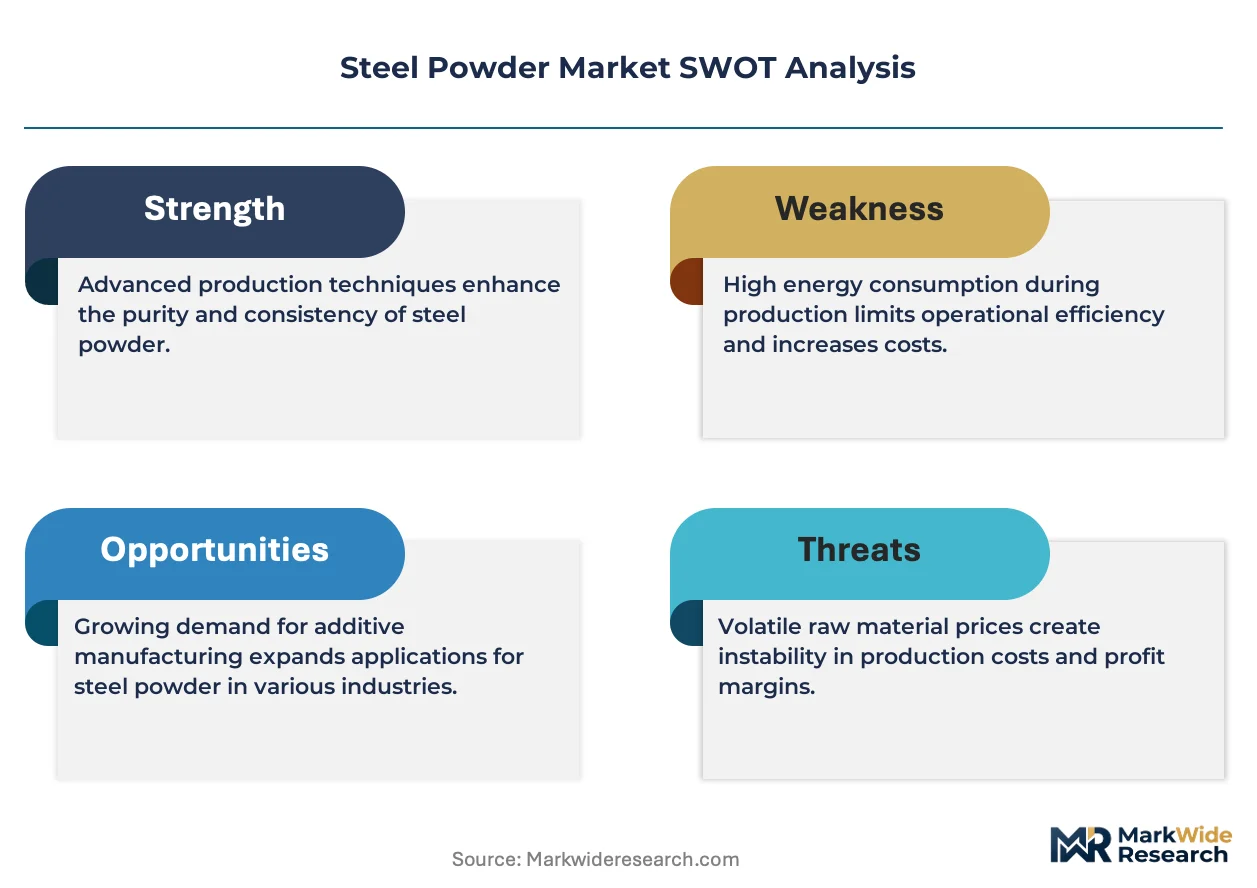
Steel powder consists of finely divided ferrous particles produced through atomization, reduction, or mechanical alloying, typically ranging from 10 to 150 micrometers in particle size with controlled carbon and oxygen content for sintering performance. Its primary purpose is to enable near-net-shape manufacturing through pressing and sintering, metal injection molding, or powder bed fusion processes that minimize material waste versus conventional machining. Atomized steel powder leads the product type landscape due to its spherical morphology and superior flowability for 3D printing and metal injection molding applications. Surface coating applications in the welding segment represent a mature but stable demand pool, while 3D printing applications in aerospace and medical end users capture the fastest expansion trajectory with the highest margin concentration.
EPA emissions standards and OSHA workplace exposure limits in the US, alongside REACH substance registration and the EU Green Deal carbon border adjustments in Europe, are elevating compliance costs for powder producers and reshaping facility investment decisions. China's GB standards and dual carbon goals under MEE oversight are similarly tightening domestic production specifications. Stakeholders must monitor how evolving regulatory thresholds for respirable metal dust and embodied carbon will filter through to product certification requirements and customer qualification timelines.
Market Dynamics
Automotive electrification is compressing demand for traditional powder-forged transmission components while simultaneously opening new specifications for soft magnetic materials in electric motor cores, forcing producers to reallocate atomization capacity between declining and emerging grade portfolios.
Growth Catalysts
- EPA emissions standards:Tighter tailpipe regulations in the US are accelerating lightweighting mandates across drivetrain assemblies, pulling atomized steel grades into gear and bearing applications previously served by wrought steel.
- Metal injection molding:Medical device manufacturers are expanding MIM adoption for surgical instrument components requiring complex geometries impossible through machining, driving demand for fine spherical powders below 25 micrometers.
- China:Domestic additive manufacturing capacity scaling under MIIT industrial policy directives is concentrating demand for gas-atomized tool steel and maraging grades within the country's eastern seaboard production clusters.
Market Restraints
- Scrap volatility:Electric arc furnace feedstock costs fluctuate with regional scrap availability, compressing margins for water-atomized carbon steel powder producers dependent on secondary metallurgy inputs.
- Supply concentration:High-purity gas-atomized grades for aerospace qualification depend on a limited set of European and North American production facilities, creating bottleneck risk during demand surges.
- Aluminum substitution:Magnesium-aluminum alloys in automotive structural components are displacing sintered steel in non-load-bearing brackets where corrosion resistance outweighs strength requirements.
Strategic Opportunities
- India:PLI scheme incentives for domestic manufacturing are attracting powder metallurgy investments for two-wheeler and small commercial vehicle components, creating early-mover positioning for qualified suppliers.
- Soft magnetic composites:Sintered soft magnetic materials for high-frequency electric motor cores represent an emerging application vector as OEMs redesign powertrain architectures around 800V systems.
- EU Green Deal:Carbon border adjustment mechanisms are creating preference for atomized powder produced with renewable electricity, favoring producers with documented Scope 2 emissions reductions.
Industry Challenges
- AM qualification timelines:Aerospace and medical device certification pathways for new powder lots extend 18-24 months, locking working capital in inventory before revenue recognition.
- Operator respiratory protection:OSHA permissible exposure limits for respirable metal dust are tightening workplace engineering controls, requiring capital deployment into enclosed powder handling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Powder Market |
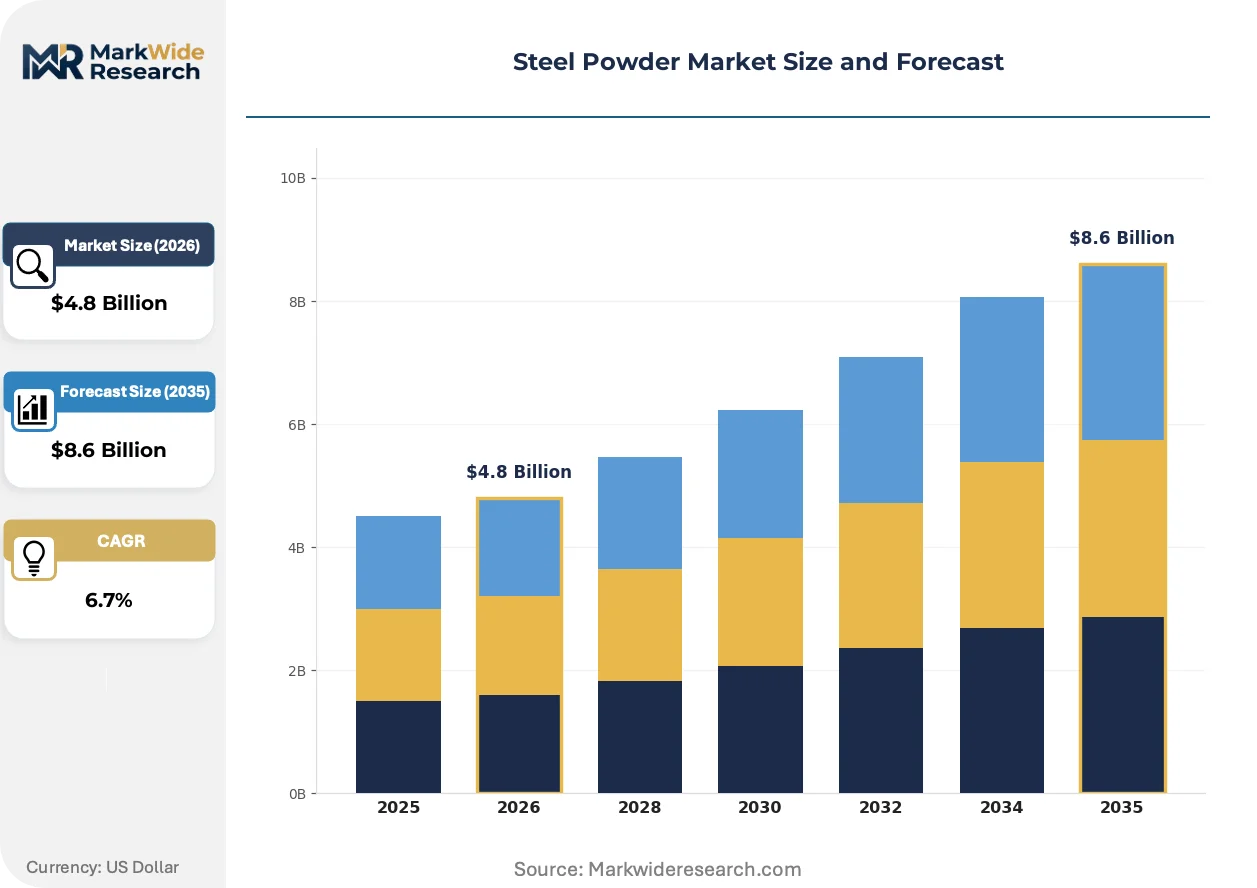
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atomized Steel Powder, Reduced Iron Powder, Stainless Steel Powder, High-Speed Steel Powder Application: 3D Printing, Metal Injection Molding, Welding, Surface Coating End User: Aerospace Industry, Automotive Manufacturers, Tooling Companies, Medical Equipment Suppliers Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Höganäs AB, Sandvik AB, Carpenter Technology Corporation, GKN Powder Metallurgy, Daido Steel, Mitsubishi Steel Manufacturing, Rio Tinto Metal Powders, BASF, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Powder Market Evolving Landscape
Process intensification in atomization technology is collapsing the historical trade-off between particle size distribution control and production throughput, enabling economic supply of grades previously restricted to specialty batches.
Plasma rotating electrode process (PREP) technology is expanding into titanium and nickel superalloy powder production for aerospace turbine components, with adopters including Tier 1 suppliers qualifying material for GE Aviation and Rolls-Royce engine programs. The structural consequence is compression of plasma atomization's market position in premium aerospace grades, as PREP offers superior sphericity with lower satellite content.
REACH substance registration requirements are forcing reformulation of process lubricants and binders used in powder metallurgy compaction, with ECHA scrutiny elevating costs for stearate-based die wall lubricants. European automotive suppliers are responding by accelerating qualification of synthetic wax alternatives, while Asian producers face exclusion from EU supply chains without SVHC compliance documentation.
Consolidation among tier-two powder metallurgy parts fabricators is compressing supplier bases, with surviving contract manufacturers demanding volume commitments and technical service integration previously split among multiple raw material vendors. This concentration is most visible in Germany's automotive supply corridor, where Schunk and GKN Sinter Metals have reduced qualified powder suppliers by 40 percent over the past qualification cycle.
Steel Powder Market Segmentation
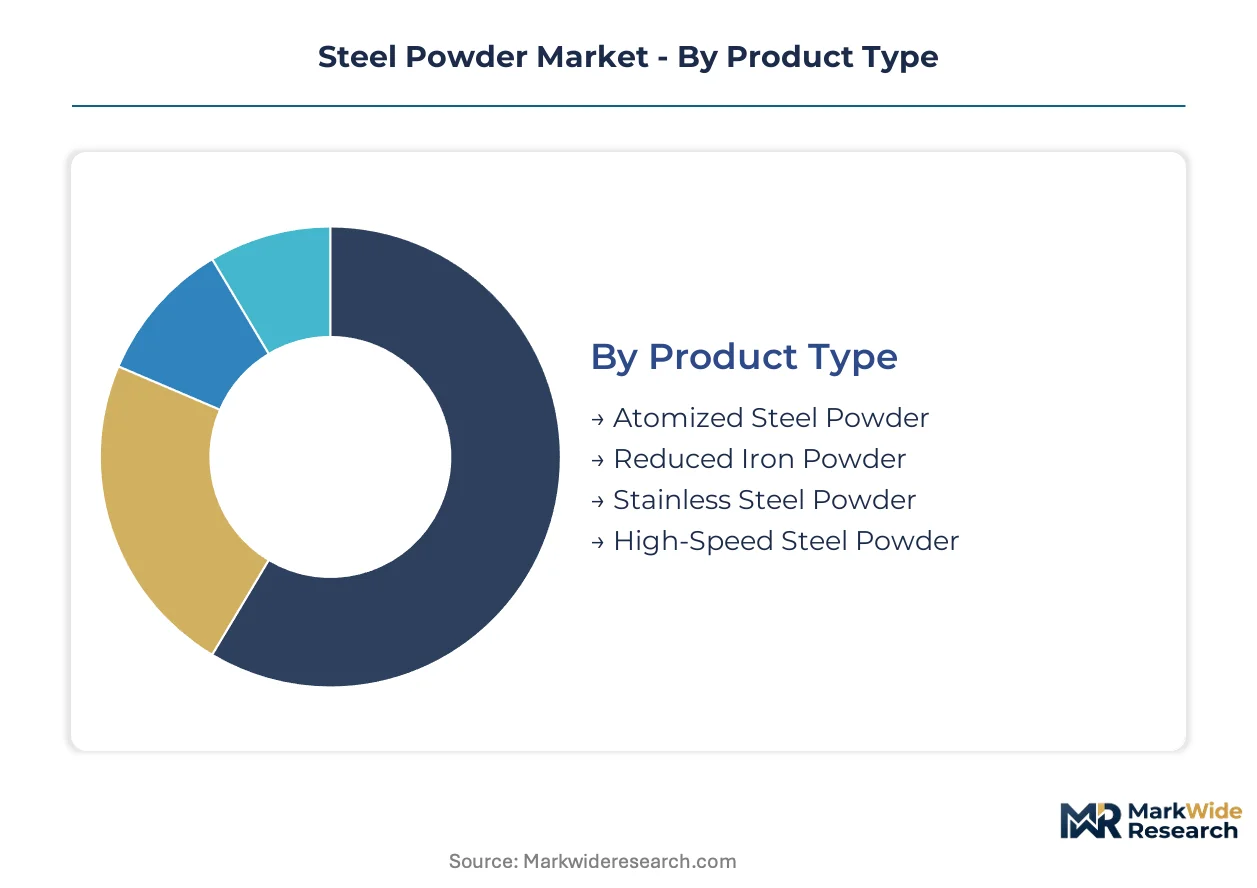
Steel powder procurement decisions hinge on particle morphology, sintering performance, and downstream process compatibility. Buyers evaluate atomization method against end-use certification requirements and total cost of near-net-shape manufacturing.
Product Type:
Purchasers prioritize flowability and oxygen content thresholds based on whether components will undergo pressing, metal injection molding, or powder bed fusion.
- Atomized Steel Powder:Spherical morphology delivers superior flowability for additive manufacturing and MIM feedstock production. Demand concentrates in China's eastern seaboard additive manufacturing clusters under MIIT industrial policy directives, with aerospace qualification timelines extending 18-24 months for new powder lots.
- Reduced Iron Powder:Irregular particle shape and higher oxygen content suit traditional press-and-sinter applications where cost sensitivity dominates. Automotive transmission component manufacturers in Germany's supply corridor favor this grade for high-volume powder-forged gears, though electrification is compressing demand for conventional drivetrain specifications.
- Stainless Steel Powder:Gas-atomized grades command premium positioning in medical and aerospace supply chains requiring corrosion resistance.
- High-Speed Steel Powder:Tool steel grades serve cutting tool manufacturers and die producers seeking wear resistance through powder metallurgy routes.
Volume sits with reduced iron powder; growth tilts toward atomized grades.
Application:
Process selection determines powder specification, with geometric complexity and production volume dictating whether buyers specify fine spherical grades or coarser irregular fractions.
- 3D Printing:Powder bed fusion and directed energy deposition demand tight particle size distributions, typically 15-45 micrometers, with minimal satellite content. Aerospace and medical device OEMs in the US and Europe drive qualification of maraging and tool steel grades, with PREP technology displacing plasma atomization for premium sphericity requirements.
- Metal Injection Molding:Fine powders below 25 micrometers enable complex geometries impossible through machining. Surgical instrument manufacturers expand MIM adoption for minimally invasive device components, pulling atomized stainless and low-alloy grades into medical supply chains.
- Welding:Surface coating applications represent mature demand for hardfacing and repair operations in heavy machinery maintenance.
- Surface Coating:Thermal spray and cladding processes consume water-atomized carbon steel grades for corrosion protection and dimensional restoration.
Mature applications anchor current volume; additive manufacturing claims the steepest expansion trajectory.
End User:
Customer certification requirements and volume scale create distinct procurement patterns across buyer categories.
- Aerospace Industry:Turbine component and structural part manufacturers impose stringent chemistry and morphology specifications. GE Aviation and Rolls-Royce engine programs qualify PREP-produced titanium and nickel superalloy powders, with gas-atomized tool steel grades following parallel pathways for airframe applications.
- Automotive Manufacturers:Powder-forged transmission components face demand compression from electrification, while soft magnetic materials for electric motor cores emerge as a replacement specification. OEMs redesigning powertrain architectures around 800V systems drive sintered soft magnetic composite qualification.
- Tooling Companies:Cutting tool and die manufacturers specify high-speed steel grades for wear-resistant components.
- Medical Equipment Suppliers:Surgical instrument and implant producers require gas-atomized stainless grades with documented biocompatibility certification.
Automotive buyers dominate procurement tonnage; aerospace and medical segments capture margin concentration.
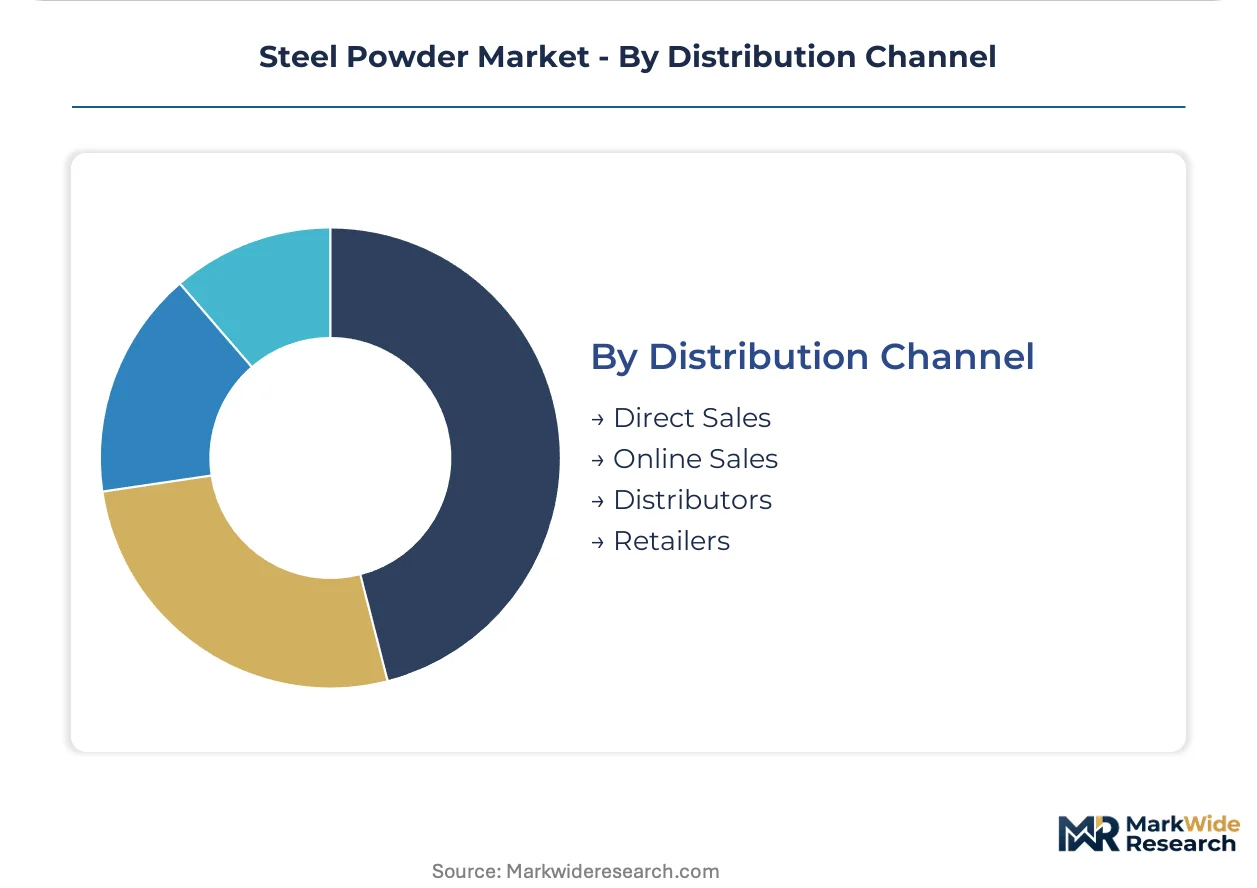
Distribution Channel:
Relationship intensity and technical service requirements shape channel selection for different buyer tiers.
- Direct Sales:Large automotive and aerospace contract manufacturers demand integrated technical service and volume commitments. Schunk and GKN Sinter Metals have reduced qualified powder suppliers by 40 percent over recent qualification cycles, consolidating procurement through direct relationships with atomization specialists.
- Distributors:Regional stockists serve tier-two powder metallurgy fabricators and job shops requiring smaller lot sizes and faster turnaround.
- Online Sales:E-commerce platforms capture prototype and research quantities for additive manufacturing users qualifying new materials.
- Retailers:Limited presence in consumer-facing welding and repair product segments.
Direct relationships control premium grade flow; distributors handle commodity volume fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dongguan anchors additive manufacturing capacity scaling for steel powder qualification, with the Pearl River Delta cluster absorbing gas-atomized tool steel shipments under MIIT industrial policy directives.
China
Domestic powder bed fusion capacity expansion concentrates demand for maraging and high-speed steel grades. MEE dual carbon goals tighten embodied carbon thresholds for atomization facilities. Shanghai and Jiangsu province production clusters prioritize renewable electricity sourcing for Scope 2 emissions compliance.
Germany
Automotive electrification compresses powder-forged transmission component orders while soft magnetic composite qualification accelerates. REACH substance registration elevates reformulation costs for die wall lubricants. Bavaria's automotive supply corridor consolidates qualified powder suppliers by 40 percent across recent qualification cycles.
United States
EPA emissions standards pull atomized steel grades into gear and bearing applications previously served by wrought steel. OSHA permissible exposure limits tighten workplace engineering controls for respirable metal dust. Pittsburgh and Cleveland production facilities deploy enclosed powder handling systems for compliance.
Japan
Medical device manufacturers expand metal injection molding adoption for surgical instrument components. METI industrial standards govern biocompatibility certification pathways for gas-atomized stainless grades. Osaka and Nagoya fabrication clusters specialize in fine spherical powders below 25 micrometers.
India
PLI scheme incentives attract powder metallurgy investments for two-wheeler and small commercial vehicle components. BIS domestic content requirements reshape supplier qualification timelines. Pune and Chennai manufacturing corridors create early-mover positioning for qualified atomized grade suppliers.
Steel Powder Market Competitive Landscape
Premium-margin players sit above commodity-margin players across atomization technology tiers, with gas-atomized spherical grades commanding aerospace qualification premiums while water-atomized carbon steel competes on scrap-input efficiency. The vendor base separates into integrated atomization specialists, regional reduced-iron producers, and materials-science conglomerates with powder divisions. Three archetypes dominate: captive supply integrators serving internal component fabrication, independent atomization houses selling qualified grades to external buyers, and trading entities aggregating commodity lots for job shops. M&A consolidation among tier-two fabricators compresses supplier bases, while capacity expansion in China concentrates high-purity gas-atomized output within domestic additive manufacturing clusters.
Among European integrated specialists, Höganäs AB and Sandvik AB occupy positions spanning premium-grade portfolios. Höganäs AB exemplifies the captive-network archetype with atomization assets positioned for additive manufacturing qualification. Sandvik AB anchors the gas-atomized stainless segment serving medical and aerospace supply chains. Carpenter Technology Corporation represents North American specialty alloy positioning for turbine and airframe applications. These three entities illustrate how geographic clustering around regulatory jurisdictions—REACH in Europe, EPA and FAA in the United States—shapes competitive differentiation more than scale alone.
| Leading Market Players |
|---|
| Höganäs AB |
| Sandvik AB |
| Carpenter Technology Corporation |
| GKN Powder Metallurgy |
| Daido Steel |
| Mitsubishi Steel Manufacturing |
| Rio Tinto Metal Powders |
| BASF |
| Evonik Industries |
| Others |
Value Network & Pricing Analysis
Aerospace and medical device OEMs concentrate procurement of qualified gas-atomized grades, anchoring value-based pricing models that tie powder premiums to 18-24 month certification timelines and lot-to-lot consistency guarantees rather than raw material input costs.
Pricing Analysis
Aerospace qualification premiums anchor value-based pricing, with maraging and tool steel grades commanding substantial markups tied to documented sphericity and satellite-free morphology. Price differentiation separates PREP-produced superalloy lots from plasma-atomized alternatives, while water-atomized carbon steel competes on scrap-input efficiency. Cost compression in commodity reduced-iron grades intensifies as electric arc furnace feedstock volatility squeezes water-atomization margins. Automotive powder-forged component manufacturers exhibit highest price sensitivity, whereas additive manufacturing users prioritize batch certification over unit cost.
Supply Chain Analysis
Freight costs for spherical powder shipments from European atomization facilities to China's eastern seaboard additive manufacturing clusters elevate landed costs substantially, favoring domestic Chinese capacity expansion under MIIT directives. Supply concentrates in Sweden, Germany, and China for high-purity gas-atomized grades, while water-atomized carbon steel production draws from regional scrap markets in the US, Japan, and India. Single-source vulnerability persists for aerospace-qualified PREP titanium and nickel superalloy lots. Distribution runs through direct technical-service relationships with tier-one automotive and aerospace contract manufacturers, with regional distributors handling job-shop fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Limited European and North American production facilities for aerospace-qualified gas-atomized grades prop pricing premiums, constraining supply elasticity against surging additive manufacturing demand.
For Market Incumbents: Hedge against aluminum-magnesium substitution in automotive structural brackets by accelerating soft magnetic composite qualification for 800V electric motor cores. Secure backward integration into renewable electricity sourcing for Scope 2 emissions compliance under EU carbon border adjustments. Prioritize enclosed powder handling system deployment ahead of OSHA permissible exposure limit tightening. For New Entrants and Emerging Players: The premium-to-economy price gap in gas-atomized stainless grades offers white-space positioning for medical device MIM feedstock supply. Target India's PLI scheme corridor for two-wheeler powder metallurgy components, where BIS domestic content requirements reshape supplier qualification timelines. Pursue synthetic wax die lubricant qualification ahead of REACH stearate reformulation deadlines. For Investors and Strategic Acquirers: The window for entry favors integrated atomization specialists with captive additive manufacturing qualification networks over commodity reduced-iron traders. Long-term viability rests on documentation capabilities for Scope 2 emissions and SVHC compliance. Monitor PREP technology adoption rates at GE Aviation and Rolls-Royce as inflection signal for plasma atomization displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Domestic Chinese atomization facilities absorb MIIT-directed additive manufacturing demand growth. |
| Backward Integration | Renewable electricity sourcing secures EU Green Deal carbon border adjustment compliance. |
| Long-term Supply Agreement | Volume commitments from Schunk and GKN Sinter Metals consolidate supplier base reduction. |
| Joint Venture | Pearl River Delta partnerships localize gas-atomized tool steel qualification for powder bed fusion. |
| Green Certification Program | Documented Scope 2 emissions reductions differentiate atomized grades in EU procurement. |
Research Methodology
Document review covered trade customs data, SEC filings from specialty alloy producers, and ECHA REACH substance registrations, complemented by interviews with atomization plant managers, powder metallurgy procurement leads at tier-one automotive suppliers, additive manufacturing feedstock specialists, and medical device MIM engineers. Secondary validation drew from MIIT industrial policy directives, EPA emissions standards documentation, and OECD steel trade statistics. Bottom-up capacity assessments triangulated against top-down demand modeling from end-use segment projections.
Segmented outputs across atomization method, powder grade chemistry, downstream application, and end-user industry fed into elasticity-adjusted demand curves. CAGRs derived from regression against automotive electrification penetration rates, additive manufacturing equipment install bases, and regulatory compliance cost trajectories. Scrap price volatility indices and renewable electricity cost curves informed input cost sensitivity bands.
Inputs from primary interview sources were available through the study window; gaps in real-time aerospace qualification timeline data introduce uncertainty bands around additive manufacturing demand acceleration scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Nickel Mining Market
Metals & Minerals
Global Magnesium Hydroxide Market
Metals & Minerals
Andalusite Market
Metals & Minerals
Chromium Mining Market
Metals & Minerals
Testing Inspection and Certification TIC for the Metals and Minerals Market
Metals & Minerals
Metal and Metal Ores Market
Metals & Minerals
Silver Mining Market
Metals & Minerals
Recycled Steel Market
Metals & Minerals
Cobalt Nitrate Market
Metals & Minerals
US Lithium Market
Metals & Minerals
Beryllium Hydroxide Market
Metals & Minerals
Pre-Painted Galvanised Iron (PPGI) Market
Metals & Minerals
Gemstones Market
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
Sapphire Mining Market
Metals & Minerals
Selenium Market