
 Silver Salt Market | 2026-2036
Silver Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Silver Salt Market Analytics
Specialty chemical distribution networks are reconfiguring around silver salt procurement, with regional distributors consolidating inventory positions to serve electronics and pharmaceutical buyers. Heraeus Holding GmbH leverages its precious metals refining heritage to sustain captive supply advantages across European markets. Johnson Matthey Plc anchors its position through backward integration into silver recovery and refining operations. American Elements competes on catalog breadth, offering spec-grade silver salts for research institutions with rapid fulfillment.
Silver salts comprise ionic compounds formed between silver and halide or carboxylate anions, typically precipitated from aqueous silver nitrate solutions and characterized by photosensitivity, antimicrobial activity, or catalytic function depending on the counterion. Silver bromide and silver chloride retain dominant positions in photographic and medical imaging applications, though this segment matures as digital technologies displace film-based systems. Silver acetate and silver iodide command premium positioning in electronics and chemical synthesis, where purity thresholds above 99.9% create margin pools for specialized producers serving semiconductor and pharmaceutical end users.
FDA purity standards for pharmaceutical-grade silver compounds, EPA discharge limits on silver-bearing industrial effluents, and China's GB standards for electronic materials collectively shape product specifications and market access conditions for producers. REACH registration requirements in Europe further constrain entry for non-compliant suppliers, consolidating demand around established registrants with full toxicological dossiers. Stakeholders must monitor regulatory divergence between jurisdictions, as tightening environmental thresholds in one region create competitive displacement opportunities for compliant producers elsewhere.
Market Dynamics
Digital radiography is compressing silver bromide consumption in medical imaging while antimicrobial coating mandates in healthcare facilities and electronics manufacturing are redirecting procurement toward silver acetate and silver nitrate derivatives with higher purity specifications.
Growth Catalysts
- Healthcare antimicrobial mandates:Hospital-acquired infection protocols in Germany and Japan now specify silver-ion coatings for catheter and implantable device surfaces, pulling pharmaceutical-grade silver salts into medical device supply chains.
- REACH registration consolidation:Full toxicological dossier requirements under ECHA registration processes have eliminated non-compliant European suppliers, concentrating demand among established registrants with proven purity documentation.
- Semiconductor packaging chemistry:Silver sintering pastes for power electronics and thermal interface materials in electric vehicle inverters require sub-ppm impurity thresholds that only specialized salt refiners can satisfy.
Market Restraints
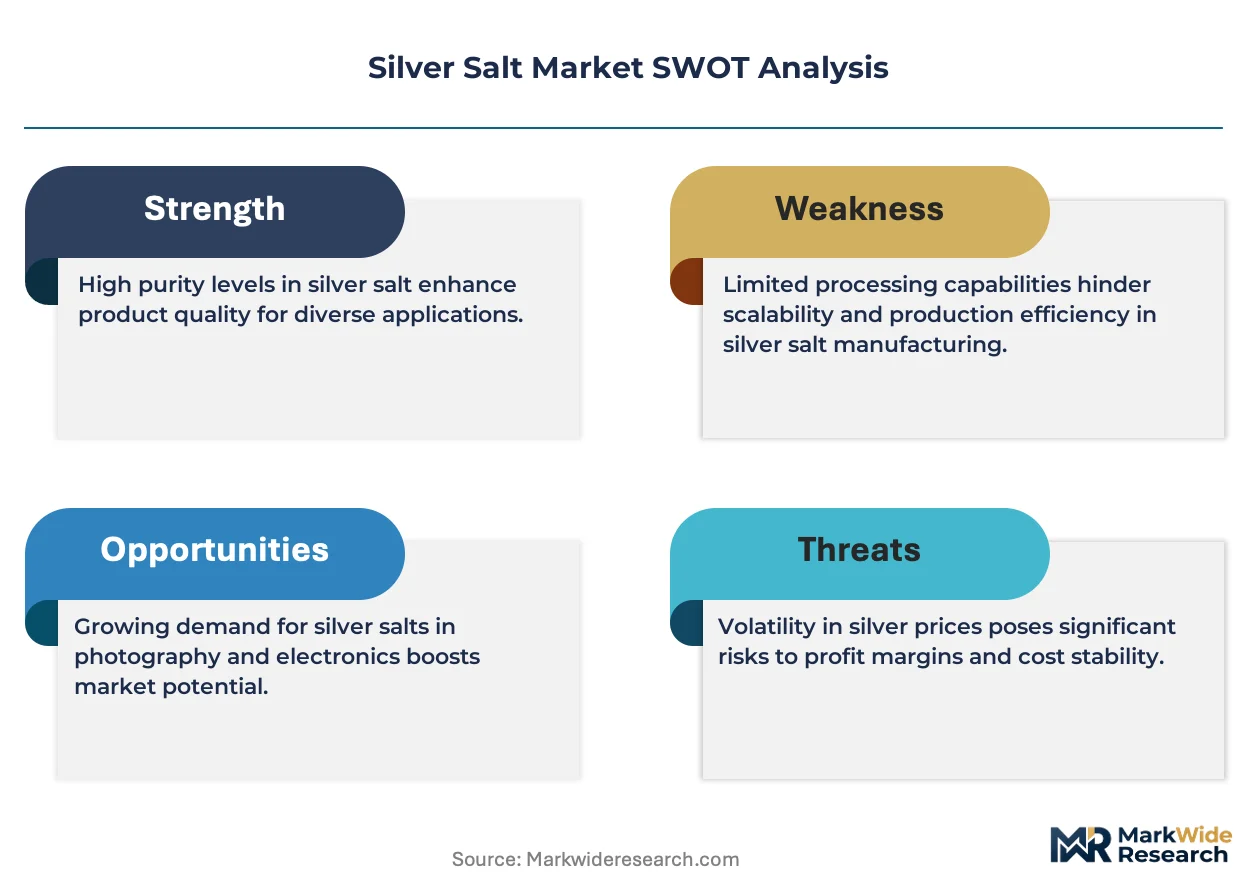
- Silver price volatility:London Bullion Market Association spot price swings above fifteen percent annually compress margin predictability for salt processors locked into six-month pharmaceutical supply contracts.
- Photographic film collapse:Kodak and Fujifilm production facility closures across Rochester and Kanagawa have eliminated a century-old demand anchor for silver halide crystals, forcing capacity reallocation.
- EPA effluent thresholds:Silver discharge limits in electroplating wastewater now require zero-liquid-discharge systems that add capital intensity for mid-scale producers serving industrial coating markets.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO accelerated approval pathways for generic active pharmaceutical ingredients create import substitution openings for silver salt suppliers to domestic formulation houses in Hyderabad and Ahmedabad.
- Wound care biologics integration:Silver sulfadiazine incorporation into hydrogel matrices for chronic wound management represents a formulation innovation channel distinct from commodity salt sales.
- EU Green Deal chemistry:Sustainable process certification under EU taxonomy criteria rewards producers with aqueous-phase precipitation methods versus solvent-intensive legacy synthesis routes.
Industry Challenges
- Pharmacopeial certification timelines:USP and EP monograph compliance for new silver salt grades requires eighteen-to-twenty-four month validation cycles that delay revenue recognition on qualified pharmaceutical sales.
- Analytical chemistry talent scarcity:ICP-MS and XRF spectroscopy expertise for sub-ppm trace metal analysis concentrates in precious metals refiners, constraining quality control expansion at independent salt processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silver Salt Market |
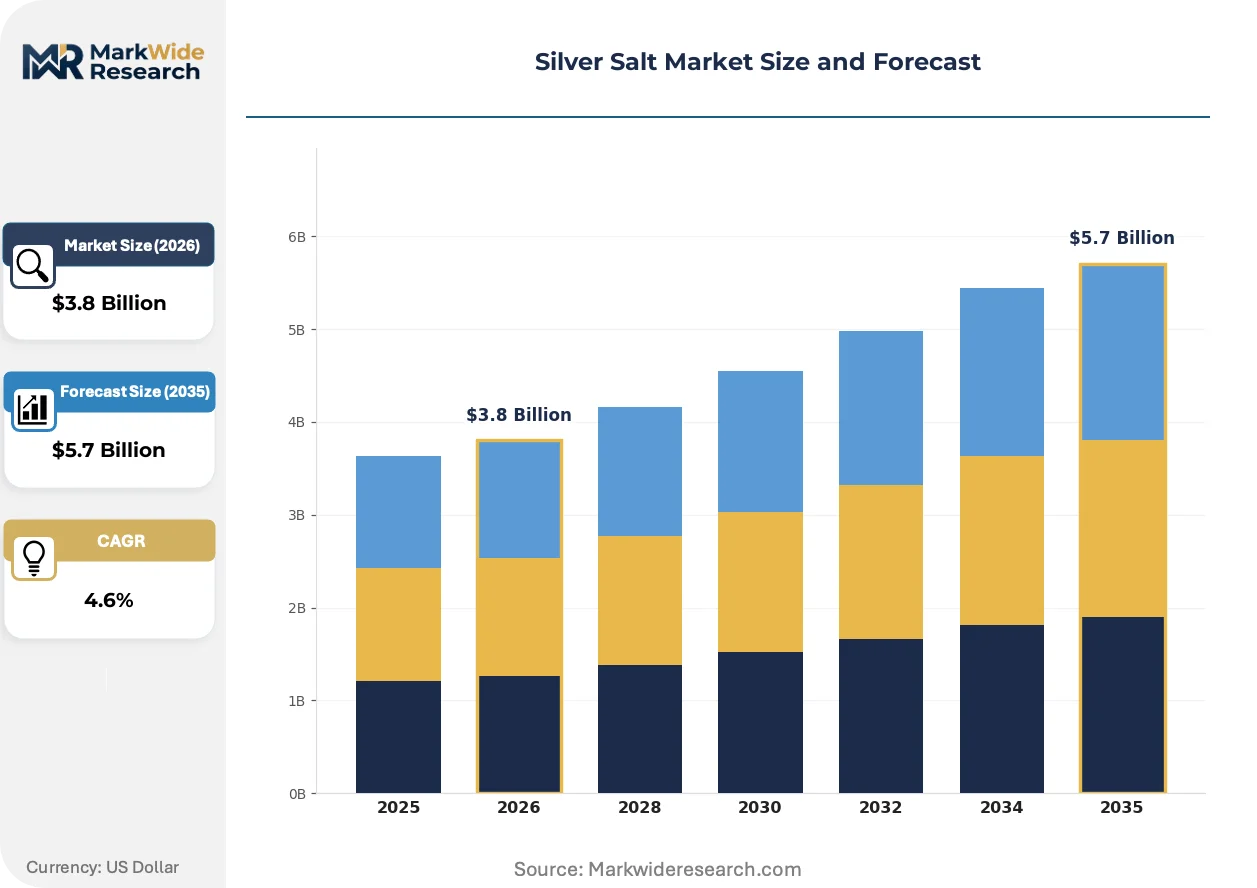
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver Chloride, Silver Bromide, Silver Iodide, Silver Acetate Application: Photography, Medicine, Electronics, Chemical Synthesis End User: Healthcare, Photographic Industries, Electronics Manufacturers, Research Institutions Packaging Type: Bulk, Small Bags, Bottles, Sachets |
| Companies Covered | ALFA AESAR, Metalor Technologies, Heraeus Holding GmbH, Strem Chemicals Inc., Ames Goldsmith Corp, Johnson Matthey Plc, Texchem Industries, Haihang Industry (Jinan) Co. Ltd, American Elements, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silver Salt Market Evolving Landscape
Process intensification and regulatory chemistry are reshaping how silver salts move from refined bullion to specification-grade materials, with purity verification and sustainable synthesis becoming order-qualifying capabilities rather than differentiators.
Electrochemical silver recovery from spent photographic and electronics waste streams is migrating from batch tank operations to continuous membrane cell architectures. Urban mining operators in Belgium and South Korea now deploy these systems to produce 99.99% pure silver feedstock for salt precipitation without virgin mining exposure. This closed-loop metal sourcing is compressing the carbon footprint claims available to downstream salt processors serving sustainability-scored pharmaceutical buyers.
REACH Annex XIV authorization requirements for silver compounds used in biocidal applications now demand substitution analysis and socioeconomic justification dossiers. ECHA's 2024 updated guidance on nanosilver classification has forced reformulation of colloidal silver products toward ionic salt alternatives. Medical device manufacturers in Ireland and the Netherlands are responding by qualifying silver acetate and silver citrate complexes that avoid the nano threshold while retaining antimicrobial efficacy claims.
Specification-driven procurement now dominates pharmaceutical and semiconductor buyer behavior, with certificates of analysis and batch-specific ICP-MS data replacing spot-buying on catalog grades. Distributors in the specialty chemical channel are consolidating inventory positions around silver nitrate, silver acetate, and silver trifluoroacetate SKUs with guaranteed 99.9%+ purity and documented trace metal profiles. This consolidation is most visible in the Boston-Cambridge biotech cluster and Basel pharmaceutical corridor, where qualified supplier lists now exclude uncertified salt sources regardless of price position.
Silver Salt Market Segmentation
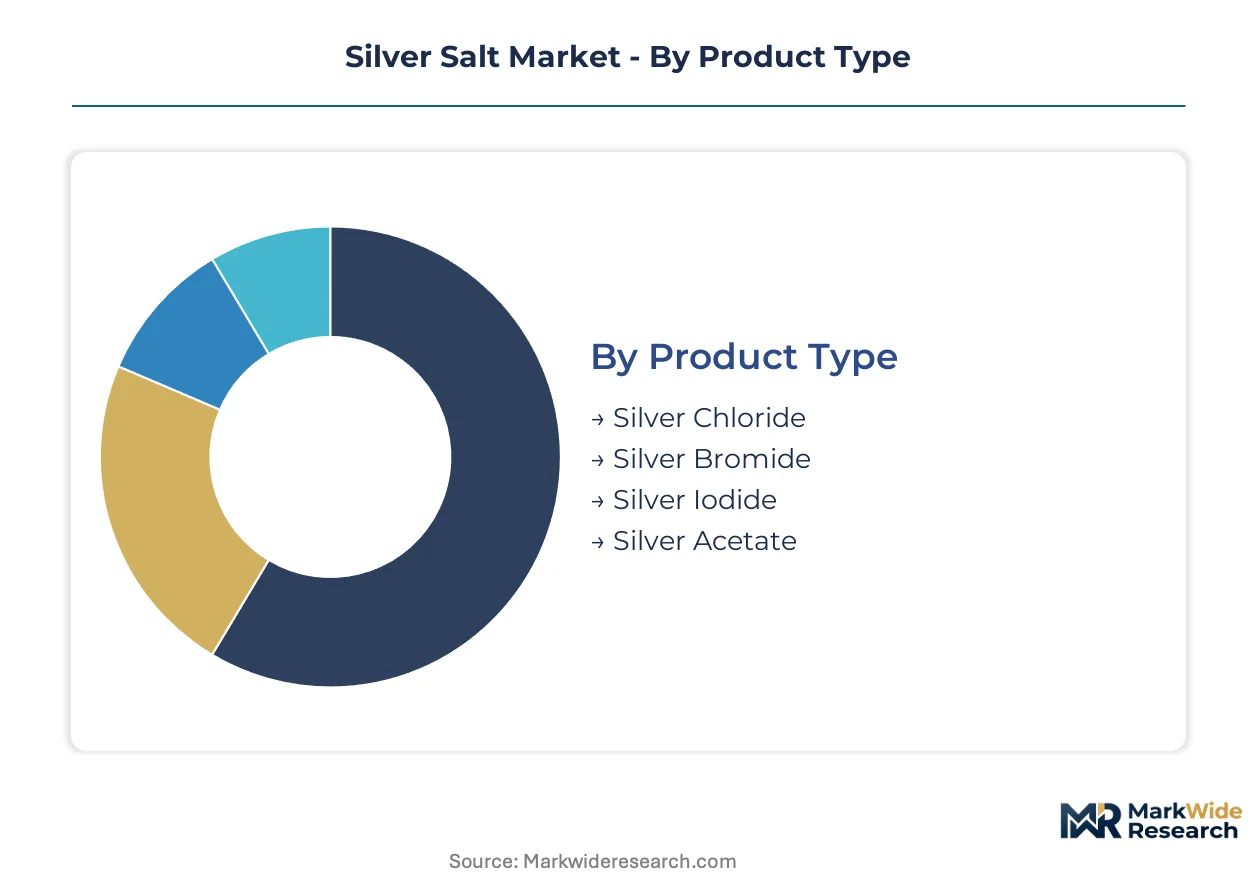
Silver salt procurement patterns diverge sharply across end-use specifications, with pharmaceutical buyers demanding pharmacopeial certification and electronics manufacturers prioritizing sub-ppm trace metal documentation. Understanding these segment boundaries clarifies why pricing spreads between commodity and specification-grade materials now exceed traditional commodity premiums.
Product Type:
After-sales service intensity concentrates in silver acetate and silver iodide, where pharmaceutical and semiconductor buyers require batch-specific analytical support and regulatory documentation updates.
- Silver Acetate:Carboxylate salt precipitated from silver nitrate and acetic acid, typically specified at 99.9%+ purity with documented trace metal profiles. Demand concentrates in Basel and Boston-Cambridge pharmaceutical corridors, where CDSCO and FDA submission packages require consistent batch certification.
- Silver Iodide:Halide compound with exceptional photosensitivity and antimicrobial release kinetics. Electronics manufacturers in Dresden and Hsinchu specify this grade for thermal interface materials in power semiconductor packaging, driven by electric vehicle inverter procurement.
- Silver Chloride:Precipitated halide retaining residual demand in electrochemical sensors and reference electrodes.
- Silver Bromide:Photographic-grade halide experiencing demand compression as medical imaging digitizes.
By volume, silver bromide leads from legacy photographic stockpiles. By growth pace, silver acetate is ahead.
Application:
Margin structures stratify across application tiers, with chemical synthesis commanding premium pricing for custom specifications and photography collapsing toward commodity clearing levels.
- Medicine:Antimicrobial coatings for catheters and implantable devices, plus silver sulfadiazine formulations for wound care. German hospital-acquired infection protocols and Japan's medical device reimbursement categories are pulling pharmaceutical-grade salts into device supply chains with mandatory purity thresholds.
- Electronics:Silver sintering pastes for power module packaging and conductive adhesives for semiconductor assembly. Taiwan and South Korea packaging houses now require REACH-compliant documentation with full toxicological dossiers for EU-exported components.
- Chemical Synthesis:Catalytic applications in organic transformation and specialty intermediate production.
- Photography:Film emulsion manufacturing now concentrated in niche archival and industrial radiography segments.
Electronics applications are expanding most quickly as automotive electrification multiplies power module demand. Medicine maintains the steepest pricing gradient per kilogram.
End User:
Customer type determines procurement channel configuration, with research institutions buying through distributor catalogs and healthcare systems negotiating direct supply agreements with qualified manufacturer lists.
- Healthcare:Hospital systems and medical device OEMs purchasing antimicrobial coatings and wound care formulations. FDA purity standards and EPA discharge limits shape supplier qualification, with eighteen-to-twenty-four month USP monograph compliance cycles delaying new vendor entry.
- Electronics Manufacturers:Semiconductor packaging houses and PCB fabricators specifying silver salts for conductive pastes and plating baths. China's GB standards for electronic materials and REACH registration requirements in Europe consolidate demand around established registrants.
- Research Institutions:Universities and national laboratories procuring catalog-grade materials for experimental protocols.
- Photographic Industries:Residual film processors and specialty emulsion manufacturers.
Healthcare buyers dominate value capture. Electronics manufacturers are gaining share fastest as power semiconductor packaging scales.
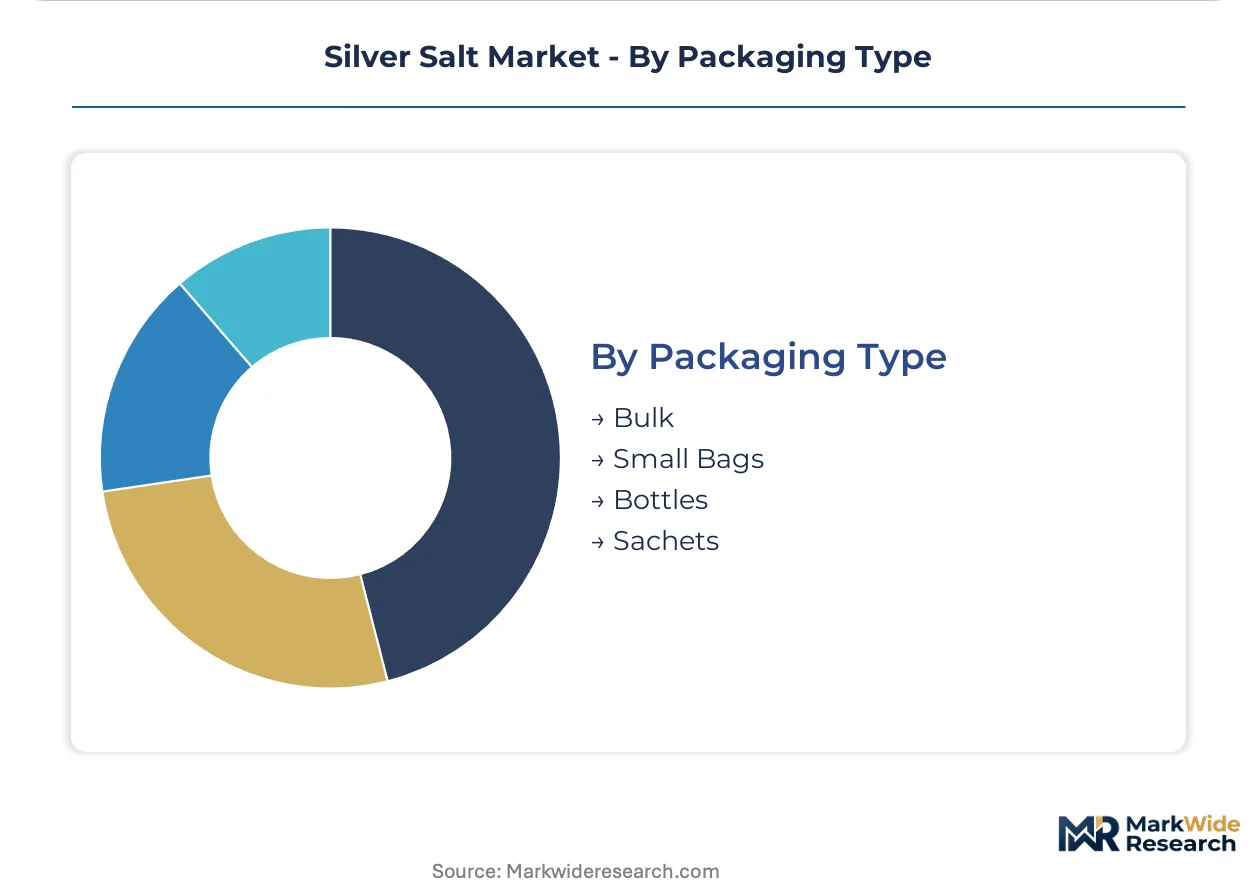
Packaging Type:
Volume scale and handling protocols determine packaging selection, with bulk shipments serving electroplating operations and single-use sachets preventing cross-contamination in pharmaceutical cleanrooms.
- Bulk:Industrial-scale containers for electroplating baths and chemical synthesis operations. EPA effluent thresholds on silver-bearing wastewater now require zero-liquid-discharge systems at receiving facilities, adding capital intensity that favors larger volume commitments.
- Bottles:Laboratory and pilot-scale procurement for research institutions and formulation development.
- Small Bags:Intermediate quantities for specialty chemical distributors serving mid-scale pharmaceutical manufacturers.
- Sachets:Single-dose packaging for point-of-use antimicrobial applications and field-deployable medical kits.
Bulk packaging dominates tonnage movements. Sachet formats are climbing the fastest as decentralized healthcare delivery expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in specification-grade silver salts concentrates in Basel and Boston-Cambridge corridors, while East Asian electronics clusters compete on volume scale and purity documentation speed.
United States
FDA pharmaceutical-grade certification requirements and EPA effluent discharge limits shape procurement for medical device OEMs. Hospital-acquired infection protocols in Massachusetts and California pull silver acetate into catheter coating supply chains. The Boston-Cambridge biotech cluster dominates specification-driven purchasing with mandatory USP monograph compliance.
Germany
REACH registration dossiers and ECHA biocidal authorization requirements consolidate demand among established European registrants. German hospital reimbursement categories now mandate silver-ion coatings for implantable devices. The Rhine-Main industrial corridor anchors precious metals refining capacity serving pharmaceutical-grade salt production.
China
GB standards for electronic materials and NMPA pharmaceutical regulations tighten purity thresholds for semiconductor and medical applications. Yangtze River Delta packaging houses specify sub-ppm impurity silver salts for power module sintering. Shenzhen and Suzhou electronics clusters drive procurement volume for silver iodide thermal interface materials.
Japan
METI industrial standards and PMDA pharmaceutical regulations govern silver salt specifications for domestic device manufacturers. Japanese medical device reimbursement categories incentivize antimicrobial coating adoption. The Kanagawa and Osaka industrial belts concentrate demand for high-purity silver acetate in electronics assembly.
India
CDSCO accelerated approval pathways for generic active pharmaceutical ingredients create import substitution openings for domestic salt suppliers. BIS standards for electronic materials are converging with REACH documentation requirements. Hyderabad and Ahmedabad formulation houses are qualifying new silver sulfadiazine sources for wound care applications.
Silver Salt Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in precious metals refining and specification chemistry. The vendor base stratifies across three tiers: integrated precious metals refiners with captive salt production, independent specialty chemical processors, and catalog distributors serving research institutions. Consolidation pressure operates through REACH registration barriers and pharmacopeial certification timelines. Dominant competitive moves include backward integration into silver recovery operations and geographic expansion into Indian pharmaceutical manufacturing corridors.
Within the integrated refiner archetype, Heraeus Holding GmbH and Johnson Matthey Plc exemplify European precious metals heritage translated into specification-grade salt dominance. American Elements occupies a position in rapid-fulfillment catalog distribution for research institutions. These three anchors illustrate how competitive positioning splits between documentation-heavy pharmaceutical supply and speed-oriented research procurement.
| Leading Market Players |
|---|
| ALFA AESAR |
| Metalor Technologies |
| Heraeus Holding GmbH |
| Strem Chemicals Inc. |
| Ames Goldsmith Corp |
| Johnson Matthey Plc |
| Texchem Industries |
| Haihang Industry (Jinan) Co. Ltd |
| American Elements |
| Others |
Value Network & Pricing Analysis
The Rhine-Main industrial corridor anchors European precious metals refining capacity, and its captive silver recovery operations translate directly into pricing power for pharmaceutical-grade salt processors serving Basel and Boston-Cambridge buyers. This geographic concentration of specification chemistry expertise creates margin pools that mid-scale competitors cannot replicate without eighteen-to-twenty-four month USP monograph compliance investments.
Pricing Analysis
Configured-to-order pricing for silver acetate and silver iodide with documented ICP-MS trace metal profiles commands spreads of three-to-five times standard catalog grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and batch-specific analytical support. Cost compression in photographic-grade silver bromide is intensifying because Kodak and Fujifilm facility closures have collapsed legacy demand anchors into commodity clearing levels. Research institutions exhibit highest price sensitivity, while semiconductor packaging houses prioritize purity documentation over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for electronics-grade silver salts. Production gravity centers on Germany, China, and Japan, with each hub feeding distinct regulatory compliance requirements. Raw material dependencies include London Bullion Market Association silver feedstock, acetic acid for carboxylate precipitation, and iodine for halide synthesis. Distribution runs through specialty chemical distributors consolidating inventory positions around qualified SKUs in the Boston-Cambridge and Basel corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a regulatory entrenchment story. REACH registration dossiers and USP monograph compliance cycles create switching costs that lock pharmaceutical buyers into established supplier relationships.
For Market Incumbents: Pre-empt emerging Indian pharmaceutical manufacturing competition by accelerating CDSCO submission packages for Hyderabad and Ahmedabad formulation houses. Secure backward integration into urban mining silver recovery operations in Belgium and South Korea to compress carbon footprint claims for sustainability-scored buyers. Capacity addition in the Yangtze River Delta serves Taiwan and South Korea packaging houses requiring REACH-compliant documentation for EU-exported components. For New Entrants and Emerging Players: Pursue wound care biologics integration as the most penetrable white-space channel, specifically silver sulfadiazine incorporation into hydrogel matrices for chronic wound management. Target research institution procurement through rapid-fulfillment catalog distribution with guaranteed 99.9%+ purity and documented trace metal profiles. Qualify silver citrate complexes as nano-threshold alternatives for Irish and Dutch medical device manufacturers reformulating under ECHA's updated nanosilver classification guidance. For Investors and Strategic Acquirers: Long-term, this sits as a specialty chemical consolidation play because REACH registration barriers and pharmacopeial certification timelines constrain organic entry. Acquisition targets should display integrated precious metals refining heritage with captive salt production and full toxicological dossiers. Watch for silver price volatility above fifteen percent annually as the signal for margin compression stress at mid-scale processors locked into fixed pharmaceutical supply contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver Recovery | Urban mining operators in Belgium and South Korea now deploy continuous membrane cell architectures to produce 99.99% pure silver feedstock without virgin mining exposure. |
| Pharmacopeial Certification Investment | USP and EP monograph compliance for new silver salt grades requires eighteen-to-twenty-four month validation cycles that delay revenue recognition on qualified pharmaceutical sales. |
| Geographic Expansion into Indian Pharmaceutical Corridors | CDSCO accelerated approval pathways for generic active pharmaceutical ingredients create import substitution openings for domestic salt suppliers to Hyderabad and Ahmedabad formulation houses. |
| Green Manufacturing Transition | Sustainable process certification under EU taxonomy criteria rewards producers with aqueous-phase precipitation methods versus solvent-intensive legacy synthesis routes. |
| Long-term Supply Agreement with Semiconductor Packaging Houses | Taiwan and South Korea packaging houses now require REACH-compliant documentation with full toxicological dossiers for EU-exported power electronics components. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with precious metals refiners, pharmaceutical procurement managers, semiconductor packaging engineers, and specialty chemical distributors; and secondary validation through customs and trade data, SEC 10-K filings, ECHA registration databases, and USP monograph documentation. Bottom-up triangulation against top-down market sizing cross-checked volume estimates across silver salt grades and end-use applications.
Forecast inputs include grade tier, end-use industry, packaging format, and regional production hub segmentation modeled across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating silver price volatility, regulatory compliance timeline compression, and automotive electrification multipliers for power module procurement. Industry-specific forecast inputs include ICP-MS spectroscopy capacity expansion rates and REACH Annex XIV authorization pipeline status.
Macroeconomic conditions sit as an overlay; deviation in London Bullion Market Association silver spot prices, EPA effluent threshold enforcement intensity, or EU Green Deal chemistry certification pace would shift the trajectory. Forecasts reflect documented assumptions regarding pharmacopeial certification timeline stability and semiconductor packaging chemistry specification evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Laminated Steel Market
Metals & Minerals
Moissanite Market
Metals & Minerals
Nickel Mining Market
Metals & Minerals
Zinc Sulfate Market
Metals & Minerals
Dead Sea Mineral Market
Metals & Minerals
Middle-East and Africa Lithium Market
Metals & Minerals
Pyroxenite Market
Metals & Minerals
Zellerite Market
Metals & Minerals
Recycled Antimony Market
Metals & Minerals
Hot Briquetted Iron (HBI) Market
Metals & Minerals
Frac Sand Market
Metals & Minerals
Mineral Ingredients Market
Metals & Minerals
Global Mining Metals Market
Metals & Minerals
Zinc Hydroxide Market
Metals & Minerals
Recycled Lead Market
Metals & Minerals
Sodium Tungstate Market