
 Audio and Video Analytics Software Market | 2026-2036
Audio and Video Analytics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Audio and Video Analytics Software Market Outlook
Edge-native inference is tilting software architecture toward on-device processing, reducing cloud egress costs for enterprise deployments. Genetec anchors its position through deep channel control across North American physical security integrators. Milestone Systems differentiates via open-platform interoperability, sustaining developer ecosystem loyalty. Gorilla Technology leverages edge computing specialization to compete in Asia-Pacific smart city tenders.
Audio and video analytics software processes streaming media through machine learning pipelines to extract actionable metadata—enabling automated object detection, acoustic event classification, and behavioral pattern recognition at frame rates exceeding thirty per second. Cloud-based deployment dominates enterprise accounts seeking elastic compute scaling, though edge computing represents the fastest-growing architecture as latency-sensitive use cases expand. Surveillance applications command the largest revenue pool among application segments, while sports analytics attracts premium pricing from broadcast rights holders demanding real-time player tracking.
FDA oversight of diagnostic imaging analytics and FCC rules on broadband infrastructure quality shape product compliance requirements for healthcare and telecommunications verticals respectively. The EU AI Act's risk-based classification system forces vendors to document training data provenance and algorithmic transparency for biometric identification functions. Stakeholders must monitor evolving data sovereignty mandates across jurisdictions to determine localization investment priorities.
Market Dynamics
Edge-native inference architectures are compressing latency budgets and forcing vendors to rebuild software stacks for heterogeneous silicon, while the EU AI Act's conformity requirements redirect R&D spending toward documentation and auditability systems.
Growth Catalysts
- Smart city surveillance mandates:Law enforcement agencies in India, Singapore, and the United Arab Emirates now specify real-time behavioral analytics in municipal tenders, accelerating platform procurement cycles.
- EU AI Act high-risk system classification:Automated biometric identification functions face mandatory conformity assessments, creating certified-vendor advantages in European public sector procurement.
- GPU-NPU heterogeneous compute:On-device inference pipelines now execute on combined graphics and neural processing units, slashing cloud egress fees for enterprise video security deployments.
Market Restraints
- Training data localization costs:India's BIS data sovereignty requirements force redundant infrastructure deployment, inflating operational expenditure for foreign platform vendors.
- Edge silicon supply concentration:Taiwan-based foundries fabricate over 90 percent of advanced NPU wafers, exposing analytics software vendors to geopolitical supply interruptions.
- Algorithmic transparency documentation:The EU AI Act mandates training data provenance records that many legacy machine learning pipelines cannot reconstruct retroactively.
Strategic Opportunities
- Healthcare diagnostic imaging:FDA-cleared radiology analytics modules command premium pricing from hospital systems seeking automated lesion detection in CT and MRI workflows.
- 5G network slicing:Telecommunications carriers in South Korea and Germany deploy guaranteed-latency slices for industrial video analytics, opening subscription revenue models.
- Sports broadcast rights monetization:Real-time player tracking and automated highlight generation attract premium licensing fees from rights holders covering football, basketball, and cricket leagues.
Industry Challenges
- Embedded systems firmware integration:Analytics software vendors must port machine learning runtimes to proprietary camera SoC architectures with limited memory and thermal envelopes.
- Cross-border model retraining:Facial recognition algorithms trained on European datasets degrade accuracy on South Asian populations, forcing jurisdiction-specific model refinement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audio and Video Analytics Software Market |
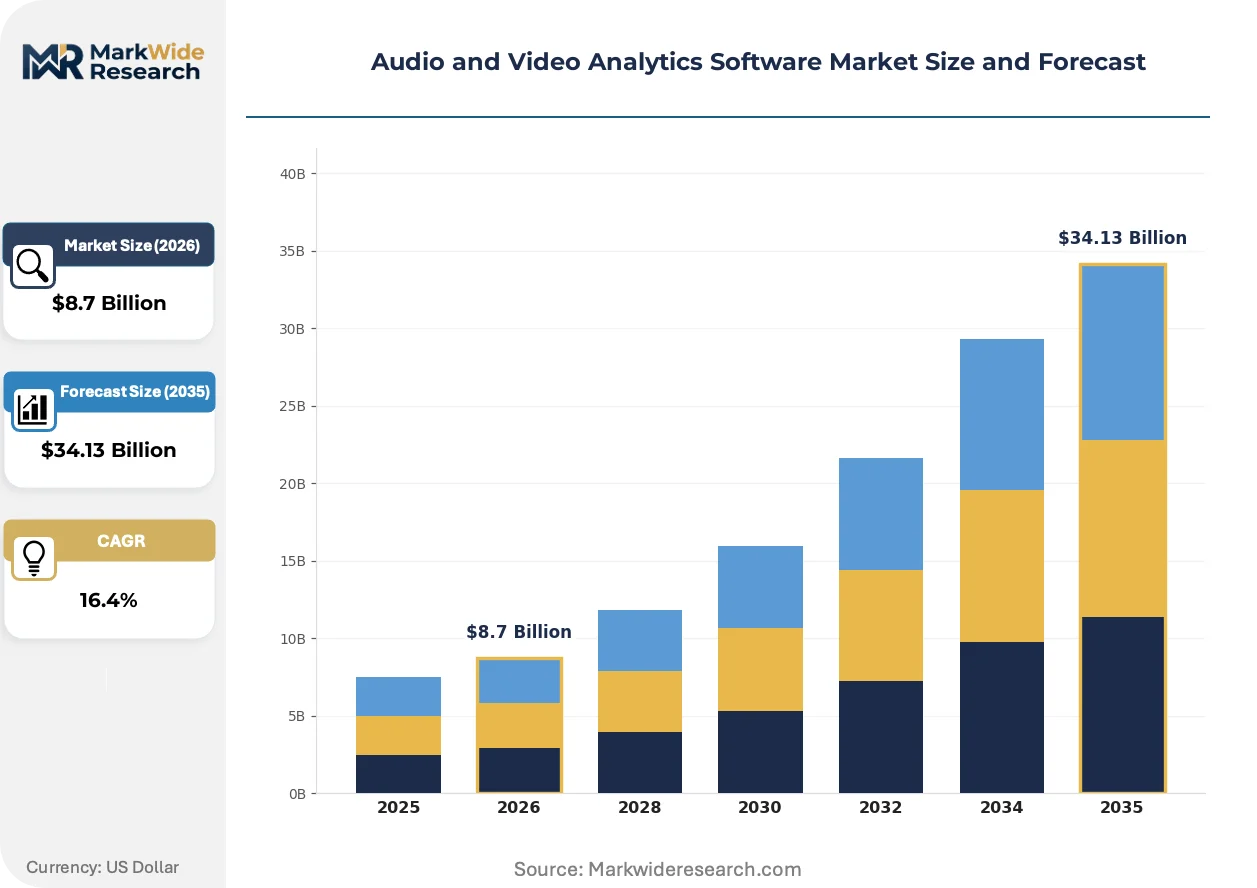
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Edge Computing Application: Surveillance, Marketing Analytics, Sports Analytics, Quality Assurance End User: Entertainment, Retail, Security, Education Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Local Hosting |
| Companies Covered | Intellivision, Irisity AB, Milestone Systems, Rhombus Systems, Digital Watchdog, Genetec, Gorilla Technology, Coram, Eagle Eye Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audio and Video Analytics Software Market Strategic Shifts
Software architecture decisions now pivot on inference location economics, while regulatory documentation requirements reshape product development roadmaps and procurement evaluation criteria.
Transformer-based video understanding models are migrating from cloud-only deployment to quantized edge variants that execute on 15-watt embedded accelerators. Retail loss prevention teams and industrial safety officers now pilot these compressed architectures for sub-100-millisecond anomaly detection. This compression is migrating from experimental deployments to production specifications in municipal traffic management systems.
The EU AI Act's risk-based classification system imposes mandatory human oversight interfaces on biometric identification functions deployed in public spaces. Vendors must now engineer real-time intervention capabilities and algorithmic explanation modules that satisfy notified body assessment protocols. European law enforcement procurement frameworks now exclude non-conforming platforms from smart city tender shortlists.
Subscription pricing for video analytics platforms displaces perpetual license models as dominant commercial structure among North American enterprise security buyers. Systems integrators now bundle edge hardware, software licenses, and managed detection services into unified monthly fees. This restructuring concentrates most visibly in healthcare campus and critical infrastructure verticals where capital expenditure constraints favor operational expenditure treatment.
Audio and Video Analytics Software Market Segmentation
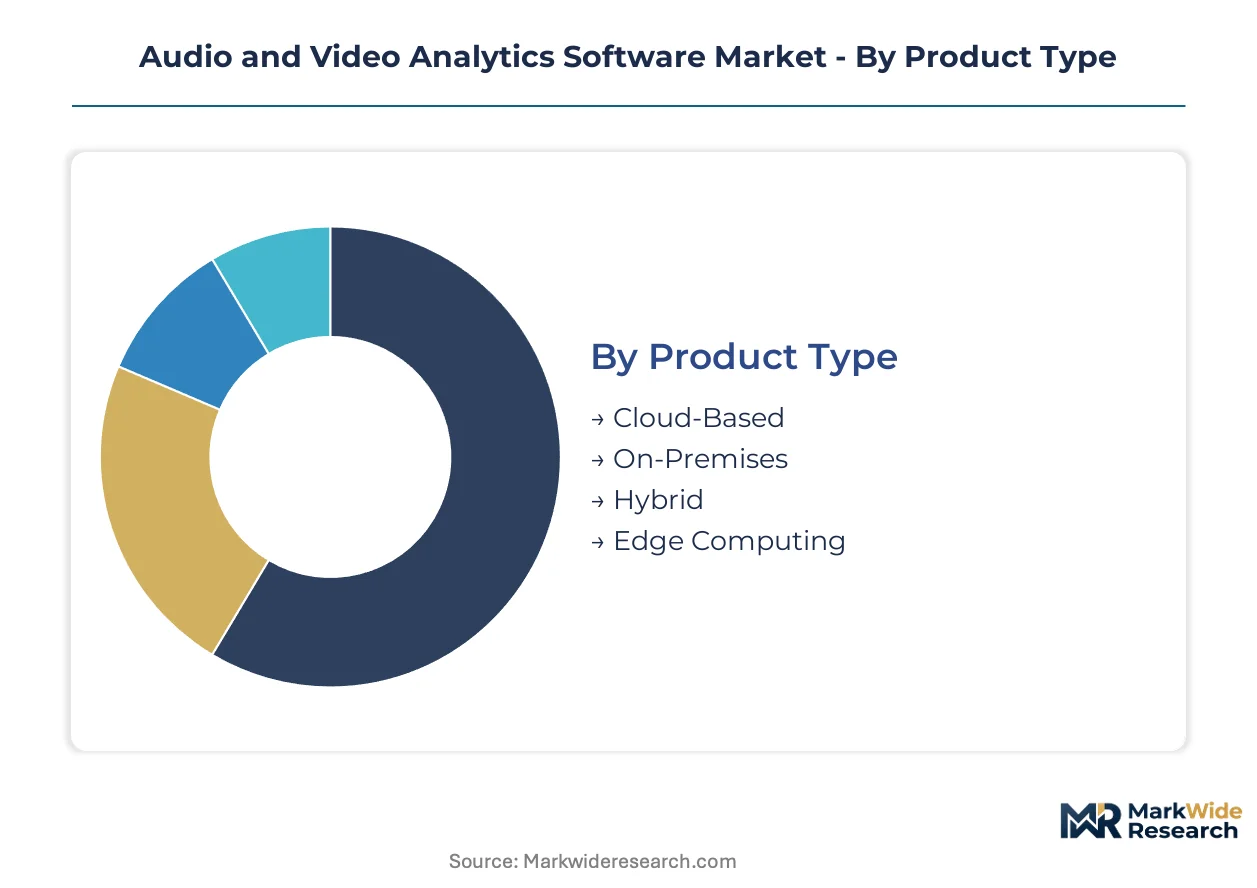
Segmentation in audio and video analytics software reveals divergent procurement rhythms across deployment architectures and end-use verticals. Cloud-based solutions refresh on 12-18 month subscription cycles while edge-native deployments lock in 5-7 year hardware-software bundles. Understanding these velocity differences shapes vendor resource allocation and channel strategy.
Product Type:
Cloud-Based platforms turn over fastest as enterprises renegotiate SaaS contracts annually, while Edge Computing deployments exhibit the longest replacement cycles tied to camera hardware lifespans.
- Cloud-Based:Elastic compute scaling enables frame-rate-intensive analytics without capital infrastructure. North American healthcare campuses drive demand for HIPAA-compliant video archival with automated lesion detection pipelines.
- Edge Computing:On-device inference executes on 15-watt embedded accelerators for sub-100-millisecond latency. Singapore smart city tenders specify edge-native behavioral analytics to minimize cloud egress costs.
- On-Premises:Dedicated server clusters serve Indian government facilities under BIS data localization mandates.
- Hybrid:Split processing architectures route sensitive biometric data locally while pushing metadata to cloud dashboards.
Cloud-Based anchors the volume base while Edge Computing gains share at the steepest rate.
Application:
Pricing tiers separate premium sports broadcast modules from standardized surveillance packages, with quality assurance commanding mid-tier licensing fees.
- Surveillance:Real-time object detection and behavioral pattern recognition process thirty-plus frames per second through machine learning pipelines. UAE law enforcement agencies mandate automated biometric identification in municipal tender specifications.
- Sports Analytics:Automated player tracking and highlight generation attract premium fees from cricket and football rights holders. South Korean broadcasters deploy 5G network slices for guaranteed-latency performance.
- Marketing Analytics:Foot traffic heatmapping and dwell-time measurement serve retail loss prevention teams.
- Quality Assurance:Defect detection in manufacturing workflows leverages acoustic event classification.
Surveillance anchors the volume base while Sports Analytics expands most quickly.
End User:
Security verticals concentrate procurement in Q4 budget cycles, whereas Entertainment buyers align purchases with broadcast rights renewal calendars.
- Security:Physical security integrators bundle edge hardware with managed detection services. EU AI Act conformity requirements now exclude non-certified platforms from European public sector shortlists.
- Retail:Loss prevention teams pilot quantized transformer models for sub-100-millisecond anomaly detection in store aisles.
- Entertainment:Real-time content moderation and automated highlight clipping serve streaming platforms.
- Education:Campus safety applications drive demand for acoustic gunshot detection integrated with access control systems.
Security anchors the volume base while Retail climbs the fastest.
Deployment:
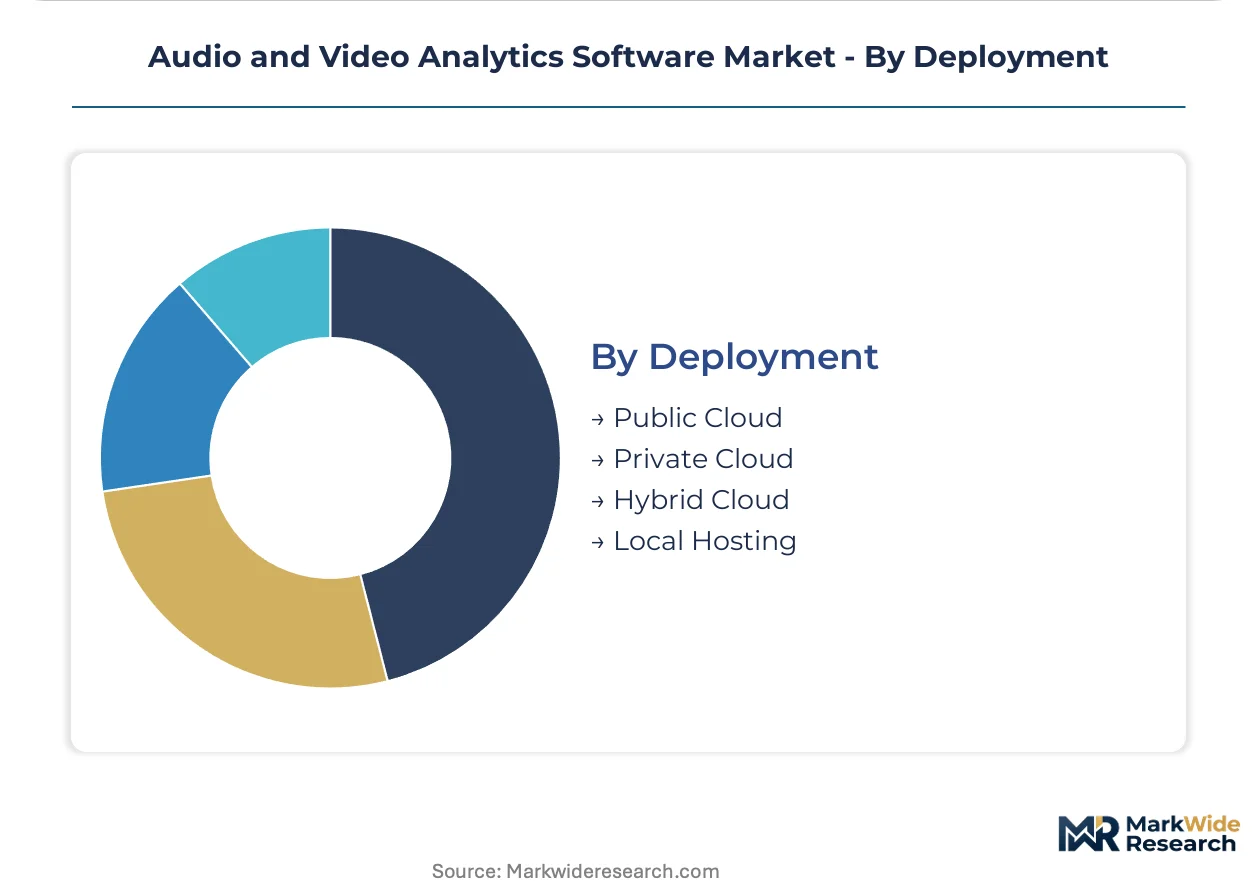
Operational expenditure treatment favors Public Cloud subscriptions, though data sovereignty requirements redirect sensitive workloads toward localized hosting models.
- Public Cloud:Shared infrastructure delivers elastic scaling for seasonal surveillance demands. German telecommunications carriers package guaranteed-latency slices for industrial video analytics subscriptions.
- Private Cloud:Dedicated tenant environments satisfy Indian BIS standards for government and financial sector deployments.
- Hybrid Cloud:Split architectures process biometric identification locally while aggregating metadata for centralized dashboards.
- Local Hosting:Air-gapped systems serve critical infrastructure operators with zero-trust network requirements.
Public Cloud anchors the volume base while Private Cloud gains share fastest among regulated industries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian software vendors export edge-native analytics platforms to UAE and Singapore smart city authorities under BIS-certified data localization frameworks. German telecommunications carriers license guaranteed-latency 5G slices to South Korean industrial operators seeking sub-100-millisecond inference pipelines.
United States
Healthcare campuses in Texas and California drive HIPAA-compliant video archival with automated lesion detection modules. FDA oversight of diagnostic imaging analytics mandates 510(k) clearance pathways for radiology software vendors. The Greater Boston cluster anchors development of transformer-based video understanding models for retail loss prevention pilots.
Germany
Industrial manufacturers in Bavaria deploy acoustic event classification for quality assurance workflows. The EU AI Act's high-risk system classification forces biometric identification vendors to document training data provenance through notified body protocols. The Eindhoven-adjacent corridor (spanning into Lower Saxony) concentrates edge silicon integration labs serving automotive video analytics.
India
Maharashtra and Telangana smart city authorities mandate real-time behavioral analytics in municipal surveillance tenders. BIS standards enforce data sovereignty requirements that push foreign vendors toward domestic cloud deployment models. The Delhi-NCR cluster hosts redundant infrastructure operations for compliance with government facility localization mandates.
Singapore
Law enforcement agencies specify edge-native behavioral analytics to minimize cloud egress costs in tropical climate deployments. The national digital regulator enforces algorithmic transparency documentation for public-space biometric systems. The one-north research corridor anchors quantized transformer model development for sub-100-millisecond anomaly detection.
United Arab Emirates
MOHAP-certified healthcare operators pilot FDA-cleared radiology analytics for automated lesion detection in CT workflows. Federal procurement frameworks exclude non-conforming platforms from critical infrastructure tenders. The Dubai Silicon Oasis cluster concentrates video analytics integration labs serving Gulf Cooperation Council smart city exports.
Audio and Video Analytics Software Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered procurement frameworks. The vendor base clusters around three strategic archetypes: physical security integrators bundling edge hardware with managed services, open-platform specialists sustaining developer ecosystems, and edge computing pure-plays targeting latency-sensitive municipal tenders. Dominant competitive moves include strategic partnerships with heterogeneous silicon vendors and geographic expansion through notified body certification pathways.
Within the channel-control tier, Genetec and Milestone Systems exemplify contrasting positioning strategies. Genetec anchors North American physical security integration through bundled hardware-software-service offerings. Milestone Systems occupies a position emphasizing open-platform interoperability that sustains developer ecosystem loyalty across European and Asia-Pacific deployments. Gorilla Technology represents the edge-specialist archetype, with its naming convention suggesting Asia-Pacific origination and smart city tender focus.
| Leading Market Players |
|---|
| Intellivision |
| Irisity AB |
| Milestone Systems |
| Rhombus Systems |
| Digital Watchdog |
| Genetec |
| Gorilla Technology |
| Coram |
| Eagle Eye Networks |
| Others |
Value Chain & Pricing Dynamics
The Shenzhen-Dubai air freight corridor carries edge computing accelerators and embedded vision processors, with per-kilogram rates directly feeding into tiered software licensing structures. Tariff volatility between Taiwan and mainland China compresses margins on NPU-dependent analytics modules, forcing vendors to differentiate pricing across certification-grade tiers.
Pricing Analysis
Next-generation transformer-based video understanding models command premium subscription rates against legacy CNN architectures and experimental diffusion-based pipelines. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-certified biometric platforms from uncertified alternatives and open-source toolkits. Pricing pressure stems from GPU-NPU heterogeneous compute commoditization as more vendors port to 15-watt embedded accelerators. Healthcare diagnostic imaging buyers exhibit lowest price sensitivity due to FDA clearance requirements, while retail loss prevention teams drive hardest bargain negotiations.
Supply Chain Analysis
Tariff exposure between Taiwan and mainland China dominates risk planning for neural processing unit procurement. Taiwan-based foundries, South Korean memory suppliers, and Japanese sensor manufacturers anchor hardware component sourcing. Raw material dependencies include advanced silicon wafers, high-bandwidth memory stacks, and thermal management substrates. Single-source vulnerability concentrates in TSMC's 7nm and 5nm fabrication nodes for edge inference chips. Distribution runs through North American physical security integrators, European notified body certification channels, and Asia-Pacific smart city tender authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by municipal budget restoration following pandemic-era austerity measures. Smart city surveillance procurement cycles now normalize across previously delayed tenders.
For Market Incumbents: Pre-empt edge-native inference commoditization by deepening channel control through exclusive silicon vendor partnerships. Secure notified body pre-certification for EU AI Act high-risk system classifications before tender windows open. Counter Gorilla Technology's Asia-Pacific municipal momentum with localized engineering presence in Singapore and UAE.
For New Entrants and Emerging Players: India's BIS-compliant domestic cloud deployment models remain underpenetrated relative to saturated North American SaaS markets. Target Maharashtra and Telangana smart city authorities with data localization guarantees as wedge against foreign incumbent pricing. Pursue sports analytics broadcast rights holders in South Korea and Germany through 5G network slicing partnerships.
For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape toward certified-vendor premiums and stranded-asset risk for non-compliant platforms. Five-to-ten-year viability favors edge computing pure-plays with heterogeneous silicon porting capabilities and healthcare FDA clearance pathways. Monitor notified body assessment queue lengths as inflection indicator for European public sector procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Pre-Certification | EU AI Act conformity assessments now gate European law enforcement procurement shortlists. |
| Edge-Native Inference Optimization | Quantized transformer models on 15-watt accelerators slash cloud egress costs for municipal deployments. |
| Healthcare FDA Clearance Pathway | 510(k) radiology analytics modules command premium hospital system pricing for CT lesion detection. |
| Data Localization Infrastructure | BIS-compliant domestic cloud deployments satisfy Indian government facility mandates. |
| 5G Network Slicing Partnerships | Guaranteed-latency subscriptions open recurring revenue from South Korean industrial operators. |
Study Parameters
The analysis maps cloud-based deployment architectures, edge-native inference pipelines, on-premises server clusters, and hybrid split-processing configurations, each validated through CTOs at physical security integrators, municipal procurement officers, healthcare biomedical engineers, and telecommunications network planning leads. Primary fieldwork combined structured interviews with secondary validation against SEC filings from Genetec and Milestone Systems, hyperscaler capex disclosures, EU AI Act implementation guidance, and BIS data localization circulars. Bottom-up segment sizing triangulated against top-down market boundary checks.
Assumptions held fixed include EU AI Act enforcement timelines, Taiwan foundry capacity allocation, and 5G network slicing commercialization pace across South Korea and Germany. Variables tested across the projection horizon encompass municipal budget restoration velocity, edge silicon process node transitions, and healthcare diagnostic imaging reimbursement pathways. Segmentation dimensions modeled span deployment architecture, application vertical, end-user industry, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to procurement cycle data and technology substitution rates.
Macroeconomic conditions sit as an overlay; deviation in municipal bond financing costs, semiconductor capital expenditure cycles, or cross-border data flow restrictions would shift the trajectory. Forecasts reflect documented assumptions about smart city tender pipeline visibility and healthcare capital budget prioritization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Self Service Analytics Market
Analytics
Capacity Management Analytics Market
Analytics
Practice Analytics Market
Analytics
United Kingdom Business Intelligence Market
Analytics
Data Discovery Market
Analytics
Augmented Analytics Market
Analytics
Europe Edge Analytics Market
Analytics
Retail Analytics Market
Analytics
RAN Analytics and Monitoring Market
Analytics
Global People and HR Analytics Software Market
Analytics
Global Enterprise Performance Management Market
Analytics
Speech Analytics Market
Analytics
Global Retail Analytics Software and Services Market
Analytics
Load (ETL) Market
Analytics
APAC Data Wrangling Market
Analytics
Saudi Arabia Geospatial Analytics Market