
 User Provisioning Software Market | 2026-2036
User Provisioning Software Market Size, Share, and Industry Trends Forecast 2026-2036
User Provisioning Software Market Analytics
North American cloud infrastructure build-out is reshaping how enterprises deploy identity lifecycle tools. Okta leverages its native SaaS architecture to capture mid-market and large enterprise transitions off legacy systems. SailPoint Technologies anchors the identity governance segment with deep compliance automation and policy enforcement capabilities. Microsoft competes through Azure AD integration, bundling provisioning with broader cloud productivity contracts.
User provisioning software automates the creation, modification, and deactivation of user accounts across IT systems, typically orchestrating access rights through directory services and application connectors using protocols such as SCIM and SAML. Its primary commercial purpose is to reduce administrative overhead, enforce least-privilege access, and maintain audit-ready identity records for security and compliance. Cloud-based deployment now leads adoption as organizations retire on-premise identity stacks, while hybrid configurations persist in regulated industries requiring data residency controls. Among end users, large enterprises generate the dominant revenue share, though government and educational institutions represent faster-growing segments as public-sector digital identity mandates expand.
Regulatory frameworks including the EU GDPR, US HIPAA, and SEC cybersecurity disclosure rules directly shape procurement priorities by mandating access logging, periodic certification, and breach notification capabilities. The US NIST Cybersecurity Framework and ISO 27001 standards further define technical requirements that provisioning vendors must satisfy for enterprise and government contracts. Stakeholders should monitor how AI-driven identity analytics and decentralized identity standards alter competitive requirements and integration architectures.
Market Dynamics
Cloud migration is collapsing traditional on-premise identity infrastructure deployment cycles, compressing procurement timelines from multi-year enterprise agreements to rolling SaaS subscriptions governed by zero-trust security mandates.
Growth Catalysts
- Zero-trust architecture mandates:NIST Cybersecurity Framework requirements in the United States are forcing federal contractors and critical infrastructure operators to automate identity lifecycle management. This creates immediate procurement pull for provisioning platforms with continuous authentication capabilities.
- Financial services compliance:SEC cybersecurity disclosure rules now require public companies to document access control procedures quarterly. Banks and insurers are expanding identity governance budgets to satisfy audit-ready provisioning standards.
- SCIM protocol standardization:Cross-application interoperability is accelerating connector development, reducing integration friction for enterprises retiring legacy directory services.
Market Restraints
- Data residency requirements:GDPR localization provisions in Germany and France restrict cloud deployment options, forcing hybrid architectures that increase operational complexity and extend sales cycles.
- Skills concentration:Identity and access management expertise clusters in the United States and Western Europe, creating talent scarcity in Asia-Pacific and Latin American implementation markets.
- Legacy system entrenchment:Mainframe-based HR systems in government and healthcare retain custom provisioning scripts that resist standard connector replacement.
Strategic Opportunities
- Decentralized identity standards:W3C Verifiable Credentials and EU digital wallet frameworks are creating new product categories for self-sovereign identity provisioning that bypasses traditional directory architectures.
- Educational institution modernization:Campus identity consolidation projects in Japan and Australia represent underpenetrated demand for semester-based automated provisioning tied to enrollment systems.
- AI-driven access analytics:Machine learning anomaly detection converging with provisioning workflows enables predictive deprovisioning based on behavioral signals rather than static policy rules.
Industry Challenges
- Cross-domain certification timelines:FedRAMP, ISO 27001, and SOC 2 Type II audits require 12-18 month validation cycles that delay government and regulated industry market entry.
- Multi-protocol integration debt:Enterprises operate simultaneous SAML, OIDC, LDAP, and proprietary authentication schemes, forcing expensive custom connector development for unified provisioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | User Provisioning Software Market |
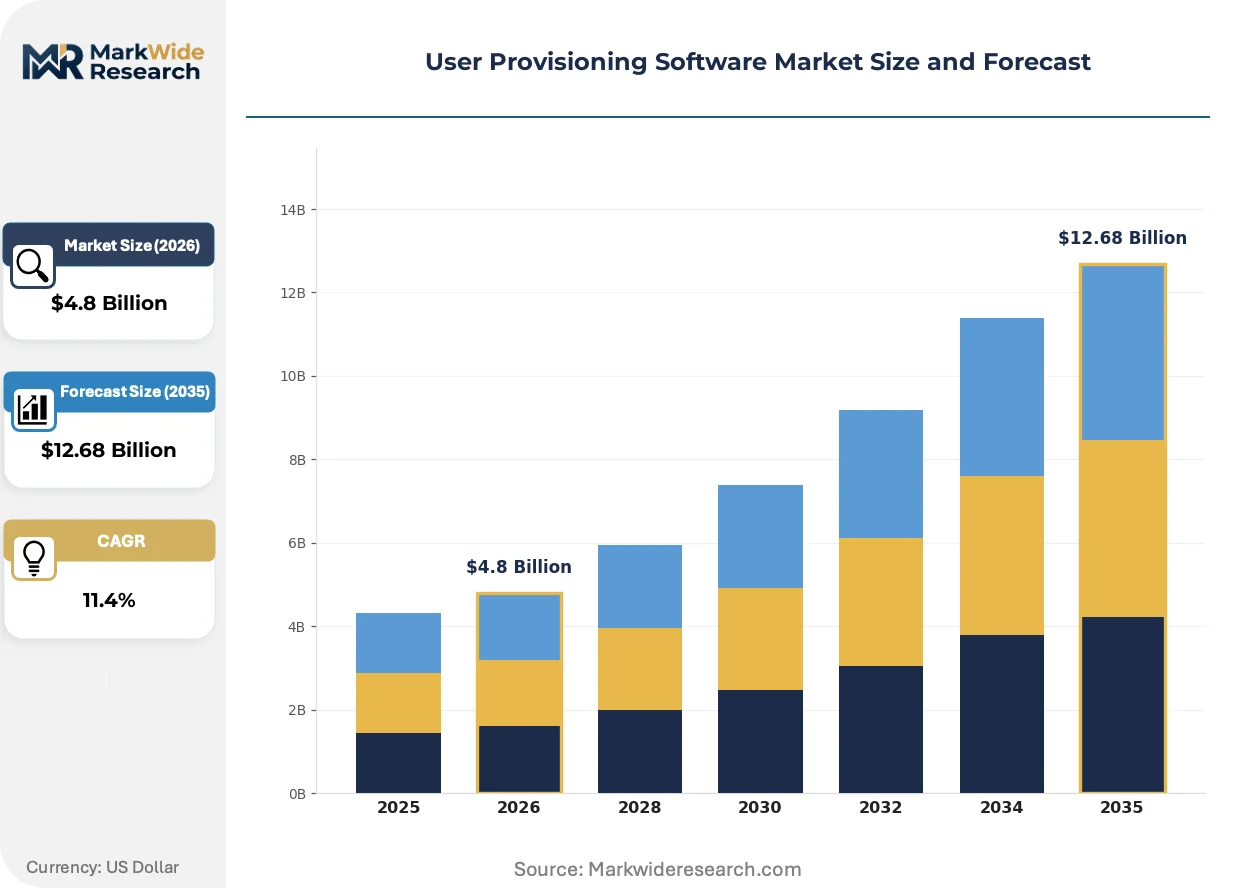
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed End User: SMEs, Large Enterprises, Government, Educational Institutions Functionality: Access Management, Identity Governance, Audit Trails, Role Management Integration Capability: API, LDAP, SAML, SCIM |
| Companies Covered | IBM, OneLogin, Okta, Saviynt, Oracle, SailPoint Technologies, Ping Identity, ManageEngine, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
User Provisioning Software Market Evolving Landscape
Artificial intelligence and decentralized architectures are restructuring how identity lifecycle tools authenticate, authorize, and audit user access across distributed enterprise environments.
Passwordless authentication using FIDO2 and WebAuthn standards is collapsing traditional credential lifecycle management. Financial services and technology firms are deploying biometric and hardware key provisioning at scale. This compression eliminates password reset helpdesk tickets and reduces the attack surface for credential-based breaches.
The EU AI Act's risk classification system for automated decision-making is reshaping provisioning algorithm transparency requirements. High-risk identity verification systems must now maintain audit trails for AI-driven access approvals. German automotive and French pharmaceutical manufacturers are restructuring governance workflows to satisfy explainability mandates.
Subscription-based consumption models are displacing perpetual license structures in mid-market procurement. Value-added resellers and managed security service providers are capturing provisioning deployment and ongoing policy management. This shift concentrates buyer power in the United States and United Kingdom where channel consolidation is most advanced.
User Provisioning Software Market Segmentation
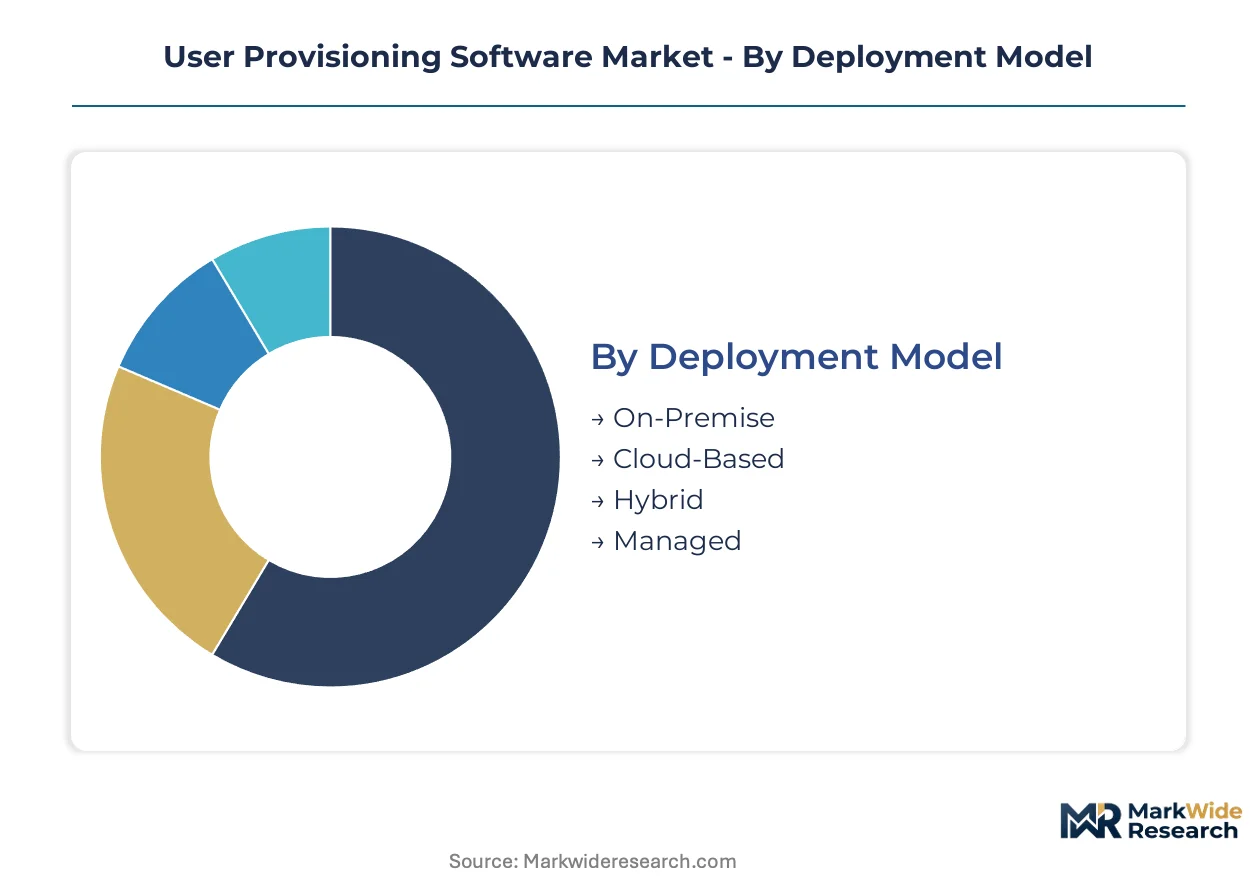
Deployment architecture and functional depth determine vendor selection criteria across the user provisioning software market. Procurement teams weight integration complexity against compliance mandates when segmenting budget allocation across deployment modes and end-user categories.
Deployment Model:
Cloud-based deployments demand lighter post-implementation support than on-premise alternatives, though hybrid configurations generate recurring professional services revenue through sustained architecture tuning.
- On-Premise:Organizations in Germany and France retain data-center-hosted identity stacks to satisfy GDPR localization requirements. German automotive manufacturers and French pharmaceutical firms absorb higher capital expenditure to maintain direct control over credential repositories and audit logs.
- Cloud-Based:Native SaaS architectures enable rapid provisioning across distributed workforces without infrastructure overhead. United States mid-market enterprises and United Kingdom financial services firms dominate adoption, driven by zero-trust mandates and compressed procurement timelines.
- Hybrid:Split architectures separate sensitive credential storage from cloud-orchestrated access workflows. Japanese government agencies and Australian healthcare networks deploy hybrid models to balance data residency with operational agility.
- Managed:Third-party operated identity services offload policy administration and certification cycles to specialized providers. United States federal contractors and United Kingdom educational consortia leverage managed services to address skills scarcity.
Cloud-based deployments hold the largest share; momentum sits with hybrid configurations as regulated industries navigate data sovereignty constraints.
End User:
Organizational scale dictates feature requirements, with large enterprises demanding granular role hierarchies while smaller entities prioritize out-of-box connector libraries.
- SMEs:Mid-market firms favor subscription pricing and rapid deployment templates over customization. United States technology startups and United Kingdom professional services firms represent concentrated demand for standardized SaaS provisioning.
- Large Enterprises:Complex workforce structures require deep identity governance automation and cross-application policy enforcement. Financial services conglomerates in the United States and Germany anchor this segment through compliance-driven procurement.
- Government:Public-sector mandates for continuous authentication and FedRAMP certification shape procurement specifications. United States federal agencies and Japanese municipal governments are expanding digital identity modernization budgets.
- Educational Institutions:Semester-based enrollment cycles create seasonal provisioning spikes requiring automated lifecycle management. Australian universities and Japanese national colleges are consolidating fragmented campus identity systems.
Large enterprises dominate current revenue; educational institutions are expanding most quickly as public-sector digital identity mandates proliferate.
Functionality:
Feature module selection correlates with regulatory exposure, with audit-intensive industries prioritizing governance and certification capabilities over basic access automation.
- Access Management:Real-time authentication orchestration and session control form the core provisioning layer. United States healthcare networks under HIPAA and German manufacturers under EU AI Act risk classifications drive demand for continuous verification.
- Identity Governance:Policy enforcement, access certification, and segregation-of-duties automation address audit requirements. SEC cybersecurity disclosure rules compel United States public companies to document quarterly access control procedures through governance tooling.
- Audit Trails:Immutable logging and forensic reporting satisfy breach notification and regulatory examination requirements. French CNIL enforcement actions and United States SEC examinations elevate audit trail priority in procurement.
- Role Management:Hierarchical permission structures and dynamic entitlement assignment reduce administrative overhead. Japanese automotive supply chains and Australian government departments deploy role-based access to manage contractor populations.
Identity governance commands premium pricing; audit trails are gaining share fastest as disclosure mandates tighten across jurisdictions.
Integration Capability:
Protocol breadth determines total cost of ownership, with multi-protocol environments requiring expensive custom connector development.
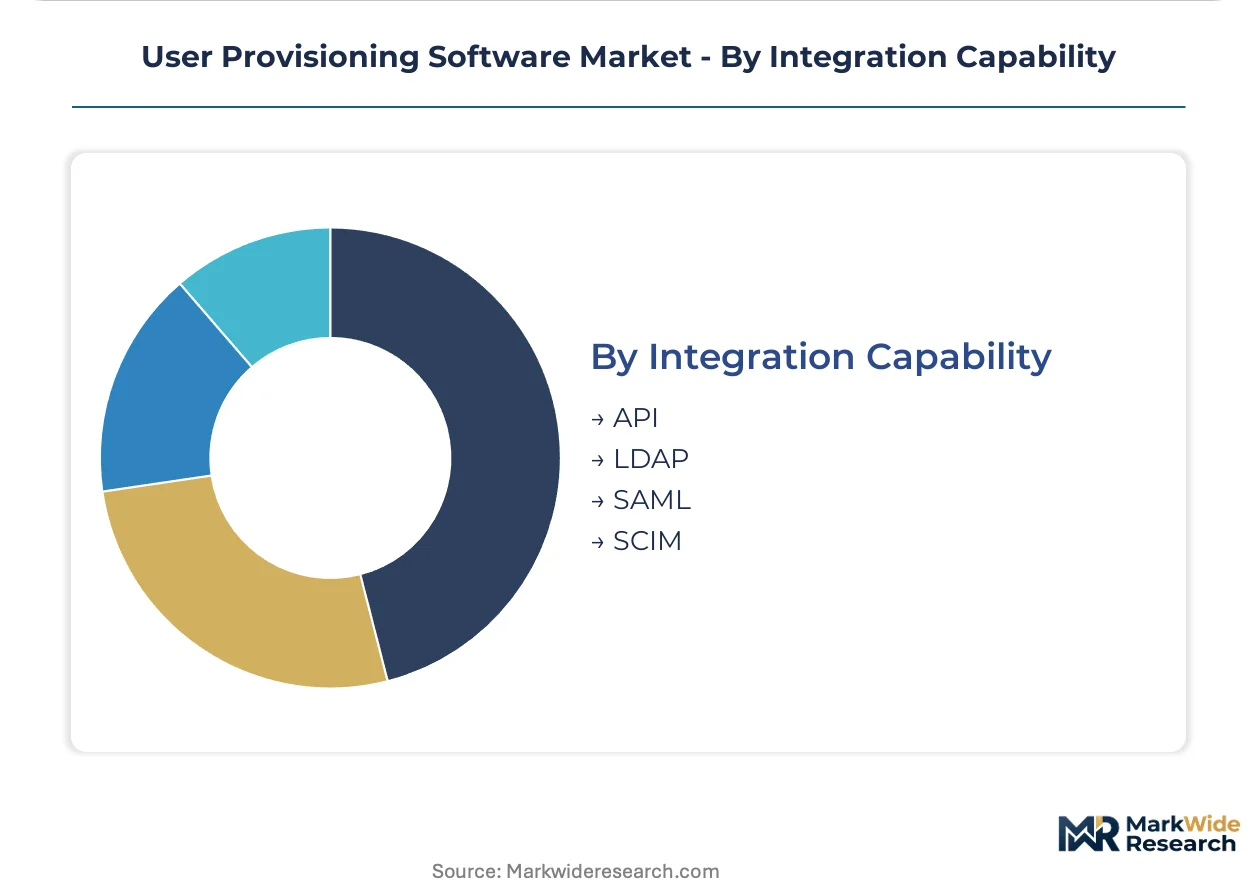
- API:REST and GraphQL endpoints enable modern application integration without middleware. United States SaaS vendors and United Kingdom fintech platforms standardize on API-first provisioning architectures.
- LDAP:Legacy directory services persist in mainframe-heavy environments despite cloud migration trends. German industrial conglomerates and Japanese government ministries retain LDAP for backward compatibility with established HR systems.
- SAML:Web-based single sign-on federation remains prevalent in enterprise application portfolios. United States healthcare providers and Australian educational institutions leverage SAML for cross-organizational trust relationships.
- SCIM:Automated user attribute synchronization is displacing manual provisioning scripts. Cross-application interoperability standardization is accelerating SCIM adoption among United States technology firms and United Kingdom enterprise software buyers.
API and SCIM together hold the dominant position; LDAP maintains residual share in legacy-entrenched sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' dense fiber backbone and hyperscale data center corridors underpin its dominance in cloud-native identity infrastructure procurement.
United States
Federal zero-trust mandates and SEC cybersecurity disclosure rules drive procurement intensity. NIST Cybersecurity Framework requirements force federal contractors toward automated lifecycle management. Northern Virginia's data center cluster hosts the densest concentration of cloud identity orchestration workloads.
Germany
Automotive and pharmaceutical manufacturers absorb higher capital expenditure for data-center-hosted identity stacks. GDPR localization provisions restrict pure cloud deployment, forcing hybrid architectures. Baden-Württemberg's industrial corridor retains on-premise credential repositories under direct enterprise control.
Japan
Municipal digital identity modernization and campus consolidation projects accelerate semester-based automated provisioning. METI guidelines shape technical specifications for public-sector procurement. Tokyo's government technology cluster leads deployment of split architectures balancing data residency with operational agility.
United Kingdom
Financial services firms under FCA supervision expand identity governance budgets for quarterly access certification. Channel consolidation concentrates buyer power among London-based enterprise software buyers. The Thames Valley technology corridor anchors SaaS provisioning adoption for mid-market professional services.
Australia
Educational institution modernization and healthcare network identity consolidation drive seasonal provisioning demand. TGA and national cybersecurity center guidelines influence procurement specifications. Melbourne and Sydney university clusters deploy automated lifecycle management tied to enrollment system integration.
User Provisioning Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in connector and protocol adaptation layers. The vendor base organizes around three strategic archetypes: cloud-native SaaS platforms with native SCIM architectures, legacy enterprise software vendors bundling provisioning within broader productivity contracts, and governance specialists emphasizing compliance automation and policy enforcement. Dominant competitive moves include vertical integration into adjacent identity governance modules and strategic partnerships with hyperscale cloud providers to secure distribution through marketplace channels.
Within the cloud-native platform tier, Okta and SailPoint Technologies occupy positions exemplifying divergent specialization vectors—Okta representing the mid-market SaaS transition play, SailPoint anchoring the governance-heavy enterprise segment. Microsoft competes through Azure AD integration, bundling provisioning capabilities within broader cloud productivity contracts that leverage existing enterprise relationships. IBM and Oracle represent legacy enterprise software vendors adapting on-premise identity stacks toward hybrid deployment models to retain installed base relationships.
| Leading Market Players |
|---|
| IBM |
| OneLogin |
| Okta |
| Saviynt |
| Oracle |
| SailPoint Technologies |
| Ping Identity |
| ManageEngine |
| Microsoft |
| Others |
Value Network & Pricing Analysis
Single-source dependency on hyperscale cloud infrastructure providers concentrates procurement leverage in the United States, compressing SaaS subscription margins for mid-market vendors while forcing hybrid deployment premiums in Germany and Japan. This chokepoint simultaneously widens pricing spreads between cloud-native and on-premise tiers and reshapes channel economics toward managed service intermediation.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with enterprise agreements scaling from per-seat SaaS subscriptions at the low end to comprehensive identity governance bundles at the premium tier. Price differentiation rests on FedRAMP certification status and SCIM connector depth, with certified vendors commanding substantial premiums over uncertified alternatives. Cost compression in the mid-market intensifies as Microsoft bundles provisioning within Azure AD productivity contracts. Large financial services conglomerates exhibit lowest price sensitivity due to SEC compliance mandates, while United Kingdom educational consortia and Australian universities drive hardest bargain on standardized SaaS tiers.
Supply Chain Analysis
Upstream feedstock of identity infrastructure draws from United States hyperscale data centers, Irish and Singaporean cloud regions for GDPR-compliant hosting, and Japanese government-certified domestic facilities. Critical components include directory service software licenses, biometric authentication hardware modules, and API gateway middleware. Single-source vulnerability concentrates in cloud infrastructure provisioning, where AWS, Azure, and Google Cloud dominate sovereign-compliant hosting capacity. Distribution runs through value-added resellers and managed security service providers in London, New York, and Tokyo corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story, with zero-trust architecture mandates accelerating replacement of legacy directory systems across federal contractors and critical infrastructure operators.
For Market Incumbents: Insulate recurring revenue streams by deepening FedRAMP and ISO 27001 certification moats against emerging cloud-native challengers. Prioritize backward integration into AI-driven access analytics to preempt behavioral deprovisioning disruption. Anchor enterprise relationships through multi-year governance automation contracts that resist SaaS-only displacement. For New Entrants and Emerging Players: Australian educational institutions and Japanese municipal governments present underpenetrated demand for semester-based automated provisioning with lighter compliance overhead. Target hybrid deployment architectures in German automotive and French pharmaceutical verticals where GDPR localization forces architectural complexity incumbents underprice. Lead with SCIM-native API-first positioning against legacy LDAP-entangled competitors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors governance-specialist platforms with proven FedRAMP authorization over horizontal SaaS generalists. Long-term viability hinges on continuous authentication convergence and decentralized identity standard adoption. Monitor W3C Verifiable Credentials implementation velocity across EU digital wallet pilots as inflection signal for architectural obsolescence risk in directory-centric incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | Unlocks United States federal agency procurement pipelines worth substantial recurring revenue. |
| SCIM Connector Library Expansion | Reduces integration friction for enterprises retiring legacy directory services toward cloud migration. |
| AI-Driven Access Analytics Development | Enables predictive deprovisioning based on behavioral signals rather than static policy enforcement. |
| Hybrid Architecture Certification Investment | Captures German and Japanese demand for data residency-compliant identity orchestration. |
| Strategic Partnership with Hyperscale Cloud Providers | Secures marketplace distribution through AWS, Azure, and Google Cloud channels. |
Research Methodology
Desk research of vendor technical documentation, regulatory filing databases, and hyperscaler partnership disclosures preceded structured interviews with chief information security officers, identity and access management directors, federal procurement officers, and managed security service provider executives. Primary fieldwork combined with secondary validation against SEC cybersecurity disclosure filings, FedRAMP authorization repositories, and EU digital identity framework progress reports. Bottom-up deployment model sizing triangulated against top-down enterprise IT budget allocation surveys.
The assumption set held cloud migration velocity and zero-trust mandate implementation timelines as primary demand drivers, with regulatory enforcement intensity and AI Act risk classification as sensitivity variables. Segmentation modeling spanned deployment architecture, organizational scale, vertical industry, integration protocol complexity, and regional adoption pattern. CAGRs derived from fitted growth curves against historical replacement cycle data and procurement pipeline visibility. Forecast inputs included NIST Cybersecurity Framework adoption rates and educational institution digital identity modernization budget trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration by hyperscale cloud providers or rapid decentralized identity standard adoption by EU member states would shift outcomes materially. Quarterly review of FedRAMP authorization timelines, SCIM protocol implementation velocity, and AI-driven access analytics product launches is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Cloud Encryption Software Market
Security Software
Global Data Privacy Management Software Tools Market
Security Software
Global Security Assertion Markup Language (SAML) Authentication Market
Security Software
Security Software for Consumers Market
Security Software
Global Visitor Management System Market
Security Software
Broadcast Censorship Solutions Market
Security Software
Business Email Compromise (BEC) Market
Security Software
VPN Software Market
Security Software
Global Data Masking Market
Security Software
Source Code Escrow Market
Security Software
Information Rights Management Market
Security Software
AI in Security Market
Security Software
Keystroke Dynamics Market
Security Software
Certificate Authority Market
Security Software
Data Leakage Prevention Product Market
Security Software
Certification Authority Market