
 Germany Data Center Networking Market | 2026-2036
Germany Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Data Center Networking Market Insights
Software-defined networking subscriptions is recalibrating vendor revenue models across Germany. Cisco Systems Inc. anchors its position through deep channel partnerships with local systems integrators. Juniper Networks Inc. differentiates via automated WAN optimization tailored to multi-tenant facilities. Dell Technologies Inc. leverages integrated server-storage-networking bundles to capture enterprise refresh cycles.
Germany data center networking comprises the physical and virtual infrastructure—switches, routers, optical transceivers, and SDN controllers operating at 400G/800G speeds—that interconnects compute and storage resources within and between facilities. Its primary purpose is to minimize latency, maximize throughput, and ensure fault tolerance for mission-critical digital services. Ethernet switching dominates capital expenditure among product types, while fibre channel retains share in financial services storage fabrics. Cloud computing applications absorb the fastest-growing share of new port deployments as hyperscalers expand Frankfurt and Berlin campuses.
Germany's Federal Network Agency and the EU Energy Efficiency Directive jointly enforce power usage effectiveness thresholds that shape equipment procurement standards. BSI IT-Grundschutz certification requirements further constrain vendor market access for government and critical infrastructure contracts. Stakeholders must monitor how the EU AI Act's risk-classification framework reshapes compliance obligations for networking gear deployed in automated decision-making environments.
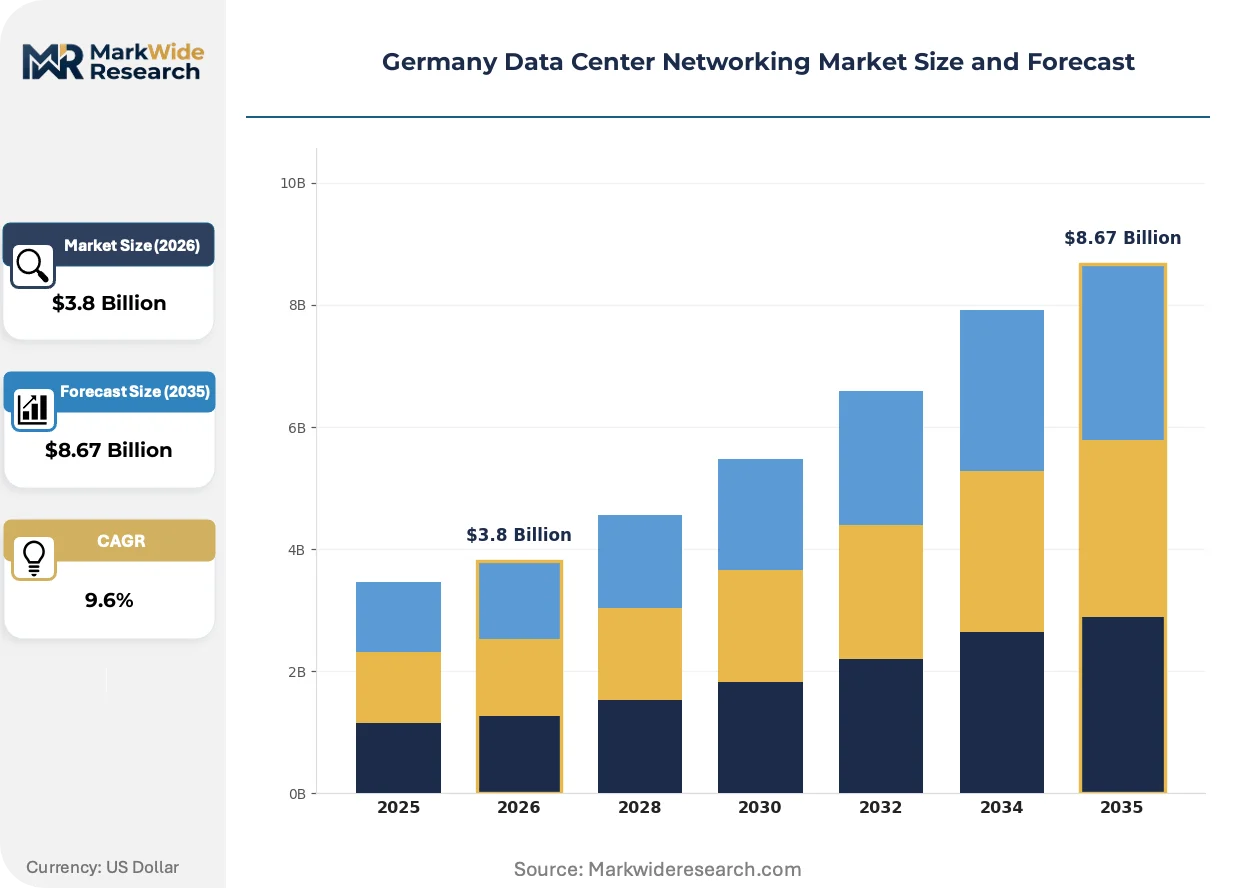
Market Dynamics
Hyperscale cloud providers in Frankfurt and Berlin are compressing refresh cycles from five years to three years to accommodate AI training clusters, forcing equipment vendors to accelerate 800G optical transceiver roadmaps and reconfigure service delivery models around rapid-deployment contracts.
Growth Catalysts
- EU Energy Efficiency Directive:Mandates for power usage effectiveness below 1.3 in new facilities are accelerating procurement of low-latency optical interconnects and liquid-cooled switching fabrics across Rhine-Main campuses.
- AI workload proliferation:Large language model training and inference clusters in Frankfurt's hyperscale facilities are driving port density requirements beyond traditional enterprise specifications.
- Rhine-Main cluster concentration:Proximity to DE-CIX and transatlantic cable landings creates natural gravity for latency-sensitive financial services and gaming infrastructure, sustaining premium equipment demand.
Market Restraints
- BSI IT-Grundschutz certification:Federal procurement rules for critical infrastructure impose 12-18 month validation timelines that exclude non-EU vendors from government and defense contracts.
- Optical component supply concentration:Dependence on Asian-manufactured 800G DSPs and coherent optics creates exposure to export control fluctuations and extended lead times.
- Copper interconnect persistence:Short-reach server-to-switch connections under 3 meters continue deploying passive DACs, limiting optical transceiver attach rates in hyperscale compute racks.
Strategic Opportunities
- Edge colocation in secondary cities:Underpenetrated facilities in Munich, Hamburg, and Düsseldorf lack high-density networking, creating whitespace for 400G/800G distributed spine architectures.
- EU AI Act risk classification:High-risk automated decision-making systems will mandate deterministic latency guarantees, opening specialized low-jitter switching segments for regulated industries.
- Convergence of IP and storage fabrics:NVMe-over-TCP adoption is collapsing separate Fibre Channel and Ethernet procurement silos, enabling unified switch platforms in enterprise data lakes.
Industry Challenges
- Optical systems engineering talent:Shortage of 400G/800G signal integrity and coherent modulation specialists delays product validation and field deployment timelines.
- Multi-generational interoperability:Brownfield facilities running 100G/200G leaf-spine architectures face complex migration paths that risk service disruption during partial upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Data Center Networking Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Firewalls, Load Balancers Technology: Ethernet, IP, MPLS, Fibre Channel End User: Enterprises, Cloud Providers, Colocation Providers, Service Providers Application: Data Storage, Cloud Computing, Virtualization, Disaster Recovery |
| Companies Covered | Cisco Systems Inc., Juniper Networks Inc., Dell Technologies Inc., IBM Corporation, VMware Inc., Huawei Technologies Co. Ltd., NVIDIA Corp. (Cumulus Networks), Extreme Networks Inc., Intel Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Data Center Networking Market Trends and Innovations
Silicon photonics co-packaging and software-defined fabric automation are compressing the traditional boundary between optical transport and electronic switching, enabling new architectural paradigms that prioritize energy per bit over port cost alone.
Co-packaged optics is absorbing the transceiver market's value chain by integrating lasers and modulators directly onto switch ASIC substrates. Hyperscale operators in Frankfurt are piloting 51.2Tbps switches with internal optical engines, eliminating pluggable modules in high-density aggregation tiers. This integration is absorbing margin from traditional transceiver vendors while reducing power consumption per gigabit by approximately 30 percent.
Germany's Federal Network Agency is enforcing the EU Energy Efficiency Directive through binding PUE thresholds that escalate annually, compelling facility operators to replace legacy copper-based top-of-rack switches with liquid-cooled alternatives. Equipment procurements now require embodied carbon disclosures under the CSRD framework, favoring vendors with European manufacturing footprints. Financial services and public sector tenders in Hesse and Berlin are the most affected, with RFPs now mandating 15-year total cost of ownership analyses.
Enterprise buyers are consolidating vendor relationships from five or more switching suppliers to two strategic partners, mirroring hyperscale procurement discipline. Systems integrators in Bavaria and Baden-Württemberg are responding with managed network-as-a-service offerings that bundle hardware, software, and operational support into single contracts. This concentration is most visible among Mittelstand manufacturers automating shop-floor connectivity, where internal IT teams lack optical networking expertise.
Germany Data Center Networking Market Segmentation
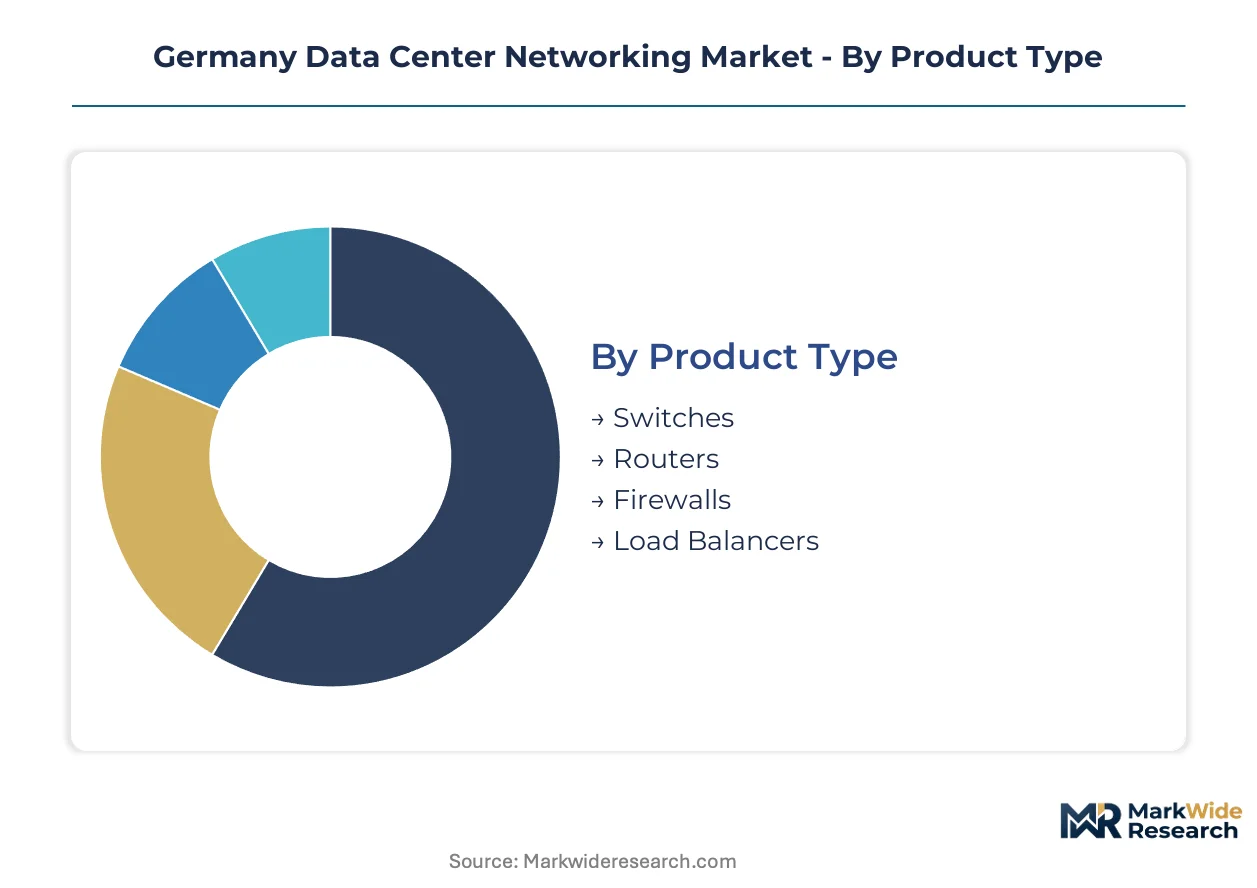
Segmentation in Germany's data center networking market reveals distinct procurement patterns across infrastructure layers. Equipment specifications, connectivity protocols, and buyer sophistication create divergent competitive dynamics that vendors must navigate separately.
Product Type:
Speed tier and port density specifications define the hardware procurement axis across Rhine-Main and Berlin facilities.
- Switches:Ethernet switches operating at 400G/800G speeds dominate capital expenditure, with spine-layer deployments in Frankfurt hyperscale campuses driving demand for 51.2Tbps aggregate capacity fabrics. Rhine-Main cloud providers compress refresh cycles to three years to accommodate AI training clusters.
- Routers:Edge and core routing platforms handle inter-facility traffic across DE-CIX exchange points, with software-defined WAN capabilities becoming mandatory for multi-tenant colocation providers seeking automated path optimization.
- Firewalls:Next-generation firewall appliances integrate deep packet inspection with zero-trust segmentation policies required under BSI IT-Grundschutz certification for federal contracts.
- Load Balancers:Application delivery controllers distribute traffic across distributed compute nodes, with hardware-based appliances retaining share in financial services latency-sensitive environments.
Mature deployment sits with switches. Newer deployment is concentrated in load balancers.
Technology:
Protocol selection traces directly to workload characteristics and legacy infrastructure inheritance patterns.
- Ethernet:Dominates new port deployments across hyperscale and enterprise facilities, with 800G optical transceivers displacing copper in aggregation tiers. PUE mandates under the EU Energy Efficiency Directive accelerate low-latency optical interconnect adoption.
- IP:Internet Protocol routing underlies all external connectivity, with IPv6 migration accelerating in Berlin cloud campuses facing address exhaustion in dense server environments.
- MPLS:Multi-Protocol Label Switching retains share in carrier-managed WAN services connecting distributed enterprise data lakes, though SD-WAN substitution pressures pricing.
- Fibre Channel:Storage-area networking protocols persist in Hesse financial services facilities with existing SAN investments, though NVMe-over-TCP convergence threatens dedicated fabric procurement.
Established infrastructure relies on Fibre Channel. Expansion is climbing the fastest in Ethernet.
End User:
Buyer type determines procurement sophistication, contract structure, and vendor relationship intensity.
- Cloud Providers:Hyperscale operators in Frankfurt and Berlin drive 800G optical transceiver roadmaps through rapid-deployment contracts, compressing traditional five-year refresh cycles.
- Enterprises:Mittelstand manufacturers and large corporates consolidate vendor relationships to two strategic partners, favoring integrated server-storage-networking bundles.
- Colocation Providers:Multi-tenant facility operators in Munich and Hamburg lack high-density networking, creating whitespace for distributed spine architectures.
- Service Providers:Telecommunications carriers deploy managed network-as-a-service offerings bundling hardware, software, and operational support for mid-market clients.
Volume concentration rests with cloud providers. Procurement complexity is expanding most quickly among colocation providers.
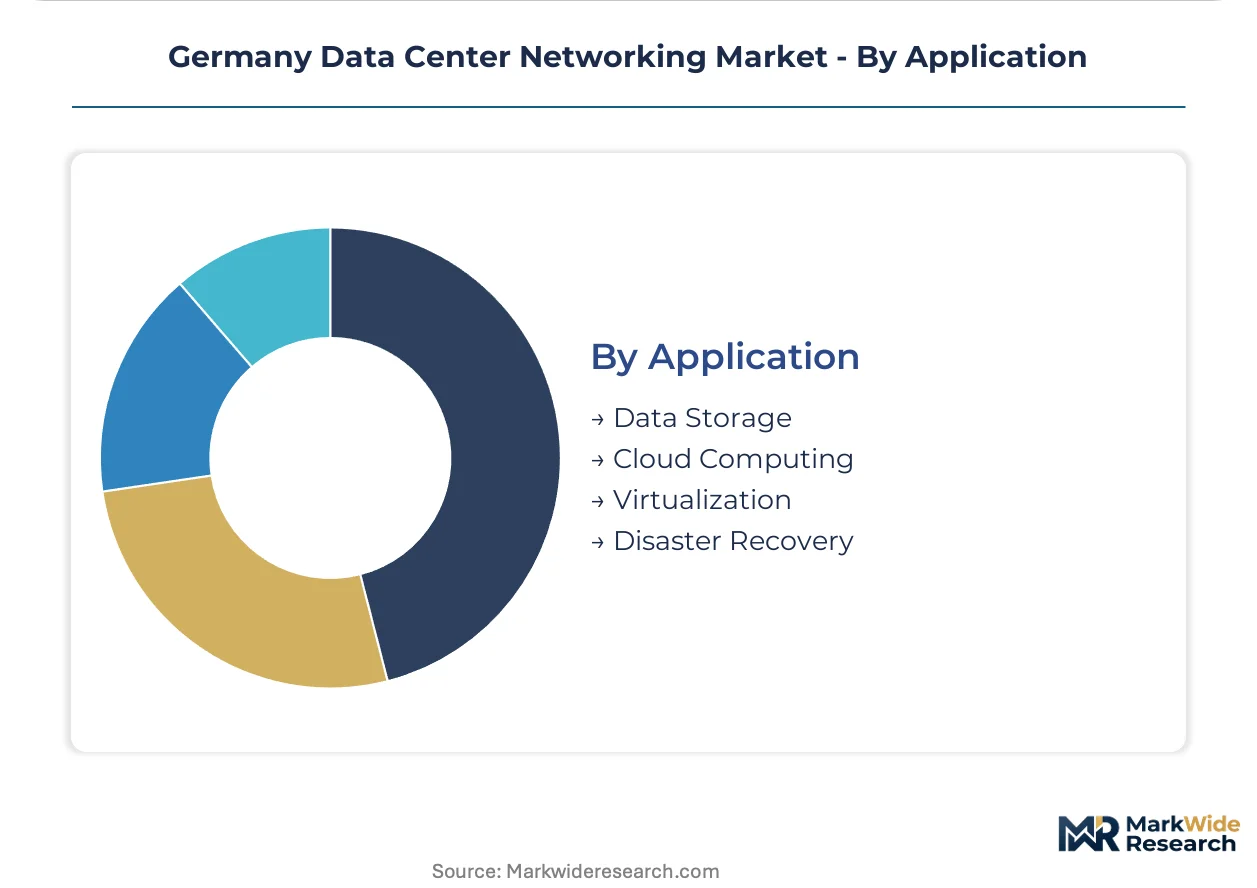
Application:
Workload purpose shapes bandwidth, latency, and resilience specifications across deployment scenarios.
- Cloud Computing:Hyperscale campuses absorb the steepest expansion trajectory of new port deployments as AI training and inference clusters demand port densities beyond traditional enterprise specifications.
- Data Storage:Enterprise data lakes drive unified switch platform adoption as NVMe-over-TCP collapses separate Fibre Channel and Ethernet procurement silos.
- Virtualization:Software-defined infrastructure requires east-west traffic optimization within facilities, favoring leaf-spine architectures with low oversubscription ratios.
- Disaster Recovery:Synchronous replication between Rhine-Main and Berlin facilities mandates deterministic latency guarantees, opening specialized low-jitter switching segments.
Critical infrastructure investment centers on disaster recovery. Capacity scaling is gaining share fastest in cloud computing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's Rhine-Main cluster concentrates Germany's data center networking demand through hyperscale campuses serving transatlantic connectivity and AI training workloads.
Bavaria
Munich's automotive and semiconductor manufacturing base drives industrial edge computing deployments requiring deterministic latency guarantees. The Bavarian State Ministry for Economic Affairs supports Industry 4.0 infrastructure investments through regional technology funding programs. Ingolstadt and Nuremberg host Mittelstand manufacturers consolidating vendor relationships for shop-floor automation networks.
North Rhine-Westphalia
Cologne and Düsseldorf financial services firms sustain demand for low-jitter switching fabrics in trading infrastructure. The state's IT security agency enforces BSI IT-Grundschutz procurement standards that constrain vendor selection for critical infrastructure contracts. Ruhr region colocation providers lack high-density networking, creating whitespace for distributed spine architectures.
Baden-Württemberg
Stuttgart's machinery and automotive engineering sectors require unified IP-storage fabrics as NVMe-over-TCP collapses separate procurement silos. The Ministry of Economic Affairs, Labour and Tourism coordinates digital infrastructure grants for SME manufacturing facilities. Karlsruhe's research institutions pilot software-defined WAN optimization for multi-tenant scientific computing environments.
Berlin-Brandenburg
Cloud providers compress refresh cycles to three years to accommodate AI inference clusters in urban hyperscale facilities. The Berlin Senate Department for Economics, Energy and Public Enterprises administers energy efficiency compliance tied to EU directive implementation. Adlershof technology park anchors public-private partnerships for automated network provisioning in research data lakes.
Hamburg
Port logistics and maritime trade finance generate demand for disaster recovery replication between northern and central facilities. The Hamburg Ministry of Economics and Innovation oversees CSRD-aligned procurement requiring 15-year total cost of ownership analyses. HafenCity development zones integrate edge colocation for latency-sensitive shipping and insurance applications.
Germany Data Center Networking Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Germany's data center networking market, creating a tiered structure where integrated infrastructure vendors face specialized component suppliers. Incumbent switching equipment manufacturers anchor enterprise relationships through channel partnerships, while optical component specialists capture margin in high-speed transceiver segments. Strategic archetypes include full-stack infrastructure bundlers, disaggregated software vendors, and silicon photonics component suppliers. Competitive intensity concentrates on rapid-deployment contract structures and service delivery model reconfiguration around three-year refresh cycles.
Within the integrated infrastructure tier, Cisco Systems Inc. and Dell Technologies Inc. exemplify vendors capturing enterprise consolidation trends through bundled server-storage-networking offerings. Juniper Networks Inc. occupies a position representing automated WAN optimization specialists targeting multi-tenant facility operators. These three companies anchor the competitive landscape through distinct channel and technology positioning strategies that reflect broader vendor archetype segmentation across Rhine-Main and Berlin deployment zones.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Juniper Networks Inc. |
| Dell Technologies Inc. |
| IBM Corporation |
| VMware Inc. |
| Huawei Technologies Co. Ltd. |
| NVIDIA Corp. (Cumulus Networks) |
| Extreme Networks Inc. |
| Intel Corporation |
| Others |
Pricing and Supply Chain Analysis
Silicon wafer spot indices and rare earth element benchmarks cascade through optical component manufacturing into three-tier pricing structures across German data center networking procurement. Equipment vendors absorb upstream volatility through contract renegotiation clauses while hyperscale buyers extract volume discounts from compressed refresh cycles.
Pricing Analysis
Cost-down pressure on 800G optical transceiver tiers accelerates because Asian DSP foundry concentration enables hyperscale buyers to consolidate procurement leverage. Pricing stratifies across premium low-jitter variants for financial services, standard enterprise SKUs, and economy-grade copper alternatives for short-reach server racks. PUE mandates under the EU Energy Efficiency Directive force facility operators toward premium optical interconnects despite higher unit costs. Cloud providers exhibit lowest price sensitivity due to TCO-driven procurement, while Mittelstand manufacturers negotiating managed network-as-a-service contracts face strict budget constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand in Frankfurt and Berlin, while systems integrators distribute to enterprise and colocation segments across secondary cities. Manufacturing concentrates in Taiwan for advanced switch ASICs, China for optical transceivers and passive components, and the United States for specialized silicon photonics designs. German equipment vendors draw from Taiwanese semiconductor foundries, Chinese rare earth processing facilities, and Malaysian assembly operations. Single-source vulnerability in coherent DSP supply creates exposure to export control fluctuations. Distribution runs through authorized distributor networks serving Rhine-Main campuses and direct fulfillment contracts for hyperscale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's data center networking sector sits in a technology-transition phase where 800G optical interconnects displace legacy copper and 100G/200G architectures. Co-packaged optics integration is compressing traditional transceiver vendor margins while opening new service revenue pools.
For Market Incumbents: Acquire silicon photonics design capabilities to defend against disaggregated switch vendors threatening integrated equipment margins. Cisco and Juniper must deepen channel control over Bavarian systems integrators as Dell's bundled server-storage-networking offerings capture Mittelstand consolidation trends. Certification investment in BSI IT-Grundschutz compliance protects federal contract access against non-EU vendor exclusion.
For New Entrants and Emerging Players: Co-packaged optics specialization offers entry into hyperscale procurement as traditional pluggable transceiver vendors lose aggregation-tier share. Edge colocation facilities in Hamburg, Munich, and Düsseldorf present the most penetrable whitespace given underinvestment in high-density spine architectures. Go-to-market through managed network-as-a-service partnerships with regional systems integrators bypasses direct competition with entrenched channel relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor optical component specialists with coherent modulation IP in German-speaking markets as 400G/800G signal integrity talent scarcity delays validation timelines. Long-term viability hinges on European manufacturing footprint advantages under CSRD embodied carbon disclosure requirements. Watch EU AI Act high-risk system classification implementation as the inflection indicator for deterministic latency guarantee demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Acquisition | Co-packaged optics integration captures 30% power reduction premiums in Frankfurt hyperscale tenders. |
| BSI IT-Grundschutz Certification Investment | Federal procurement compliance opens Hesse and Berlin critical infrastructure contracts to qualified vendors. |
| Edge Colocation Partnership | Munich and Hamburg distributed spine deployments address underpenetrated secondary city whitespace. |
| Managed Network-as-a-Service Launch | Bundled hardware-software-support contracts mirror hyperscale discipline for Mittelstand manufacturers. |
| Liquid-Cooled Switching Platform Development | PUE threshold compliance under EU Energy Efficiency Directive shapes Rhine-Main procurement specifications. |
Research Methodology
SEC filings, hyperscaler capital expenditure disclosures, and EU regulatory databases formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with data center facility operators, network engineering directors at cloud providers, procurement leads at colocation providers, and channel managers at systems integrators validated equipment deployment trends and refresh cycle compression patterns. Bottom-up port shipment estimates and top-down infrastructure spending analysis triangulated segment-level demand across the analysis window.
Historical trendline analysis of Ethernet switching revenue, optical transceiver shipments, and data center construction permits established baseline growth trajectories. The analytical framework modeled product type segmentation by speed tier, technology protocol adoption curves, end-user procurement sophistication, and application workload characteristics across the projection horizon. CAGRs derived from equipment vendor guidance, facility operator expansion announcements, and regulatory compliance timelines. AI training cluster density requirements and NVMe-over-TCP convergence patterns served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen export control expansions affecting DSP supply, abrupt shifts in EU AI Act implementation timelines, and hyperscale demand destruction from macroeconomic contraction. Forecasts reflect base-case assumptions regarding PUE threshold enforcement consistency and three-year refresh cycle stabilization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Europe Data Center Networking Market
Data Center and Networking
Vietnam Data Center Networking Market
Data Center and Networking
Data Deduplication Tools Market
Data Center and Networking
Content Delivery Network (CDN) Market
Data Center and Networking
Global Heterogeneous Network Market
Data Center and Networking
New Zealand Data Center Networking Market
Data Center and Networking
Application Delivery Network (ADN) Market
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Global Network Configuration and Change Management Market
Data Center and Networking
Canada Data Center Networking Market
Data Center and Networking
Hong Kong Data Center Networking Market
Data Center and Networking
Global Cloud Content Delivery Network Market
Data Center and Networking
Communications Service Provider (CSP) Network Market
Data Center and Networking
Managed Network Services Market
Data Center and Networking
Mobile Data Traffic Market