
 Hardware Encryption Market | 2026-2036
Hardware Encryption Market Size, Share, and Industry Trends Forecast 2026-2036
Hardware Encryption Market Intelligence
FIPS 140-3 validation is unwinding the competitive landscape for hardware encryption vendors, forcing costly recertification cycles that smaller players cannot absorb. Samsung Electronics leverages captive semiconductor fabrication to sustain cost leadership in NAND-based encrypted storage. Thales anchors European demand through its certified hardware security module portfolio. Micron Technology competes on memory-integrated encryption density for enterprise data centers.
Hardware encryption employs dedicated cryptographic processors embedded within storage controllers, network interfaces, or standalone modules to perform AES-256, RSA, or ECC operations without exposing plaintext to host systems. The technology protects data at rest and in transit across government, financial, and healthcare infrastructure where software-only solutions prove vulnerable to side-channel attacks. Full Disk Encryption dominates volume shipments due to baseline regulatory requirements, while Hardware Security Modules capture disproportionate margin pools from high-assurance applications. Asymmetric Encryption leads enterprise network security deployments, though Quantum Cryptography represents the fastest-growing technology segment as post-quantum migration timelines tighten.
NIST FIPS 140-3 in the United States, ETSI standards under the EU Cybersecurity Act, and China's GB/T cryptographic certification collectively shape product roadmaps and market access conditions for hardware encryption vendors. These frameworks mandate physical tamper resistance, side-channel countermeasures, and supply chain provenance that determine which architectures qualify for public-sector procurement. Stakeholders must monitor post-quantum algorithm standardization timelines and corresponding hardware refresh cycles to avoid stranded inventory and compliance gaps.
Market Dynamics
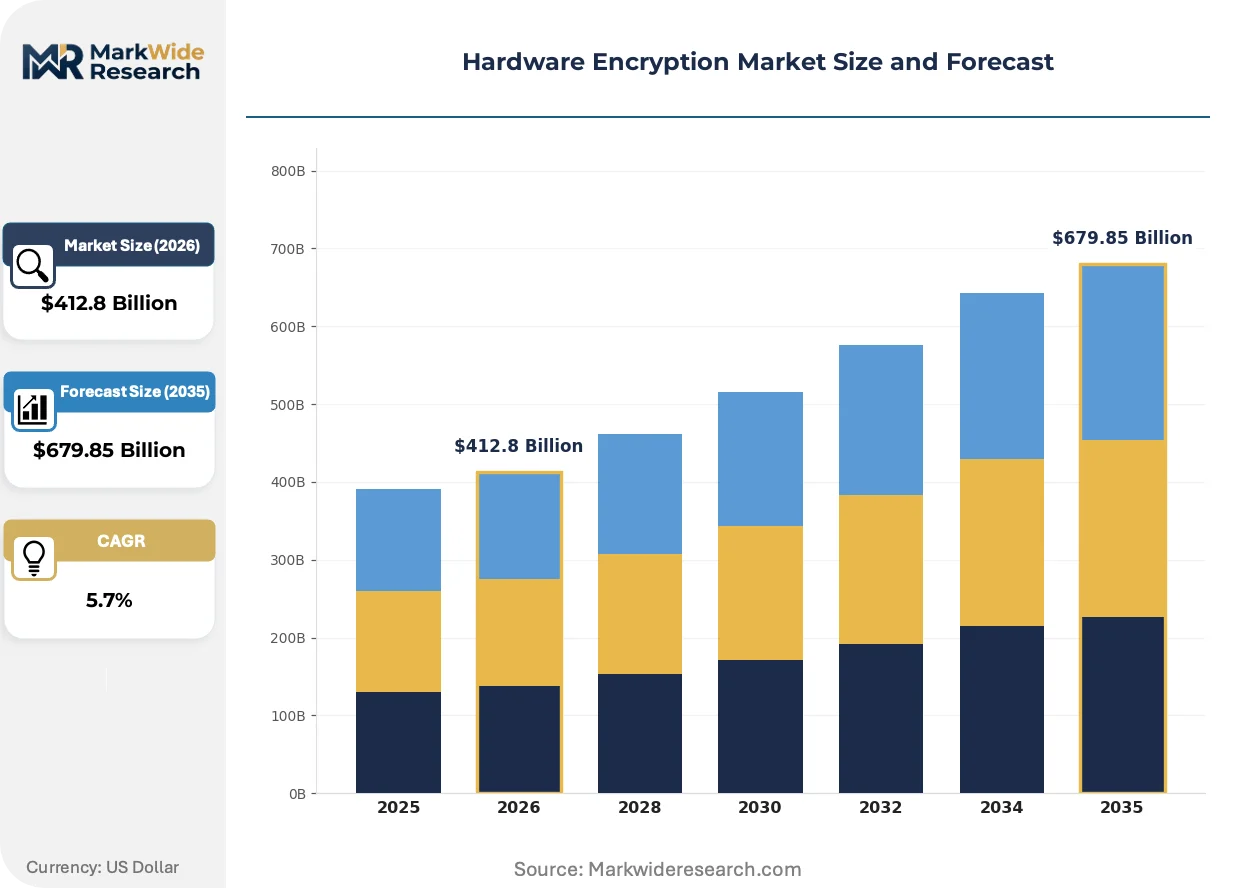
FIPS 140-3 recertification mandates are forcing hardware encryption vendors into costly architectural redesigns, consolidating procurement decisions around certified suppliers while squeezing marginal players from public-sector tenders.
Growth Catalysts
- GDPR data residency mandates:Germany's automotive and financial sectors are mandating hardware-based key storage for cross-border transaction processing, accelerating HSM deployment in manufacturing clusters.
- Post-quantum algorithm standardization:NIST's lattice-based cryptography finalists are driving early hardware refresh cycles among defense contractors preparing for quantum-resistant infrastructure.
- Healthcare data breach penalties:HIPAA enforcement actions exceeding $5 million per incident are pushing hospital networks toward self-encrypting drives for patient record systems.
Market Restraints
- Silicon supply concentration:Advanced cryptographic processor fabrication depends on TSMC's 7nm and 5nm nodes, creating single-source vulnerability for high-assurance modules.
- Recertification cost barriers:FIPS 140-3 Level 3 validation cycles now exceed 18 months and $800,000 per product variant, freezing SME vendor participation.
- Software encryption substitution:Cloud-native key management services from hyperscalers are capturing mid-market workloads previously served by on-premise hardware.
Strategic Opportunities
- Edge computing security gaps:Autonomous vehicle ECUs and industrial IoT gateways lack standardized hardware roots of trust, creating openings for automotive-grade secure elements.
- EU Cybersecurity Act certification:ETSI's Common Criteria-based hardware evaluation schemes are creating preferential market access for pre-certified European suppliers.
- Memory-integrated encryption convergence:CXL-attached persistent memory controllers with inline AES engines are enabling new performance tiers for AI training infrastructure.
Industry Challenges
- Cryptographic engineering talent scarcity:Side-channel analysis and fault injection testing expertise concentrates among defense contractors, limiting vendor validation capacity.
- Legacy infrastructure integration friction:Mainframe and SCADA systems with decades-old bus architectures require custom firmware bridges for modern HSM connectivity.
- Supply chain provenance verification:NIST's hardware bill of materials requirements demand semiconductor-level traceability that most vendors cannot document.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hardware Encryption Market |
| Market Size in 2026 | $412.8 Billion |
| Market Size in 2035 | $679.85 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Disk Encryption, USB Encryption, Network Encryption, Hardware Security Modules Technology: Symmetric Encryption, Asymmetric Encryption, Quantum Cryptography, Tokenization End User: Government, BFSI, Aerospace, Healthcare Deployment Model: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Western Digital Technologies, Samsung Electronics, Micron Technology, Seagate Technology, Intel Corporation, Kingston Technology Corporation, NetApp, Thales, Gemalto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hardware Encryption Market Strategic Shifts & Innovations
Hardware encryption architectures are bifurcating between commodity full-disk controllers and high-margin quantum-resistant modules, with certification velocity determining competitive survival.
Homomorphic encryption accelerators are supplanting traditional secure enclaves for privacy-preserving machine learning workloads. Cloud service providers in North America are deploying experimental FPGA-based solutions for encrypted inference. This shift is compressing margins on conventional HSM products while opening specialized silicon categories.
ETSI's quantum-safe cryptography standardization timeline is accelerating procurement clause revisions across European defense and critical infrastructure tenders. Hardware vendors must now pre-integrate CRYSTALS-Kyber and CRYSTALS-Dilithium engines to maintain eligibility. German automotive OEMs are imposing 2030 quantum-readiness deadlines on tier-one suppliers.
Consolidated enterprise buying through managed security service providers is displacing direct hardware procurement for mid-market customers. MSSPs are standardizing on multi-tenant HSM-as-a-service platforms with API-first key orchestration. This pattern is most visible in United Kingdom financial services, where three banking consortiums have pooled infrastructure procurement.
Hardware Encryption Market Segmentation
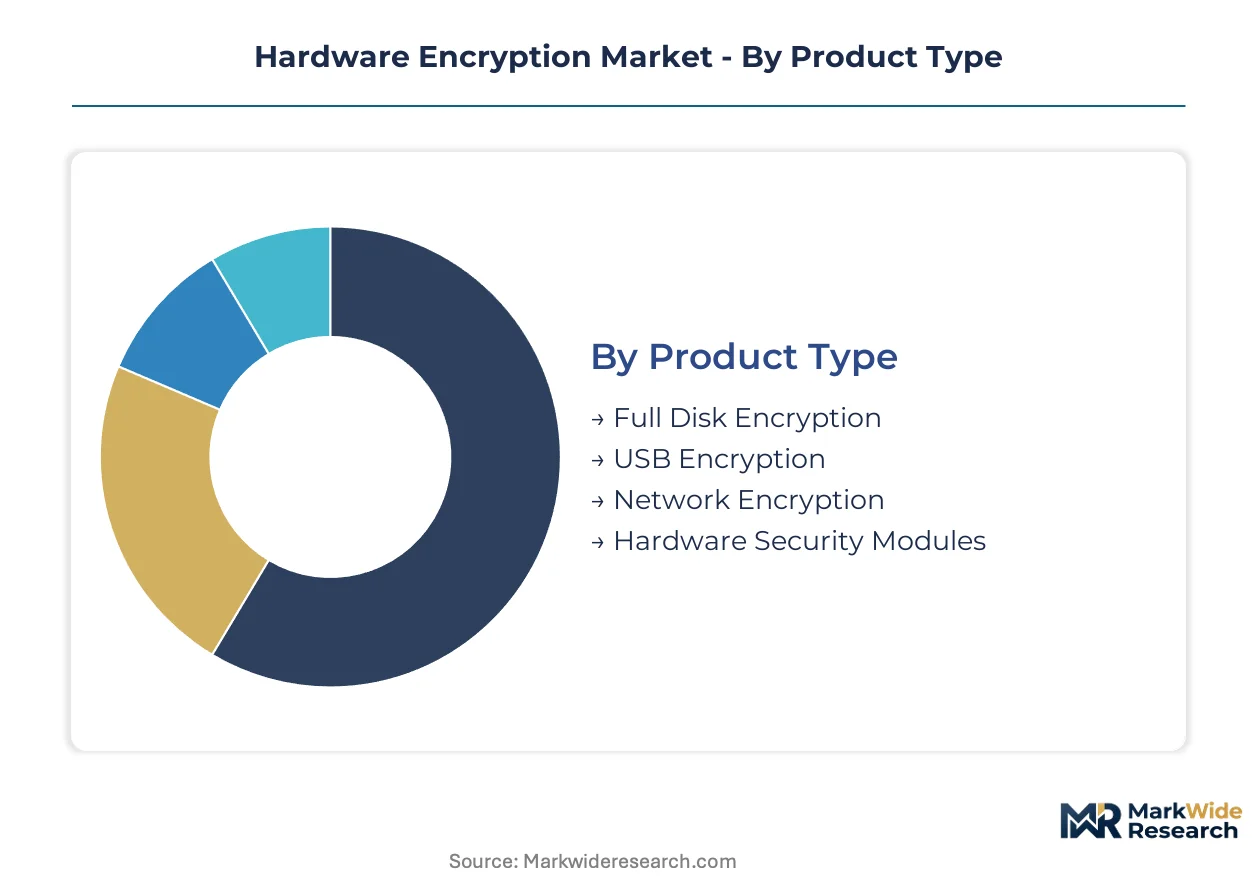
Segmentation in hardware encryption reveals how margin pools concentrate around certification tiers and integration complexity. Product architecture choices determine whether vendors compete on volume or capture premium pricing from high-assurance applications.
Product Type:
Margin concentration follows certification depth, with validated modules commanding multiples over commodity storage controllers.
- Full Disk Encryption:Self-encrypting drive controllers embed AES-256 engines directly into NAND flash or HDD firmware, performing cryptographic operations without host CPU involvement. Healthcare networks in the United States are mandating these drives for HIPAA-compliant patient record storage after enforcement actions crossed $5 million per breach incident. The dominant share belongs to Full Disk Encryption, while Hardware Security Modules are closing the gap fastest.
- Hardware Security Modules:Tamper-resistant appliances or PCIe cards generate, store, and manage cryptographic keys within physically protected boundaries certified to FIPS 140-3 Level 3 or Common Criteria EAL4+. German automotive OEMs are requiring HSM-backed key storage for ECU firmware signing as digitization accelerates across manufacturing clusters.
- USB Encryption:Portable flash drives with onboard cryptographic processors enforce PIN or biometric authentication before data access. Enterprises deploy these for contractor file transfers and executive travel security.
- Network Encryption:Inline appliances or MACsec/IPsec accelerators protect data in transit across WAN links and data center interconnects. Financial services firms deploy these for inter-bank transaction protection.
Volume leadership rests with Full Disk Encryption, though Hardware Security Modules are expanding most quickly on post-quantum refresh cycles.
Technology:
Technology selection maps directly to threat model sophistication, with quantum-resistant algorithms attracting defense-sector investment ahead of standardization completion.
- Asymmetric Encryption:RSA-4096 and ECC P-256/P-384 implementations handle key exchange and digital signatures across enterprise PKI infrastructure. NIST's post-quantum migration timelines are forcing hardware refresh decisions among United States defense contractors preparing for CRYSTALS-Kyber and CRYSTALS-Dilithium deployment. Asymmetric Encryption holds the installed base advantage, while Quantum Cryptography is gaining share fastest.
- Quantum Cryptography:Lattice-based and hash-based hardware engines provide algorithmic resistance against quantum computing attacks. ETSI standardization under the EU Cybersecurity Act is accelerating procurement clause revisions across European critical infrastructure tenders.
- Symmetric Encryption:AES-128 and AES-256 block ciphers dominate bulk data protection for storage and transport applications. Hardware implementations achieve line-rate throughput without host processor overhead.
- Tokenization:Format-preserving substitution replaces sensitive data elements with non-sensitive equivalents, reducing cryptographic scope in payment processing environments.
Symmetric Encryption processes the highest data volumes, though Quantum Cryptography is climbing the fastest on regulatory pull-through.
End User:
End-use concentration reflects regulatory enforcement intensity, with breach penalty regimes directly correlating to hardware security spending.
- BFSI:Banks, insurers, and payment processors deploy HSM clusters for transaction signing, key ceremony operations, and regulatory audit trails. United Kingdom banking consortiums are pooling procurement through managed security service providers to amortize infrastructure costs across multiple institutions.
- Government:Defense and civilian agencies mandate FIPS 140-3 validated modules for classified and sensitive but unclassified workloads. NIST certification requirements are consolidating supplier bases around vendors with sustained validation capacity.
- Healthcare:Hospital networks and health information exchanges implement self-encrypting storage for electronic health records. HIPAA enforcement escalation is converting software-only encryption to hardware-backed implementations.
- Aerospace:Satellite operators and airframe manufacturers require radiation-hardened cryptographic modules for command authentication and secure telemetry.
BFSI maintains the largest committed budgets, while Healthcare is accelerating fastest on enforcement-driven replacement cycles.
Deployment Model:
Deployment architecture determines supply chain configuration, with edge-native implementations requiring automotive-grade temperature and vibration specifications absent from data center products.
- On-Premise:Dedicated hardware appliances within enterprise facilities provide maximum control over key material and audit logging. Financial services firms in Germany favor this model for GDPR data residency compliance.
- Cloud-Based:Hyperscaler-managed HSM services offer API-accessible key management without capital expenditure. Mid-market enterprises are migrating here from owned infrastructure.
- Hybrid:Split deployments maintain root of trust on-premise while delegating operational key handling to cloud services. This architecture satisfies multi-jurisdiction compliance requirements.
- Edge Computing:Distributed cryptographic modules in vehicles, industrial gateways, and remote sensors protect data generation points. German automotive OEMs are imposing 2030 quantum-readiness deadlines on tier-one suppliers for these deployments.
On-Premise retains the largest footprint, though Edge Computing is expanding most rapidly on autonomous vehicle and industrial IoT security mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber cable landing stations in Ireland and the Netherlands underpin Europe's data sovereignty infrastructure. Germany's automotive manufacturing corridors and the United States' defense procurement networks anchor hardware encryption demand across distinct regulatory environments.
United States
NIST FIPS 140-3 recertification mandates are consolidating supplier bases around vendors with sustained validation capacity. The Department of Defense's CMMC 2.0 framework now requires Level 3 certification for cryptographic modules handling controlled unclassified information. Defense contractors in the Baltimore-Washington corridor are accelerating hardware refresh cycles ahead of post-quantum algorithm standardization.
Germany
GDPR data residency mandates are pushing automotive OEMs toward hardware-backed key storage for ECU firmware signing. The BSI's technical guidelines for quantum-safe cryptography are tightening procurement eligibility for critical infrastructure tenders. Manufacturing clusters in Bavaria and Baden-Württemberg are imposing 2030 quantum-readiness deadlines on tier-one suppliers.
China
GB/T cryptographic certification requirements are creating parallel validation tracks for domestic and export-oriented product lines. The State Cryptography Administration's commercial encryption regulations mandate hardware security modules for financial transaction processing. Semiconductor foundries in the Yangtze River Delta are expanding captive production of cryptographic processors for government and banking procurement.
Japan
METI's cybersecurity framework revisions are mandating hardware roots of trust for industrial control systems in critical infrastructure. The JIS X 0902 standard for cryptographic modules is converging with Common Criteria evaluation methodologies. Automotive electronics suppliers in the Nagoya manufacturing belt are integrating secure elements for connected vehicle platforms.
United Kingdom
Banking consortiums are pooling infrastructure procurement through managed security service providers to amortize HSM costs across multiple institutions. The National Cyber Security Centre's guidance on quantum-safe migration is accelerating clause revisions in financial services tenders. London's fintech cluster is deploying hybrid cloud-HSM architectures for multi-jurisdiction compliance.
Hardware Encryption Market Key Industry Players
Listed leaders compete with private specialists across certification velocity and captive fabrication capacity. The vendor base separates into three tiers: multinational semiconductor conglomerates with captive foundry access, defense-focused security module specialists with sustained validation pipelines, and regional storage component fabricators competing on cost. Consolidation pressures concentrate around FIPS 140-3 Level 3 validation capacity, which now exceeds eighteen months per product variant. Strategic moves center on backward integration into cryptographic processor design and geographic expansion through ETSI pre-certification for European market access.
Within the semiconductor-integrated tier, Samsung Electronics and Micron Technology exemplify scale-driven positioning through captive NAND fabrication and memory-integrated encryption density. Thales occupies a position among defense-security specialists with sustained Common Criteria and FIPS validation capacity across European and North American procurement channels. Kingston Technology Corporation represents the component-specialist archetype, competing on volume shipments for enterprise storage replacement cycles.
| Leading Market Players |
|---|
| Western Digital Technologies |
| Samsung Electronics |
| Micron Technology |
| Seagate Technology |
| Intel Corporation |
| Kingston Technology Corporation |
| NetApp |
| Thales |
| Gemalto |
| Others |
Cost & Logistics Intelligence
Post-quantum algorithm migration is displacing legacy cryptographic processor inventories, simultaneously redrawing foundry demand geography toward Taiwan and South Korea while compressing pricing premiums on FIPS 140-2 certified modules. This substitution dynamic concentrates procurement leverage among defense contractors with pre-approved validation pipelines, forcing commodity-tier vendors toward volume-driven contract structures.
Pricing Analysis
Volume-discount tiering structures separate FIPS 140-3 Level 4 validated modules from Level 2 storage controllers and uncertified economy-grade components. Certification depth and captive semiconductor fabrication capacity drive price differentiation, with German automotive OEMs paying premiums for BSI-evaluated quantum-safe engines while mid-market healthcare networks negotiate standard-tier self-encrypting drive contracts. Pricing pressure stems from cloud-native key management services capturing workloads previously served by on-premise hardware. Government and defense segments demonstrate least price sensitivity due to mandated compliance requirements, whereas mid-market financial services exhibit highest elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate defense and critical infrastructure procurement, with eighteen-month validation cycles forcing advance commitments to cryptographic processor wafer starts. Advanced node fabrication concentrates in Taiwan, South Korea, and the United States, drawing from EUV lithography equipment, silicon wafers, and rare earth packaging materials. Single-source vulnerability at TSMC's 5nm capacity creates structural risk for high-assurance module production. Distribution runs through certified value-added resellers and direct OEM partnerships rather than commodity electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware encryption sits in early-cycle expansion as post-quantum migration timelines convert deferred infrastructure spending into immediate procurement mandates across defense and automotive verticals.
For Market Incumbents: Compound validation capacity advantages by accelerating FIPS 140-3 Level 4 pipeline submissions before NIST crystallizes post-quantum hardware requirements. Secure captive foundry allocation agreements with TSMC or Samsung to preempt supply rationing during defense-sector refresh waves. Deepen backward integration into cryptographic processor design to capture margin pools currently flowing to fabless competitors.
For New Entrants and Emerging Players: Anchor in edge computing security gaps where automotive-grade secure elements lack standardized roots of trust and incumbent certification velocity lags demand. Target industrial IoT gateway deployments in German manufacturing clusters where ETSI pre-certification creates preferential access. Pursue MSSP partnership routes rather than direct enterprise sales to bypass entrenched procurement relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward defense-security specialists with sustained Common Criteria validation pipelines and established relationships with European national cybersecurity agencies. Long-term viability hinges on post-quantum hardware refresh cycle capture rather than commodity storage controller volume. Watch NIST algorithm standardization completion as the inflection signal triggering accelerated procurement clause revisions across federal and defense tenders.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Hardware Certification | FIPS 140-3 Level 4 validation with CRYSTALS-Kyber engines secures eligibility for Department of Defense CMMC 2.0 procurement mandates. |
| Cryptographic Processor Backward Integration | In-house AES and lattice-based accelerator design reduces dependency on TSMC allocation cycles and captures silicon margin. |
| ETSI Pre-Certification for European Access | Common Criteria EAL4+ evaluation under EU Cybersecurity Act unlocks German automotive and critical infrastructure tenders. |
| Edge-Native Secure Element Development | Automotive-grade temperature and vibration specifications address autonomous vehicle ECU security gaps ahead of 2030 quantum-readiness deadlines. |
| MSSP Platform Partnership | API-first HSM-as-a-service architectures capture mid-market financial services migrating from owned infrastructure to pooled procurement models. |
Research Approach
Initial hypotheses were tested against primary input from hardware security module product managers, semiconductor foundry planning officers, defense contractor procurement leads, and automotive OEM cybersecurity architects and refined through secondary validation. Primary fieldwork combined structured interviews with secondary analysis of NIST certification databases, ETSI technical specifications, SEC 10-K filings from listed semiconductor vendors, and customs trade data for cryptographic processor imports. Bottom-up demand modeling across end-use segments was triangulated against top-down market sizing from foundry capacity disclosures and defense procurement budget allocations.
Variance decomposition across the projection horizon isolates volume, price, and mix contributions to value expansion. Segmentation dimensions modeled include product architecture tier, certification level, deployment model, end-use vertical, and regional regulatory cluster. CAGRs were derived from segment-level growth rate synthesis rather than single-point extrapolation. Forecast inputs incorporated NIST post-quantum standardization timelines, GDPR enforcement intensity indices, and automotive ECU digitization curves.
Material uncertainties — algorithm standardization delays, foundry capacity rationing, and certification backlog extensions — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained regulatory enforcement and supply chain continuity. Revision becomes warranted when FIPS 140-3 validation cycle duration crosses twenty-four months or when post-quantum algorithm selection diverges from NIST finalist projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Messaging Security Market
Security Software
Asia Pacific Video Management System Market
Security Software
Global Email Verification Tools Market
Security Software
Global Log Management Market
Security Software
Network Camera and Video Analytics Market
Security Software
Europe IP Video Intercom Device and Equipment Market
Security Software
Application Control Market
Security Software
Global Consumer Identity and Access Management Market
Security Software
Phone Antivirus Software Market
Security Software
Global Software-Defined Security Market
Security Software
Global Error Monitoring Software Market
Security Software
Public Key Infrastructure (PKI) Market
Security Software
Cloud Security Software Market
Security Software
Remote Access Management Market
Security Software
Employee Fraud Detection Market
Security Software
Broadcast Censorship Solutions Market