
 Network Camera and Video Analytics Market | 2026-2036
Network Camera and Video Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Network Camera and Video Analytics Market Outlook
4K resolution and AI-enhanced imaging is redrawing procurement standards across the network camera industry. Hangzhou Hikvision Digital Technology Co., Ltd. leverages its vertically integrated sensor manufacturing to dominate mid-market deployments. Axis Communications AB differentiates through open-platform software ecosystems that sustain premium positioning in European enterprise accounts. Bosch Security Systems anchors its competitive stance with automotive-grade reliability standards transferred from its mobility division.
Network cameras and video analytics comprise IP-connected imaging devices coupled with software algorithms that perform real-time object detection, behavioral analysis, and automated alerting without continuous human monitoring. These systems encode video streams at resolutions up to 8K while edge processors execute convolutional neural networks directly on camera hardware, enabling sub-100-millisecond response times for security and operational applications. Fixed cameras and dome cameras represent the mature volume base where margin compression is most severe, while thermal cameras command premium pricing in perimeter defense and fire-detection roles. Edge analytics is the fastest-expanding technology category as latency-sensitive applications in traffic monitoring and industrial monitoring reject cloud-dependent architectures.
FCC certification requirements in the United States, GDPR data-processing constraints under European regulators, and China's GB standards for network equipment collectively determine which products gain market access. The EU AI Act's risk-classification framework for biometric identification is forcing vendors to reengineer firmware architectures before products can ship to member states. Stakeholders must monitor whether national procurement rules in defense, transportation, and critical infrastructure sectors fragment into incompatible technical standards that multiply compliance costs.
Market Dynamics
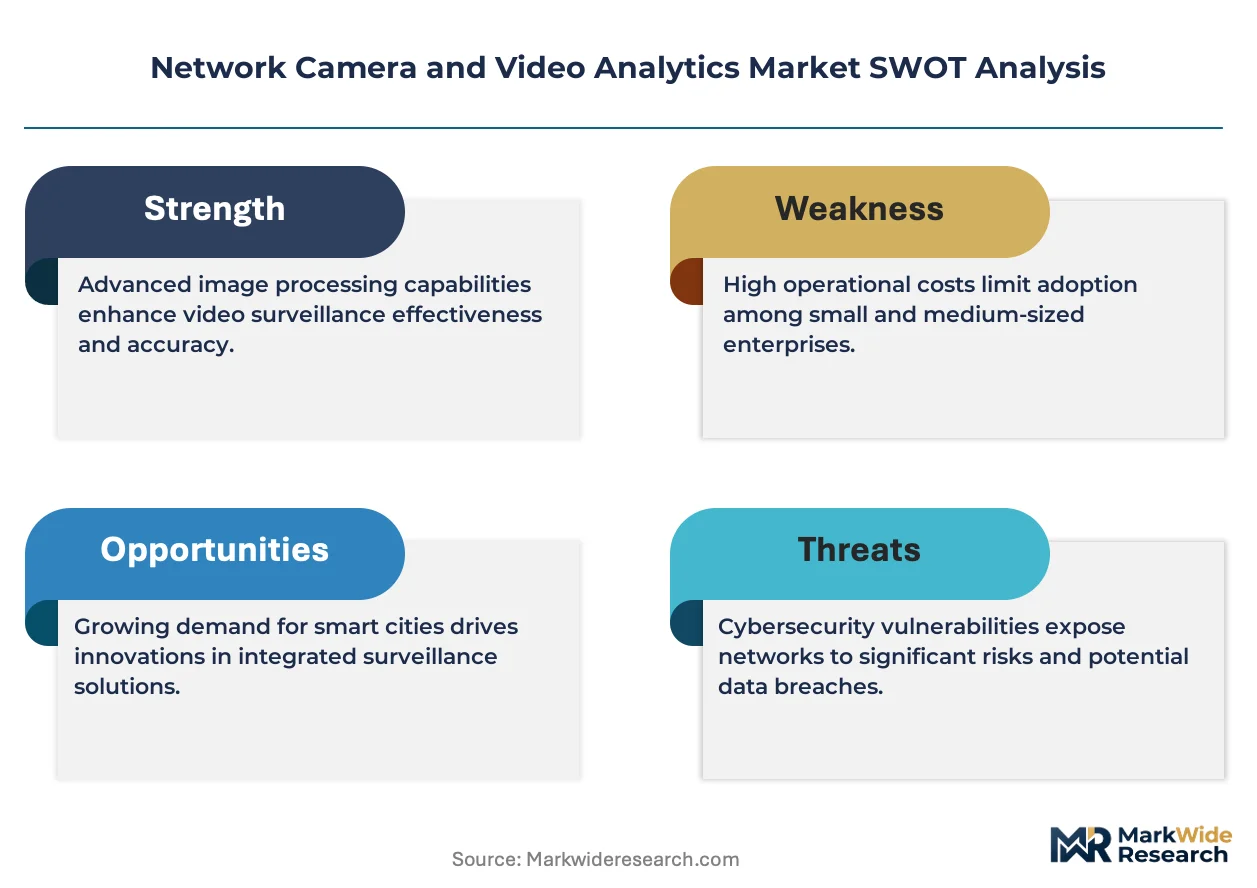
The transition from cloud-dependent processing to on-device inference is compressing latency benchmarks and rewiring competitive advantage toward edge silicon capabilities.
Growth Catalysts
- EU AI Act biometric risk classification:Mandates for privacy-by-design firmware are accelerating procurement of compliant architectures in European smart city deployments.
- Edge analytics convergence:Convolutional neural networks executing directly on camera hardware are displacing centralized server farms in traffic monitoring applications.
- Singapore-Dubai-Barcelona cluster demand:Municipal procurement of AI-enabled traffic systems is concentrating volume in urban infrastructure verticals.
Market Restraints
- Sensor cost volatility:Image sensor wafer pricing fluctuations are compressing margins in the fixed and dome camera volume base.
- Supply concentration in East Asian component hubs:Dependency on concentrated semiconductor packaging capacity creates vulnerability to regional disruption.
- GDPR data-processing constraints:European regulatory friction limits cross-border video data flows and complicates multi-national enterprise deployments.
Strategic Opportunities
- India smart city infrastructure:Underpenetrated municipal surveillance markets present white space for AI-enabled perimeter defense systems.
- Industrial thermal monitoring:Fire-detection applications in energy and manufacturing facilities are expanding addressable demand beyond traditional security.
- ISO/IEC 27001 certification tailwind:Enterprise cybersecurity mandates are creating preference premiums for certified device vendors.
Industry Challenges
- Embedded AI firmware engineering scarcity:Talent gaps in low-power neural network optimization are extending product development cycles.
- FCC certification timeline compression:Radio frequency approval bottlenecks for wireless-enabled cameras are delaying US market entry.
- Legacy analog infrastructure integration:Hybrid deployment complexity with existing coaxial cabling is inflating total cost of ownership quotes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Camera and Video Analytics Market |
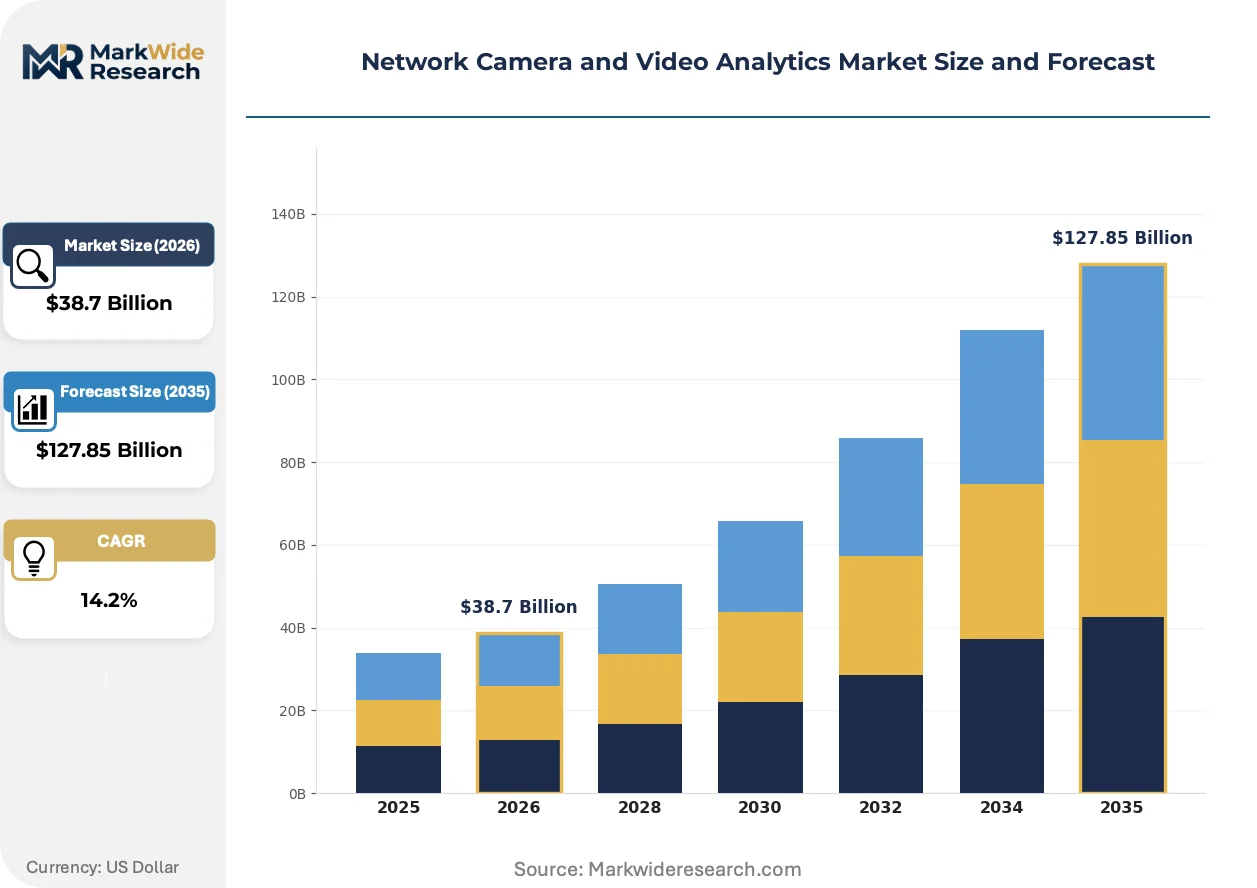
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Cameras, PTZ Cameras, Thermal Cameras, Dome Cameras Application: Traffic Monitoring, Retail Surveillance, Industrial Monitoring, Smart Cities Technology: IP Cameras, Analog Cameras, Cloud-Based Solutions, Edge Analytics End User: Government, Transportation, Retail, Education |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Dahua Technology Co., Ltd., Axis Communications AB, Hanwha Vision Co., Ltd., Honeywell International Inc., Bosch Security Systems, Motorola Solutions, Inc., Canon Inc., ADT Security Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Camera and Video Analytics Market Strategic Shifts
Resolution standards and processing architectures are advancing in parallel, with hardware miniaturization and regulatory pressure jointly determining which product configurations gain commercial traction.
Neural processing units embedded directly within camera housings are executing real-time object detection without external server dependency. Industrial monitoring and autonomous vehicle infrastructure buyers are adopting these systems fastest, demanding sub-100-millisecond response guarantees. Edge AI silicon is miniaturizing thermal and power envelopes, enabling fanless designs that expand deployment environments.
The EU AI Act's risk-tier framework for biometric identification systems is forcing firmware rearchitecture before products ship to member states. Vendors must now embed audit trails and explainability layers that were previously optional. European enterprise and government accounts are most affected, with procurement specifications now requiring explicit compliance documentation.
Enterprise buyers are consolidating vendor relationships and demanding unified platform management across heterogeneous device fleets. System integrators and value-added resellers are losing ground to direct manufacturer relationships for large-scale deployments. This concentration is most visible in United States critical infrastructure and transportation verticals, where single-source accountability is displacing multi-vendor best-of-breed approaches.
Network Camera and Video Analytics Market Segmentation
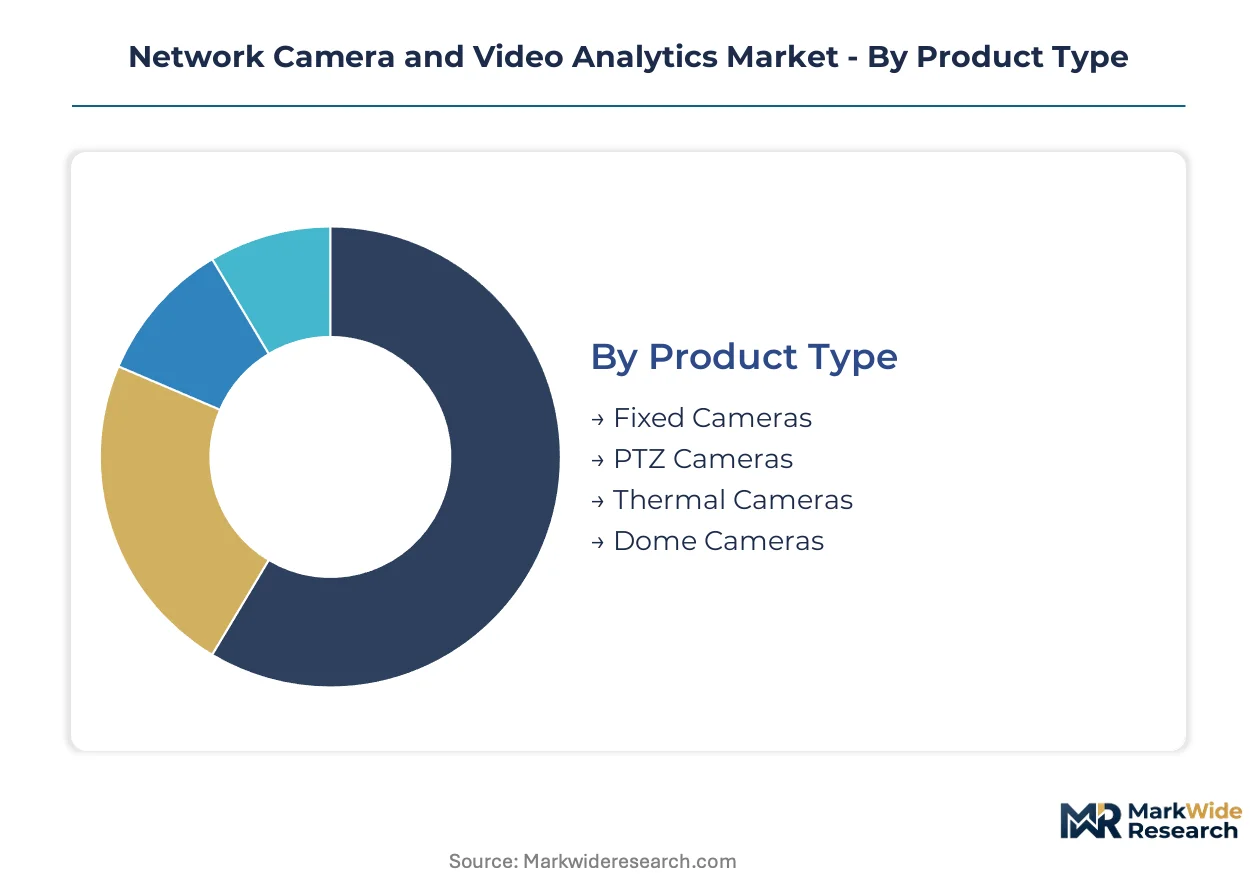
Network camera procurement decisions split across hardware form factors, deployment architectures, and compliance requirements that vary sharply by end-use vertical. Understanding where margin pools concentrate within each dimension reveals which product configurations command pricing power versus those trapped in commodity competition.
Product Type:
Margin pools concentrate in specialized imaging technologies where sensor differentiation and thermal engineering create defensible pricing tiers.
- Thermal Cameras:Uncooled microbolometer arrays detect infrared radiation across temperature differentials as small as 0.05°C, enabling perimeter defense and fire-detection applications. Energy facilities in Texas and manufacturing plants in Germany are driving procurement for predictive maintenance and early-warning systems.
- PTZ Cameras:Pan-tilt-zoom mechanisms with 30x optical zoom and continuous 360-degree rotation deliver targeted surveillance for large-area coverage. Airport authorities in Dubai and sports stadium operators in Singapore specify these units for active threat tracking and crowd flow analysis.
- Fixed Cameras:Stationary housings with fixed focal lengths dominate volume shipments for basic security coverage.
- Dome Cameras:Vandal-resistant enclosures with 360-degree fisheye lenses serve retail and hospitality environments requiring discrete positioning.
The dominant share belongs to Fixed Cameras, while Thermal Cameras is closing the gap fastest.
Application:
Volume concentration tracks municipal infrastructure spending cycles and regulatory mandates for public safety digitization.
- Smart Cities:Integrated sensor networks combining video analytics with air quality, noise, and traffic flow monitoring. Barcelona's municipal deployment and Singapore's Lamppost-as-a-Platform initiative are establishing procurement templates for multi-sensor urban operating systems.
- Traffic Monitoring:AI-enabled intersection management with automatic license plate recognition and pedestrian collision prediction. State transportation departments in California and highway operators in Germany are replacing legacy inductive loop systems with camera-based alternatives.
- Retail Surveillance:Footfall analytics and loss prevention systems for store operations optimization.
- Industrial Monitoring:Process safety and quality control applications in manufacturing environments.
Smart Cities captures the largest deployment value, with Traffic Monitoring expanding most quickly as federal infrastructure funding accelerates.
Technology:
Architecture choices determine latency performance, data sovereignty compliance, and total cost of ownership across deployment scales.
- Edge Analytics:Neural processing units executing convolutional neural networks directly on camera hardware achieve sub-100-millisecond inference without cloud dependency. Critical infrastructure operators in the United States and autonomous vehicle testbeds in China are mandating on-device processing for cybersecurity and latency guarantees.
- IP Cameras:Network-connected devices transmitting H.265-encoded streams over Ethernet or WiFi infrastructure. Enterprise security teams in Germany favor these units for centralized management and integration with access control systems.
- Cloud-Based Solutions:Centralized processing architectures with remote storage and analytics execution.
- Analog Cameras:Coaxial-based legacy systems surviving in cost-constrained retrofit environments.
IP Cameras maintains installed base leadership, though Edge Analytics is gaining share fastest as latency-sensitive applications reject cloud-dependent architectures.
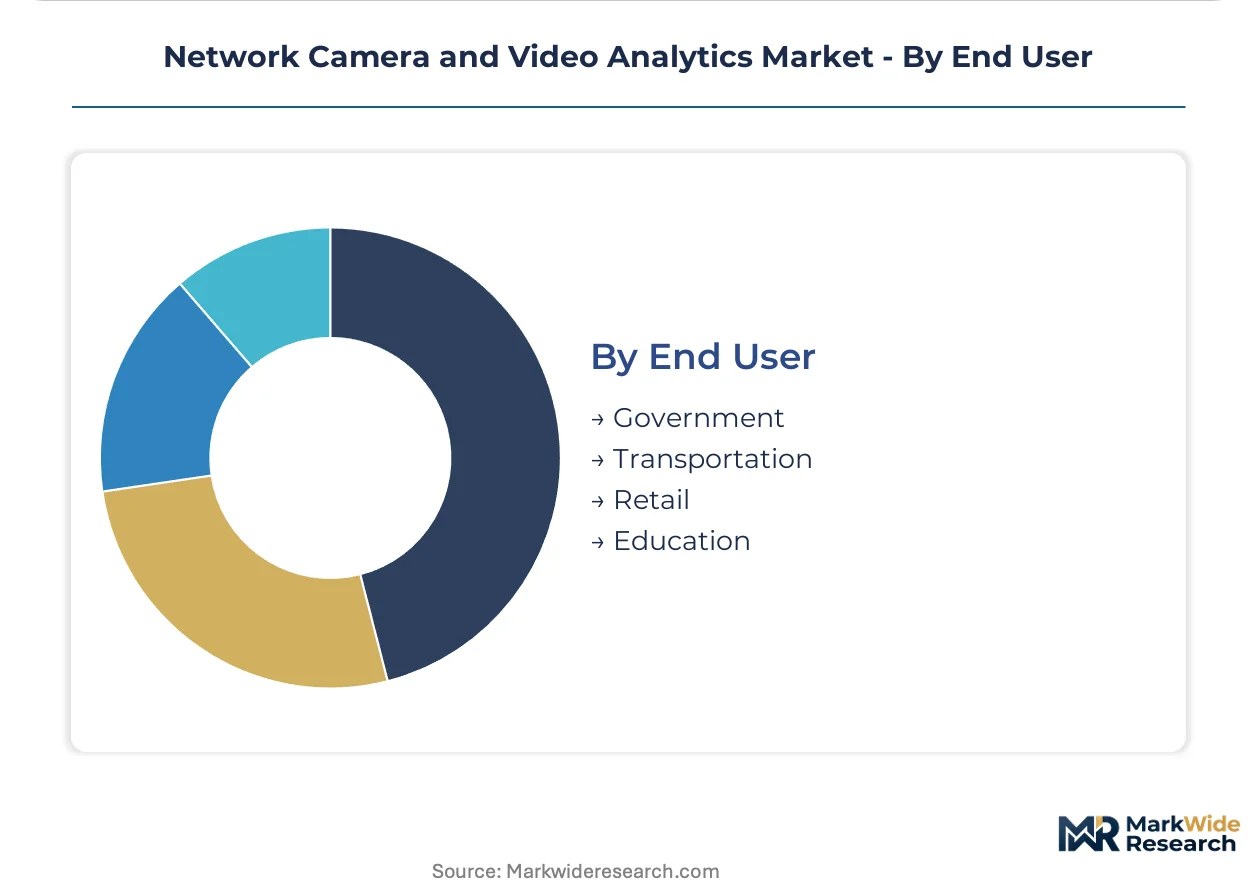
End User:
Budget authority and procurement complexity vary sharply across public and private sector buyers with divergent compliance obligations.
- Government:Federal, state, and municipal agencies with classified and unclassified facility security requirements. Defense installations in the United States and government buildings in Singapore specify NDAA-compliant supply chains and FIPS 140-2 encryption standards.
- Transportation:Airports, seaports, railways, and highway operators with 24/7 operational continuity mandates. Port authorities in Dubai and rail operators in Germany are consolidating vendor relationships for integrated platform management.
- Retail:Store chains and shopping centers prioritizing shrinkage reduction and customer analytics.
- Education:K-12 and university campuses with emergency response and access control requirements.
Government accounts represent the deepest vertical, while Transportation is climbing the fastest on infrastructure modernization cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in network camera components tilt toward East Asian manufacturing hubs, while regulatory divergence across jurisdictions is fragmenting product certification pathways. The United States, Germany, China, Japan, and Singapore concentrate procurement authority for AI-enabled surveillance infrastructure.
United States
Critical infrastructure operators and autonomous vehicle testbeds mandate sub-100-millisecond edge processing for cybersecurity guarantees. FCC certification timelines for wireless-enabled cameras create bottlenecks delaying market entry. Texas energy facilities and California transportation departments anchor procurement for thermal monitoring and traffic analytics systems.
Germany
Industrial manufacturers and rail operators consolidate vendor relationships for integrated platform management spanning security and operational technology. GDPR data-processing constraints limit cross-border video flows and complicate multi-national enterprise deployments. Bavarian automotive plants and Hamburg port authorities specify automotive-grade reliability standards for perimeter defense applications.
China
GB standards for network equipment determine product market access alongside MIIT cybersecurity review requirements for government procurement. Smart city deployments in Beijing and Shanghai accelerate AI-enabled traffic monitoring with domestic silicon preference. Yangtze River Delta manufacturers concentrate edge AI chip packaging capacity.
Japan
METI industrial digitization programs subsidize factory automation integrating video analytics for quality control and predictive maintenance. JIS standards compliance creates preference premiums for certified device vendors in enterprise security tenders. Kanto region semiconductor packaging specialists supply neural processing units for fanless camera designs.
Singapore
Lamppost-as-a-Platform initiatives establish procurement templates for multi-sensor urban operating systems combining video with environmental monitoring. Government buildings specify NDAA-compliant supply chains and FIPS 140-2 encryption for classified facility security. The municipal deployment anchors regional demand for privacy-by-design firmware architectures.
Network Camera and Video Analytics Market Competitive Environment
Listed leaders compete with private specialists across ownership structures, with publicly traded security conglomerates facing agile unlisted challengers in edge AI firmware development. The vendor base arranges into three tiers: integrated sensor manufacturers commanding mid-market volume, open-platform software specialists holding European enterprise accounts, and diversified industrial conglomerates leveraging cross-divisional reliability standards. Consolidation pressure intensifies as enterprise buyers demand single-source accountability across heterogeneous device fleets. Dominant competitive moves include strategic partnerships for silicon supply security and portfolio diversification into thermal imaging verticals.
Among Chinese fabricators, Hangzhou Hikvision Digital Technology Co., Ltd. and Dahua Technology Co., Ltd. exemplify the vertically integrated archetype with captive sensor production. Axis Communications AB occupies a position representing the open-platform software ecosystem model sustaining premium positioning in privacy-sensitive European markets. Bosch Security Systems anchors the industrial conglomerate tier, transferring automotive-grade reliability standards from mobility divisions into security hardware.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Dahua Technology Co., Ltd. |
| Axis Communications AB |
| Hanwha Vision Co., Ltd. |
| Honeywell International Inc. |
| Bosch Security Systems |
| Motorola Solutions, Inc. |
| Canon Inc. |
| ADT Security Services |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation agreements with Yangtze River Delta packaging houses lock in neural processing unit supply and stabilize unit economics for edge AI camera manufacturers facing volatile sensor wafer markets. These contractual structures insulate procurement teams from spot-market swings while committing volume thresholds that shape pricing visibility across quarterly production cycles.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in network camera procurement. Thermal imaging systems with uncooled microbolometer arrays command premium positioning due to fire-detection certification tiers and predictive maintenance integration complexity. Cost compression in fixed dome camera segments is intensifying because image sensor wafer pricing fluctuates with semiconductor foundry utilization rates. Municipal government accounts exhibit lowest price sensitivity due to compliance-driven specification requirements, while retail chains prioritize per-unit economy tiers for high-volume store deployments.
Supply Chain Analysis
Japan and Taiwan anchor neural processing unit and image sensor wafer fabrication for edge AI camera architectures. Component sourcing draws from South Korean memory packaging, Chinese lens module assembly, and German precision motor manufacturing for PTZ mechanisms. Single-source vulnerability concentrates in East Asian semiconductor packaging capacity exposed to regional logistics disruption. Distribution runs through authorized security integrators and direct enterprise relationships, with value-added resellers losing ground to manufacturer-direct procurement for large-scale smart city deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across privacy-by-design firmware development as EU AI Act compliance mandates create specialized engineering niches inaccessible to generalist vendors.
For Market Incumbents: Compound platform integration investments to consolidate heterogeneous device fleet management contracts displacing multi-vendor approaches in United States critical infrastructure. Deepen silicon supply security through strategic partnerships with Yangtze River Delta packaging specialists. Accelerate ISO/IEC 27001 certification coverage to capture enterprise cybersecurity mandate premiums before compliance deadlines tighten.
For New Entrants and Emerging Players: Firmware explainability layer development represents a service-layer gap where incumbents under-serve European government accounts facing EU AI Act audit trail requirements. Target India municipal surveillance markets with AI-enabled perimeter defense systems optimized for tropical climate deployment and localized language support. Pursue direct relationships with state transportation departments bypassing legacy security integrator channels.
For Investors and Strategic Acquirers: Edge AI firmware engineering boutiques with low-power neural network optimization capabilities constitute the most defensible acquisition target archetype given talent scarcity extending product development cycles. Long-term viability favors vendors with demonstrated compliance documentation for biometric risk classification frameworks. Monitor FCC certification timeline compression as inflection indicator for wireless-enabled camera market entry velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Silicon Partnership | Secures neural processing unit supply from Yangtze River Delta packaging specialists for latency-critical traffic monitoring. |
| Privacy-by-Design Certification | Accelerates EU AI Act compliance documentation for biometric identification systems in Barcelona and Singapore deployments. |
| Industrial Thermal Vertical Expansion | Captures fire-detection procurement from Texas energy facilities and German manufacturing plants beyond traditional security. |
| Direct Enterprise Channel Buildout | Displaces value-added resellers in United States transportation and critical infrastructure verticals demanding single-source accountability. |
| ISO/IEC 27001 Accreditation | Creates preference premiums in enterprise security tenders from Hamburg port authorities and Bavarian automotive plants. |
Study Parameters
Cross-validation between procurement director interviews and customs trade data anchors the qualitative findings on component sourcing patterns. Primary fieldwork engaged security system integrators, municipal IT directors, semiconductor packaging specialists, and enterprise facility managers across Singapore, Germany, and the United States. Secondary sources included FCC equipment authorization databases, EU AI Act implementation guidance, GB standards documentation, and SEC filings from listed security conglomerates. Bottom-up demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis tested forecast robustness against edge AI adoption velocity and regulatory timeline scenarios throughout the projection horizon. Segmentation dimensions spanned hardware form factor, deployment architecture, technology category, and end-use vertical with regional regulatory cluster differentiation. CAGRs were derived from recursive substitution modeling with iterative convergence checks. Industry-specific inputs incorporated smart city infrastructure budget cycles and thermal camera penetration rates in energy facility retrofit programs.
Underlying assumptions cover EU AI Act enforcement consistency and sensor wafer pricing stabilization, with deviation risk concentrated in FCC certification bottlenecks and East Asian logistics disruption. Forecasts reflect documented conditions subject to revision from regulatory framework amendments or semiconductor supply shocks. Recalibration cycles align with material shifts in privacy regulation implementation and municipal procurement standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Network Encryption Market
Security Software
Global Enterprise Data Loss Prevention Software Market
Security Software
Global Anti-Spam Software Market
Security Software
Cloud Security Software Market
Security Software
Passwordless Authentication Market
Security Software
Phone Antivirus Software Market
Security Software
United States Consumer Identity and Access Management Market
Security Software
E Passport Market
Security Software
Europe IP Video Intercom Device and Equipment Market
Security Software
Personal Data Recovery Software Market
Security Software
Global Digital Identity Solutions Market
Security Software
Vsaas Market
Security Software
Data Loss Prevention Market
Security Software
Global Hardware Security Modules (HSM) Market
Security Software
Data Privacy Software Market
Security Software
Global Runtime Application Self-Protection Market