
 Europe User Provisioning Market | 2026-2036
Europe User Provisioning Market Size, Share, and Industry Trends Forecast 2026-2036
Europe User Provisioning Market Insights
GDPR Article 32 is broadening the cost-of-entry calculus for identity infrastructure across European enterprises. Microsoft leverages its Entra ID stack to anchor hybrid deployment scenarios in regulated industries. Okta competes through native API connectivity that simplifies multi-directory environments. ForgeRock differentiates via specialized access orchestration for complex workforce populations.
User provisioning denotes the automated lifecycle management of digital identities, encompassing account creation, entitlement assignment, access modification, and deactivation through directory services and identity governance platforms. The process typically integrates with HR systems via SCIM protocols and enforces role-based access control policies to maintain least-privilege security postures. Cloud-based deployment leads in new contract value as organizations retire legacy on-premises infrastructure, while workflow automation functionality captures expanding margin pools by reducing manual certification overhead. Healthcare end users demonstrate concentrated demand for audit compliance modules that satisfy EMA pharmacovigilance traceability requirements.
EU NIS2 Directive mandates and ECHA REACH-aligned data residency rules are reshaping procurement specifications for cross-border identity operations. The European Data Protection Board and national supervisory authorities enforce binding corporate rules that dictate where provisioning logs must physically reside. Stakeholders must evaluate whether their orchestration layers can satisfy divergent member-state implementations of the EU AI Act's automated decision-making transparency obligations.
Market Dynamics
EU NIS2 Directive compliance deadlines are compressing procurement cycles for identity infrastructure across European enterprises, forcing accelerated replacement of legacy provisioning stacks with automated governance platforms that satisfy cross-border data residency mandates.
Growth Catalysts
- GDPR Article 32 mandates:Data breach notification requirements and security obligation enforcement are compelling mid-market enterprises to deploy automated access certification workflows that reduce manual audit preparation overhead.
- Financial services expansion:German and French banking regulators are intensifying scrutiny of orphan account accumulation, driving concentrated demand for lifecycle management platforms that enforce timely deprovisioning.
- Cloud migration acceleration:Nordic healthcare clusters are retiring on-premises directory services in favor of API-native provisioning architectures that integrate with electronic health record systems.
Market Restraints
- Specialized talent scarcity:Identity architects with SCIM protocol expertise and EU data residency knowledge command premium compensation, inflating implementation costs for complex workforce populations.
- Legacy system entrenchment:French public sector entities operate decades-old directory infrastructures that resist API-based integration, extending sales cycles and diluting vendor margins.
- Member-state divergence:Divergent national implementations of the EU AI Act's automated decision-making transparency obligations create compliance fragmentation that complicates pan-European deployment roadmaps.
Strategic Opportunities
- Healthcare pharmacovigilance alignment:EMA traceability requirements for clinical trial access logs represent an underpenetrated vertical where specialized audit modules command pricing premiums.
- AI governance convergence:Integration of machine learning inference monitoring with identity provisioning workflows enables vendors to capture emerging budgets for algorithmic accountability infrastructure.
- Polish and Romanian enterprise segments:Rapid digitization of mid-market manufacturers in these economies creates first-mover advantages for cloud-native provisioning platforms with localized data residency options.
Industry Challenges
- Multi-directory integration complexity:Enterprises operating hybrid Microsoft Active Directory and legacy LDAP environments face protracted migration timelines that delay value realization and extend vendor support burdens.
- Cross-border log residency orchestration:Binding corporate rules enforced by the European Data Protection Board and national supervisory authorities require architectural redesign of centralized provisioning hubs to satisfy physical data location mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe User Provisioning Market |
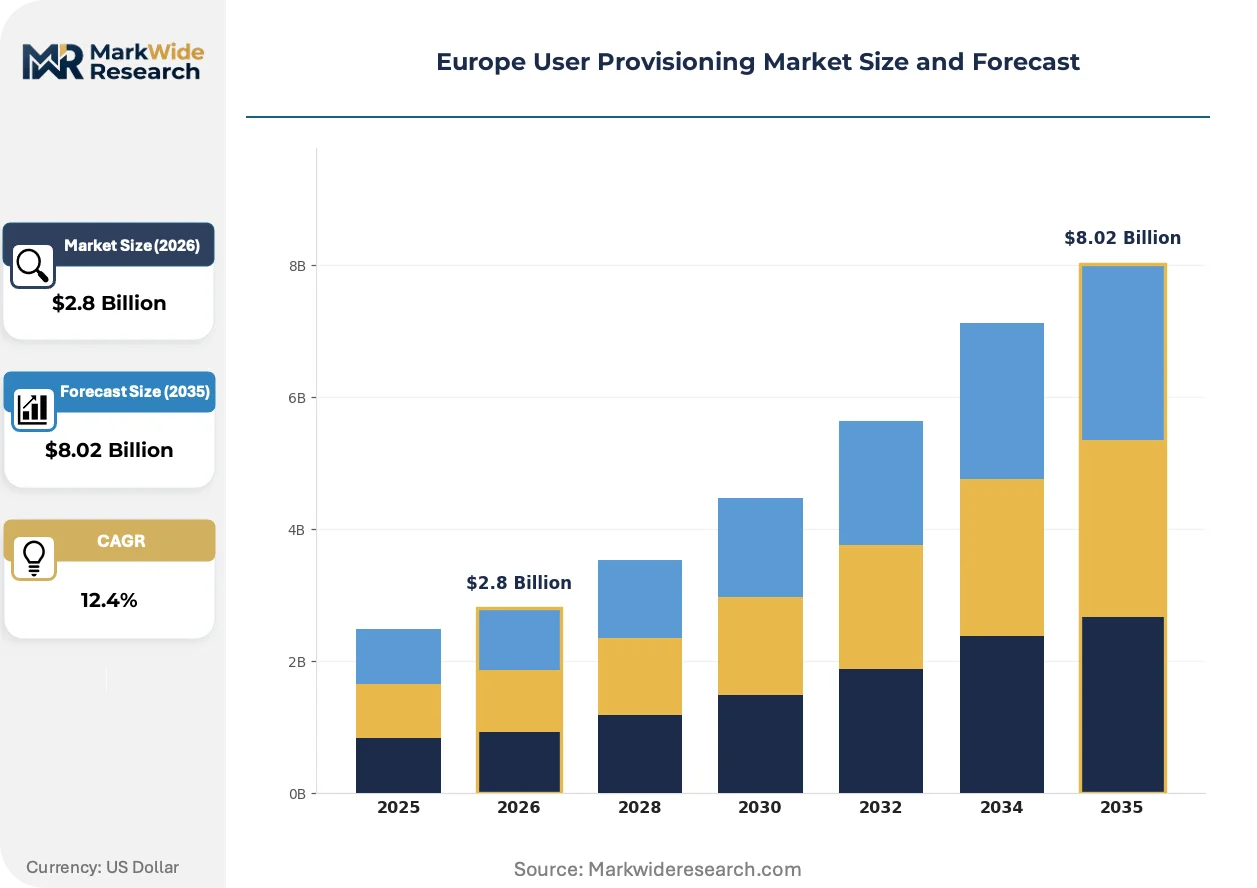
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.02 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Functionality: User Management, Access Control, Audit Compliance, Workflow Automation End User: Healthcare, Education, Retail, Finance Integration: APIs, Single Sign-On, LDAP, Active Directory |
| Companies Covered | Microsoft, Oracle Corporation, IBM, Okta, ForgeRock, Ping Identity, Centrify Corporation, OneLogin, Broadcom, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe User Provisioning Market Trends and Innovations
Automated decision transparency and algorithmic accountability are redefining functional requirements for identity infrastructure, shifting competitive advantage toward platforms that embed governance-by-design rather than retrofit compliance.
Continuous authentication engines are integrating behavioral biometrics with provisioning workflows to enable dynamic entitlement adjustment based on real-time risk scoring. Financial services institutions in the Netherlands and Belgium are piloting these capabilities for high-value transaction authorization. This convergence is integrating identity verification with access management into unified trust fabrics that reduce standalone password vault deployment.
The EU AI Act's automated decision-making provisions are mandating explainability trails for access approval algorithms used in employment and credit decisions. Vendors must now engineer audit logging that captures model inference rationale alongside traditional provisioning events. Healthcare and banking sectors face the steepest compliance curves, with German insurers already restructuring their governance committees to satisfy documentation requirements.
Subscription-based consumption models are displacing perpetual licensing for workforce identity platforms, compressing upfront commitment thresholds and accelerating procurement velocity. Mid-market enterprises in Spain and Italy are driving this transition, favoring usage-scaled contracts that align cost with actual identity volume. Channel partners are restructuring compensation frameworks to prioritize recurring revenue attachment over implementation services.
Europe User Provisioning Market Segmentation
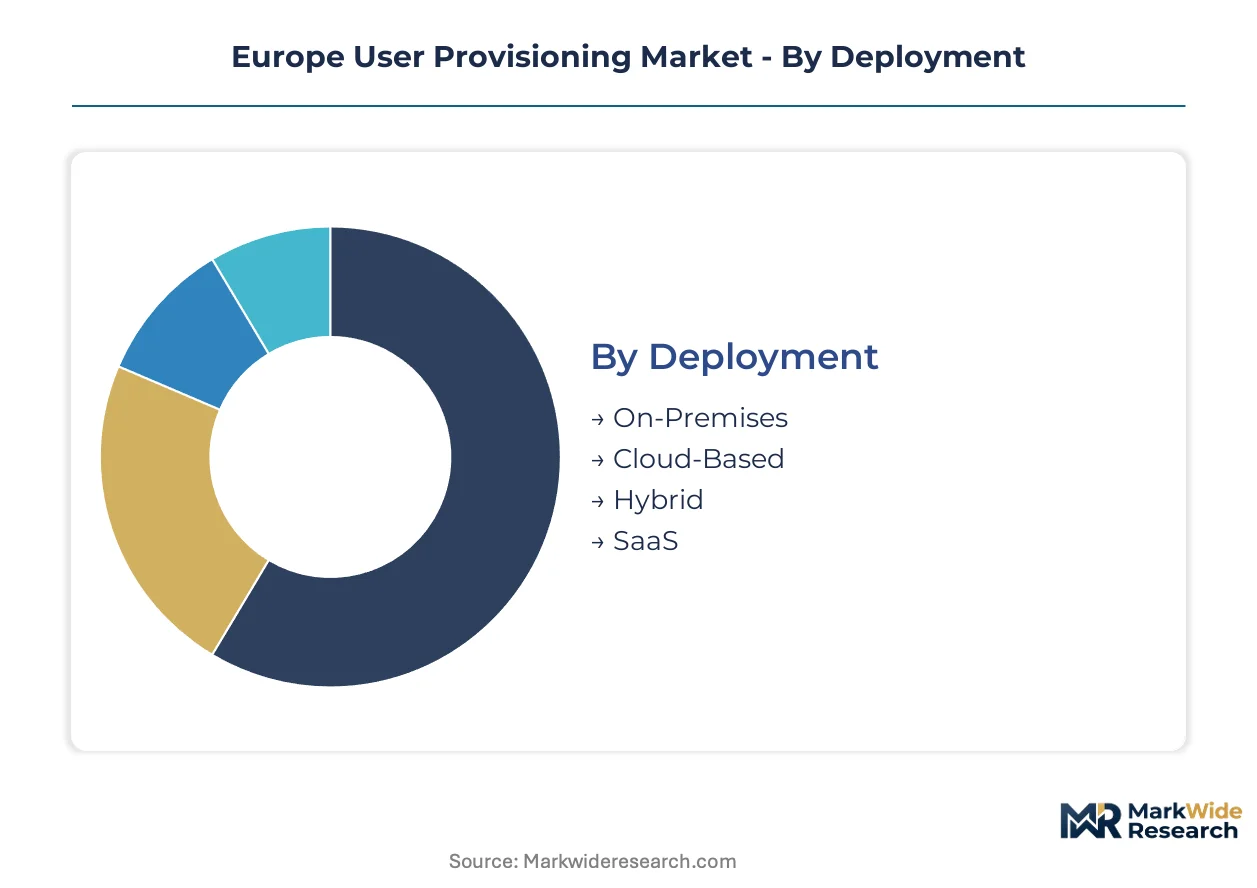
Segmentation of the Europe User Provisioning Market reveals how deployment architectures, functional modules, and integration protocols align with divergent compliance burdens and infrastructure maturity across member states. Understanding these divisions enables vendors to calibrate pricing, localization, and channel strategy for specific procurement contexts.
Deployment:
Cloud-native architectures are displacing legacy directory services as GDPR Article 32 and NIS2 Directive deadlines compress replacement timelines.
- On-Premises:Traditional directory installations maintained within enterprise data centers. French public sector entities retain these systems due to decades-old infrastructure entrenchment and procurement rigidity, though API integration costs inflate implementation budgets.
- Cloud-Based:Fully managed provisioning services delivered via hyperscale infrastructure. Nordic healthcare clusters in Sweden and Denmark are driving disproportionate demand as they retire on-premises LDAP systems for electronic health record integration.
- Hybrid:Split architectures preserving sensitive identity data on-premises while extending provisioning to cloud workloads. German financial institutions favor this model to satisfy BaFin data residency expectations without sacrificing SaaS agility.
- SaaS:Subscription-delivered identity platforms with zero infrastructure ownership. Mid-market manufacturers in Poland and Romania are adopting these rapidly to bypass capital expenditure constraints.
Cloud-Based leads on scale; SaaS leads on momentum.
Functionality:
Procurement specifications now weight automated governance capabilities more heavily than core directory services as audit preparation overhead becomes a board-level cost concern.
- User Management:Lifecycle orchestration spanning account creation, modification, and deactivation. Healthcare providers in the Netherlands deploy these modules to satisfy EMA pharmacovigilance traceability mandates for clinical trial access logs.
- Access Control:Policy enforcement engines implementing least-privilege and role-based entitlement structures. Belgian banking regulators are intensifying scrutiny of excessive permission accumulation, driving concentrated replacement demand.
- Audit Compliance:Automated certification workflows and attestation reporting for supervisory examination. EU AI Act transparency obligations are expanding this category's addressable market as algorithmic decision trails become mandatory.
- Workflow Automation:Low-code provisioning pipelines reducing manual intervention in entitlement approvals. Spanish and Italian mid-market enterprises favor these capabilities to compress IT operational headcount.
Access Control dominates current contract value; Workflow Automation is climbing the fastest.
End User:
Vertical-specific compliance architectures are fragmenting procurement requirements as sectoral regulators impose divergent identity governance standards.
- Healthcare:Identity systems integrating with electronic health records and clinical trial management platforms. EMA traceability rules and national e-health frameworks in Germany and France command specialized audit module premiums.
- Education:Campus-wide identity federation for student, faculty, and researcher populations. Universities in Finland and Norway are consolidating legacy student information system integrations.
- Retail:High-volume seasonal workforce provisioning with rapid onboarding and offboarding cycles. Omnichannel operators in the UK and Ireland prioritize API-native architectures for point-of-sale system connectivity.
- Finance:Rigorous orphan account elimination and segregation of duties enforcement. ECB and national banking authority examinations in Germany, France, and the Netherlands are accelerating governance platform replacement.
Finance leads on scale; Healthcare leads on momentum.
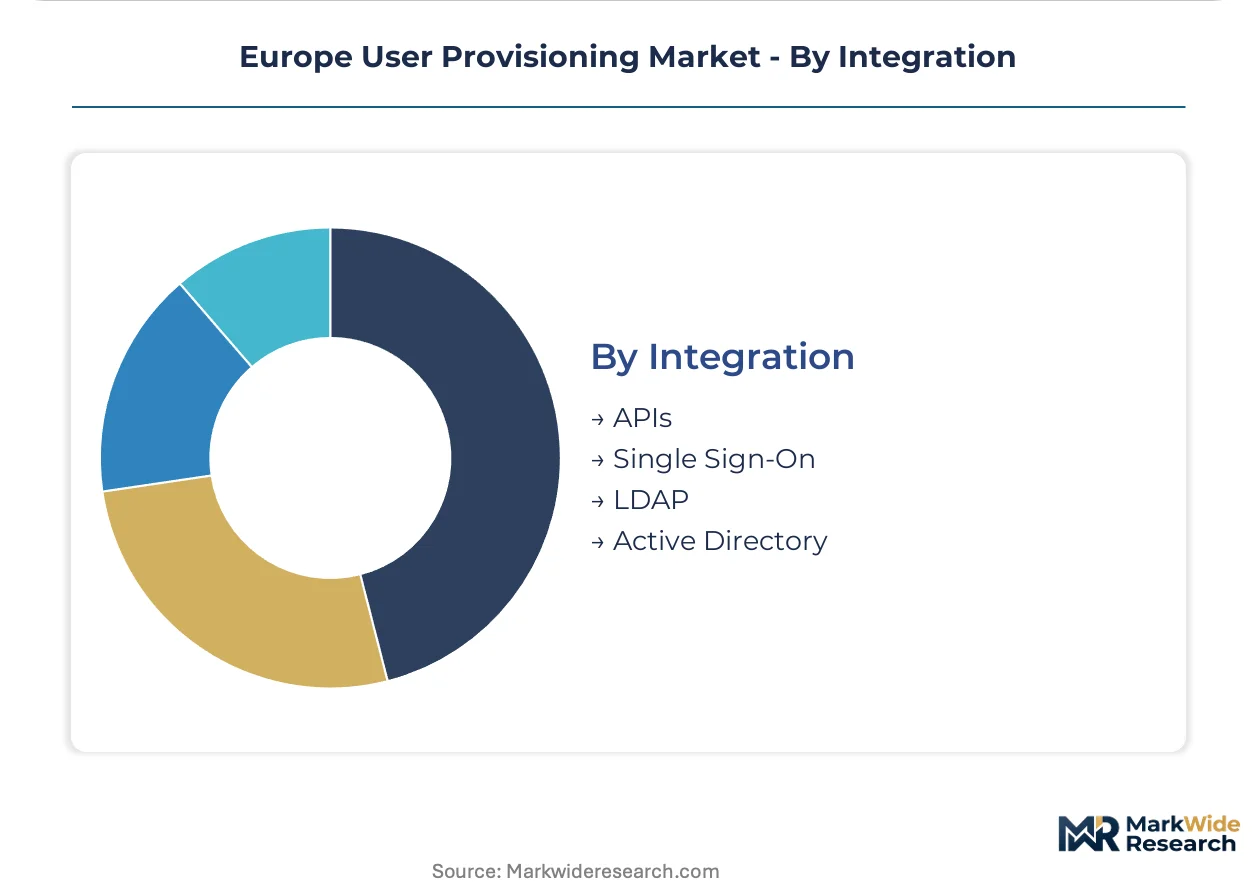
Integration:
Protocol diversity in European enterprise environments is elevating multi-directory orchestration capabilities from convenience to competitive necessity.
- APIs:REST and SCIM-based connectivity for cloud-native application integration. Vendors with native API breadth are capturing mid-market displacement opportunities in Spain and Italy.
- Single Sign-On:Unified authentication across federated application portfolios. SSO functionality is converging with provisioning platforms as standalone password vault deployments decline.
- LDAP:Legacy directory protocol support for decades-old infrastructure. French public sector resistance to API migration extends sales cycles for vendors maintaining LDAP compatibility layers.
- Active Directory:Microsoft-centric identity synchronization for hybrid Azure deployments. German and Austrian enterprises with entrenched Microsoft stacks anchor procurement decisions around Entra ID interoperability.
Active Directory leads on scale; APIs lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Identity architects with SCIM protocol expertise cluster disproportionately in Germany and France, anchoring continental Europe's workforce governance infrastructure development.
Germany
BaFin examinations of orphan account accumulation drive concentrated replacement demand for lifecycle management platforms. The EU NIS2 Directive implementation timeline compresses procurement cycles for mid-market Mittelstand manufacturers. Frankfurt's financial services cluster leads adoption of hybrid deployment architectures that preserve sensitive identity data on-premises.
France
CNIL enforcement of GDPR Article 32 security obligations compels automated access certification workflows. Decades-old directory infrastructure in public sector entities resists API-based integration, extending sales cycles. Paris-based banking headquarters anchor governance platform procurement for cross-border operations.
Sweden
Nordic healthcare clusters retire on-premises LDAP systems for electronic health record integration. EMA pharmacovigilance traceability mandates command specialized audit module premiums. Stockholm's hospital networks pilot continuous authentication engines with behavioral biometrics for clinical trial access.
Netherlands
Dutch banking regulators intensify scrutiny of excessive permission accumulation in financial institutions. The EU AI Act's automated decision-making transparency obligations reshape governance committee structures. Amsterdam's fintech corridor experiments with algorithmic accountability infrastructure for credit decision workflows.
Poland
Rapid digitization of mid-market manufacturers creates first-mover advantages for cloud-native provisioning platforms. Localized data residency options satisfy binding corporate rules enforced by national supervisory authorities. Warsaw's enterprise software market favors subscription-based consumption models over perpetual licensing.
Europe User Provisioning Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment architecture segments, creating a tiered competitive structure. The vendor landscape consolidates around three strategic archetypes: hyperscale cloud platforms with identity-as-a-service portfolios, specialized access orchestration vendors, and legacy enterprise software providers modernizing directory services. Dominant competitive moves include strategic partnerships with electronic health record vendors and geographic expansion into underpenetrated Central European manufacturing segments.
Within the hyperscale platform tier, Microsoft anchors hybrid deployment scenarios through its Entra ID stack interoperability with entrenched Active Directory environments. Okta occupies a position exemplifying API-native connectivity for multi-directory environments, while ForgeRock represents specialized access orchestration capabilities for complex workforce populations. These three companies collectively illustrate the competitive divergence between cloud-native agility and legacy integration depth that shapes procurement decisions across German financial institutions and Nordic healthcare clusters.
| Leading Market Players |
|---|
| Microsoft |
| Oracle Corporation |
| IBM |
| Okta |
| ForgeRock |
| Ping Identity |
| Centrify Corporation |
| OneLogin |
| Broadcom |
| Others |
Pricing and Supply Chain Analysis
API-native provisioning architectures are displacing legacy directory maintenance contracts, compressing implementation margins while concentrating vendor pricing power among SCIM protocol specialists. This technology shift simultaneously reduces buyer switching costs and elevates premium pricing for multi-directory orchestration capabilities across German financial institutions and Nordic healthcare clusters.
Pricing Analysis
Bundled lifecycle management suites command premium positioning against unbundled workflow automation modules. Subscription-based SaaS consumption models dominate new contract value, with three-tier pricing structure across premium, standard, and economy levels differentiating by integration complexity and audit module depth. Price differentiation rests on SCIM protocol certification tiers and localized data residency guarantees. Cost compression in mid-market segments is intensifying because Polish and Romanian manufacturers favor usage-scaled contracts over perpetual licensing. Healthcare providers demonstrate lowest price sensitivity due to EMA pharmacovigilance compliance mandates, while retail omnichannel operators exhibit highest sensitivity given seasonal workforce volume volatility.
Supply Chain Analysis
Reverse-logistics flows for identity infrastructure center on decommissioned on-premises directory hardware and expired certificate repositories requiring secure data destruction protocols. Software supply chains draw from hyperscale cloud infrastructure concentrated in Ireland, Germany, and the Netherlands to satisfy EU data residency requirements. Critical input dependencies include SCIM protocol libraries, behavioral biometric engines, and API gateway middleware. Single-source vulnerability in Microsoft Entra ID interoperability layers creates concentration risk for hybrid deployment architectures. Distribution runs through systems integrators and channel partners restructuring compensation frameworks around recurring revenue attachment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge from divergent NIS2 Directive implementation timelines, with German Mittelstand manufacturers facing compressed procurement cycles against French public sector procurement rigidity that extends vendor sales cycles and inflates margin capture potential.
For Market Incumbents: Acquire SCIM protocol engineering talent pools to anchor specialized integration capabilities against API-native challengers. Consolidate channel partner networks in Central European manufacturing corridors to preempt cloud-native displacement. Investment in localized data residency infrastructure addresses binding corporate rule enforcement by national supervisory authorities. For New Entrants and Emerging Players: Continuous authentication engines with behavioral biometrics integration represent the most penetrable white-space wedge against entrenched directory service vendors. Target EMA pharmacovigilance-aligned audit modules in Swedish and Dutch healthcare clusters where specialized compliance premiums persist. A direct enterprise sales motion with usage-based contracting accelerates procurement velocity in Spanish and Italian mid-market segments. For Investors and Strategic Acquirers: Valuations sit cheapest among legacy directory service providers modernizing toward API-native architectures. Long-term viability centers on algorithmic accountability infrastructure convergence with identity governance workflows over the medium-term horizon. Acquisition target archetypes include specialized access orchestration vendors with ForgeRock-comparable complex workforce capabilities. Monitor EU AI Act automated decision-making transparency enforcement patterns as inflection indicator for audit compliance module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native SCIM connectivity with electronic health record systems captures Nordic healthcare replacement demand. |
| Geographic Expansion | Localized data residency options in Warsaw and Bucharest preempt Central European manufacturing procurement. |
| Strategic Partnership | Electronic health record vendor alliances unlock EMA pharmacovigilance traceability module premiums. |
| Product Launch | Algorithmic accountability infrastructure addresses EU AI Act automated decision transparency mandates. |
| Acquisition of Specialist Firm | Behavioral biometric engine capabilities enable continuous authentication convergence with provisioning workflows. |
Research Methodology
Bottom-up healthcare and financial services modeling reconciled against top-down cloud infrastructure deployment tracking forms the analytical core of this study. Primary interviews with identity architects, CISOs at German Mittelstand manufacturers, Dutch banking compliance officers, and Nordic healthcare IT directors combined with secondary validation against SEC filings, hyperscaler capex disclosures, EMA regulatory submissions, and national supervisory authority enforcement patterns. Top-down and bottom-up triangulation ensures segmentation integrity across deployment architectures and functional modules.
Historical trendline analysis of identity governance platform replacement cycles informs projection frameworks across the analysis window. Segmentation dimensions modeled include deployment model, organization size, vertical compliance burden, integration protocol complexity, and regional regulatory cluster. CAGRs derive from fitted growth curves adjusted for NIS2 Directive deadline compression effects. Forecast inputs incorporate SCIM protocol adoption velocity and EU AI Act implementation divergence across member states.
The model holds under stable regulatory enforcement patterns; deviation in NIS2 Directive national implementation timelines or EDPB binding corporate rule reinterpretation would shift procurement velocity assumptions. Practitioners should monitor CNIL and BaFin examination intensity for early signals of compliance-driven replacement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
AI Security Platforms Market
Security Software
Data Privacy Software Market
Security Software
Security Software for Consumers Market
Security Software
Fraud Detection Software Market
Security Software
Secure Digital Card Market
Security Software
Digital Risk Protection Software Market
Security Software
Global User Provisioning Market
Security Software
Ultra-Secure Smartphone Market
Security Software
Secaas Market
Security Software
Global Background Check Software Market
Security Software
Global Data Loss Prevention Software Market
Security Software
Biometric POS Terminals Market
Security Software
Anomaly Detection Market
Security Software
Security Information and Event Management Software Market
Security Software
Device-Embedded Biometric Authentication Market
Security Software
Anomaly Detection Tools Market