
 Anti-Money Laundering (AML) Software Solution Market | 2026-2036
Anti-Money Laundering (AML) Software Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Money Laundering (AML) Software Solution Market Outlook
Subscription-based SaaS financing is reshaping competitive entry in AML software, lowering upfront capital barriers for mid-tier banks and fintech challengers. Oracle leverages its cloud infrastructure dominance to bundle compliance modules with core banking platforms. SAS sustains R&D intensity in behavioral analytics for transaction monitoring. ComplyAdvantage specializes in API-first architectures that accelerate deployment for digital-native financial institutions.
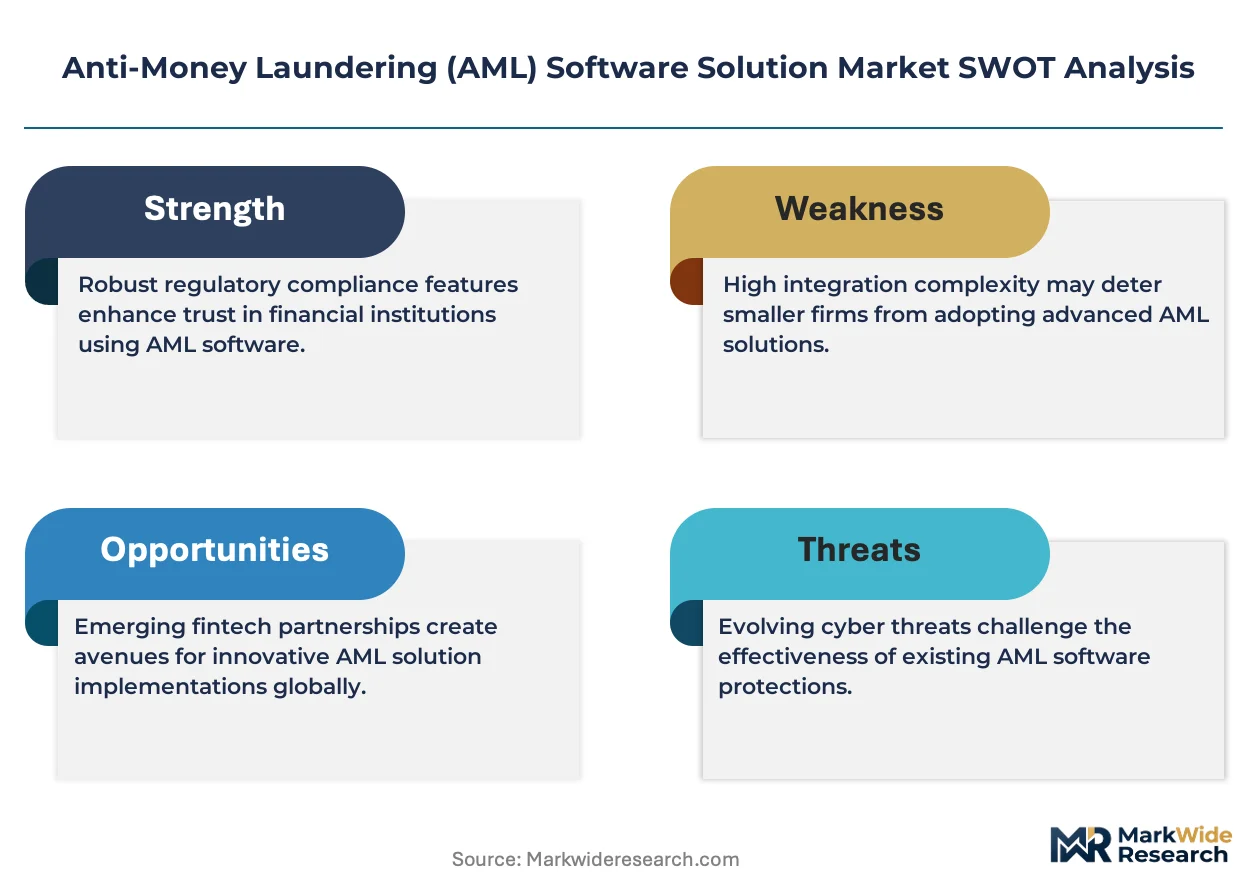
Anti-Money Laundering software solutions encompass rule-based and machine-learning systems that screen transactions, customer profiles, and counterparties against watchlists, sanctions databases, and behavioral baselines to detect suspicious financial activity. These platforms automate case management, regulatory filing generation, and audit trail maintenance for financial crime compliance programs. Cloud-based deployment is capturing the fastest expansion as regulated entities abandon capital-intensive on-premise data centers. Transaction monitoring functionality anchors the largest revenue pool, though risk assessment modules are gaining share among non-bank payment providers facing new supervisory scrutiny. Financial institutions remain the dominant end-user segment, but law enforcement agencies are emerging as a distinct procurement category for analytics-intensive investigation tools.
The Financial Crimes Enforcement Network (FinCEN) in the United States mandates suspicious activity report filing protocols that directly shape software feature requirements and update cycles. The European Banking Authority (EBA) guidelines on customer due diligence and the EU's Anti-Money Laundering Authority (AMLA) establishment are converging technical standards across member states. Stakeholders must monitor whether fragmented national implementation of AMLA rules creates compliance complexity that favors modular, jurisdiction-configurable platforms over monolithic suites.
Market Dynamics
Real-time transaction monitoring is displacing batch-processing architectures as the default technical standard, forcing incumbent vendors to reengineer core platforms and opening entry points for cloud-native competitors.
Growth Catalysts
- FinCEN enforcement intensity:Escalated penalties against US financial institutions for compliance failures are accelerating replacement cycles for outdated screening systems. Procurement teams prioritize platforms with automated suspicious activity report generation.
- Payment processor expansion:Non-bank payment providers in the United States face expanded supervisory scrutiny under state-level money transmission licensing, driving demand for modular risk assessment modules.
- Behavioral analytics maturation:Machine learning models trained on transaction sequence patterns are reducing false-positive rates in customer monitoring, improving operational efficiency for compliance departments.
Market Restraints
- Cloud infrastructure concentration:Reliance on hyperscale cloud providers for AML platform hosting creates systemic resilience risks and vendor lock-in concerns for regulated entities.
- Data localization mandates:Divergent national requirements for transaction data storage within territorial boundaries fragment platform architectures and inflate deployment costs.
- Skilled analyst scarcity:Shortage of professionals capable of interpreting algorithmic alerts and conducting enhanced due diligence investigations constrains effective utilization of advanced software capabilities.
Strategic Opportunities
- Law enforcement procurement:Analytics-intensive investigation tools represent an emerging customer segment distinct from financial institutions, with agencies seeking cross-border transaction tracing capabilities.
- API-first deployment:Pre-built integration interfaces reduce implementation timelines for digital-native banks and fintech challengers, expanding addressable market beyond traditional core banking replacement cycles.
- EU AML Authority harmonization:Converging technical standards across member states creates demand for jurisdiction-configurable platforms that can adapt to national implementation variations.
Industry Challenges
- Legacy system interoperability:Core banking platforms with decades-old data architectures resist seamless integration with modern API-based compliance modules, extending implementation timelines.
- Model explainability requirements:Regulators in the United States and European Union demand transparent documentation of machine learning decision pathways, complicating black-box algorithm deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Money Laundering (AML) Software Solution Market |
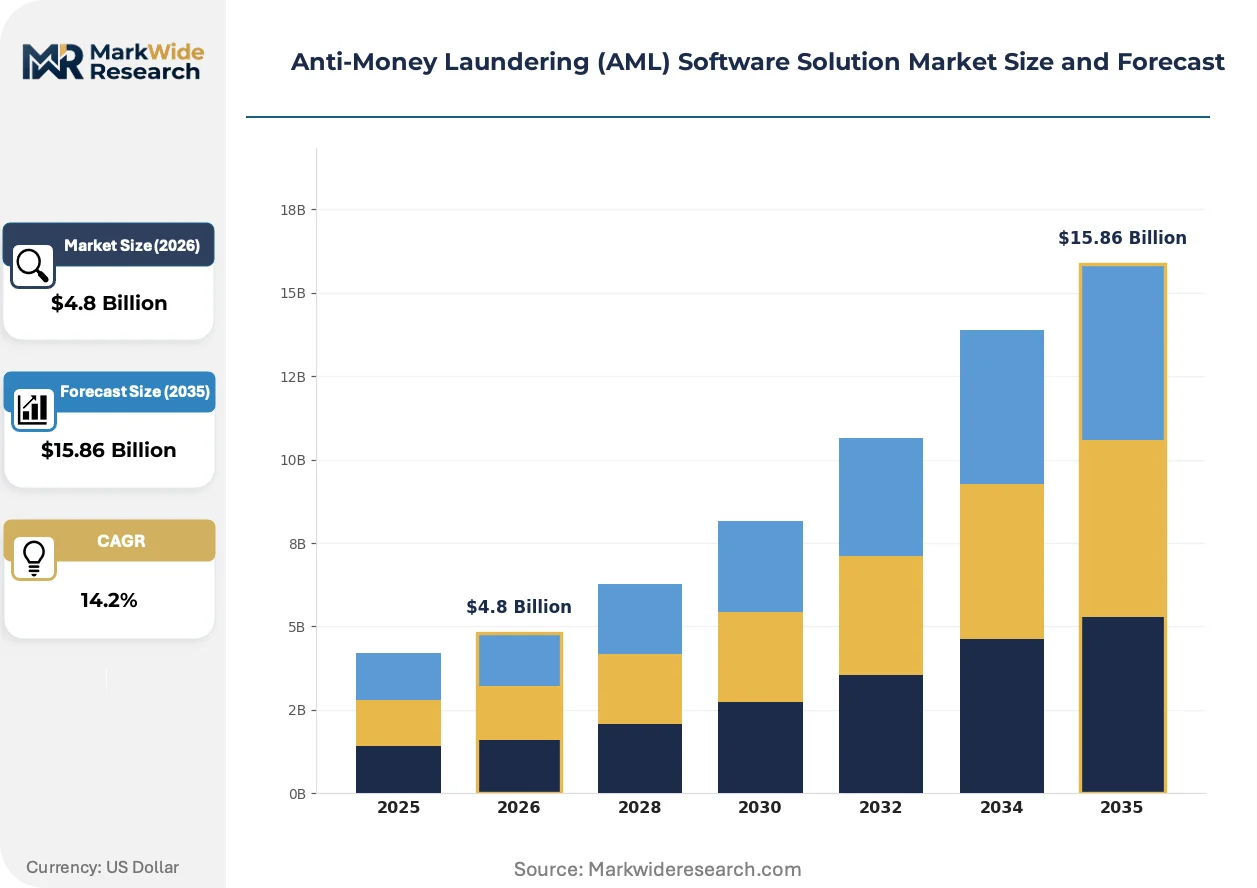
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Services End User: Financial Institutions, Corporations, Governments, Law Enforcement Functionality: Fraud Detection, Risk Assessment, Transaction Monitoring, Reporting Compliance Type: Regulatory Reporting, Internal Policy, Risk Management, Operational Compliance |
| Companies Covered | LexisNexis Risk Solutions, NICE Actimize, ComplyAdvantage, Fenergo, Oracle, SAS, Fiserv, FIS, Jumio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Money Laundering (AML) Software Solution Market Strategic Shifts
Artificial intelligence architectures are hybridizing rule-based and neural approaches, compressing the trade-off between detection precision and computational latency that previously forced binary platform choices.
Graph neural networks applied to transaction networks are hybridizing entity resolution and relationship mapping into unified screening workflows. Large US banks with complex correspondent banking operations are piloting these systems for counterparty risk assessment. The technology is hybridizing previously separate vendor categories for transaction monitoring and know-your-customer verification into consolidated procurement decisions.
The European Union's Sixth Anti-Money Laundering Directive mandates centralized beneficial ownership registers accessible to obliged entities, transforming customer due diligence from document collection to real-time registry verification. Financial institutions must reconfigure onboarding workflows to integrate API connections to national registers. Digital banks in Germany and the Netherlands are responding by automating ownership structure parsing to compress account opening timelines.
Subscription-based SaaS financing is displacing perpetual license models as the dominant commercial structure for mid-tier bank procurement. Fintech challengers and regional banks in the United States favor operational expenditure treatment over capital-intensive on-premise deployments. This shift is most visible among institutions with under $50 billion in assets seeking to avoid data center infrastructure commitments.
Anti-Money Laundering (AML) Software Solution Market Segmentation
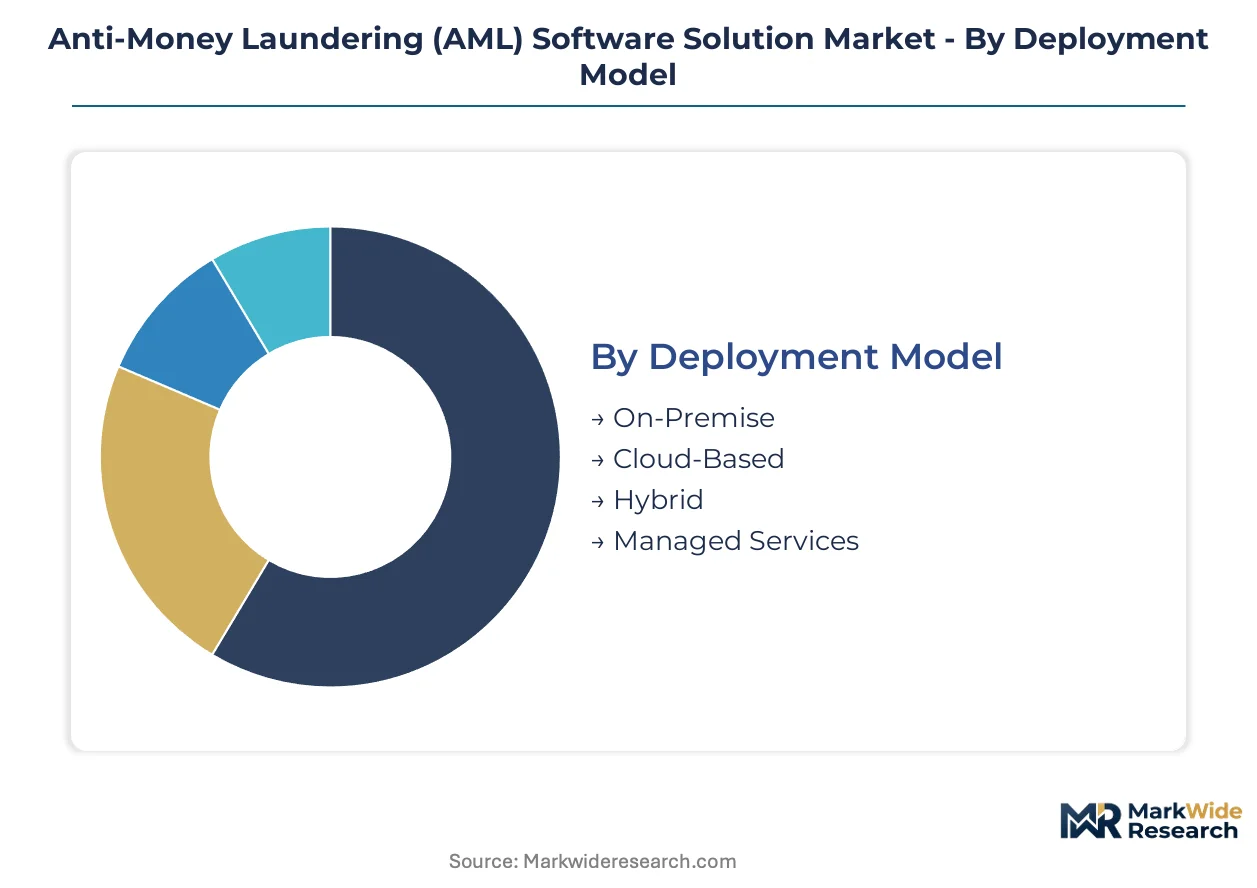
AML software procurement patterns diverge sharply across deployment architectures, end-user sophistication, and regulatory pressure intensity. Segment-level strategies must account for divergent compliance maturity between established banks and emerging fintech challengers.
Deployment Model:
Cloud migration dominates vendor roadmaps, though legacy infrastructure constraints preserve hybrid architectures for established institutions.
- On-Premise:Hardware-resident installations within bank-owned data centers deliver sovereign control over sensitive transaction data. Tier-1 US banks with decades-old core systems maintain these deployments to satisfy internal risk committees, though maintenance overhead erodes operational agility.
- Cloud-Based:Multi-tenant SaaS platforms hosted on hyperscale infrastructure compress implementation timelines from months to weeks. Regional US banks and payment processors under $50 billion in assets favor this model to convert capital expenditure into operational expenditure treatment.
- Hybrid:Split architectures segregate customer data on-premise while routing analytics workloads to cloud environments. German and Dutch digital banks deploy this pattern to reconcile data localization mandates with computational scalability.
- Managed Services:Outsourced compliance operations bundle software licensing with analyst staffing. Mid-tier institutions facing skilled analyst scarcity contract these arrangements to maintain regulatory filing velocity.
Cloud-Based deployments hold the steepest expansion curve; On-Premise retains volume leadership among assets under management.
End User:
Procurement authority concentrates in regulated entities, though enforcement agencies are emerging as a distinct analytics customer base.
- Financial Institutions:Banks, credit unions, and broker-dealers constitute the foundational revenue pool with multi-year enterprise licensing. FinCEN enforcement intensity in the United States accelerates replacement cycles for outdated screening systems among this cohort.
- Corporations:Non-financial multinationals deploy AML modules for supplier due diligence and treasury compliance. Manufacturing conglomerates with complex cross-border payment flows represent an expanding addressable market beyond traditional banking.
- Governments:Central banks and financial intelligence units procure analytics platforms for systemic risk surveillance. National regulators in EU member states are standardizing technical specifications ahead of AML Authority harmonization.
- Law Enforcement:Police and prosecutorial agencies acquire investigation tools with cross-border transaction tracing capabilities. This segment exhibits the fastest procurement velocity as agencies modernize financial crime units.
Financial Institutions anchor procurement volume; Law Enforcement demonstrates the most rapid budget expansion.
Functionality:
Feature prioritization reflects operational pressure points, with real-time processing displacing batch architectures as the technical baseline.
- Fraud Detection:Pattern-recognition engines identify synthetic identity schemes and account takeover attempts. Payment processors integrate these modules at transaction authorization gateways to block suspicious flows before settlement.
- Risk Assessment:Customer scoring models synthesize behavioral baselines with external data feeds. Non-bank payment providers facing state-level money transmission licensing deploy these tools to satisfy supervisory scrutiny.
- Transaction Monitoring:Real-time surveillance of payment flows against watchlists and sanctions databases anchors the largest revenue pool. Machine learning models trained on sequence patterns are reducing false-positive rates for US compliance departments.
- Reporting:Automated suspicious activity report generation and audit trail maintenance streamline regulatory filing. FinCEN protocols directly shape feature requirements and software update cycles for vendors serving US institutions.
Transaction Monitoring commands the largest installed base; Risk Assessment is expanding most quickly among non-bank payment providers.
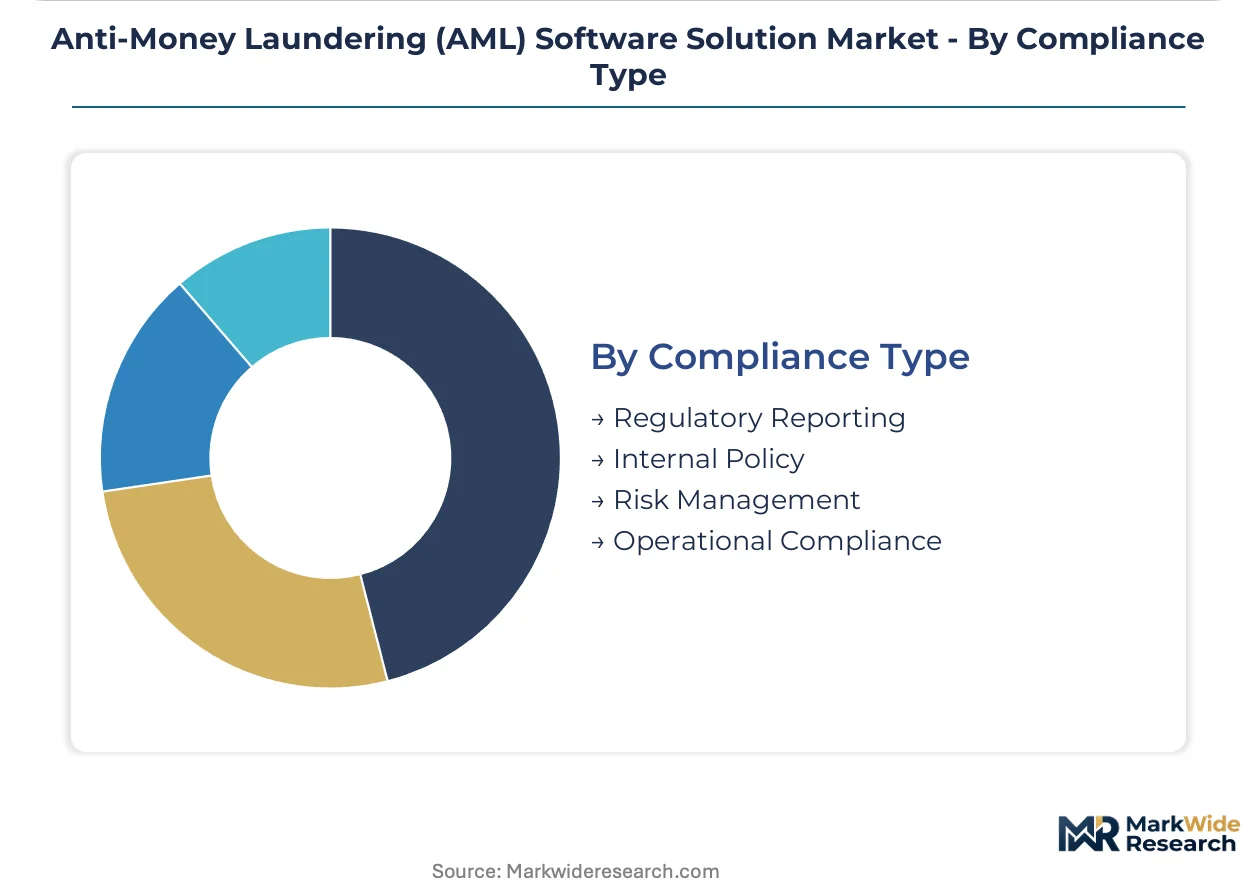
Compliance Type:
Regulatory pressure intensity determines module prioritization, with external filing obligations superseding internal policy automation.
- Regulatory Reporting:Structured data submission to FinCEN, EBA, and national financial intelligence units mandates specific output formats. Software vendors maintain dedicated engineering teams to track evolving filing protocols across jurisdictions.
- Internal Policy:Institution-specific risk thresholds and escalation workflows embed proprietary compliance philosophies. Large US banks with complex correspondent banking operations customize these layers extensively.
- Risk Management:Enterprise-wide exposure quantification integrates AML data with credit and market risk systems. Treasury functions at multinational corporations demand this convergence for consolidated risk visibility.
- Operational Compliance:Day-to-day workflow automation for analyst caseload distribution and quality assurance. This functionality addresses skilled analyst scarcity by compressing investigation timelines.
Regulatory Reporting retains mandatory spend priority; Risk Management is gaining share fastest as enterprises pursue unified risk infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where FinCEN enforcement actions command premium procurement budgets, while European buyers extract concessions through harmonized technical standards and collective purchasing leverage.
United States
FinCEN enforcement intensity drives replacement cycles for legacy screening systems among money-center banks and regional institutions. The Bank Secrecy Act and Patriot Act provisions mandate suspicious activity report automation, shaping vendor feature roadmaps. New York and Chicago financial districts host concentrated procurement decision-making for correspondent banking compliance suites.
United Kingdom
London's fintech density generates demand for API-first deployment models that compress implementation timelines. The Financial Conduct Authority's operational resilience requirements push cloud-native architectures over on-premise installations. The Square Mile and Canary Wharf clusters anchor vendor sales operations targeting European headquarters.
Germany
BaFin supervision of payment institutions and digital banks accelerates modular risk assessment procurement. The EU's Sixth Anti-Money Laundering Directive mandates beneficial ownership registry integration, reconfiguring onboarding workflows. Frankfurt's banking quarter and Berlin's fintech corridor split demand between established institutions and challengers.
Singapore
Monetary Authority of Singapore licensing of digital payment token service providers expands addressable market beyond traditional banking. MAS technology risk management guidelines favor cloud-resident compliance platforms with local data sovereignty controls. Raffles Place and Marina Bay financial hubs concentrate procurement authority for Southeast Asian operations.
Netherlands
DNB supervision of payment institutions and crypto-asset service providers drives demand for real-time transaction monitoring. The Dutch central bank's fintech licensing regime requires automated compliance infrastructure as a condition of authorization. Amsterdam's Zuidas district hosts regional headquarters procurement for EU-wide platform rollouts.
Anti-Money Laundering (AML) Software Solution Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower functional scope. The vendor base stratifies across three tiers: hyperscale cloud providers bundling compliance modules, established financial software houses with core banking integration capabilities, and API-native challengers targeting digital-first institutions. Dominant competitive moves include strategic partnerships between cloud infrastructure operators and specialized analytics vendors, plus geographic expansion through jurisdiction-specific regulatory certifications.
Among the named players, Oracle and SAS exemplify the platform integrator archetype with enterprise-grade deployment scale, while ComplyAdvantage occupies a position representing the API-first challenger segment. LexisNexis Risk Solutions and NICE Actimize sit within the specialized compliance tier, anchoring vertical-specific expertise. These five entities collectively span the competitive spectrum from infrastructure-backed suites to modular point solutions.
| Leading Market Players |
|---|
| LexisNexis Risk Solutions |
| NICE Actimize |
| ComplyAdvantage |
| Fenergo |
| Oracle |
| SAS |
| Fiserv |
| FIS |
| Jumio |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in cloud infrastructure regions serving regulated financial institutions drives both supplier prioritization of enterprise clients and pricing premiums for compliant-ready deployments. FinCEN enforcement intensity in the United States compresses procurement timelines, forcing buyers to absorb higher upfront configuration costs rather than negotiate extended implementation schedules.
Pricing Analysis
The customization-premium spread between configured-to-order enterprise deployments and standard SaaS tiers spans three-to-fivefold in annual contract value. Subscription-based SaaS financing dominates mid-tier bank procurement, while perpetual licensing persists among money-center banks with complex correspondent banking operations. Price differentiation rests on integration complexity and regulatory jurisdiction coverage, with US-facing configurations commanding premiums over EU-standard deployments. Regional banks under $50 billion in assets exhibit highest price sensitivity, whereas Tier-1 institutions prioritize feature depth over cost containment. Cost compression in standard SaaS tiers is intensifying because hyperscale cloud providers bundle compliance modules with core infrastructure commitments.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for hardware-dependent on-premise deployments, though cloud-native software delivery attenuates direct component exposure. Software development concentrates in the United States, the United Kingdom, and Ireland, with implementation services drawing from India and Poland. Raw material dependencies center on semiconductor availability for on-premise server installations, API gateway infrastructure, and data residency hardware. Single-source vulnerability in hyperscale cloud provider concentration creates systemic resilience concerns for regulated entities. Distribution runs through direct enterprise sales teams for Tier-1 banks, supplemented by channel partners and systems integrators serving mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among cloud-native fintech challengers and consolidated regional banking networks, fragmenting procurement authority away from monolithic core banking replacement cycles. This shift favors modular, API-first vendors over integrated suite providers.
For Market Incumbents: Insulate core banking integration advantages by accelerating real-time transaction monitoring reengineering before cloud-native competitors achieve feature parity. Invest in jurisdiction-configurable platform architectures to capture EU AML Authority harmonization opportunities. Prioritize analyst staffing partnerships addressing skilled compliance professional scarcity. For New Entrants and Emerging Players: Pursue law enforcement analytics procurement as the most penetrable segment, where investigation tool modernization budgets expand faster than financial institution replacement cycles. Target non-bank payment providers facing state-level money transmission licensing as a white-space vertical underserved by incumbent vendor roadmaps. Deploy API-first go-to-market positioning compressing implementation timelines from months to weeks. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because escalating FinCEN enforcement and EU directive implementation create durable demand for compliance automation regardless of interest rate cycles. Acquisition target archetypes include behavioral analytics specialists and cross-border transaction tracing tool developers. Monitor FinCEN penalty announcement velocity as the signal indicating compliance budget expansion inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Platform Reengineering | Incumbent vendors must rebuild core architectures to displace batch-processing legacy systems before cloud-native competitors capture mid-tier bank procurement. |
| API-First Architecture Deployment | Pre-built integration interfaces accelerate implementation timelines for digital-native banks and payment processors seeking rapid compliance infrastructure. |
| Jurisdiction-Configurable Module Development | EU AML Authority harmonization creates demand for platforms adapting to national implementation variations across member states. |
| Law Enforcement Analytics Partnership | Police and prosecutorial agencies seek cross-border transaction tracing capabilities as distinct procurement category from financial institutions. |
| Analyst Staffing Managed Services | Mid-tier institutions contract bundled compliance operations to maintain regulatory filing velocity amid skilled professional scarcity. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with bank compliance officers, fintech CTOs, regulatory technology procurement leads, and cloud infrastructure platform engineers. Secondary validation drew from FinCEN enforcement action databases, EBA technical standard guidelines, SEC 10-K disclosures from listed financial software vendors, and hyperscaler capex allocation reports. Bottom-up segmentation modeling triangulated against top-down market sizing from regulatory filing volume trends and enterprise software spending surveys.
Calibration against historical deployment timelines and regulatory implementation deadlines anchored the analytical framework across the analysis window. Segmentation dimensions modeled encompass deployment architecture, end-user institution type, functional module category, compliance obligation type, and regional regulatory cluster. CAGRs were derived from slope-intercept fitting of adoption curve inflection points, with inputs including cloud migration velocity among regional banks, payment processor licensing expansion rates, and machine learning model deployment penetration in transaction monitoring.
Sensitivities concentrate around FinCEN enforcement intensity fluctuations, EU AML Authority implementation pace variations, and hyperscale cloud provider market concentration regulatory interventions. Forecasts reflect documented assumptions regarding regulatory timeline adherence and technology adoption elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
VPN Software Market
Security Software
North America Secure Access Service Edge Market
Security Software
Website Monitoring Software Market
Security Software
Broadcast Censorship Solutions Market
Security Software
Keystroke Dynamics Market
Security Software
Ultra-Secure Smartphone Market
Security Software
Security Testing Market
Security Software
Digital Risk Protection Platform Market
Security Software
Global Data Loss Prevention Software Market
Security Software
Security Software for Consumers Market
Security Software
Automotive Over-the-Air Cybersecurity Hardening Test Equipment Market
Security Software
Global Hardware Security Modules (HSM) Market
Security Software
Global Security Orchestration Automation and Response (SOAR) Market
Security Software
User Provisioning Software Market
Security Software
Security Software Market
Security Software
US Hardware Encryption Market