
 Video Intercom Devices and Equipment Market | 2026-2036
Video Intercom Devices and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Video Intercom Devices and Equipment Market Outlook
The EU Green Deal's building renovation mandates is consolidating demand for energy-efficient access control across European commercial real estate. Hikvision leverages its vertical integration in camera manufacturing to dominate IP intercom supply chains. Panasonic Corporation sustains technology leadership through R&D intensity in audio-visual integration. Dahua Technology anchors its position with manufacturing scale across Asia-Pacific distribution channels.
Video intercom devices and equipment encompass audio-visual communication systems enabling two-way interaction, visitor verification, and remote access control, typically operating over twisted-pair wiring, Ethernet, or wireless protocols with resolutions from 720p to 4K and Power-over-Ethernet functionality. These systems serve primary commercial and residential purposes by replacing mechanical entry systems with identity-verified access management. IP Intercoms command the fastest expansion as building automation shifts toward centralized network management, while Wired Intercoms retain share in legacy infrastructure upgrades where existing cabling reduces installation costs. Cloud-Based Solutions within the Technology dimension attract recurring revenue models, though Analog Technology persists in price-sensitive retrofit markets across older building stock.
The FCC in the United States enforces electromagnetic compatibility standards that shape product certification timelines for wireless intercom models entering North American distribution. ETSI standards in Europe and BIS certification requirements in India further fragment compliance pathways, forcing manufacturers to maintain multiple testing protocols. China's MIIT governs network access licenses for IP-connected devices, adding regulatory layers for cloud-integrated systems. Stakeholders must monitor convergence between cybersecurity mandates and physical access protocols as building management systems unify under single-network architectures.
Market Dynamics
The migration from analog to IP-based intercom architectures is compressing installation timelines and collapsing the boundary between physical security and building automation networks. This infrastructure convergence forces manufacturers to certify products across multiple compliance regimes simultaneously.
Growth Catalysts
- EU Green Deal building mandates:Energy efficiency directives in Germany and France require smart entry systems in renovated multi-tenant structures, pulling IP intercom demand into commercial retrofit pipelines.
- India's PLI scheme for electronics:Domestic manufacturing incentives strengthen local supply chains for connected security hardware, reducing import dependency for smart city deployments.
- Power-over-Ethernet standardization:IEEE 802.3bt compliance enables single-cable installations, cutting deployment costs in new residential construction across Southeast Asian markets.
Market Restraints
- Copper and semiconductor input volatility:Ethernet cable and image sensor costs fluctuate with commodity markets, squeezing margins on mid-tier product lines.
- MIIT network access licensing in China:Cloud-integrated IP intercoms face extended approval timelines, delaying product launches for manufacturers dependent on Chinese manufacturing bases.
- Legacy analog substitution inertia:Existing twisted-pair infrastructure in aging European housing stock defers full system replacements to major renovation cycles.
Strategic Opportunities
- Underpenetrated Indian residential towers:Tier-2 cities lack installed base of any intercom type, creating first-mover advantage for IP-native vendors.
- Audio-visual AI convergence:Facial recognition integration with visitor management systems opens premium pricing in corporate security verticals.
- BIS certification streamlining:India's electronics regulator is harmonizing testing protocols, reducing duplicate compliance costs for imported components.
Industry Challenges
- Cybersecurity engineering talent scarcity:Firmware hardening against network intrusion requires specialized skills concentrated in Israeli and Estonian security clusters.
- Multi-protocol integration complexity:SIP, ONVIF, and proprietary building management interfaces demand extensive custom engineering for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Intercom Devices and Equipment Market |
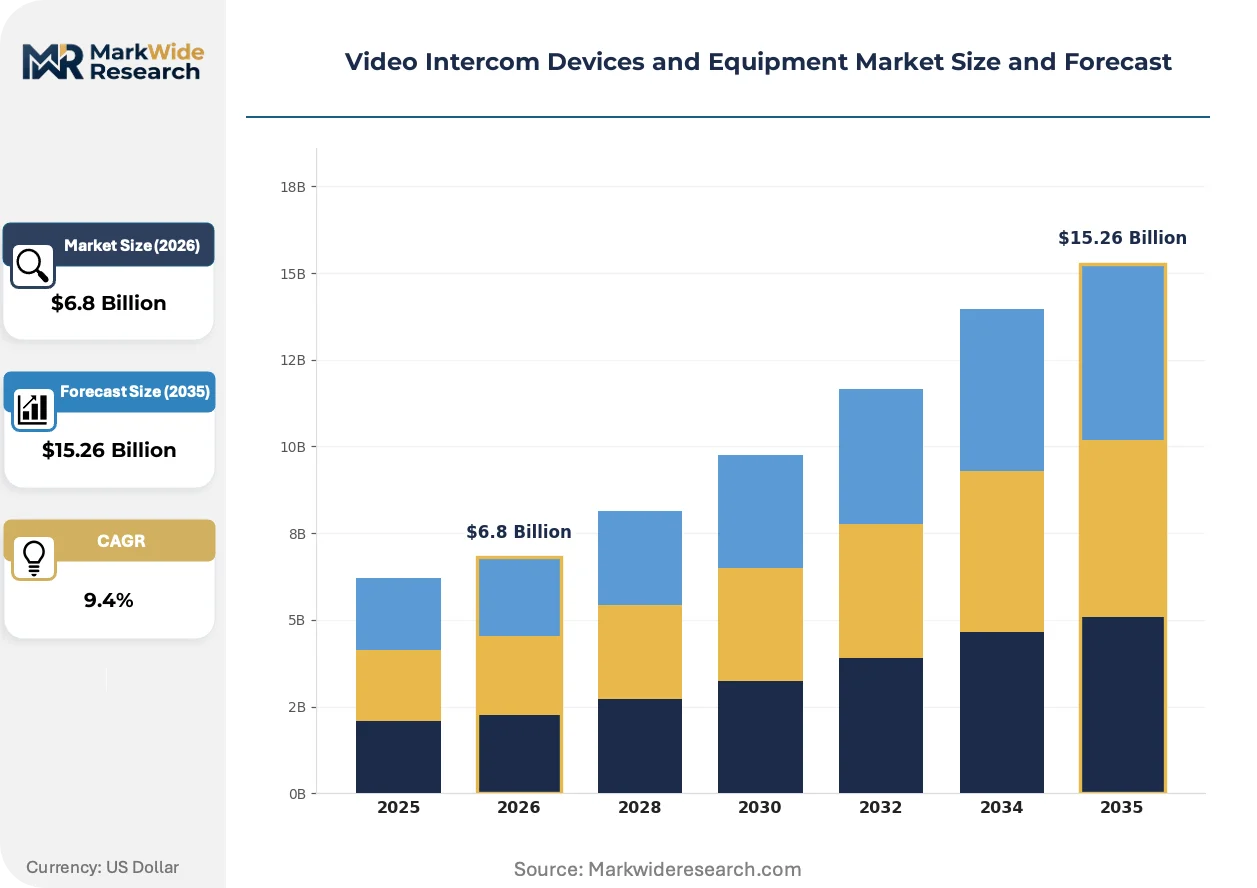
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Intercoms, Wireless Intercoms, Video Door Phones, IP Intercoms Technology: Analog Technology, Digital Technology, Cloud-Based Solutions, Mobile Integration Installation Type: Indoor Installation, Outdoor Installation, Surface-Mounted, Flush-Mounted End User: Residential Complexes, Commercial Buildings, Schools, Healthcare Facilities |
| Companies Covered | Hikvision, Panasonic Corporation, Honeywell International Inc., Legrand, Dahua Technology, Aiphone, Axis Communications, Samsung, Comelit Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Intercom Devices and Equipment Market Strategic Shifts
Edge computing architectures are redistributing processing load away from central servers, enabling real-time visitor verification without cloud latency. This shift collapses the traditional distinction between intercom endpoints and intelligent sensors.
Artificial intelligence inference at the device level is decentralizing facial recognition and anomaly detection from server rooms to door stations. Property managers in Dubai and Singapore commercial towers deploy these capabilities for frictionless tenant access. The technology is decentralizing competitive advantage toward firmware sophistication rather than hardware scale.
ETSI's cybersecurity certification framework for IoT devices is mandating secure boot and encrypted firmware updates across European distribution channels. Manufacturers must redesign supply chains to embed hardware security modules from component sourcing stages. IP intercom product lines targeting EU commercial real estate face the steepest compliance cost increases.
Facility managers increasingly specify intercom systems through integrated security contractors rather than electrical distributors. This channel consolidation compresses vendor visibility and rewards bundled service capabilities. The pattern is most pronounced in German and Dutch commercial property markets where single-source security contracts dominate procurement.
Video Intercom Devices and Equipment Market Segmentation
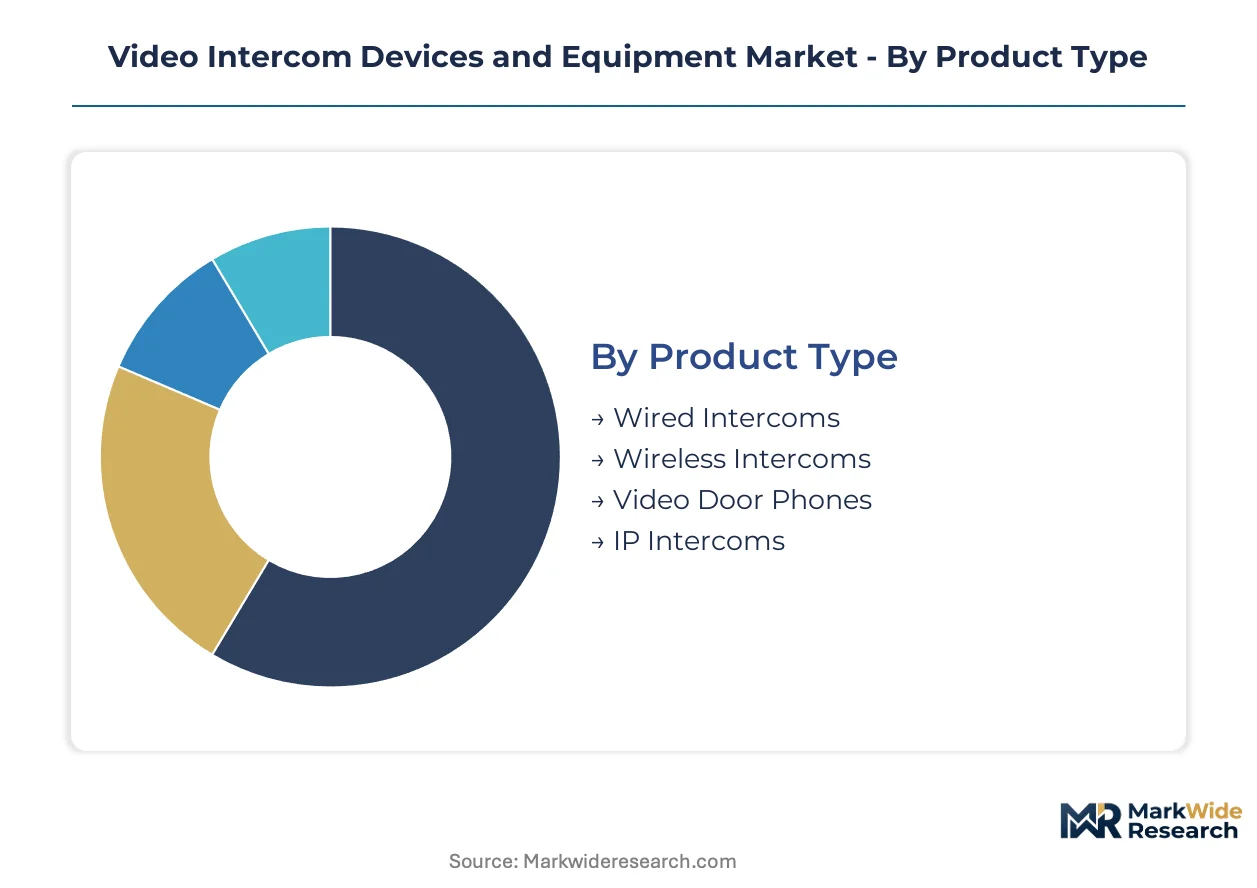
Video intercom segmentation reflects divergent compliance burdens across installation environments. Certification requirements for outdoor IP-rated hardware diverge sharply from indoor consumer electronics standards, while healthcare and educational end-uses trigger additional data protection protocols.
Product Type:
FCC electromagnetic compatibility testing applies to wireless models, whereas IP intercoms face MIIT network access licensing in China and ETSI cybersecurity certification in Europe. Wired variants navigate simpler electrical safety frameworks.
- IP Intercoms:Ethernet-powered devices supporting IEEE 802.3bt Power-over-Ethernet with centralized network management capabilities. Demand concentrates in German multi-tenant renovations under EU Green Deal efficiency mandates, where building automation integration is compulsory.
- Wired Intercoms:Twisted-pair systems leveraging existing copper infrastructure for analog or hybrid digital signaling. Legacy upgrades in aging European housing stock sustain volume, though full replacements await major renovation cycles.
- Wireless Intercoms:RF-based units operating in unlicensed spectrum bands with battery or adapter power. FCC Part 15 compliance timelines extend North American distribution schedules.
- Video Door Phones:Compact entry-level units combining camera, display, and call button for single-family or small multi-tenant use. Price-sensitive retrofit markets in India favor basic feature sets.
IP Intercoms sits at the top of the volume ranking, with Wireless Intercoms climbing the fastest.
Technology:
Cost stratification separates premium cloud architectures from economy analog tiers, with digital hybrid systems occupying mid-market positioning.
- Cloud-Based Solutions:Firmware-over-the-air architectures enabling remote management and subscription revenue models. ETSI IoT cybersecurity frameworks mandate secure boot and encrypted updates across EU distribution, embedding hardware security modules from component sourcing stages.
- Analog Technology:Legacy baseband signaling over dedicated wiring with minimal processing overhead. Persistent demand in price-sensitive retrofit markets where existing twisted-pair infrastructure defers replacement investments.
- Digital Technology:On-device encoding with local storage and SIP/ONVIF protocol support. Hybrid deployments bridge legacy wiring with IP backbone connectivity.
- Mobile Integration:Smartphone-native visitor notification and remote unlock via proprietary or standards-based applications. Indian smart city deployments leverage domestic PLI scheme manufacturing for connected security hardware.
Analog Technology retains the largest installed base, though Cloud-Based Solutions are expanding most quickly.
Installation Type:
Application environment dictates enclosure ratings, with outdoor and flush-mounted variants commanding premium engineering margins.
- Outdoor Installation:IP65+ rated housings with temperature tolerance and vandal resistance for exposed mounting. Dubai and Singapore commercial towers specify these for frictionless tenant access with edge AI inference.
- Flush-Mounted:Recessed wall integration requiring precise cavity preparation and finishing trades coordination. German commercial property markets favor aesthetic concealment in high-specification buildings.
- Indoor Installation:Climate-controlled environment units with reduced enclosure protection. Standardized mounting accelerates deployment in new residential construction.
- Surface-Mounted:External wall or door frame attachment with minimal structural modification. Retrofit-friendly form factor reduces labor costs in existing building stock.
Indoor Installation leads volume deployment, while Flush-Mounted specifications gain share fastest in premium commercial segments.
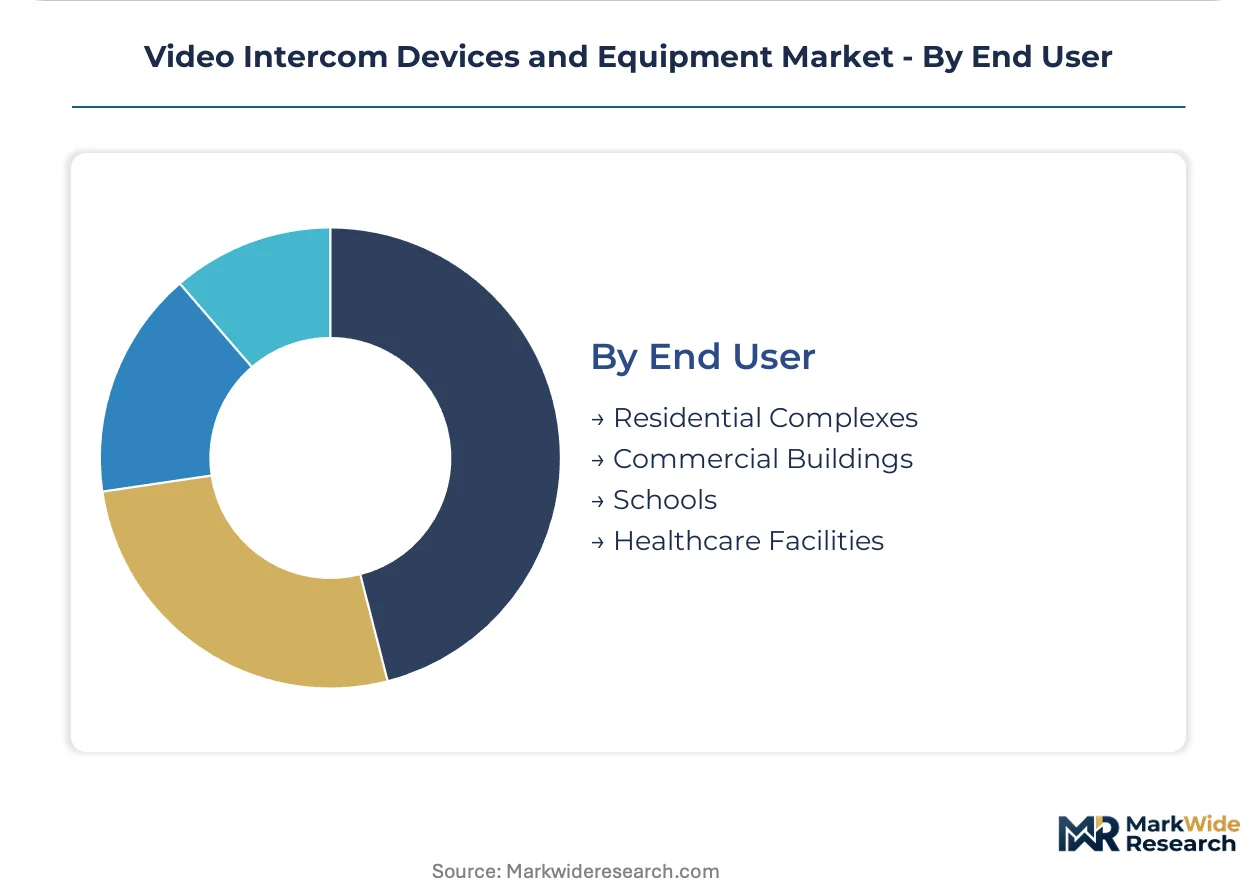
End User:
Customer type determines cybersecurity rigor, with healthcare and education verticals imposing patient data and child protection protocols beyond baseline commercial requirements.
- Commercial Buildings:Multi-tenant office and mixed-use properties requiring visitor management integration and access control federation. Audio-visual AI convergence enables facial recognition premium pricing in corporate security verticals.
- Residential Complexes:Multi-unit housing from mid-rise to high-rise density with centralized lobby and individual unit stations. Tier-2 Indian cities lack installed base of any intercom type, creating first-mover openings.
- Healthcare Facilities:HIPAA-aligned patient privacy requirements restricting video retention and access logging. Specialized firmware hardening against network intrusion demands scarce cybersecurity engineering talent.
- Schools:Child safety mandates driving visitor screening and emergency lockdown integration. BIS certification harmonization in India reduces duplicate compliance costs for imported security components.
Residential Complexes dominates shipment volume, with Healthcare Facilities posting the steepest expansion trajectory on security modernization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Video intercom manufacturing originated in post-war Japan and Germany, where precision electronics and building automation first converged. These foundations established supply chain patterns that persist across contemporary production networks.
Germany
Multi-tenant renovations in Berlin and Hamburg drive IP intercom installations under EU Green Deal efficiency mandates. ETSI cybersecurity certification frameworks mandate secure boot protocols for cloud-integrated systems. The Rhine-Ruhr industrial corridor hosts building automation integrators specializing in centralized network management for commercial real estate.
United States
Smart city deployments in Dallas and Atlanta accelerate wireless intercom adoption for municipal security infrastructure. FCC Part 15 compliance timelines extend product certification schedules for RF-based models. Silicon Valley cybersecurity clusters supply firmware hardening expertise for network-connected access control systems.
China
Domestic construction in Shenzhen and Chengdu absorbs volume production of Power-over-Ethernet devices. MIIT network access licensing delays cloud-integrated IP intercom launches by 6-12 months. The Yangtze River Delta concentration of image sensor foundries anchors camera module supply chains.
India
Tier-2 cities including Pune and Ahmedabad lack installed intercom base, creating first-mover openings for IP-native vendors. PLI scheme electronics manufacturing incentives strengthen domestic supply chains for connected security hardware. Bangalore's technology corridor hosts firmware development centers serving smart city procurement.
United Arab Emirates
Dubai commercial towers specify edge AI inference capabilities for frictionless tenant access systems. MOHAP building safety regulations align with international cybersecurity standards for networked entry devices. Abu Dhabi sovereign wealth deployment accelerates premium security infrastructure in government and hospitality verticals.
Video Intercom Devices and Equipment Market Competitive Environment
Premium-margin players sit above commodity-margin players across firmware sophistication and certification breadth. The vendor base stratifies between full-stack security conglomerates, specialized intercom fabricators, and regional electrical equipment suppliers. Three archetypes dominate: vertically integrated camera manufacturers leveraging sensor supply chains, building automation specialists bundling intercoms into integrated security contracts, and telecom-heritage firms applying voice-protocol expertise to IP architectures. Competitive moves concentrate on M&A for cybersecurity capabilities and strategic partnerships with smart city integrators.
Among Asian electronics conglomerates, Hikvision and Dahua Technology exemplify scale-driven positions anchored in component supply chain control. Panasonic Corporation occupies a heritage-technology tier, translating audio-visual integration R&D into building automation compatibility. Legrand represents the European electrical equipment archetype, distributing through contractor channels that consolidate procurement decisions in commercial property markets.
| Leading Market Players |
|---|
| Hikvision |
| Panasonic Corporation |
| Honeywell International Inc. |
| Legrand |
| Dahua Technology |
| Aiphone |
| Axis Communications |
| Samsung |
| Comelit Group |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal building efficiency mandates gate qualified supply and premium-tier pricing access by requiring ETSI cybersecurity certification and secure boot protocols for cloud-integrated IP intercoms targeting commercial real estate. Manufacturers embedding hardware security modules from component sourcing stages face steeper compliance costs that concentrate pricing power among firmware-sophisticated vendors serving German multi-tenant renovations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ETSI-certified cloud-native systems from digital hybrid bridges and legacy analog units. Price differentiation hinges on firmware sophistication and certification breadth versus volume manufacturing scale. Pricing pressure stems from copper and semiconductor input volatility squeezing margins on mid-tier product lines. Residential retrofit buyers in aging European housing stock exhibit highest price sensitivity, while Dubai commercial towers accepting edge AI inference capabilities show lowest.
Supply Chain Analysis
Specialized cybersecurity engineering talent shortages in Shenzhen and Chengdu manufacturing zones constrain firmware hardening capacity for network-connected devices. Component sourcing concentrates in China's Yangtze River Delta image sensor foundries, South Korean memory suppliers, and Taiwanese semiconductor packaging houses. Raw material dependencies include copper for Ethernet cabling, CMOS image sensors, and hardware security modules. Single-source vulnerability runs through MIIT network access licensing delays that extend cloud-integrated product launches. Distribution runs through integrated security contractors consolidating procurement decisions in German and Dutch commercial property markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in firmware-over-the-air architectures and edge AI inference capabilities as building automation shifts toward centralized network management. Premium-tier pricing power accrues to vendors mastering ETSI cybersecurity certification and multi-protocol integration engineering.
For Market Incumbents: Hedge against analog substitution inertia in aging European housing stock by accelerating IP-native product certification across ETSI, FCC, and BIS frameworks simultaneously. Deepen backward integration into image sensor supply chains to offset copper and semiconductor input volatility. Capture bundled service capabilities through integrated security contractor channels consolidating procurement in German commercial property markets. For New Entrants and Emerging Players: Begin with underpenetrated Tier-2 Indian residential towers in Pune and Ahmedabad where PLI scheme manufacturing incentives strengthen domestic supply chains and first-mover openings persist. Target healthcare facilities vertical requiring HIPAA-aligned patient privacy firmware hardening against network intrusion. Pursue smartphone-native mobile integration as primary go-to-market angle leveraging India's connected security hardware manufacturing base. For Investors and Strategic Acquirers: Roll-up economics work for cybersecurity-specialist firmware developers because firmware sophistication is displacing hardware scale as the locus of competitive advantage across Dubai and Singapore commercial tower deployments. Long-term viability favors acquisition targets with Israeli or Estonian security cluster engineering talent and ETSI pre-certified product pipelines. Monitor BIS certification harmonization progress as inflection indicator for reduced duplicate compliance costs enabling import-dependent vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Capability Acquisition | Firmware hardening expertise from Israeli and Estonian clusters addresses talent scarcity constraining cloud-integrated system launches. |
| Smart City Integrator Partnership | PLI scheme manufacturing alignment with Bangalore development centers accelerates procurement access for Indian municipal deployments. |
| ETSI Pre-Certification Investment | Secure boot and encrypted update protocols embed hardware security modules from component sourcing stages for EU commercial real estate. |
| Edge AI Inference Development | Facial recognition integration at door stations captures premium pricing in Dubai and Singapore corporate security verticals. |
| Multi-Protocol Engineering Scale-Up | SIP, ONVIF, and proprietary building management interface customization reduces deployment friction for centralized network management. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with building automation integrators, facility managers, cybersecurity firmware engineers, and integrated security contractors with secondary validation. Secondary sources included ETSI cybersecurity certification documentation, MIIT network access licensing records, BIS electronics testing protocols, and EU Green Deal building renovation mandate filings. Bottom-up shipment modeling across product type, technology, installation type, and end user segments triangulated against top-down construction spend and smart city procurement data.
Segment-weighting approaches distributed volume and value projections across IP intercom, wired intercom, wireless intercom, and video door phone categories, with technology dimension weightings reflecting cloud-based solution, analog, digital, and mobile integration adoption curves. CAGRs were derived from installation base growth, replacement cycle acceleration, and new construction penetration assumptions. Forecast inputs incorporated Power-over-Ethernet standardization timelines, PLI scheme manufacturing capacity buildouts, and ETSI IoT cybersecurity framework compliance cost trajectories across the analysis window.
Several conditions sit outside the modeled scope, including sudden MIIT regulatory reinterpretations, copper commodity price spike events exceeding historical volatility bands, and cybersecurity talent pool migration disruptions. Forecasts reflect assumptions about renovation cycle timing and smart city procurement continuity. Material deviation in ETSI certification cost trajectories or BIS harmonization progress warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
GDPR Software and Tools Market
Security Software
Security Software Market
Security Software
Smartphone Security Market
Security Software
Contactless Smart Card Market
Security Software
Global Consumer Identity and Access Management Market
Security Software
Saudi Arabia Managed Security Services Market
Security Software
DC and PKI Market
Security Software
Passport Reader Market
Security Software
Mobile Data Protection Solutions and Services Market
Security Software
Global Digital Vehicle Forensics Market
Security Software
Europe Smart Doorbell Market
Security Software
Mobile Antivirus Software Market
Security Software
Network Video Recorder (NVR) Market
Security Software
Automotive Endpoint Authentication Market
Security Software
DNS Protection Software Market
Security Software
Global Mobile Security Software Market