
 Government Open Data Management Platform Market | 2026-2036
Government Open Data Management Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Government Open Data Management Platform Market Foresight
Subscription-based SaaS financing is rewriting competitive dynamics for mid-tier vendors seeking government contracts. OpenGov Inc. leverages cloud-native architecture to reduce upfront capital barriers for municipal buyers. Tyler Technologies Inc. anchors its position through deep integration with legacy permitting and billing systems. Esri Global Inc. dominates geospatial data layers that underpin location-aware open data portals.
A government open data management platform constitutes an integrated software environment for ingesting, cataloging, standardizing, and publishing machine-readable public datasets through APIs and visual interfaces. The system employs metadata tagging protocols such as DCAT or Schema.org to ensure interoperability across heterogeneous agency sources. Cloud-based solutions lead technology adoption due to elastic scaling requirements during election-cycle traffic spikes. Public cloud deployment captures the fastest growth trajectory as agencies abandon aging on-premises infrastructure. Citizen engagement applications concentrate margin pools where analytics dashboards demonstrate measurable service-delivery outcomes.
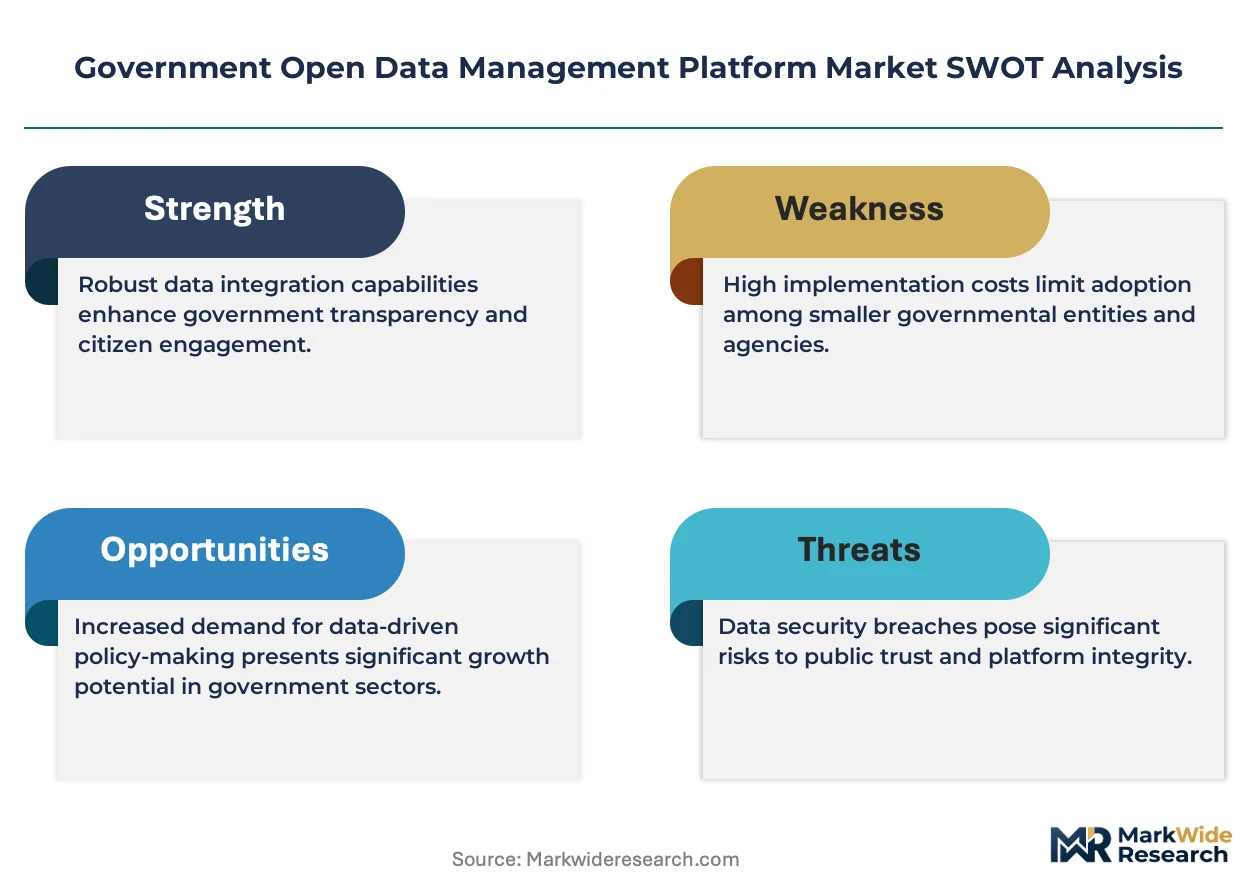
The EU Open Data Directive, the US OPEN Government Data Act, and ISO 37120 smart city indicators collectively mandate standardized data formats and accessibility benchmarks. EMA and national health regulators in Europe now require clinical trial transparency portals that interface directly with government open data frameworks. Stakeholders must monitor evolving procurement rules around data sovereignty and cross-border API interoperability as these determine which platform architectures qualify for public-sector deployment.
Market Dynamics
The transition from on-premises infrastructure to public cloud deployment is compressing procurement cycles and forcing vendors to restructure pricing models around consumption-based billing rather than perpetual licenses.
Growth Catalysts
- EU Open Data Directive:Mandates machine-readable publication of public sector information across member states, creating standardized demand for interoperable cataloging systems.
- Smart city municipal clusters:Urban digitization initiatives in Barcelona, Singapore, and Toronto are generating concentrated procurement of geospatial-integrated portals.
- API-first architectures:Real-time data streaming protocols enable civic developers to build third-party applications atop government datasets.
Market Restraints
- Data sovereignty compliance:Cross-border cloud storage restrictions in Germany, France, and China fragment platform deployment architectures.
- Legacy system integration costs:Proprietary mainframe databases in aging tax and property registries resist standard metadata tagging.
- Skilled metadata architect shortage:Deep expertise in DCAT, Schema.org, and ISO 19115 standards concentrates in a thin talent pool.
Strategic Opportunities
- Clinical trial transparency portals:EMA and national health regulators now mandate direct interfaces with government open data frameworks.
- Subscription SaaS penetration:Mid-tier municipalities previously priced out of capital-intensive deployments now access elastic cloud solutions.
- Geospatial-analytics convergence:Integration of Esri layer technologies with real-time sensor networks opens location-aware service delivery.
Industry Challenges
- Interoperability certification timelines:ISO 37120 smart city indicator compliance requires 18-24 month validation cycles that delay revenue recognition.
- Technical debt in agency workflows:Decades-old permitting databases lack field-level documentation needed for automated metadata extraction.
- Cross-border API governance:Divergent national standards for data format, access logging, and citizen privacy create compliance fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Government Open Data Management Platform Market |
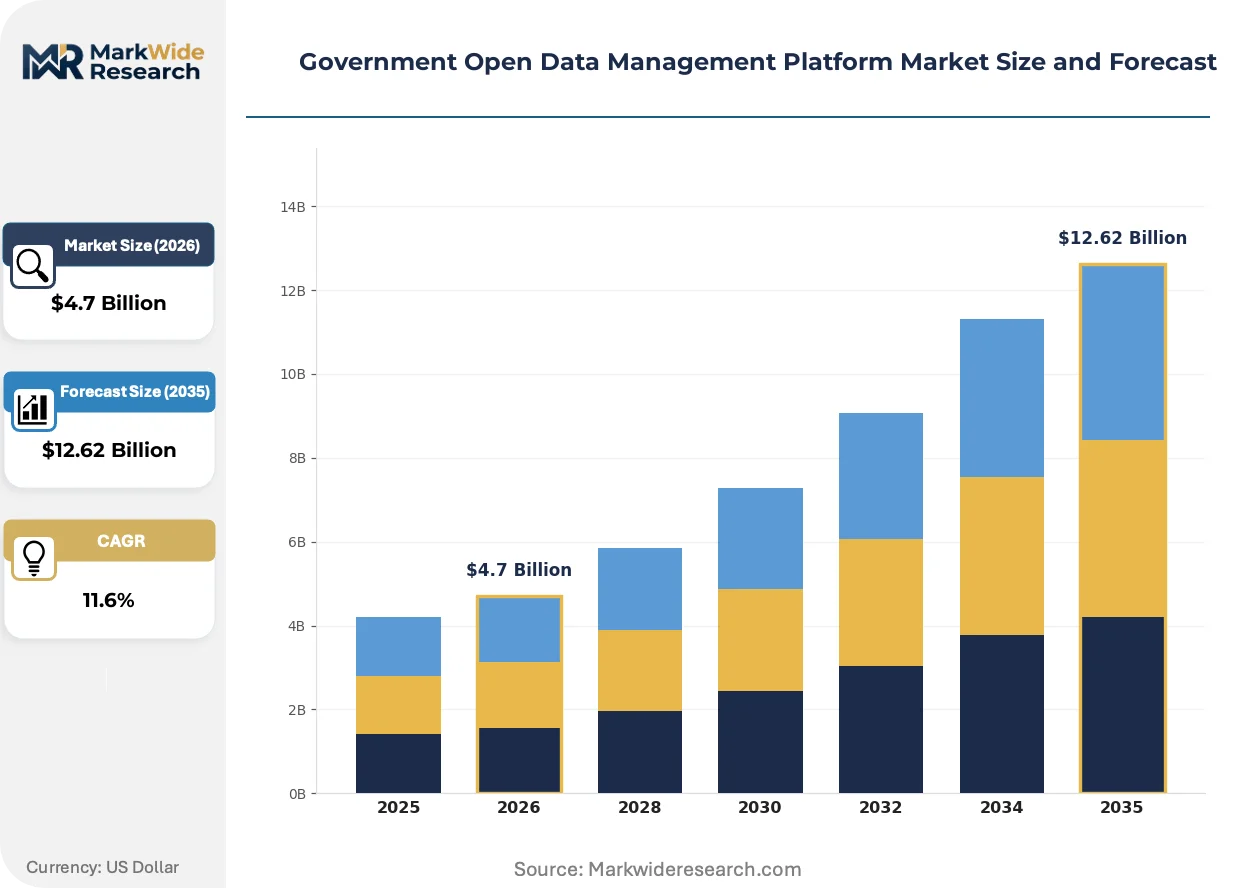
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.62 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Public Sector Transparency, Policy Development, Data Sharing, Citizen Engagement Technology: Cloud-Based Solutions, Data Visualization Tools, API Management, Data Analytics Deployment: On-Premises, Hybrid Cloud, Public Cloud, Private Cloud End User: Government Agencies, NGOs, Research Institutions, Academia |
| Companies Covered | OpenGov Inc., Tyler Technologies Inc., Esri Global Inc., Collibra, CartoDB Inc., CivicActions, DATA.WORLD INC., Opendatasoft, Oracle Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Government Open Data Management Platform Market Shifts & Advancements
Platform architectures are pivoting from static repository models toward real-time streaming infrastructures that embed analytics directly into citizen-facing interfaces.
Containerized microservices architectures are migrating from monolithic legacy stacks toward modular, API-driven components that agencies can deploy independently. State transportation departments and environmental agencies are adopting these patterns fastest, driven by election-cycle traffic spikes that demand elastic scaling. The structural compression of deployment timelines from 18 months to 6 weeks is enabling smaller municipalities to launch portals without dedicated IT departments.
REACH chemical safety data sharing requirements and the EU AI Act's transparency mandates are forcing convergence between open data portals and algorithmic accountability frameworks. Industrial consequence: platform vendors must now embed explainability layers and bias audit trails into core product stacks. Health and environmental agencies across Nordic countries are responding by procuring integrated disclosure systems that unify dataset publication with automated impact assessments.
Consumption-based billing models are displacing perpetual license structures across federal and state procurement channels. Systems integrators and value-added resellers face margin compression as agencies contract directly with cloud-native vendors for metered API access. This pattern is most visible in US federal deployments, where GSA schedule reforms now prioritize operational expenditure treatment over capital appropriations.
Government Open Data Management Platform Market Segmentation
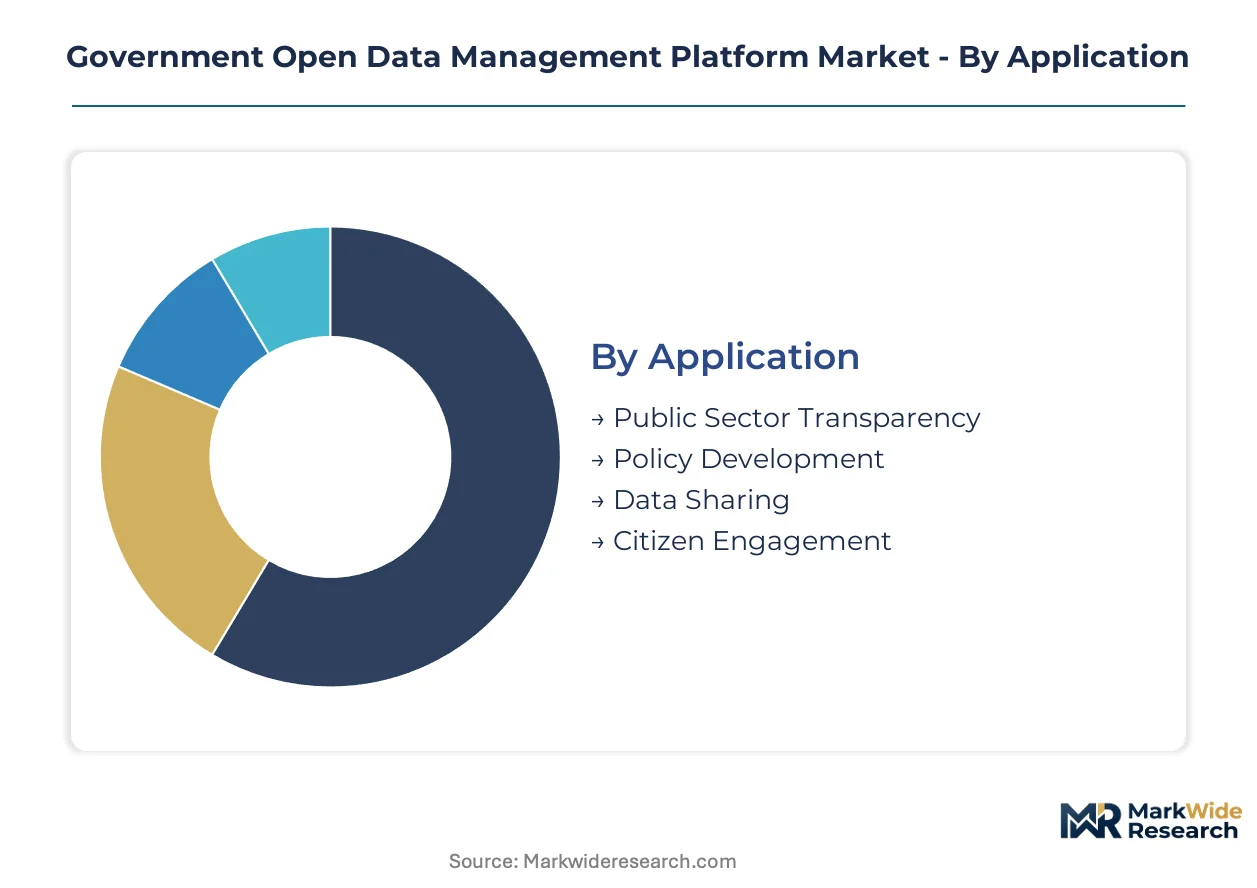
Segmentation in this market reveals how procurement priorities diverge between legacy-bound federal agencies and cloud-native municipal buyers. Understanding these splits helps vendors align product architecture with compliance requirements and budget cycles.
Application:
Cost tier determines platform configuration complexity, with high-touch transparency mandates commanding premium pricing against lighter citizen engagement modules.
- Public Sector Transparency:Mandated disclosure systems for procurement records, elected official finances, and regulatory enforcement actions. State-level procurement offices in California and New York concentrate demand as sunshine laws tighten audit requirements.
- Policy Development:Legislative analytics environments that aggregate cross-agency datasets for evidence-based rulemaking. Parliamentary technology services in Germany and the Netherlands drive specialized procurement for impact assessment tooling.
- Data Sharing:Inter-agency federation protocols enabling standardized metadata exchange across departmental silos.
- Citizen Engagement:Self-service portals with embedded feedback loops and petition mechanisms. Municipal deployments in Singapore and Toronto prioritize mobile-first interfaces for service request routing.
Public Sector Transparency holds installed capacity. Citizen Engagement is rotating up the share rankings.
Technology:
Application workload characteristics dictate whether agencies prioritize elastic scaling, visual discovery, or real-time integration capabilities.
- Cloud-Based Solutions:Multi-tenant SaaS architectures with automated compliance patching and consumption metering. Federal GSA schedule contracts and state procurement offices in Texas and Florida are accelerating migration from capital-intensive on-premises estates.
- API Management:Gateway infrastructure for rate limiting, authentication, and developer onboarding. Nordic health regulators and EMA-mandated clinical trial portals require enterprise-grade throttling for high-frequency researcher access.
- Data Visualization Tools:Embedded charting libraries and geospatial rendering engines for non-technical civil servant audiences.
- Data Analytics:Predictive modeling modules that surface anomaly detection and trend forecasting across published datasets.
Cloud-Based Solutions anchors revenue concentration. API Management is climbing the fastest as regulatory interoperability mandates proliferate.
Deployment:
Customer type and data sensitivity classification determine infrastructure location strategy across sovereignty and latency constraints.
- Public Cloud:Hyperscaler-hosted environments with shared responsibility models for security patching. Small and mid-sized municipalities in the United States and Canadian provinces are adopting fastest where dedicated IT staffing is unavailable.
- Hybrid Cloud:Split architectures retaining sensitive identity or audit logs on-premises while publishing sanitized datasets to public endpoints. German federal agencies and French regional councils mandate this pattern under national data localization statutes.
- On-Premises:Air-gapped or government-facility-hosted systems for classified or critical infrastructure data.
- Private Cloud:Dedicated single-tenant environments with sovereign cloud certification for defense and intelligence community buyers.
Public Cloud captures volume expansion. Hybrid Cloud is gaining share fastest where cross-border data governance tightens.
End User:
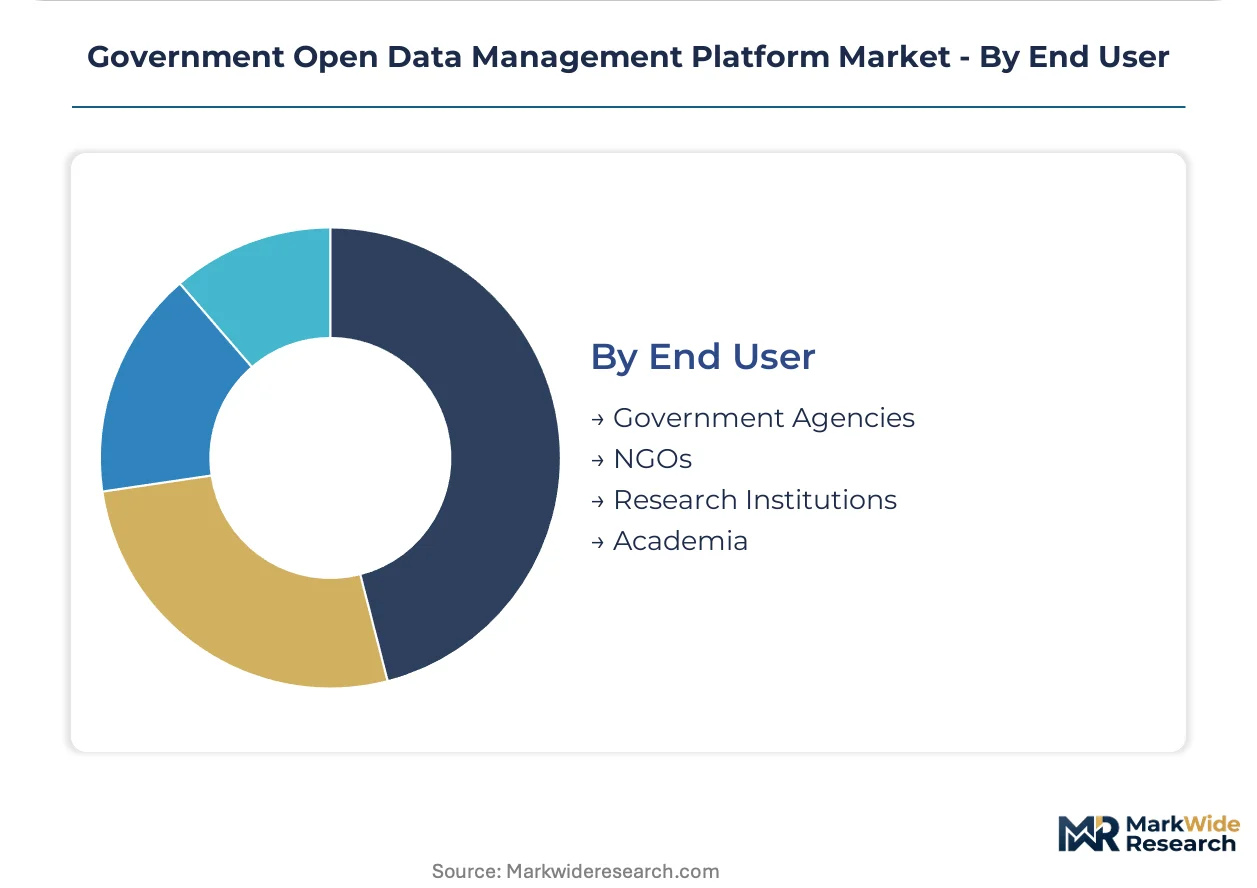
Volume scale and procurement authority fragment across institutional categories with divergent technical sophistication and funding mechanisms.
- Government Agencies:Sovereign buyers with formal appropriations cycles and mandatory accessibility compliance. United States federal departments and state-level digital service teams concentrate platform procurement through centralized IT shared services.
- Research Institutions:Grant-funded academic and applied research centers requiring API access for longitudinal analysis. European Research Council-funded consortia and United States National Science Foundation grantees drive demand for high-throughput data extraction capabilities.
- NGOs:Advocacy organizations and watchdog groups leveraging freedom of information frameworks for accountability monitoring.
- Academia:University-based policy schools and data science programs integrating portal access into curriculum and publication workflows.
Government Agencies dominate installed base. Research Institutions are expanding most quickly as open science mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Open Data Directive mandates machine-readable publication across member states, while the US OPEN Government Data Act drives federal and state-level procurement. Smart city digitization clusters in Barcelona, Singapore, and Toronto concentrate municipal demand for geospatial-integrated portals.
United States
Federal GSA schedule contracts and state-level digital service teams in Texas and Florida accelerate migration from on-premises estates to consumption-based cloud models. The OPEN Government Data Act mandates standardized data formats for federal agencies. Municipal deployments concentrate in California and New York where sunshine laws tighten audit requirements for transparency portals.
Germany
Federal agencies and regional councils mandate hybrid cloud architectures under national data localization statutes that restrict cross-border storage. The country's data protection framework requires split deployments retaining sensitive audit logs on-premises. Smart city initiatives in Berlin and Hamburg drive procurement of interoperability-certified cataloging systems.
France
Regional councils and metropolitan authorities prioritize sovereign cloud certifications for defense and critical infrastructure data management. National data sovereignty compliance fragments platform deployment architectures across public and hybrid environments. The Paris-Saclay cluster and Lyon metropolitan area concentrate municipal open data portal procurement.
Singapore
Urban digitization initiatives generate concentrated procurement of mobile-first citizen engagement interfaces for service request routing. The national smart city program mandates real-time data streaming protocols for civic developer ecosystems. Government Technology Agency deployments anchor demand for API-first architectures with embedded analytics dashboards.
Canada
Provincial and municipal buyers adopt public cloud solutions fastest where dedicated IT staffing remains unavailable for on-premises management. Federal transparency mandates align with provincial sunshine laws in Ontario and British Columbia. The Toronto-Waterloo corridor concentrates smart city platform procurement with geospatial-analytics convergence requirements.
Government Open Data Management Platform Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where cloud-native vendors displace legacy systems integrators. The vendor base separates into three strategic archetypes: SaaS-native platform builders, legacy system integrators with deep permitting and billing integration, and geospatial data layer specialists. Dominant competitive moves include consumption-based pricing restructuring and API-first architecture migration to capture municipal buyers previously priced out of capital-intensive deployments.
Within the cloud-native tier, OpenGov Inc. and Tyler Technologies Inc. exemplify contrasting approaches to municipal market penetration. OpenGov Inc. represents the SaaS-native archetype with architecture designed to reduce upfront capital barriers for mid-tier government buyers. Tyler Technologies Inc. anchors the legacy-integration position through established relationships with tax and property registry systems. Esri Global Inc. occupies the geospatial-specialist tier, dominating location-aware data layers that underpin smart city portal functionality across North American and European deployments.
| Leading Market Players |
|---|
| OpenGov Inc. |
| Tyler Technologies Inc. |
| Esri Global Inc. |
| Collibra |
| CartoDB Inc. |
| CivicActions |
| DATA.WORLD INC. |
| Opendatasoft |
| Oracle Corp. |
| Others |
Supply & Pricing Matrix
Overcapacity in European cloud infrastructure regions is compressing vendor margins and accelerating consumption-based pricing adoption across municipal procurement channels. Utilization rates below sixty percent in Frankfurt and Amsterdam hyperscaler zones are forcing platform providers to restructure contract terms around metered API access rather than perpetual licenses, reshaping both supplier economics and buyer negotiation leverage.
Pricing Analysis
Certification level creates the primary spread between deployment tiers, with ISO 37120 smart city indicator compliance commanding premium positioning against basic transparency modules. Subscription SaaS models now dominate federal and state procurement, displacing capital-intensive on-premises licensing. Price differentiation rests on metadata architect availability and cross-border data sovereignty bundling. Small and mid-sized municipalities exhibit highest price sensitivity due to constrained IT appropriations, while defense and intelligence buyers prioritize sovereign cloud certifications over cost.
Supply Chain Analysis
Export control restrictions on advanced encryption and geospatial processing technologies are fragmenting component sourcing across jurisdictional boundaries. Software development concentrates in the United States, Germany, and India, with cloud infrastructure provisioning anchored in hyperscaler regions. Platform architectures draw from open-source cataloging protocols, containerized orchestration layers, and API gateway components. Single-source vulnerability in specialized metadata tagging expertise creates bottlenecks. Distribution runs through GSA schedule contracts and state procurement offices, supplemented by direct municipal SaaS contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent platform vendors face substitution pressure from low-code portal builders and generative AI-native entrants that automate metadata extraction without specialized architect labor. Defense requires reinforcing integration moats and certification barriers that generic alternatives cannot replicate.
For Market Incumbents: Build workflow integration moats by embedding deeply into legacy tax and property registry systems that resist rip-and-replace. Invest in ISO 37120 pre-certification programs to compress municipal sales cycles. Prioritize hybrid cloud architecture development to capture German and French data localization requirements. Counter low-code substitution threats through API ecosystem density that generic platforms cannot match.
For New Entrants and Emerging Players: Pursue clinical trial transparency portal specialization where EMA mandates create standardized demand with limited incumbent presence. Target Nordic health regulators and mid-tier Canadian provinces with consumption-based pricing that eliminates upfront capital barriers. Enter through geospatial-analytics convergence partnerships rather than competing directly with Esri layer dominance.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment segments as containerized microservices reduce infrastructure overhead. Long-term viability favors vendors with recurring revenue concentration above seventy percent and federal contract vehicles already established. Acquisition target archetype: SaaS-native platforms with existing GSA schedule placement and municipal customer bases exceeding one hundred deployments. Monitor API interoperability mandate acceleration as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep embedding with Tyler Technologies' legacy permitting systems locks in municipal renewals. |
| Geographic Expansion | Entry into Singapore's Government Technology Agency procurement opens ASEAN smart city corridors. |
| Strategic Partnership | Esri layer integration partnerships enable location-aware service delivery differentiation. |
| Acquisition of Specialist Firm | DCAT metadata architect talent pools concentrate in boutique European consultancies. |
| Product Launch | Clinical trial transparency modules align with EMA algorithmic accountability mandates. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with government technology officers, municipal CIOs, platform engineering leads, and procurement contract specialists; and secondary validation through GSA schedule contract awards, EU Open Data Directive implementation reports, ISO certification registries, and municipal budget appropriation documents. Bottom-up deployment counts across fifty metropolitan statistical areas were triangulated against top-down vendor revenue segmentation.
Forecast inputs incorporated deployment model migration rates, regulatory mandate phase-in schedules, and municipal digitization appropriation trends across the projection horizon. Segmentation dimensions modeled include application type, technology stack, deployment architecture, and end-user institutional category. CAGRs were derived from elasticity-adjusted adoption curves calibrated to election-cycle procurement patterns and cloud infrastructure cost trajectories.
Sensitivities concentrate around data sovereignty regulation tightening, API interoperability standard revisions, and generative AI automation of metadata tagging workflows. Forecasts reflect assumptions on municipal IT staffing constraints and federal grant program continuity. Material shifts in cross-border cloud governance or low-code platform capability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Managed File Transfer (MFT) Market
Digital Solutions
China Digital Twin Market
Digital Solutions
On-Demand Warehousing Platforms Market
Digital Solutions
Smart Signage Market
Digital Solutions
Subscription (Digital) Services Market
Digital Solutions
Connected Stadium Solution Market
Digital Solutions
Graphical Situational Display Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
Cloud E-Signature Tools Market
Digital Solutions
Data Integration Market
Digital Solutions
Saudi Arabia ICT Market
Digital Solutions
Cloud MFT Services Market
Digital Solutions
North America Smart Card Market
Digital Solutions
API Management Market
Digital Solutions
Europe Content Moderation Services Market
Digital Solutions
Global Interactive Voice Response Market