
 Global Nano Metal Oxide Market | 2026-2036
Global Nano Metal Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nano Metal Oxide Market Intelligence
The increasing use of advanced chemical vapor deposition is reconfiguring how nano-scale films are applied in semiconductor manufacturing. Evonik Industries AG leverages its chemical expertise to provide high-purity precursors for these advanced processes. American Elements specializes in supplying a wide range of custom nano-materials for research and niche industrial uses, while Nanophase Technologies Corporation focuses on engineered oxide particles for commercial applications.
Nano metal oxides are inorganic materials with particle dimensions under 100 nanometers, creating unique quantum size effects. These properties, such as enhanced reactivity and UV blocking, dictate their use in industrial and consumer products. While titanium dioxide and zinc oxide dominate volume due to their use in coatings and cosmetics, applications in catalysts and sensors are showing significant momentum. The electronics sector provides a high-margin outlet for specialized materials like cerium oxide.
Market access is shaped by regulations like the EU's REACH framework and the US EPA's policies under the Toxic Substances Control Act. These rules require comprehensive safety data and risk assessments for nanomaterials before commercialization. The key strategic decision for producers now involves balancing investment in scalable, low-cost precipitation methods against high-performance but costly sol-gel techniques.
Market Dynamics
The central force shaping the market is the semiconductor industry's push for miniaturization, which necessitates novel materials with specific quantum-scale properties. This demand is met by advances in deposition technologies that enable precise application of nano-scale films.
Growth Catalysts
- Advanced Deposition Processes:The adoption of advanced chemical vapor deposition and atomic layer deposition in semiconductor fabrication allows for the precise, uniform application of nano metal oxide films, enabling the production of smaller, more powerful electronic components.
- Electronics Sector Expansion:Concentrated demand from electronics manufacturing hubs in South Korea and Taiwan for specialized materials like high-purity cerium oxide and hafnium oxide provides a high-margin growth engine for specialized producers.
- Environmental Mandates:Stricter emissions standards in the automotive and industrial sectors, particularly in Europe and Japan, are increasing the use of nano-ceria and other oxides as catalysts for pollution control systems.
Market Restraints
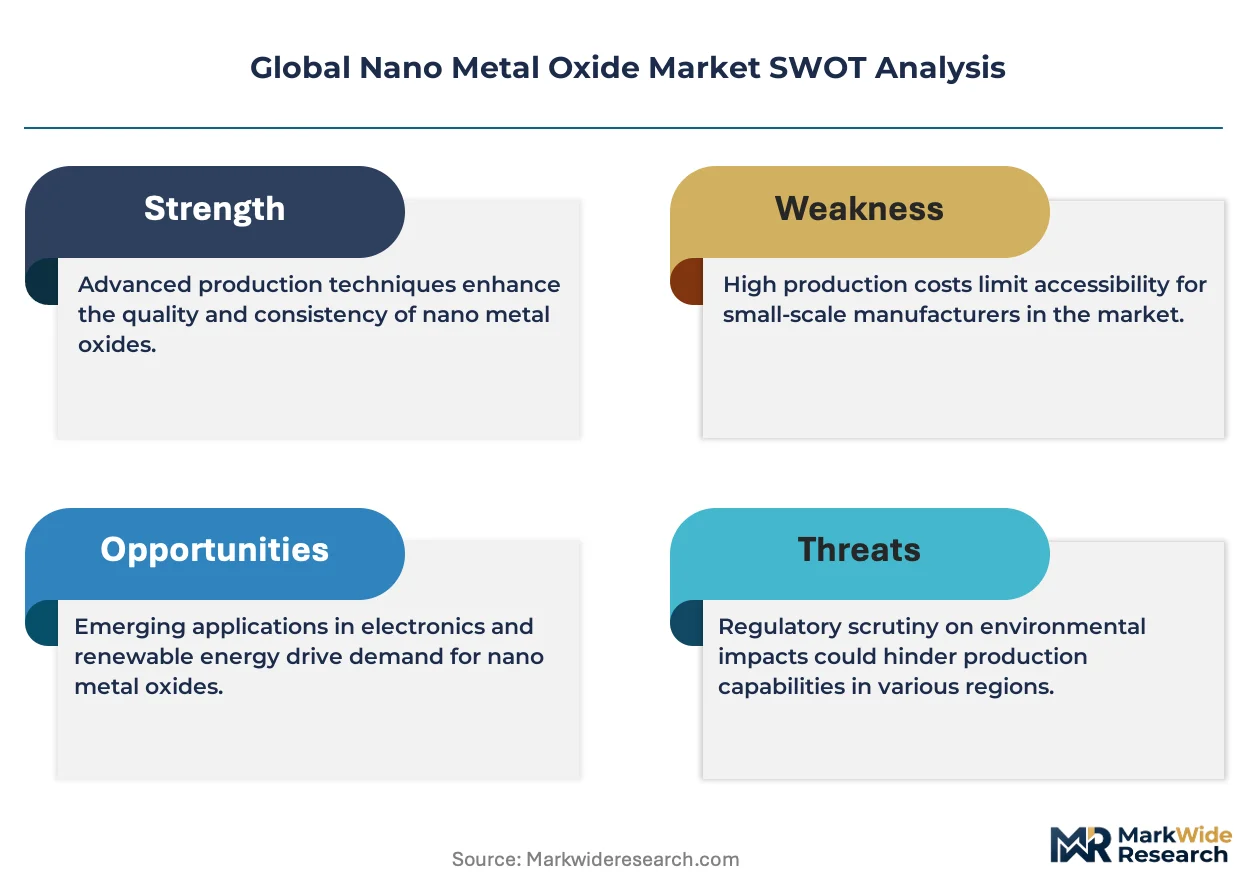
- High Precursor Costs:The production of high-purity nano metal oxides requires expensive and volatile organometallic precursors, creating a significant cost barrier for new entrants and pressuring margins for existing producers.
- Regulatory Compliance Burden:Frameworks like the EU's REACH and the US EPA's TSCA require extensive and costly toxicological data and risk assessments before nanomaterials can be commercialized, slowing product introduction.
- Production Scalability Issues:Achieving consistent particle size, morphology, and purity at industrial scale remains a significant technical hurdle, particularly for complex synthesis methods like sol-gel or hydrothermal techniques.
Strategic Opportunities
- Biomedical Applications:Iron oxide and cerium oxide nanoparticles present opportunities as contrast agents in magnetic resonance imaging (MRI) and as therapeutic agents in targeted drug delivery systems, representing an emerging high-value segment.
- Energy Storage Materials:The development of next-generation lithium-ion batteries and supercapacitors creates an opening for nano metal oxides like manganese oxide and tin oxide to be used as advanced anode and cathode materials.
- Smart Sensor Integration:The convergence of nano metal oxides with AI-driven software offers a pathway to develop highly sensitive and selective chemical sensors for environmental monitoring, industrial process control, and medical diagnostics.
Industry Challenges
- Capital-Intensive Scaling:The transition from laboratory-scale synthesis to commercial-volume production requires substantial capital investment in specialized reactors, purification systems, and cleanroom facilities, posing a challenge for smaller firms.
- Characterization Standardization:A lack of universally accepted standards and metrology for characterizing nanomaterial properties, such as particle size distribution and surface area, creates inconsistencies and complicates quality control across the supply chain.
- Specialized Talent Scarcity:The industry faces a shortage of material scientists and chemical engineers who possess the interdisciplinary expertise in quantum physics, surface chemistry, and process engineering required for advanced nanomaterial development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nano Metal Oxide Market |
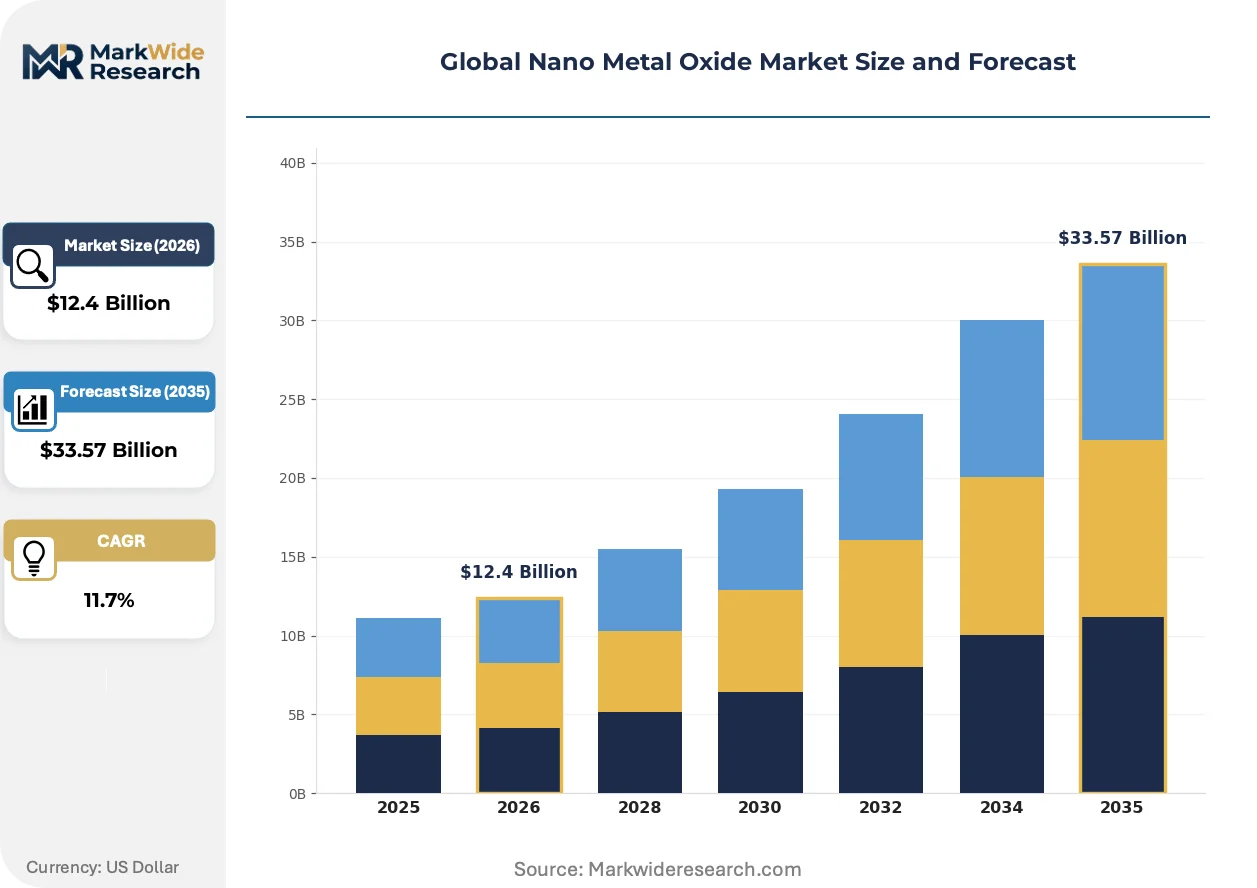
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $33.57 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zinc Oxide, Titanium Dioxide, Iron Oxide, Cerium Oxide, Aluminum Oxide, Copper Oxide Application: Coatings, Electronics, Catalysts, Sensors, Photovoltaics, Cosmetics End User Industry: Semiconductor Manufacturers, Paint Producers, Renewable Energy Firms, Personal Care Brands, Chemical Processors, Packaging Companies Technology: Sputtering, Sol-Gel, Hydrothermal, Chemical Vapor Deposition, Precipitation, Electrochemical Methods |
| Companies Covered | Nanoshel LLC, Hongwu International Group Ltd., Nanophase Technologies Corporation, Nanografi Nano Technology, Meliorum Technologies, Inc., American Elements, Baikowski SAS, Evonik Industries AG, SkySpring Nanomaterials Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nano Metal Oxide Market Strategic Shifts & Innovations
Material science innovation is focused on achieving atomic-level control over film properties, enabling new functionalities in electronics and energy. Concurrently, evolving regulatory frameworks are forcing a greater emphasis on lifecycle safety and material traceability from production to end-of-life.
Atomic Layer Deposition (ALD) provides a method for depositing films one atomic layer at a time. Semiconductor manufacturers are rapidly adopting ALD for creating ultra-thin gate oxides and diffusion barriers essential for sub-10 nanometer chip nodes. This level of precision is collapsing the boundary between surface chemistry and bulk material properties, allowing for the engineering of entirely new electronic behaviors at the quantum level.
Regulatory scrutiny over nanomaterials is intensifying globally. South Korea's K-REACH legislation, mirroring the EU's framework, now requires specific registration and risk assessment for nanomaterials, increasing compliance costs for manufacturers and importers. This directly impacts high-volume materials like titanium dioxide and zinc oxide used in cosmetics and coatings, compelling companies to invest in comprehensive safety data or seek alternative formulations.
A clear shift toward performance-based material specification is altering procurement dynamics. Instead of purchasing commoditized powders, buyers in the aerospace and medical device sectors are co-developing custom nano-dispersions with suppliers to meet specific functional requirements like thermal conductivity or biocompatibility. This collaborative model bypasses traditional distribution channels and is most advanced in the highly integrated industrial ecosystems of Germany and Japan.
Global Nano Metal Oxide Market Segmentation
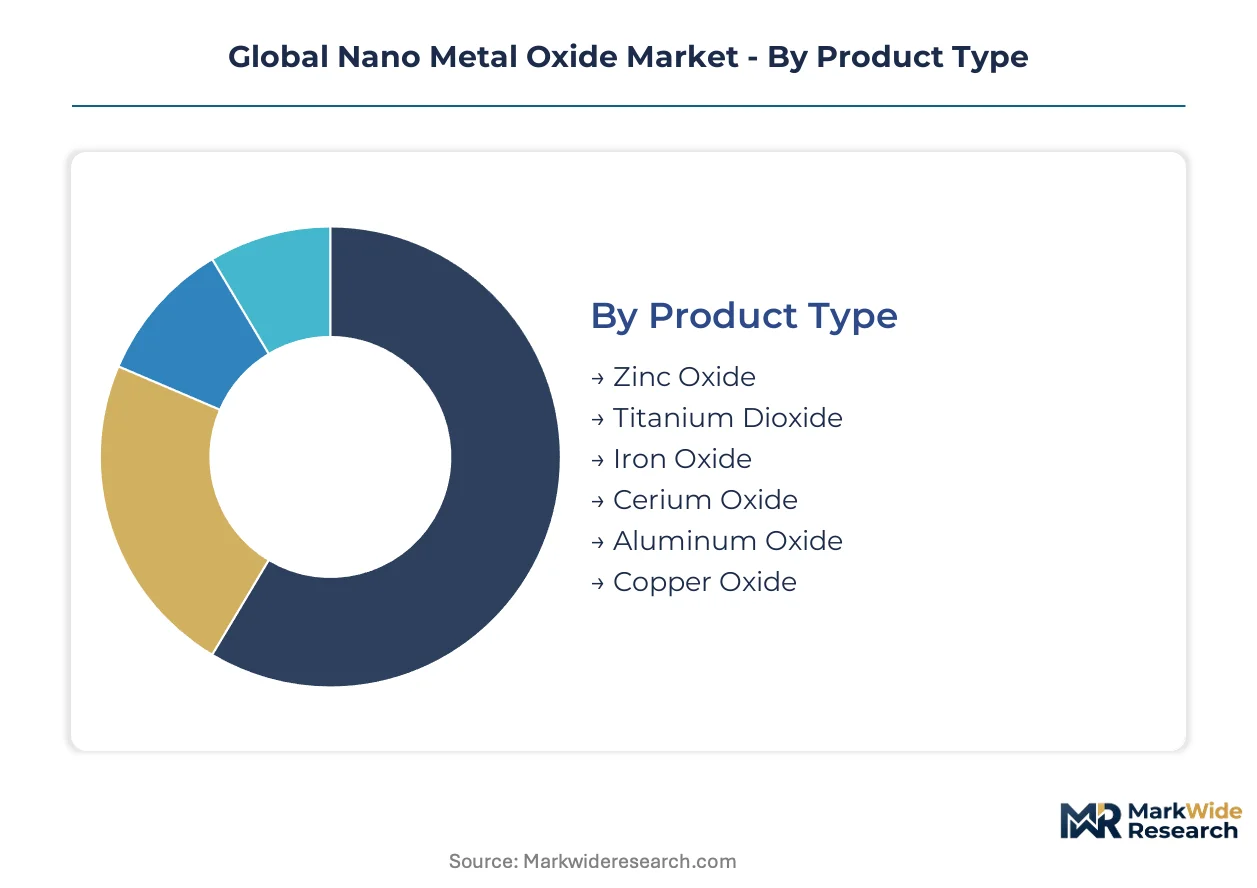
The Global Nano Metal Oxide Market's diverse applications and production methods necessitate a detailed segmentation analysis. Understanding these distinct market facets provides clarity on demand drivers and technological advancements. This granular view helps stakeholders identify specific growth pockets and competitive pressures across various segments.
Product Type:
The inherent material properties and cost structures define the distinct categories of nano metal oxides available in the market.
- Titanium Dioxide:Titanium dioxide nanoparticles offer high refractive index and UV absorption, widely used in sunscreens and protective coatings. European cosmetics manufacturers drive demand, influenced by stringent regulations.
- Cerium Oxide:Cerium oxide nano-particles exhibit unique redox properties, critical for catalytic converters and CMP slurries. Electronics manufacturing hubs like South Korea and Taiwan drive demand for high-purity cerium oxide.
- Zinc Oxide:Zinc oxide nanoparticles offer broad-spectrum UV protection and antibacterial properties for personal care.
- Iron Oxide:Iron oxide nanoparticles are employed in magnetic data storage, biomedical imaging, and pigments.
- Aluminum Oxide:Aluminum oxide nanoparticles serve as abrasives, catalysts, and high-performance ceramics.
- Copper Oxide:Copper oxide nanoparticles are utilized in catalysts, sensors, and antimicrobial coatings.
Titanium Dioxide holds installed capacity. Cerium Oxide is rotating up the share rankings.
Application:
Specific end-use applications dictate the required performance characteristics and volume of nano metal oxides.
- Electronics:Nano metal oxides are integral to advanced electronic components, forming ultra-thin films for gate oxides and memory devices. South Korea and Taiwan's semiconductor industries drive demand for these specialized materials.
- Catalysts:Nano metal oxides like cerium oxide enhance reaction efficiency and reduce emissions in automotive and industrial processes. Stricter environmental mandates in Europe and Japan drive increased deployment.
- Coatings:Protective and functional coatings utilize nano metal oxides for enhanced durability, UV resistance, and self-cleaning.
- Sensors:Nano metal oxides provide high surface area and tunable conductivity for sensitive detection in gas and chemical sensors.
- Photovoltaics:Nano metal oxides improve light absorption and electron transport in solar cells, boosting energy conversion.
- Cosmetics:Cosmetic formulations incorporate nano metal oxides for UV protection, opacifying effects, and skin benefits.
The Electronics sector is gaining share fastest. Cosmetics maintains a stable but volume-driven consumption profile.
End User Industry:
The diverse industrial landscape utilizes nano metal oxides for specialized functionalities across a range of manufacturing processes.
- Semiconductor Manufacturers:These firms integrate nano metal oxides into advanced chip architectures for improved performance, miniaturization, and power efficiency. High-purity hafnium oxide and cerium oxide are critical inputs for next-generation devices.
- Renewable Energy Firms:Companies in solar and battery technologies employ nano metal oxides to enhance energy conversion, storage capacity, and electrode stability. Manganese oxide and tin oxide show promise as advanced anode and cathode materials.
- Paint Producers:Paint producers use nano metal oxides for UV resistance, antimicrobial properties, and improved scratch durability.
- Personal Care Brands:Personal care brands incorporate nano metal oxides like zinc oxide and titanium dioxide into sunscreens and cosmetics.
- Chemical Processors:Chemical processors leverage nano metal oxides as catalysts for various reactions, improving efficiency and selectivity.
- Packaging Companies:Packaging companies apply nano metal oxides for UV blocking, gas barrier properties, and antimicrobial protection.
Semiconductor Manufacturers exhibit the steepest expansion trajectory. Paint Producers represent a mature segment with consistent material demand.
Technology:
The production technologies for nano metal oxides range from high-precision deposition methods to scalable synthesis routes.
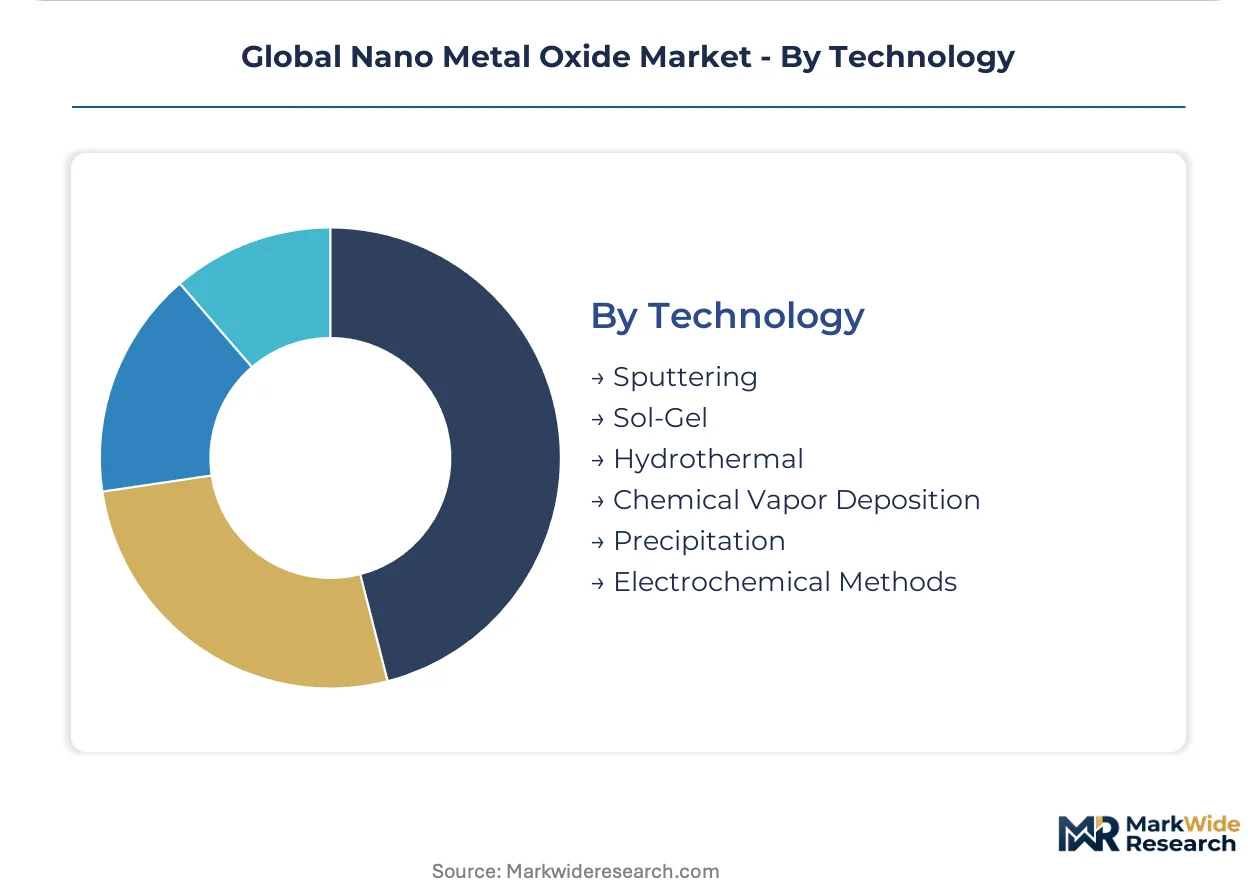
- Chemical Vapor Deposition:This advanced technique enables precise application of ultra-thin nano metal oxide films with atomic-level control, crucial for semiconductor fabrication. Manufacturers in South Korea and Taiwan rapidly adopt CVD.
- Sol-Gel:The sol-gel method produces highly pure and homogeneous nano metal oxides with controlled particle size and morphology, ideal for high-performance applications. While capital-intensive, this technique is favored for specialized materials.
- Sputtering:Sputtering is a physical vapor deposition technique creating thin films of nano metal oxides for optical and electronic devices.
- Hydrothermal:The hydrothermal method synthesizes crystalline nano metal oxides at elevated temperatures and pressures for industrial catalysts.
- Precipitation:Precipitation methods offer a scalable and cost-effective route for producing nano metal oxides for high-volume commodity applications.
- Electrochemical Methods:Electrochemical synthesis enables controlled growth of nano metal oxide nanostructures, used in sensors and energy storage.
Chemical Vapor Deposition technology is experiencing the most significant technological advancements. Precipitation methods provide the foundational volume for industrial-scale production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global nano metal oxide market exhibits a complex export-import balance, with advanced manufacturing hubs driving high-value material consumption while primary production often occurs in resource-rich regions. Specialized materials for electronics are disproportionately consumed in East Asia, creating distinct trade flows for high-purity oxides. Regulatory environments significantly influence market access and production costs across continents.
South Korea
Semiconductor manufacturers in South Korea drive substantial demand for high-purity cerium oxide and hafnium oxide to enable miniaturization and performance gains. The K-REACH legislation mandates stringent registration and risk assessment for nanomaterials, impacting local producers and importers. Gyeonggi Province, home to major semiconductor fabrication plants, represents a concentrated hub for advanced material procurement.
Taiwan
Taiwan's semiconductor industry requires advanced nano metal oxides for chemical vapor deposition processes and ultra-thin film applications. The country's Environmental Protection Administration (EPA) implements policies that influence the industrial handling and disposal of nanomaterials. The Hsinchu Science Park acts as a critical center for research, development, and high-volume manufacturing of advanced electronic components.
Germany
Germany's automotive and industrial sectors demand nano metal oxides for catalysts in pollution control systems and high-performance ceramics. The EU's REACH framework requires comprehensive safety data for nanomaterials, influencing product development and market entry. Bavaria, with its strong automotive and chemical industries, exemplifies a region focused on performance-based material specifications.
United States
US demand for nano metal oxides spans biomedical applications, energy storage, and specialized research in materials science. The US EPA's Toxic Substances Control Act (TSCA) governs the commercialization and use of nanomaterials, requiring extensive safety evaluations. Silicon Valley and Boston serve as key innovation centers, fostering advancements in semiconductor research and biomedical technologies.
Japan
Japanese environmental mandates increase the use of nano-ceria in automotive catalysts, while its electronics industry seeks advanced materials for next-generation devices. METI provides guidance on nanomaterial safety and industrial application, supporting a collaborative development model. The Kansai region, a hub for advanced materials and electronics manufacturing, actively engages in co-developing custom nano-dispersions.
Global Nano Metal Oxide Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with a few large chemical conglomerates alongside numerous specialized material science firms. This structure supports both high-volume commodity production and niche, high-performance applications. Key strategic archetypes include large-scale chemical producers, custom nanomaterial suppliers, and engineered particle specialists. Companies primarily engage in capacity expansion and strategic partnerships to maintain market relevance.
Specialists in custom nanomaterials include American Elements, which provides a wide range of tailor-made materials for research and niche industrial uses. Evonik Industries AG exemplifies a large chemical producer leveraging its expertise to provide high-purity precursors for advanced deposition processes. Nanophase Technologies Corporation occupies the engineered particle segment, focusing on commercial applications for its oxide products.
| Leading Market Players |
|---|
| Nanoshel LLC |
| Hongwu International Group Ltd. |
| Nanophase Technologies Corporation |
| Nanografi Nano Technology |
| Meliorum Technologies, Inc. |
| American Elements |
| Baikowski SAS |
| Evonik Industries AG |
| SkySpring Nanomaterials Inc. |
| Others |
Cost & Logistics Intelligence
Under-utilized sol-gel facilities in Europe influence supplier behavior and pricing posture for specialized nano metal oxides. This dynamic creates pressure on margins for high-purity materials while commodity oxides maintain stable pricing.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for nano metal oxides. Price differentiation stems from high-purity quality grades and extensive customization requirements for specialized applications. Pricing softness reflects high precursor costs and capital-intensive production methods, particularly for sol-gel derived materials. Semiconductor manufacturers exhibit low price sensitivity for critical inputs, while paint producers remain highly cost-conscious for volume-driven materials.
Supply Chain Analysis
Export control regimes, such as those governing dual-use technologies, limit the flow of advanced nano metal oxide precursors. Supply concentration for high-purity materials centers in South Korea, Japan, and parts of Europe, while commodity oxides often originate from China. The supply chain relies on consistent access to expensive organometallic precursors and specific rare earth elements. Regulatory restrictions, including REACH and K-REACH, represent a structural risk, influencing direct supply channels to OEM manufacturers and specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global nano metal oxide market presents an early-cycle expansion story driven by the increasing penetration of advanced deposition technologies in semiconductor manufacturing. This fundamental technological shift creates new opportunities across the value chain.
For Market Incumbents:
Build intellectual property moats through continuous R&D into novel material properties and advanced synthesis methods. Pursue upstream control over high-purity precursor production to mitigate supply chain risks and cost volatility from specialized material science firms. Expand production capacity in key electronics manufacturing hubs like South Korea to serve concentrated demand. Proactively address intensifying regulatory scrutiny over nanomaterial safety to maintain market access.
For New Entrants and Emerging Players:
Establish a beachhead in emerging high-value segments such as biomedical applications for iron oxide nanoparticles. Focus on co-developing custom nano-dispersions with end-users in energy storage for next-generation battery materials. The most penetrable segment remains niche biomedical uses, where performance outweighs initial cost. Leverage agile R&D to quickly adapt materials for specific functional requirements in these specialized areas.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting upwards across the specialized nano metal oxide sub-segment, indicating significant long-term growth potential. Target acquisition profiles include specialized material science firms possessing unique intellectual property in advanced synthesis methods like sol-gel or hydrothermal. These companies offer differentiation in a market prone to commoditization. The signal to watch is the accelerated adoption rates of Atomic Layer Deposition (ALD) for new chip nodes.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in East Asia | This initiative directly addresses concentrated demand from semiconductor manufacturers in South Korea and Taiwan. |
| Advanced Precursor R&D | New precursors enable atomic-level control in chemical vapor deposition for next-generation electronic components. |
| Biomedical Application Development | Iron oxide nanoparticles offer high-value opportunities as contrast agents in magnetic resonance imaging. |
| Lifecycle Safety Data Investment | Comprehensive safety data ensures compliance with EU REACH and US EPA regulations for new nanomaterials. |
| Custom Nano-dispersion Co-development | This fosters deep partnerships with aerospace and medical device sectors for performance-based materials. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary research anchors the qualitative findings of this study. Interviews engaged R&D directors, procurement leads, material scientists, and regulatory experts across key regions. Secondary data sources included industry association reports, patent databases, and government agency publications from the EU and US EPA. This approach ensured robust bottom-up and top-down triangulation.
The quantitative model calibrates historical trends with future projections across the analysis window to derive Compound Annual Growth Rates. Segmentation dimensions modeled include product type, application, end-user industry, technology, and regional regulatory environment. Forecast inputs incorporate semiconductor fabrication roadmaps and evolving environmental mandate schedules.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or raw material price volatility would shift the trajectory. Forecasts reflect current assumptions about technological development and regulatory policy. Material shifts in semiconductor manufacturing roadmaps would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Global Gold Nanorods Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
Carbon Nanotubes (Cnts) Market
Nanomaterials
1,8-Dinitroanthraquinone Market
Nanomaterials
Nano Fillers Market
Nanomaterials
Global Nano Silver Market
Nanomaterials
Global Nanoclay Reinforcement Market
Nanomaterials
United States Gold Nanoparticles Market
Nanomaterials
Global Cerium Oxide Nanoparticles Market
Nanomaterials
Nanocomposites Market
Nanomaterials
Copper Nano Powder Market
Nanomaterials
Nanocellulose Materials Market
Nanomaterials
Nanoscale Chemicals Market
Nanomaterials
Colloidal Selenium Nanoparticles Market
Nanomaterials
Nanotools Market
Nanomaterials
Global Graphene Based Supercapacitors Market