
 Inorganic Nano Porous Adsorbents Market | 2026-2036
Inorganic Nano Porous Adsorbents Market Size, Share, and Industry Trends Forecast 2026-2036
Inorganic Nano Porous Adsorbents Market Analytics
Pharmaceutical-grade purity specifications is rotating demand toward specialized nano porous materials with tighter particle size distribution and controlled pore architectures. BASF SE leverages its integrated catalyst and adsorbent platform to sustain supply security for European chemical manufacturers. Clariant AG anchors its position through deep specialization in custom zeolite formulations for healthcare and environmental applications.
Inorganic nano porous adsorbents are crystalline or amorphous solid materials featuring engineered pore diameters typically below 100 nanometers, synthesized through hydrothermal crystallization, sol-gel processing, or chemical vapor deposition to achieve high surface area and selective molecular sieving for separation, purification, and catalytic functions. Zeolites dominate volume demand across petrochemical catalysis and natural gas dehydration where thermal stability and acid site density determine performance, while metal-organic frameworks represent the fastest-expanding product class due to their exceptional tunability for carbon capture and pharmaceutical chiral separations despite current manufacturing scale constraints. Gas separation applications command premium pricing for pressure-swing adsorption systems in hydrogen purification and air separation units, whereas water treatment remains the most mature application segment with established municipal and industrial procurement channels.
EPA rules under the Clean Air Act and OSHA workplace exposure limits shape product certification requirements for adsorbents deployed in US industrial settings, while REACH registration and the EU F-Gas Regulation mandate disclosure of chemical composition and restrict fluorinated gas emissions in cooling and refrigeration applications where desiccant adsorbents play critical roles. China's GB standards and MEE environmental enforcement are elevating local content requirements for air and water treatment materials. Stakeholders must evaluate how divergent purity standards across EPA, REACH, and Chinese regulatory frameworks will affect cross-border product registration costs and manufacturing location decisions.
Market Dynamics
Petrochemical refiners in China and the US Gulf Coast are accelerating procurement of high-performance zeolites for catalytic cracking units, tightening purity specifications faster than incumbent manufacturing capacity can adapt.
Growth Catalysts
- EPA emissions rules:The Clean Air Act mandates stricter purity thresholds for industrial gas processing adsorbents, forcing upgrade cycles across US refineries and chemical plants.
- Carbon capture deployment:Metal-organic frameworks are capturing investment for post-combustion capture systems where tunable pore architectures outperform amine scrubbing on energy intensity.
- China's ethylene expansion:State-backed petrochemical complexes in Jiangsu and Zhejiang are scaling molecular sieve capacity, concentrating demand for specialized zeolite formulations.
Market Restraints
- Alumina and rare earth input volatility:Price swings in lanthanum and cerium oxides destabilize cost structures for high-acidity zeolite catalysts.
- Manufacturing scale constraints:Metal-organic framework production remains concentrated in academic and pilot-scale facilities, limiting commercial throughput.
- REACH registration friction:ECHA disclosure requirements for novel nano porous compositions extend product launch timelines by 18-24 months in European markets.
Strategic Opportunities
- India's pharmaceutical manufacturing:CDSCO certification pathways for chiral separation adsorbents remain underdeveloped, creating first-mover openings for specialized MOF suppliers.
- EU F-Gas Regulation phase-down:Desiccant adsorbents for fluorinated gas recovery systems face mandated demand expansion through 2030.
- Digital twin integration:Convergence of process simulation software with real-time adsorbent performance monitoring enables predictive replacement contracts.
Industry Challenges
- Hydrothermal synthesis expertise:Shortages of crystallization engineers with zeolite-specific process knowledge constrain capacity expansion timelines.
- Cross-border certification complexity:Divergent EPA, REACH, and GB standards force redundant testing protocols for multi-territory product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inorganic Nano Porous Adsorbents Market |
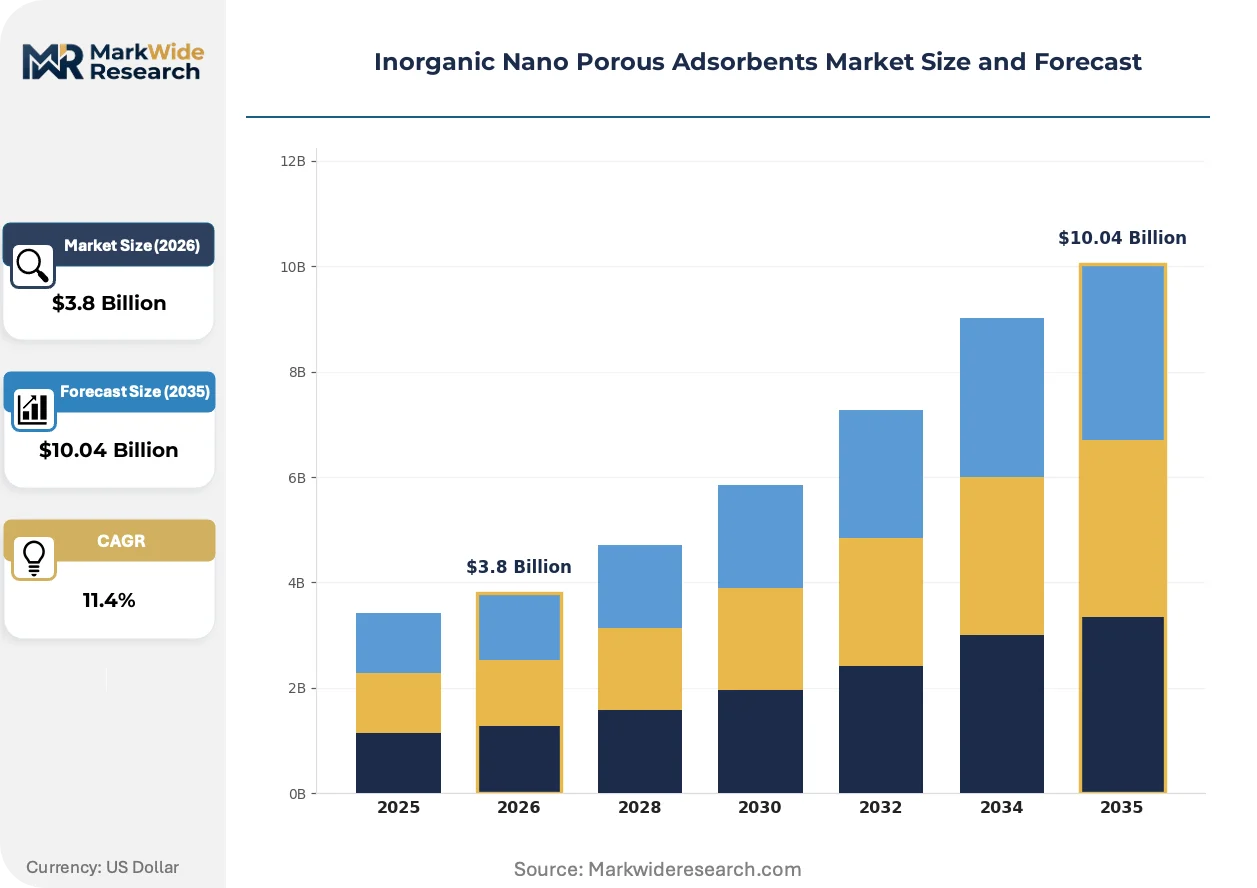
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zeolites, Activated Alumina, Silica, Metal-Organic Frameworks Application: Water Treatment, Gas Separation, Catalysis, Pharmaceuticals End User: Chemical Industry, Environmental Services, Healthcare, Research Institutions Distribution Channel: Direct Sales, Online Sales, Wholesalers, Distributors |
| Companies Covered | BASF SE, Arkema Group, Clariant AG, Zeochem AG, W.R. Grace & Co., Honeywell International, Evonik Industries AG, Cabot Corporation, Exxon Mobil Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inorganic Nano Porous Adsorbents Market Evolving Landscape
Manufacturing-scale metal-organic frameworks are disrupting established separation technologies through programmable pore geometries that legacy zeolites cannot replicate. Three concurrent developments are compressing competitive timelines.
Metal-organic framework synthesis is decomposing the cost-performance trade-off that has protected incumbent zeolite suppliers for decades. Hydrogen purification operators in Germany and Japan are piloting MOF-based pressure-swing adsorption units at commercial scale. This is decomposing the historical premium pricing structure for high-purity hydrogen separation, forcing zeolite manufacturers to defend position through integrated catalyst-adsorbent bundles rather than standalone product sales.
The EU F-Gas Regulation is tightening recovery rate mandates for fluorinated gases in commercial refrigeration and air conditioning systems. Industrial gas processors must now deploy specialized desiccant adsorbents capable of sub-ppm moisture control during refrigerant reclamation. European HVAC service networks are responding by certifying technicians on adsorbent replacement protocols, creating a secondary demand channel distinct from original equipment manufacturing.
Refinery procurement departments are consolidating adsorbent purchasing through multi-year framework agreements that bundle catalytic cracking catalysts with regeneration services. This compresses spot-market participation and favors suppliers with integrated technical service capabilities. The US Gulf Coast and Rotterdam-Antwerp refining clusters exhibit the most advanced contract structures, with performance guarantees tied to unit run-length outcomes rather than material specifications alone.
Inorganic Nano Porous Adsorbents Market Segmentation
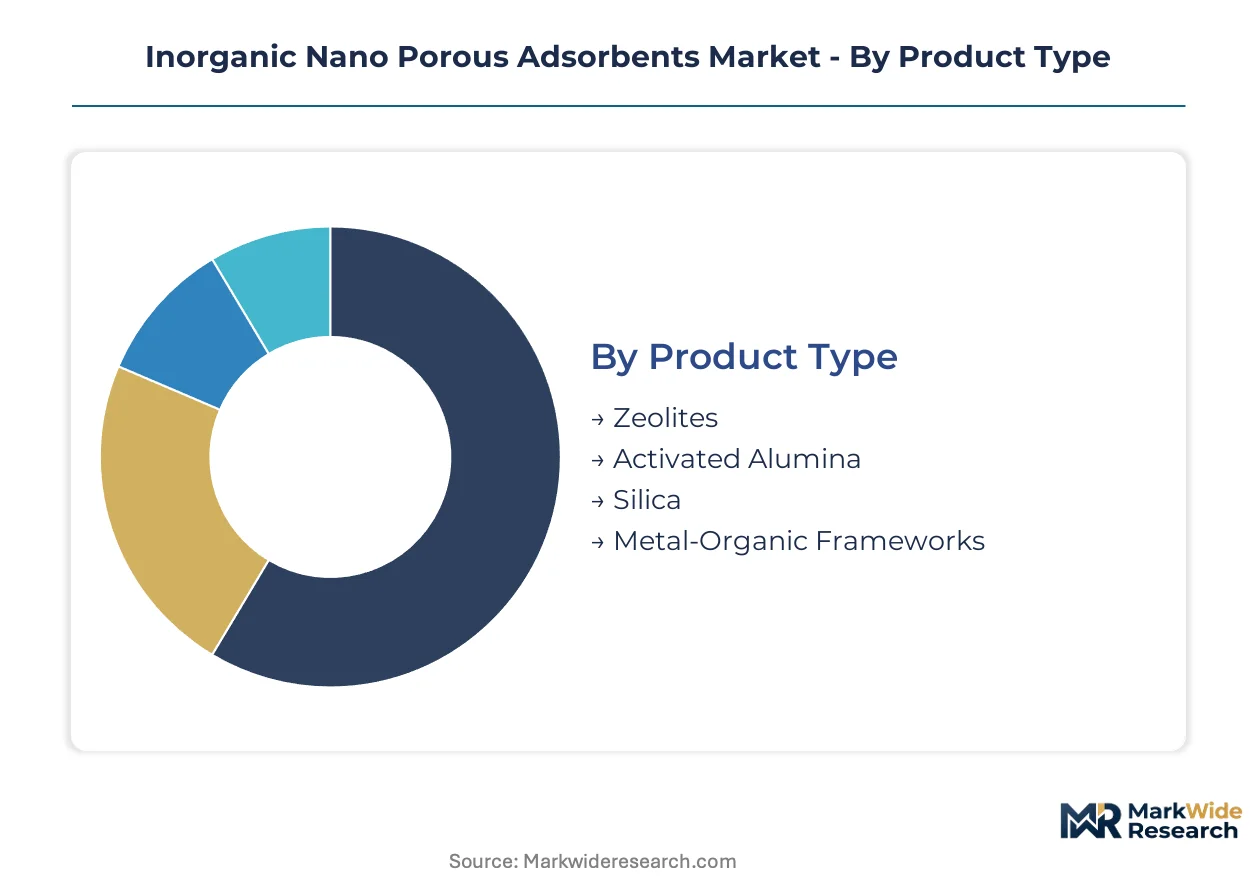
Segmentation in the Inorganic Nano Porous Adsorbents Market reveals how regulatory pressure, synthesis complexity, and end-use performance requirements fragment purchasing behavior across distinct technical tiers. Buyers in petrochemical and pharmaceutical sectors prioritize certification grade over unit cost, while environmental applications favor proven scalability.
Product Type:
EPA emissions thresholds under the Clean Air Act and EU F-Gas Regulation purity mandates are forcing divergence between commodity desiccants and specialty materials requiring advanced synthesis control.
- Zeolites:Crystalline aluminosilicates with tunable pore diameters between 0.3-2 nanometers synthesized via hydrothermal crystallization. Petrochemical refiners in China and the US Gulf Coast are consolidating procurement through multi-year framework agreements that bundle catalytic cracking catalysts with regeneration services.
- Metal-Organic Frameworks:Coordination polymers with exceptional surface area exceeding 7,000 square meters per gram and programmable pore geometries. Hydrogen purification operators in Germany and Japan are piloting MOF-based pressure-swing adsorption units at commercial scale, though manufacturing remains concentrated in academic and pilot-scale facilities.
- Activated Alumina:Amorphous aluminum oxide with mesoporous structure used primarily for moisture removal in compressed air and natural gas systems.
- Silica:Porous silicon dioxide materials employed in chromatography and drying applications where chemical inertness is paramount.
Established volume favors Zeolites; emerging adoption favors Metal-Organic Frameworks.
Application:
Cost stratification separates mature municipal procurement from premium industrial systems where performance guarantees determine contract value.
- Gas Separation:Pressure-swing and temperature-swing adsorption systems for hydrogen purification, air separation, and carbon capture. Refinery procurement departments in Rotterdam-Antwerp and Singapore clusters now demand performance guarantees tied to unit run-length outcomes rather than material specifications alone.
- Water Treatment:Municipal and industrial decontamination systems leveraging established zeolite and activated alumina supply chains. Procurement channels remain the most mature with standardized tender processes across US, European, and Chinese utilities.
- Catalysis:Fluid catalytic cracking and hydrocracking applications in petroleum refining where thermal stability and acid site density determine performance.
- Pharmaceuticals:Chiral separation and active pharmaceutical ingredient purification requiring pharmaceutical-grade purity specifications with tighter particle size distribution.
Water Treatment commands procurement volume; Gas Separation commands price premiums.
End User:
Customer technical sophistication determines whether purchases flow through specification-driven engineering contracts or commodity spot markets.
- Chemical Industry:Petrochemical manufacturers and specialty chemical producers requiring integrated catalyst-adsorbent bundles. State-backed complexes in Jiangsu and Zhejiang provinces are scaling molecular sieve capacity for ethylene production.
- Healthcare:Pharmaceutical manufacturers and medical gas suppliers with stringent purity requirements. CDSCO certification pathways in India for chiral separation adsorbents remain underdeveloped, creating first-mover openings.
- Environmental Services:Air and water treatment contractors serving municipal and industrial clients under tightening MEE enforcement in China and EPA rules in the US.
- Research Institutions:Academic and government laboratories developing next-generation materials with limited commercial scale requirements.
Chemical Industry anchors procurement scale; Healthcare drives specification intensity.
Distribution Channel:
Supply chain configuration separates integrated technical service providers from transactional material suppliers.
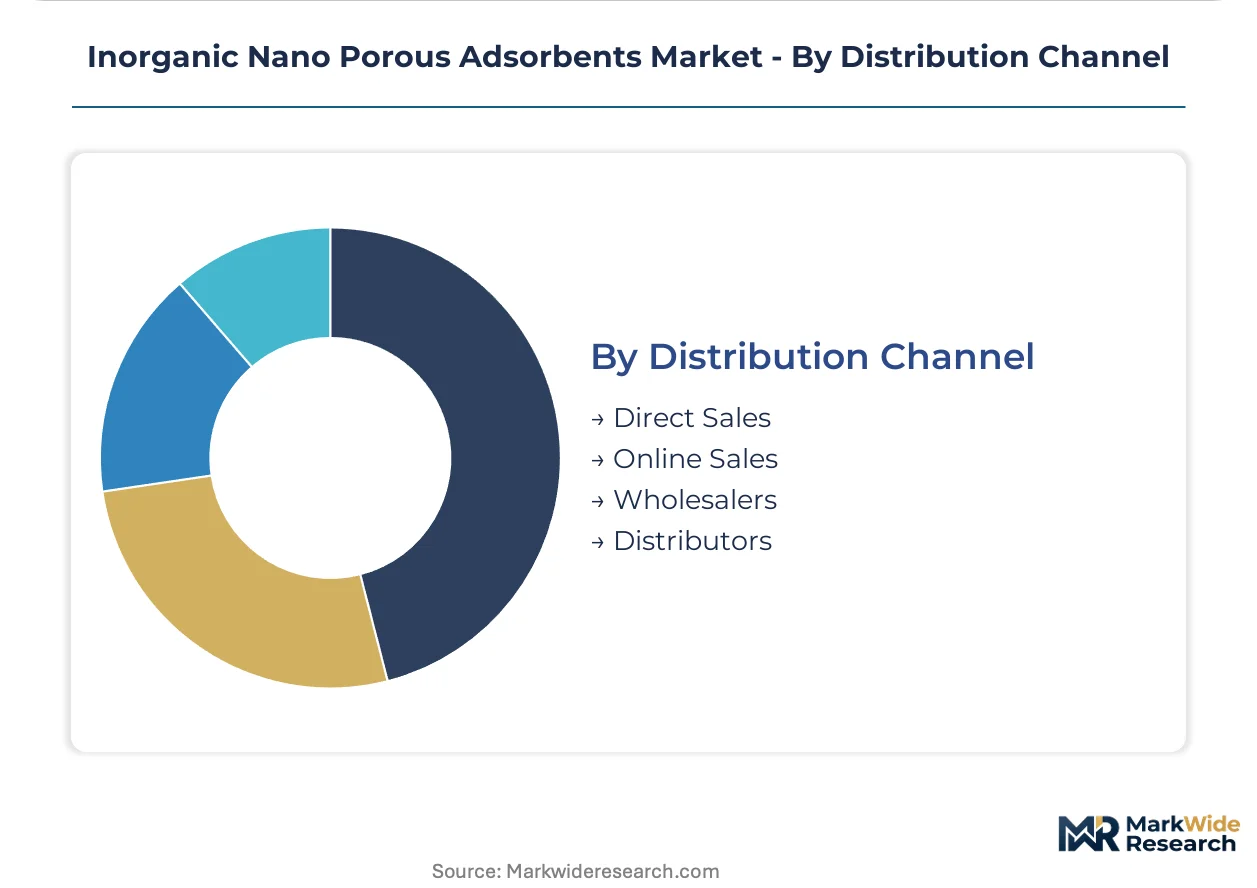
- Direct Sales:Manufacturer-to-end-user relationships with embedded technical service and performance guarantees. BASF SE and Clariant AG leverage integrated platforms to sustain supply security for European chemical manufacturers.
- Distributors:Regional stocking networks serving smaller environmental services contractors and maintenance-repair-operations procurement.
- Wholesalers:Volume aggregators for standardized activated alumina and silica products with limited technical differentiation.
- Online Sales:E-commerce platforms for research-grade materials and small-batch specialty orders from academic institutions.
Direct Sales concentrates value capture; Distributors extend geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports specialized zeolite formulations to petrochemical refiners across Germany and the US Gulf Coast, consolidating molecular sieve supply chains for ethylene production. European and North American buyers prioritize EPA and REACH-certified materials, while Asian producers scale hydrothermal synthesis capacity.
United States
Petrochemical refiners along the US Gulf Coast are accelerating procurement of high-performance zeolites for fluid catalytic cracking units. EPA rules under the Clean Air Act mandate stricter purity thresholds, forcing upgrade cycles across Texas and Louisiana chemical plants. Houston-area refining clusters now demand performance guarantees tied to unit run-length outcomes.
China
State-backed petrochemical complexes in Jiangsu and Zhejiang provinces are scaling molecular sieve capacity for ethylene production. MEE environmental enforcement and GB standards are elevating local content requirements for air and water treatment materials. Shanghai and Ningbo industrial zones concentrate domestic zeolite manufacturing for both captive use and export.
Germany
Hydrogen purification operators are piloting metal-organic framework-based pressure-swing adsorption units at commercial scale. The EU F-Gas Regulation tightens recovery rate mandates for fluorinated gases in industrial refrigeration systems. Ruhr industrial region and Bavarian chemical parks anchor demand for specialty desiccant adsorbents with sub-ppm moisture control.
India
Pharmaceutical manufacturers are expanding chiral separation capacity for active pharmaceutical ingredient purification. CDSCO certification pathways for specialized nano porous adsorbents remain underdeveloped, creating regulatory complexity for importers. Maharashtra and Gujarat pharmaceutical clusters drive specification-intensive procurement for healthcare-grade materials.
Japan
Industrial gas processors are deploying advanced pressure-swing adsorption systems for hydrogen purification and carbon capture applications. METI industrial policy supports domestic manufacturing of high-purity molecular sieves for semiconductor and chemical sectors. Osaka-Kobe and Chubu-Nagoya industrial corridors concentrate demand for thermal-stable zeolite catalysts.
Inorganic Nano Porous Adsorbents Market Competitive Landscape
Listed leaders compete with private specialists across integrated catalyst-adsorbent platforms and custom formulation capabilities. The vendor base stratifies into three tiers: multinational chemical conglomerates with full synthesis-to-service pipelines, mid-cap zeolite specialists with regional technical service networks, and academic spin-offs commercializing metal-organic frameworks. Dominant competitive moves include backward integration into rare earth oxide supply chains and multi-year framework agreements bundling catalysts with regeneration services.
Within the multinational tier, BASF SE and Clariant AG exemplify integrated platform strategies, while Honeywell International occupies a position bridging industrial automation with adsorbent system engineering. These three entities anchor the premium segment through embedded technical service capabilities and performance-based contracting structures that compress spot-market participation for standalone material sales.
| Leading Market Players |
|---|
| BASF SE |
| Arkema Group |
| Clariant AG |
| Zeochem AG |
| W.R. Grace & Co. |
| Honeywell International |
| Evonik Industries AG |
| Cabot Corporation |
| Exxon Mobil Corporation |
| Others |
Value Network & Pricing Analysis
Multi-year framework agreements bundling catalytic cracking catalysts with regeneration services lock in supply access for US Gulf Coast and Rotterdam-Antwerp refiners while anchoring price visibility against alumina and rare earth oxide volatility. These contracts compress spot-market participation and transfer performance risk to suppliers through unit run-length guarantees rather than standalone material specifications.
Pricing Analysis
Next-generation metal-organic framework pricing commands substantial premiums over incumbent zeolite benchmarks due to manufacturing scale constraints and pilot-scale production concentration. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and commodity desiccant tiers reflects certification intensity under EPA and REACH purity mandates. Cost compression in standard zeolite formulations is intensifying as Chinese state-backed complexes expand ethylene production capacity. Petrochemical refiners exhibit lowest price sensitivity due to performance-guarantee contracting, while municipal water treatment utilities drive procurement volume at economy tiers.
Supply Chain Analysis
Strategic stockpiling of lanthanum and cerium oxides dominates inventory strategy among European and North American zeolite manufacturers seeking insulation from rare earth price swings. Manufacturing concentrates in China, Germany, and the United States, with hydrothermal synthesis expertise constraining capacity expansion timelines. Supply chains draw from bauxite-derived alumina, synthetic zeolite precursors, and metal-organic framework ligand chemicals. Single-source vulnerability in rare earth oxide supply from Chinese processors creates structural risk. Distribution runs through integrated technical service providers for premium tiers and regional distributors for standardized activated alumina products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through refinery procurement consolidation in the US Gulf Coast and Rotterdam-Antwerp clusters, where multi-year framework agreements now bundle catalysts with regeneration services and compress spot-market leverage for standalone material suppliers.
For Market Incumbents: Consolidate technical service capabilities around integrated catalyst-adsorbent platforms to defend against metal-organic framework displacement in hydrogen purification applications. Prioritize backward integration into rare earth oxide supply chains to stabilize cost structures for high-acidity zeolite catalysts. Expand hydrothermal synthesis capacity in Jiangsu and Zhejiang provinces to capture China's ethylene production scaling. For New Entrants and Emerging Players: Predictive replacement contracting using digital twin integration represents a service-layer gap where incumbents under-serve mid-sized environmental services contractors. Target India's pharmaceutical manufacturing clusters where CDSCO certification pathways for chiral separation adsorbents remain underdeveloped. Pursue white-label technical service partnerships with European HVAC service networks facing EU F-Gas Regulation desiccant replacement mandates. For Investors and Strategic Acquirers: Capital is best deployed toward academic spin-offs commercializing metal-organic frameworks with demonstrated pilot-scale hydrogen purification performance. Long-term viability over the next decade hinges on manufacturing scale breakthroughs that decompose current cost-performance trade-offs against zeolite incumbents. Watch for inflection when MOF-based pressure-swing adsorption units achieve commercial throughput in Germany or Japan.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Supply | Captive lanthanum and cerium oxide sourcing stabilizes high-acidity zeolite cost structures against Chinese export volatility. |
| Multi-Year Framework Agreement Expansion | Performance-guaranteed contracts bundling catalysts with regeneration services compress spot-market participation in Rotterdam-Antwerp clusters. |
| Pharmaceutical-Grade Certification Investment | REACH and FDA tier compliance unlocks chiral separation premiums in active pharmaceutical ingredient purification. |
| Digital Twin Integration Partnership | Real-time adsorbent performance monitoring enables predictive replacement contracts with mid-sized environmental contractors. |
| MOF Manufacturing Scale-Up | Pilot-to-commercial throughput expansion decomposes cost barriers against incumbent zeolites in hydrogen purification. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with petrochemical procurement directors, zeolite plant managers, pharmaceutical regulatory affairs leads, and environmental services contractors. Secondary validation drew from EPA Clean Air Act filings, ECHA REACH registration databases, Chinese customs trade data, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up capacity modeling triangulated against top-down demand segmentation across product type, application, and end-user categories.
Across the analysis window, volume and value outputs reflect segmentation by synthesis complexity tier, end-use certification grade, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, capacity expansion announcements, and purity standard escalation trajectories. Forecast inputs incorporated ethylene production scaling in Chinese state-backed complexes, EU F-Gas Regulation phase-down mandates, and metal-organic framework pilot-scale commercialization timelines.
Forecasts assume regulatory continuity in EPA, REACH, and Chinese GB standards regimes; material policy shifts would require re-modeling around accelerated emissions thresholds or novel nano porous composition disclosure requirements. Revision becomes warranted when metal-organic framework manufacturing throughput crosses commercial viability thresholds or rare earth oxide supply disruptions exceed historical volatility bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Global Carbon Nanomaterials Market
Nanomaterials
United States Gold Nanoparticles Market
Nanomaterials
Global Nanoclay Market
Nanomaterials
Metal Nanoparticles Market
Nanomaterials
Nanoscale Chemicals and Materials Market
Nanomaterials
Nano Zinc Oxide Market
Nanomaterials
Nanotechnology Market
Nanomaterials
Nanocellulose Materials Market
Nanomaterials
Nanoparticle Titanium Dioxide (Tio2) Market
Nanomaterials
Graphene Aerogel Market
Nanomaterials
Nanotools Market
Nanomaterials
Nano Composite Zirconia Market
Nanomaterials
Nanocomposites Market
Nanomaterials
Platinum Nanoparticles Market
Nanomaterials
Nanotubes Market
Nanomaterials
Global Gold Nanorods Market