
 Silver Nanoparticles Market | 2026-2036
Silver Nanoparticles Market Size, Share, and Industry Trends Forecast 2026-2036
Silver Nanoparticles Market Analysis
REACH is realigning the cost-of-entry calculus for European silver nanoparticle suppliers through tightened substance registration and nanomaterial disclosure mandates. NovaCentrix leverages its pulse-thermal processing expertise to sustain North American electronics market penetration. Tanaka Holdings anchors Asian precious metals supply chains through captive refining and controlled particle-size distribution. Nanoshel LLC differentiates via rare-earth doping capabilities that extend functional performance beyond standard antimicrobial grades.
Silver nanoparticles are engineered metallic structures typically spanning 1-100 nanometers, synthesized through chemical reduction, electrochemical methods, or laser ablation to deliver surface plasmon resonance and potent antimicrobial activity. Colloidal solutions dominate current revenue flows due to established textile and coating integration protocols, while composite materials represent the fastest-expanding category as electronics manufacturers embed conductive nano-silver into flexible circuit substrates. Medical devices command premium margin pools driven by sterilization-critical applications, whereas food packaging remains price-sensitive and volume-constrained by regulatory hesitation.
The EPA governs antimicrobial claims in the United States through FIFRA registration requirements, while the EU MDR imposes clinical evidence thresholds for device-integrated nano-silver. BIS certification in India and China's GB standards for nano-products collectively fragment market access protocols across major consumption zones. Stakeholders must monitor evolving nano-specific toxicity databases and pre-register adaptively under shifting substance-control frameworks.
Market Dynamics
The EU MDR is compressing market access timelines for silver nanoparticle-integrated medical devices, forcing suppliers to front-load clinical evidence generation and biocompatibility testing budgets before product commercialization.
Growth Catalysts
- Antimicrobial coating mandates:FDA and EPA registration pathways for device-integrated nano-silver are streamlining under consolidated antimicrobial claims frameworks, accelerating hospital procurement cycles for sterilization-critical equipment.
- REACH nanomaterial disclosure:ECHA's tightened substance registration requirements are creating first-mover advantages for pre-registered European suppliers with existing toxicity dossiers.
- Flexible electronics embedding:Conductive nano-silver inkjet printing is absorbing capital allocation from printed circuit board manufacturers in Germany and the United States.
Market Restraints
- Silver price volatility:Precious metal input costs fluctuate with London Bullion Market Association spot pricing, compressing margin predictability for colloidal solution producers.
- Toxicity database gaps:Incomplete OECD nano-specific hazard classifications delay regulatory clearances in jurisdictions without harmonized standards.
- Substitute displacement:Copper and zinc oxide nanoparticles are capturing price-sensitive textile antimicrobial contracts where efficacy thresholds permit lower-performance alternatives.
Strategic Opportunities
- India BIS certification whitespace:Early compliance with Bureau of Indian Standards nano-product specifications opens access to pharmaceutical manufacturing corridors in Hyderabad and Mumbai.
- Food packaging regulatory tailwind:EFSA's evolving guidance on active and intelligent packaging creates pathway for shelf-life-extending silver nanoparticle films pending full authorization.
- Photovoltaic metallization convergence:Laser-ablated nano-silver pastes are merging with perovskite cell fabrication lines, creating dual-use supply contracts.
Industry Challenges
- Particle-size distribution control:Achieving sub-20-nanometer uniformity at scale requires electrochemical synthesis expertise that remains concentrated among specialized equipment operators.
- MDR clinical evidence timelines:Biocompatibility testing for Class III medical devices extends certification cycles beyond typical venture capital fund horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silver Nanoparticles Market |
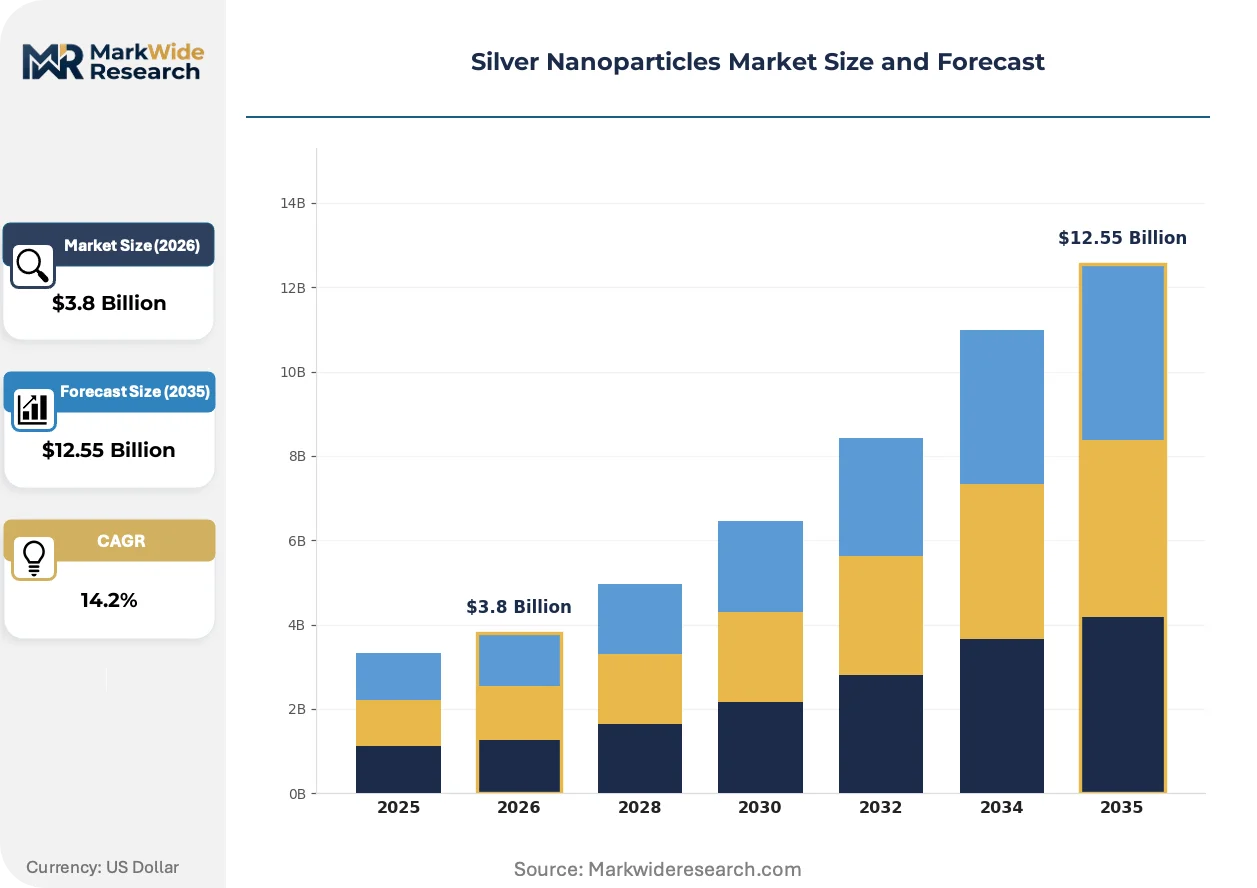
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous Solutions, Colloidal Solutions, Solid Forms, Composite Materials Application: Medical Devices, Textiles, Food Packaging, Electronics End User: Pharmaceuticals, Biotechnology, Electronics Manufacturers, Textile Industry Distribution Channel: Online Stores, Direct Sales, Distributors, Retail Outlets |
| Companies Covered | Tanaka Holdings Co., Ltd., NovaCentrix, NanoComposix (Fortis Life Sciences), Nanoshel LLC, Meliorum Technologies, Inc., American Elements, Ames Goldsmith Corporation, Advanced Nano Products Co., Ltd., Merck KGaA (Sigma-Aldrich), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silver Nanoparticles Market Emerging Trajectories
Green synthesis protocols are displacing traditional chemical reduction methods, with biological extract-based production gaining traction among sustainability-conscious European and North American buyers.
Laser ablation synthesis is absorbing research investment from electrochemical equipment manufacturers as the technology eliminates residual solvent contamination in pharmaceutical-grade outputs. German precision engineering clusters are piloting continuous-flow laser systems for gram-scale production. The method is absorbing market share from batch chemical reduction in applications where purity specifications exceed 99.9 percent.
REACH authorization lists are expanding nano-silver substance categories, compelling formulators to submit updated safety data sheets for existing product registrations. ECHA's 2024-2025 work program prioritizes nanomaterial environmental fate studies. Medical device coatings face the steepest compliance cost escalation as registrants must demonstrate no-observed-adverse-effect levels for systemic exposure scenarios.
Hospital procurement consortia are consolidating supplier qualification requirements around ISO 10993 biocompatibility certifications, displacing fragmented institutional purchasing protocols. Group Purchasing Organizations in the United States are mandating pre-qualified nano-silver coating vendors for catheter and wound dressing contracts. This concentration is most visible in the Northeastern hospital networks where supply chain rationalization programs have eliminated single-source dependencies.
Silver Nanoparticles Market Segmentation
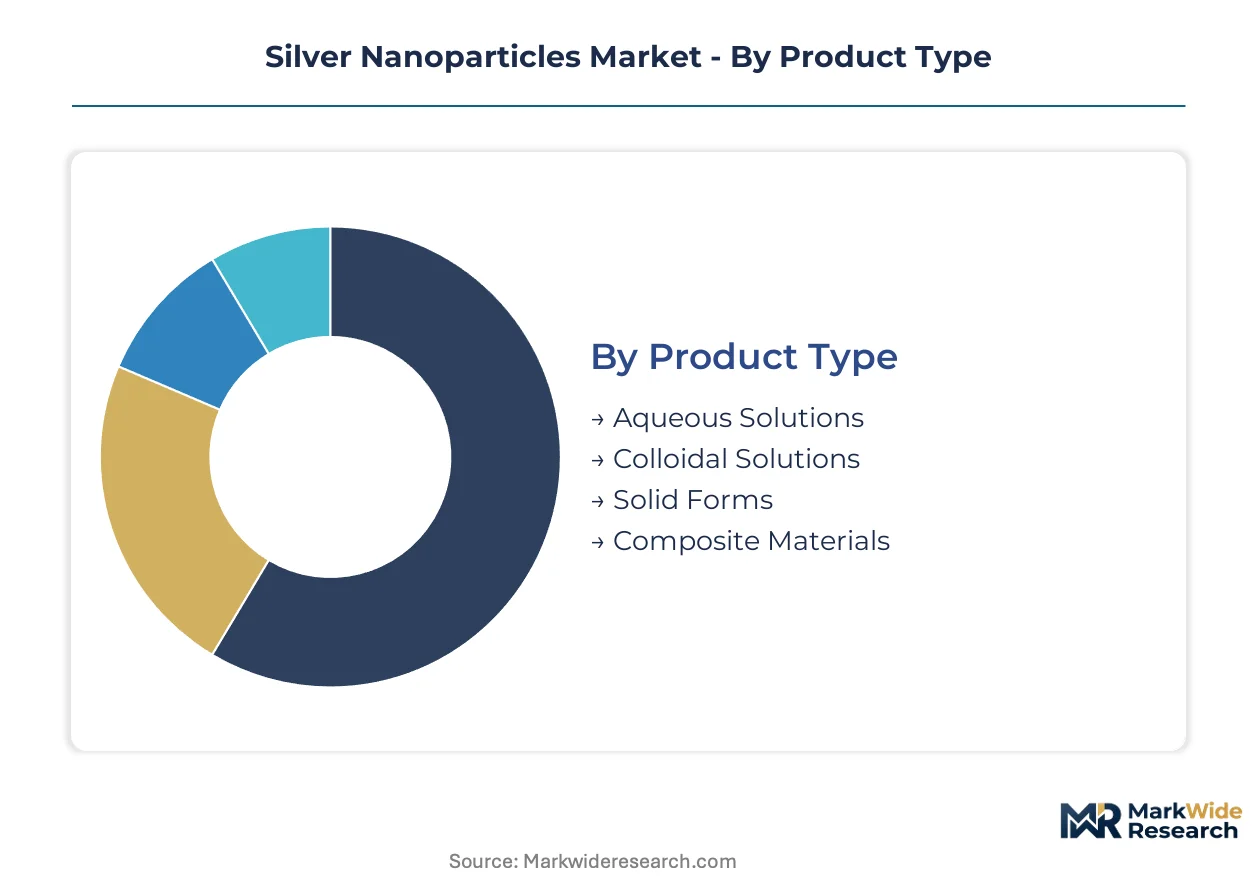
Silver nanoparticle suppliers navigate divergent technical specifications and regulatory thresholds across end-use verticals. Segmentation reveals where formulation complexity commands premium pricing versus where standardization drives volume. Each category exposes distinct upgrade cycles and replacement dynamics that reshape procurement patterns.
Product Type:
Upgrade cycles vary dramatically by physical form, with liquid formats requiring periodic reformulation and solid forms demanding capital-intensive synthesis retooling.
- Aqueous Solutions:Water-dispersed nanoparticles stabilized with surfactants or polymers enable direct integration into spray-applied coatings and wet-processing textile lines. Pharmaceutical manufacturers in Germany and the United States specify these for parenteral-grade applications where residual solvent limits are stringent.
- Colloidal Solutions:Suspensions in organic or mixed-phase carriers dominate current revenue flows through established textile and coating integration protocols. REACH-registered European suppliers leverage existing toxicity dossiers to defend positioning in medical device sterilization applications.
- Solid Forms:Powdered nanoparticles with controlled agglomeration states suit dry-blending operations in polymer masterbatch production.
- Composite Materials:Nano-silver embedded in polymer, ceramic, or metal matrices enables conductive pathways in flexible electronics substrates.
Volume placements concentrate in Colloidal Solutions; the faster expansion belongs to Composite Materials.
Application:
Cost-tier stratification separates sterilization-critical medical applications from price-sensitive packaging segments.
- Medical Devices:Catheters, wound dressings, and implantable hardware integrate nano-silver coatings to prevent biofilm formation. FDA registration pathways and EU MDR clinical evidence requirements compress supplier margins while extending certification timelines beyond typical venture capital horizons.
- Electronics:Conductive inks, flexible circuit substrates, and EMI shielding layers absorb capital allocation from printed circuit board manufacturers. German precision engineering clusters pilot continuous-flow laser synthesis for gram-scale production of pharmaceutical-grade outputs.
- Textiles:Antimicrobial finishing for healthcare uniforms and activewear faces displacement pressure from copper and zinc oxide alternatives.
- Food Packaging:Active shelf-life extension films remain constrained by EFSA authorization gaps and regulatory hesitation.
Margin concentration sits with Medical Devices; Electronics climbs the fastest as inkjet printing displaces traditional PCB fabrication.
End User:
Customer-type differentiation separates specification-heavy pharmaceutical buyers from volume-driven textile processors.
- Pharmaceuticals:Sterile manufacturing environments and parenteral drug delivery systems demand sub-20-nanometer particle uniformity with comprehensive biocompatibility documentation. ISO 10993 certification mandates from hospital procurement consortia in the United States filter supplier qualification.
- Electronics Manufacturers:Printed circuit board and flexible display producers prioritize conductivity specifications and sintering temperature compatibility over antimicrobial efficacy claims.
- Biotechnology:Cell culture contamination control and diagnostic assay development require low-endotoxin formulations with batch-to-batch consistency.
- Textile Industry:Finishing houses and fiber producers seek cost-optimized colloidal solutions for durable antimicrobial treatment.
Specification intensity peaks in Pharmaceuticals; Electronics Manufacturers expand procurement fastest as conductive ink adoption accelerates.
Distribution Channel:
Supply concentration patterns favor direct relationships for specification-critical accounts while fragmented retail serves commodity buyers.
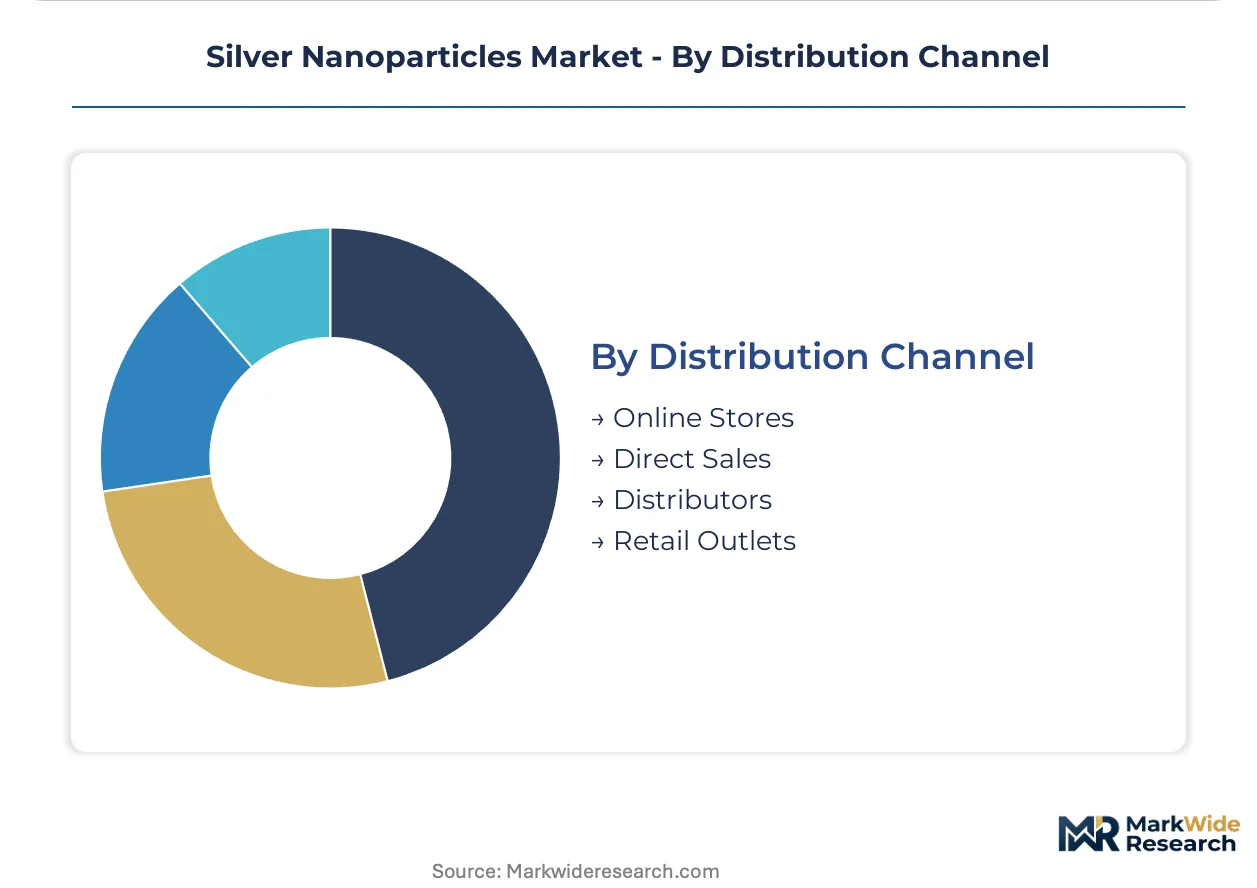
- Direct Sales:Technical field support and custom formulation services lock in pharmaceutical and medical device OEMs with multi-year supply agreements. ECHA pre-registration status and REACH-compliant safety data sheets become table stakes for European direct procurement.
- Distributors:Regional inventory positioning and just-in-time delivery serve mid-volume textile finishers and electronics job shops without internal formulation expertise.
- Online Stores:Catalog sales of standard colloidal concentrations target research institutions and pilot-scale manufacturers.
- Retail Outlets:Limited penetration in consumer-facing antimicrobial products with nano-silver claims.
Relationship value concentrates in Direct Sales; Distributors gain share fastest among mid-tier electronics and textile processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Hyderabad and Shenzhen concentrate pharmaceutical-grade nano-silver synthesis capacity through tax-advantaged precision manufacturing incentives.
United States
Hospital procurement consortia in the Northeastern corridor drive sterilization-critical device coating demand through consolidated vendor qualification programs. FDA antimicrobial claims registration under FIFRA streamlines pathway documentation for catheter and wound dressing integrators. Boston-Cambridge biotechnology clusters absorb parenteral-grade colloidal solutions for diagnostic assay development.
Germany
Precision engineering clusters in Bavaria pilot continuous-flow laser ablation systems for gram-scale pharmaceutical outputs. REACH nanomaterial disclosure mandates through ECHA create first-mover advantages for pre-registered suppliers with existing toxicity dossiers. Stuttgart's automotive electronics corridor embeds conductive nano-silver into flexible circuit substrates for next-generation sensor arrays.
China
GB standards for nano-products fragment market access protocols while Yangtze River Delta electronics manufacturers scale inkjet-printed conductive ink adoption. Dual carbon goals accelerate green synthesis protocol investment among sustainability-conscious exporters. Suzhou pharmaceutical corridors demand sub-20-nanometer particle uniformity for sterile manufacturing environments.
India
BIS certification whitespace in pharmaceutical manufacturing corridors opens procurement pathways for Hyderabad and Mumbai-based formulators. CDSCO clinical evidence requirements for device-integrated nano-silver compress certification timelines for domestic suppliers. Gujarat textile finishers seek cost-optimized colloidal solutions amid copper and zinc oxide displacement pressure.
Japan
METI funding for perovskite photovoltaic metallization converges with laser-ablated nano-silver paste development in Osaka-Kobe industrial zones. JIS standards for nano-product quality assurance filter supplier qualification for electronics manufacturers. Kanto region biotechnology firms prioritize low-endotoxin formulations with batch-to-batch consistency for cell culture applications.
Silver Nanoparticles Market Vendor Landscape
North American producers anchor one tier; Asian precious metals specialists hold captive refining advantages through controlled particle-size distribution. The vendor base splits between consolidated precious metals conglomerates with vertical supply chain control and fragmented electrochemical synthesis equipment operators. Three archetypes dominate: scale-driven refiners with captive silver sourcing, precision synthesis specialists with sub-20-nanometer uniformity expertise, and formulation integrators with REACH-registered toxicity dossiers. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as players defend positioning against substitute nanoparticle displacement.
Within the precious metals conglomerate tier, Tanaka Holdings exemplifies captive refining integration through its Tokyo-based corporate structure. NovaCentrix occupies a position among North American electrochemical synthesis specialists with pulse-thermal processing capabilities. Nanoshel LLC represents the rare-earth doping differentiation archetype, extending functional performance beyond standard antimicrobial grades through its Delaware-registered limited liability structure.
| Leading Market Players |
|---|
| Tanaka Holdings Co., Ltd. |
| NovaCentrix |
| NanoComposix (Fortis Life Sciences) |
| Nanoshel LLC |
| Meliorum Technologies, Inc. |
| American Elements |
| Ames Goldsmith Corporation |
| Advanced Nano Products Co., Ltd. |
| Merck KGaA (Sigma-Aldrich) |
| Others |
Supply Flow & Price Mechanics
Hospital procurement consortia in the United States are consolidating vendor qualification requirements around ISO 10993 biocompatibility certifications, forcing suppliers to absorb upfront testing costs and compressing margin structures for non-compliant producers while rewarding pre-certified incumbents with pricing power.
Pricing Analysis
Short lead-time premiums dominate pharmaceutical-grade nano-silver contracts, with German and United States buyers paying substantial markups for sub-20-nanometer uniformity delivered on compressed schedules. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered medical device grades from textile finishing colloids and research-use powders. Price differentiation hinges on certification tier and volume scale, with FDA-registered suppliers capturing margin premiums while textile processors face intensifying cost compression from copper and zinc oxide substitutes. Electronics manufacturers show lowest price sensitivity, prioritizing conductivity specifications over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from United States hospital Group Purchasing Organizations and German automotive electronics clusters require suppliers to maintain qualified backup production lines across at least two jurisdictions. Raw material supply concentrates in Japan, Germany, and the United States through Tanaka Holdings' captive refining, NovaCentrix's pulse-thermal processing, and specialized electrochemical equipment operators. Production rests on silver bullion feedstock, surfactant stabilizers, and laser ablation equipment subject to London Bullion Market Association price volatility. Single-source vulnerability persists in sub-20-nanometer synthesis expertise. Distribution runs through direct technical sales for pharmaceutical OEMs and regional distributors for mid-volume textile finishers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU MDR's clinical evidence thresholds function as a cost-of-compliance moat, elevating barrier-to-entry economics for silver nanoparticle-integrated medical devices and consolidating advantage around incumbents with pre-existing toxicity dossiers.
For Market Incumbents: Hedge against copper and zinc oxide displacement in textile antimicrobial contracts by deepening backward integration into captive silver refining and accelerating green synthesis protocol certification for sustainability-conscious European buyers. Prioritize capacity addition in Germany's precision engineering clusters to defend positioning against emerging Asian electrochemical specialists. For New Entrants and Emerging Players: Mid-tier electronics job shops in China's Yangtze River Delta represent an underserved buyer archetype seeking conductive ink alternatives without minimum order requirements from established suppliers. Penetrate through technical field support partnerships with regional distributors and flexible formulation services for pilot-scale flexible circuit substrate development. For Investors and Strategic Acquirers: The window for entry favors precision synthesis specialists with sub-20-nanometer uniformity expertise and existing ECHA pre-registration status. Long-term viability centers on consolidation plays as REACH authorization list expansion accelerates compliance cost divergence between registered and unregistered suppliers. Monitor EFSA's active packaging guidance evolution as inflection signal for food packaging segment authorization.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Toxicity Dossier Expansion | ECHA pre-registration status secures first-mover advantage in EU medical device supply chains. |
| Green Synthesis Protocol Certification | Biological extract-based production unlocks sustainability premiums from European and North American buyers. |
| Laser Ablation Capacity Buildout | Continuous-flow systems in German clusters eliminate residual solvent contamination for pharmaceutical-grade outputs. |
| Hospital GPO Partnership Development | ISO 10993 certification alignment with United States procurement consortia locks in multi-year catheter and wound dressing contracts. |
| Perovskite Photovoltaic Metallization Licensing | METI-funded convergence in Osaka-Kobe industrial zones creates dual-use supply contract opportunities. |
Methodological Framework
Document review covered FDA 510(k) filings, ECHA substance registration databases, and hospital procurement contract disclosures, complemented by interviews with electrochemical synthesis equipment operators, pharmaceutical manufacturing executives, and biomedical engineers at sterilization-critical device OEMs. Secondary validation drew from SEC 10-K filings of precious metals conglomerates, customs trade data for nano-silver imports, and OECD nano-specific hazard classification updates. Bottom-up demand modeling across end-use verticals was triangulated against top-down precious metals consumption estimates.
Historical shipment data was cross-referenced against expert panel input from German precision engineering clusters and United States biotechnology corridors. The analytical framework segmented by product type, application, end user, and distribution channel across the analysis window, with CAGRs derived from regression analysis of adoption curve inflection points in medical device sterilization and flexible electronics embedding. Forecast inputs included REACH authorization timeline scenarios and silver spot price volatility bands.
Revisions become necessary when EFSA grants full food packaging authorization, ECHA expands nano-silver substance categories, or perovskite photovoltaic metallization achieves commercial scale. Forecasts reflect assumptions around regulatory clearance timelines and substitute displacement thresholds. A model refresh is warranted upon material change in EU MDR clinical evidence requirements or hospital procurement consortium vendor qualification protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Copper Nano Powder Market
Nanomaterials
Global Graphene Based Supercapacitors Market
Nanomaterials
Nanocomposites Market
Nanomaterials
Aluminium Oxide Nanoparticles Market
Nanomaterials
Lipid Nanoparticles Market
Nanomaterials
1,8-Dinitroanthraquinone Market
Nanomaterials
Inorganic Nano Porous Adsorbents Market
Nanomaterials
Graphene Aerogel Market
Nanomaterials
Global Gold Nanorods Market
Nanomaterials
United States Gold Nanoparticles Market
Nanomaterials
Nanomaterials for Printing Market
Nanomaterials
Global Gold Nanoparticles Market
Nanomaterials
Carbon Nanotubes (Cnts) Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Nanotechnology Market
Nanomaterials
Nano Copper Oxide Market