
 Melamine Based Adhesives Market | 2026-2036
Melamine Based Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Melamine Based Adhesives Market Intelligence
The development of low-formaldehyde and no-added formaldehyde (NAF) resin systems is reconfiguring product formulations and manufacturing processes for wood-based panels. BASF leverages its extensive chemical research capabilities to develop advanced melamine-urea-formaldehyde (MUF) resins with reduced emissions. Hexion sustains its market position through a broad portfolio of thermosetting resins and a global manufacturing footprint serving the construction and furniture industries.
Melamine-based adhesives are thermosetting polymers created through the condensation reaction of melamine and formaldehyde. These resins are prized for their exceptional durability, high moisture resistance, and thermal stability once cured, making them suitable for demanding applications. The woodworking application segment, particularly for laminates and particleboard, constitutes the largest area of consumption. Within product types, pure melamine-formaldehyde resins command a premium for high-performance uses, while melamine-urea-formaldehyde (MUF) resins offer a cost-effective alternative.
Formaldehyde emission standards set by bodies like the United States EPA under TSCA Title VI and the European Chemicals Agency (ECHA) under REACH directly influence product chemistry. Compliance with these regulations is a prerequisite for market access in North America and Europe, driving innovation in scavenger technologies. Future competitive advantage will hinge on developing cost-effective, high-performance adhesive systems that meet or exceed evolving global environmental and health standards.
Market Dynamics
The central force shaping the melamine based adhesives market is the global regulatory clampdown on formaldehyde emissions. Mandates from bodies like the US EPA and ECHA are compelling a fundamental reformulation of resin chemistry, prioritizing occupant health and environmental safety.
Growth Catalysts
- Furniture and Panel Demand:Sustained construction and renovation activity, particularly in Asian wood panel manufacturing hubs like China and Vietnam, drives volume consumption for particleboard, MDF, and laminate production.
- Superior Performance Properties:The inherent moisture resistance, thermal stability, and durability of cured melamine resins make them the preferred choice for high-end furniture, flooring, and exterior-grade wood composites.
- Stringent Emission Standards:Regulations such as the EPA's TSCA Title VI and Europe's E1 classification create a strong incentive for manufacturers to adopt premium, low-emitting melamine-based adhesive systems to ensure market access.
Market Restraints
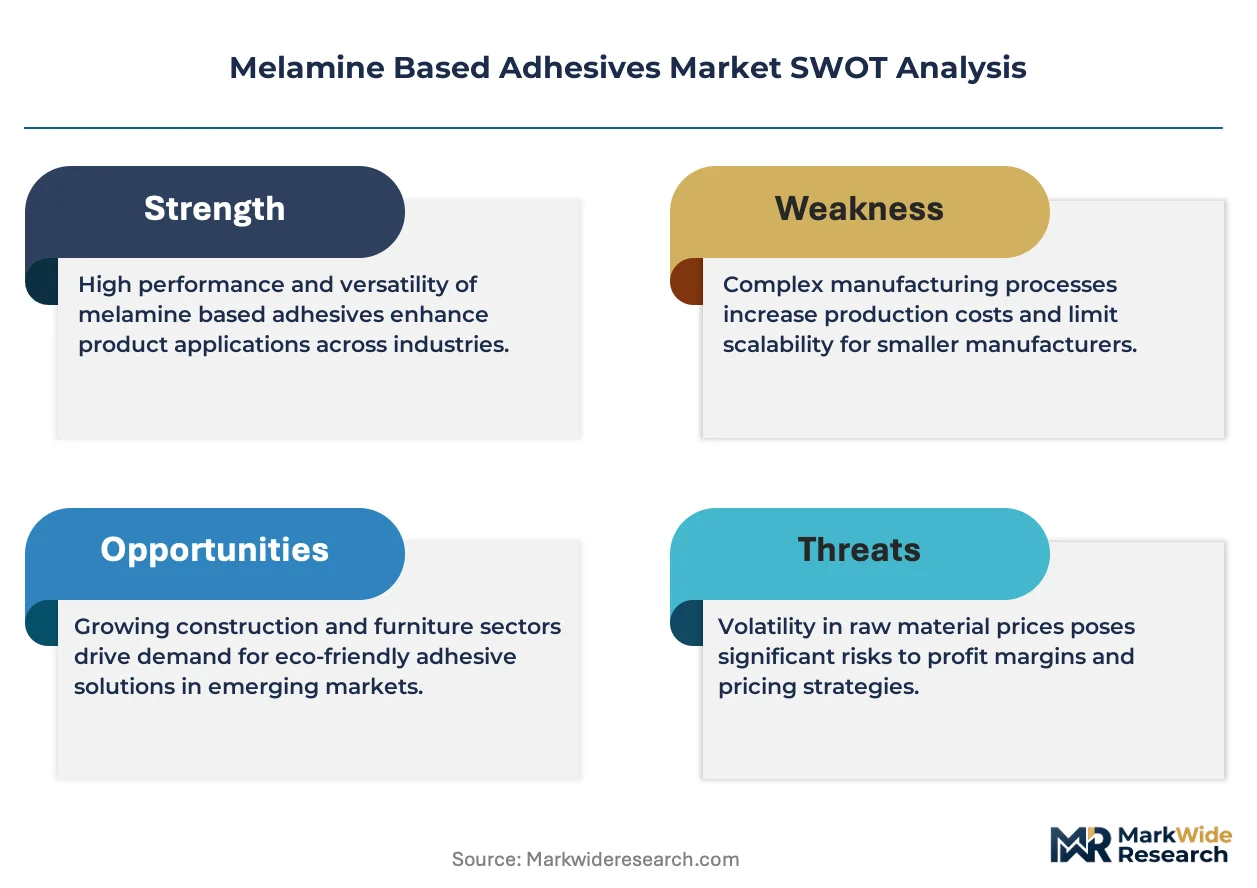
- Raw Material Price Volatility:The costs of key precursors, namely melamine and formaldehyde, are linked to volatile petrochemical and natural gas markets, creating margin pressure for adhesive producers.
- Competition from Substitutes:In certain non-structural or less demanding applications, alternative adhesive systems like polyvinyl acetate (PVA) and isocyanate-based binders present a cost-competitive threat.
- High Curing Requirements:The thermosetting nature of melamine resins necessitates high-temperature and high-pressure press cycles, which increases energy consumption and limits their use with heat-sensitive substrates.
Strategic Opportunities
- Bio-Based Formulations:Developing partially or fully bio-based melamine adhesives using renewable feedstocks offers a path to reduce carbon footprint and appeal to environmentally conscious market segments.
- Expansion in Southeast Asia:Growing furniture production and construction sectors in countries like Indonesia and Thailand represent underpenetrated markets for advanced, low-emission adhesive solutions.
- Development of NAF Systems:Innovating no-added formaldehyde (NAF) binders that utilize melamine to enhance performance provides a significant opportunity to capture the premium, health-focused building materials market.
Industry Challenges
- Complex Global Compliance:Adhering to a patchwork of regional formaldehyde standards, from CARB P2 in California to F**** (JIS) in Japan, requires sophisticated testing, certification, and supply chain management.
- Capital-Intensive Production Upgrades:Transitioning manufacturing plants to produce next-generation, ultra-low emitting formaldehyde (ULEF) or NAF resins demands significant capital expenditure on new reactors and process controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Melamine Based Adhesives Market |
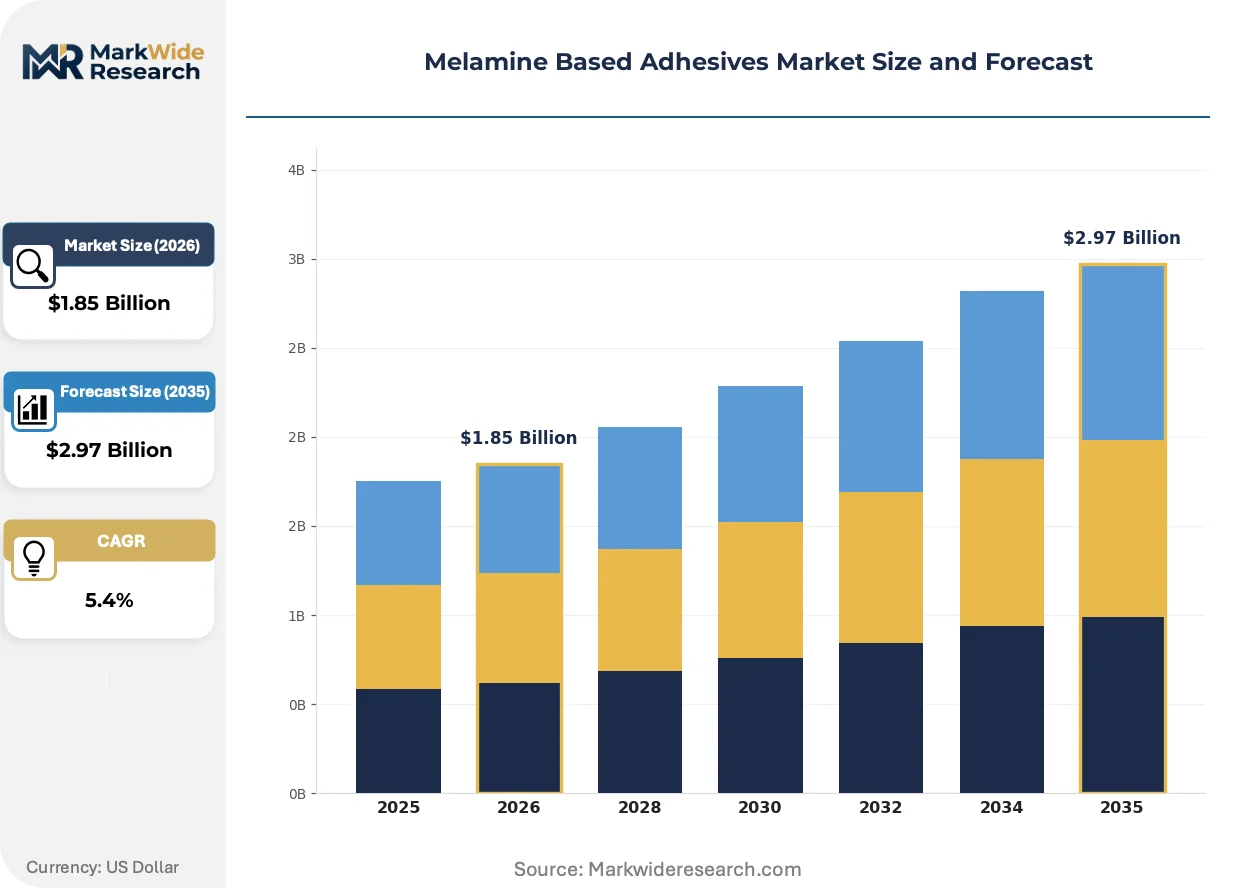
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea-formaldehyde Resins, Phenol-formaldehyde Resins, Melamine-formaldehyde Resins, Others Application: Woodworking, Automotive, Construction, Packaging End User: Furniture Manufacturers, Construction Companies, Automotive OEMs, Consumer Goods Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Hexion, Georgia-Pacific Chemicals, OCI Nitrogen, BASF, Prefere Resins Holding, Innospec, Georgia-Pacific, AkzoNobel, Dow Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Melamine Based Adhesives Market Strategic Shifts & Innovations
The market's evolution is defined by a dual pursuit of environmental compliance and enhanced material performance. This pressure spurs innovation in both resin chemistry and the manufacturing processes that rely on these critical bonding agents.
Advanced formulation software and chemical modeling platforms are a key technological development. Resin manufacturers are adopting these tools at an accelerated pace within their research and development departments. This software-driven approach is virtualizing the traditionally slow, iterative process of physical lab testing, enabling faster creation of resins that meet specific emission and performance targets.
European regulatory frameworks, particularly the reclassification of formaldehyde as a more hazardous substance under ECHA's REACH regulation, are having a direct impact. The industrial consequence is an accelerated phase-out of higher-emission adhesive systems across the continent. Wood panel producers supplying the European furniture and construction sectors are most affected, driving their rapid shift toward scavenger-enhanced MUF and NAF adhesive systems.
A distinct behavioral shift is visible in the procurement of finished goods like cabinetry and flooring, where buyers increasingly demand products with documented eco-certifications. This trend disrupts purchasing decisions based purely on cost, elevating validated environmental health and safety as a key criterion. This demand-side pull is most pronounced in North American and European consumer markets, forcing transparency and compliance throughout the value chain.
Melamine Based Adhesives Market Segmentation
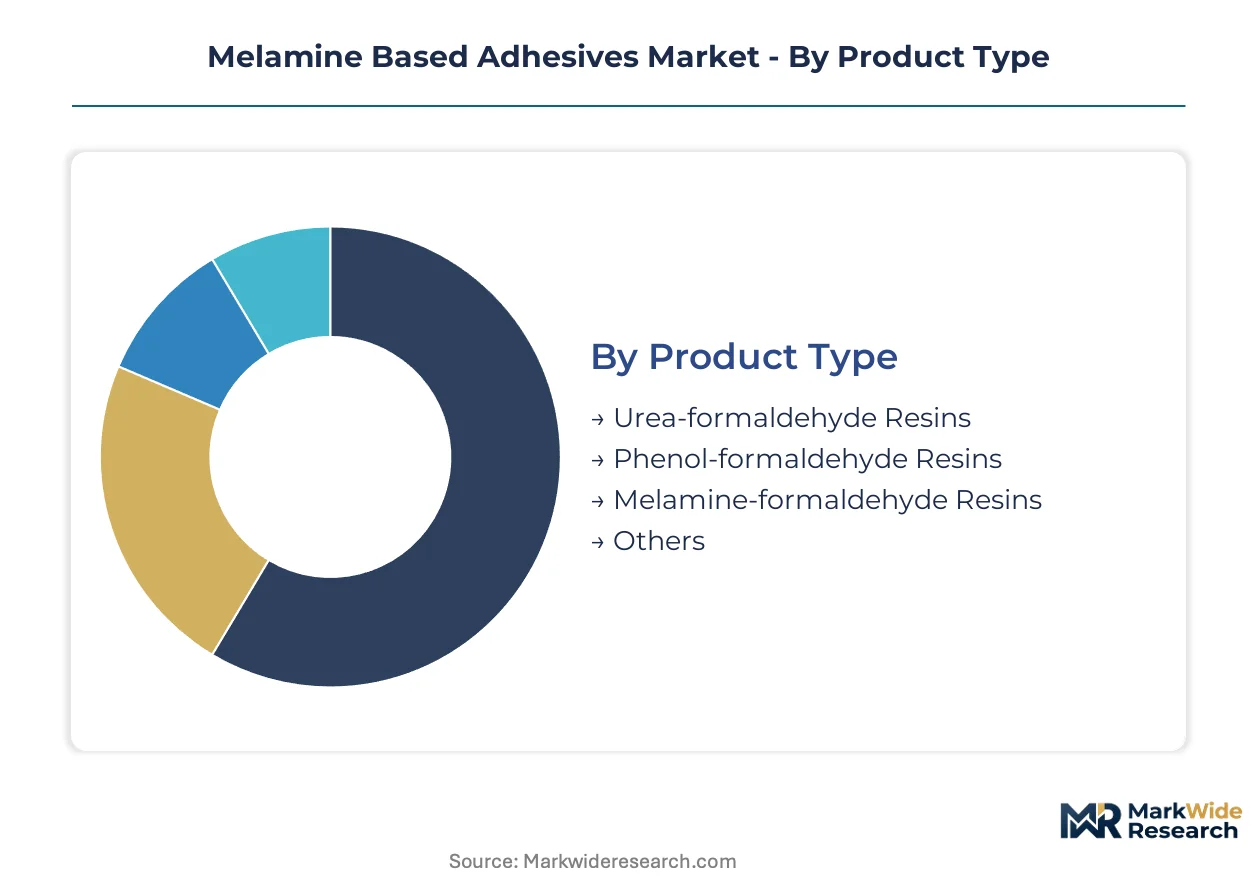
The melamine based adhesives market is meticulously segmented to reflect the diverse applications and product formulations driving its expansion. Understanding these distinct categories provides clarity on demand drivers, technological preferences, and procurement dynamics across the value chain.
Product Type:
The chemical composition of melamine-based adhesives defines distinct product types, influencing performance and cost tiers.
- Melamine-formaldehyde Resins:These thermosetting polymers are formed by the condensation of melamine and formaldehyde, offering exceptional durability, high moisture resistance, and thermal stability once cured. Demand concentrates in high-performance applications like premium laminates and exterior-grade wood products, particularly in European and North American markets.
- Urea-formaldehyde Resins:These are cost-effective thermosetting adhesives widely used in wood-based panel production due to their strong bonding properties and rapid curing. Consumption remains high in Asian manufacturing hubs like China and Vietnam for particleboard and MDF, driven by furniture and construction sectors.
- Phenol-formaldehyde Resins:These resins provide excellent water resistance and durability, primarily utilized in exterior-grade plywood and engineered wood products.
- Others:This category includes modified melamine resins, specialty blends, and niche formulations designed for specific performance requirements or regulatory compliance.
Urea-formaldehyde Resins hold significant installed capacity. Melamine-formaldehyde Resins are rotating up the share rankings.
Application:
End-use applications delineate demand patterns for melamine-based adhesives, shaping innovation priorities.
- Woodworking:This application segment encompasses laminates, particleboard, and MDF production, representing the largest area of consumption for melamine-based adhesives. Demand is significant in China and Southeast Asia, driven by robust furniture manufacturing and construction activity.
- Construction:Melamine adhesives are integral to various building materials, including flooring, wall panels, and structural wood components, valued for their durability and moisture resistance. European and North American construction projects increasingly specify low-emission adhesive systems.
- Automotive:Used for interior paneling, headliners, and composite components, melamine adhesives contribute to lightweighting and structural integrity in vehicle manufacturing.
- Packaging:Niche applications exist in specialized packaging where high bond strength and moisture resistance are critical, though it represents a smaller volume segment.
Woodworking applications maintain the largest volume. Construction applications are expanding most quickly.
End User:
The primary purchasers of melamine-based adhesives shape procurement strategies and product development focus.
- Furniture Manufacturers:These companies are major consumers of melamine-based adhesives for bonding wood panels, laminates, and veneers in residential and commercial furniture. Production in China and Vietnam heavily relies on these adhesives for cost-effective and durable products.
- Construction Companies:These firms utilize melamine adhesives in building projects for flooring installation, panel assembly, and structural element fabrication, seeking durable and compliant bonding solutions. Demand for low-emission products is strong in regulated markets like Germany and California.
- Automotive OEMs:Original Equipment Manufacturers integrate melamine-bonded components into vehicle interiors and structural elements for performance and aesthetic reasons.
- Consumer Goods:This segment includes diverse applications from sporting goods to electronics, where specific bonding properties of melamine adhesives are required.
Furniture Manufacturers drive substantial adhesive volumes. Construction Companies are rapidly increasing their consumption.
Distribution Channel:
The pathways through which melamine-based adhesives reach end-users vary significantly, impacting market access and pricing.
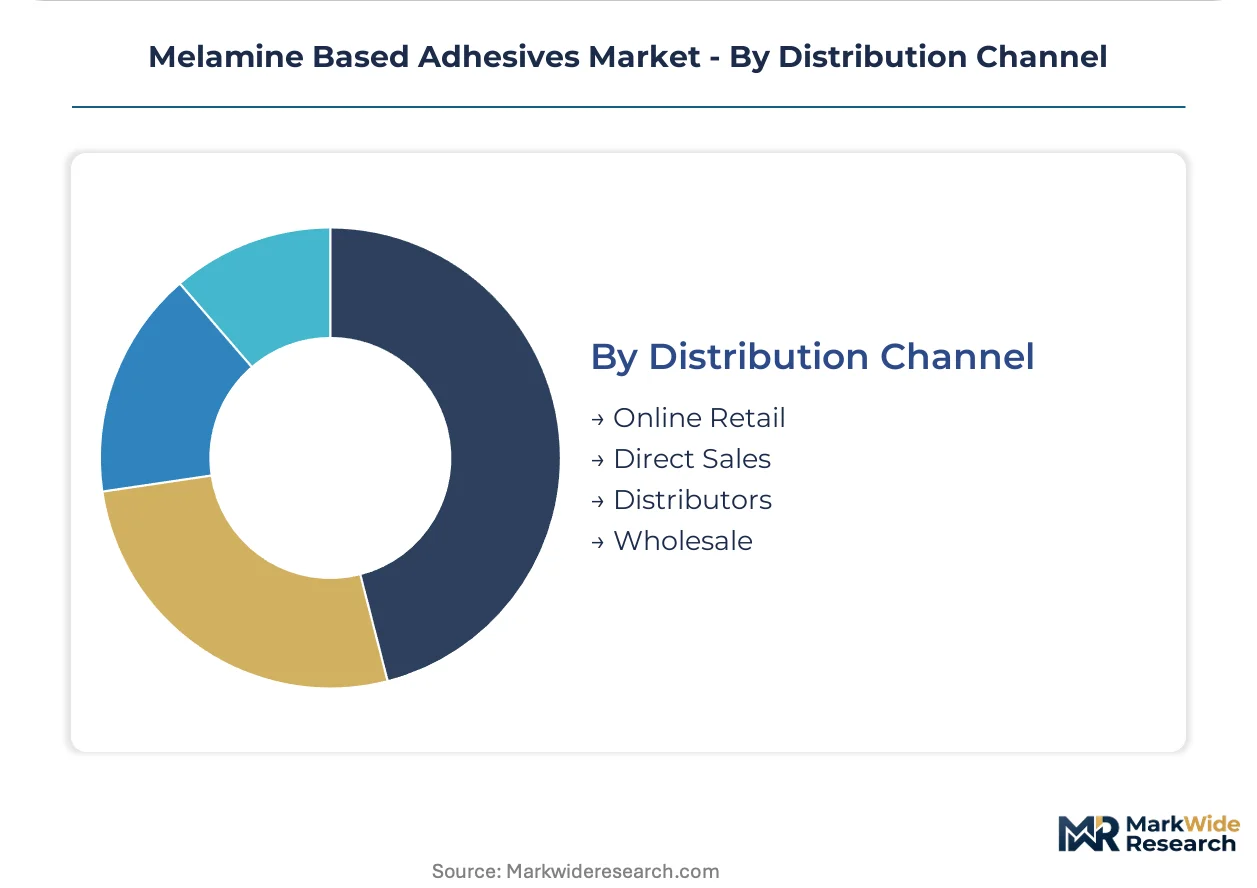
- Direct Sales:Large-volume industrial customers, such as major wood panel manufacturers and integrated furniture producers, often procure melamine adhesives directly from resin suppliers. This channel allows for customized formulations and technical support.
- Distributors:Distributors serve smaller and medium-sized enterprises, providing access to a range of adhesive products, warehousing, and local delivery services across diverse geographies. They play a crucial role in market penetration in fragmented regions.
- Online Retail:A nascent channel for specialized or smaller-volume purchases, particularly for DIY projects or niche industrial applications requiring specific adhesive types.
- Wholesale:Wholesalers supply bulk quantities to various industrial users and smaller distributors, acting as intermediaries in the supply chain for standard melamine adhesive products.
Direct Sales channels manage the largest bulk transactions. Distributors are gaining share in fragmented markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The trade flow of wood-based panels from Asia to North America and Europe significantly influences the melamine based adhesives market. Manufacturers in these exporting regions require compliant adhesive systems for international market access. This demand shapes product development and regulatory adherence across major production hubs.
United States
Demand for melamine-based adhesives in the United States is driven by robust residential construction and renovation activities. Strict mandates from the US EPA under TSCA Title VI compel manufacturers to adopt low-emission formulations. Wood panel manufacturing clusters in the Southeast, particularly around states like Georgia and North Carolina, are key consumption centers.
Germany
Germany's market for melamine adhesives benefits from its strong furniture manufacturing sector and high standards for indoor air quality. European Chemicals Agency (ECHA) regulations, including REACH and the E1 classification, directly influence product chemistry. Chemical producers in the Rhine-Main region actively develop advanced, low-formaldehyde resin systems for both domestic use and export.
China
China anchors global demand for melamine based adhesives, fueled by its massive wood panel and furniture production capacity. The country's GB standards for formaldehyde emissions are increasingly aligning with international benchmarks, pushing for cleaner formulations. Major wood processing and furniture manufacturing hubs, such as those in Guangdong and Jiangsu provinces, consume substantial volumes.
Vietnam
Vietnam's rapidly expanding furniture export industry drives significant consumption of melamine adhesives for wood-based panels. Manufacturers prioritize durable and moisture-resistant adhesives to meet international quality specifications. Production facilities near Ho Chi Minh City and Binh Duong province form critical clusters for wood product fabrication.
Brazil
Brazil's construction sector and furniture industry contribute to the steady demand for melamine-based adhesives in Latin America. Local building codes and environmental regulations increasingly influence adhesive selection. Wood panel producers in the southern states, including Paraná and Santa Catarina, represent significant end-users for these bonding agents.
Melamine Based Adhesives Market Key Industry Players
Channel-controlling players compete with product-specialist players across the melamine based adhesives market. The market exhibits a tiered structure, with large chemical conglomerates alongside specialized resin manufacturers. Strategic archetypes include diversified chemical giants, focused adhesive producers, and regional suppliers. Companies are pursuing portfolio diversification and strategic partnerships to navigate evolving regulatory landscapes.
Diversified chemical companies, such as BASF, exemplify the strategy of leveraging extensive R&D capabilities for advanced resin formulations. Hexion occupies a position as a global thermosetting resin supplier with a broad product portfolio serving construction and furniture industries. Georgia-Pacific Chemicals represents a significant North American player, focusing on wood panel adhesives and resin technologies. These entities collectively shape product innovation and market access for melamine-based solutions.
| Leading Market Players |
|---|
| Hexion |
| Georgia-Pacific Chemicals |
| OCI Nitrogen |
| BASF |
| Prefere Resins Holding |
| Innospec |
| Georgia-Pacific |
| AkzoNobel |
| Dow Chemical |
Cost & Logistics Intelligence
China's massive wood panel and furniture manufacturing hubs, particularly in Guangdong and Jiangsu provinces, exert significant influence over global melamine adhesive pricing due to their production scale. This concentration of capacity often dictates pricing trends for key raw materials and finished adhesive products.
Pricing Analysis
Cost-plus contract patterns, often indexed to petrochemical and natural gas prices, define melamine adhesive pricing. Price differentiation stems from formulation complexity, such as low-formaldehyde content, and volume scale for large industrial buyers. Pricing pressure originates from volatile raw material costs, particularly melamine and formaldehyde. Furniture manufacturers, especially in Asian markets, exhibit high price sensitivity for commodity-grade adhesives, while European and North American buyers prioritize compliance and performance.
Supply Chain Analysis
Major chemical conglomerates like BASF and Hexion, along with regional specialists, hold significant melamine adhesive production capacity. The supply chain for melamine adhesives concentrates primarily in China, Germany, and the United States. Raw material dependencies include melamine and formaldehyde, both derived from petrochemicals, making the chain susceptible to commodity price volatility. Distribution runs through a mix of direct sales to large industrial customers and distributors serving smaller enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a high-growth disruption driven by stringent formaldehyde emission regulations, forcing rapid reformulation and innovation in adhesive chemistry. The shift towards low- and no-added formaldehyde systems fundamentally alters product development.
For Market Incumbents:
Insulate core market share by accelerating investment in advanced R&D for NAF and ULEF formulations. Consolidate market position through strategic acquisitions of specialized resin technologies or regional producers in high-growth areas like Southeast Asia. This counters margin pressure from raw material volatility and regulatory compliance costs. Deepen vertical integration into key raw material production to mitigate supply chain risks.
For New Entrants and Emerging Players:
Southeast Asia's underpenetrated construction and furniture manufacturing sectors offer a significant entry point for advanced adhesive solutions. Focus on developing cost-effective, bio-based NAF systems tailored for specific regional wood panel applications. A go-to-market angle emphasizing rapid technical support and localized supply chains can differentiate offerings. Target small-to-medium enterprises seeking compliant and performance-driven alternatives.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors specialized resin manufacturers with proven low-emission or bio-based adhesive portfolios. The long-term viability of this market is strong, driven by continuous regulatory tightening and demand for sustainable materials. Target mid-sized companies demonstrating intellectual property in advanced MUF or NAF chemistries, particularly those with established market access in Europe or North America. A signal to watch is the widespread adoption of bio-based feedstocks in commercial-scale production.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced R&D in NAF Resins | Develops next-generation products meeting strict emission standards and securing future market access. |
| Capacity Expansion in Southeast Asia | Captures demand from rapidly growing furniture and wood panel manufacturing hubs in the region. |
| Strategic Partnerships for Bio-based Feedstocks | Secures sustainable raw material supply and enhances product environmental profiles for conscious buyers. |
| Enhanced Technical Support & Certification Services | Provides value-added services, aiding customer compliance and fostering loyalty in regulated markets. |
| Digitalization of Formulation & Process Control | Accelerates new product development and optimizes manufacturing efficiency for complex resin systems. |
Research Approach
Operator-level perspectives from R&D directors, procurement leads, plant managers, and regulatory affairs specialists anchored the qualitative base. Primary interviews were conducted with key industry participants, complemented by extensive secondary validation. Data sources included customs and trade data, chemical industry association reports, and environmental agency publications. This approach facilitated bottom-up and top-down triangulation for robust market insights.
Scenario-bracketing informed the quantitative model, projecting market dynamics across the analysis window. Segmentation dimensions modeled included product type, application, end-user, and regional regulatory compliance tiers. Compound annual growth rates were derived from historical data analysis and projected demand growth in key end-use sectors like furniture manufacturing. Forecast inputs integrated raw material price trends and evolving emission standards.
Practitioners should monitor shifts in petrochemical prices, new regulatory mandates, and advancements in bio-based chemistry for early signals of market revision. Forecasts reflect assumptions regarding economic stability and technological adoption within the adhesives sector. Cross-checking against national chemical industry reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle-East and Africa Acrylic Adhesives Market
Adhesives & Sealants
Contact Cement Market
Adhesives & Sealants
Ethylene Butyl Acrylate Market
Adhesives & Sealants
Water Based Adhesive Market
Adhesives & Sealants
Laminating Adhesives Market
Adhesives & Sealants
Hot Glue Guns Market
Adhesives & Sealants
Global Construction Adhesives and Sealants Market
Adhesives & Sealants
Global Sealants Market
Adhesives & Sealants
Heat Resistant Sealant Market
Adhesives & Sealants
Anaerobic Adhesives and Sealants Market
Adhesives & Sealants
Acrylic Flooring Adhesives Market
Adhesives & Sealants
Glass Adhesive Market
Adhesives & Sealants
Tissue Adhesives Market
Adhesives & Sealants
South America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Asia-Pacific Waterproofing Products Market
Adhesives & Sealants
Europe Construction Adhesives and Sealants Market