
 Polymer Nanocomposites Market | 2026-2036
Polymer Nanocomposites Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Nanocomposites Market Analysis
Multi-source procurement for carbon nanotube feedstock is rebalancing toward qualified second-source agreements as supply volatility reshapes compounder economics. RTP Company leverages its thermoplastic compounding scale to anchor North American automotive programs with consistent lot-to-lot conductivity. Arkema S.A. specializes in polyamide nanocomposite grades that sustain structural performance at elevated temperatures for under-hood applications. Evonik Industries AG controls the high-barrier silica dispersion segment for flexible electronics packaging through proprietary surface chemistry.
Polymer nanocomposites are multiphase materials in which nanoscale fillers such as clay platelets, carbon nanotubes, or metal oxides disperse within a thermoplastic or thermoset matrix at loadings typically below 5 weight percent, achieving property enhancements that would require 20-40 percent conventional filler. Melt intercalation dominates commercial production for commodity thermoplastics, while solvent dispersion preserves exfoliation quality in high-performance epoxy systems for aerospace. Reinforced nanocomposites occupy the largest volume position across automotive and construction end users, yet electrical conductive nanocomposites generate disproportionate margin contribution from electronics and healthcare device applications where percolation thresholds demand precision formulation. Barrier nanocomposites are gaining fastest in food packaging and flexible display encapsulation as oxygen transmission rate specifications tighten below 0.01 cc per square meter per day.
REACH registration requirements in Europe and EPA toxics release reporting in the United States impose documentation burdens on nanoscale filler importers that favor established suppliers with regulatory affairs infrastructure. China's SAMR mandatory national standards for nanomaterial classification create additional market access gates for imported compounds. Japan's METI guidelines on chemical substance handling in manufacturing further segment compliance capabilities among compounders. Stakeholders must monitor evolving definitions of nanomaterial status under these frameworks, as threshold adjustments could reclassify existing products and trigger new testing obligations without warning.
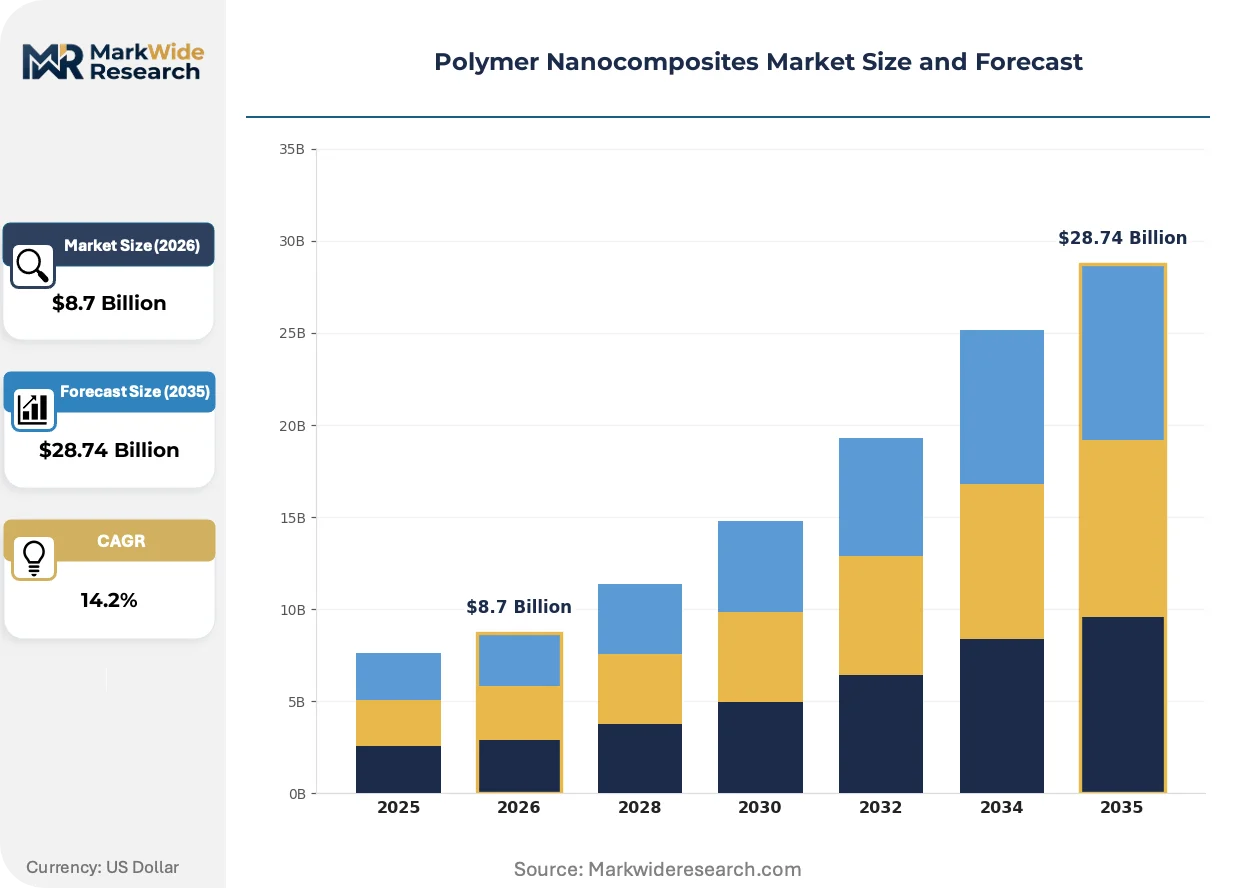
Market Dynamics
Automotive lightweighting mandates and electronics miniaturization are compressing filler loadings while demanding simultaneous property gains, forcing compounders to master sub-5 weight percent nanoscale dispersion precision at commercial throughput.
Growth Catalysts
- GB Standards Tightening:China's electrical conductivity specifications for consumer electronics are accelerating precision formulation demand from display and battery enclosure manufacturers.
- Automotive Lightweighting:Germany's KBA fuel efficiency targets and Japan's METI vehicle weight reduction programs are expanding structural nanocomposite specifications in under-hood and body panel applications.
- OLED Encapsulation Demand:South Korea's display manufacturing cluster around Seoul and Suwon is driving barrier nanocomposite consumption for flexible electronics packaging.
Market Restraints
- Carbon Nanotube Feedstock Volatility:Single-source dependence on Asian suppliers for high-purity CNTs creates lot-to-lot conductivity inconsistency that disrupts compounder economics.
- REACH Documentation Burden:ECHA registration requirements for nanoscale fillers impose testing costs that favor established suppliers with regulatory infrastructure, marginalizing new entrants.
- Epoxy Solvent Processing Costs:Aerospace-grade exfoliation quality requires solvent dispersion methods that carry higher capital intensity and environmental compliance costs than melt intercalation.
Strategic Opportunities
- Healthcare Device Convergence:Precision percolation threshold formulation for implantable electronics and diagnostic equipment represents an underpenetrated margin pool beyond automotive and packaging.
- SAMR Standard Alignment:China's mandatory national standards for nanomaterial classification create first-mover advantage for compounders establishing local testing partnerships.
- Food Packaging Barrier Migration:Oxygen transmission rate specifications below 0.01 cc per square meter per day are opening technical specification windows for silica dispersion specialists.
Industry Challenges
- Exfoliation Quality Control:Maintaining platelet dispersion uniformity at commercial scale requires process engineers with rare combinations of polymer rheology and surface chemistry expertise.
- Multi-Jurisdiction Classification Divergence:Evolving nanomaterial definitions under EPA toxics reporting, REACH thresholds, and SAMR criteria create simultaneous compliance exposure without harmonized testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Nanocomposites Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Conductive Nanocomposites, Electrical Conductive Nanocomposites, Barrier Nanocomposites, Reinforced Nanocomposites Application: Aerospace, Automotive Parts, Packaging, Electronics End User: Consumer Goods, Healthcare Devices, Construction Materials, Textile Industry Technology: Solvent Dispersion, Melt Intercalation, In-Situ Polymerization, Electrospinning |
| Companies Covered | RTP Company, 3M Company, Arkema S.A., DuPont, Nanocyl SA, Evonik Industries AG, Cabot Corporation, Nanophase Technologies Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Nanocomposites Market Emerging Trajectories
Active materials development is compressing the gap between laboratory exfoliation quality and commercial melt compounding throughput, while regulatory fragmentation is forcing compounders to build jurisdiction-specific compliance architectures.
Surface-modified graphene platelet dispersions are decentralizing electrical conductivity formulation from carbon nanotube dominance in automotive EMI shielding applications. Tier 1 suppliers in Germany and Japan are qualifying hybrid filler systems at 2-3 weight percent loadings. This shift is decentralizing supply chain power from CNT specialists toward platelet dispersion compounders with proprietary surface chemistry IP.
REACH registration requirements for nanoscale substances are tightening documentary evidence standards for imported fillers entering European compounder facilities. ECHA's evolving guidance on polymer additive classification is forcing reformulation reviews across epoxy and polyamide grades. High-performance aerospace laminates face the steepest compliance recertification timelines as lot traceability requirements extend back to raw ore sourcing.
Compounders are consolidating specification development relationships directly with OEM material engineering teams, bypassing traditional distributor technical service functions. South Korean display manufacturers now require co-development agreements for barrier nanocomposite qualification. This pattern is most visible in Seoul's OLED supply chain, where encapsulation material approval cycles have compressed from 18 months to 9 months through direct engagement models.
Polymer Nanocomposites Market Segmentation
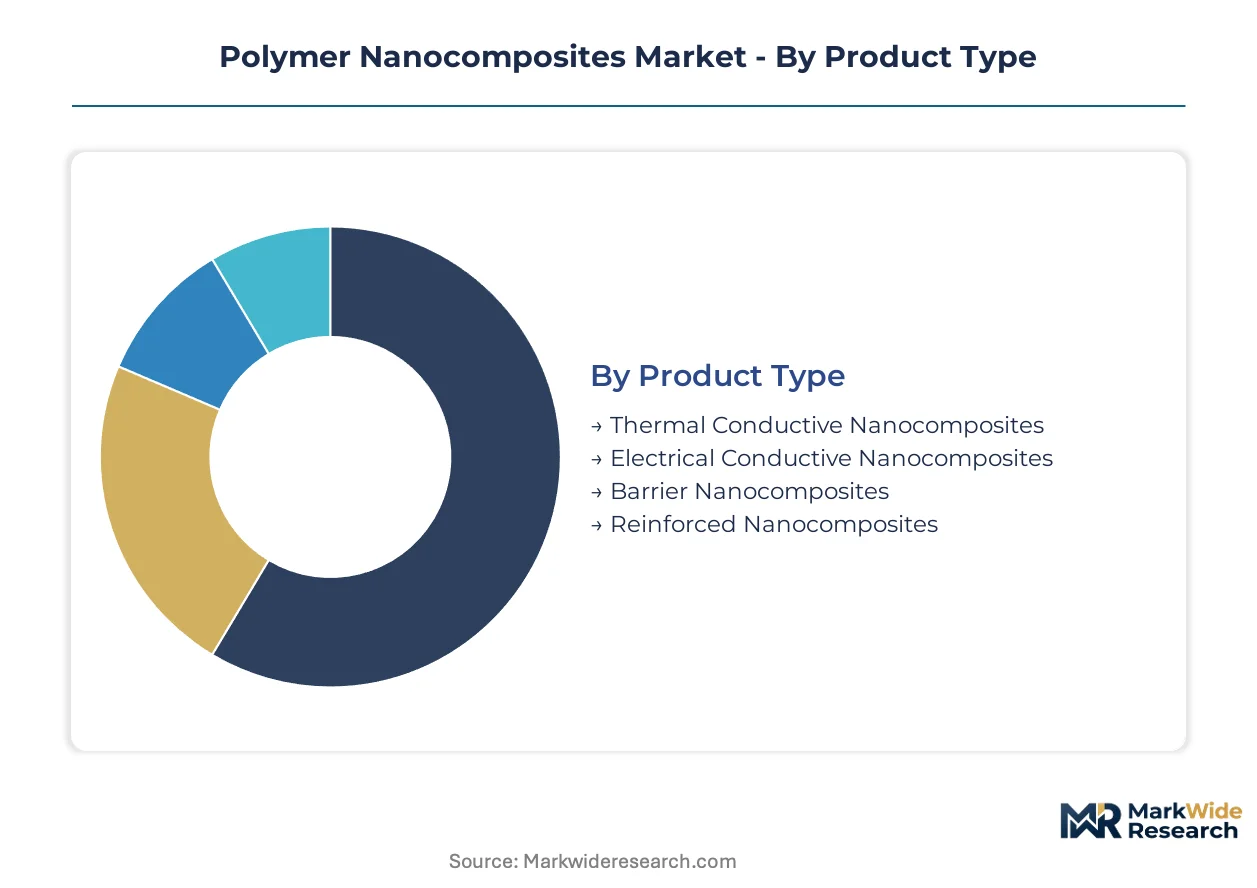
Polymer nanocomposite specifications diverge sharply across thermal, electrical, and mechanical performance axes, with each product type demanding distinct filler morphologies and dispersion protocols. Compounders must align production infrastructure with the precision requirements of target applications, as barrier specifications for OLED encapsulation bear little resemblance to reinforced under-hood automotive grades.
Product Type:
Thermal and electrical conductivity specifications create the steepest formulation complexity gradients, separating commodity compounders from precision specialists.
- Electrical Conductive Nanocomposites:Carbon nanotube or graphene platelet dispersions achieve percolation thresholds at 2-3 weight percent loadings. Demand concentrates in South Korea's display manufacturing cluster around Seoul, where EMI shielding specifications for flexible electronics are tightening under GB standards influence.
- Barrier Nanocomposites:Exfoliated clay or silica dispersions reduce oxygen transmission below 0.01 cc per square meter per day. Food packaging and flexible OLED encapsulation in Germany and Japan are driving qualification programs for ultra-high-barrier grades.
- Reinforced Nanocomposites:Clay or carbon fiber reinforcements at sub-5 weight percent loadings replace 20-40 percent conventional filler volumes. Automotive lightweighting programs in Germany anchor volume consumption for structural body panel applications.
- Thermal Conductive Nanocomposites:Boron nitride or alumina-filled systems manage heat dissipation in power electronics. Electric vehicle battery enclosure manufacturers are qualifying grades for thermal runaway protection.
Mature deployment sits with reinforced nanocomposites. Newer deployment is concentrated in barrier nanocomposites.
Application:
End-use performance thresholds resegment the supply base, with aerospace solvent processing and automotive melt compounding rarely sharing equipment footprints.
- Automotive Parts:Under-hood structural components and body panels leverage reinforced grades for KBA-mandated weight reduction. Germany's compounders dominate specification development with OEM engineering teams.
- Electronics:EMI shielding, thermal management, and flexible encapsulation demand precision percolation control. South Korean display manufacturers require co-development agreements with compressed 9-month qualification cycles.
- Packaging:Oxygen barrier specifications for extended shelf-life food products are migrating from passive films to active nanocomposite structures. Japanese converters lead technical specification advancement.
- Aerospace:Epoxy-based systems require solvent dispersion methods preserving exfoliation quality for laminate prepregs. REACH registration documentation extends lot traceability to raw ore sourcing.
Volume concentration favors automotive parts. Margin expansion is climbing the fastest in electronics.
End User:
Customer technical capabilities determine whether compounders sell standardized grades or enter joint development relationships.
- Healthcare Devices:Implantable electronics and diagnostic equipment demand precision percolation thresholds with biocompatibility certification. This segment generates disproportionate margin contribution relative to volume.
- Consumer Goods:Smartphone and laptop enclosures utilize electrical conductive grades for static dissipation. China's GB standards for electrical conductivity are accelerating formulation precision requirements.
- Construction Materials:Reinforced nanocomposites improve mechanical properties in structural composites and coatings. Building code adoption for fire-rated applications varies by jurisdiction.
- Textile Industry:Electrospun nanofibers incorporate antimicrobial or UV-blocking nanoparticles. Functional performance claims face evolving nanomaterial classification scrutiny under SAMR and REACH frameworks.
Specification maturity sits with consumer goods. Technical development is expanding most quickly in healthcare devices.
Technology:
Process selection locks compounders into distinct capital intensity and regulatory exposure profiles.
- Melt Intercalation:Twin-screw extrusion of nanoclays into thermoplastic matrices dominates commodity production. RTP Company leverages this scale for consistent lot-to-lot conductivity in North American automotive programs.
- Solvent Dispersion:Preserves exfoliation quality in high-performance epoxy systems for aerospace laminates. Environmental compliance costs and capital intensity exceed melt methods substantially.
- In-Situ Polymerization:Monomer infiltration of layered silicates before polymerization achieves superior dispersion. Limited commercial deployment due to batch processing constraints.
- Electrospinning:Produces nanofiber mats with embedded nanoparticles for filtration and textile applications. Throughput limitations restrict scale beyond specialty medical and defense contracts.
Commercial scale concentrates with melt intercalation. Process innovation is gaining share fastest in solvent dispersion as barrier specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive lightweighting programs in Germany and Japan anchor structural nanocomposite demand, while South Korea's display manufacturing cluster drives barrier specifications for flexible OLED encapsulation. China's GB standards for electrical conductivity reshape material specifications across consumer electronics supply chains.
United States
Electric vehicle battery enclosure manufacturers are qualifying thermal conductive grades for thermal runaway protection under NHTSA safety guidelines. EPA toxics release reporting requirements impose documentation burdens on nanoscale filler importers that favor established suppliers with regulatory affairs infrastructure. RTP Company leverages its thermoplastic compounding scale to anchor North American automotive programs with consistent lot-to-lot conductivity.
Germany
KBA fuel efficiency targets expand structural nanocomposite specifications in under-hood and body panel applications for premium automotive OEMs. REACH registration requirements for nanoscale substances tighten documentary evidence standards for imported fillers entering European compounder facilities. Arkema S.A. specializes in polyamide nanocomposite grades that sustain structural performance at elevated temperatures for under-hood applications.
China
GB standards for electrical conductivity in consumer electronics accelerate precision formulation demand from display and battery enclosure manufacturers. SAMR mandatory national standards for nanomaterial classification create additional market access gates for imported compounds. Shenzhen and Dongguan manufacturing clusters concentrate electrical conductive nanocomposite consumption for smartphone and laptop enclosure production.
Japan
METI vehicle weight reduction programs expand reinforced nanocomposite consumption for structural automotive components. METI guidelines on chemical substance handling in manufacturing segment compliance capabilities among compounders. Nagoya's automotive engineering corridor hosts specification development relationships between compounders and OEM material engineering teams for compressed qualification cycles.
South Korea
Flexible OLED encapsulation demand drives barrier nanocomposite consumption with oxygen transmission rate specifications tightening below 0.01 cc per square meter per day. MFDS biocompatibility certification requirements shape healthcare device formulation standards for implantable electronics. The Seoul-Suwon display manufacturing cluster requires co-development agreements with compressed 9-month qualification cycles for encapsulation material approval.
Polymer Nanocomposites Market Vendor Landscape
Capacity expansion dominates the current landscape as compounders scale sub-5 weight percent nanoscale dispersion precision to meet commercial throughput requirements. The vendor base organizes around three strategic archetypes: diversified chemical conglomerates with regulatory infrastructure, specialized nanomaterial compounders with proprietary surface chemistry IP, and regional thermoplastic processors with automotive qualification relationships. M&A activity and strategic partnerships concentrate among compounders seeking to secure carbon nanotube feedstock agreements and establish local testing partnerships for SAMR compliance.
Among diversified chemical conglomerates, BASF SE and Evonik Industries AG exemplify the integrated archetype that controls high-barrier silica dispersion segments through proprietary surface chemistry. RTP Company occupies a position within the specialized compounder tier, leveraging thermoplastic compounding scale for consistent lot-to-lot conductivity in North American automotive programs. Arkema S.A. represents the performance materials specialist segment with polyamide nanocomposite grades engineered for elevated temperature structural applications.
| Leading Market Players |
|---|
| RTP Company |
| 3M Company |
| Arkema S.A. |
| DuPont |
| Nanocyl SA |
| Evonik Industries AG |
| Cabot Corporation |
| Nanophase Technologies Corporation |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
China's dual carbon goals and tightening GB standards for electrical conductivity in consumer electronics gate qualified supply access and premium-tier pricing power for compounders demonstrating precision percolation threshold control. Buyers in South Korea's display manufacturing cluster now demand co-development agreements with compressed qualification cycles, segmenting pricing tiers by technical capability rather than volume scale alone.
Pricing Analysis
Volume concentration in reinforced nanocomposites for automotive lightweighting generates commodity-level margins, while electrical conductive and barrier nanocomposites for electronics packaging command premium pricing. Price differentiation hinges on REACH registration documentation completeness and SAMR compliance certification tier. Cost compression in reinforced grades is intensifying as German and Japanese OEMs consolidate specification development with fewer qualified compounders. Tier 1 automotive suppliers exhibit highest price sensitivity due to KBA-mandated cost targets, whereas healthcare device manufacturers prioritize biocompatibility certification over unit economics.
Supply Chain Analysis
REACH registration and SAMR nanomaterial classification certification gate supply chain participation, favoring compounders with established regulatory affairs infrastructure. High-purity carbon nanotube feedstock draws from China, Japan, and South Korea, while exfoliated clay and silica dispersions source from Germany and the United States. Single-source dependence on Asian CNT suppliers creates lot-to-lot conductivity inconsistency that disrupts compounder economics. Distribution runs through direct OEM engagement models in Seoul and Suwon, bypassing traditional distributor technical service functions for barrier nanocomposite qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward integration into carbon nanotube feedstock agreements and proprietary surface chemistry IP determines margin sustainability. Players are pursuing upstream control over high-purity CNT supply to escape single-source volatility and anchor conductivity consistency.
For Market Incumbents: Acquire carbon nanotube feedstock agreements with qualified second-source provisions to escape single-source volatility from Asian suppliers. Invest in proprietary surface chemistry IP for silica dispersion segments serving flexible OLED encapsulation in South Korea, defending against hybrid filler system displacement by graphene platelet compounders in German and Japanese automotive EMI shielding applications. For New Entrants and Emerging Players: Launch via co-development agreement models with South Korean display manufacturers seeking compressed 9-month qualification cycles for barrier nanocomposite encapsulation materials. Target healthcare device convergence for implantable electronics and diagnostic equipment, where precision percolation threshold formulation generates disproportionate margin contribution relative to volume and biocompatibility certification requirements create defensible positioning. For Investors and Strategic Acquirers: Compressed qualification cycles from 18 months to 9 months in Seoul's OLED supply chain is the leading indicator that direct OEM engagement models are displacing distributor-mediated technical service functions. Over the medium-term horizon, vertically integrated compounders with captive CNT supply and proprietary dispersion IP represent the most viable acquisition archetype. Monitor ECHA guidance evolution on polymer additive classification as the signal for compliance recertification cost spikes that will marginalize non-integrated players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CNT Feedstock | Secures lot-to-lot conductivity consistency for RTP Company and Arkema S.A. automotive programs. |
| Proprietary Surface Chemistry IP Development | Enables Evonik Industries AG to control high-barrier silica dispersion for flexible electronics packaging. |
| SAMR Local Testing Partnership Establishment | Creates first-mover advantage for compounders accessing China's GB standards-compliant consumer electronics supply chain. |
| Direct OEM Co-Development Agreement | Compresses barrier nanocomposite qualification cycles with Seoul-Suwon display manufacturers to 9 months. |
| Healthcare Device Biocompatibility Certification | Opens precision percolation formulation margin pool beyond automotive and packaging volume concentration. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with thermoplastic compounding plant managers, automotive OEM material engineering directors, display manufacturer procurement leads, and regulatory affairs specialists at compounder facilities. ECHA REACH registration databases, SAMR nanomaterial classification standards, EPA toxics release reporting disclosures, and Korean customs import records provided quantitative grounding. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Data-stream reconciliation between volume consumption figures from automotive production databases and value estimates from compounder facility capacity disclosures shaped the analytical framework. Modeled dimensions spanned product type, application, end user, and technology protocol across the projection horizon, with regional production cluster and regulatory framework as additional segmentation axes. CAGRs derived from fitted growth curves incorporating KBA fuel efficiency target trajectories, METI vehicle weight reduction program timelines, and GB standards implementation schedules for electrical conductivity specifications.
Carbon nanotube feedstock supply disruption, ECHA threshold adjustments for nanomaterial reclassification, and SAMR enforcement intensity variations are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding melt intercalation scale-up rates and solvent dispersion cost trajectories. A model refresh is warranted upon material change in REACH registration evidence standards or compressed qualification cycle adoption beyond South Korea's display cluster.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Global Gold Nanoparticles Market
Nanomaterials
Global Gold Nanorods Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
Nanoparticle Titanium Dioxide (Tio2) Market
Nanomaterials
United States Gold Nanoparticles Market
Nanomaterials
Asia-Pacific Nanocellulose Materials Market
Nanomaterials
Global Nanofilms Market
Nanomaterials
Silver Nanoparticles Market
Nanomaterials
Graphene Aerogel Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Metal Nitride Nanoparticles Market
Nanomaterials
Global Cerium Oxide Nanoparticles Market
Nanomaterials
Aluminium Oxide Nanoparticles Market
Nanomaterials
Global Nanoclay Market
Nanomaterials
Nanotechnology Market
Nanomaterials
Metal and Metal Oxide Nanoparticles Market