
 Nanochemicals Market | 2026-2036
Nanochemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Nanochemicals Market Intelligence
Project finance and leasing structures for nanochemical production facilities is reshaping competitive entry barriers, allowing mid-scale firms to access advanced synthesis equipment without full capital ownership. BASF SE leverages its integrated Ludwigshafen complex to sustain captive supply of high-purity nanoparticles. Evonik Industries AG anchors its position through specialized organosilane nanochemistry for electronics coatings. DuPont competes by controlling proprietary nanocomposite formulations for automotive lightweighting applications.
Nanochemicals comprise engineered substances with at least one dimension between 1 and 100 nanometers, typically synthesized through sol-gel processing, chemical vapor deposition, or hydrothermal methods to achieve surface-area-driven reactivity in catalysis, drug delivery, and energy conversion. Nanoparticles occupy the largest revenue pool due to mature manufacturing protocols, while nanocomposites represent the fastest-expanding segment as automotive and aerospace buyers prioritize strength-to-weight ratios. Biomedical applications command premium margins because regulatory validation requirements limit supplier qualification to a narrow tier of certified producers.
EPA oversight under the Toxic Substances Control Act governs nanoscale material notification in the United States, while REACH registration mandates in Europe enforce comprehensive toxicity documentation for commercial nanochemical volumes. ECHA's evolving guidance on nanoforms continues to extend compliance costs for importers and domestic manufacturers alike. Stakeholders must monitor pending regulatory determinations on nano-specific hazard classifications that could redraw market access boundaries without advance notice.
Market Dynamics
REACH nanoform registration requirements in Europe are compressing supplier qualification timelines, forcing manufacturers to front-load toxicity documentation before commercial volumes. This regulatory compression is reshaping capital allocation across synthesis, testing, and compliance functions simultaneously.
Growth Catalysts
- Pharmaceutical Targeted Delivery:Oncology and immunology pipelines require surface-functionalized nanoparticles for precision bioaccumulation. FDA IND pathways for nano-enabled therapeutics are streamlining first-in-human timelines.
- REACH Compliance Deadlines:ECHA's 2025 nanoform guidance updates are mandating standardized characterization protocols. Domestic European producers gain first-mover advantage in data generation.
- Automotive Lightweighting Mandates:CAFE standards in the United States and EU CO2 fleet targets are accelerating nanocomposite adoption for structural components. Polymer-matrix nanocomposites replace metal stampings in battery enclosures.
Market Restraints
- Precursor Chemical Volatility:Organometallic reagents and high-purity metal salts face supply disruptions from semiconductor sector competition. Price spikes in germanium and indium derivatives compress formulation margins.
- Synthesis Equipment Concentration:Chemical vapor deposition reactors and plasma synthesis systems are manufactured by a limited vendor base in Germany and Japan. Lead times extend 14-18 months for scaled production units.
- Substitution by Conventional Materials:Micro-scale fillers and surface-treated pigments compete in cost-sensitive coatings and packaging applications. Buyers downgrade specifications where nanoscale performance is not strictly required.
Strategic Opportunities
- India Manufacturing Localization:BIS nanomaterial standards implementation is creating certified-supplier gaps. Early entrants capture pharmaceutical and agrochemical formulation demand.
- Green Hydrogen Catalysis:Platinum-group-metal nanocatalysts for PEM electrolyzers are scaling from pilot to gigawatt production. Offtake agreements with electrolyzer OEMs lock in multi-year volume commitments.
- Digital Twin Integration:AI-driven process control is converging with real-time spectroscopic monitoring. Virtual batch optimization reduces yield loss in hydrothermal synthesis.
Industry Challenges
- Characterization Talent Scarcity:Electron microscopy and dynamic light scattering expertise sits concentrated in academic and national lab settings. Industrial employers compete for PhD-level analytical chemists.
- Cleanroom Capital Requirements:ISO Class 5-7 facilities for pharmaceutical-grade nanoparticle production demand $40-80 million per greenfield site. Financing structures must accommodate 5-7 year validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanochemicals Market |
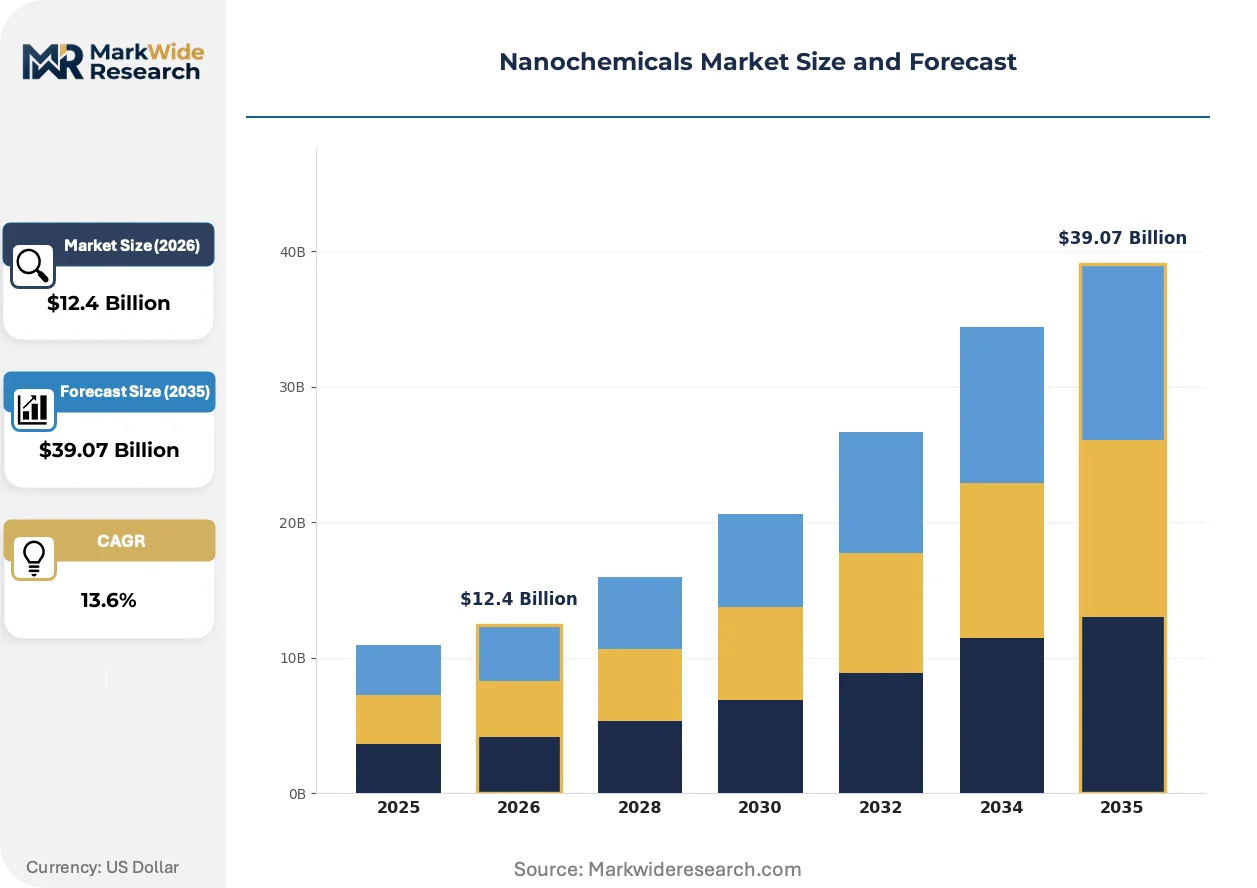
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $39.07 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanoparticles, Nanotubes, Nanocomposites, Nanosheets Application: Coatings, Electronics, Energy Storage, Biomedical End User: Pharmaceuticals, Electronics Manufacturing, Automotive, Agriculture Distribution Channel: Direct Sales, Online, Distributors, Retail |
| Companies Covered | BASF SE, Evonik Industries AG, Merck KGaA, DuPont, SABIC, Huntsman Corporation, Mitsubishi Chemical Group Corporation, Solvay SA, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanochemicals Market Strategic Shifts & Innovations
Computational materials science is compressing discovery cycles for novel nanostructures, while regulatory data requirements are shifting competitive advantage toward integrated testing capabilities. Synthesis automation is reducing batch-to-batch variability in commercial-scale production.
Digital twin platforms for sol-gel and hydrothermal reactors are virtualizing process development workflows. Specialty chemical manufacturers deploy these systems to simulate nucleation kinetics and aging conditions before physical pilot runs. Automotive coatings formulators adopt virtualized batch records to accelerate customer qualification timelines.
ECHA's evolving nanoform-specific guidance under REACH Annex VI is extending dossier requirements for surface-modified and aggregated nanoparticles. Manufacturers must generate dissolution rate data and environmental fate studies not previously mandated. Importers into the European Union face the steepest compliance cost escalation as they lack historical testing archives.
Formulators are consolidating supplier relationships around certified producers with pre-submitted REACH dossiers. Procurement teams at pharmaceutical and electronics manufacturers now require ECHA registration numbers as standard vendor qualification criteria. Germany and the Netherlands host the densest concentrations of compliant suppliers, concentrating contract manufacturing decisions in the Rhine-Ruhr and Rotterdam-Antwerp corridors.
Nanochemicals Market Segmentation
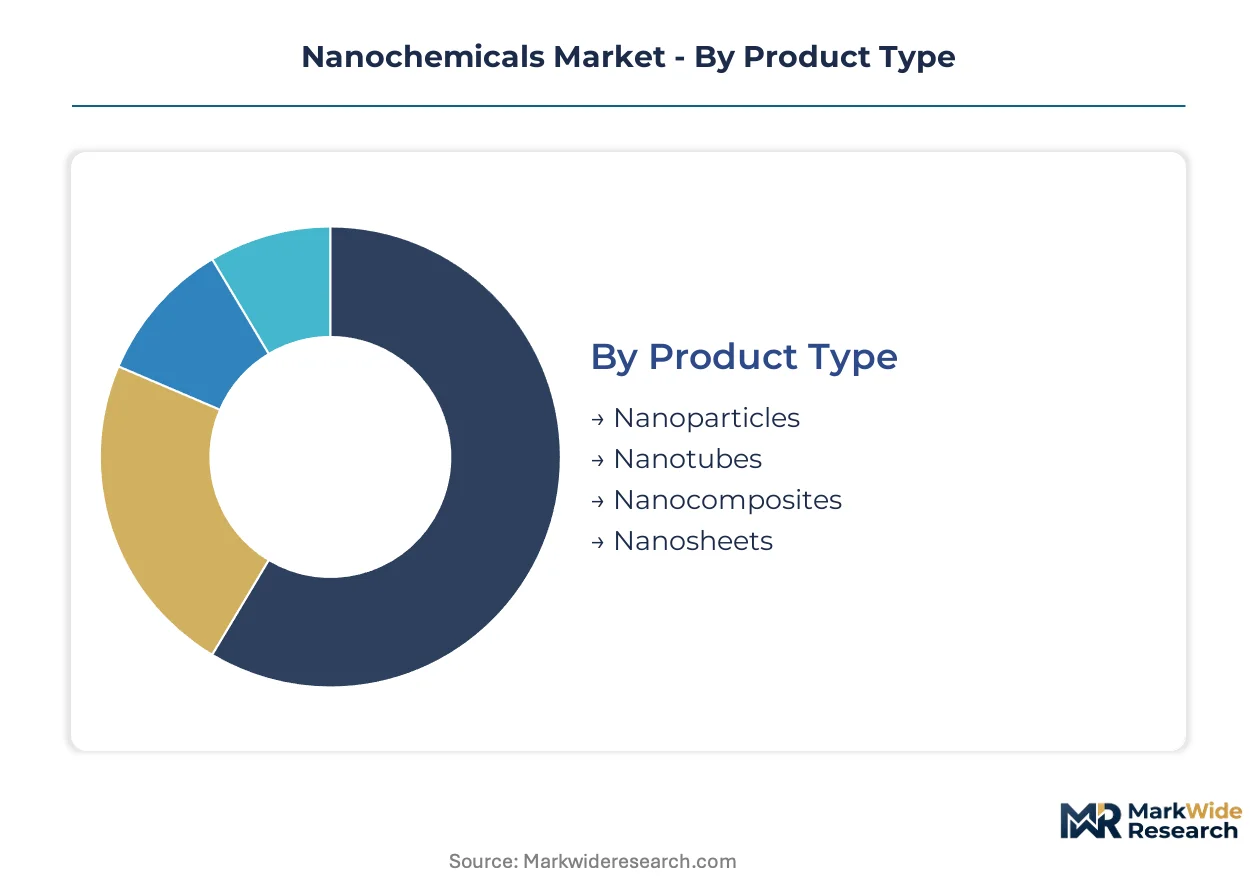
Segmentation in nanochemicals separates volume commodities from premium-validated grades. Product architecture, application specificity, and channel access each create distinct margin tiers and qualification barriers.
Product Type:
Product architecture governs synthesis complexity and surface-area-driven reactivity, with manufacturing maturity varying sharply across dimensional geometries.
- Nanoparticles:Spherical or irregular zero-dimensional structures synthesized via sol-gel or flame pyrolysis, typically metal oxides or quantum dots. Pharmaceutical manufacturers in Germany concentrate procurement for targeted drug delivery systems, with FDA IND pathways compressing supplier validation timelines.
- Nanocomposites:Matrix-embedded nanoscale reinforcements combining polymers with carbon nanotubes or clay platelets. Automotive OEMs in Michigan and Stuttgart prioritize these for battery enclosure lightweighting as CAFE and EU CO2 fleet mandates tighten.
- Nanotubes:Cylindrical carbon or inorganic structures with exceptional tensile properties.
- Nanosheets:Two-dimensional layered materials including graphene and transition metal dichalcogenides.
Nanoparticles hold installed capacity. Nanocomposites are rotating up the share rankings.
Application:
End-use function determines purity thresholds, with biomedical and electronics commanding certification premiums over industrial coatings.
- Biomedical:Surface-functionalized nanocarriers for oncology therapeutics and diagnostic imaging agents. CDSCO in India and FDA in the United States enforce parallel validation tracks that limit qualified supplier pools to certified producers with ISO 13485 traceability.
- Electronics:High-purity organosilanes and conductive nanomaterials for semiconductor packaging and display coatings. Taiwan Semiconductor and Samsung Foundry concentrate demand in Hsinchu and Pyeongtaek, with sub-10nm node requirements driving atomic-layer deposition precursor specifications.
- Coatings:Scratch-resistant and anti-corrosive surface treatments for automotive and marine substrates.
- Energy Storage:Silicon nanowire anodes and solid-state electrolyte additives for lithium-ion and next-generation batteries.
Biomedical commands margin premiums. Energy Storage is expanding most quickly as gigafactory investments accelerate.
End User:
Customer type dictates order scale and technical service intensity, with pharmaceutical buyers requiring batch documentation that agricultural formulators rarely demand.
- Pharmaceuticals:Formulators of nano-enabled therapeutics requiring GMP-compliant synthesis and extensive toxicity dossiers. EMA and national European regulators enforce REACH nanoform registration that favors domestic producers with pre-submitted characterization archives.
- Electronics Manufacturing:Semiconductor foundries and component assemblers purchasing high-purity precursors under long-term supply agreements. Japanese and Korean electronics clusters concentrate procurement decisions, with METI-aligned suppliers gaining preferential qualification.
- Automotive:Tier-1 suppliers and OEMs integrating nanocomposites into structural and powertrain components.
- Agriculture:Agrochemical formulators deploying nano-encapsulated pesticides and micronutrient delivery systems.
Pharmaceuticals anchor premium pricing. Electronics Manufacturing is gaining share fastest through foundry capacity expansion.
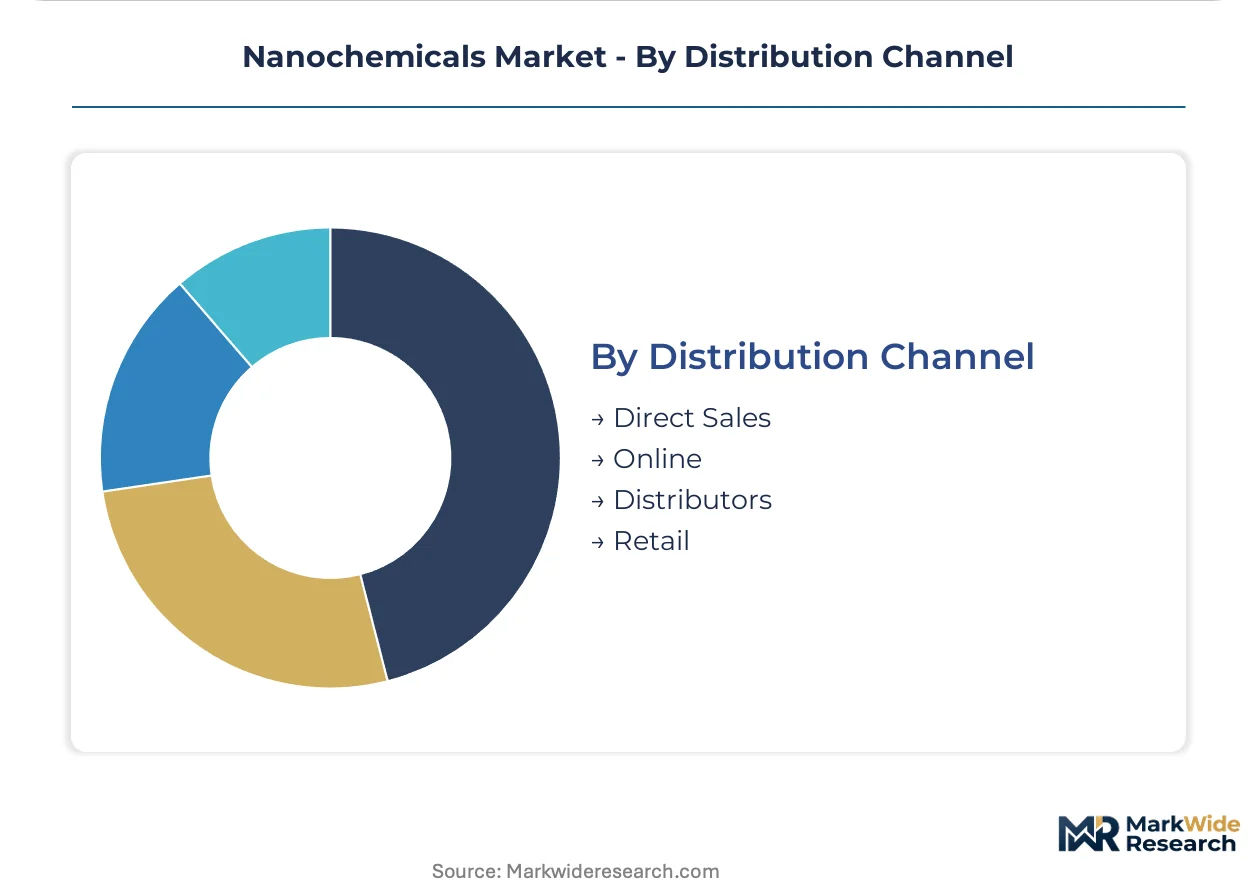
Distribution Channel:
Channel structure reflects buyer sophistication and volume scale, with direct relationships dominating validated grades and intermediaries serving fragmented demand.
- Direct Sales:Manufacturer-to-end-user contracts for pharmaceutical-grade and electronics-purity nanochemicals. BASF SE and Evonik Industries leverage technical service teams to secure multi-year supply agreements with explicit quality specifications.
- Distributors:Specialized chemical distributors stocking industrial-grade nanoparticles for coatings and agriculture. Brenntag and Univar Solutions maintain regional warehouses in Rotterdam and Singapore to serve mid-scale formulators without direct supplier relationships.
- Online:E-commerce platforms for research quantities and catalog chemicals.
- Retail:Limited consumer-facing sales through scientific supply stores.
Direct Sales holds relationship density. Distributors are rotating up the share rankings as mid-market access expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical formulators in Germany and electronics manufacturers in East Asia drive concentrated procurement of validated nanochemical grades. Automotive OEMs in the United States and South Korea accelerate nanocomposite adoption for lightweighting mandates. Regulatory divergence across EPA, ECHA, and METI frameworks fragments supplier qualification requirements.
United States
Automotive OEMs in Michigan and California prioritize nanocomposite battery enclosures to meet CAFE fleet efficiency targets. EPA notification requirements under the Toxic Substances Control Act govern commercial nanoscale material introduction. The Boston-Cambridge corridor concentrates biomedical nanoparticle startups seeking FDA IND pathway acceleration.
Germany
BASF SE and Evonik Industries anchor the Ludwigshafen-Rhine-Ruhr research cluster for high-purity nanoparticle production. ECHA's REACH nanoform registration mandates compress supplier qualification timelines for pharmaceutical and electronics buyers. The country's national pharmaceutical regulator enforces parallel validation tracks that limit qualified supplier pools.
China
Semiconductor foundries in Hsinchu and Shanghai drive demand for atomic-layer deposition precursors and conductive nanomaterials. The country's national standards administration implements GB nanomaterial specifications that create certified-supplier gaps for domestic producers. Yangtze River Delta electronics clusters concentrate procurement decisions for display coating applications.
Japan
METI-aligned suppliers gain preferential qualification from Tokyo and Osaka semiconductor manufacturers purchasing organosilane nanochemistry. The country's industrial ministry coordinates national nanotechnology initiatives that standardize characterization protocols. Nagoya automotive suppliers integrate carbon nanotube composites into structural components for export markets.
India
Pharmaceutical formulators in Maharashtra and Gujarat seek CDSCO-validated nanocarriers for oncology therapeutics. BIS nanomaterial standards implementation creates certified-supplier gaps that early entrants exploit. Hyderabad's vaccine and biologics cluster drives demand for surface-functionalized nanoparticles with ISO 13485 traceability.
Nanochemicals Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered supply relationships. The vendor base clusters around integrated chemical conglomerates with captive synthesis capabilities, mid-scale specialists with equipment-leasing structures, and research-grade suppliers serving fragmented academic demand. Three archetypes dominate: vertically integrated giants with Ludwigshafen-style complexes, regional specialists with organosilane or nanocomposite focus, and platform distributors aggregating mid-market access. M&A activity concentrates on testing and characterization capabilities, while capacity expansion targets pharmaceutical-grade cleanroom facilities.
Among German chemical conglomerates, BASF SE and Evonik Industries AG exemplify integrated archetypes with Rhine-Ruhr research clustering. Merck KGaA occupies a position bridging pharmaceutical validation and electronics purity requirements. DuPont represents the materials-science specialist model with automotive and aerospace formulation focus. These three anchors demonstrate how geographic concentration and regulatory pre-submission create defensive positioning against importer competition.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Merck KGaA |
| DuPont |
| SABIC |
| Huntsman Corporation |
| Mitsubishi Chemical Group Corporation |
| Solvay SA |
| Thermo Fisher Scientific Inc. |
| Others |
Cost & Logistics Intelligence
Ludwigshafen's integrated chemical complex anchors European nanoparticle capacity, concentrating synthesis expertise that translates into pricing power over pharmaceutical and electronics buyers lacking alternative qualified suppliers. REACH nanoform registration costs compress importer margins while rewarding domestic producers with pre-submitted dossiers, creating asymmetric cost structures that downstream formulators absorb through long-term offtake premiums.
Pricing Analysis
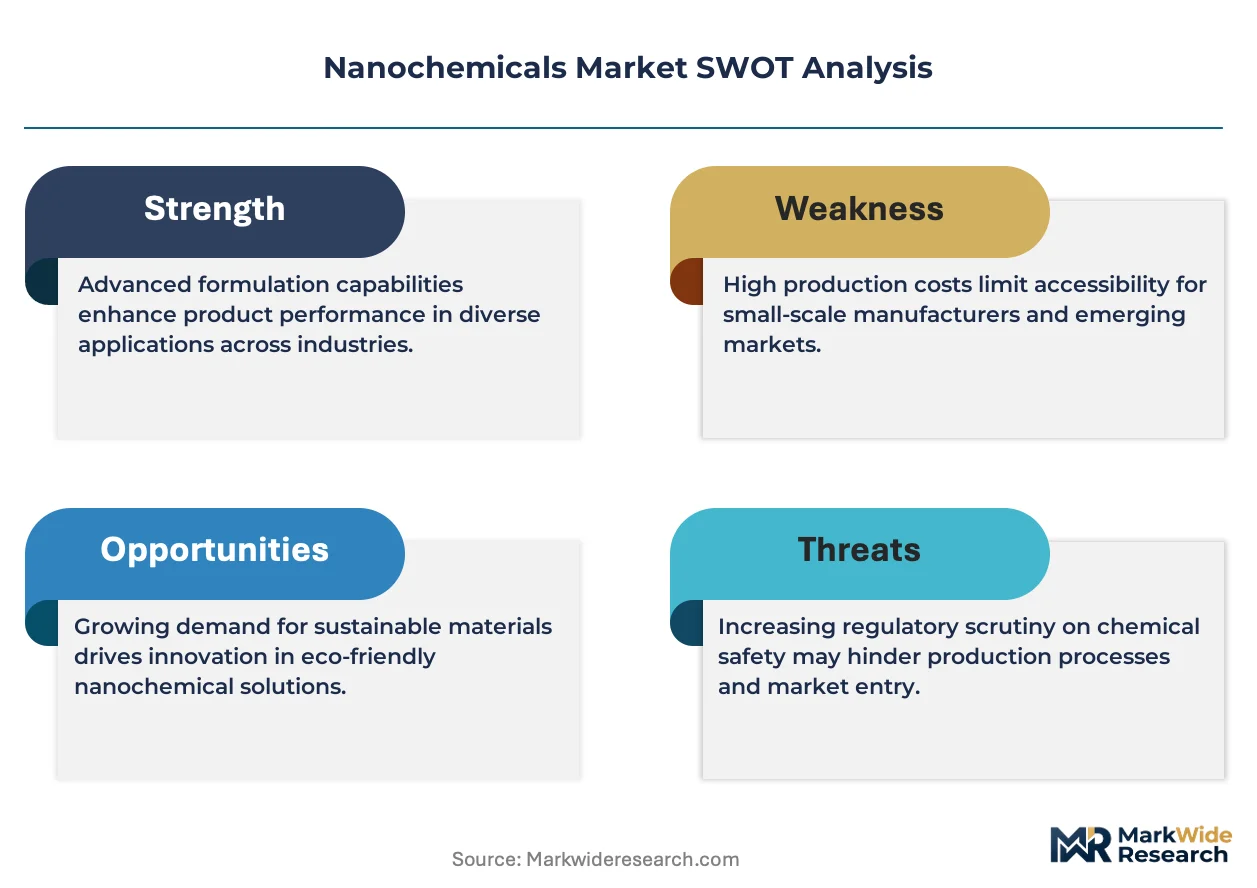
Certification level creates the primary spread between pharmaceutical-grade and industrial-grade nanochemicals. Three-tier pricing structure across GMP-validated, technical-grade, and research-catalog tiers separates BASF SE's captive supply premiums from distributor-stocked commodities. Cost compression in technical-grade metal oxides is intensifying because semiconductor sector competition for organometallic precursors spikes germanium and indium salt prices. Agricultural formulators exhibit highest price sensitivity, downgrading to micro-scale fillers where nanoscale performance is not strictly required, while oncology drug developers accept premium pricing for FDA IND-tracked nanocarriers.
Supply Chain Analysis
Export-control restrictions on plasma synthesis and chemical vapor deposition equipment limit technology flows from Germany and Japan to emerging producers. Supply concentrates in Germany, China, and the United States for high-purity nanoparticle output, with the Rhine-Ruhr and Yangtze River Delta hosting densest qualified supplier clusters. Synthesis draws from organometallic reagents, high-purity metal salts, and specialized reactor vessels that face 14-18 month procurement lead times. Single-source vulnerability sits with Japanese and German equipment vendors controlling scaled production reactor manufacturing. Distribution runs through direct manufacturer relationships for validated grades and specialized chemical distributors for industrial-tier volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment constructs defensive moats in nanochemicals, as REACH nanoform dossier requirements and FDA IND pathway validation create switching costs that lock pharmaceutical buyers into pre-qualified supplier relationships.
For Market Incumbents: Harden compliance infrastructure against ECHA's evolving nanoform guidance by pre-submitting surface-modified particle characterization archives before mandate expansion. Deepen backward integration into organometallic precursor production to insulate margins from semiconductor sector demand spikes in germanium and indium derivatives. Expand cleanroom capacity in the Rhine-Ruhr corridor to capture CDSCO validation demand from Indian pharmaceutical formulators seeking ISO 13485-traceable nanocarriers. For New Entrants and Emerging Players: Pursue certified-supplier gaps in India's BIS nanomaterial standards implementation, where domestic pharmaceutical and agrochemical formulators lack qualified local sources. Target green hydrogen catalysis applications, where platinum-group-metal nanocatalyst offtake agreements with electrolyzer OEMs offer multi-year volume commitments absent entrenched competition. Deploy equipment-leasing structures to access chemical vapor deposition reactors without full capital ownership, lowering barrier to pharmaceutical-grade cleanroom entry. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated testing and characterization capabilities as acquisition targets, given electron microscopy and dynamic light scattering expertise concentration in academic settings. Five-to-ten year viability hinges on regulatory data generation scale rather than synthesis capacity alone. Watch for ECHA hazard classification determinations on nano-specific environmental fate as inflection indicator that could redraw market access boundaries without advance notice, forcing portfolio repositioning among importers lacking historical archives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Captive organometallic supply insulates BASF SE and Evonik Industries from semiconductor sector price spikes. |
| REACH Nanoform Dossier Pre-Submission | Early ECHA registration locks pharmaceutical buyers into qualified supplier relationships before mandate expansion. |
| Cleanroom Capacity Expansion | ISO Class 5-7 facilities in Germany capture CDSCO-tracked demand from Indian oncology formulators. |
| Digital Twin Process Integration | AI-driven sol-gel reactor virtualization at specialty chemical manufacturers reduces yield loss before physical pilot runs. |
| Green Hydrogen Catalyst Partnership | Platinum-group-metal nanocatalyst offtake agreements with electrolyzer OEMs secure multi-year volume commitments. |
Research Approach
Operator-level perspectives from plant managers at nanoparticle synthesis facilities, procurement leads at pharmaceutical formulators, technical R&D directors at automotive coatings developers, and regulatory affairs specialists at electronics manufacturers anchored the qualitative base. Primary interview insights combined with secondary validation from ECHA guidance documents, FDA IND pathway filings, customs and trade data, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across the projection horizon.
Scenario-bracketing framed analytical approach across the analysis window, with segmentation dimensions spanning product architecture, application purity tier, end-user industry, and regional regulatory cluster. CAGRs derived from installed capacity trajectories, pipeline visibility from pharmaceutical oncology therapeutics, and automotive lightweighting mandate compliance schedules. Forecast inputs incorporated green hydrogen electrolyzer deployment curves and semiconductor node transition timelines for atomic-layer deposition precursor specifications.
Sensitivities concentrate around ECHA nanoform hazard classification determinations, EPA TSCA notification requirement expansion, and precursor chemical supply disruptions from semiconductor sector demand competition. Forecasts reflect documented assumptions on regulatory timeline adherence and equipment vendor delivery schedules. Material shifts in REACH Annex VI guidance scope or cleanroom capital cost inflation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Lipid Nanoparticles Market
Nanomaterials
Colloidal Selenium Nanoparticles Market
Nanomaterials
Nanoscale Chemicals Market
Nanomaterials
Polymeric Nanoparticles Market
Nanomaterials
Global Nanoclay Reinforcement Market
Nanomaterials
Carbon Nanotubes (Cnts) Market
Nanomaterials
Nanoparticle Analysis Market
Nanomaterials
Global Cerium Oxide Nanoparticles Market
Nanomaterials
Nanomaterial Supercapacitors Market
Nanomaterials
Metal and Metal Oxide Nanoparticles Market
Nanomaterials
Americas Gold Nanoparticles Market
Nanomaterials
Global Nanosilica Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Nanocellulose Market
Nanomaterials
Nanotools Market
Nanomaterials
Global Graphene Based Supercapacitors Market