
 Global Mobile Security Software Market | 2026-2036
Global Mobile Security Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Security Software Market Foresight
Artificial intelligence is broadening threat detection capabilities beyond signature-based scanning. Microsoft Corporation leverages its cloud infrastructure to embed security layers across Azure mobile endpoints. CrowdStrike Holdings, Inc. specializes in AI-driven behavioral analytics that identify anomalous device activity in real time. Kaspersky Lab, Inc. anchors its position through deep malware research capabilities and nation-state threat intelligence.
Mobile security software encompasses applications, platforms, and services engineered to protect smartphones, tablets, and connected endpoints from malware, network intrusion, data exfiltration, and unauthorized access through cryptographic protocols, runtime application self-protection, and continuous authentication mechanisms. Its primary purpose is to safeguard enterprise and consumer data across distributed mobile workforces. Endpoint protection and threat intelligence solutions command the deepest margin pools as organizations prioritize proactive defense over reactive remediation. Cloud-based deployment is expanding fastest as financial institutions and telecommunication providers abandon capital-intensive on-premises architectures for scalable SaaS delivery models.
The U.S. SEC enforces disclosure requirements for material cybersecurity incidents that directly elevate mobile security procurement in regulated sectors. The EU AI Act and GDPR impose algorithmic transparency and data sovereignty standards that reshape how threat intelligence platforms process cross-border mobile telemetry. Japan's METI publishes guidelines for IoT and mobile device security that influence procurement specifications across Asia-Pacific supply chains. Stakeholders must weigh the trade-off between centralized cloud-native architectures and fragmented hybrid deployments as regulatory jurisdictions multiply compliance obligations.
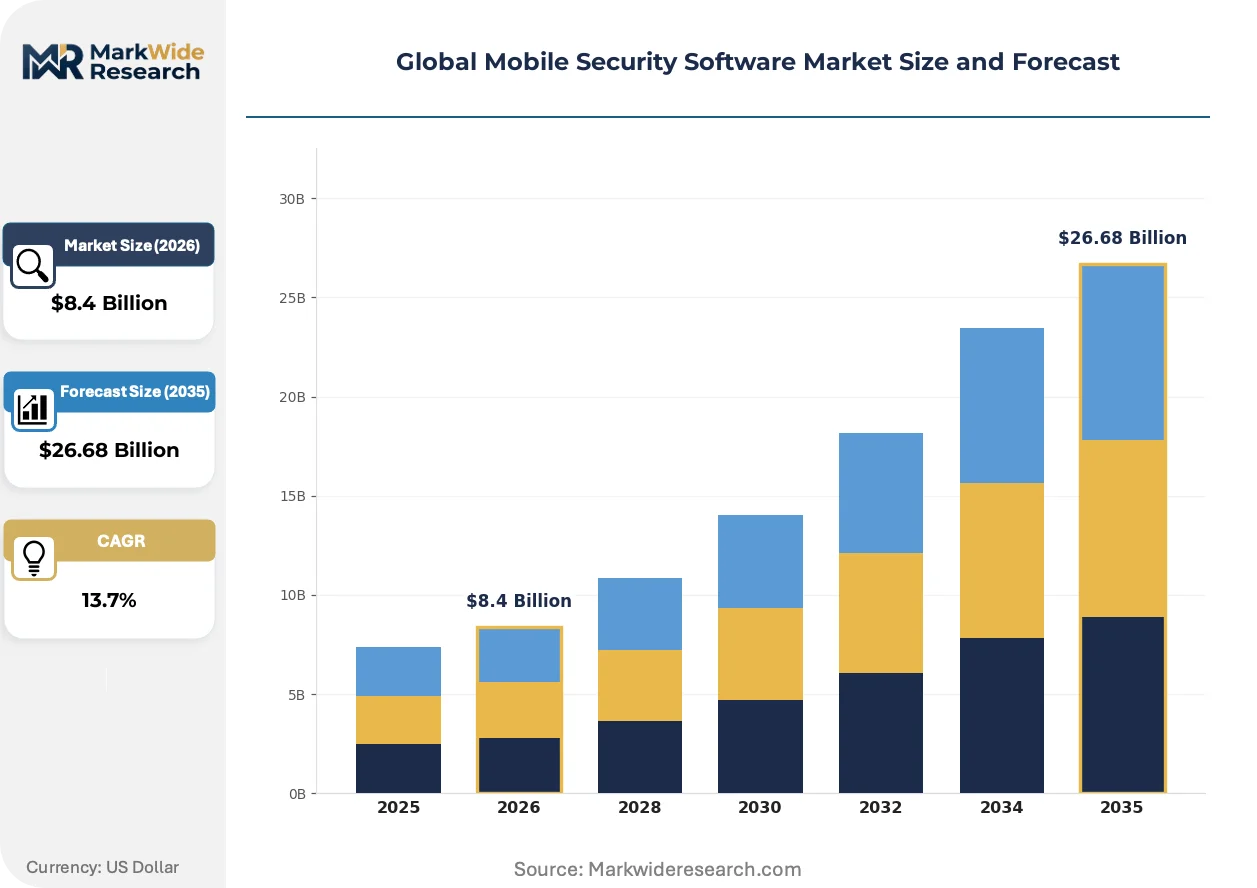
Market Dynamics
Zero-trust security architectures are dismantling perimeter-based defenses across enterprise mobility stacks, forcing vendors to embed continuous authentication and runtime protection directly into endpoint software layers rather than network gateways.
Growth Catalysts
- SEC Cybersecurity Disclosure Rules:Material incident reporting mandates from the U.S. Securities and Exchange Commission compel publicly traded financial institutions to harden mobile endpoint telemetry and audit trails.
- Bring-your-own-device proliferation:Enterprise workforces accessing corporate cloud resources via personal smartphones and tablets expand the attack surface requiring agent-based mobile threat defense.
- EU AI Act algorithmic transparency:Cross-border threat intelligence platforms must rearchitect data processing pipelines to satisfy European Union mandates on automated decision-making in security analytics.
Market Restraints
- Cloud infrastructure concentration:Dominant hyperscaler control over mobile security SaaS delivery creates single-point-of-failure risk and vendor lock-in for enterprise subscribers.
- Specialized talent scarcity:Shortage of professionals combining mobile operating system internals expertise with adversarial machine learning knowledge inflates implementation costs.
- False positive fatigue:Behavioral analytics engines generating excessive benign alerts degrade security operations center efficiency and erode trust in automated response systems.
Strategic Opportunities
- India digital payment expansion:Unified Payments Interface volume growth and RBI mobile banking security guidelines create unmet demand for indigenous threat detection platforms.
- 5G network slicing security:Convergence of edge computing and network function virtualization enables real-time malware containment at the radio access network layer.
- Japan METI IoT guidelines:Procurement specifications mandating device attestation for connected endpoints open adjacent markets for mobile-to-IoT security convergence.
Industry Challenges
- Certificate pinning complexity:Mobile application developers struggle to implement and rotate cryptographic certificates without breaking legitimate user connectivity across fragmented Android and iOS versions.
- Interoperability with legacy MDM:Enterprises maintaining on-premises mobile device management infrastructure face integration friction when layering cloud-native threat detection atop existing policy engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Security Software Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution/Offering: Mobile Antivirus, Endpoint Protection, Data Encryption, Mobile Device Management, Threat Intelligence Application: Secure Messaging, Mobile Banking, Enterprise Mobility, Location Tracking, Access Control Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services End User: Financial Institutions, Government Agencies, Retail Chains, Telecommunication Providers |
| Companies Covered | Microsoft Corporation, CrowdStrike Holdings, Inc., Symantec Corporation (Broadcom Inc.), Trend Micro Inc., Sophos Group PLC, McAfee Corp., Kaspersky Lab, Inc., International Business Machines Corporation (IBM), Check Point Software Technologies Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Security Software Market Shifts & Advancements
Artificial intelligence is compressing detection latency windows while regulatory fragmentation forces architectural compromises between centralized cloud processing and sovereign data residency requirements.
On-device machine learning inference is automating malware classification at the endpoint without cloud round-trip delays. Telecommunication providers deploying 5G standalone cores are embedding these lightweight neural models directly into subscriber identity modules. This architecture is automating threat containment decisions at the network edge, reducing reliance on centralized security operations centers for routine incident response.
Japan's METI publishes iterative security guidelines that explicitly reference mobile device management and application sandboxing requirements. Japanese automotive and electronics manufacturers extending supply chain security audits downstream to component vendors now mandate mobile security certification for supplier-facing collaboration platforms. Original equipment manufacturers in Toyota City and Osaka industrial corridors are responding by pre-installing government-aligned endpoint protection on enterprise-issued devices.
Subscription fatigue among small and medium enterprises is fragmenting purchasing authority away from centralized IT departments toward line-of-business units. Chief financial officers in mid-market financial services firms now evaluate mobile security spend against revenue protection metrics rather than compliance checklists. This behavioral pivot is most visible in German Mittelstand manufacturing clusters, where plant managers procure endpoint protection through operational technology budgets independent of corporate cybersecurity procurement channels.
Global Mobile Security Software Market Segmentation
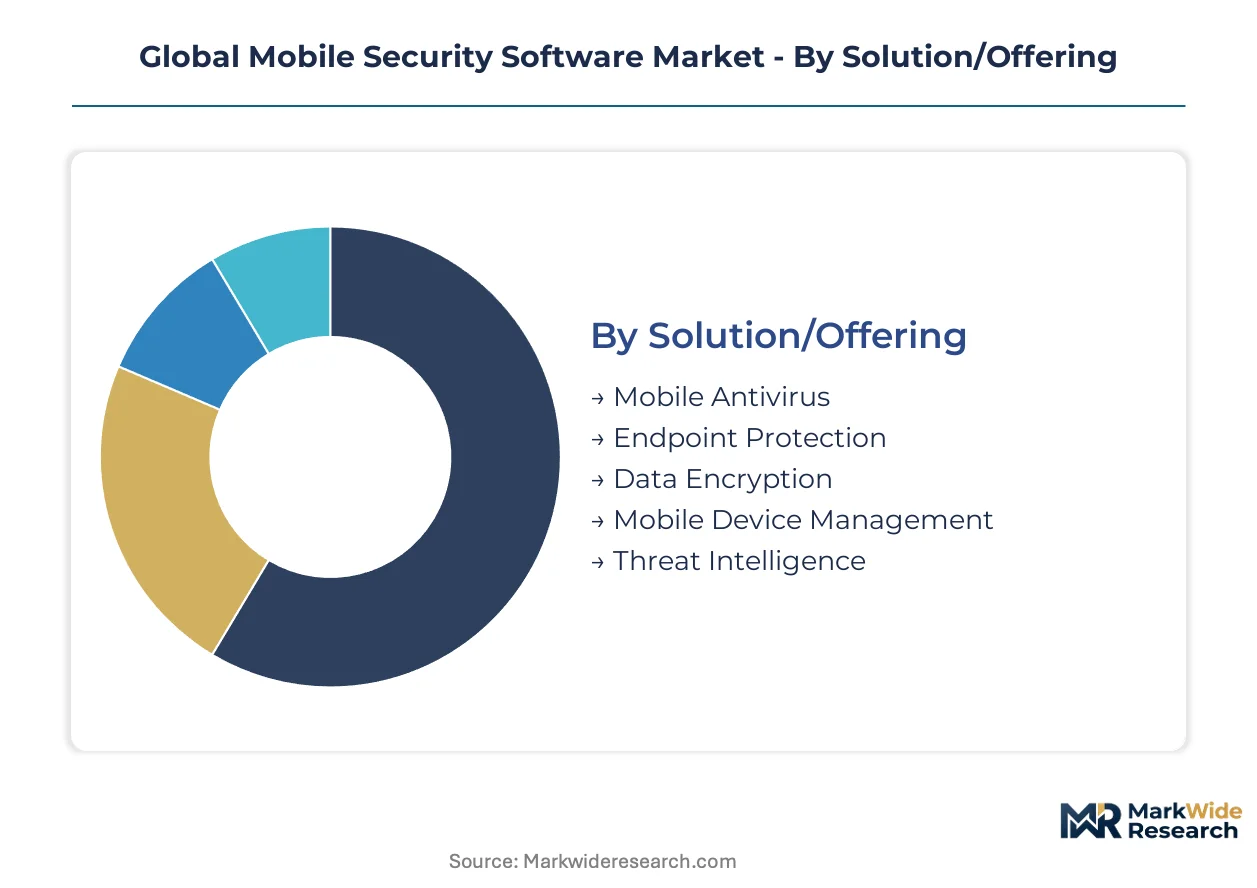
Mobile security software procurement patterns diverge sharply across solution architectures, with regulatory mandates from the SEC, EU AI Act, and METI driving certification requirements that reshape vendor selection criteria. Understanding these segment boundaries enables stakeholders to align compliance obligations with deployment economics.
Solution/Offering:
Certification burdens cluster heaviest in endpoint protection and threat intelligence, where SOC 2 Type II and ISO 27001 attestations are table stakes for financial services procurement.
- Mobile Antivirus:Signature-based scanning engines with heuristic augmentation target consumer and small-business segments. Demand concentrates in retail banking mobile applications where RBI and SEC disclosure rules elevate baseline protection requirements.
- Endpoint Protection:Agent-based platforms integrating runtime application self-protection and continuous device attestation. Financial institutions in the United States and Germany prioritize these solutions to satisfy zero-trust architecture mandates and GDPR Article 32 technical measures.
- Data Encryption:Cryptographic protocols securing data-at-rest and data-in-transit across mobile endpoints.
- Mobile Device Management:Policy enforcement and remote wipe capabilities for enterprise-issued and BYOD deployments.
- Threat Intelligence:Feeds correlating mobile-specific indicators of compromise with nation-state and criminal actor tactics.
Leading the category by volume: Endpoint Protection. Growing fastest: Threat Intelligence.
Application:
Cost tier stratification separates enterprise mobility deployments commanding premium pricing from commoditized location tracking solutions.
- Secure Messaging:End-to-end encrypted communication platforms with ephemeral content and screenshot prevention. Healthcare and government agencies in Germany and Japan drive demand under BSI and METI confidentiality guidelines.
- Mobile Banking:Application hardening, certificate pinning, and anti-tampering controls protecting financial transactions. Indian UPI expansion and RBI security directives generate the steepest volume trajectory among application segments.
- Enterprise Mobility:Cross-platform security for BYOD and corporate-issued devices accessing cloud resources.
- Location Tracking:Geofencing and asset monitoring with privacy-preserving data minimization.
- Access Control:Biometric and behavioral authentication for mobile workforce resource provisioning.
Highest-margin deployments: Enterprise Mobility. Expanding most quickly: Mobile Banking.
Deployment:
Volume concentration favors cloud-based delivery as telecommunication providers abandon capital-intensive infrastructure.
- Cloud-Based:SaaS-delivered security orchestration with elastic scaling and centralized telemetry. Financial institutions in the United States and Japan dominate subscription volumes, driven by SEC incident disclosure rules and METI cloud security guidelines.
- On-Premises:Air-gapped installations for classified government and defense environments. German government agencies under BSI IT-Grundschutz mandates sustain this segment despite broader cloud migration.
- Hybrid:Split architectures processing sensitive data locally while leveraging cloud analytics.
- Managed Services:Outsourced security operations center functions with guaranteed response time commitments.
Dominant by revenue: Cloud-Based. Gaining share fastest: Managed Services.
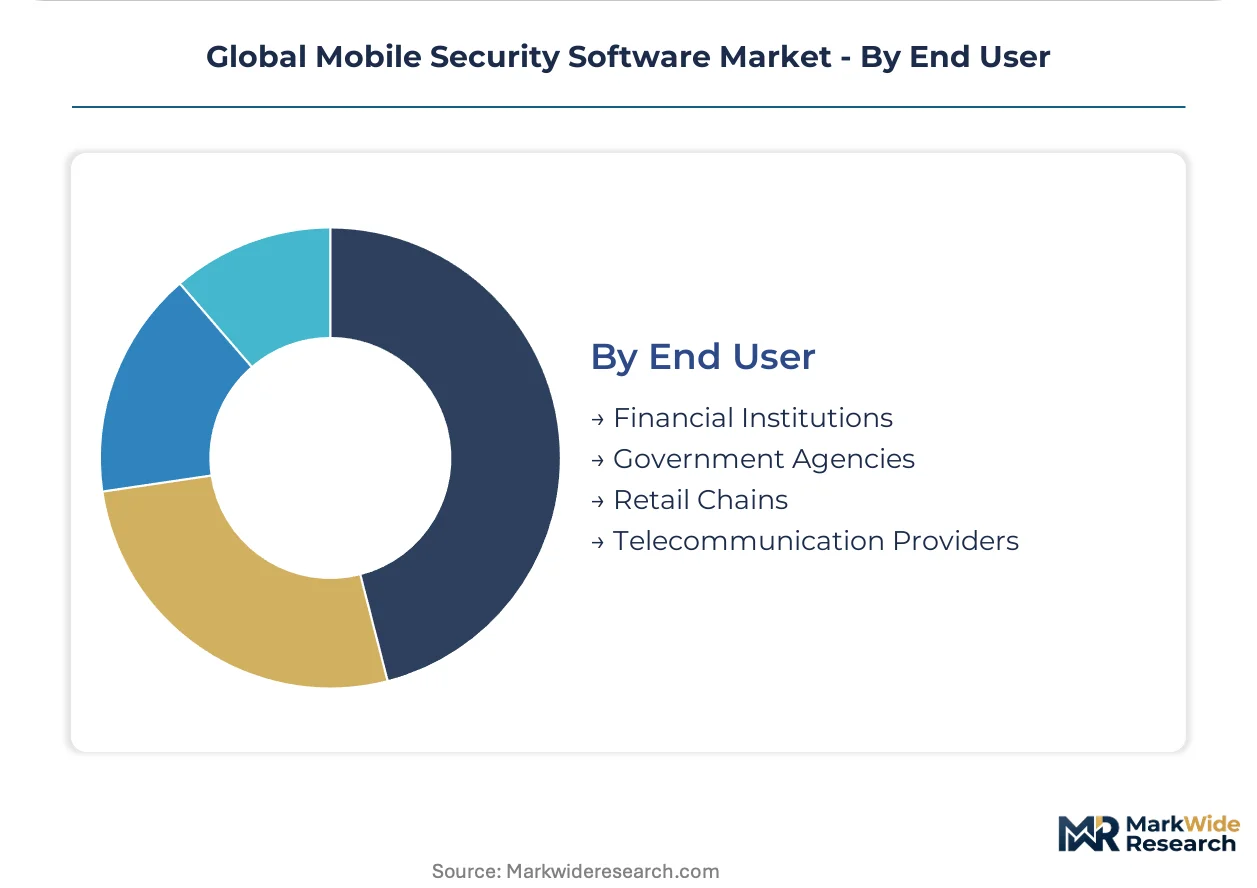
End User:
Customer type determines procurement authority, with financial institutions centralizing decisions under CISOs while retail chains fragment purchasing to line-of-business units.
- Financial Institutions:Tier-1 banks and insurance carriers with dedicated mobile security budgets. United States and European institutions under SEC and EU AI Act algorithmic transparency mandates drive the deepest investment per endpoint.
- Government Agencies:Federal, state, and municipal entities with classified and unclassified mobility requirements. Japanese ministries following METI procurement specifications and German agencies under BSI compliance sustain steady demand.
- Retail Chains:Point-of-sale and inventory management mobile deployments with cost-constrained protection.
- Telecommunication Providers:5G network slicing and subscriber identity module security for consumer and enterprise markets.
Largest absolute spend: Financial Institutions. Fastest budget growth: Telecommunication Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's concentration of venture capital and cybersecurity talent accelerates mobile security software development. The United States, Germany, Japan, India, and the United Kingdom concentrate procurement authority and regulatory innovation.
United States
Financial institutions in New York and San Francisco drive enterprise mobility deployments. SEC cybersecurity disclosure rules compel publicly traded banks to harden mobile endpoint telemetry. Boston's cybersecurity cluster generates behavioral analytics engines for real-time threat detection.
Germany
Automotive and industrial manufacturers anchor demand for zero-trust mobile architectures. BSI IT-Grundschutz mandates shape procurement specifications for federal agencies. Bavaria's Mittelstand manufacturing clusters fragment purchasing authority toward plant-level operational technology budgets.
Japan
Automotive supply chains and electronics manufacturers generate concentrated demand. METI publishes iterative security guidelines referencing mobile device management and application sandboxing. Toyota City and Osaka industrial corridors pre-install government-aligned endpoint protection on enterprise devices.
India
Unified Payments Interface volume expansion creates unmet demand for indigenous threat detection platforms. RBI mobile banking security guidelines elevate baseline protection requirements. Bengaluru and Mumbai fintech clusters drive procurement of application hardening and anti-tampering controls.
United Kingdom
Financial services and telecommunications providers dominate cloud-based security orchestration subscriptions. GDPR Article 32 technical measures reshape how threat intelligence platforms process cross-border mobile telemetry. London's cybersecurity vendor ecosystem concentrates AI-driven behavioral analytics development.
Global Mobile Security Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with cloud-native platforms commanding premium pricing over on-premises alternatives. The vendor base organizes into three tiers: hyperscale cloud providers embedding security layers across infrastructure stacks, pure-play cybersecurity specialists delivering AI-driven threat detection, and legacy endpoint protection vendors transitioning subscription models. Dominant competitive moves include strategic partnerships with telecommunications providers for 5G network slicing integration and portfolio diversification into adjacent IoT security domains.
Within the pure-play cybersecurity tier, CrowdStrike Holdings, Inc. and Kaspersky Lab, Inc. exemplify divergent strategic positioning. Microsoft Corporation anchors the hyperscale tier through cloud infrastructure integration. These three entities represent distinct archetypes: behavioral analytics specialization, deep malware research capabilities, and platform ecosystem leverage respectively.
| Leading Market Players |
|---|
| Microsoft Corporation |
| CrowdStrike Holdings, Inc. |
| Symantec Corporation (Broadcom Inc.) |
| Trend Micro Inc. |
| Sophos Group PLC |
| McAfee Corp. |
| Kaspersky Lab, Inc. |
| International Business Machines Corporation (IBM) |
| Check Point Software Technologies Ltd |
| Others |
Supply & Pricing Matrix
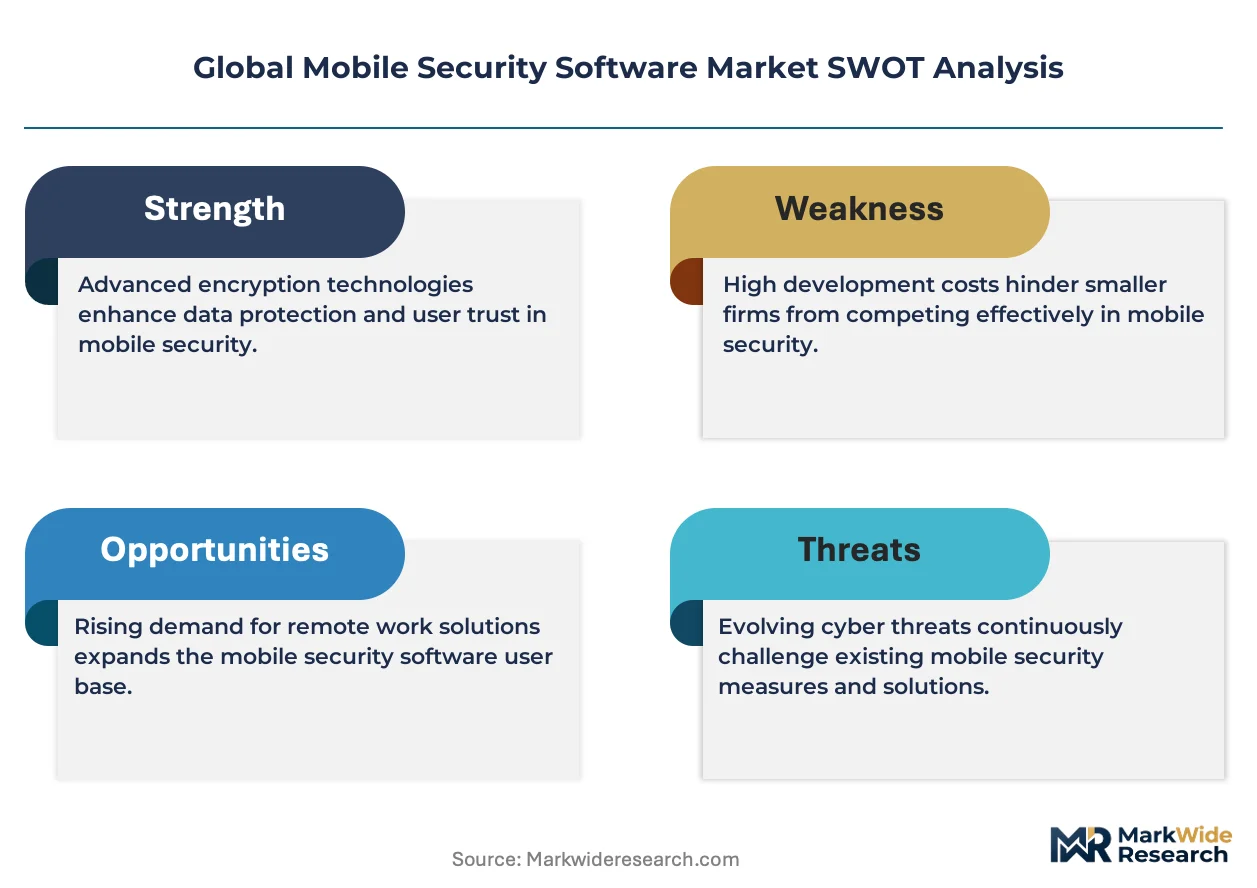
SEC disclosure mandates compelling financial institutions to harden mobile endpoint telemetry are forcing vendors to absorb compliance certification costs, compressing margins on standard-tier SaaS subscriptions while creating pricing power for SOC 2 Type II attested premium offerings.
Pricing Analysis
Short lead-time provisioning for threat intelligence feeds commands 15-25 percent premiums over standard 30-day implementation cycles in the mobile security software market. Subscription-based SaaS tiers dominate, with price differentiation anchored in ISO 27001 certification grade and integration complexity with legacy mobile device management stacks. Pricing pressure stems from hyperscaler bundling of security layers into cloud infrastructure contracts, eroding standalone vendor margins. Small and medium enterprises exhibit acute price sensitivity, while tier-1 financial institutions prioritize compliance-grade solutions regardless of cost tier.
Supply Chain Analysis
Freight and data residency compliance costs for cross-border threat intelligence telemetry are escalating as EU AI Act algorithmic transparency mandates fragment processing architectures. Software development concentrates in the United States, India, and Israel, with cloud infrastructure provisioning drawing from hyperscaler data centers in Germany, Japan, and Singapore. Supply chain risk centers on single-source dependency for AI training datasets and nation-state threat intelligence feeds. Distribution runs through direct enterprise sales teams and telecommunications provider channel partnerships for 5G-embedded security modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Control over upstream threat intelligence sourcing and downstream telecommunications integration channels is becoming the decisive competitive moat in mobile security software, with vendors racing to secure exclusive data feed partnerships and SIM-embedded deployment pathways.
For Market Incumbents: To counter hyperscaler bundling of security into cloud infrastructure contracts, deepen exclusive partnerships with telecommunications providers for 5G network slicing integration and accelerate certification investment for EU AI Act algorithmic transparency compliance to defend premium pricing tiers. For New Entrants and Emerging Players: Enter via India's Unified Payments Interface expansion corridor, where RBI mobile banking security guidelines have outpaced indigenous threat detection platform supply. Target mid-market German Mittelstand manufacturers through operational technology procurement channels rather than centralized IT departments. For Investors and Strategic Acquirers: The window for entry favors pure-play behavioral analytics specialists with on-device machine learning inference capabilities and established telecommunications provider distribution relationships. Watch for inflection signals in 5G standalone core deployment timelines among tier-1 carriers.| Strategic Initiative | Industry Significance |
|---|---|
| Telecommunications Partnership | 5G network slicing integration embeds security at radio access network layer for real-time containment. |
| Regulatory Certification Investment | SOC 2 Type II and EU AI Act compliance unlocks tier-1 financial institution procurement pipelines. |
| On-Device AI Development | Lightweight neural models in subscriber identity modules eliminate cloud round-trip latency for threat classification. |
| Threat Intelligence Feed Expansion | Exclusive nation-state and criminal actor tactic databases differentiate behavioral analytics engines. |
| Geographic Market Expansion | India UPI volume growth and RBI guidelines create unmet demand for indigenous platform deployment. |
Research Methodology
Document review covered SEC cybersecurity disclosure filings, EU AI Act regulatory texts, METI security guidelines, and RBI mobile banking directives, complemented by interviews with chief information security officers at tier-1 financial institutions, telecommunications provider security architects, mobile device management procurement leads, and threat intelligence platform engineers. Secondary sources included hyperscaler capex disclosures, ISO certification databases, and customs records for telecommunications equipment with embedded security modules. Bottom-up endpoint deployment estimates were triangulated against top-down SaaS subscription revenue analysis.
Historical adoption curves for zero-trust architecture migration were cross-referenced against panel input from enterprise mobility deployment specialists across the United States, Germany, and Japan. The analytical framework modeled segmentation across deployment model, organization size, vertical industry, integration complexity with legacy infrastructure, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted penetration projections and compliance-mandated replacement cycle acceleration. Industry-specific inputs included 5G standalone core deployment schedules and financial institution SEC disclosure incident frequency.
Revisions become necessary when telecommunications provider infrastructure rollouts stall, regulatory jurisdictions introduce conflicting data sovereignty requirements, or hyperscaler bundling strategies materially alter standalone vendor addressable markets. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Saudi Arabia Managed Security Services Market
Security Software
Europe User Provisioning Market
Security Software
Secaas Market
Security Software
Antivirus Software Package Market
Security Software
Europe Video Management System Market
Security Software
Devsecops Market
Security Software
Remote Access Management Market
Security Software
Europe Encryption Software Market
Security Software
US Hardware OTP Token Authentication Market
Security Software
Network Camera and Video Analytics Market
Security Software
DC and PKI Market
Security Software
Global Data Breach Notification Software Market
Security Software
Security Software Market
Security Software
Global SMS Firewall Market
Security Software
Secure Email Gateway Market
Security Software
Automotive Endpoint Authentication Market