
 Europe Video Management System Market | 2026-2036
Europe Video Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Video Management System Market Insights
IP-to-cloud migration is reconfiguring how video management platforms store, process, and distribute surveillance data across distributed architectures. Milestone Systems leverages its open-platform architecture to sustain developer ecosystem loyalty across Nordic deployments. Bosch Security and Safety Systems anchors its competitive position through in-house camera-to-software integration, while Axis Communications specializes in edge-computing camera endpoints that reduce central server loads.
A Video Management System constitutes software infrastructure that ingests, records, indexes, and retrieves digital video streams from IP cameras and encoders, typically supporting H.265 compression and ONVIF protocol interoperability for multi-vendor hardware compatibility. Its primary commercial purpose centers on enabling organizations to monitor physical spaces, investigate incidents, and operationalize video-derived intelligence for security and process optimization. Cloud-based and hybrid deployments represent the fastest-expanding architecture categories as enterprises seek elastic storage without fully surrendering on-premises control over sensitive footage. Among end-user verticals, government and transportation applications command the deepest investment cycles due to critical infrastructure protection mandates and public safety funding priorities.
The EU AI Act imposes strict conformity requirements on biometric identification systems, directly shaping product roadmaps for analytics modules sold into European jurisdictions. GDPR and the proposed Cyber Resilience Act further constrain data retention architectures and mandate security-by-design certifications, raising compliance barriers for non-European suppliers. Stakeholders must weigh the cost of modular AI governance tooling against the risk of exclusion from public-sector procurement frameworks that now embed algorithmic accountability clauses.
Market Dynamics
The EU AI Act is compressing product development cycles for biometric analytics modules, forcing vendors to embed conformity-by-design into software architectures before public-sector procurement gates close to non-compliant systems.
Growth Catalysts
- Smart city infrastructure mandates:German municipal authorities are accelerating centralized video platform procurement to meet federal digital infrastructure targets for public safety networks.
- GDPR-compliant edge processing:Demand for localized video analytics is pulling investment toward edge-computing camera deployments that minimize cross-border data transfers.
- Rail modernization programs:French and British rail operators are replacing legacy analog surveillance with IP-based platforms to satisfy critical infrastructure protection requirements.
Market Restraints
- Semiconductor supply concentration:Dependence on Asian foundries for AI accelerator chips creates vulnerability in encoder and edge device manufacturing pipelines.
- Cyber Resilience Act compliance costs:Mandatory security-by-design certifications impose fixed overhead that disproportionately burdens mid-tier software vendors.
- Cloud storage substitution pressure:Hyperscale cloud providers are bundling native video services that compete with specialized VMS platforms on price elasticity.
Strategic Opportunities
- Eastern European underpenetration:Polish and Romanian municipal governments lack mature surveillance networks, creating first-mover advantages for compliant platform vendors.
- AI-Act regulatory tailwind:Algorithmic accountability clauses in EU public procurement frameworks favor suppliers with pre-certified biometric governance tooling.
- 5G-IoT convergence:Integration of cellular-connected sensors with video platforms enables real-time situational awareness for transportation and utility operators.
Industry Challenges
- Embedded systems cybersecurity expertise:Shortage of engineers qualified in IEC 62443 standards for industrial control systems slows secure-by-design implementation.
- Legacy analog integration complexity:Hybrid deployments require custom protocol bridges that extend deployment timelines and inflate professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Video Management System Market |
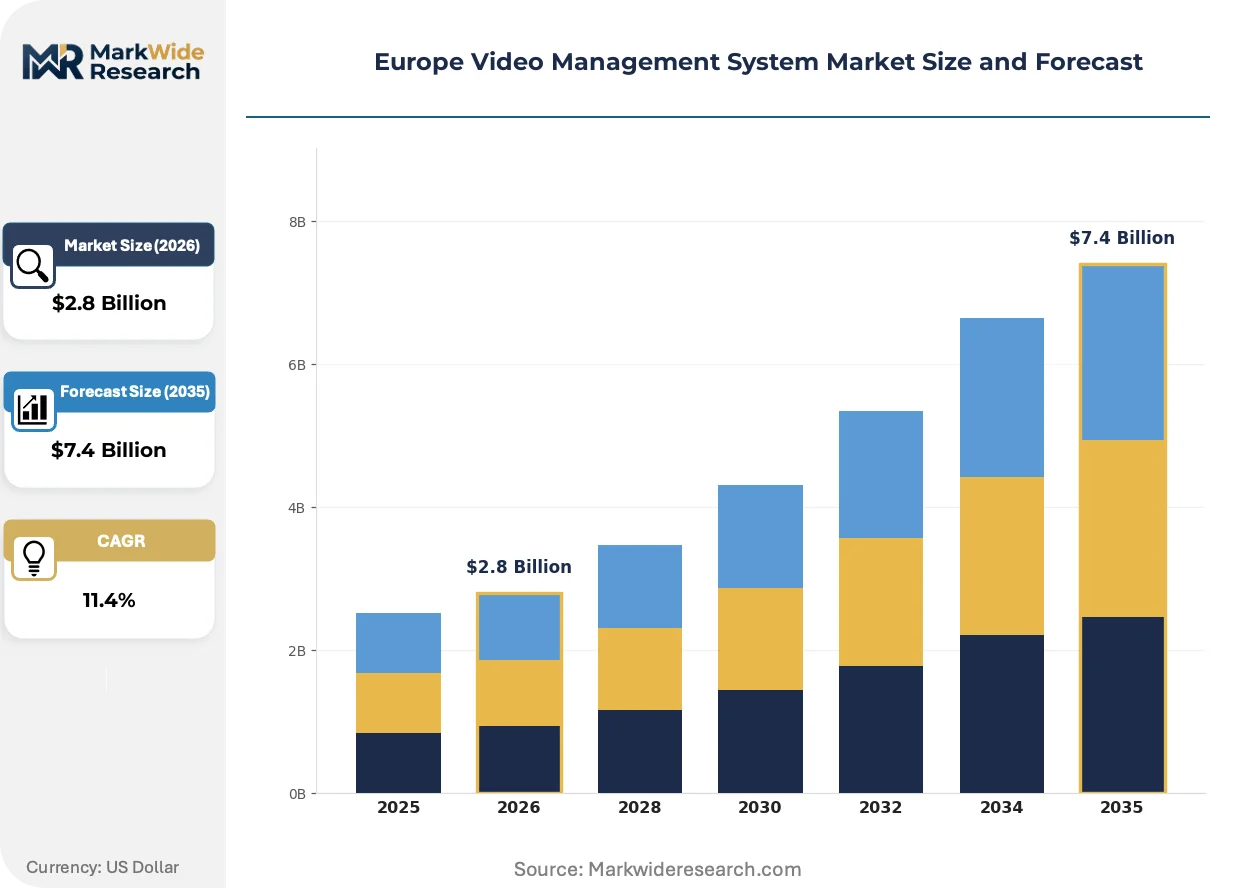
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premises, Hybrid, Software as a Service End User: Retail, Transportation, Government, Healthcare Deployment: Public Cloud, Private Cloud, Onsite, Virtualized Feature: Real-time Analytics, Remote Monitoring, Centralized Management, Motion Detection |
| Companies Covered | Honeywell International Inc, Bosch Security and Safety Systems, Johnson Controls, Axis Communications AB, Genetec Inc, Hangzhou Hikvision Digital Technology Co., Ltd, Milestone Systems, Verint Systems, Dahua Technology, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Video Management System Market Trends and Innovations
Video management architectures are fragmenting across three vectors: computational geography, regulatory jurisdiction, and procurement modality. Each shift carries distinct implications for vendor business models and buyer total cost of ownership.
Edge-native AI inference is collapsing the traditional hierarchy between camera, server, and cloud tiers. Transportation authorities in France are deploying H.265-enabled endpoints with onboard object classification, reducing bandwidth consumption and central server licensing requirements. This compression of the compute stack is enabling smaller municipalities to operate enterprise-grade surveillance without dedicated data center investments.
The EU AI Act's biometric identification conformity requirements are reshaping product roadmaps for analytics vendors serving European jurisdictions. Systems deployed for law enforcement or border control must now complete third-party conformity assessments before commercialization. German security integrators are prioritizing suppliers with pre-certified modules to avoid procurement disqualification in federal and state tenders.
Subscription-based platform licensing is displacing perpetual software ownership in municipal and enterprise accounts. French and British transportation authorities are favoring operational expenditure models that bundle maintenance, updates, and elastic cloud storage. This shift compresses upfront capital requirements while locking vendors into multi-year service relationships with stringent uptime guarantees.
Europe Video Management System Market Segmentation
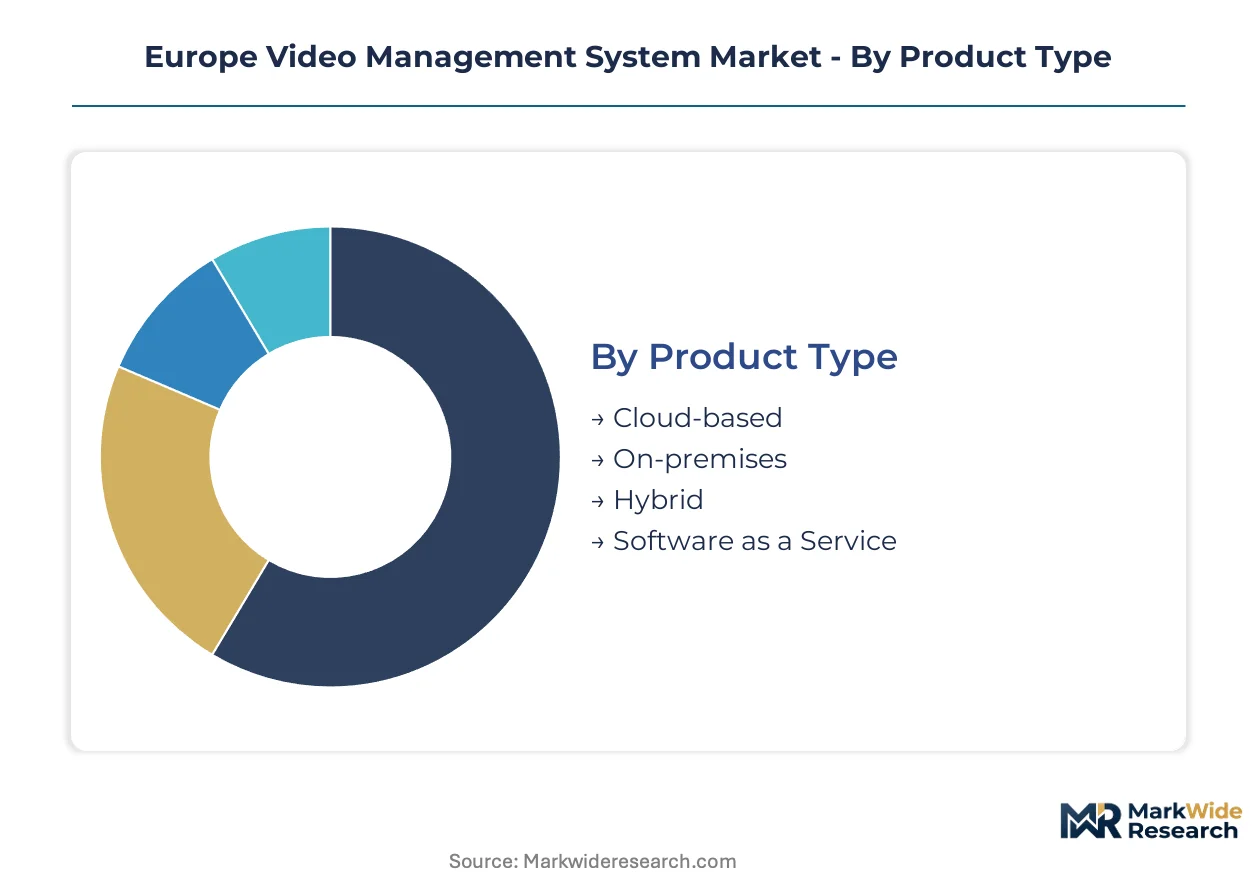
Video management platforms fragment across infrastructure topology, buyer sophistication, and regulatory exposure. Each segmentation axis determines procurement modality, margin structure, and compliance burden for vendors operating across European jurisdictions.
Product Type:
After-sales service intensity varies sharply across deployment architectures, with cloud-native platforms demanding continuous subscription support while on-premises systems require episodic upgrade cycles.
- Cloud-based:Multi-tenant architectures eliminate local server maintenance while shifting liability for uptime and data sovereignty to vendor operations centers. German municipal authorities favor these platforms for elastic scaling during major public events without capital-intensive infrastructure expansion.
- On-premises:Perpetual licensing models with dedicated hardware stacks retain full data custody within organizational firewalls. French defense contractors and nuclear facility operators mandate these deployments to satisfy classified information handling protocols.
- Hybrid:Tiered storage policies archive sensitive footage locally while pushing analytics workloads to cloud regions with GDPR adequacy decisions. British rail operators deploy hybrid stacks to balance real-time edge processing with centralized incident review capabilities.
- Software as a Service:Fully managed subscriptions bundle encryption key rotation, patch management, and API maintenance into per-camera pricing. Polish mid-market retailers adopt SaaS to avoid cybersecurity competency gaps in internal IT departments.
On-premises architectures hold the largest share; momentum sits with hybrid deployments gaining share fastest.
End User:
Buyer procurement sophistication determines feature bundling and contract duration, with government tenders demanding algorithmic accountability tooling that retail accounts rarely specify.
- Transportation:Mission-critical uptime requirements drive redundant failover architectures and 99.99% availability SLAs. French and British rail modernization programs specify IP-based platforms with onboard edge analytics to reduce bandwidth consumption across remote trackside locations.
- Government:EU AI Act conformity assessments mandate third-party certification for biometric identification modules before federal procurement eligibility. German state police forces require pre-certified facial recognition governance tooling to avoid tender disqualification.
- Retail:Loss prevention and customer flow optimization prioritize cost-per-camera metrics over advanced analytics. Romanian shopping center operators deploy entry-level cloud subscriptions with motion-based alerting rather than AI-powered behavioral analysis.
- Healthcare:Patient privacy constraints under GDPR limit retention periods and mandate anonymization for secondary analytics use. British NHS trusts favor private cloud deployments with clinical-grade encryption for ward monitoring and pharmacy security.
Government verticals command the deepest investment cycles; retail adoption is climbing the fastest as SaaS pricing penetrates mid-market accounts.
Deployment:
Infrastructure location decisions directly determine latency, sovereignty compliance, and total cost of ownership across multi-year operational horizons.
- Private Cloud:Single-tenant virtualized environments hosted in EU-regulated data centers satisfy data residency requirements for sensitive workloads. Dutch port authorities operate private cloud VMS to retain custody of customs and border surveillance footage.
- Public Cloud:Hyperscale provider infrastructure delivers elastic compute for analytics spikes without capacity planning. Italian regional governments leverage public cloud object storage for archival footage while keeping live monitoring on local servers.
- Onsite:Bare-metal installations in organizational data centers minimize external attack surfaces and third-party dependency. Swiss banking facilities mandate onsite deployments for trading floor surveillance under FINMA operational risk guidelines.
- Virtualized:Containerized VMS workloads running on existing enterprise hypervisors optimize hardware utilization. Belgian manufacturing conglomerates virtualize video management alongside ERP systems to consolidate data center footprints.
Onsite deployments retain dominant installed base; private cloud configurations are expanding most quickly among compliance-sensitive buyers.
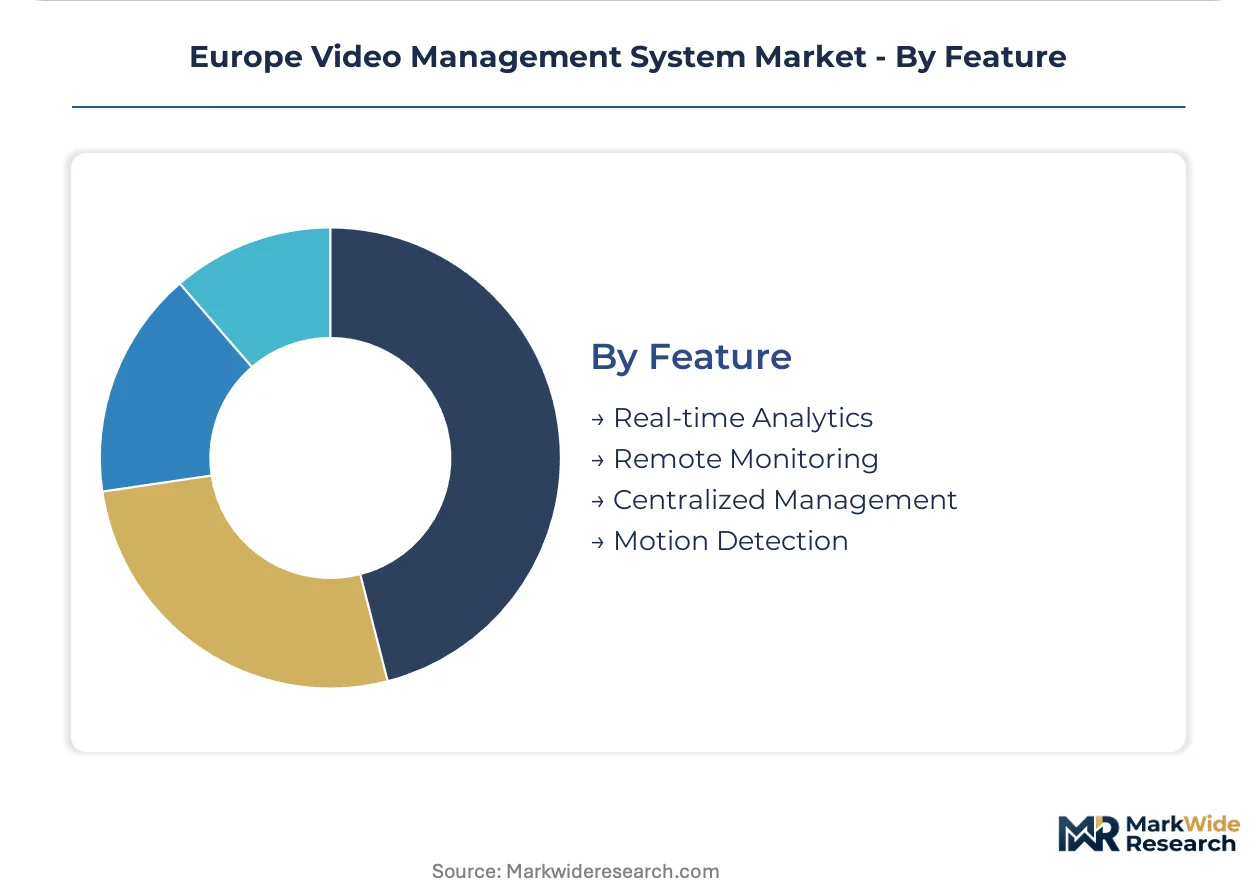
Feature:
Module selection reflects operational maturity, with advanced analytics requiring specialized calibration and ongoing algorithm governance that basic monitoring functions avoid.
- Real-time Analytics:On-camera inference engines classify objects and behaviors without central server round-trips, slashing bandwidth requirements. French transportation authorities deploy H.265 endpoints with onboard vehicle and pedestrian detection to enable immediate platform alerting.
- Centralized Management:Unified control planes aggregate thousands of distributed cameras into single-pane-of-glass operations. British critical infrastructure operators demand centralized architectures to coordinate multi-site security responses across energy and water utilities.
- Remote Monitoring:Mobile-optimized client applications extend situational awareness to field personnel and contracted security services. Spanish logistics providers equip drivers with remote monitoring access to depot surveillance during off-hours incident response.
- Motion Detection:Rules-based pixel-change algorithms trigger recording and alerting without computational overhead of AI classification. Hungarian small-business installers specify motion detection for cost-constrained convenience store deployments.
Centralized management holds the largest feature attachment rate; real-time analytics exhibits the steepest expansion trajectory as edge computing costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transportation authorities and municipal governments constitute the dominant buyer archetypes across European jurisdictions, with procurement concentrated in federal infrastructure programs and critical facility modernization mandates.
Germany
Rail operators and smart city planners drive platform procurement through federal digital infrastructure targets. The EU AI Act compels biometric analytics vendors to complete conformity assessments before state police tender eligibility. Bavarian municipal authorities deploy centralized video platforms across Munich and Nuremberg transit networks.
France
SNCF rail modernization and nuclear facility security upgrades sustain demand for hybrid deployment architectures. ANSM and CNIL guidance on healthcare surveillance constrains retention periods for hospital video systems. Paris-Île-de-France operators prioritize edge-computing endpoints to reduce bandwidth across regional express networks.
United Kingdom
Critical infrastructure operators and NHS trusts anchor procurement for private cloud and onsite deployments. GDPR adequacy decisions shape cross-border data handling for transportation analytics. London and Southeast utilities coordinate multi-site security responses through centralized management platforms.
Poland
Municipal governments and mid-market retailers represent underpenetrated demand for SaaS-based surveillance subscriptions. National cybersecurity standards align with EU Cyber Resilience Act pre-certification pathways. Warsaw and Krakow shopping center operators adopt entry-level cloud platforms for loss prevention.
Netherlands
Port authorities and logistics providers demand private cloud architectures for customs and border surveillance data custody. REACH and GDPR jointly constrain chemical facility monitoring system specifications. Rotterdam port operators retain footage sovereignty through single-tenant virtualized environments.
Europe Video Management System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a moderately consolidated structure where scale advantages in certification and federal procurement access separate tier-one vendors from regional integrators. Three archetypes dominate: open-platform ecosystem builders, vertically integrated hardware-software bundlers, and edge-native camera specialists. Competitive moves concentrate on strategic partnerships for AI governance tooling and geographic expansion into Eastern European municipal markets.
Among Denmark-based open-platform specialists, Milestone Systems exemplifies ecosystem-centric positioning through developer network cultivation. Bosch Security and Safety Systems, a German GmbH, anchors the integrated hardware-software archetype with captive camera-to-platform supply chains. Axis Communications AB, a Swedish entity, occupies the edge-computing endpoint tier with onboard inference capabilities that reduce central infrastructure dependency.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Bosch Security and Safety Systems |
| Johnson Controls |
| Axis Communications AB |
| Genetec Inc |
| Hangzhou Hikvision Digital Technology Co., Ltd |
| Milestone Systems |
| Verint Systems |
| Dahua Technology |
| Others |
Pricing and Supply Chain Analysis
Taiwanese foundry capacity for AI accelerator chips determines downstream pricing leverage for European VMS vendors sourcing edge-computing hardware. Cost-plus contracts with Taiwanese semiconductor suppliers index pricing to wafer utilization rates, compressing margins when foundry loads spike. German municipal buyers face elongated procurement timelines as encoder manufacturers absorb foundry premium pass-throughs.
Pricing Analysis
Cost-plus contracts with Taiwanese foundry indexation anchor hardware procurement pricing for edge devices and AI accelerators. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-certified biometric modules from uncertified analytics and basic motion-detection subscriptions. Pricing pressure stems from hyperscale cloud providers bundling native video services at per-camera rates below specialized VMS platforms. Retail mid-market accounts exhibit highest price sensitivity, while German state police forces accept premium tiers for pre-certified governance tooling.
Supply Chain Analysis
Upstream feedstock for AI inference engines draws from Taiwanese and South Korean foundry output for GPU and NPU silicon, plus German and Dutch sensor fabs for imaging components. Raw material dependencies span 300mm silicon wafers, advanced packaging substrates, and rare earth elements for camera magnet assemblies. Single-source vulnerability concentrates in 7nm and below process nodes where only two foundries maintain commercial viability. Distribution runs through authorized security integrators in France and Germany, with direct OEM relationships penetrating British rail and Dutch port authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act fragmentation creates specialized vendor niches as compliance requirements diverge across member state procurement frameworks. Municipal buyers now segment between certified biometric governance suppliers and basic monitoring platforms.
For Market Incumbents: Build certification moats through third-party EU AI Act conformity assessments for biometric identification modules before competitor catch-up. Anchor defensive positioning by acquiring Eastern European system integrators with established municipal relationships in Poland and Romania. Threaten margin compression from hyperscale cloud entrants demands channel control reinforcement through exclusive distributor agreements. For New Entrants and Emerging Players: Pursue SaaS-based subscriptions in Polish and Romanian municipal markets where legacy analog underinvestment creates greenfield deployment opportunities. Target mid-market healthcare facilities in Spain and Italy seeking GDPR-compliant private cloud ward monitoring without capital-intensive infrastructure. Angle go-to-market through clinical engineering partnerships rather than traditional security integrators. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because EU AI Act enforcement depth will separate compliant platform vendors from commoditized hardware suppliers. Acquisition targets should display pre-certified biometric governance modules and established French or German federal procurement relationships. Signal to watch is Cyber Resilience Act implementation timeline accelerating consolidation among mid-tier software vendors unable to absorb certification overhead.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Pre-certified biometric modules unlock German state police and federal tender eligibility. |
| Eastern European Integrator Acquisition | Polish and Romanian municipal relationships provide first-mover platform deployment channels. |
| Edge-Native AI Inference Development | On-camera processing reduces bandwidth costs for French rail remote trackside locations. |
| Hybrid Cloud Architecture Expansion | Tiered storage policies satisfy British NHS data residency requirements for patient footage. |
| 5G-IoT Sensor Integration Partnership | Cellular-connected endpoints enable real-time Dutch port situational awareness applications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU procurement databases, vendor SEC disclosures, and member state critical infrastructure budgets. Primary interviews engaged VMS product managers, German municipal procurement officers, French rail security directors, Dutch port authority IT leads, and Polish system integrators. Secondary sources encompassed EU AI Act implementation guidance, GDPR adequacy decisions, Cyber Resilience Act draft texts, and transportation authority modernization tenders. Bottom-up camera shipment estimates triangulated against top-down software licensing revenue analysis.
Forecast inputs incorporate deployment model adoption curves, vertical procurement cycle timing, and regulatory compliance phase-in schedules across the analysis window. Segmentation dimensions modeled include infrastructure topology, end-user vertical, feature module attachment rates, and regional regulatory cluster. CAGRs derived from elasticity-adjusted growth rate synthesis. Industry-specific inputs span EU AI Act conformity assessment timelines and 5G network rollout schedules affecting edge device connectivity.
Macroeconomic conditions sit as an overlay; deviation in infrastructure investment cycles, semiconductor supply availability, or GDPR enforcement intensity would shift the trajectory. Cross-checking against national critical infrastructure budget allocations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Security Software Market
Security Software
Anti-Money Laundering (AML) Software Solution Market
Security Software
Anomaly Detection Tools Market
Security Software
AI Security Platforms Market
Security Software
Secaas Market
Security Software
Data Loss Prevention Market
Security Software
Risk-Based Authentication (RBA) Market
Security Software
Social Media Security Market
Security Software
North America Video Management System Market
Security Software
US Hardware Encryption Market
Security Software
Digital Risk Protection Platform Market
Security Software
Europe Enterprise Firewall Market
Security Software
Home Webcam Market
Security Software
Contactless Smart Card Market
Security Software
Network Video Recorder (NVR) Market
Security Software
Global User Provisioning Market