
 Security Software Market | 2026-2036
Security Software Market Size, Share, and Industry Trends Forecast 2026-2036
Security Software Market Intelligence
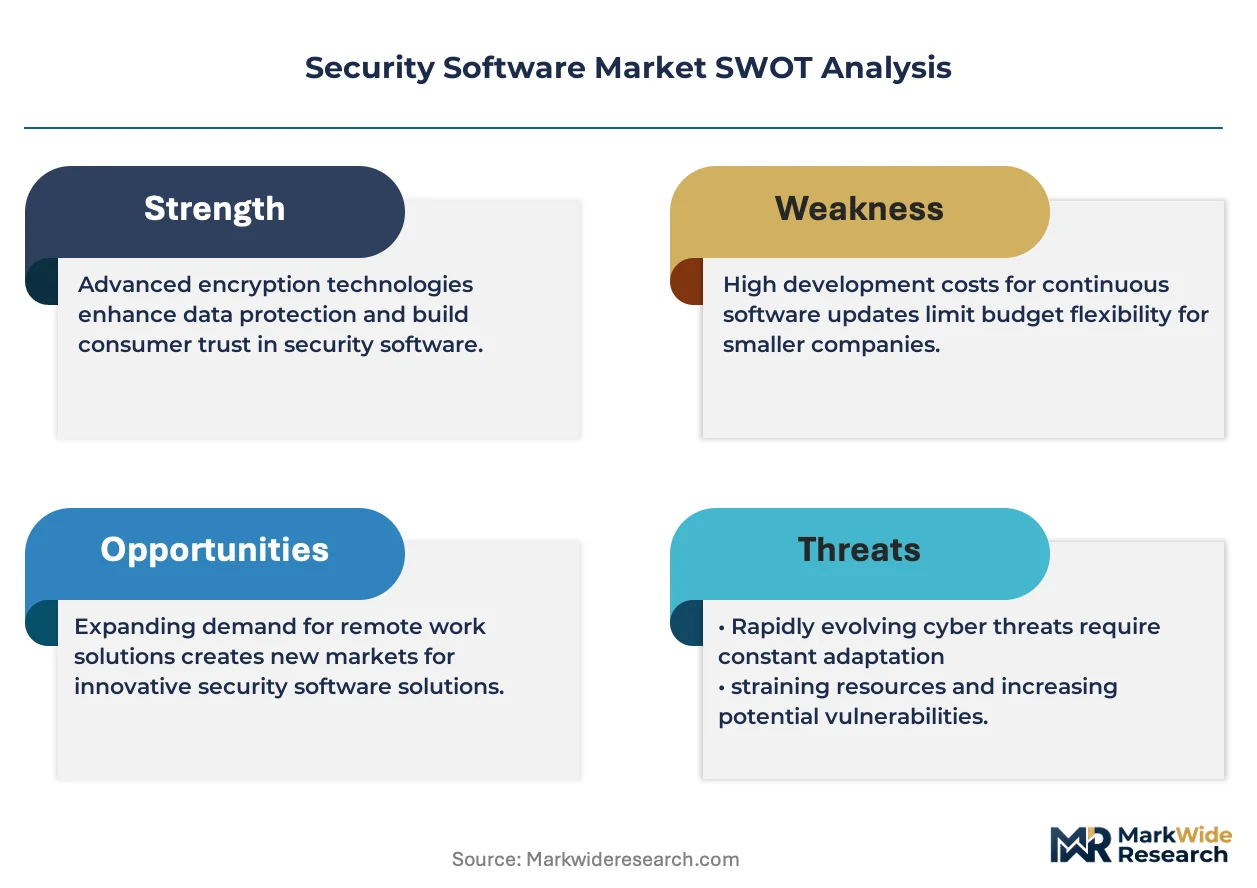
The shift toward zero-trust security architecture is collapsing the distinction between traditional network perimeters and individual endpoint protection. This paradigm is reshaping competitive positioning by demanding integrated, context-aware security solutions rather than siloed products. Palo Alto Networks leverages its comprehensive platform to address this change, while CrowdStrike specializes in cloud-native endpoint detection and response. Fortinet competes through its broad security fabric, which unifies diverse functions across network, cloud, and endpoint environments.
Security software encompasses a suite of applications designed to protect computer systems, networks, and data from malicious attacks and unauthorized access. Functionality relies on advanced methods including cryptographic protocols for data encryption and behavioral analytics for real-time threat detection. Cloud-Based deployment models dominate new sales, offering greater scalability than traditional on-premises installations. Among product types, Identity Management and Endpoint Protection software are experiencing significant investment, driven by remote work and complex IT environments.
Regulatory frameworks serve as a primary catalyst for market adoption, creating non-discretionary spending. The EU’s GDPR imposes strict data protection and breach notification standards, directly influencing demand for encryption and compliance monitoring software. In the United States, HIPAA mandates specific security controls for health information, while regulations in China require data localization. Vendor success depends on delivering solutions that can adapt to this fragmented and evolving global compliance landscape.
Market Dynamics
The imperative to secure distributed digital assets against increasingly sophisticated threats is the central force shaping the security software market. This pressure moves organizations toward unified platforms and zero-trust principles, away from fragmented, perimeter-based defense strategies.
Growth Catalysts
- Data Privacy Mandates:Stringent regulations, including the EU's GDPR and Brazil's LGPD, create non-discretionary demand for encryption, identity management, and data loss prevention software to ensure compliance and avoid significant financial penalties.
- Healthcare Digitization:The healthcare sector's adoption of electronic health records and telehealth, governed by rules like HIPAA in the United States, requires advanced security solutions to protect sensitive patient information from breaches.
- IoT Proliferation:The rapid expansion of Internet of Things (IoT) devices in industrial and consumer settings creates a vast new attack surface, driving demand for specialized endpoint protection and network segmentation tools to secure these connected systems.
Market Restraints
- Integration Complexity:The high technical complexity and cost of integrating diverse security products into a unified platform can be a significant barrier, particularly for small and medium-sized enterprises lacking dedicated IT security teams.
- Talent Scarcity:A persistent global shortage of skilled cybersecurity professionals limits the ability of organizations to effectively deploy, manage, and utilize advanced security software, constraining market potential.
- Legacy System Inertia:Securing legacy operational technology (OT) and industrial control systems, which were not designed with modern security in mind, presents considerable technical challenges and often requires costly and disruptive upgrades.
Strategic Opportunities
- Emerging Economies:Rapid digitalization in Southeast Asian nations, such as Indonesia and Vietnam, presents significant opportunities for vendors as businesses and governments invest in foundational cybersecurity infrastructure for the first time.
- AI Security:The growing adoption of artificial intelligence creates a new frontier for security solutions designed to protect AI models and data from adversarial attacks, data poisoning, and theft.
- Security and Observability Convergence:Integrating security data with IT observability platforms offers an opportunity to provide a unified view of system health and security posture, enabling faster, more context-aware threat response.
Industry Challenges
- Vendor Sprawl:Many organizations struggle with "alert fatigue" and operational inefficiency stemming from the use of dozens of disparate, non-integrated security tools, making it difficult to achieve a holistic security view.
- Rapid Threat Evolution:The continuous and rapid evolution of cyberattack techniques requires vendors to constantly innovate, forcing a difficult balance between developing new features and maintaining the stability of existing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Security Software Market |
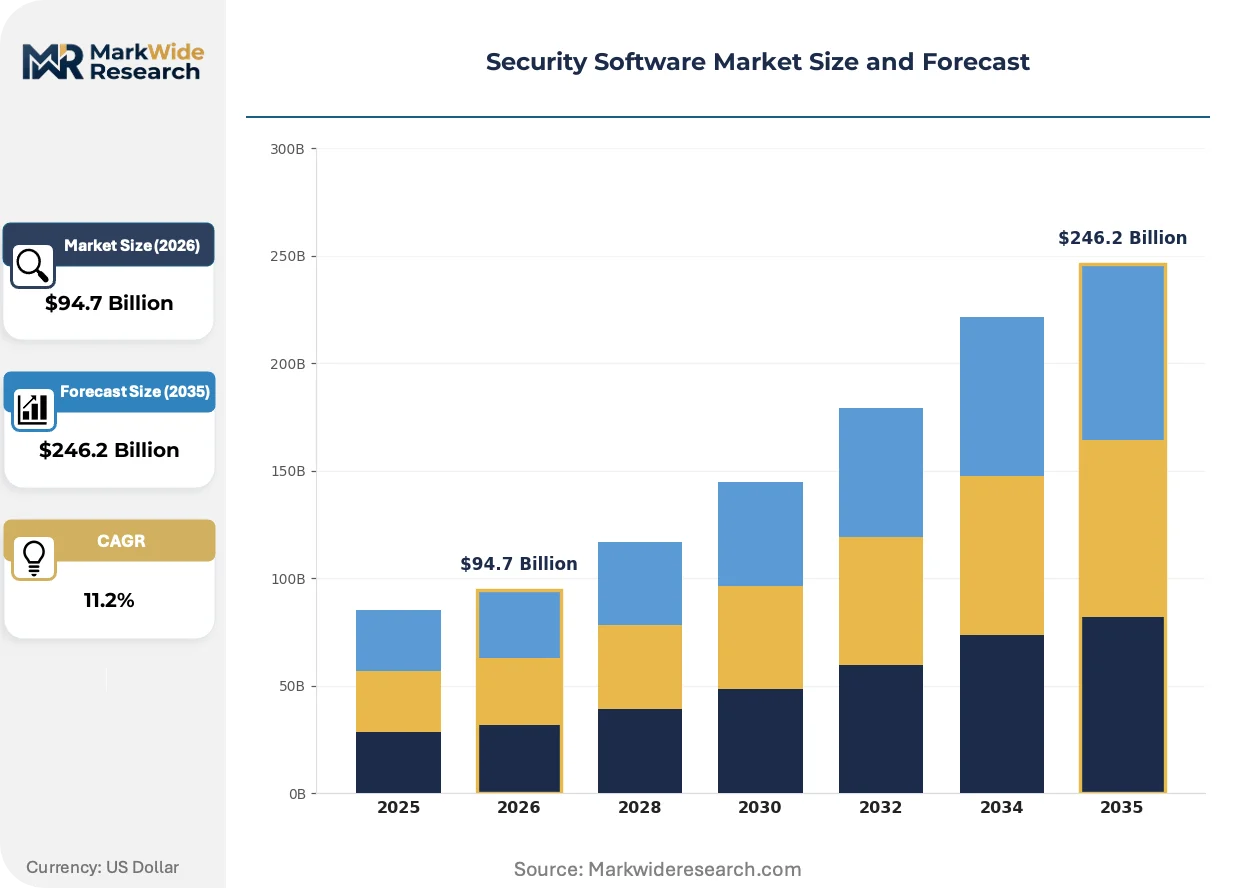
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $246.2 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antivirus, Firewall, Intrusion Detection, Encryption Software, Identity Management, Data Loss Prevention Deployment: On-Premises, Cloud-Based, Hybrid, Managed Security Service Providers Use Case: Threat Detection, Access Control, Risk Management, Compliance Monitoring, Network Security, Endpoint Protection End User Industry: Banking & Finance, Telecommunications, Government Bodies, Education Sector, Hospitality, Manufacturing |
| Companies Covered | Palo Alto Networks, CrowdStrike, Fortinet, Zscaler, Check Point Software Technologies, Okta, CyberArk, Broadcom, Trend Micro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Security Software Market Strategic Shifts & Innovations
Automation and artificial intelligence are fundamentally altering security operations, shifting the focus from manual threat hunting to orchestrated, machine-speed response. This enables security teams to manage an expanding and increasingly complex threat landscape with greater efficiency.
Extended Detection and Response (XDR) platforms function by integrating security telemetry from endpoints, networks, cloud workloads, and email systems. Enterprises in regulated industries like banking and government are adopting XDR to improve threat visibility. This integrated data approach is displacing traditional, siloed Security Information and Event Management (SIEM) tools by providing more automated, context-rich investigation capabilities.
The European Union's Digital Operational Resilience Act (DORA) creates a binding digital resilience framework for the financial sector. Its industrial consequence is a mandate for entities to implement advanced threat intelligence sharing, rigorous resilience testing, and third-party risk management. The financial services segment is most affected, spurring investment in specific software modules for compliance and risk reporting.
Subscription-based purchasing models are becoming the default method for acquiring security software, replacing perpetual licenses. This procurement change allows customers greater flexibility and predictability in spending, aligning costs with actual usage. The shift is most prominent in the cloud security segment, especially among technology startups and mid-market firms in the United States and Europe.
Security Software Market Segmentation
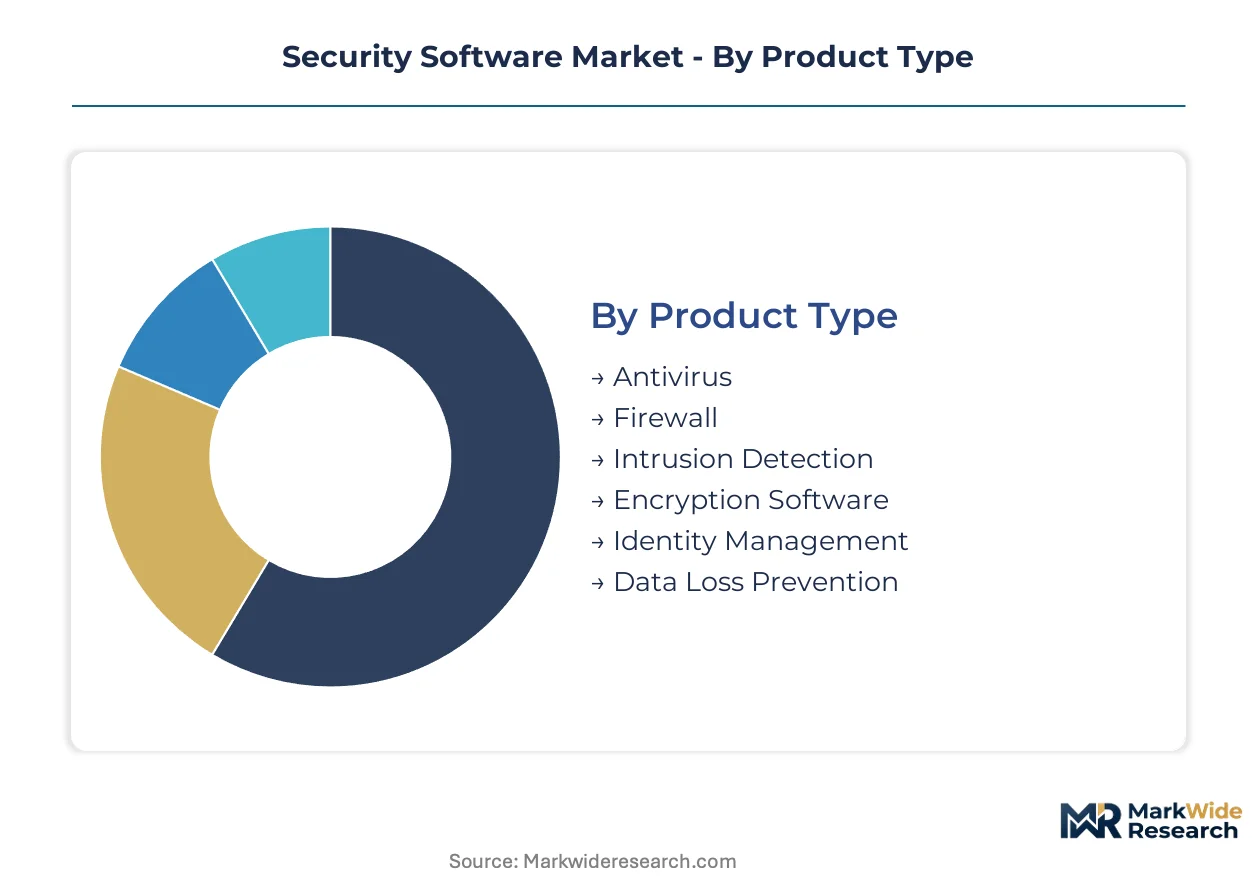
The security software market's segmentation provides a granular view of distinct product offerings, deployment methods, and end-user requirements. Understanding these divisions helps organizations align their security investments with specific operational needs and regulatory mandates. Each segment reflects unique technological functionalities and market adoption patterns across various industries.
Product Type:
Margin pools within product type segmentation often concentrate around advanced, specialized solutions that address complex, evolving threats.
- Identity Management:This software category provides robust authentication, authorization, and access control mechanisms for users and devices. High investment in Identity Management is driven by the rise of remote work environments and the need to secure complex IT ecosystems, particularly in the United States.
- Encryption Software:This technology employs cryptographic protocols to protect sensitive data at rest and in transit, preventing unauthorized access. Demand for encryption software is concentrating in Europe, fueled by stringent data protection regulations like GDPR, which mandate robust data security measures.
- Antivirus:Antivirus programs detect, prevent, and remove malicious software, offering foundational protection against common cyber threats.
- Firewall:Firewall solutions monitor and filter network traffic, establishing a barrier between trusted internal networks and untrusted external networks.
- Intrusion Detection:Intrusion detection systems monitor network or system activities for malicious activity or policy violations, alerting administrators to potential threats.
- Data Loss Prevention:Data Loss Prevention (DLP) tools prevent sensitive information from leaving an organization's network, ensuring compliance and data integrity.
Antivirus holds installed capacity. Identity Management is rotating up the share rankings.
Deployment:
Customer type significantly influences deployment choices, with cloud-native offerings attracting agile enterprises and managed services appealing to those with limited internal resources.
- Cloud-Based:This deployment model delivers security software as a service over the internet, offering scalability, flexibility, and reduced infrastructure overhead. Cloud-Based solutions dominate new sales, particularly among technology startups and mid-market firms in the United States and Europe.
- Managed Security Service Providers:MSSPs deliver outsourced monitoring and management of security devices and systems, providing expertise and resources to organizations. This model addresses the talent scarcity challenge, especially for small and medium-sized enterprises seeking comprehensive security without dedicated in-house teams.
- On-Premises:On-premises deployment involves installing and running security software on an organization's own servers and infrastructure.
- Hybrid:Hybrid deployment combines elements of both on-premises and cloud-based solutions, offering flexibility for organizations with mixed IT environments.
Cloud-Based deployment is expanding most quickly. Managed Security Service Providers are demonstrating strong growth.
Use Case:
Application diversity within use case segmentation reflects the broad spectrum of security challenges organizations face today.
- Threat Detection:This use case involves identifying and analyzing potential security breaches, suspicious activities, and vulnerabilities through behavioral analytics and signature-based methods. Real-time threat detection is a critical requirement for financial institutions and government bodies facing sophisticated cyberattacks.
- Endpoint Protection:Endpoint protection secures individual computing devices like laptops, desktops, and mobile phones from malicious threats. The shift to zero-trust architectures and remote work mandates robust endpoint protection across all industries.
- Access Control:Access control mechanisms regulate who or what can view or use resources within a computing environment.
- Risk Management:Risk management solutions identify, assess, and mitigate potential security risks to an organization's assets and operations.
- Compliance Monitoring:Compliance monitoring tools ensure that an organization's security practices adhere to relevant regulatory frameworks and industry standards.
- Network Security:Network security encompasses measures to protect the underlying network infrastructure from unauthorized access, misuse, and disruption.
Threat Detection remains a foundational requirement. Endpoint Protection is demonstrating robust expansion.
End User Industry:
Volume of sensitive data and regulatory pressure primarily define the demand across various end-user industries.
- Banking & Finance:This sector requires sophisticated threat detection against financial fraud, data encryption for customer information, and robust compliance monitoring for regulations like DORA. The high value of assets and stringent regulatory environment in the banking sector drives significant security software investment globally.
- Government Bodies:Government entities require advanced security solutions to protect critical national infrastructure, classified data, and citizen information. Regulations in countries like China requiring data localization influence specific security software procurements for government agencies.
- Telecommunications:Telecommunications providers need to secure vast network infrastructures and protect subscriber data from various cyber threats.
- Education Sector:The education sector requires security software to protect student data, intellectual property, and network resources from cyberattacks.
- Hospitality:Hospitality businesses deploy security software to protect guest data, payment information, and operational systems from breaches.
- Manufacturing:Manufacturing firms utilize security software to protect intellectual property, operational technology (OT) systems, and supply chain integrity.
Banking & Finance consistently drives demand. Telecommunications is experiencing notable uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global security software market exhibits a nuanced demand landscape, with significant regional variations in procurement and regulatory influence. Compliance requirements often dictate the adoption of specific software types, shaping market dynamics across different continents. This regional disparity creates distinct opportunities for vendors adapting to local mandates.
United States
Organizations in the United States prioritize advanced threat detection and identity management solutions to combat sophisticated cyberattacks. HIPAA mandates specific security controls for health information, driving investment in data protection software within the healthcare sector. Technology hubs like Silicon Valley and the Boston Corridor drive innovation in new security solutions.
Germany
German enterprises focus on robust data protection and industrial IoT security, driven by the country's strong manufacturing base. GDPR strongly influences demand for encryption and data loss prevention software across all industries. Financial centers in Frankfurt invest heavily in advanced threat detection for banking and finance operations.
China
Chinese demand for security software is shaped by national cybersecurity policies and data localization requirements. The government's GB standards influence procurement of compliance monitoring and network security tools. Beijing and Shanghai technology zones foster development of domestic security platforms for critical infrastructure.
Indonesia
Rapid digitalization in Indonesia creates foundational cybersecurity infrastructure needs, particularly for mobile-first economies. Indonesia's Personal Data Protection Law (UU PDP) drives demand for identity management and data loss prevention solutions. Jakarta's burgeoning tech sector requires robust endpoint protection for new enterprises and startups.
Brazil
Brazilian organizations focus on digital transformation security and protection against financial fraud, especially within the banking sector. Brazil's LGPD creates demand for data privacy and compliance monitoring solutions across various industries. São Paulo's financial industry prioritizes real-time threat detection and access control mechanisms.
Security Software Market Key Industry Players
Concentration sits with established platform providers and specialized solution vendors, creating a tiered market structure. The landscape includes firms offering broad security fabrics alongside niche players focusing on specific threat vectors. Strategic archetypes encompass integrated security platforms, cloud-native endpoint specialists, and compliance-driven solution providers. Many firms engage in portfolio diversification and strategic partnerships to broaden their offerings.
Within the integrated security platform archetype, Palo Alto Networks exemplifies a comprehensive approach to zero-trust architecture. CrowdStrike, a US-based firm, represents the cloud-native endpoint detection and response specialization. Fortinet, another US-based company, anchors the broad security fabric segment, unifying diverse functions across multiple environments. These companies navigate a market demanding context-aware solutions.
| Leading Market Players |
|---|
| Palo Alto Networks |
| CrowdStrike |
| Fortinet |
| Zscaler |
| Check Point Software Technologies |
| Okta |
| CyberArk |
| Broadcom |
| Trend Micro |
| Others |
Cost & Logistics Intelligence
Subscription-based purchasing models, now the default for security software, lock in predictable revenue streams for vendors and offer customers transparent cost visibility. This model shapes how software capabilities are delivered and priced over time.
Pricing Analysis
Enterprise customers anchor subscription-based pricing models, often tiered by user count or feature set. Price differentiation stems from advanced feature sets, customization for specific regulatory compliance, and bundled managed services. Pricing pressure stems from intense vendor competition and the challenge of integrating disparate tools, forcing providers to offer competitive packages. Small and medium-sized enterprises exhibit higher price sensitivity compared to large financial institutions or government bodies with non-discretionary spending.
Supply Chain Analysis
Minimal physical inventory characterizes the security software supply chain, with delivery primarily through cloud-based platforms and digital downloads. Software development talent concentrates in technology hubs across the United States, Germany, and China. Key dependencies include access to highly skilled cybersecurity professionals and robust cloud infrastructure from providers like Amazon Web Services. A structural risk involves the rapid evolution of cyber threats, demanding constant innovation and updates from vendors. Distribution runs through direct sales, channel partners, and Managed Security Service Providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The security software market faces a significant challenge in the persistent global shortage of skilled cybersecurity professionals. This talent gap impacts organizations' ability to deploy, manage, and optimize advanced security solutions effectively.
For Market Incumbents:Fortify comprehensive platform capabilities by integrating Extended Detection and Response (XDR) functionalities to counter rapid threat evolution. Invest in AI-driven security automation to reduce operational burden and address alert fatigue from vendor sprawl. Strategic partnerships with cloud providers can expand reach and offer deeper integration. Prioritize R&D in behavioral analytics to maintain a competitive edge against emerging attack vectors.
For New Entrants and Emerging Players:ISO 27001 certification fast-tracks offer a credible entry point for new security software solutions. Target the burgeoning AI security segment, protecting models and data from adversarial attacks, or specialized IoT protection for industrial settings. Emerging economies in Southeast Asia, such as Indonesia, present significant opportunities for foundational cybersecurity infrastructure. Partnering with Managed Security Service Providers provides an effective go-to-market angle for reaching underserved small and medium-sized enterprises.
For Investors and Strategic Acquirers:Capital is best deployed toward specialized solution vendors with strong intellectual property in emerging areas like AI security or XDR platforms. The long-term viability hinges on companies that can integrate context-aware security into zero-trust architectures. Acquisition targets should include firms addressing the talent scarcity through automation or providing deep compliance expertise for fragmented global regulations. The signal to watch is significant regulatory shifts, such as new data localization laws, creating non-discretionary spending opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies disparate security tools, reducing alert fatigue for enterprise customers. |
| Acquisition of Specialist Firm | Gains niche expertise in areas like AI security or specific regulatory compliance. |
| Strategic Partnership | Expands market reach and enhances solution capabilities through joint development. |
| Geographic Expansion | Captures new market share in rapidly digitalizing emerging economies. |
| Product Launch | Addresses new attack vectors by introducing advanced AI-driven threat detection. |
Research Approach
A spread of perspectives from Chief Technology Officers, Chief Security Officers, IT procurement leaders, and Managed Security Service Provider executives converged on the working assumptions. This study combined extensive primary interviews with rigorous secondary validation from sources including SEC filings, industry association reports, and government cybersecurity advisories. A triangulated approach, integrating both bottom-up market sizing and top-down validation, ensured data accuracy.
Product Type, Deployment, Use Case, End User Industry, and regional regulatory frameworks formed the segmentation dimensions modeled across the analysis window. Compound Annual Growth Rates were derived from historical data trends and projected adoption rates, considering evolving threat landscapes. Key forecast inputs included cybersecurity spending trends within regulated industries and anticipated compliance deadlines for new data protection laws.
Underlying assumptions cover current regulatory stability and established threat landscapes, with deviation risk concentrated in geopolitical cyber warfare and unforeseen technological breakthroughs. Forecasts reflect these assumptions, acknowledging potential shifts from rapid policy changes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Italy Endpoint Detection and Response Market
Security Software
Global Anti-Spam Software Market
Security Software
DC and PKI Market
Security Software
Hardware OTP Token Authentication Market
Security Software
Mobile Threat Management Security Software Market
Security Software
Video Intercom Devices and Equipment Market
Security Software
Fraud Detection Software Market
Security Software
Global Reputation Protection Software Market
Security Software
Application Control Software Market
Security Software
Identity Governance and Administration Market
Security Software
Patch and Remediation Software Market
Security Software
Europe Anti-Money Laundering Software Market
Security Software
Confidential Computing Market
Security Software
Biometric POS Terminals Market
Security Software
Banking Encryption Software Market
Security Software
Employee Fraud Detection Market