
 Europe Encryption Software Market | 2026-2036
Europe Encryption Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Encryption Software Market Analytics
Multi-source procurement of cryptographic modules is broadening as enterprises reduce dependence on single-vendor suites. Thales leverages its hardware security module lineage to anchor high-assurance contracts with European central banks. Sophos competes through integrated endpoint protection bundles that bundle encryption with threat detection. ESET sustains regional dominance from its Bratislava engineering base, where R&D intensity focuses on lightweight disk encryption for SME fleets.
Encryption software comprises algorithmic systems that transform plaintext into ciphertext using symmetric keys, asymmetric key pairs, or hashing protocols to enforce confidentiality, integrity, and non-repudiation. AES-256 and RSA-4096 represent standard technical specifications governing commercial implementations across the region. Endpoint encryption leads product type demand because remote work expansion exposes laptops and mobile devices to physical theft and network interception. Cloud-based deployment grows fastest among financial services institutions migrating vault operations to EU-sovereign data centers. Asymmetric encryption commands premium positioning within government and defense procurement where public-key infrastructure underpins classified communications.
GDPR enforcement by national data protection authorities, the EU AI Act's risk-classification framework, and ETSI cybersecurity certification standards collectively mandate encryption for personal data processing and high-risk AI systems. The European Data Protection Board's cross-border enforcement mechanism pressures multinationals to standardize encryption policies across all EU subsidiaries. Stakeholders must monitor the interplay between quantum-resistant algorithm migration timelines and existing PKI certificate lifecycles to avoid stranded cryptographic investments.
Market Dynamics
Quantum-resistant algorithm migration timelines are compressing procurement cycles across European financial and defense sectors, forcing premature retirement of RSA-4096 certificate infrastructures before standard NIST post-quantum protocols achieve full ETSI certification.
Growth Catalysts
- GDPR cross-border enforcement:The European Data Protection Board's consolidated penalty mechanism pressures multinationals to deploy uniform encryption stacks across all EU subsidiaries, eliminating jurisdiction-by-jurisdiction policy variation.
- Cloud vault migration:Financial services institutions are relocating cryptographic operations to EU-sovereign data centers to satisfy data residency mandates under the EU AI Act's risk-classification framework.
- Defense procurement modernization:France's defense-technology corridor is accelerating adoption of asymmetric encryption with public-key infrastructure for classified communications systems.
Market Restraints
- Hardware security module concentration:High-assurance contracts depend on a limited supplier base with manufacturing concentrated in specific European industrial clusters, creating single-source vulnerability.
- Certificate lifecycle stranding:Existing PKI investments face accelerated obsolescence as quantum-resistant standards emerge, forcing write-downs of unamortized cryptographic infrastructure.
- Skill scarcity in lattice-based cryptography:The talent pipeline for post-quantum algorithm implementation remains underdeveloped relative to deployment timelines mandated by national security agencies.
Strategic Opportunities
- Polish SME encryption penetration:Disk encryption adoption among Polish manufacturing and logistics mid-caps remains below Western European benchmarks, presenting whitespace for lightweight deployment models.
- AI system encryption mandates:The EU AI Act's high-risk system classification creates compliance-driven demand for encryption of training datasets and model weights in automated decision systems.
- Edge-to-cloud key orchestration:Convergence of confidential computing with hardware security modules enables unified key management across distributed IoT sensor networks and central analytics platforms.
Industry Challenges
- Legacy mainframe integration:Banking core systems running on decades-old transaction processing architectures require expensive middleware development to interface with modern API-driven encryption services.
- ETSI certification backlog:Evaluation queues for Common Criteria and EUCC security certifications extend delivery timelines, delaying product releases and compressing revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Encryption Software Market |
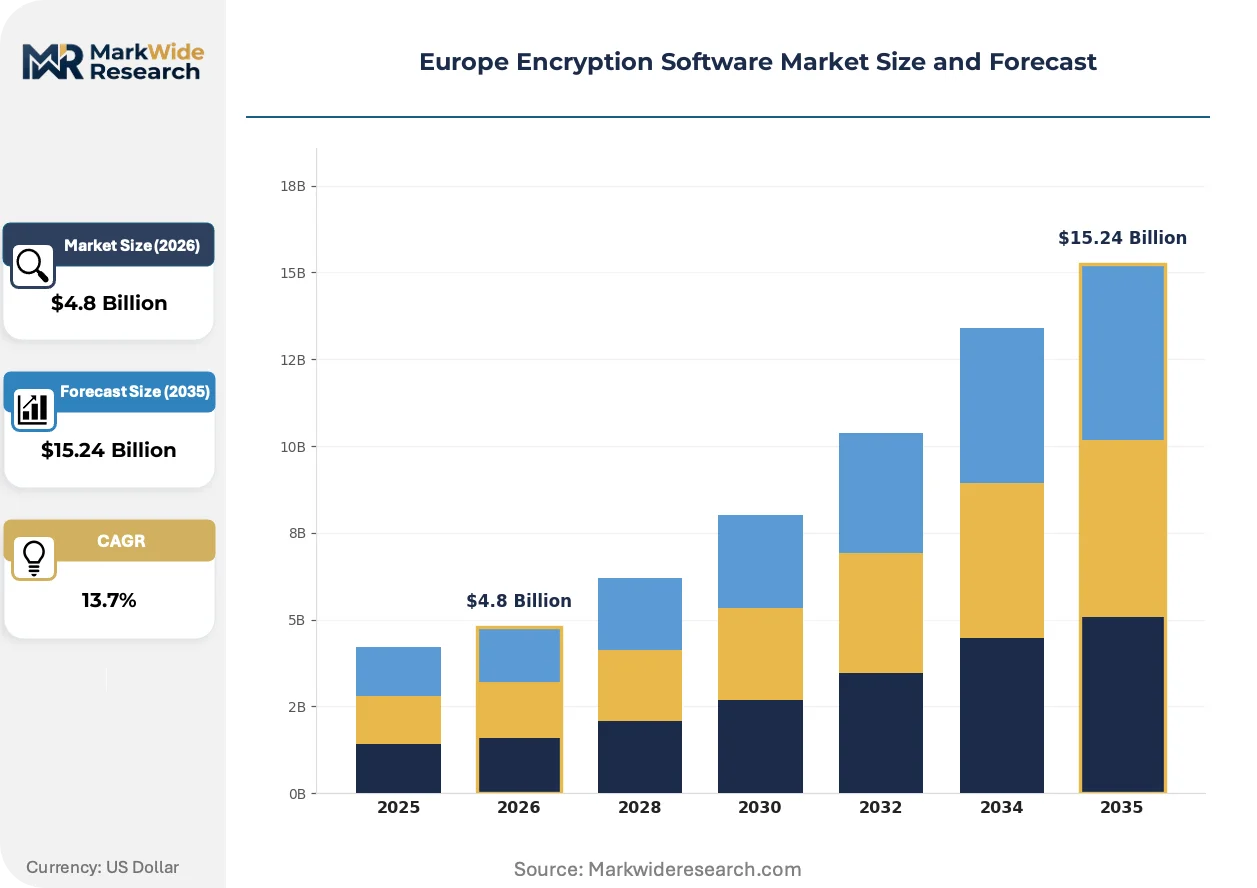
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endpoint Encryption, File Encryption, Disk Encryption, Email Encryption Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Healthcare, Financial Services, Government, IT & Telecom Technology: Symmetric Encryption, Asymmetric Encryption, Hashing, Tokenization |
| Companies Covered | Micro Focus, Stormshield, Sophos, ESET, Bitdefender, Thales, Cryptomathic, TrustArc, Boxcryptor, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Encryption Software Market Evolving Landscape
Post-quantum cryptographic standardization is forcing premature infrastructure refresh cycles across European enterprise and government sectors. Vendors are racing to bridge algorithmic readiness gaps while maintaining interoperability with legacy certificate authorities.
Homomorphic encryption is consolidating around privacy-preserving analytics in healthcare and financial services. Dutch hospital networks and German insurance consortia are piloting implementations for cross-institutional data pooling without decryption exposure. This technology is consolidating vendor positioning around specialized cryptographic acceleration hardware rather than pure software licensing.
The EU AI Act's risk-classification framework mandates encryption for personal data processing within high-risk automated decision systems. Industrial consequence includes mandatory security-by-design documentation for AI model training pipelines. Medical device manufacturers and credit scoring platforms face the steepest compliance ramps, with notified bodies expanding cybersecurity audit capacity.
Subscription-based encryption licensing is displacing perpetual enterprise agreements among mid-market buyers. Managed detection and response providers are bundling encryption with endpoint telemetry, collapsing separate procurement decisions into unified security service contracts. This pattern concentrates most visibly in Nordic professional services firms and Benelux logistics operators seeking operational expenditure predictability.
Europe Encryption Software Market Segmentation
Encryption software procurement patterns diverge sharply across deployment architectures and end-use verticals. European buyers prioritize compliance alignment over feature breadth, concentrating vendor selection around GDPR auditability and EU AI Act risk-tier certification.
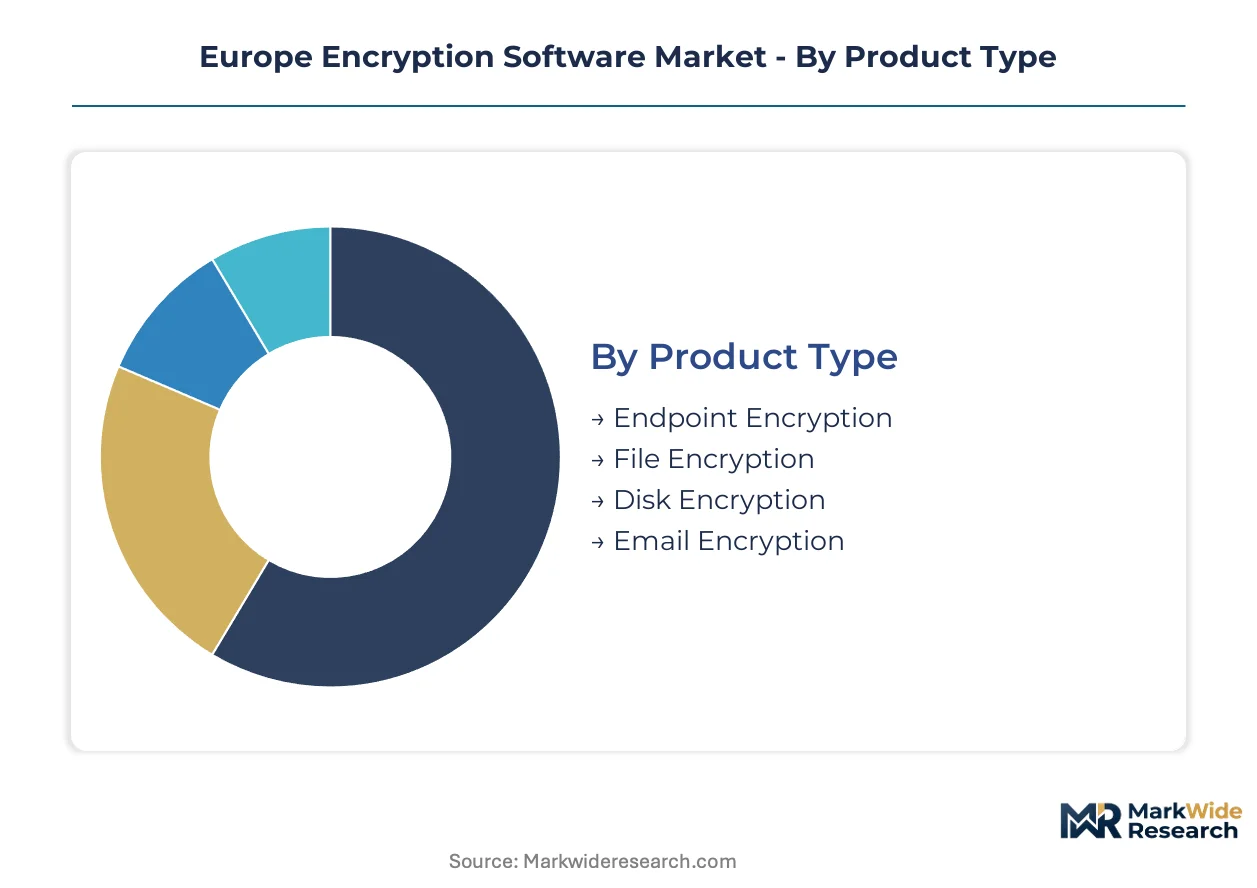
Product Type:
Supply concentration among hardware security module vendors shapes product-level procurement, with endpoint and disk encryption commanding premium positioning through Thales and Gemalto integration.
- Endpoint Encryption:Software agents encrypt data on laptops, mobile devices, and removable media using AES-256 protocols. German banking clusters and French defense contractors drive demand for hardware-backed key storage with tamper-resistant modules.
- Disk Encryption:Full-volume cryptographic protection for HDD and SSD storage, typically implemented via BitLocker or open-source LUKS derivatives. ESET's Bratislava engineering base dominates SME fleet deployments across Central Europe with lightweight agent architectures.
- File Encryption:Selective protection for individual documents and archives, often integrated into collaboration platforms.
- Email Encryption:S/MIME and PGP implementations for message-level confidentiality, concentrated in legal and professional services procurement.
Endpoint encryption absorbs the bulk of installed capacity; disk encryption is expanding most quickly.
Deployment:
Cost tier differentiation separates sovereign cloud mandates from budget-constrained on-premises retention, with hybrid architectures emerging as the compromise position for mid-cap enterprises.
- Cloud-Based:Encryption services delivered via EU-sovereign data centers with key escrow managed by certified providers. Financial services institutions migrating vault operations to Frankfurt and Paris facilities drive steepest expansion trajectory here.
- Managed Services:Third-party operation of key management infrastructure with SLAs covering certificate lifecycle and incident response. Nordic professional services firms favor this model for operational expenditure predictability.
- On-Premises:Customer-operated hardware security modules and key management servers retained for classified government systems.
- Hybrid:Split architectures keeping master keys on-premises while encrypting data volumes in cloud storage, common among Benelux logistics operators with cross-border data flows.
Cloud-based deployment captures the majority of new contract value; managed services is climbing the fastest among mid-market buyers.
End User:
Application-specific compliance deadlines concentrate procurement timing, with healthcare and financial services facing the steepest regulatory ramps under GDPR enforcement and MDR cybersecurity annexes.
- Financial Services:Encryption for payment card data, trading communications, and cloud vault operations with ECB oversight requirements. German and French institutions lead procurement volume for quantum-resistant algorithm migration.
- Government:Classified communications systems using asymmetric encryption with national PKI infrastructure. France's defense-technology corridor accelerates adoption ahead of NATO interoperability mandates.
- Healthcare:Patient record protection and cross-institutional data pooling with homomorphic encryption pilots in Dutch hospital networks.
- IT & Telecom:Infrastructure protection for 5G core networks and subscriber identity management, subject to ETSI cybersecurity certification standards.
Financial services accounts for the largest share of encryption software expenditure; government procurement is gaining share fastest through defense modernization programs.
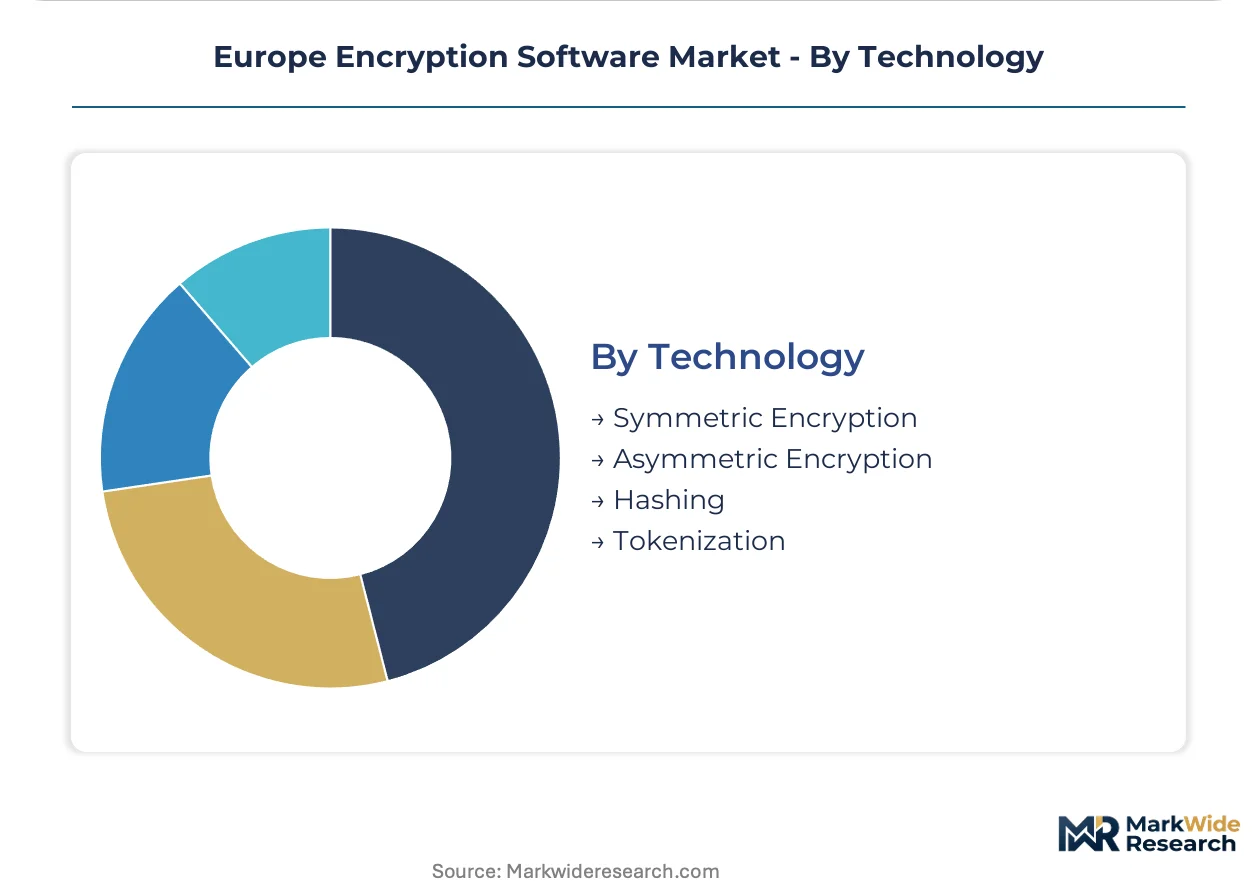
Technology:
Maturity curves separate established symmetric implementations from emerging post-quantum alternatives, with tokenization carving out a distinct niche in payment data protection.
- Symmetric Encryption:Single-key algorithms, primarily AES-256, dominating bulk data protection for performance efficiency. Hardware acceleration via Intel SGX and ARM TrustZone underpins most commercial implementations.
- Asymmetric Encryption:Public-key infrastructure with RSA-4096 and elliptic curve variants, commanding premium positioning in government and defense procurement where non-repudiation requirements apply.
- Hashing:One-way functions for data integrity verification and password storage, standardized through SHA-3 and BLAKE3 protocols.
- Tokenization:Replacement of sensitive data elements with non-sensitive equivalents, concentrated in payment processing and PCI-DSS compliance scenarios.
Symmetric encryption retains the dominant share of operational deployments; asymmetric encryption is expanding most quickly through PKI modernization initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial clusters anchor encryption software demand across Europe, with Frankfurt's banking infrastructure and Munich's defense-technology corridor driving procurement concentration.
Germany
Financial services procurement concentrates in Frankfurt's banking district, where institutions migrate vault operations to sovereign cloud facilities. The Federal Financial Supervisory Authority (BaFin) mandates encryption for payment data under PSD2 implementation. Munich's defense-technology corridor accelerates asymmetric encryption adoption for classified NATO communications systems.
France
Government and defense procurement dominates demand, with Paris-region contractors modernizing public-key infrastructure for secure communications. The National Agency for Food, Environmental and Occupational Health Safety (ANSES) extends encryption requirements to medical device cybersecurity under MDR annexes. Toulouse's aerospace cluster integrates hardware security modules into satellite ground control systems.
United Kingdom
London's financial services sector drives cloud-based encryption adoption for cross-border transaction processing. The Information Commissioner's Office enforces GDPR penalties that pressure multinationals to standardize encryption policies across EU subsidiaries. Cambridge's technology corridor hosts homomorphic encryption pilots for healthcare data analytics.
Netherlands
Amsterdam's data center hub attracts EU-sovereign cloud encryption deployments from financial institutions seeking data residency compliance. The Dutch Data Protection Authority coordinates with the European Data Protection Board on cross-border enforcement mechanisms. Eindhoven's semiconductor cluster supplies cryptographic acceleration hardware for edge computing applications.
Poland
Manufacturing and logistics mid-caps in the Silesian and Greater Poland regions present underpenetrated demand for lightweight disk encryption solutions. The Personal Data Protection Office aligns enforcement with GDPR cross-border penalty frameworks. Warsaw's emerging fintech sector drives SME-focused encryption procurement from managed security service providers.
Europe Encryption Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors bridge algorithmic readiness gaps with hardware security module integration. The market structures around three tiers: legacy enterprise suites, cloud-native platforms, and specialized cryptographic hardware suppliers. Two archetypes define positioning: integrated cybersecurity conglomerates bundling encryption with endpoint protection, and pure-play cryptography specialists anchoring high-assurance government contracts. Portfolio diversification and quantum-resistant algorithm licensing represent the dominant competitive vectors.
Within the integrated cybersecurity tier, Sophos and ESET exemplify bundled endpoint protection strategies that collapse encryption procurement into unified security service contracts. Thales occupies a position among hardware security module specialists, anchoring high-assurance contracts with European central banks through its legacy in tamper-resistant cryptographic infrastructure. These three companies represent distinct archetypes: British-headquartered bundled security platforms, Bratislava-based regional SME specialists, and Paris-region defense-technology incumbents.
| Leading Market Players |
|---|
| Micro Focus |
| Stormshield |
| Sophos |
| ESET |
| Bitdefender |
| Thales |
| Cryptomathic |
| TrustArc |
| Boxcryptor |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between ETSI-certified quantum-resistant suites and uncertified legacy modules manifests in pricing premiums of three-to-five multiples and supply chain configurations that anchor high-assurance production in France's defense-technology corridor and Germany's banking hardware clusters. This bifurcation concentrates procurement power among buyers with sovereign-cloud mandates while squeezing mid-market vendors into subscription-based service bundling.
Pricing Analysis
Warranty and service-bundling unbundling distinguishes premium hardware security module contracts from commodity endpoint encryption licenses. The dominant pricing structure runs through subscription-based SaaS tiers with managed key-escrow services, while price differentiation rests on Common Criteria certification level and geographic data-residency guarantees. Pricing pressure stems from ETSI certification backlog delays compressing revenue recognition windows. Financial services institutions show least price sensitivity due to regulatory penalty exposure; Polish manufacturing mid-caps exhibit highest sensitivity, favoring lightweight disk encryption without hardware-backed key storage.
Supply Chain Analysis
Workforce availability for lattice-based cryptography implementation concentrates in France's Paris-region defense contractors and Germany's Munich engineering clusters, with secondary capacity in the Netherlands' Eindhoven semiconductor corridor. Hardware security module fabrication draws from German precision manufacturing, French aerospace-grade electronics, and Dutch cryptographic acceleration chip design. Single-source vulnerability pervades high-assurance tamper-resistant module supply. Distribution runs through certified systems integrators with EUCC audit credentials rather than direct vendor-to-enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Encryption Software Market functions as a cost-of-compliance story where GDPR cross-border enforcement and EU AI Act risk-classification mandates erect barrier-to-entry moats favoring vendors with pre-existing ETSI certification relationships and sovereign-cloud infrastructure.
For Market Incumbents: Anchor defensive positioning through accelerated post-quantum algorithm licensing with national security agencies and captive supply of hardware security module manufacturing capacity in Germany's industrial clusters. Threat substitution from cloud-native encryption platforms demands consolidation of high-assurance government contracts before NIST post-quantum standards achieve full ETSI certification. Certification investment represents the critical lever for margin defense against commodity endpoint encryption vendors. For New Entrants and Emerging Players: Managed security service provider partnerships offer the most penetrable route into Polish manufacturing and logistics mid-caps where disk encryption adoption lags Western European benchmarks. White-space concentrates in AI system encryption for automated decision platforms facing EU AI Act compliance deadlines. Go-to-market execution favors lightweight agent architectures with subscription-based operational expenditure predictability rather than perpetual license competition against entrenched endpoint protection bundles. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated cybersecurity conglomerates seeking quantum-resistant algorithm portfolios and ETSI-certified hardware security module capabilities. Long-term viability favors vendors with sovereign-cloud infrastructure in Frankfurt and Paris facilities plus established relationships with European central banks. Signal to watch: acceleration of national security agency procurement timelines for post-quantum migration, which would compress valuation windows for legacy PKI-dependent targets.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Algorithm Licensing | NIST standard adoption with French ANSSI and German BSI accelerates high-assurance contract capture. |
| Sovereign Cloud Infrastructure Expansion | Frankfurt and Paris data center certification under EU AI Act data residency mandates locks in financial services demand. |
| Hardware Security Module Acquisition | Tamper-resistant manufacturing capacity in Munich and Toulouse clusters anchors defense procurement modernization. |
| Managed Detection and Response Bundling | Nordic professional services firms collapse separate encryption decisions into unified security service contracts. |
| ETSI Certification Fast-Track Investment | Common Criteria and EUCC evaluation queue priority reduces delivery timeline compression and revenue recognition risk. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with chief information security officers, IT procurement officers at financial institutions, platform engineers at sovereign-cloud providers, and regulatory affairs leads at medical device manufacturers. Secondary validation drew from European Data Protection Board enforcement decisions, ETSI cybersecurity certification databases, ECB payment system oversight reports, and national data protection authority penalty registers. Bottom-up deployment estimates across encryption product types reconciled with top-down market sizing through iterative triangulation.
Data-stream reconciliation across deployment architecture, end-use vertical, and technology maturity dimensions shaped the analytical framework over the projection horizon. Segmentation modeling incorporated product type, deployment mode, end-user industry, and geographic regulatory cluster. CAGRs derived from weighted average of historical procurement trajectory and regulatory deadline acceleration effects. Industry-specific forecast inputs included quantum-resistant algorithm standardization timelines and EU AI Act implementation phase-in schedules.
The model holds under sustained GDPR enforcement intensity and ETSI certification queue stability; deviation in NIST post-quantum standard finalization timelines or EU AI Act risk-tier reclassification would shift deployment trajectories. Forecasts reflect documented assumptions regarding sovereign-cloud migration rates and hardware security module manufacturing capacity expansion. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Network Encryption Market
Security Software
AI in Security Market
Security Software
Data Leakage Prevention Product Market
Security Software
Cloud Identity and Access Management Software Market
Security Software
Global Background Screening Market
Security Software
Cloud Encryption Software Market
Security Software
ATM Security Market
Security Software
Global Data Privacy Management Software Tools Market
Security Software
Personal Data Recovery Software Market
Security Software
Embedded Security Market
Security Software
Cloud File Security Software Market
Security Software
Privacy Management Software Market
Security Software
Anti-Money Laundering (AML) Software Solution Market
Security Software
Global Data Breach Notification Software Market
Security Software
Digital Risk Protection Software Market
Security Software
DNS Protection Software Market