
 Remote Access Management Market | 2026-2036
Remote Access Management Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Access Management Market Outlook
Platform licensing revenue is narrowing as vendors shift toward recurring subscription models. Microsoft leverages its Entra identity suite to anchor enterprise deployments across hybrid cloud environments. CyberArk sustains premium positioning through specialized privileged access management capabilities for critical infrastructure operators. Okta competes aggressively in the mid-market with cloud-native single sign-on integrations that reduce deployment friction.
Remote access management governs authenticated connectivity to organizational resources from external endpoints, employing encryption protocols, multi-factor authentication, and session monitoring to enforce least-privilege access across distributed workforces. Cloud-based deployment leads technology adoption as enterprises retire on-premises VPN concentrators in favor of elastic, API-driven access fabrics. Zero trust architecture represents the fastest-expanding technology segment, displacing traditional RDP and perimeter-based VPN approaches that lack continuous verification.
NIST cybersecurity frameworks and the EU AI Act shape product standards for biometric authentication and behavioral analytics in remote access platforms. GDPR and state-level privacy regulations in California and Virginia constrain how vendors process session data and user telemetry across jurisdictions. Stakeholders must monitor evolving certification requirements for government and defense procurement channels.
Market Dynamics
Zero trust architecture mandates from NIST and the EU cybersecurity framework are forcing wholesale replacement of perimeter-based VPN infrastructure across enterprise IT estates. This structural shift concentrates procurement authority with CISOs and compliance officers rather than network operations teams.
Growth Catalysts
- NIST SP 800-207 Framework:Federal agencies and contractors face binding zero trust implementation deadlines, creating immediate demand for continuous verification platforms that replace static credential models.
- Critical Infrastructure Sectors:Energy utilities, water treatment facilities, and transportation operators deploy privileged access management under sector-specific cybersecurity directives from the Department of Homeland Security.
- Biometric Authentication Convergence:Fingerprint, facial recognition, and behavioral keystroke analysis integrate into remote access stacks as hardware security keys reach commodity pricing.
Market Restraints
- Certificate Authority Concentration:Browser root store policies limit viable commercial certificate providers to a handful of vendors, creating single-point-of-failure risk for device trust anchoring.
- GDPR Session Data Constraints:European privacy regulators restrict retention periods for user behavioral telemetry used in risk-scoring algorithms, degrading anomaly detection efficacy.
- Legacy RDP Protocol Persistence:Windows Server estates in manufacturing and healthcare retain Remote Desktop Protocol dependencies that resist certificate-based authentication retrofitting without application rewrites.
Strategic Opportunities
- Operational Technology Convergence:IT-OT network segmentation projects in industrial facilities create demand for remote access gateways that broker connections to SCADA and PLC systems without VPN tunneling.
- Japan's Digital Agency Cloud-First Mandate:Central government agencies accelerate migration to G-Cloud environments, requiring FedRAMP-equivalent access controls for distributed civil servant workforces.
- Device Posture Assessment Integration:Endpoint detection and response vendors partner with access management platforms to enforce conditional access based on real-time malware infection status and patch compliance.
Industry Challenges
- Identity Architect Skill Scarcity:Enterprise IT departments struggle to hire engineers proficient in SAML, OIDC, and SCIM protocol implementation across hybrid cloud directory services.
- Multi-Cloud Policy Fragmentation:AWS, Azure, and Google Cloud implement divergent conditional access APIs, forcing vendors to maintain three parallel integration codebases for feature parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Access Management Market |
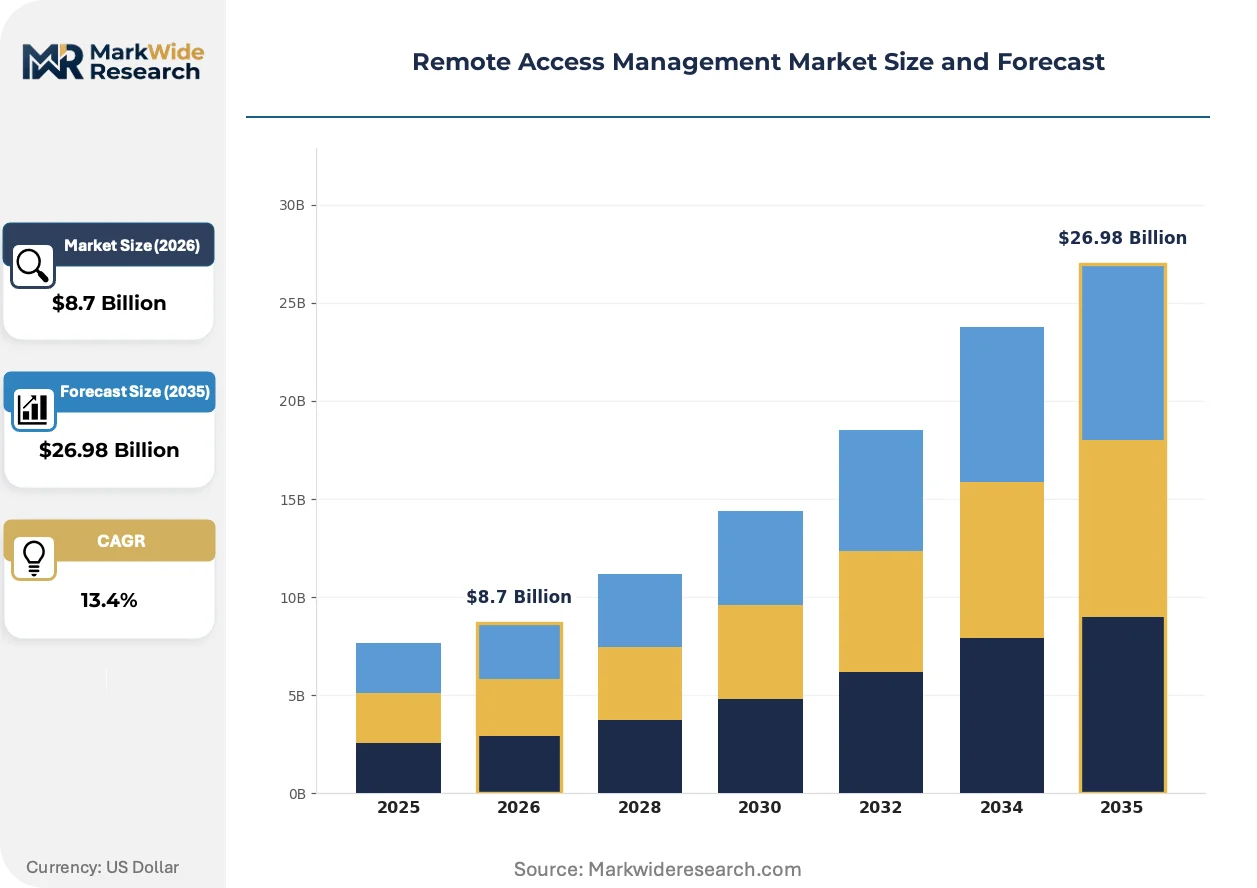
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Service Technology: VPN, RDP, VDI, Zero Trust End User: Small Businesses, Enterprises, Government, Academic Institutions Solution: Software, Hardware, Subscription, Professional Services |
| Companies Covered | Microsoft, ForgeRock, Okta, 12Port, SailPoint, CyberArk, Saviynt, NinjaOne, Ping Identity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Access Management Market Strategic Shifts
Continuous authentication mechanisms are displacing session-based login events across enterprise security architectures. Vendors race to embed behavioral biometrics and device trust signals into access decisions without adding user friction.
Passwordless FIDO2 authentication is digitizing credential lifecycle management for distributed workforces. Financial services firms and technology companies deploy hardware security keys and platform authenticators at scale, eliminating phishing vectors associated with SMS and TOTP codes. This shift compresses help desk ticket volumes tied to password resets while raising procurement emphasis on cross-platform key management.
EU AI Act risk classification rules reshape biometric deployment in remote access platforms. High-risk categorization for real-time remote biometric identification triggers conformity assessment obligations, compliance documentation requirements, and human oversight mandates. German and French enterprise buyers now prioritize vendors with established EU notified body certifications for facial recognition and keystroke dynamics.
Consumption-based licensing displaces perpetual seat counts in enterprise procurement negotiations. Mid-market buyers favor monthly active user pricing tied to actual authentication events rather than provisioned licenses, pressuring vendors to meter infrastructure costs against variable revenue streams. This pattern concentrates in United States SaaS-native companies with seasonal workforce fluctuations.
Remote Access Management Market Segmentation
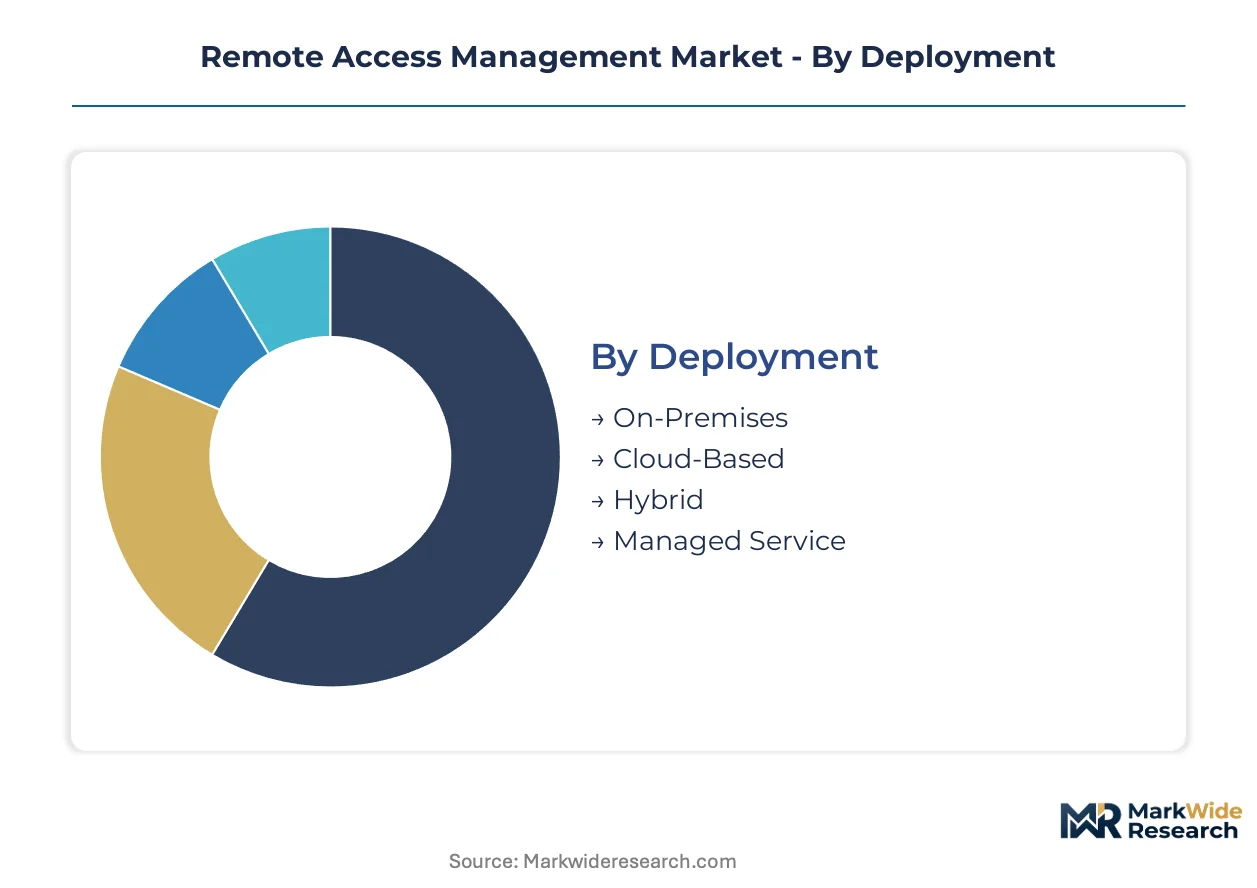
Remote access management procurement varies sharply by deployment mode, technology maturity, and buyer sophistication. Vendors must align licensing models and service architectures to distinct operational constraints across these dimensions.
Deployment:
After-sales service intensity escalates with infrastructure control retained by the buyer, driving diverging support obligations across deployment modes.
- On-Premises:Organizations maintain dedicated VPN concentrators and identity servers within corporate data centers. Demand concentrates in German manufacturing and Japanese financial institutions where data sovereignty requirements block external data processing.
- Cloud-Based:Elastic access fabrics delivered via API-driven platforms eliminate hardware lifecycle management. United States SaaS-native enterprises and United Kingdom professional services firms drive procurement as they retire legacy concentrator estates.
- Hybrid:Split architectures anchor sensitive workloads on-premises while bursting authentication services to cloud infrastructure. Energy utilities in Texas and Alberta deploy this model to satisfy NERC CIP obligations without sacrificing operational flexibility.
- Managed Service:Third-party providers assume full responsibility for platform operations, patching, and incident response. Australian healthcare networks and Singaporean government agencies favor this option amid persistent identity architect scarcity.
By volume, Cloud-Based leads. By growth pace, Hybrid is ahead.
Technology:
Cost tier stratification separates commodity protocols from premium continuous verification architectures requiring specialized engineering investment.
- Zero Trust:Continuous verification platforms eliminate implicit trust through device posture assessment, behavioral analytics, and micro-segmentation. Federal contractors facing NIST SP 800-207 deadlines and EU institutions under cybersecurity directive mandates anchor demand.
- VPN:Encrypted tunneling protocols persist as baseline connectivity for bulk remote workforce access. Legacy installations in Indian business process outsourcing and Brazilian industrial conglomerates resist displacement due to embedded application dependencies.
- RDP:Microsoft's proprietary protocol dominates Windows-centric environments despite certificate-based authentication retrofit challenges. Healthcare systems in Illinois and manufacturing plants in Ohio retain substantial estates.
- VDI:Virtual desktop infrastructure centralizes compute and data while streaming pixels to endpoint devices. Financial services compliance teams in New York and London deploy VDI to enforce data loss prevention without endpoint agent complexity.
Zero Trust commands premium pricing. VPN retains the largest installed base.
End User:
Customer type dictates sales cycle length, procurement authority locus, and compliance documentation burden.
- Enterprises:Global 2000 organizations with distributed workforces and multi-cloud estates. CISO-led procurement in United States technology and German automotive sectors prioritizes API extensibility and SIEM integration.
- Government:Civilian and defense agencies with classified or controlled unclassified information handling requirements. FedRAMP and equivalent certifications gate vendor participation in United States federal and Japanese G-Cloud channels.
- Small Businesses:Organizations under 500 employees with limited security operations capacity. Managed service bundles and Microsoft Entra native integration reduce deployment friction for United Kingdom and Canadian professional services firms.
- Academic Institutions:Universities and research facilities with seasonal enrollment fluctuations and open research collaboration norms. Identity federation through InCommon and eduGAIN shapes procurement in California and Massachusetts higher education systems.
Enterprises generate the highest absolute revenue. Government exhibits the steepest expansion trajectory.
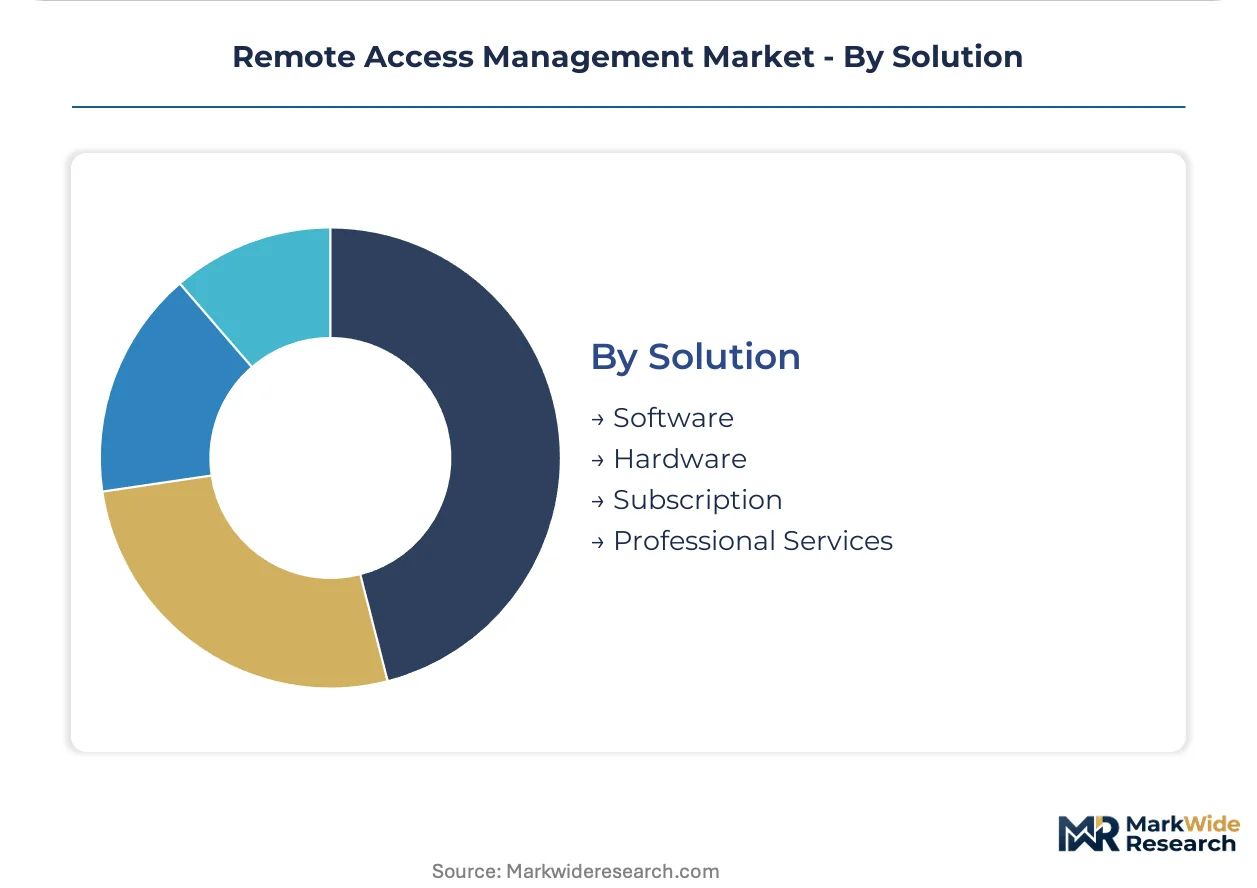
Solution:
Margin structure varies dramatically between perpetual license maintenance streams and consumption-metered SaaS arrangements.
- Subscription:Recurring revenue models tied to monthly active users or authentication event volumes. United States mid-market buyers with seasonal workforce patterns drive adoption of this pricing flexibility.
- Software:Perpetual licenses for on-premises identity platforms with annual maintenance contracts. German critical infrastructure operators and Japanese manufacturers favor this model for capital expenditure treatment and depreciation schedules.
- Hardware:Physical appliances including VPN concentrators, hardware security modules, and FIDO2 security keys. Financial services token deployments in Singapore and Netherlands sustain this segment despite cloud migration headwinds.
- Professional Services:Implementation, integration, and managed detection and response offerings. Identity architect scarcity elevates services attach rates for complex SAML and OIDC directory federation projects.
Subscription revenue is climbing fastest. Software maintains the largest revenue base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mid-market buyers in the United States exhibit the highest price elasticity, driving consumption-based licensing negotiations, while German critical infrastructure operators maintain inelastic demand for perpetual deployments governed by data sovereignty mandates.
United States
Federal contractors facing NIST SP 800-207 zero trust deadlines and SaaS-native enterprises retiring legacy VPN estates anchor procurement volume. FedRAMP certification gates vendor participation in civilian and defense agency channels. Technology clusters in Seattle and Austin concentrate cloud-native access fabric deployments for distributed workforces.
Germany
Automotive manufacturers and chemical conglomerates demand on-premises identity platforms satisfying GDPR data residency requirements. The country's national data protection regulator enforces strict session telemetry retention limits that constrain behavioral analytics efficacy. Industrial concentrations in Bavaria and North Rhine-Westphalia sustain perpetual license preferences for capital expenditure treatment.
Japan
Financial institutions and central government agencies under the Digital Agency cloud-first mandate accelerate FedRAMP-equivalent access control procurement. METI cybersecurity guidelines shape biometric authentication standards for distributed civil servant workforces. Tokyo and Osaka metropolitan areas lead hybrid architecture deployments balancing sensitive workload anchoring with operational flexibility.
United Kingdom
Professional services firms and mid-market enterprises drive cloud-based subscription adoption with seasonal workforce pricing flexibility. The Information Commissioner's Office constrains cross-border session data processing under post-Brexit GDPR continuity arrangements. London's financial services compliance teams deploy virtual desktop infrastructure to enforce data loss prevention without endpoint agent complexity.
Singapore
Government agencies and healthcare networks favor managed service providers amid persistent identity architect scarcity across Southeast Asia. The country's national cybersecurity agency mandates zero trust architecture adoption for critical information infrastructure operators. Financial services token deployments in the central business district sustain hardware security module demand despite regional cloud migration headwinds.
Remote Access Management Market Competitive Environment
Platform consolidators and privileged access specialists split the market between breadth-oriented identity suites and depth-focused critical infrastructure solutions. The vendor landscape exhibits moderate concentration with tiered positioning across enterprise, mid-market, and government segments. Three archetypes dominate: cloud-native SaaS platforms, legacy infrastructure retrofitters, and OT-security converged gateways. Competitive dynamics center on strategic partnerships with endpoint detection vendors and vertical integration into hardware security key distribution channels.
Within the cloud-native tier, Microsoft and Okta exemplify divergent approaches to enterprise deployment friction reduction. CyberArk occupies a premium position representing specialized privileged access capabilities for energy utilities and transportation operators facing sector-specific cybersecurity directives. These three anchors illustrate how vendor strategy bifurcates between platform breadth and infrastructure depth.
| Leading Market Players |
|---|
| Microsoft |
| ForgeRock |
| Okta |
| 12Port |
| SailPoint |
| CyberArk |
| Saviynt |
| NinjaOne |
| Ping Identity |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific fiber cable routes connecting Singapore to Los Angeles anchor cloud infrastructure delivery costs for remote access platforms, concentrating supply-side pricing power among hyperscale data center operators while forcing tiered subscription differentiation based on latency guarantees and data residency compliance.
Pricing Analysis
Managed detection and response service tiers now drive lifetime value capture across vendor portfolios. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized deployments from commercial SaaS and freemium developer tiers. Cost compression in the mid-market intensifies because Microsoft bundles Entra capabilities into existing enterprise agreements. Seasonal workforce buyers in United States professional services exhibit highest price elasticity, while German critical infrastructure operators show inelastic demand for sovereign-cloud deployments.
Supply Chain Analysis
BIS export controls on advanced encryption modules restrict hardware security key flows from United States manufacturers to Chinese and Russian markets. Semiconductor fabrication for FIDO2 authenticators centers on Taiwan and South Korea, with final assembly in Vietnam and Mexico. Single-source vulnerability concentrates in TSMC's advanced node production for secure enclave chips. Distribution runs through value-added resellers and systems integrators rather than direct enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote access management functions as a service-attach opportunity where recurring subscription revenue expands faster than perpetual license hardware sales, rewarding vendors who embed continuous authentication and managed detection capabilities into long-term contracts.
For Market Incumbents: Pre-empt margin erosion from Microsoft's bundled identity suite by deepening privileged access specialization for energy utilities and transportation operators facing DHS cybersecurity directives. Invest in FedRAMP High authorization to defend federal contractor channels against emerging cloud-native competitors. Prioritize API extensibility investments that preserve SIEM integration moats.
For New Entrants and Emerging Players: Pursue operational technology convergence opportunities in industrial facilities where IT-OT segmentation creates demand for SCADA-aware remote access gateways. Japan's Digital Agency cloud-first mandate offers the most penetrable government segment for FedRAMP-equivalent certification. Lead with managed service positioning to bypass identity architect scarcity in Australian healthcare and Singaporean government agencies.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy networking vendors with stranded VPN concentrator product lines and established channel relationships in manufacturing verticals. Long-term viability hinges on zero trust architecture transition completion rather than perpetual license maintenance streams. Watch NIST SP 800-207 compliance deadline acceleration as inflection indicator for federal contractor demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Zero Trust Architecture Certification | FedRAMP authorization opens civilian and defense agency procurement channels. |
| Operational Technology Gateway Development | SCADA-aware access brokers capture industrial facility IT-OT convergence budgets. |
| Biometric Authentication Partnership | EU AI Act conformity assessment accelerates facial recognition deployment in German enterprises. |
| Consumption-Based Licensing Transition | Monthly active user pricing aligns revenue with seasonal workforce patterns in professional services. |
| Managed Detection and Response Integration | EDR vendor partnerships enable conditional access based on real-time endpoint posture. |
Study Parameters
A standing panel of CISOs, identity architects, federal procurement officers, and OT security engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from NIST cybersecurity framework publications, FedRAMP authorization databases, EU cybersecurity directive implementation reports, and hyperscaler identity service disclosures. Bottom-up deployment volume estimates triangulated against top-down enterprise IT spending allocations.
Scenario bracketing anchored projections across base, accelerated zero trust adoption, and legacy infrastructure persistence cases. Segmentation dimensions spanned deployment model, organization size, vertical compliance intensity, technology maturity tier, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to replacement cycle data for VPN concentrators and RDP estates. Forecast inputs incorporated NIST SP 800-207 implementation timelines and EU AI Act biometric conformity assessment obligations.
Sensitivities concentrate around federal zero trust deadline extensions, EU AI Act enforcement variance, and hyperscaler bundling aggression. Forecasts reflect assumptions regarding identity architect hiring rates and certificate authority market structure stability. Material shifts in NIST framework mandate timing or EU biometric regulatory interpretation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
POS Security Market
Security Software
Application Control Market
Security Software
Anti-Money Laundering (AML) Software Solution Market
Security Software
Single Sign-On Market
Security Software
Social Media Security Market
Security Software
Global Log Management Market
Security Software
Mobile Threat Management Security Software Market
Security Software
Network Video Recorder (NVR) Market
Security Software
Global Wireless Intrusion Prevention System Market
Security Software
Secure Email Gateway Market
Security Software
North America Secure Access Service Edge Market
Security Software
US and Latin America Identity and Access Management (IAM) Market
Security Software
Europe Video Management System Market
Security Software
Privacy Management Software Market
Security Software
Europe Lawful Interception Market
Security Software
DNS Protection Software Market