
 Global Mobile Application Market | 2026-2036
Global Mobile Application Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Application Market Intelligence
Mobile developer talent scarcity across cloud-native and AI-integrated disciplines is reorganizing how platforms compete for technical capacity. Google LLC leverages its Android ecosystem to sustain developer loyalty through integrated tooling and distribution scale. Apple Inc. anchors premium monetization via strict App Store curation and proprietary hardware-software alignment. ByteDance Ltd. differentiates through algorithmic content delivery that commands disproportionate user engagement hours.
A mobile application constitutes software designed for execution on smartphones and tablets, typically distributed through platform-specific app stores and optimized for touch interfaces, sensor integration, and intermittent network connectivity. These applications serve commercial purposes spanning transaction facilitation, content consumption, enterprise workflow enablement, and real-time communication. Social Networking and Entertainment categories currently dominate consumer screen time and in-app purchase revenue pools. Productivity and Finance segments are expanding fastest among Enterprise Deployment channels as small businesses and large enterprises replace legacy desktop workflows. The Operating System dimension remains structurally bifurcated, with iOS capturing disproportionate monetization per user while Android sustains volume leadership across third-party markets and OEM pre-installs.
The EU AI Act and GDPR impose algorithmic transparency and data processing standards that constrain deployment timelines for AI-infused applications in Europe. The FDA regulates mobile health applications as medical devices when they provide diagnostic or therapeutic functionality, creating segmented compliance pathways in the United States. China's SAMR and MIIT enforce content moderation and data localization mandates that shape product architecture for apps operating in that market. Stakeholders must monitor evolving cross-border data governance frameworks to determine whether to maintain unified codebases or fragment technical infrastructure by jurisdiction.
Market Dynamics
Algorithmic governance frameworks are forcing mobile application developers to re-architect data pipelines and consent mechanisms before deployment, compressing release timelines and elevating compliance costs across all major distribution markets.
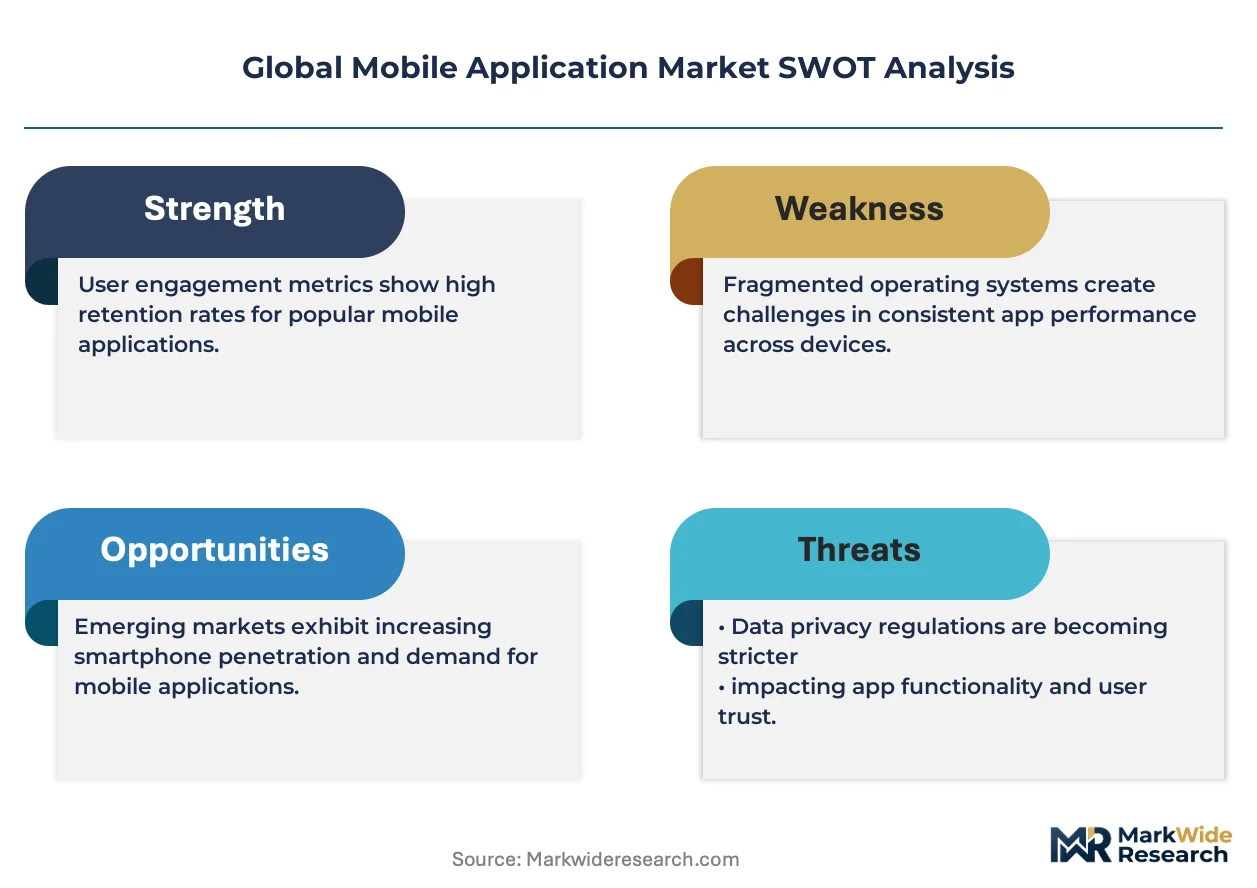
Growth Catalysts
- EU AI Act compliance tooling:European algorithmic transparency mandates are creating specialized demand for explainable AI middleware that developers must embed to access the EU market.
- Enterprise workflow digitization:Small and medium enterprises in Brazil and India are replacing desktop productivity suites with mobile-first finance and operations applications.
- Sensor fusion capabilities:Advances in on-device machine learning are enabling health and fitness applications to process biometric data without cloud transmission, satisfying FDA guidance on data minimization.
Market Restraints
- Platform gatekeeper concentration:Apple and Google control essential distribution infrastructure, extracting 15-30% of in-app transaction value and limiting direct developer-consumer relationships.
- Cross-border data fragmentation:China's data localization requirements under SAMR and MIIT directives force parallel technical infrastructure for apps operating in that market.
- Legacy codebase technical debt:Established applications built on monolithic architectures face prohibitive refactoring costs to implement modern privacy-preserving computation.
Strategic Opportunities
- India's rural smartphone penetration:Tier-2 and Tier-3 cities present underdeveloped demand for vernacular-language financial inclusion and agricultural productivity applications.
- Convergence of AR and spatial computing:Hardware advances in light-field displays and depth sensing are opening industrial training and remote assistance use cases.
- GDPR Article 25 compliance automation:Privacy-by-design tooling represents an emerging software category as European enforcement intensifies against dark patterns and coerced consent.
Industry Challenges
- Cloud-native architecture expertise scarcity:Mobile developers with production experience in Kubernetes orchestration and serverless edge deployment command premium compensation.
- FDA 510(k) pathway navigation:Diagnostic health applications face extended validation timelines and clinical evidence requirements that strain startup capital reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Application Market |
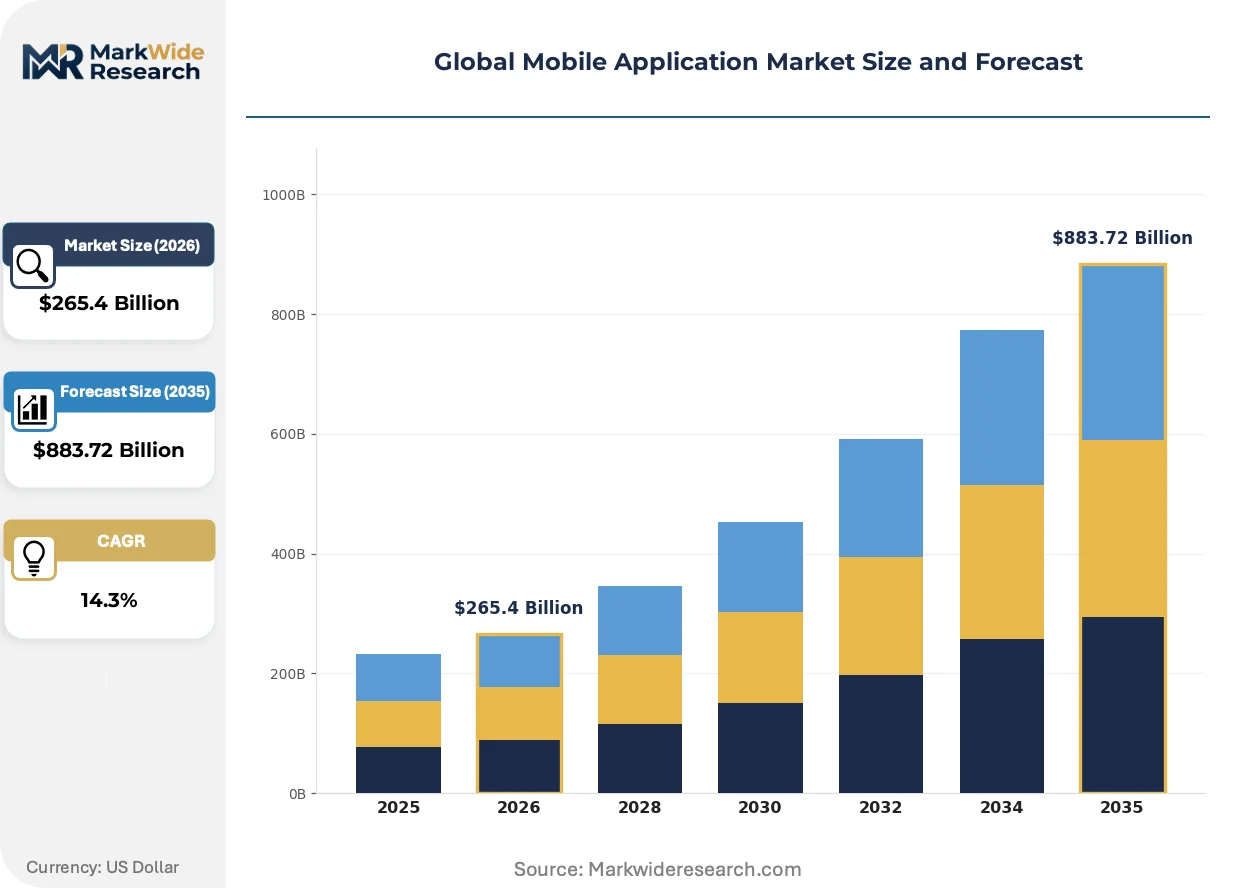
| Market Size in 2026 | $265.4 Billion |
| Market Size in 2035 | $883.72 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Social Networking, Entertainment, Productivity, Education, Finance, Travel Operating System: iOS, Android, Windows, KaiOS, HarmonyOS Distribution Channel: App Stores, Direct Downloads, OEM Pre-installs, Enterprise Deployment, Third-party Markets End User Category: Consumers, Small Businesses, Large Enterprises, Educational Institutions, Government Agencies |
| Companies Covered | Apple Inc., Google LLC, Microsoft Corporation, Tencent Holdings Ltd., ByteDance Ltd., Meta Platforms, Inc., Amazon.com, Inc., Alibaba Group Holding Ltd., Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Application Market Strategic Shifts & Innovations
On-device inference and federated learning architectures are redistributing computational load away from centralized cloud infrastructure, altering cost structures and data sovereignty postures simultaneously.
On-device large language models are displacing cloud-based natural language processing for consumer-facing applications. Mid-tier smartphone manufacturers in India and Southeast Asia are pre-installing compressed foundation models to differentiate hardware. This compression is displacing subscription revenue models for cloud API-dependent productivity applications.
The EU AI Act's risk classification system imposes documentation and human oversight requirements on high-risk application categories including biometric identification and credit scoring. Developers targeting European markets must maintain algorithmic audit trails and impact assessments. Health and finance segments face the steepest compliance burden, with some firms delaying EU launches to restructure decision pipelines.
Consumer acquisition through traditional app store search and featuring is yielding to creator-driven distribution via short-form video platforms. Independent developers in Brazil and the United States are building audience on TikTok and Instagram before directing traffic to direct-download progressive web applications. This channel shift is most pronounced among entertainment and social utility categories where demographic alignment with platform-native content formats accelerates conversion.
Global Mobile Application Market Segmentation
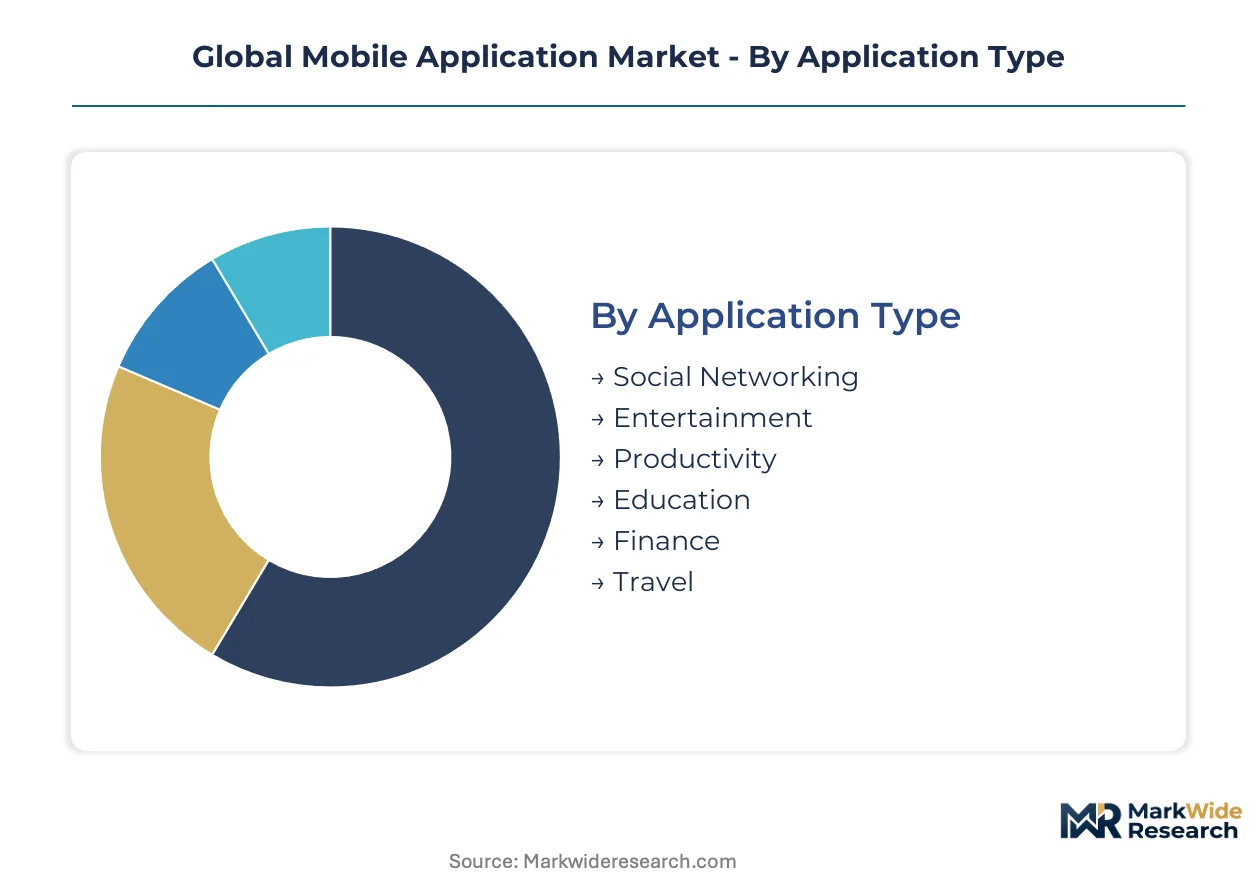
Mobile application segmentation reveals how platform economics and user behavior diverge across technical and commercial dimensions. Distinct monetization mechanics, compliance burdens, and distribution pathways shape competitive strategy within each category.
Application Type:
Social Networking faces acute substitution pressure from short-form video platforms that capture comparable engagement hours through algorithmic content feeds. Entertainment applications confront direct competition from browser-based streaming services and embedded media players that bypass app store economics entirely.
- Social Networking:Architected around real-time content feeds, messaging infrastructure, and network effect lock-in. Demand concentrates in India and Brazil where smartphone-first communication patterns dominate personal and commercial interaction. Regulatory scrutiny from the EU AI Act's transparency mandates elevates compliance costs for algorithmic ranking systems.
- Entertainment:Streaming video, interactive gaming, and immersive audio experiences optimized for variable network conditions. Monetization in the United States skews toward subscription models with in-app purchase supplementation. ByteDance's algorithmic distribution engines have redefined user acquisition economics for this segment.
- Productivity:Enterprise workflow tools replacing desktop suites with cloud-synchronized mobile experiences.
- Education:Interactive learning platforms and credentialing applications serving formal and self-directed instruction.
- Finance:Mobile banking, investment management, and payment infrastructure subject to RBI and SEBI oversight in India.
- Travel:Booking engines, itinerary management, and real-time logistics coordination for leisure and business mobility.
Social Networking anchors the volume base while Finance gains share at the steepest rate.
Operating System:
Cost tier stratification separates premium hardware-integrated platforms from volume-oriented open ecosystems. Development resource allocation follows divergent monetization potential across these environments.
- iOS:Proprietary mobile operating system with strict hardware-software integration and curated distribution through Apple's App Store. Revenue per user in the United States significantly exceeds Android equivalents due to affluent demographic concentration and frictionless payment infrastructure.
- Android:Open-source platform with customizable distributions across OEM manufacturers. Volume leadership in India, Brazil, and third-party markets sustains developer investment despite lower per-transaction yields. Google's Play Services integration creates platform loyalty through proprietary API dependencies.
- Windows:Desktop-heritage operating system with limited mobile market presence concentrated in enterprise productivity scenarios.
- KaiOS:Lightweight operating system for feature phones with essential application support and minimal hardware requirements.
- HarmonyOS:Huawei-developed distributed operating system subject to SAMR content moderation and data localization directives in China.
Android dominates installed base volume while HarmonyOS expands most quickly in its home market.
Distribution Channel:
Application maturity determines channel selection, with established developers pursuing direct relationships to circumvent platform fees. Geographic regulatory variation fragments optimal distribution strategy.
- App Stores:Centralized distribution through Apple App Store and Google Play with automated review processes and integrated payment systems. Platform gatekeeper economics extract substantial transaction shares while providing discovery infrastructure.
- Direct Downloads:Progressive web applications and sideloaded binaries that bypass store commissions entirely. Brazilian and United States developers increasingly leverage TikTok audience building to drive direct acquisition.
- OEM Pre-installs:Manufacturer-bundled applications on new device activation, particularly significant for finance and productivity categories in India.
- Enterprise Deployment:Mobile device management distribution for internal workforce applications with customized security policies.
- Third-party Markets:Regional app stores and alternative distribution platforms with localized payment integration.
App Stores retain volume leadership while Direct Downloads climb the fastest as creator-driven acquisition matures.
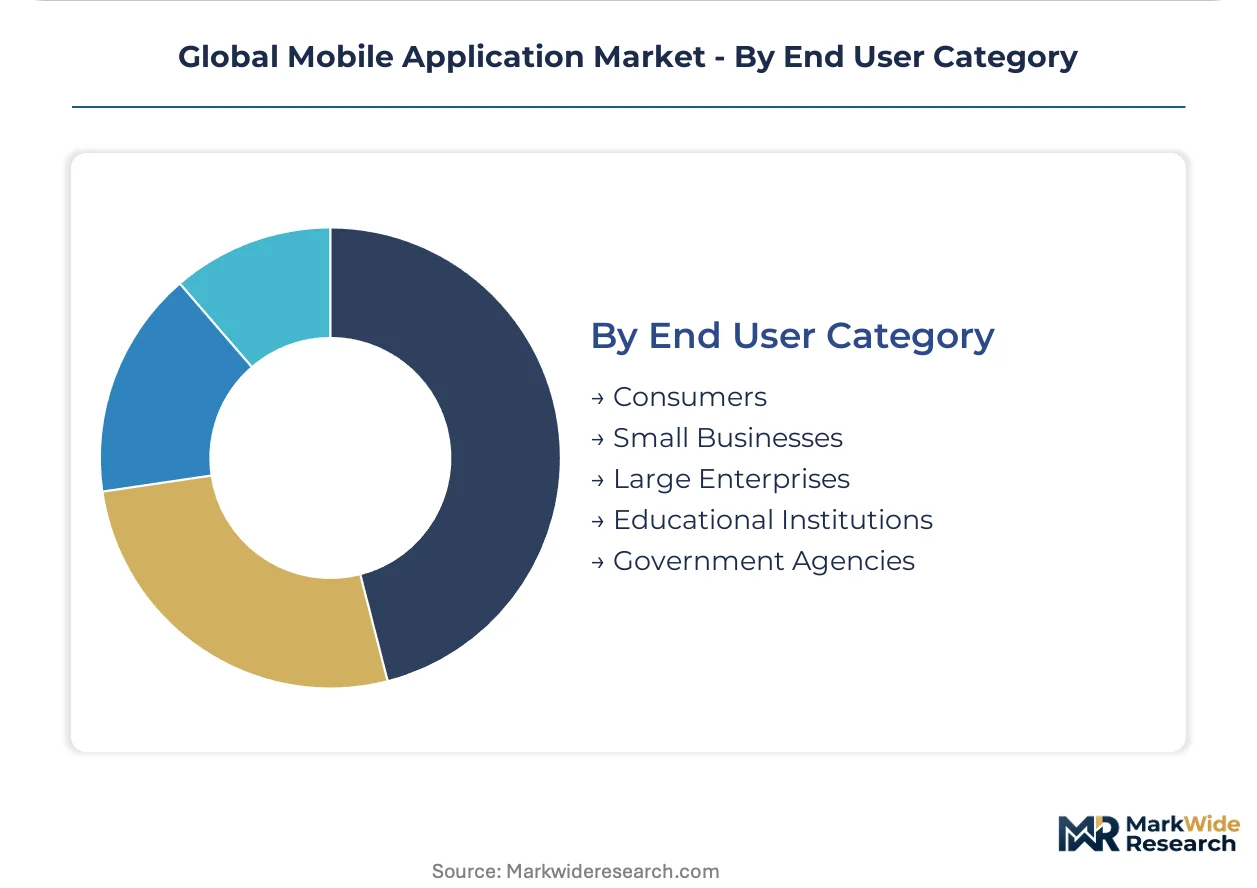
End User Category:
Customer type segmentation aligns pricing architecture with procurement sophistication and compliance requirements. Enterprise buyers demand administrative controls absent from consumer deployments.
- Consumers:Individual users selecting applications through personal preference with minimal organizational oversight. In-app purchase revenue concentrates in Entertainment and Social Networking categories.
- Small Businesses:Owner-operated enterprises in Brazil and India replacing desktop productivity suites with mobile-first finance and operations tools. Limited IT staff drives preference for turnkey cloud solutions.
- Large Enterprises:Organizations with dedicated mobility teams requiring SSO integration, audit logging, and custom security configurations.
- Educational Institutions:Schools and universities procuring licensed application suites with administrative dashboards and content filtering.
- Government Agencies:Public sector entities with procurement regulations mandating data residency and supply chain security certifications.
Consumers anchor the volume base while Small Businesses gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on mobile health applications shapes deployment strategies in the United States, while EU AI Act transparency mandates compress release timelines for algorithmic applications across European markets. India and Brazil concentrate demand growth as smartphone penetration deepens in tier-2 and tier-3 cities.
United States
Enterprise workflow digitization and premium consumer monetization drive iOS development investment. FDA 510(k) pathways regulate diagnostic health applications as medical devices, extending validation timelines for clinical evidence. Silicon Valley and Seattle anchor venture deployment into AI-infused productivity tools.
India
Rural smartphone penetration and vernacular-language financial inclusion applications expand addressable markets beyond urban centers. RBI and SEBI oversight governs mobile banking and investment management platforms. Bengaluru and Hyderabad concentrate developer talent pools for cloud-native architecture specialization.
Brazil
Small business replacement of desktop productivity suites with mobile-first finance tools accelerates enterprise adoption. ANVISA regulates health-related application claims under medical device frameworks. São Paulo anchors fintech application development clusters serving Latin American markets.
China
SAMR and MIIT enforce data localization and content moderation mandates that fragment technical infrastructure for multinational deployments. Dual carbon goals shape energy consumption standards for data-intensive applications. Shenzhen and Hangzhou concentrate hardware-software integration capabilities for on-device inference.
Germany
GDPR Article 25 privacy-by-design requirements elevate compliance tooling demand among application developers targeting European markets. KBA and national regulators enforce sector-specific standards for mobility and industrial applications. Munich and Berlin anchor enterprise mobility solution development for automotive and manufacturing verticals.
Global Mobile Application Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in mobile application platform provision. Apple and Google control essential distribution infrastructure through proprietary operating systems and curated app stores. Three strategic archetypes dominate: ecosystem integrators leveraging hardware-software alignment, algorithmic content platforms optimizing engagement metrics, and enterprise productivity enablers replacing legacy desktop workflows. Competitive moves concentrate on M&A for AI capability acquisition and geographic expansion into underpenetrated smartphone markets.
Within the ecosystem integrator tier, Apple Inc. and Google LLC exemplify platform gatekeeper positioning through hardware-software integration and distribution scale. ByteDance Ltd. occupies a distinct position among algorithmic content platforms, commanding disproportionate user engagement through recommendation engine sophistication. These three entities represent divergent competitive vectors: proprietary hardware alignment, open ecosystem volume leadership, and AI-native content distribution.
| Leading Market Players |
|---|
| Apple Inc. |
| Google LLC |
| Microsoft Corporation |
| Tencent Holdings Ltd. |
| ByteDance Ltd. |
| Meta Platforms, Inc. |
| Amazon.com, Inc. |
| Alibaba Group Holding Ltd. |
| Samsung Electronics |
| Others |
Cost & Logistics Intelligence
Platform-scale economies in cloud infrastructure and developer tooling concentrate cost advantages among ecosystem integrators, compressing price floors for independent publishers while elevating monetization thresholds for premium-tier distribution. This scale dynamic simultaneously reshapes supply chain sourcing patterns as smaller studios outsource compute and middleware to hyperscaler marketplaces.
Pricing Analysis
Geographic price spreads separate iOS monetization in the United States from Android yield curves in India and Brazil, where transaction friction and payment instrument penetration suppress effective revenue per user. Subscription-SaaS tiered models dominate enterprise productivity and finance segments, while freemium-in-app purchase hybrids anchor consumer entertainment. Price differentiation rests on platform curation stringency and hardware-software integration depth. Pricing pressure stems from ByteDance's algorithmic content platforms capturing engagement hours without app store economics. Small businesses in emerging markets exhibit highest price sensitivity; large enterprises with SSO integration requirements show lowest.
Supply Chain Analysis
India and Brazil concentrate developer talent pools for cloud-native mobile architecture, while the United States anchors AI/ML research and venture deployment infrastructure. Compute infrastructure draws from AWS, Google Cloud, and Azure hyperscaler regions; middleware and SDK dependencies rest on Firebase, Twilio, and Stripe API ecosystems. Single-source vulnerability concentrates around Apple's App Store and Google's Play Store distribution chokepoints. Distribution runs through platform-gated app stores, direct-download progressive web applications, and OEM pre-install partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile application markets sit in early-cycle expansion as enterprise workflow digitization and on-device AI inference create new monetization surfaces beyond traditional app store economics. Rural smartphone penetration in India and Brazil extends addressable markets for vernacular-language productivity tools.
For Market Incumbents: Secure algorithmic audit trail capabilities before EU AI Act enforcement intensifies against high-risk application categories. Consolidate developer tooling stacks to reduce cloud-native talent acquisition costs. Vertical integration into on-device inference hardware partnerships with mid-tier OEMs in India defends against compressed cloud-API subscription models.
For New Entrants and Emerging Players: Differentiate on federated learning architectures that satisfy FDA data minimization guidance without cloud transmission infrastructure. Target India's Tier-2 and Tier-3 cities with vernacular-language agricultural productivity applications. Build creator-driven distribution on TikTok and Instagram before directing traffic to direct-download progressive web applications that bypass platform gatekeeper fees.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enterprise productivity enablers with SSO integration and audit logging capabilities. Long-term viability across the projection horizon favors platforms with proprietary on-device inference compression or exclusive OEM pre-install relationships. Acquisition target archetype: cloud-native specialists with Kubernetes orchestration expertise and existing RBI/SEBI compliance frameworks. Signal to watch: FDA 510(k) clearance velocity for diagnostic health applications as clinical evidence requirements strain startup capital reserves.
| Strategic Initiative | Industry Significance |
|---|---|
| On-Device AI Compression Partnership | Mid-tier OEM pre-installs in India displace cloud-API subscription dependency for productivity tools. |
| EU AI Act Compliance Automation | Explainable AI middleware embeds algorithmic audit trails required for biometric and credit-scoring applications. |
| Federated Learning Architecture Deployment | Health applications satisfy FDA guidance on data minimization without cloud transmission infrastructure. |
| Creator-Driven Distribution Buildout | TikTok audience acquisition in Brazil and the United States bypasses app store discovery economics entirely. |
| Rural Vernacular Localization | Tier-2 and Tier-3 Indian cities present underdeveloped demand for agricultural finance and operations tools. |
Research Approach
Initial hypotheses were tested against primary input from mobile platform engineering leads, app store product managers, enterprise IT procurement officers, and fintech compliance directors and refined through secondary validation. Primary fieldwork combined structured interviews with developer ecosystem stakeholders and enterprise mobility decision-makers. Secondary sources encompassed SEC filings from platform gatekeepers, App Annie/Sensor Tower engagement metrics, hyperscaler capex disclosures, and regulatory filings with FDA, EU AI Act documentation, and RBI circulars. Bottom-up installation and revenue estimates triangulated against top-down smartphone penetration and digital payment growth curves.
Variance decomposition across the projection horizon isolates adoption rate uncertainty, regulatory implementation timing, and platform policy shifts as primary forecast sensitivity drivers. Segmentation dimensions modeled include application type, operating system, distribution channel, organization size, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns and adjusted for enforcement intensity of GDPR Article 25 and EU AI Act transparency mandates. Industry-specific inputs incorporate FDA 510(k) pathway velocity and SAMR data localization directive implementation.
Forecasts assume regulatory continuity in EU AI Act risk classification frameworks and FDA mobile health guidance; material policy shifts would require re-modeling of deployment timelines and compliance cost structures. Forecasts reflect assumptions on platform gatekeeper fee stability and cross-border data flow permissibility. Recalibration cycles align with material shifts in algorithmic governance enforcement, on-device inference hardware availability, and creator-driven distribution channel maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Performance Appraisal Software Market
Software & Services
Mobile Application Development Platform (MADP) Market
Software & Services
Problem Management Software Market
Software & Services
Global Virtual Data Room (VDR) Market
Software & Services
Appointment Scheduling Software Market
Software & Services
Global Diagram Software Market
Software & Services
Global Screen and Script Writing Software Market
Software & Services
Data Migration Software Services Market
Software & Services
Emotion Recognition and Sentiment Analysis Software Market
Software & Services
Sales Training Software Market
Software & Services
Change Control Management Software Market
Software & Services
Global Continuous Integration Tools Market
Software & Services
Enterprise Resource Planning Market
Software & Services
Service Dispatch Software Market
Software & Services
Website Builder Tool Market
Software & Services
Lighting Control Software Market