
 Automotive Endpoint Authentication Market | 2026-2036
Automotive Endpoint Authentication Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Endpoint Authentication Market Intelligence
Fleet operator consolidation around telematics-managed pools is repositioning procurement leverage toward volume-contracted authentication stacks. NXP Semiconductors N.V. leverages its secure element portfolio to anchor OEM trust in hardware-rooted identity verification. Infineon Technologies AG sustains R&D intensity across automotive-qualified TPM architectures. Robert Bosch GmbH competes through integrated vehicle system design that embeds endpoint authentication within broader domain controllers.
Automotive endpoint authentication denotes the cryptographic verification of identity for every connected node within a vehicle ecosystem, typically employing hardware security modules with tamper-resistant silicon and challenge-response protocols to prevent unauthorized access to CAN bus segments and over-the-air interfaces. Its primary commercial purpose is to enforce zero-trust boundaries between infotainment domains, powertrain controllers, and external cloud services. Biometric systems command premium positioning where driver-specific cabin personalization intersects with theft deterrence, while cloud-based solutions represent the fastest-expanding architecture as automakers migrate key lifecycle management off-vehicle. RFID and NFC technologies retain cost advantages in passive entry applications, though Bluetooth Low Energy is displacing legacy radio configurations in smartphone-as-key deployments.
NHTSA guidelines and UNECE R155 collectively shape product standards by mandating cybersecurity management systems as prerequisites for vehicle type approval, directly conditioning market access for authentication subsystem suppliers. The EU AI Act and GDPR impose additional constraints on biometric data processing within European vehicle deployments, forcing architecture choices toward edge-based template storage. Stakeholders must monitor regulatory divergence between hardware-centric federal safety mandates and data-sovereignty privacy frameworks to align R&D roadmaps with divergent compliance timelines.
Market Dynamics
UNECE R155 mandates are compressing certification timelines for hardware security modules, forcing tier-1 suppliers to pre-integrate authentication stacks before vehicle platform freezes.
Growth Catalysts
- Fleet Telematics Consolidation:Commercial vehicle operators in Germany are mandating tamper-proof identity verification for pooled asset management, expanding procurement volumes for embedded security modules.
- UNECE R155 Type Approval:Cybersecurity management system requirements now condition market access across EU member states, accelerating OEM adoption of standardized challenge-response protocols.
- Bluetooth Low Energy Displacement:Smartphone-as-key architectures are replacing legacy RFID passive entry systems in premium vehicle segments, driving refresh cycles for authentication hardware.
Market Restraints
- Silicon Supply Concentration:Advanced secure element fabrication depends on concentrated foundry capacity in Taiwan, exposing authentication module lead times to geopolitical disruption.
- Biometric Cost Structure:Driver-specific cabin personalization systems require specialized infrared and capacitive sensor arrays, pricing these configurations above mass-market penetration thresholds.
- GDPR Template Storage Constraints:EU data sovereignty rules prevent cloud-based biometric profile hosting, forcing edge-based architectures that increase per-unit silicon requirements.
Strategic Opportunities
- India Fleet Digitization:Commercial vehicle telematics penetration remains below Western levels, creating whitespace for authentication-integrated fleet management platforms under BIS automotive electronics standards.
- Software-Defined Vehicle Convergence:Domain controller centralization enables consolidated identity verification across zonal architectures, reducing discrete module counts while expanding security scope.
- EU AI Act Compliance Services:Biometric driver monitoring systems require algorithmic transparency documentation, opening advisory revenue streams for certification engineering specialists.
Industry Challenges
- Cryptographic Engineering Talent Scarcity:Automotive-qualified firmware developers with hardware security module expertise command premium compensation, constraining R&D scaling for mid-tier suppliers.
- Multi-Standard Certification Overlap:Simultaneous UNECE R155, ISO/SAE 21434, and GDPR compliance creates conflicting documentation requirements that extend product validation cycles.
- Legacy CAN Bus Integration Friction:Older vehicle architectures lack secure onboard communication channels, requiring gateway retrofits that complicate aftermarket authentication deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Endpoint Authentication Market |
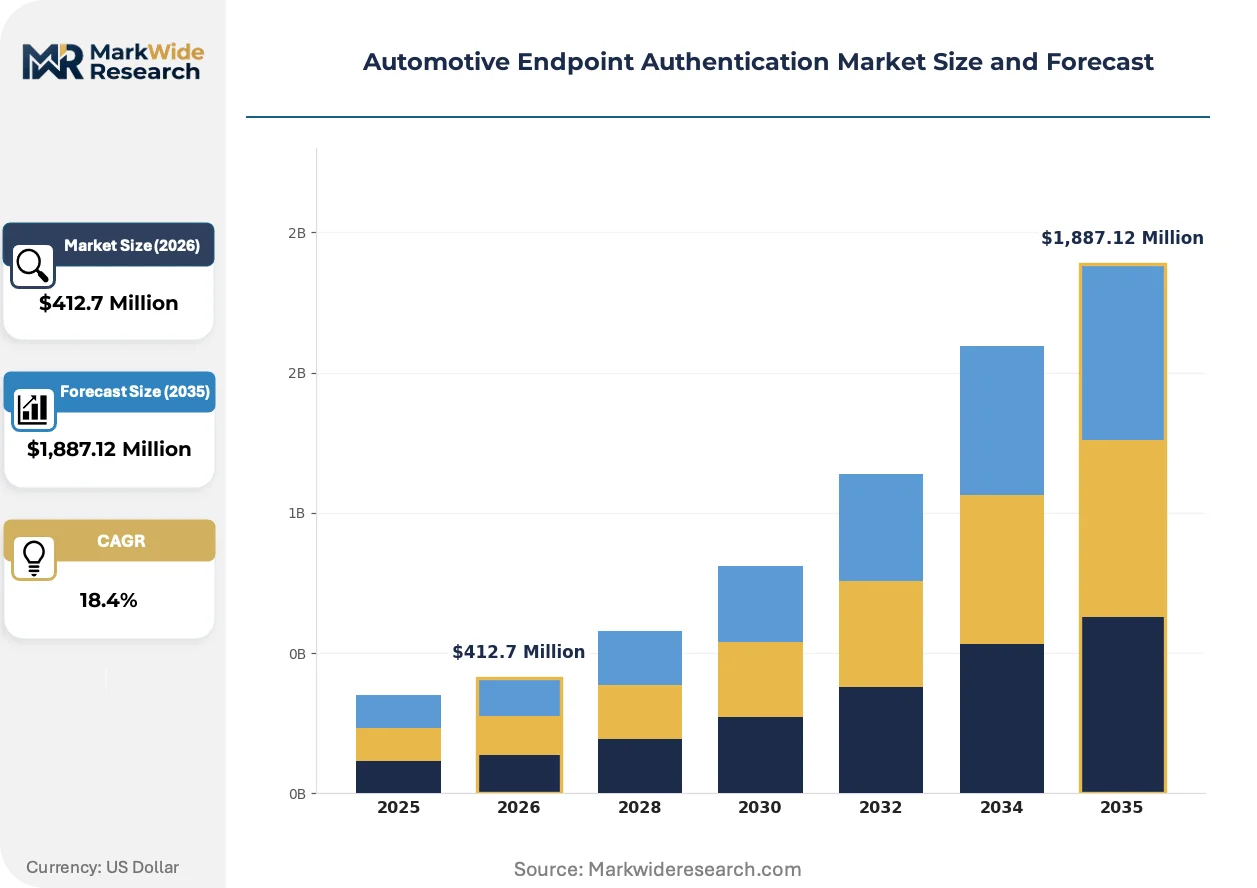
| Market Size in 2026 | $412.7 Million |
| Market Size in 2035 | $1,887.12 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biometric Systems, Smart Keys, Token-Based Systems, Remote Authentication End User: OEMs, Fleet Operators, Aftermarket Providers, Vehicle Assemblers Technology: RFID, NFC, Bluetooth, Cloud-Based Solutions Application: Access Control, Software Updates, Vehicle Tracking, User Identification |
| Companies Covered | NXP Semiconductors N.V., Infineon Technologies AG, STMicroelectronics N.V., Renesas Electronics Corporation, Microchip Technology Incorporated, Continental AG, Robert Bosch GmbH, Texas Instruments, Harman International Industries Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Endpoint Authentication Market Strategic Shifts & Innovations
Post-quantum cryptographic migration is forcing premature hardware refresh cycles as automakers confront long vehicle lifecycles against evolving threat models.
Hardware security modules with lattice-based algorithm support are electrifying trust anchor deployment across zonal E/E architectures. Tier-1 suppliers in Stuttgart and Tokyo are qualifying tamper-resistant silicon for 15-year service horizons. This capability compression is eliminating software-only authentication from next-generation platform bids.
EU AI Act algorithmic transparency mandates are restructuring biometric system documentation requirements for driver monitoring deployments. Automotive OEMs must now maintain technical files on neural network training data provenance. German premium manufacturers are responding by shifting template matching to edge-based execution within NXP and Infineon secure enclaves.
Fleet procurement departments are consolidating authentication stack sourcing under multi-year volume contracts with telematics platform providers. Traditional discrete component distributors are losing specification influence to integrated vehicle system vendors. This channel compression is most visible in German commercial vehicle manufacturing clusters around Munich and Wolfsburg.
Automotive Endpoint Authentication Market Segmentation
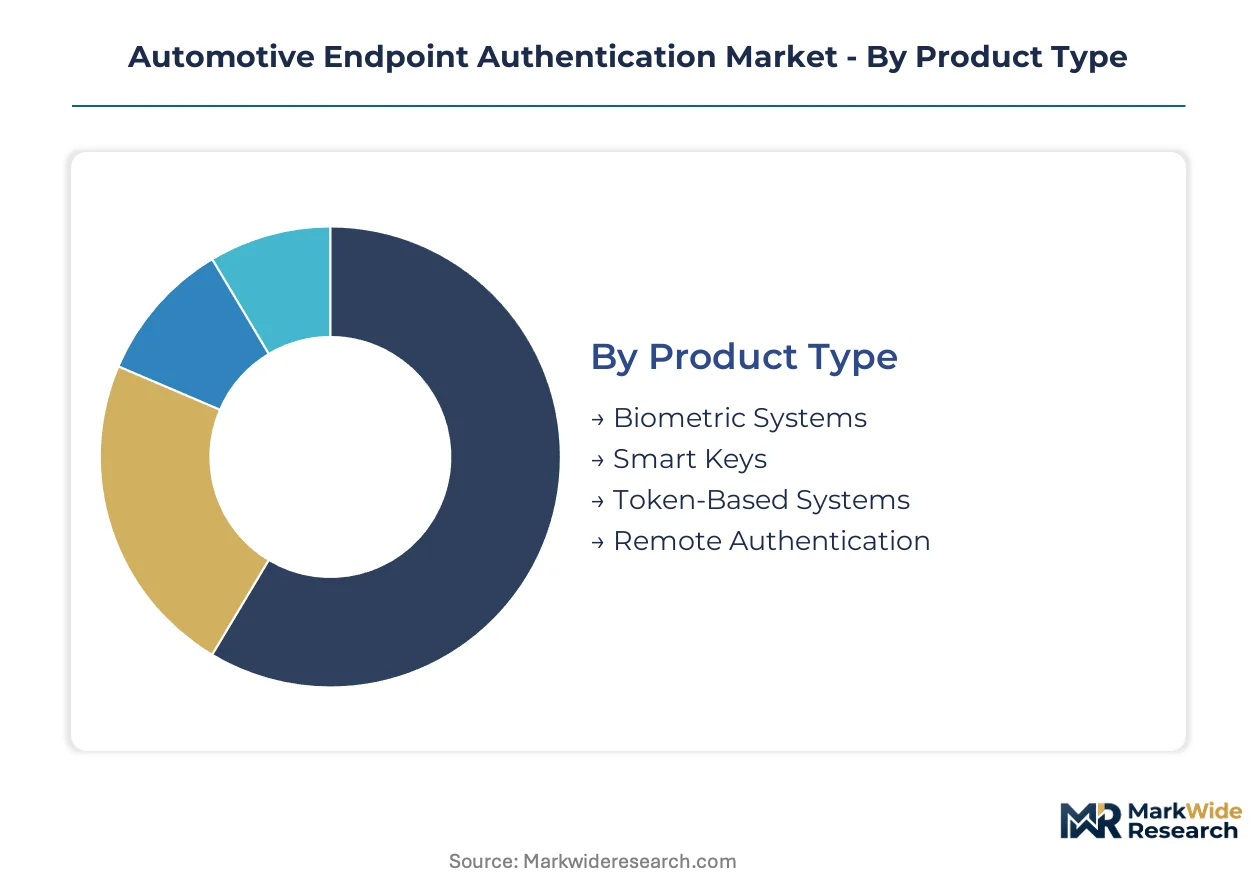
Automotive endpoint authentication segments diverge sharply in capital requirements, with biometric sensor arrays and secure element fabrication demanding foundry investments that software-centric alternatives avoid. Fleet procurement patterns and UNECE R155 certification timelines reshape which segments absorb R&D expenditure.
Product Type:
Biometric systems and smart keys command the heaviest upfront capital, requiring specialized silicon foundry access and precision sensor manufacturing that token-based alternatives circumvent.
- Biometric Systems:Infrared and capacitive sensor arrays perform driver-specific template matching within tamper-resistant enclaves. German premium manufacturers concentrate procurement here, compelled by EU AI Act algorithmic transparency mandates that favor edge-based execution over cloud hosting.
- Smart Keys:Bluetooth Low Energy and ultra-wideband radios enable smartphone-as-key architectures with challenge-response protocols anchored in hardware security modules. Demand clusters in Stuttgart and Wolfsburg manufacturing corridors where OEM platform freezes compress supplier qualification timelines.
- Token-Based Systems:Physical key fobs with embedded secure elements retain cost advantages in economy vehicle segments.
- Remote Authentication:Cloud-credential verification for over-the-air access management minimizes per-unit hardware costs.
Most installed capacity flows through Smart Keys. Expansion is steepest in Biometric Systems.
End User:
OEMs and fleet operators drive volume concentration, with procurement centralization favoring suppliers capable of multi-year volume contracting.
- OEMs:Integrated vehicle system vendors embed authentication within domain controllers, consolidating discrete module counts. Munich and Wolfsburg clusters demand pre-integrated stacks ahead of platform freezes.
- Fleet Operators:Commercial vehicle pools mandate tamper-proof identity verification for asset management, expanding procurement volumes for embedded security modules under telematics-managed contracts.
- Aftermarket Providers:Gateway retrofit solutions address legacy CAN bus architectures lacking secure onboard channels.
- Vehicle Assemblers:Contract manufacturers integrate authentication hardware specified by platform owners.
OEMs dominate current procurement volumes. Fleet operators are gaining share fastest as telematics consolidation accelerates.
Technology:
RFID and NFC retain established cost structures while Bluetooth and cloud architectures capture specification influence in next-generation platforms.
- Bluetooth:Low-energy radio configurations displace legacy passive entry systems in smartphone-as-key deployments. Premium segments in Germany specify these for driver-phone pairing protocols.
- Cloud-Based Solutions:Lifecycle management and credential provisioning migrate off-vehicle, reducing embedded silicon requirements. GDPR constraints on biometric data force hybrid architectures with edge template storage.
- RFID:Passive radio-frequency identification retains presence in economy vehicle passive entry applications.
- NFC:Near-field communication supports short-range smartphone authentication with minimal power draw.
Bluetooth carries the largest installed base. Cloud-based solutions are climbing the fastest as automakers decouple key management from vehicle hardware.
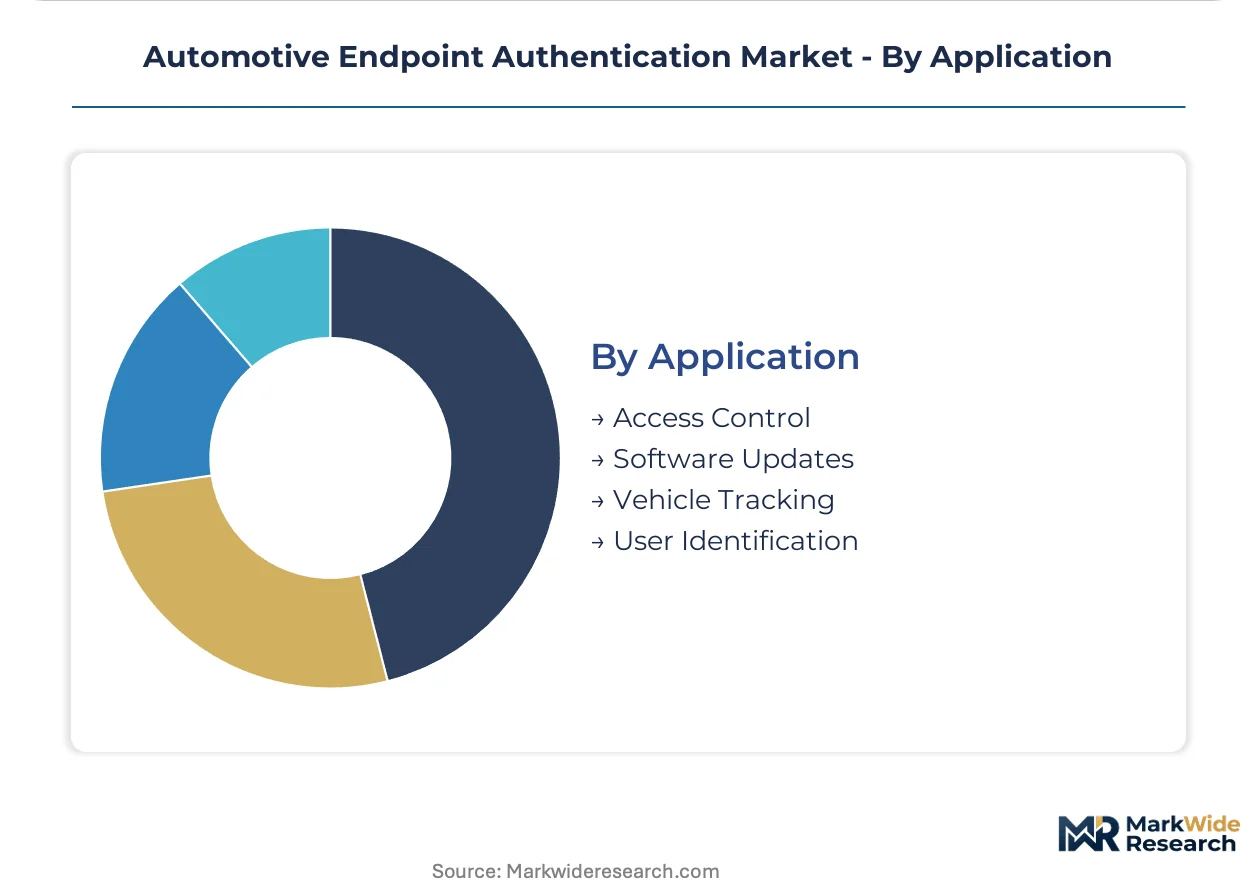
Application:
Access control and software updates concentrate regulatory scrutiny, with UNECE R155 mandating standardized protocols for type approval.
- Access Control:Cryptographic verification secures cabin entry and powertrain enablement across infotainment and drivetrain domains. Fleet operators in Germany mandate this for pooled commercial vehicle pools.
- Software Updates:Over-the-air firmware delivery requires authenticated code signing and verification. UNECE R155 cybersecurity management systems condition EU market access on robust update protocols.
- Vehicle Tracking:Telematics-linked identity verification supports stolen vehicle recovery and usage-based insurance.
- User Identification:Driver-specific profile loading enables cabin personalization and parental control enforcement.
Access control absorbs the most authentication hardware. Software updates are gaining share fastest as OTA deployment expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's regulatory stringency around UNECE R155 outpaces the United States' voluntary NHTSA guidance, compressing supplier qualification timelines in Stuttgart while Detroit OEMs pursue dual-track compliance strategies. This divergence reshapes where authentication hardware gets specified first.
Germany
Commercial fleet operators in Munich and Wolfsburg mandate tamper-proof identity verification for pooled asset management, expanding procurement volumes for embedded security modules. UNECE R155 cybersecurity management system requirements condition EU market access, forcing OEMs to pre-integrate authentication stacks before platform freezes. The Stuttgart manufacturing corridor concentrates supplier engineering resources around hardware security module qualification.
United States
NHTSA guidelines shape product development without mandating specific protocols, allowing OEMs flexibility in challenge-response architecture selection. The IRA's domestic content provisions incentivize secure element fabrication reshoring discussions, though foundry capacity remains concentrated offshore. Detroit's automotive engineering clusters drive specification influence for smartphone-as-key deployments across premium vehicle segments.
China
Domestic OEMs accelerate connected vehicle platform deployment, expanding demand for cryptographic verification across infotainment and drivetrain domains. MIIT cybersecurity standards for intelligent vehicles mandate identity authentication for over-the-air update channels. The Yangtze River Delta semiconductor ecosystem cultivates local secure element design capabilities alongside foreign supplier partnerships.
Japan
Automotive-qualified hardware security module expertise concentrates among established electronics conglomerates serving domestic OEM platform requirements. METI's connected vehicle security guidelines emphasize standardized authentication protocols for vehicle-to-infrastructure communication. The Nagoya manufacturing corridor integrates endpoint verification within domain controller architectures for next-generation electric vehicle platforms.
India
Commercial vehicle telematics penetration remains below Western levels, creating whitespace for authentication-integrated fleet management platforms. BIS automotive electronics standards establish baseline security requirements for connected vehicle components entering the domestic market. The Tamil Nadu and Maharashtra manufacturing corridors attract telematics platform providers seeking volume-contracted authentication stack deployment.
Automotive Endpoint Authentication Market Key Industry Players
German producers anchor one tier; Dutch and Japanese specialists hold differentiated positions in secure element architectures. Market structure tilts toward consolidated procurement leverage as fleet operators and OEMs consolidate multi-year volume contracts with integrated system vendors. Three archetypes dominate: semiconductor fabricators with automotive-qualified secure element portfolios, tier-1 system integrators embedding authentication within domain controllers, and telematics platform providers consolidating authentication stack sourcing. Competitive moves center on pre-integration partnerships ahead of vehicle platform freezes and backward integration into secure element design capabilities.
Among semiconductor specialists, NXP Semiconductors N.V. and Infineon Technologies AG occupy positions exemplifying hardware-rooted trust anchor deployment, while Robert Bosch GmbH represents integrated vehicle system design archetypes that embed authentication within broader domain controller architectures. These three entities illustrate how competitive positioning diverges between silicon-centric and system-level approaches to endpoint verification.
| Leading Market Players |
|---|
| NXP Semiconductors N.V. |
| Infineon Technologies AG |
| STMicroelectronics N.V. |
| Renesas Electronics Corporation |
| Microchip Technology Incorporated |
| Continental AG |
| Robert Bosch GmbH |
| Texas Instruments |
| Harman International Industries Incorporated |
| Others |
Cost & Logistics Intelligence
Secure element fabrication costs in Taiwan flow through hardware security module pricing tiers, with foundry capacity constraints compressing margins for tier-1 suppliers serving German OEM platform freezes. Biometric sensor arrays carry premium positioning where EU AI Act compliance adds edge-based silicon requirements, while Bluetooth Low Energy modules compete on volume scale in smartphone-as-key deployments.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for automotive-qualified secure elements, though Taiwan concentration maintains premium tiers for tamper-resistant silicon. Three-tier pricing structure across premium, standard, and economy levels separates UNECE R155-certified modules from uncertified alternatives and legacy RFID configurations. Cost compression in economy vehicle segments is intensifying because fleet operators consolidate multi-year volume contracts. Aftermarket providers show highest price sensitivity; German premium OEMs demonstrate lowest sensitivity where platform integration timelines override unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan foundry capacity for advanced secure element nodes, exposing authentication module lead times to geopolitical disruption. Supply draws from Taiwan, South Korea, and Germany for semiconductor fabrication, with sensor arrays sourcing from Japan and China. Silicon wafers, cryptographic IP cores, and automotive-grade packaging materials constitute critical input dependencies. Tariff exposure runs through cross-border chip shipments amid tightening export controls. Distribution runs through tier-1 system integrators embedding authentication within domain controllers, bypassing traditional discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive endpoint authentication has shifted to a late-cycle quality story as UNECE R155 mandates force OEMs toward pre-integrated, certified stacks rather than cost-optimized alternatives.
For Market Incumbents: Deploy pre-integration partnerships ahead of vehicle platform freezes to lock out modular competitors. Deepen captive supply of secure element design capabilities through backward integration into automotive-qualified foundry relationships. Software-only authentication vendors pose substitution threat as hardware security modules absorb specification influence. For New Entrants and Emerging Players: Enter via India commercial vehicle telematics whitespace where BIS standards create compliant entry paths below German procurement concentration. Target fleet operator procurement departments consolidating authentication stack sourcing under telematics-managed contracts. Go-to-market leverage rests on volume-contracted pricing under multi-year service agreements. For Investors and Strategic Acquirers: Consolidation pressure builds where cryptographic engineering talent scarcity constrains R&D scaling for mid-tier suppliers. Long-term viability favors semiconductor fabricators with automotive-qualified secure element portfolios and tier-1 system integrators with domain controller anchoring. Signal to monitor: post-quantum cryptographic migration forcing premature hardware refresh cycles across extended vehicle lifecycles.| Strategic Initiative | Industry Significance |
|---|---|
| Hardware Security Module Pre-Integration | UNECE R155 platform freezes compress supplier qualification timelines for tier-1 embedding. |
| Post-Quantum Cryptographic Migration | Lattice-based algorithm support eliminates software-only authentication from next-generation bids. |
| Edge-Based Biometric Template Storage | EU AI Act and GDPR constraints force architectures toward NXP and Infineon secure enclaves. |
| Fleet Telematics Stack Consolidation | Volume-contracted authentication sourcing shifts procurement leverage toward integrated platform providers. |
| India Manufacturing Footprint Expansion | Tamil Nadu and Maharashtra corridors attract telematics platform providers seeking whitespace deployment. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet telematics operators with secondary validation against UNECE regulatory filings, vehicle production databases, IHS Markit registration data, and SEC disclosures from semiconductor fabricators. Bottom-up segment sizing and top-down market reconciliation anchored volume estimates.
Segment-weighted modeling distributed value across biometric systems, smart keys, token-based systems, and remote authentication by vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from fitted growth curves applied to base-year estimates across the projection horizon. Forecast inputs incorporated UNECE R155 implementation timelines, fleet telematics penetration curves, and secure element foundry capacity utilization.
Inputs from regulatory filings and semiconductor supply disclosures were available through the study window; gaps in OEM platform freeze schedules and post-quantum standardization timelines introduce uncertainty bands. Forecasts reflect documented assumptions about certification adoption rates and foundry expansion plans. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Geofencing Market
Security Software
Public Cloud Management and Security Services Market
Security Software
Website Monitoring Software Market
Security Software
Application Control Market
Security Software
Global Background Screening Market
Security Software
Mobile Data Protection Solutions and Services Market
Security Software
Global Data Classification Market
Security Software
Employee Computer Monitoring Software Market
Security Software
Broadcast Censorship Solutions Market
Security Software
Cyber Attack Simulation Software Market
Security Software
Global Secure Access Service Edge Market
Security Software
Endpoint Detection and Response Market
Security Software
North America Secure Access Service Edge Market
Security Software
Identity Governance and Administration Market
Security Software
User Provisioning Software Market
Security Software
Identity-As-A-Service (Idaas) Market