
 Middle East and Africa Food Fortifying Agents Market | 2026-2036
Middle East and Africa Food Fortifying Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Food Fortifying Agents Market Foresight
Market Context
Modular premix bundling is hardening as the dominant procurement format across Middle East and Africa food fortifying agents buyers. Tate & Lyle PLC leverages its sweetener-fortifier integration to anchor supply relationships with regional beverage bottlers. Chr. Hansen Holding AS specializes in probiotic strain customization for North African dairy cooperatives. BASF SE dominates synthetic vitamin A and D3 production scale serving sub-Saharan flour millers.
Technical Definition and Segments
Food fortifying agents are concentrated bioactive compounds—vitamins, minerals, amino acids, and live microbial cultures—engineered to precise potency specifications and incorporated into food matrices to correct or prevent nutritional deficiencies in populations. These agents undergo microencapsulation, spray drying, or fluid bed agglomeration to ensure thermal stability and controlled release during processing and digestion. Vitamins command the largest value share among product types due to mandatory flour and edible oil fortification programs, while probiotics represent the fastest-expanding category as fermented dairy consumption spreads through East African urban centers. The food and beverage application segment absorbs the majority of volume, though dietary supplements are capturing margin pools through direct-to-consumer channels in Gulf Cooperation Council markets. Powder formulations maintain manufacturing preference for bulk handling and extended shelf stability in climates with variable cold chain reliability.
Regulatory Environment
South Africa's National Regulator for Compulsory Specifications enforces mandatory maize meal fortification standards that dictate vitamin and mineral minimums for domestic millers and importers alike. The Gulf Standardization Organization coordinates fortification labeling and maximum permissible levels across Saudi Arabia, UAE, and Kuwait, creating a partially harmonized compliance zone that reduces formulation fragmentation for suppliers. East African Community technical regulations on food fortification are progressively converging with Codex Alimentarius frameworks, though implementation timelines vary by member state. Stakeholders must monitor divergence between national fortification schedules and actual laboratory verification capacity, as enforcement gaps create both compliance risk and first-mover advantage for quality-certified suppliers.
Market Dynamics
Modular premix bundling is hardening procurement standards across Middle East and Africa food fortifying agents buyers, compressing supplier qualification timelines and elevating technical documentation requirements for vitamin stability under tropical storage conditions.
Growth Catalysts
- FSSAI-aligned fortification mandates:East African Community technical regulations are converging with Codex Alimentarius frameworks, accelerating compliance adoption across Kenya, Tanzania, and Uganda.
- Urban dairy consumption clusters:Fermented dairy demand in Ethiopian and Kenyan cities is expanding probiotic fortification requirements for regional dairy cooperatives.
- Flour miller procurement scale:South Africa's National Regulator for Compulsory Specifications enforces vitamin and mineral minimums that drive consistent bulk premix demand from domestic and import channels.
Market Restraints
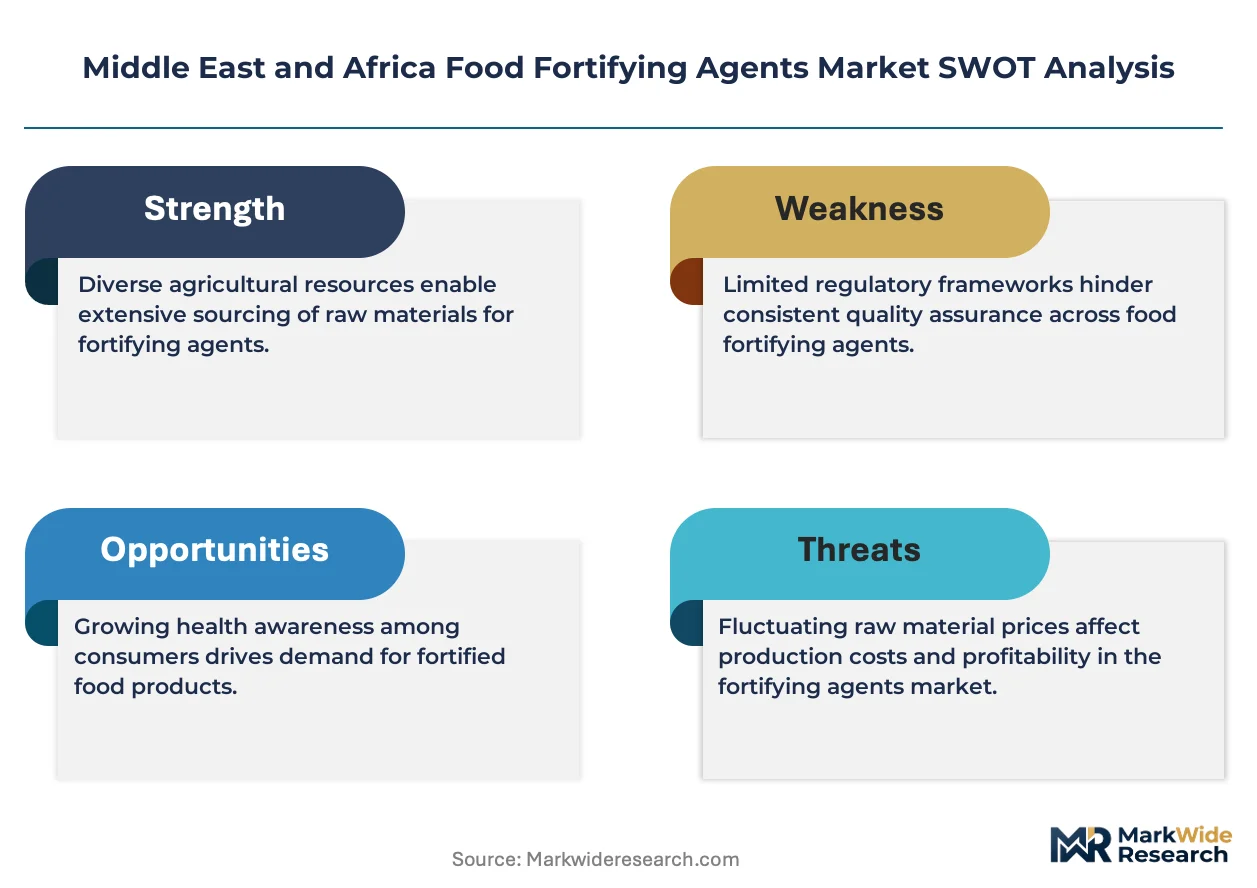
- Vitamin A and D3 input concentration:Synthetic vitamin production concentrates among a limited supplier base, creating supply security exposure for sub-Saharan flour millers.
- Cold chain reliability gaps:Probiotic strain viability degrades rapidly in climates with intermittent refrigeration, limiting distribution reach to secondary cities.
- Gulf Standardization Organization divergence:Partial harmonization across Saudi Arabia, UAE, and Kuwait still permits national labeling variations that fragment formulation runs.
Strategic Opportunities
- Nigerian infant nutrition corridor:Vitamin premix procurement acceleration by Lagos and Kano-based manufacturers creates first-mover positioning for certified suppliers.
- Direct-to-consumer supplement channels:Gulf Cooperation Council markets are developing e-commerce and pharmacy retail pathways for premium micronutrient products.
- Spray drying-microencapsulation convergence:Combined thermal protection technologies enable probiotic inclusion in ambient-stable food matrices previously inaccessible to live cultures.
Industry Challenges
- Laboratory verification capacity gaps:Divergence between national fortification schedules and actual testing infrastructure in East African member states creates enforcement uncertainty.
- Microencapsulation equipment capex:Fluid bed agglomeration systems require substantial capital deployment that constrains mid-scale processor entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Food Fortifying Agents Market |
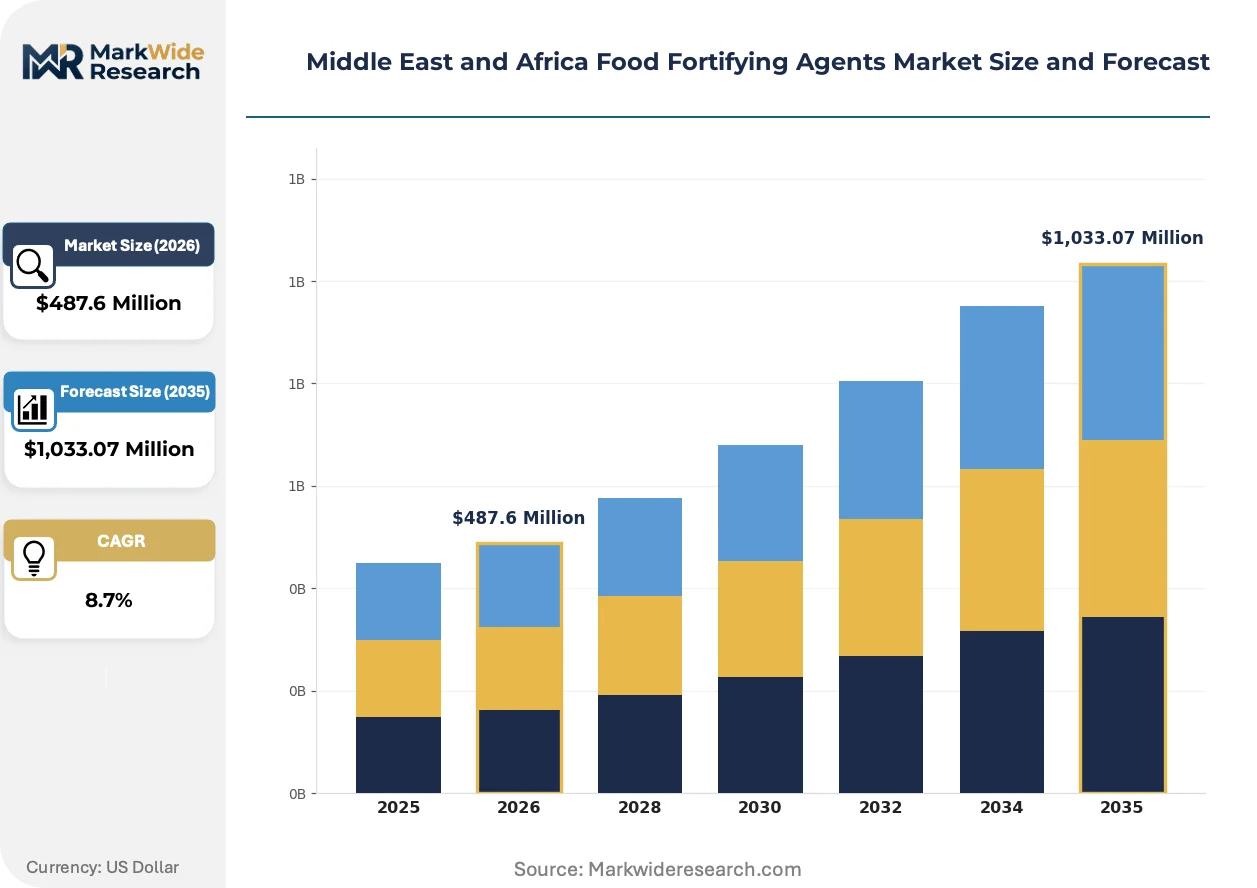
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Amino Acids, Probiotics Application: Food & Beverage, Nutraceuticals, Dietary Supplements, Animal Feed End User: Manufacturers, Retailers, Health Professionals, Consumers Form: Powder, Liquid, Granules, Tablets |
| Companies Covered | Tate & Lyle PLC, Koninklijke DSM NV, Chr. Hansen Holding AS, Archer Daniels Midland Company, Ingredion Incorporated, Africa Improved Foods Rwanda Limited, BASF SE, Cargill, Incorporated, Glanbia PLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Food Fortifying Agents Market Shifts & Advancements
Active reformulation of fortifying agent delivery systems is reshaping competitive positioning among Middle East and Africa suppliers, with thermal stability and controlled-release properties now determining procurement decisions ahead of base nutrient cost.
Microencapsulation technology is consolidating as the dominant delivery platform for heat-sensitive vitamins and probiotics across regional processed food manufacturing. Nigerian and Ethiopian infant nutrition producers are adopting spray-dried lipid-coated premixes at accelerating rates. This technology is consolidating supplier relationships around technical service capabilities rather than commodity pricing.
South Africa's National Regulator for Compulsory Specifications is tightening maize meal fortification verification protocols, expanding laboratory audit frequencies for domestic millers. Industrial consequence includes elevated documentation burdens and accelerated third-party certification adoption. Sub-Saharan flour millers are responding by pre-qualifying suppliers with established stability testing portfolios.
Buying committees at regional beverage bottlers are unbundling sweetener and fortifier procurement decisions that were historically combined. Tate & Lyle PLC's integrated supply relationships face displacement by specialized vitamin premix vendors with dedicated technical support teams. This pattern concentrates in South Africa's Johannesburg-Cape Town processed food corridor where formulation complexity has outpaced generalist supplier capabilities.
Middle East and Africa Food Fortifying Agents Market Segmentation
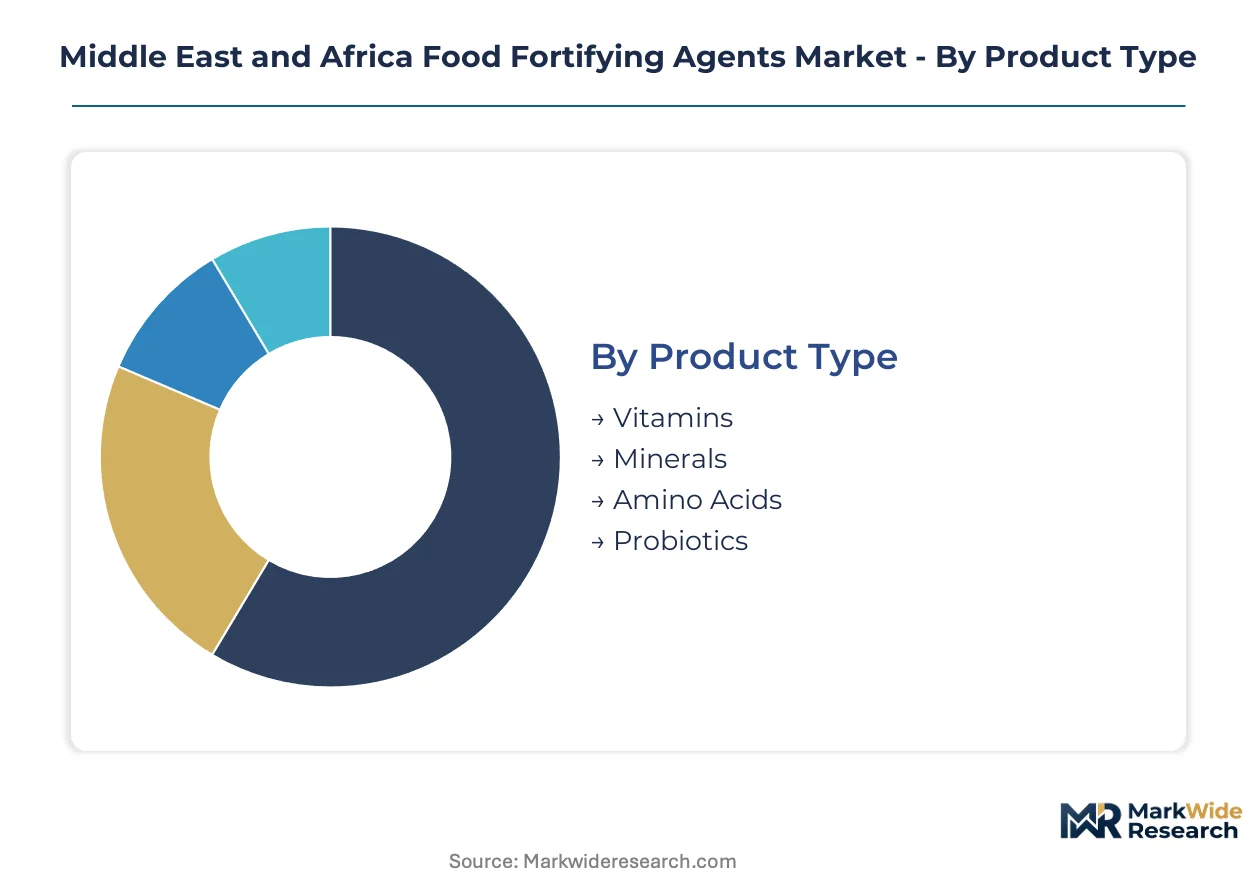
Food fortifying agents in the Middle East and Africa exhibit divergent integration patterns across product and application categories. Some segments operate as standalone nutritional inputs while others embed deeply into processed food matrices, reshaping supplier qualification requirements and procurement timelines for regional buyers.
Product Type:
Standalone vitamin and mineral premixes serve commodity fortification programs, while probiotic strains require embedded delivery systems for viability.
- Vitamins:Concentrated bioactive compounds including A, D, B-complex, and E variants engineered to precise International Units. South African flour millers under National Regulator for Compulsory Specifications mandates drive bulk procurement of vitamin A and D3 premixes for maize meal fortification.
- Probiotics:Live microbial cultures—primarily Lactobacillus and Bifidobacterium strains—requiring microencapsulation or lipid coating for thermal protection. Kenyan and Ethiopian dairy cooperatives are expanding refrigerated fermented product lines, accelerating demand for ambient-stable probiotic delivery formats.
- Minerals:Iron, zinc, iodine, and selenium compounds standardized for food matrix incorporation. Gulf Cooperation Council edible oil processors utilize mineral premixes for mandatory fortification compliance.
- Amino Acids:Lysine, methionine, and tryptophan fortifiers targeting protein quality enhancement. Nigerian infant nutrition manufacturers procure amino acid premixes for complementary feeding formulations.
Vitamins lead volumes today; probiotics are gaining share fastest.
Application:
Cost tier stratification separates mass-market fortification from premium nutraceutical positioning across regional consumption patterns.
- Food & Beverage:Processed food matrices including flour, edible oil, dairy, and beverages receiving mandatory or voluntary nutrient enhancement. Johannesburg and Cape Town manufacturing corridors concentrate formulation demand for vitamin-mineral premix bundling.
- Dietary Supplements:Direct-to-consumer micronutrient products distributed through pharmacy and e-commerce channels. UAE and Saudi Arabia health-conscious demographics are expanding premium supplement procurement through retail digitization.
- Nutraceuticals:Functional food and beverage products with health claims beyond basic nutrition. East African urban centers are developing localized nutraceutical production for regional immune and digestive health positioning.
- Animal Feed:Livestock and aquaculture nutrition fortification for protein production efficiency. South African poultry integrators utilize feed-grade vitamin and mineral premixes for operational cost management.
Food and beverage applications dominate volume throughput; dietary supplements command the steepest margin expansion trajectory.
End User:
Customer type determines technical service intensity and procurement decision complexity across the value chain.
- Manufacturers:Industrial food processors, flour millers, dairy cooperatives, and infant nutrition producers requiring bulk premix supply with stability documentation. Nigerian and Ethiopian infant nutrition producers are accelerating supplier qualification for FSSAI-aligned vitamin premix sourcing.
- Retailers:Supermarket chains, pharmacy networks, and e-commerce platforms distributing fortified consumer packaged goods and supplements. Gulf Cooperation Council retail consolidation is compressing supplier negotiation timelines for private-label fortification programs.
- Health Professionals:Clinicians, nutritionists, and public health programs prescribing or distributing therapeutic nutritional products. East African Community national fortification programs engage health professionals for compliance monitoring and consumer education.
- Consumers:Direct purchasers of fortified foods, supplements, and specialized nutrition products. Kenyan and Ethiopian urban consumers are expanding probiotic-enriched dairy consumption through modern retail penetration.
Manufacturers absorb the majority of premix volume; health professional channels are expanding most quickly through public program scale.
Form:
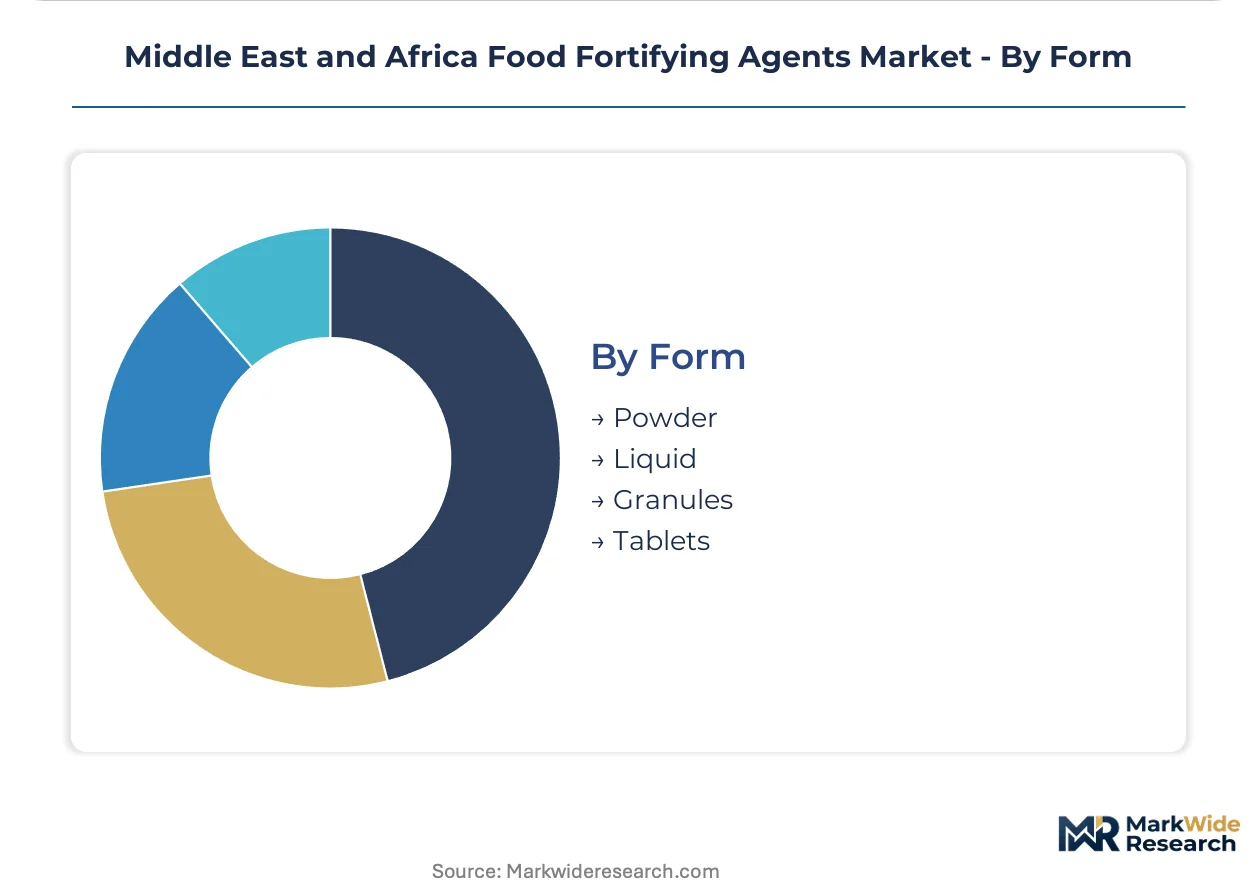
Supply concentration favors powder formats where cold chain infrastructure remains variable across the region.
- Powder:Spray-dried or agglomerated premixes optimized for bulk handling, extended shelf stability, and tropical climate storage. Sub-Saharan flour millers specify powder vitamin premixes for logistics reliability in intermittent cold chain conditions.
- Liquid:Oil-soluble vitamin suspensions and aqueous mineral solutions for beverage and dairy fortification. South African beverage bottlers utilize liquid vitamin D and E fortifiers for homogeneous distribution in ready-to-drink products.
- Granules:Intermediate particle size formats balancing flowability with dissolution characteristics. North African dairy processors specify granulated mineral premixes for dry-mix yogurt and fermented milk applications.
- Tablets:Compressed single-nutrient or multivitamin formats for direct consumption and supplement manufacturing. Gulf Cooperation Council dietary supplement producers import tablet-grade raw materials for local packaging and branding.
Powder formulations dominate procurement tonnage; liquid formats are climbing fastest through beverage fortification expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food fortifying agent production scaled initially through European colonial supply chains into North Africa, then industrialized locally as South African and Nigerian processed food sectors expanded from the 1980s onward.
South Africa
Maize meal fortification mandates from the National Regulator for Compulsory Specifications drive consistent bulk premix procurement from domestic millers. Vitamin A and D3 minimums apply equally to imported and locally milled products. The Johannesburg-Cape Town manufacturing corridor concentrates formulation demand for vitamin-mineral premix bundling across beverage and bakery applications.
Nigeria
Lagos and Kano-based infant nutrition manufacturers are accelerating vitamin premix procurement to meet FSSAI-aligned quality standards for export positioning. The national food fortification alliance coordinates wheat flour and vegetable oil mandatory enrichment programs. Northern grain processing clusters around Kano are expanding premix storage infrastructure to reduce tropical degradation losses.
Ethiopia
Addis Ababa dairy cooperatives are scaling probiotic-enriched fermented milk production for urban retail penetration. The Ethiopian Food and Drug Administration aligns fortification regulations with East African Community technical standards. Industrial parks in the capital region are attracting foreign premix suppliers through duty-free manufacturing incentives.
UAE
Dubai and Abu Dhabi serve as re-export hubs for Gulf Cooperation Council fortification inputs, leveraging Jebel Ali port logistics for Saudi and Kuwaiti markets. The Ministry of Health and Prevention enforces Gulf Standardization Organization labeling harmonization for edible oil and dairy fortifiers. Free zone manufacturing facilities in Dubai Industrial City are expanding spray-drying capacity for regional vitamin premix production.
Kenya
Nairobi-based millers are adopting modular premix bundling under East African Community convergence with Codex Alimentarius frameworks. The Kenya Bureau of Standards mandates wheat flour and maize meal fortification with iron, zinc, and B-vitamins. Rift Valley dairy processing clusters are deploying microencapsulated probiotic strains for ambient-stable yogurt distribution to secondary cities.
Middle East and Africa Food Fortifying Agents Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technical service capabilities and stability documentation depth. The supplier base concentrates among multinational chemical and ingredient conglomerates with established tropical climate formulation expertise, while regional African processors occupy mid-tier positions through government contract relationships. Three archetypes dominate: integrated nutrition conglomerates with sweetener-fortifier bundling, specialized microbial culture houses with probiotic customization capabilities, and synthetic vitamin manufacturers with pharmaceutical-grade production scale. Capacity expansion and strategic technical partnerships represent the dominant competitive vectors as buyers compress supplier qualification timelines.
Within the synthetic vitamin tier, BASF SE and Koninklijke DSM NV exemplify scale-driven positioning through pharmaceutical-grade production infrastructure serving sub-Saharan flour millers. Among specialized microbial suppliers, Chr. Hansen Holding AS occupies a position representing probiotic strain customization expertise for North African dairy applications. Tate & Lyle PLC sits within the integrated nutrition conglomerate archetype, though its sweetener-fortifier bundling relationships face displacement by dedicated premix vendors in South Africa's processed food corridor.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Koninklijke DSM NV |
| Chr. Hansen Holding AS |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Africa Improved Foods Rwanda Limited |
| BASF SE |
| Cargill, Incorporated |
| Glanbia PLC |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade certification divergence between synthetic vitamin manufacturers and commodity premix blenders manifests in parallel supply chain configurations across Middle East and Africa markets. Premium suppliers anchor pricing power through stability documentation depth while commodity tiers compete on bulk volume terms, with South African flour millers and Nigerian infant nutrition producers sorting procurement decisions across this bifurcation.
Pricing Analysis
Contract-based long-term offtake dominates procurement relationships between sub-Saharan flour millers and synthetic vitamin suppliers, with pricing stratifying across premium, standard, and economy tiers based on certification grade and technical service bundling. Price differentiation stems from Codex Alimentarius alignment depth and tropical stability testing portfolios. Cost compression in economy-tier premixes intensifies as East African Community regulatory convergence accelerates supplier qualification timelines. Small-scale dairy cooperatives in Kenya and Ethiopia exhibit highest price sensitivity, while Gulf Cooperation Council dietary supplement manufacturers prioritize certification grade over unit cost.
Supply Chain Analysis
Returns and stability-failure remediation flows concentrate among microencapsulation equipment operators serving Nigerian and Ethiopian infant nutrition corridors. Geographic supply concentration centers on Germany, Netherlands, and India for synthetic vitamin A and D3 inputs, with South Africa and UAE functioning as regional blending and distribution hubs. Raw material dependencies include retinol acetate, cholecalciferol, and lipid coating substrates. Single-source vulnerability pervades pharmaceutical-grade vitamin production. Distribution runs through Johannesburg-Cape Town manufacturing corridors for southern African markets and Jebel Ali free zones for Gulf re-export.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where East African Community alignment with Codex Alimentarius frameworks generates sustained demand acceleration for certified premix suppliers.
For Market Incumbents: Hedge synthetic vitamin concentration risk through backward integration into microencapsulation capacity or strategic partnerships with regional spray-drying operators in South Africa and UAE. BASF SE and Koninklijke DSM NV face displacement pressure from specialized premix vendors with dedicated technical service teams; incumbents should anchor relationships through stability documentation depth and tropical climate formulation expertise rather than commodity scale alone. For New Entrants and Emerging Players: Spray drying-microencapsulation convergence offers entry positioning into probiotic fortification segments previously inaccessible to live cultures. White-space targets include ambient-stable probiotic delivery for Kenyan and Ethiopian dairy cooperatives, and modular premix bundling for Nigerian infant nutrition manufacturers seeking FSSAI-aligned certification. Go-to-market execution should prioritize technical service partnerships with regional millers over direct commodity pricing competition. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized microbial culture houses possessing probiotic strain customization capabilities and established North African dairy relationships. Long-term viability through the projection horizon favors suppliers with pharmaceutical-grade production infrastructure and tropical stability portfolios. Acquisition targets should demonstrate convergence between laboratory verification capacity and national fortification schedule enforcement. Monitor East African Community implementation timeline divergence as inflection indicator for compliance-driven demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Capacity Expansion | Enables probiotic inclusion in ambient-stable matrices for Kenyan dairy distribution. |
| Backward Integration into Synthetic Vitamin Production | Reduces supply security exposure for sub-Saharan flour millers dependent on limited supplier base. |
| Long-term Supply Agreement with East African Millers | Locks in procurement relationships ahead of Codex Alimentarius compliance acceleration. |
| Joint Venture with Regional Spray-drying Operators | Combines tropical formulation expertise with local manufacturing incentives in Ethiopian industrial parks. |
| Certification Investment for FSSAI Alignment | Qualifies suppliers for Nigerian infant nutrition corridor procurement acceleration. |
Research Methodology
Direct dialogue with premix procurement managers at flour millers and infant nutrition manufacturers, regulatory affairs leads at national food safety authorities, and technical directors at dairy cooperatives grounded qualitative findings. Secondary validation drew from East African Community technical regulation filings, South Africa's National Regulator for Compulsory Specifications audit protocols, Gulf Standardization Organization harmonization documents, and customs trade data for vitamin premix imports. Bottom-up demand estimates from individual facility procurement patterns triangulated against top-down market sizing from production capacity and fortification mandate coverage rates.
Bottom-up segment modeling tracked vitamin, probiotic, mineral, and amino acid premix demand across food and beverage, dietary supplement, nutraceutical, and animal feed applications. The analytical framework incorporated product type, application tier, end-user archetype, and formulation format as core segmentation dimensions. CAGRs were derived from regression analysis against fortification mandate implementation schedules and processed food production growth trajectories. Industry-specific forecast inputs included laboratory verification capacity expansion timelines and cold chain infrastructure development patterns across secondary cities.
The model holds under sustained regulatory enforcement and stable input chemical pricing; deviation in East African Community implementation pace or synthetic vitamin supply disruptions would shift volume and value trajectories. Practitioners should monitor national fortification schedule divergence from actual laboratory verification capacity for early signals of compliance-driven demand acceleration or enforcement gaps.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Global Fortified Edible Oils Market
Vitamin Fortified
Micronutrients Market
Vitamin Fortified
Prenatal Vitamin Preparation Market
Vitamin Fortified
Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Beta Carotene Market
Vitamin Fortified
Global Fortified Yogurt Market
Vitamin Fortified
Fortified Cereal Market
Vitamin Fortified
Fortified Breakfast Spreads Market
Vitamin Fortified
Global Vitamin Tonics Market
Vitamin Fortified
Vitamin AD Drops Market
Vitamin Fortified
Feed Vitamins Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
Feed Grade Vitamin D Market
Vitamin Fortified
Fortified Food Market
Vitamin Fortified
Asia-Pacific Feed Vitamins Market
Vitamin Fortified
Sodium Ascorbate Market