
 Global Mixed Tocopherol Market | 2026-2036
Global Mixed Tocopherol Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mixed Tocopherol Market Analysis
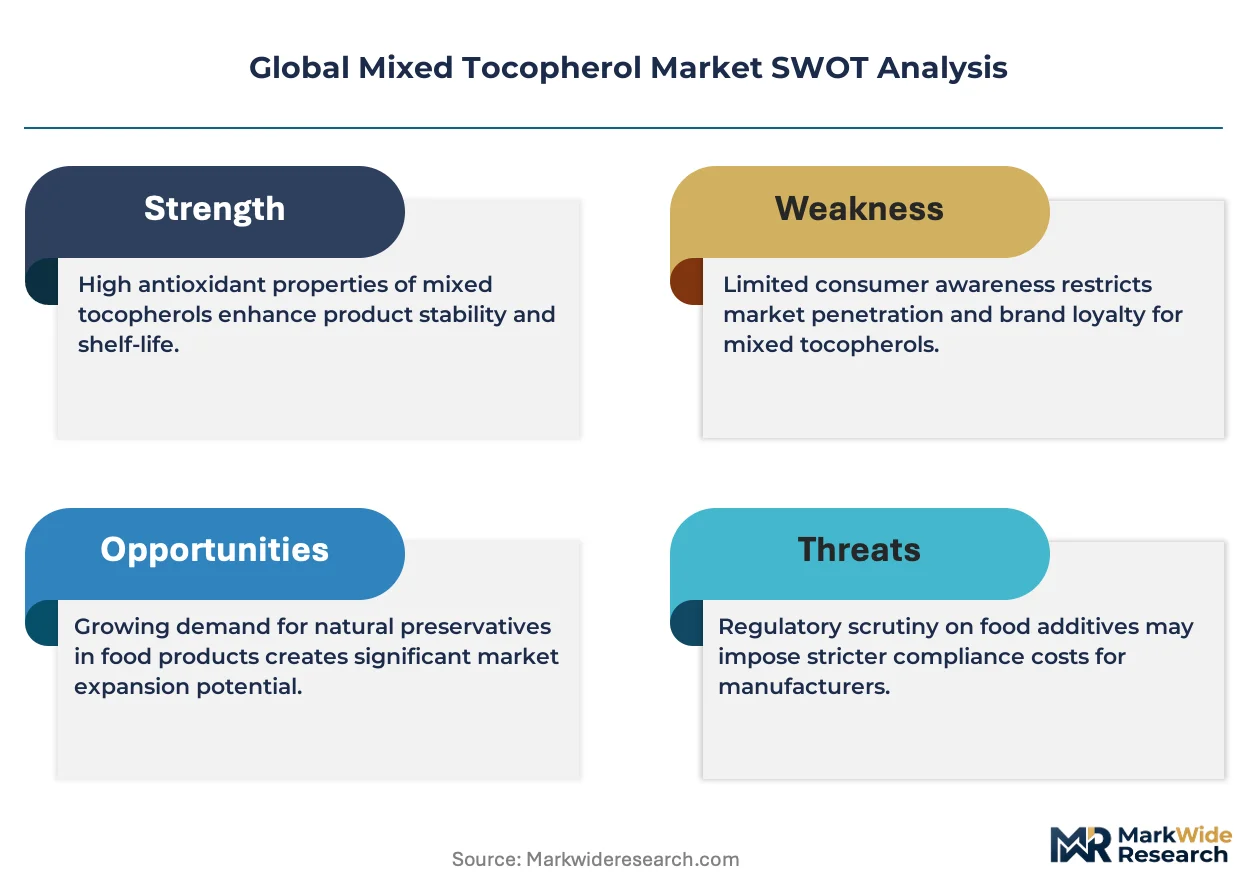
Cosmetic brands are redrawing procurement priorities for mixed tocopherols as clean-label skincare formulations gain shelf space. Davos Life Science leverages its extraction expertise to supply high-purity natural grades for premium cosmetic applications. BASF anchors European supply through backward integration into vegetable oil refining streams.
Mixed tocopherols comprise a blend of alpha, beta, gamma, and delta vitamin E homologs extracted from soybean, sunflower, or rapeseed distillates, typically standardized to 50-95% total tocopherol content with antioxidant activity measured by international units per gram. Natural product types command premium positioning in food and beverages where manufacturers replace synthetic TBHQ and BHT with label-friendly alternatives. Synthetic grades compete on cost in animal feed applications where price sensitivity limits formulation flexibility.
REACH in Europe, FDA food additive regulations in the United States, and China's GB standards collectively shape purity thresholds, labeling requirements, and import documentation for cross-border tocopherol trade. The EU Green Deal's bio-based chemicals targets are redirecting investment toward solvent-free extraction technologies. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs and supply chain disruptions.
Market Dynamics
Clean-label substitution pressure is restructuring procurement hierarchies across food, cosmetics, and nutraceutical end-uses, forcing reformulation timelines to compress from 18 months to under 9 months for major brand portfolios.
Growth Catalysts
- EU F-Gas Regulation:Cosmetic manufacturers must eliminate fluorinated propellants and synthetic stabilizers, redirecting R&D budgets toward natural antioxidant systems.
- Plant-derived feedstock expansion:Sunflower and rapeseed distillate availability is rising in Black Sea and Canadian agricultural belts, diversifying supply beyond soybean dependence.
- Nutraceutical capsule demand:Softgel and hard-shell dietary supplement volumes are absorbing premium natural tocopherol grades at contract premiums.
Market Restraints
- Vegetable oil price volatility:Distillate feedstock costs swing with palm and soybean oil futures, compressing extractor margins unpredictably.
- Chinese supply concentration:Over 60% of natural tocopherol refining capacity sits in Shandong and Jiangsu provinces, creating single-geography risk.
- Synthetic vitamin E substitution:Petrochemical-derived all-rac-alpha-tocopherol acetate undercuts natural grades by 40-50% in animal feed applications.
Strategic Opportunities
- India food additive liberalization:FSSAI is expanding natural antioxidant approved-lists, opening formulation trials for domestic snack and edible oil processors.
- Solvent-free supercritical extraction:CO2 and ethanol-water systems are eliminating hexane residues, qualifying for EU organic cosmetic certifications.
- Direct-to-brand e-procurement platforms:Specialty chemical marketplaces are collapsing traditional three-tier distribution for mid-volume cosmetic compounders.
Industry Challenges
- Analytical chemistry talent scarcity:HPLC method validation for tocopherol homolog quantification requires scarce phytochemistry specialists.
- REACH registration timelines:New cosmetic-grade entrants face 12-18 month substance evaluation periods before EU market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mixed Tocopherol Market |
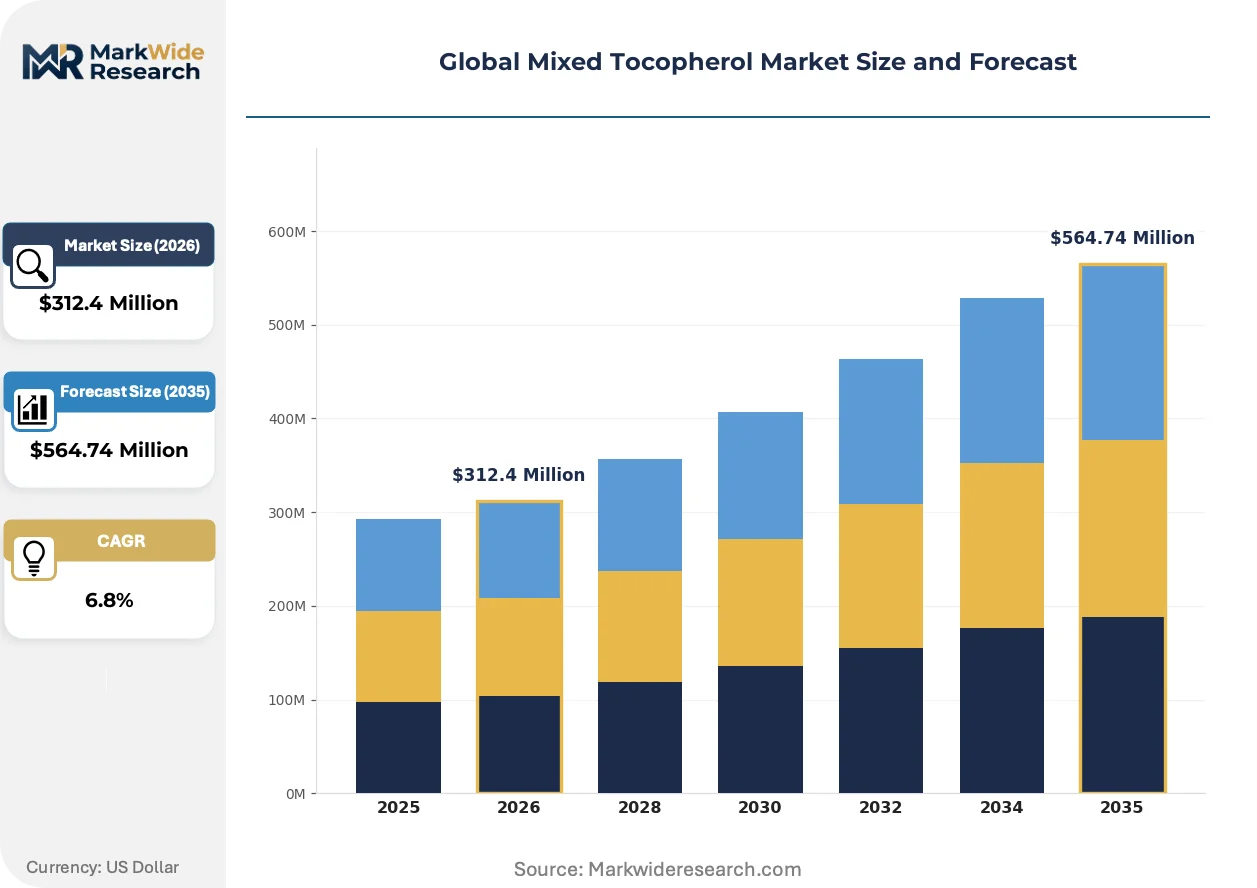
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Blends, Concentrates Application: Food & Beverages, Cosmetics, Pharmaceuticals, Animal Feed End User: Food Manufacturers, Cosmetic Brands, Nutraceutical Companies, Veterinary Clinics Packaging Type: Bottles, Drums, Totes, Pouches |
| Companies Covered | DuPont Danisco, Davos Life Science, Archer Daniels Midland Company, Vitae Naturals, Nutralliance, BASF, The Scoular Company, Cofco Tech Bioengineering, DSM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mixed Tocopherol Market Emerging Trajectories
Extraction technology maturation and regulatory purity escalation are bifurcating the supply base into commodity distillate traders and certified-grade specialists serving premium formulation houses.
Molecular distillation coupled with simulated moving bed chromatography is decomposing the traditional 50% mixed tocopherol standard into isolated alpha, gamma, and delta fractions. Nutraceutical contract manufacturers are specifying 90%+ alpha-tocopherol for USP-grade supplements. This fractionation capability is compressing spot markets for unstandardized distillates.
REACH Annex XVII restrictions on residual solvents are tightening maximum allowable hexane limits in cosmetic-grade tocopherols to 5 ppm. ECHA enforcement inspections are disqualifying non-compliant Indian and Chinese suppliers from EU cosmetic ingredient approvals. German and French formulators are accelerating supplier audits to pre-empt registration suspensions.
Long-term offtake contracting is displacing spot purchasing for natural vitamin E. North American dietary supplement brands are locking 24-36 month supply agreements directly with vegetable oil refiners. This channel consolidation is squeezing independent distributors in the US Midwest and Atlantic Canada.
Global Mixed Tocopherol Market Segmentation
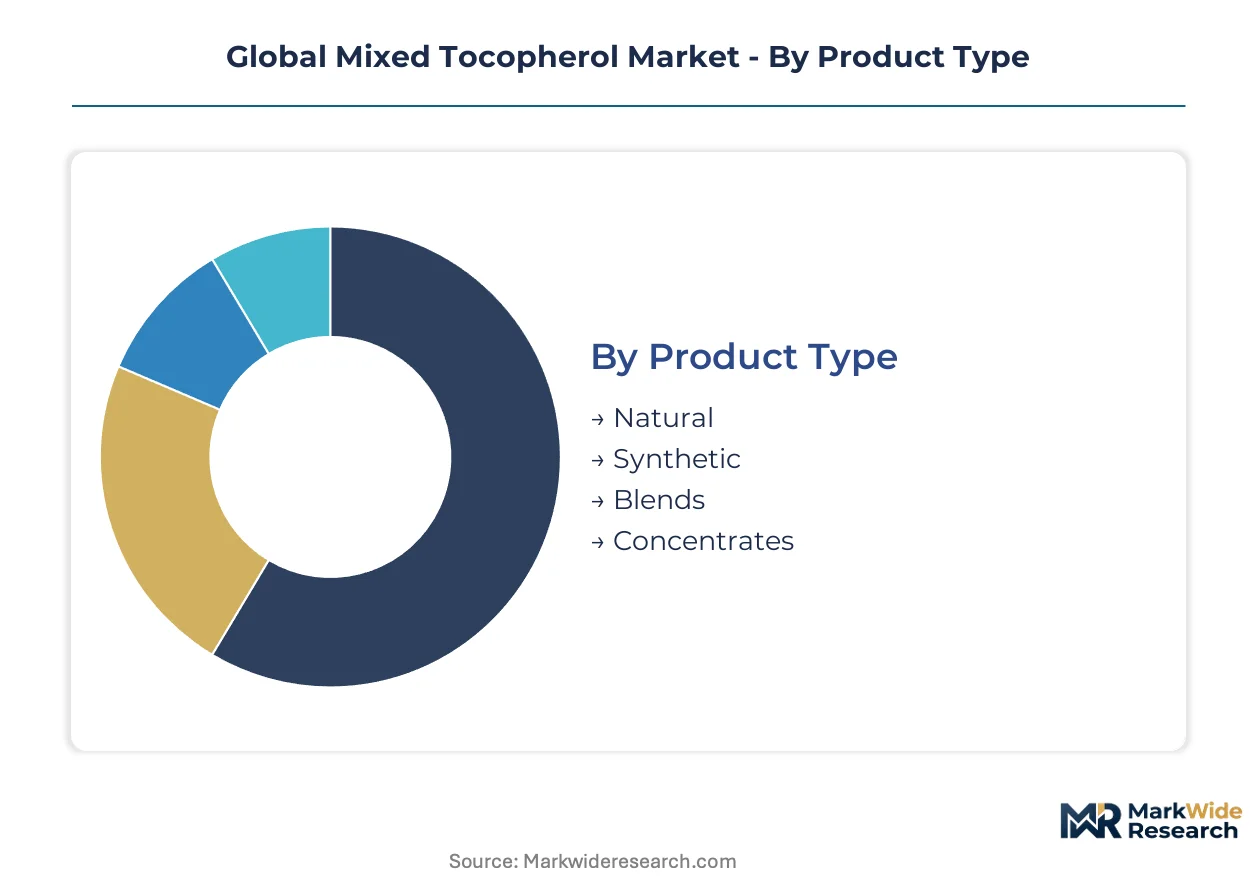
Mixed tocopherol procurement patterns diverge sharply across product grades and end-use specifications. Segment boundaries determine pricing power, regulatory compliance burdens, and supplier qualification timelines for buyers worldwide.
Product Type:
Natural grades dominate export flows to EU and North American premium markets, while synthetic and blended formulations serve cost-sensitive domestic processors in Asia and Latin America.
- Natural:Extracted from soybean, sunflower, or rapeseed distillates with alpha, beta, gamma, and delta homologs in varying ratios. Demand concentrates in German and French cosmetic formulators seeking REACH-compliant, solvent-free certifications for clean-label skincare launches.
- Synthetic:Petrochemical-derived all-rac-alpha-tocopherol acetate produced via trimethylhydroquinone alkylation. Chinese and Indian animal feed compounders absorb volumes where cost minimization overrides natural positioning requirements.
- Blends:Hybrid formulations combining natural tocopherols with synthetic carriers or stabilizers. Mexican and Brazilian food processors utilize these for partial clean-label transitions without full natural grade premiums.
- Concentrates:High-potency standardized extracts typically exceeding 90% total tocopherol content. USP-grade specifications drive uptake in North American dietary supplement softgel manufacturing.
Natural holds the largest share; momentum sits with concentrates.
Application:
Application selection determines homolog specificity, with alpha-dominant grades commanding pharmaceutical premiums and gamma-rich blends penetrating food antioxidant substitution.
- Food & Beverages:Gamma-tocopherol-rich blends replace TBHQ and BHT in edible oils, snacks, and cereals. Chinese domestic manufacturers lead substitution volume as GB standards tighten synthetic additive approvals.
- Cosmetics:High-purity alpha-tocopherol and mixed homolog formulations serve antioxidant and skin-conditioning functions. EU F-Gas Regulation compliance is redirecting R&D budgets toward natural stabilizer systems in German and French premium brands.
- Pharmaceuticals:USP-grade alpha-tocopherol for parenteral and oral dosage forms. Indian CDSCO and US FDA dual-filing requirements extend qualification timelines for new suppliers.
- Animal Feed:Cost-optimized synthetic and natural-synthetic blends for poultry and swine nutrition. Brazilian and Indonesian integrated protein producers specify feed-grade tocopherols for export meat certification programs.
Food & Beverages anchors volume absorption; Cosmetics climbs the fastest on clean-label reformulation.
End User:
End user procurement sophistication ranges from specification-heavy pharmaceutical buyers to price-tolerant feed operations, fragmenting supplier engagement models.
- Food Manufacturers:Multinational processors in US, Germany, and Japan drive natural grade contracting with 24-36 month offtake agreements. Clean-label substitution timelines compress from 18 months to under 9 months for major brand portfolios.
- Cosmetic Brands:Premium formulators in France, South Korea, and California specify sub-5 ppm hexane residues and organic certifications. REACH registration documentation requirements filter supplier bases aggressively.
- Nutraceutical Companies:Softgel and hard-shell capsule manufacturers absorb isolated alpha-tocopherol fractions at contract premiums. Direct sourcing from vegetable oil refiners displaces distributor intermediaries in North America.
- Veterinary Clinics:Small-volume therapeutic applications for companion animal supplements. Dispersed demand across regional veterinary chains limits supplier economies of scale.
Food Manufacturers command procurement volume; Nutraceutical Companies deliver margin expansion.
Packaging Type:
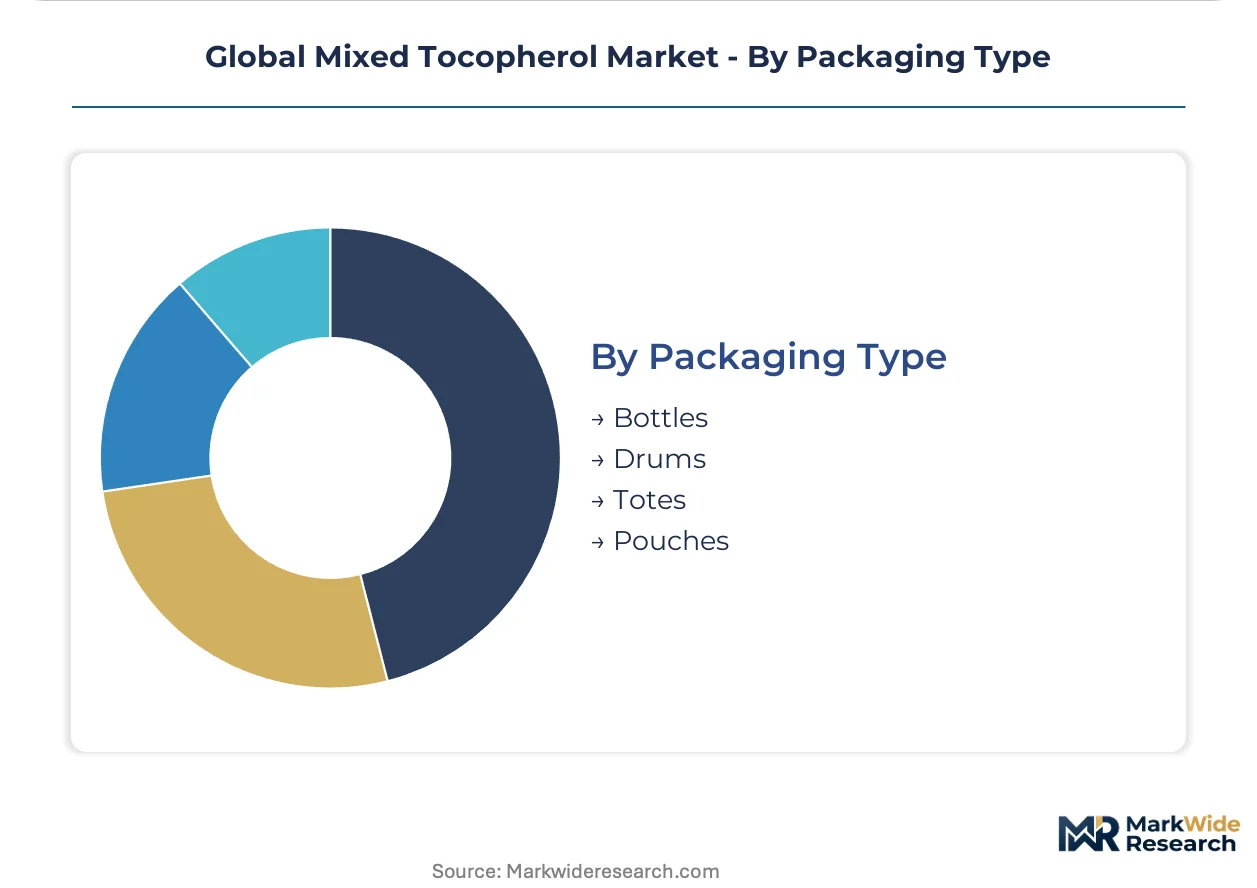
Packaging selection tracks shipment scale and oxidation sensitivity, with bulk formats dominating intercontinental trade and unit-dose formats serving niche pharmaceutical applications.
- Bottles:Amber glass and fluoropolymer-lined containers for pharmaceutical and high-value cosmetic grades. Swiss and Japanese API manufacturers specify nitrogen-flushed packaging for oxidative stability.
- Drums:Standard 200-liter steel and composite drums for mid-volume food and feed additive shipments. Black Sea and Canadian sunflower distillate suppliers utilize drum formats for European processor deliveries.
- Totes:Intermediate bulk containers for large-scale cosmetic compounder and food manufacturer intake. German and Dutch toll manufacturers prefer totes for just-in-time antioxidant blending operations.
- Pouches:Aluminum-laminated flexible packaging for sample quantities and clinical trial materials. Indian and Chinese exporters deploy pouches for initial customer qualification shipments before drum-scale contracting.
Drums capture the highest shipment frequency; totes gain share on integrated compounder consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Over 60% of natural tocopherol refining capacity concentrates in Shandong and Jiangsu provinces of China, creating single-geography risk that buyers in Germany, France, and the United States must hedge through dual-sourcing strategies. This concentration pattern shapes procurement security calculations across premium cosmetic and nutraceutical supply chains.
China
Domestic food manufacturers in Shandong and Jiangsu are substituting synthetic antioxidants with plant-derived alternatives at accelerating rates. GB standards tightening synthetic additive approvals drive reformulation mandates. Zhejiang and Guangdong cosmetic compounders absorb high-purity natural grades for export-oriented skincare production.
Germany
REACH Annex XVII enforcement disqualifies non-compliant Asian suppliers from cosmetic ingredient approvals. ECHA inspections accelerate supplier audits by Frankfurt and Hamburg formulators. Bavarian toll manufacturers prefer tote-based just-in-time antioxidant blending for integrated compounder operations.
United States
FDA food additive regulations shape purity thresholds for dietary supplement softgel manufacturing. North American brands lock 24-36 month offtake agreements directly with vegetable oil refiners. Midwest and Atlantic Canada distributors face margin compression from channel consolidation.
India
FSSAI expansion of natural antioxidant approved-lists opens formulation trials for domestic snack and edible oil processors. CDSCO dual-filing requirements with US FDA extend qualification timelines for new pharmaceutical-grade suppliers. Maharashtra and Gujarat food manufacturers pilot clean-label transitions.
France
EU F-Gas Regulation redirects R&D budgets toward natural stabilizer systems in premium cosmetic brands. ANSM oversight reinforces solvent-residue testing for hexane limits below 5 ppm. Paris and Lyon formulators specify sub-5 ppm hexane residues and organic certifications for clean-label skincare launches.
Global Mixed Tocopherol Market Vendor Landscape
Concentration sits with integrated vegetable oil refiners and specialty extraction houses that control distillate feedstock access. The supply base bifurcates into commodity distillate traders and certified-grade specialists serving premium formulation houses. Three archetypes dominate: backward-integrated agribusiness conglomerates, solvent-free extraction technology specialists, and pharmaceutical-grade fractionation houses. Competitive moves center on long-term offtake contracting and REACH registration pre-qualification to lock buyer relationships ahead of regulatory deadlines.
Among the integrated extraction specialists, Davos Life Science exemplifies high-purity natural grade supply for premium cosmetic applications, while BASF anchors European supply through captive vegetable oil refining streams. Archer Daniels Midland Company occupies a position within the agribusiness-integrated tier, leveraging upstream control over soybean and sunflower distillate sourcing.
| Leading Market Players |
|---|
| DuPont Danisco |
| Davos Life Science |
| Archer Daniels Midland Company |
| Vitae Naturals |
| Nutralliance |
| BASF |
| The Scoular Company |
| Cofco Tech Bioengineering |
| DSM |
| Others |
Supply Flow & Price Mechanics
REACH Annex XVII compliance gates both supplier qualification and price differentiation in European cosmetic-grade tocopherol procurement. ECHA enforcement of residual solvent limits below 5 ppm hexane simultaneously filters non-compliant Asian suppliers and creates certification premiums for qualified specialists serving German and French formulators.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across the European cosmetic-grade segment. Pricing stratifies across premium, standard, and economy tiers based on certification level and volume scale. Cost compression in feed-grade natural tocopherols is intensifying because synthetic all-rac-alpha-tocopherol acetate undercuts by 40-50%. Animal feed compounders exhibit highest price sensitivity; nutraceutical softgel manufacturers show least.
Supply Chain Analysis
Strait of Malacca transit underwrites distillate feedstock flows from Black Sea sunflower belts to Shandong refining clusters. Supply concentrates in China, Germany, and India for downstream processing. Raw material dependencies center on soybean oil distillates, sunflower distillates, and rapeseed processing streams. Single-source vulnerability runs through Shandong and Jiangsu provinces where over 60% of natural refining capacity sits. Distribution runs through long-term offtake contracting displacing spot purchasing for premium grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Mixed Tocopherol Market sits in a cyclical recovery phase as vegetable oil price volatility moderates and clean-label reformulation demand reaccelerates through food and cosmetic end-uses.
For Market Incumbents: Consolidate backward integration into vegetable oil refining streams to secure distillate feedstock access against margin compression from price volatility. Lock 24-36 month offtake agreements with North American dietary supplement brands before REACH registration deadlines filter supplier bases. Prioritize solvent-free extraction certification investment to defend positioning against ECHA enforcement acceleration. For New Entrants and Emerging Players: Differentiate on solvent-free supercritical CO2 extraction technology to qualify for EU organic cosmetic certifications where incumbent capacity lacks rapid retooling capability. Target Indian food additive liberalization under FSSAI expansion as the most penetrable geography. Pursue direct-to-brand e-procurement platform partnerships to bypass entrenched three-tier distribution structures. For Investors and Strategic Acquirers: Carve-out targets emerge from agribusiness conglomerates with captive vegetable oil refining assets but underutilized tocopherol extraction capacity. Long-term viability favors specialists with fractionation capability for USP-grade alpha-tocopherol isolation. Watch for REACH registration suspension signals as inflection indicators for supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Distillate Sourcing | Captive vegetable oil refining streams anchor margin defense against feedstock volatility in Shandong clusters. |
| Solvent-Free Extraction Certification | CO2 and ethanol-water systems qualify for EU organic cosmetic certifications under ECHA enforcement acceleration. |
| Long-Term Supply Agreement Lock-In | Direct contracting with North American nutraceutical brands displaces Midwest distributor intermediaries. |
| Fractionation Capacity Expansion | Simulated moving bed chromatography enables USP-grade alpha-tocopherol supply for premium supplement manufacturing. |
| Dual-Sourcing Geographic Diversification | Black Sea and Canadian sunflower distillate procurement hedges single-geography risk in Jiangsu province. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC filings from listed agribusiness conglomerates, ECHA registration databases, and FSSAI approved-additive notifications. Extraction plant managers, procurement leads at German cosmetic compounders, North American nutraceutical contract manufacturers, and Indian edible oil processors provided operational validation. Bottom-up volume modeling from distillate throughput rates triangulates against top-down market sizing from trade flow analysis.
Segmentation dimensions modeled span product grade tier, end-use industry application, packaging format, and regional production hub concentration across the analysis window. CAGRs derive from regression against vegetable oil price indices, clean-label substitution elasticities, and regulatory compliance cost trajectories. Forecast inputs incorporate REACH registration timeline assumptions and FSSAI liberalization implementation pacing.
The analysis sits within stated boundaries; outcomes outside sustained vegetable oil price stability and ECHA enforcement continuity would require recalibration. Forecasts reflect documented assumptions around regulatory divergence trajectories and feedstock supply expansion rates. Practitioners should keep alternative scenarios live as Chinese domestic demand absorption and EU Green Deal bio-based targets evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Middle East and Africa Vitamin a Market
Vitamin Fortified
Natural Beta Carotene Market
Vitamin Fortified
Riboflavin Market
Vitamin Fortified
Fortified Breakfast Spreads Market
Vitamin Fortified
Vitamin Yeast Market
Vitamin Fortified
Fortified Milk and Milk Products Market
Vitamin Fortified
Synthetic Vitamin E Market
Vitamin Fortified
Esterified Vitamins Market
Vitamin Fortified
Asia-Pacific Food Fortifying Agent Market
Vitamin Fortified
Prenatal Vitamin Preparation Market
Vitamin Fortified
Vitamin D3 Oil Market
Vitamin Fortified
North America Vitamin D Market
Vitamin Fortified
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Pantothenic Acid Market
Vitamin Fortified
Ready-To-Use Therapeutic Food and Supplementary Food (RUTF and RUSF) Market