
 Middle East Feed Vitamins Market | 2026-2036
Middle East Feed Vitamins Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Feed Vitamins Market Foresight
A capital-intensity divergence between integrated multinationals and regional distributors is reorganizing competitive tiers in the Middle East feed vitamins space. BASF SE leverages its Ludwigshafen manufacturing base and Gulf distribution partnerships to supply vitamin A and E premixes to Saudi poultry conglomerates. Kemin Industries differentiates through specialized antioxidant delivery systems tailored for ruminant stress conditions in hot climates. Adisseo anchors its position via liquid methionine and vitamin blending capabilities serving UAE-based aquaculture feed producers.
Middle East feed vitamins comprise water-soluble and fat-soluble organic compounds formulated into premixes to prevent deficiency disorders and optimize metabolic performance in livestock. Vitamin E functions primarily as a lipid-phase antioxidant protecting cell membranes from peroxidation in heat-stressed animals, while vitamin A supports epithelial integrity and reproductive function across poultry and ruminant species. The vitamin E segment leads value contribution due to premium pricing for natural-source tocopherols in dairy and breeder operations. Poultry dominates animal-type demand as Saudi Arabia and Egypt expand broiler capacity under food security programs. Liquid formulations are gaining share in automated feed mills seeking homogeneous mixing precision and reduced dust exposure.
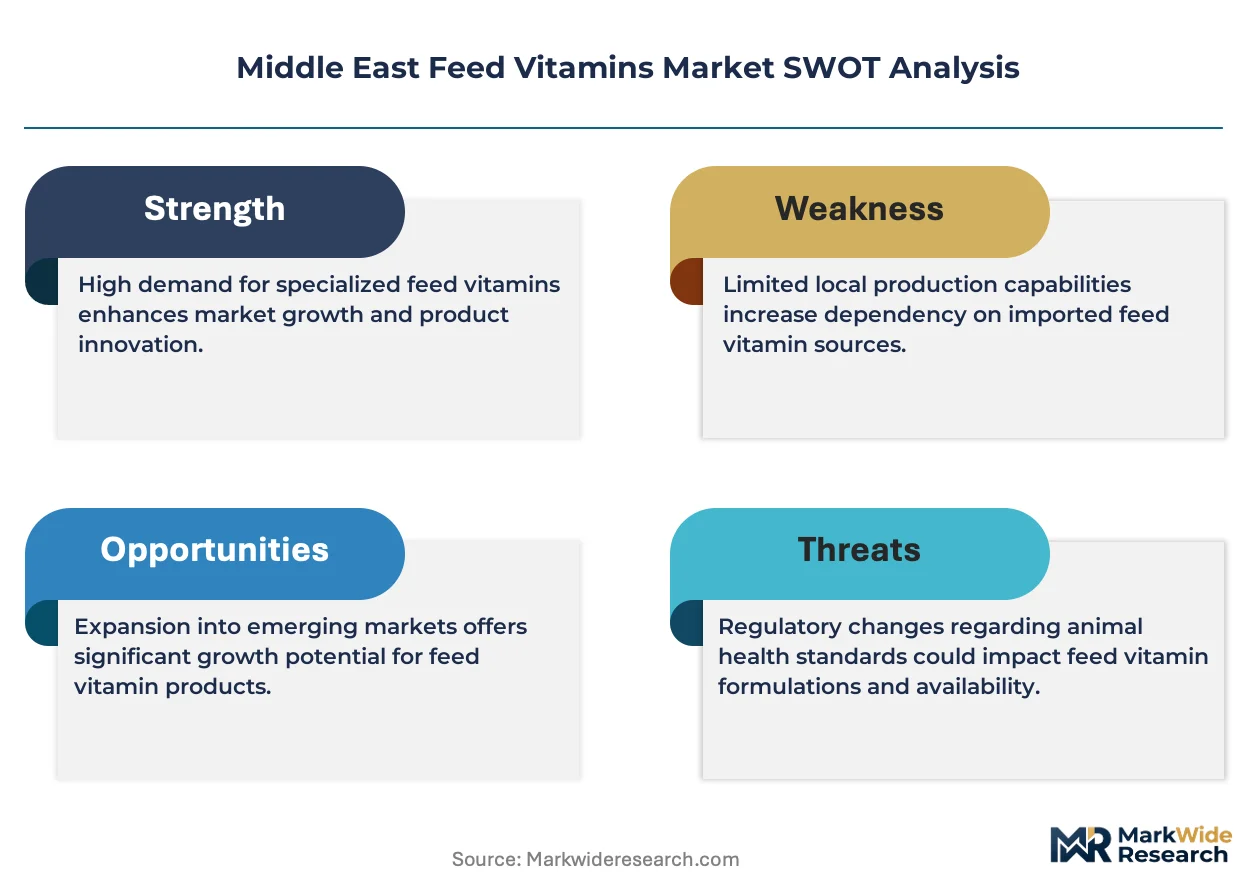
Saudi Food and Drug Authority (SFDA) and UAE Ministry of Climate Change and Environment (MOCCAE) enforce maximum vitamin inclusion limits and premix registration requirements that shape product formulation standards across Gulf markets. Egypt's agricultural quarantine regulations and import licensing through the General Organization for Veterinary Services control cross-border vitamin premix flows from European suppliers. Stakeholders must monitor evolving Gulf harmonization of feed additive standards and the shift toward localized premix manufacturing as import substitution policies intensify.
Market Dynamics
Import substitution mandates under Saudi Vision 2030 and UAE food security frameworks are restructuring supply chains, forcing premix manufacturers to localize blending capacity or surrender market access to domestic producers.
Growth Catalysts
- SFDA premix registration mandates:Saudi Food and Drug Authority requirements for localized vitamin premix documentation accelerate domestic production investment by foreign suppliers seeking market continuity.
- Heat-stress antioxidant demand:Natural-source vitamin E tocopherols gain preference in UAE and Saudi dairy operations managing thermal load in open-housed ruminant systems.
- Qassim feed milling cluster:Concentrated infrastructure in Saudi Arabia's central region reduces logistics friction for vitamin distributors serving integrated poultry and dairy operations.
Market Restraints
- Feed-grade vitamin import dependency:Gulf markets rely on European and Asian bulk vitamin manufacturers, exposing premixers to currency volatility and shipping disruptions through the Strait of Hormuz.
- Limited domestic chemical synthesis:No regional production of vitamin A acetate or D3 crystals forces complete reliance on imported intermediates for local premix formulation.
- MOCCAE maximum inclusion ceilings:UAE Ministry of Climate Change and Environment caps on fat-soluble vitamin concentrations restrict premium formulation differentiation in breeder feeds.
Strategic Opportunities
- Egyptian aquaculture expansion:General Organization for Veterinary Services import licensing reforms may open Nile Delta shrimp and tilapia feed production to specialized vitamin premix suppliers.
- Liquid vitamin delivery systems:Automated feed mills in Saudi Arabia's Riyadh and Jeddah corridors seek homogeneous mixing precision through oil-suspension vitamin technologies.
- Biofortification alignment:Gulf national nutrition strategies linking livestock product quality to human vitamin intake create demand for enhanced vitamin D and B12 retention in dairy.
Industry Challenges
- Premix formulation chemist scarcity:Gulf universities produce limited feed science graduates, forcing manufacturers to recruit European or South Asian technical staff at premium compensation.
- SFDA-MOCCAE regulatory divergence:Non-harmonized vitamin stability testing protocols between Saudi Arabia and UAE force dual certification costs for cross-border premix suppliers.
- Legacy batch mixing infrastructure:Older feed mills in Egypt's Delta region lack precision dosing equipment, limiting uptake of micro-encapsulated vitamin technologies requiring exact inclusion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Feed Vitamins Market |
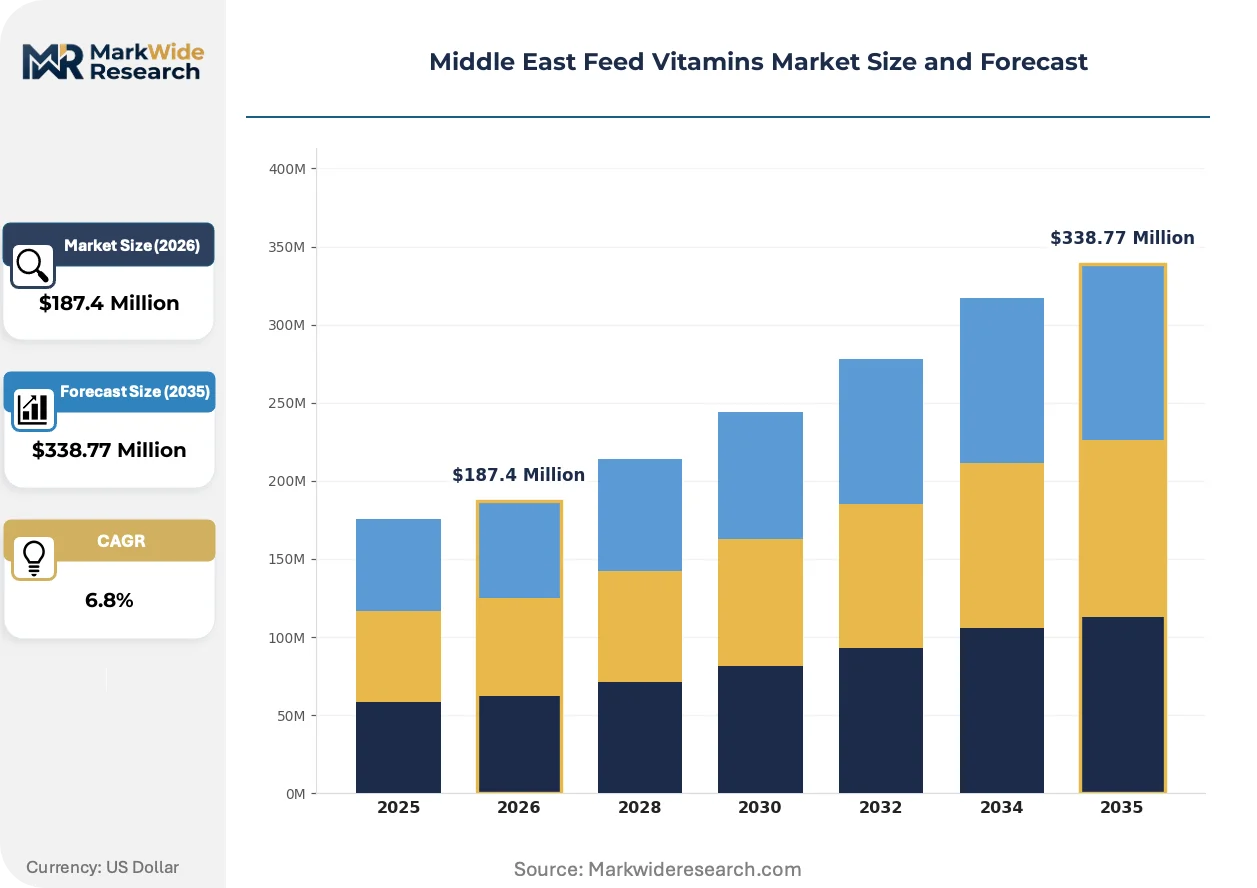
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin A, Vitamin D, Vitamin E, Vitamin K Animal Type: Poultry, Ruminants, Swine, Aquaculture Form: Liquid, Powder, Granular, Tablet Distribution Channel: Online, Wholesale, Retail, Direct Sales |
| Companies Covered | BASF SE, ADM Animal Nutrition, Kemin Industries, Evonik Industries, DSM-Firmenich, Adisseo, Biomin, Alltech, Cargill, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Feed Vitamins Market Shifts & Advancements
Micro-encapsulation and precision dosing technologies are reconfiguring how vitamins survive feed processing, while regulatory pressure on antibiotic growth promoters elevates nutritional intervention as the primary performance optimization lever.
Micro-encapsulated vitamin C and choline products are bifurcating the premix market between commodity dry powders and protected forms capable of surviving pelleting temperatures above 85°C. Saudi poultry integrators in the Riyadh corridor are adopting these technologies at accelerated procurement cycles to maintain growth performance under heat stress without antibiotic support. This technological split is compressing margins for undifferentiated bulk vitamin distributors while rewarding formulation houses with in-house encapsulation capabilities.
SFDA's 2023 updated feed additive registration framework now requires stability data under Gulf climate conditions, extending approval timelines for European premix suppliers accustomed to temperate-zone testing protocols. The industrial consequence is a bottleneck in new product introductions, with some manufacturers withdrawing marginal SKUs rather than funding redundant stability studies. Poultry breeder operations, most sensitive to vitamin degradation in extended storage, are responding by consolidating supplier relationships with entities maintaining dedicated Gulf warehousing.
Integrated livestock operators are consolidating vitamin procurement under direct premix manufacturing partnerships, bypassing traditional distributor intermediaries. The channel disruption concentrates volume with multinational premix houses capable of technical service deployment to farm-level nutritionists. This pattern is most visible in Saudi Arabia's central Qassim region, where Almarai and other vertically coordinated dairy-poultry groups negotiate multi-year vitamin supply agreements with embedded formulation support.
Middle East Feed Vitamins Market Segmentation
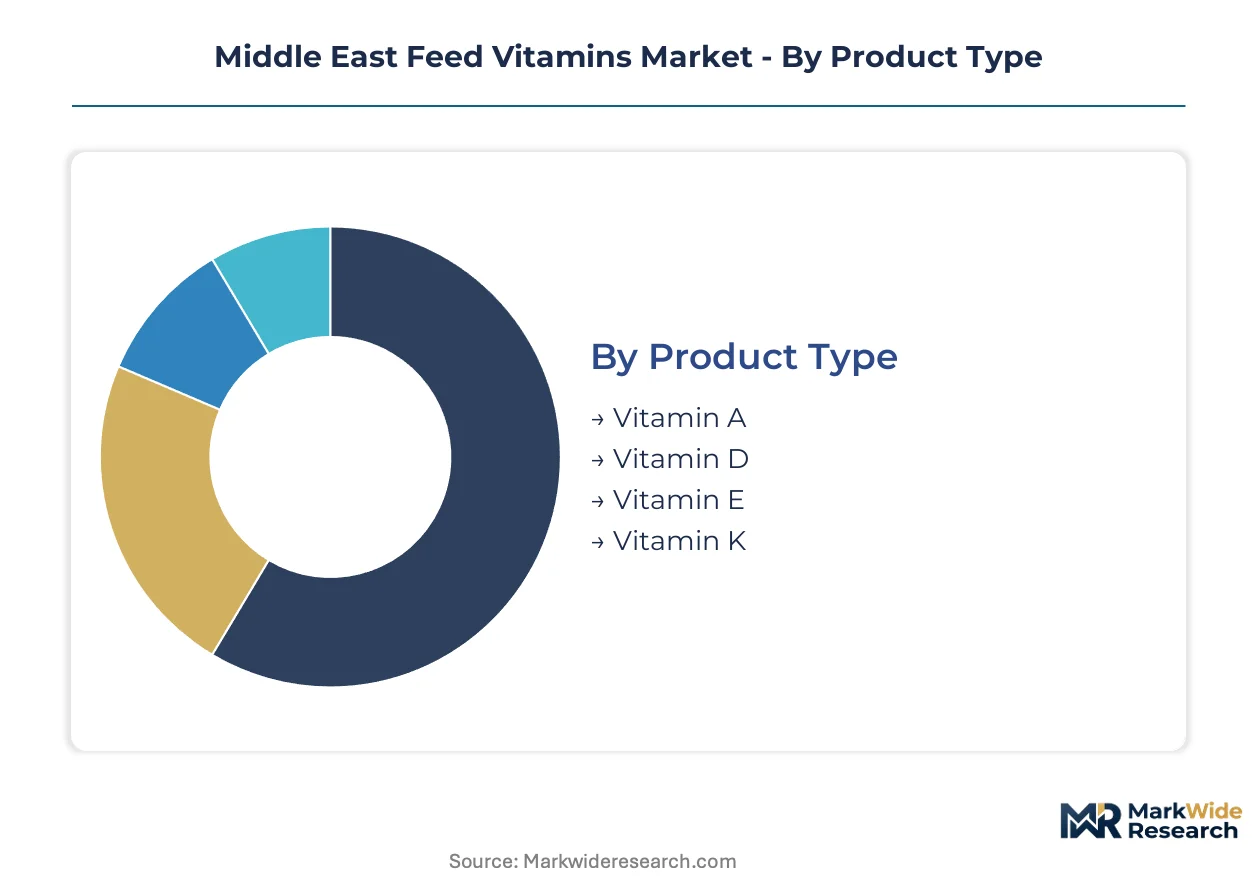
Feed vitamin segmentation in the Middle East reflects divergent regulatory tolerances across Gulf markets and the operational requirements of heat-stressed livestock systems. Product form and distribution channel choices are increasingly shaped by SFDA stability mandates and the automation levels of Saudi feed milling clusters.
Product Type:
SFDA and MOCCAE impose distinct maximum inclusion limits on fat-soluble vitamins, forcing formulation adjustments that vary by compound class across Saudi and UAE markets.
- Vitamin E:Natural-source tocopherols function as lipid-phase antioxidants protecting cell membranes from peroxidation in heat-stressed ruminants. Saudi dairy operations in the Qassim region specify natural-form vitamin E for breeder herds despite premium pricing, driven by SFDA registration preferences for stability-documented natural forms.
- Vitamin A:Retinyl acetate and palmitate esters support epithelial integrity and reproductive performance across poultry and ruminant species. UAE poultry integrators concentrate demand for vitamin A premixes in the Riyadh corridor, constrained by MOCCAE ceiling limits that restrict high-potency breeder formulations.
- Vitamin D:Cholecalciferol (D3) regulates calcium metabolism and bone mineralization in high-production laying hens. Egyptian aquaculture feed producers source vitamin D for Nile Delta tilapia operations under General Organization for Veterinary Services import licensing.
- Vitamin K:Menadione derivatives support coagulation function in rapidly growing broilers. Saudi broiler operations incorporate vitamin K at standard inclusion rates with limited formulation differentiation.
Vitamin E handles the majority of throughput; Vitamin D is expanding most quickly on share as aquaculture feed producers fortify bone development in high-density farming systems.
Animal Type:
Cost tier differentiation separates commodity livestock operations from premium breeder and export-oriented protein production.
- Poultry:Broiler and layer operations dominate volume consumption, with Saudi Arabia's central Qassim region hosting the densest concentration of integrated poultry groups. SFDA premix registration mandates accelerate procurement centralization under direct manufacturer partnerships.
- Ruminants:Dairy cattle and sheep operations in open-housed desert systems drive antioxidant vitamin demand. UAE dairy producers specify heat-stress formulations with elevated vitamin E inclusion for Holstein herds in Al Ain and Dubai emirates.
- Aquaculture:Shrimp and tilapia feed production in Egypt's Nile Delta requires water-soluble vitamin premixes adapted to extruded feed processing. General Organization for Veterinary Services licensing reforms may streamline import pathways for specialized suppliers.
- Swine:Limited regional pork production restricts segment scale to Lebanon and non-Gulf markets with minimal regulatory alignment to SFDA frameworks.
Poultry handles the majority of throughput; Aquaculture is climbing the fastest as Egyptian production capacity expands under food security programs.
Form:
Customer type segmentation separates automated feed mills from legacy batch operations with incompatible precision dosing infrastructure.
- Liquid:Oil-suspension and water-miscible vitamin concentrates enable homogeneous distribution in automated feed mills. Saudi operations in Riyadh and Jeddah corridors specify liquid vitamin systems for continuous mixing lines with reduced dust exposure.
- Powder:Dry premixes remain standard for smaller feed mills and on-farm mixing operations. Egyptian Delta region mills rely on powder formulations due to limited precision dosing equipment.
- Granular:Free-flowing granules improve handling characteristics in high-temperature storage conditions. UAE distributors stock granular forms for warehousing stability under Gulf climate exposure.
- Tablet:Compressed vitamin supplements serve niche ruminant bolus applications and on-farm top-dressing protocols. Saudi sheep operations in Asir region use tablet supplements for targeted deficiency correction.
Powder handles the majority of throughput; Liquid is gaining share fastest as Saudi feed mill automation accelerates.
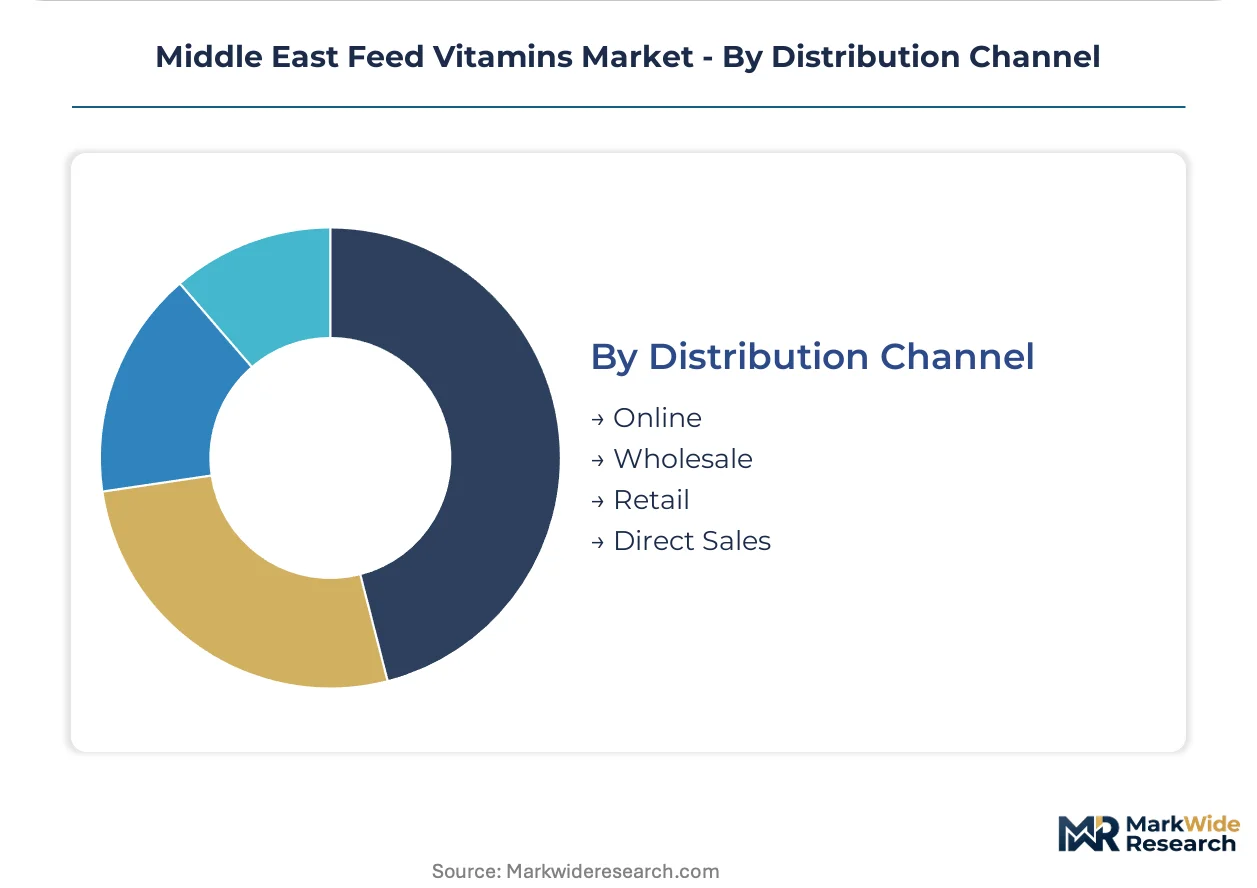
Distribution Channel:
Supply concentration in Saudi Arabia's Qassim region and Egypt's Nile Delta shapes channel efficiency and margin capture.
- Direct Sales:Multinational premix manufacturers negotiate multi-year supply agreements with integrated livestock operators. Almarai and vertically coordinated Saudi groups consolidate procurement under embedded technical service contracts.
- Wholesale:Regional distributors stock standard vitamin premixes for independent feed mills and smaller poultry operations. Wholesale channels dominate Egyptian market access under General Organization for Veterinary Services import licensing structures.
- Online:Digital procurement platforms serve specialty vitamin products and smaller volume orders. UAE-based aquaculture feed producers utilize online channels for rapid reordering of standardized premix SKUs.
- Retail:Farm supply stores and veterinary distributors handle top-dressing supplements and small-scale premix sales. Retail penetration remains limited to peripheral livestock regions with fragmented farm structures.
Direct Sales handles the majority of throughput; Online is expanding most quickly as procurement digitization penetrates secondary feed production centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia concentrates fat-soluble vitamin demand for heat-stressed dairy herds, while Egypt drives water-soluble formulations for aquaculture expansion. The UAE prioritizes antioxidant premixes for open-housed ruminant systems. Each geography deploys distinct regulatory frameworks and procurement models.
Saudi Arabia
Central Qassim region hosts dense clusters of integrated poultry and dairy operations demanding stability-documented vitamin E for breeder herds. SFDA premix registration mandates force foreign suppliers to localize blending capacity or surrender market access. Riyadh and Jeddah corridors accelerate liquid vitamin adoption in automated feed mills.
United Arab Emirates
MOCCAE maximum inclusion ceilings constrain high-potency breeder formulations while driving demand for natural-source tocopherols in Al Ain and Dubai emirate dairy operations. Heat-stress management protocols specify elevated antioxidant inclusion for Holstein herds in open-housed desert systems. Dubai-based distributors stock granular forms for warehousing stability under Gulf climate exposure.
Egypt
Nile Delta shrimp and tilapia feed producers source water-soluble vitamin premixes under General Organization for Veterinary Services import licensing structures. Aquaculture expansion under food security programs drives fastest-segment growth for vitamin D fortification in high-density farming systems. Legacy batch mixing infrastructure in Delta region mills limits uptake of precision-dosed micro-encapsulated technologies.
Kuwait
Poultry integrators scale vitamin premix programs to improve broiler feed conversion efficiency under national food security frameworks. Import dependency on European and Asian bulk vitamin manufacturers exposes premixers to currency volatility and shipping disruptions through regional chokepoints. Wholesale distribution channels dominate market access for independent feed mills.
Qatar
Livestock self-sufficiency targets accelerate procurement centralization under direct manufacturer partnerships with embedded technical service contracts. Limited domestic chemical synthesis forces complete reliance on imported intermediates for local premix formulation. Doha-based operations consolidate volume with multinational premix houses capable of farm-level nutritionist deployment.
Middle East Feed Vitamins Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Middle East feed vitamins space. German and Swiss chemical conglomerates anchor the upper tier through captive manufacturing bases and Gulf distribution partnerships. Mid-scale regional premix houses occupy the specialist tier with climate-adapted formulation capabilities. Competitive dynamics center on backward integration into blending capacity and multi-year supply agreements with embedded technical service.
Within the integrated chemical tier, BASF SE and DSM-Firmenich represent archetypes of manufacturing-origin market presence. Kemin Industries occupies a position exemplifying specialized antioxidant delivery systems. Adisseo anchors the liquid methionine and vitamin blending segment serving aquaculture feed producers. These entities sit within competitive positions shaped by import substitution mandates and SFDA registration requirements rather than pure manufacturing scale.
| Leading Market Players |
|---|
| BASF SE |
| ADM Animal Nutrition |
| Kemin Industries |
| Evonik Industries |
| DSM-Firmenich |
| Adisseo |
| Biomin |
| Alltech |
| Cargill |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day premix inventory cycles in Saudi Arabia's Qassim region concentrate pricing power with European bulk vitamin manufacturers who control acetate and tocopherol intermediate supply. This lead-time exposure forces regional blenders to absorb currency volatility or surrender margin through fixed-price contract structures with integrated poultry conglomerates.
Pricing Analysis
Long-term offtake agreements dominate procurement between multinational premix houses and Saudi integrated livestock operators, compressing spot market liquidity for independent Egyptian feed mills. Premium-mid-economy pricing differentiation separates stability-documented natural-source vitamin E from commodity synthetic tocopherols, with SFDA registration preferences widening the spread. Cost compression in standard-grade vitamin A premixes is intensifying as Chinese acetate exports expand Gulf market penetration. Independent poultry operations in Egypt's Delta region exhibit highest price sensitivity, while Saudi dairy breeder herds demonstrate lowest sensitivity due to performance-linked procurement criteria.
Supply Chain Analysis
Strategic stockpile preferences prevail among UAE distributors maintaining granular vitamin forms for Gulf climate warehousing stability, while Saudi automated mills pursue just-in-time liquid concentrate delivery. Bulk vitamin production concentrates in China, Germany, and Switzerland, with regional premix blending anchored in Saudi Arabia and the UAE. Local formulation draws from imported vitamin A acetate, D3 crystals, and natural-source tocopherol intermediates. Single-source vulnerability runs through the Strait of Hormuz shipping corridor. Distribution runs through direct manufacturer partnerships with embedded technical service contracts serving integrated operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and formulation support layers are expanding faster than commodity premix hardware sales, creating service-attach economics for suppliers capable of deploying farm-level nutritionists.
For Market Incumbents: Fortify backward integration into micro-encapsulation capabilities to defend margin position against commodity bulk vitamin distributors. Deepen captive supply of stability-documented natural-source tocopherols for Saudi SFDA-registered formulations. Channel control through multi-year technical service agreements with Qassim-region poultry integrators anchors volume retention against emerging regional blenders.
For New Entrants and Emerging Players: Lead with liquid vitamin delivery systems targeting Saudi Riyadh and Jeddah corridor feed mill automation upgrades as the most penetrable white-space segment. Egyptian aquaculture expansion under General Organization for Veterinary Services licensing reforms offers secondary entry pathway. A go-to-market angle emphasizing homogeneous mixing precision and reduced dust exposure distinguishes against legacy powder distributors.
For Investors and Strategic Acquirers: Long-term, this sits as a import-substitution infrastructure play because Saudi Vision 2030 localization mandates are structurally rewiring supply chain ownership toward domestic blending capacity. Acquisition target archetype: regional premix houses with SFDA registration capabilities and existing Gulf distribution partnerships. The signal to watch is MOCCAE-SFDA regulatory harmonization progress as inflection indicator for cross-border scale economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Encapsulation | In-house micro-encapsulation capabilities capture premium pricing for heat-stress formulations in Saudi dairy operations. |
| SFDA Registration Investment | Localized stability documentation secures market continuity under Saudi premix registration mandates. |
| Liquid Delivery System Deployment | Oil-suspension technologies align with Riyadh corridor feed mill automation upgrades seeking homogeneous mixing. |
| Egyptian Aquaculture Partnership | Nile Delta tilapia and shrimp feed producers represent fastest-expanding vitamin D demand segment under food security programs. |
| Technical Service Contract Expansion | Embedded farm-level nutritionist deployment consolidates procurement relationships with vertically integrated Saudi operators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SFDA regulatory filings, MOCCAE additive registrations, and trade flow data through Saudi customs records. Primary interviews engaged premix formulation chemists, procurement directors at integrated poultry operations, feed mill engineering managers, and distribution channel partners across Saudi Arabia, UAE, and Egypt. Secondary validation drew from General Organization for Veterinary Services licensing databases, EU feed additive manufacturer disclosures, and Gulf logistics operator manifests. Bottom-up volume estimates from individual feed mill consumption patterns triangulate against top-down national livestock inventory projections.
Segmentation dimensions modeled span vitamin compound class, animal species application, product physical form, and distribution channel structure across the projection horizon. The analytical framework incorporates heat-stress formulation premiums, SFDA stability testing cost burdens, and feed mill automation adoption curves as industry-specific forecast inputs. CAGRs derive from regression against livestock production targets under national food security programs and observed premix inclusion rate trends.
The analysis sits within stated boundaries; outcomes outside sustained Saudi localization policy enforcement or prolonged Strait of Hormuz shipping disruption would require recalibration. Forecasts reflect assumptions regarding regulatory harmonization timelines and feed mill capital investment cycles. Revision becomes warranted when Egyptian aquaculture licensing reform crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
Vitamin AD Drops Market
Vitamin Fortified
Tocopherols Market
Vitamin Fortified
Global Mixed Tocopherol Market
Vitamin Fortified
Vitamin B Complex Market
Vitamin Fortified
Middle East and Africa Vitamin a Market
Vitamin Fortified
Global Vitamin Tonics Market
Vitamin Fortified
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market
Vitamin Fortified
Global Fortified Yogurt Market
Vitamin Fortified
Sodium Ascorbate Market
Vitamin Fortified
Asia-Pacific Feed Vitamins Market
Vitamin Fortified
Middle East and Africa Food Fortifying Agents Market
Vitamin Fortified
Water Soluble Vitamins Market
Vitamin Fortified
Food Grade Vitamin B1 Market
Vitamin Fortified
Food Fortifying Agents Market
Vitamin Fortified
Europe Feed Vitamins Market