
 Global Adult Vitamin Gummies Market | 2026-2036
Global Adult Vitamin Gummies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adult Vitamin Gummies Market Analysis
North American contract manufacturers is pivoting toward pectin-based production lines to serve clean-label demand. Church & Dwight Co Inc leverages its retail shelf presence across mass-market channels. Bayer AG anchors European pharmacy distribution with pharmacist-recommended positioning. Pharmavite LLC differentiates through USP-verified potency claims that sustain consumer trust.
Adult vitamin gummies are chewable, gelatin or pectin-based matrices containing micronutrients in doses calibrated for adult dietary reference intakes, produced via starch molding or depositing processes that control moisture below fifteen percent to ensure stability. These products deliver supplementation compliance advantages over tablets for consumers with swallowing difficulties or pill fatigue. Multivitamin formulations occupy the largest volume position due to broad demographic targeting, while sugar-free variants capture the fastest expansion as diabetic and keto-adherent populations reject sucrose-based alternatives. Online retail channels deepen margin pools by eliminating wholesale markups and enabling subscription replenishment models.
FDA cGMP enforcement and EFSA health claims verification create dual compliance thresholds that filter out undercapitalized entrants. ISO 17025 laboratory accreditation shapes quality benchmarks for active ingredient assay validation. Stakeholders must monitor evolving gelatin versus pectin raw material cost spreads and their impact on formulation economics.
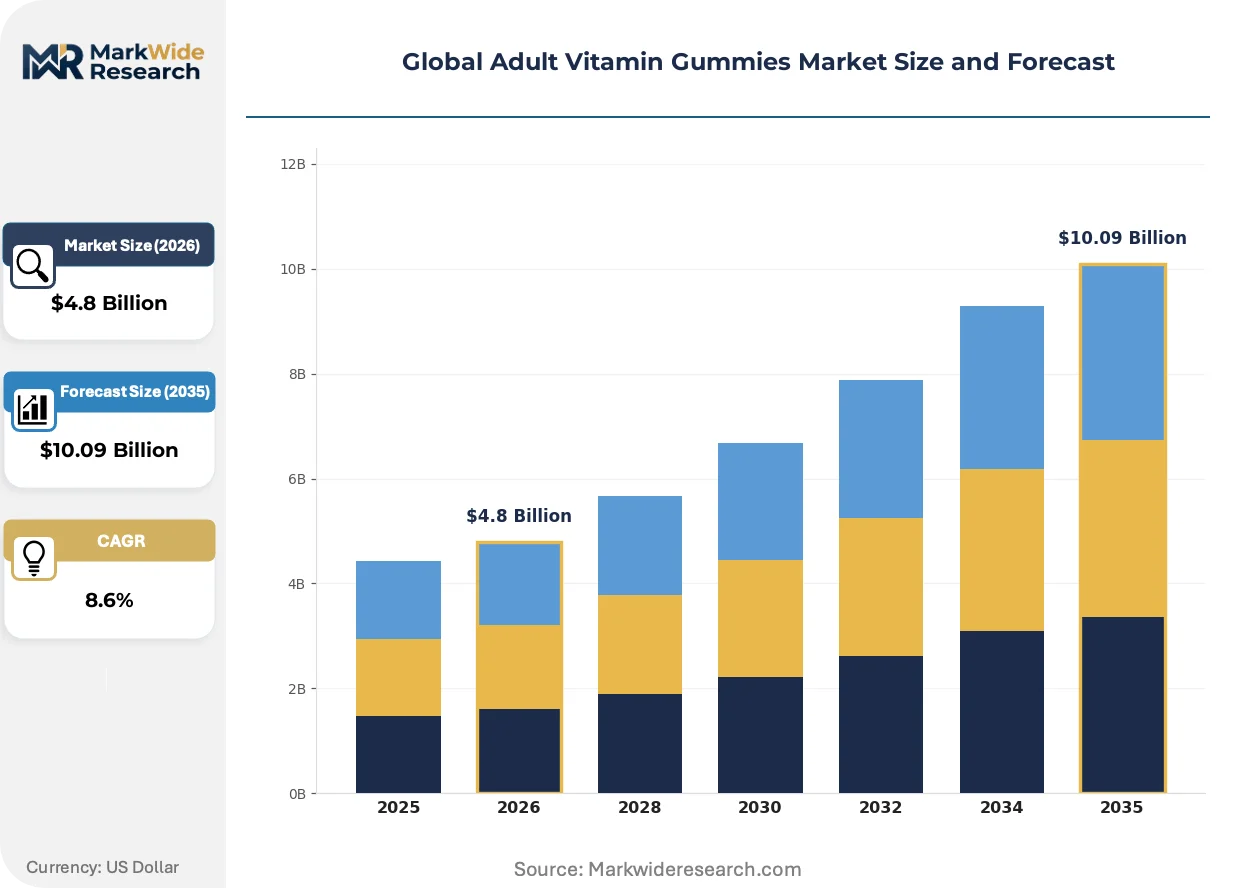
Market Dynamics
Clean-label formulation mandates from FDA and EFSA are forcing manufacturers to abandon gelatin in favor of pectin-based matrices, reshaping raw material procurement and production line investments across the adult vitamin gummies supply base.
Growth Catalysts
- EFSA Health Claims Verification:Pharmacist-recommended positioning in European pharmacy channels accelerates consumer trust and repeat purchase rates for clinically positioned brands.
- Pectin Process Innovation:Starch molding and depositing advances enable moisture control below fifteen percent, extending shelf stability without synthetic preservatives.
- Millennial Wellness Expenditure:This demographic cohort allocates disproportionate supplement budgets toward convenient, palatable formats that address pill fatigue and swallowing difficulties.
Market Restraints
- Gelatin-Pectin Cost Spread Volatility:Citrus peel supply fluctuations and porcine gelatin price instability compress formulation margins unpredictably.
- Dual Jurisdiction Compliance Burden:Simultaneous FDA cGMP and EFSA health claims enforcement creates fixed cost barriers that filter undercapitalized entrants from commercialization.
- Tablet and Capsule Substitution:Lower per-dose cost and established insurance reimbursement pathways sustain conventional format preference among cost-sensitive demographics.
Strategic Opportunities
- Subscription Replenishment Models:Direct-to-consumer platforms eliminate wholesale markups while capturing recurring revenue streams and first-party consumption data.
- Sugar-Free Variant Expansion:Diabetic and ketogenic-adherent populations reject sucrose-based alternatives, creating unmet demand for polyol-sweetened formulations.
- USP-Verified Potency Positioning:Third-party assay validation commands shelf price premiums in United States retail channels where quality skepticism persists.
Industry Challenges
- ISO 17025 Laboratory Accreditation Timeline:Active ingredient assay validation requirements delay product launch schedules and strain quality control staffing.
- Moisture Stability Expertise Scarcity:Formulation chemists with pectin matrix experience command compensation premiums that elevate R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adult Vitamin Gummies Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multivitamin, Vitamin C, Vitamin D, Omega-3 Formulation: Organic, Non-GMO, Sugar-Free, Gelatin-Based End User: Health-Conscious Consumers, Fitness Enthusiasts, Seniors, Busy Professionals Distribution Channel: Supermarkets, Online Retail, Pharmacies, Health Stores |
| Companies Covered | Church & Dwight Co Inc, Hero Nutritionals LLC, Amway Corp, Nature's Way Products LLC, Herbaland Naturals Inc, Bayer AG, Pharmavite LLC, SmartyPants Vitamins, Haleon Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adult Vitamin Gummies Market Emerging Trajectories
Formulation chemistry, compliance architecture, and channel economics are converging to redefine competitive advantage in adult vitamin gummies, with technology adoption pacing and regulatory navigation determining margin capture.
Pectin-based gelling systems are absorbing the functional role previously served by porcine and bovine gelatin across clean-label product lines. Contract manufacturers in the United States and Germany are retrofitting starch molding equipment to accommodate higher setting temperatures and altered viscosity profiles. This transition is compressing gelatin supplier bargaining power while elevating citrus-derived hydrocolloid demand.
EFSA health claims verification procedures now require randomized controlled trial evidence for immune and cognitive benefit assertions. European manufacturers must reformulate marketing language or invest in clinical substantiation that adds twelve to eighteen months to commercialization timelines. Pharmacy-distributed brands face the steepest compliance burden as pharmacist recommendation liability attaches to unsubstantiated claims.
Direct procurement through brand-owned digital storefronts is displacing traditional wholesale-pharmacy-retail intermediation for replenishment-oriented consumers. Subscription algorithms leveraging consumption velocity data enable predictive manufacturing and reduced safety stock requirements. This channel migration is most visible in United States urban markets where same-day delivery infrastructure supports impulse-to-habit conversion.
Global Adult Vitamin Gummies Market Segmentation
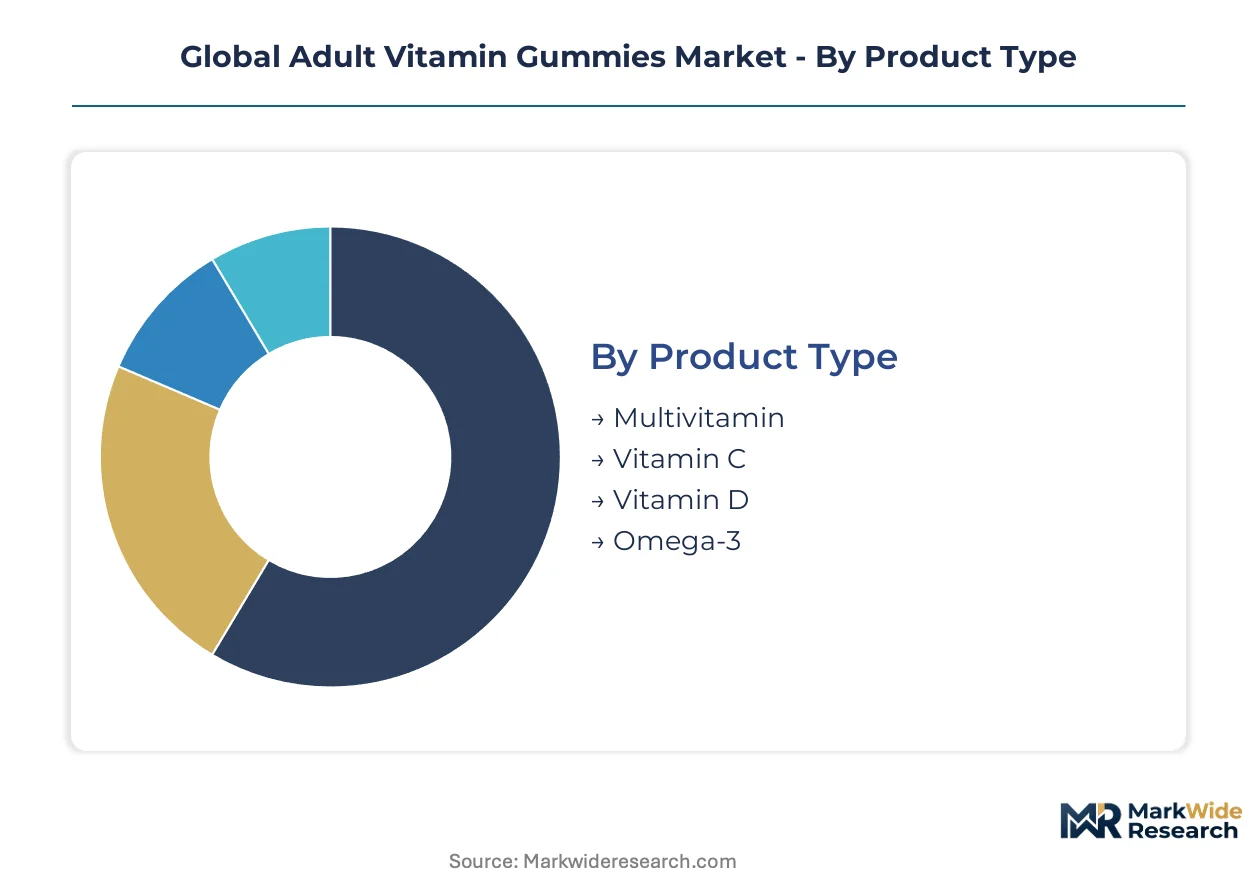
Adult vitamin gummies segment along four functional dimensions that determine formulation chemistry, procurement economics, and channel strategy. Product type dictates micronutrient calibration against dietary reference intakes. Formulation choices between gelatin and pectin matrices reshape raw material sourcing and clean-label positioning. End-user psychographics drive palatability engineering and packaging format decisions. Distribution channel selection determines margin capture and compliance burden intensity.
Product Type:
Upgrade cycles in adult vitamin gummies follow shifting consumer health priorities and emerging clinical evidence on micronutrient deficiencies.
- Multivitamin:Broad-spectrum formulations deliver calibrated doses of 10-15 essential micronutrients in single-dose matrices. Demand concentrates among health-conscious consumers in Germany and the United States seeking convenience-driven supplementation compliance. Mass-market positioning and pharmacy shelf presence sustain volume leadership despite per-unit margin compression.
- Vitamin C:Ascorbic acid matrices target immune function positioning with doses ranging from 250mg to 1000mg per serving. Fitness enthusiasts in China and urban United States markets drive repeat purchase velocity through seasonal consumption spikes. EFSA health claims verification requirements constrain marketing language in European pharmacy channels.
- Vitamin D:Cholecalciferol formulations address documented deficiency prevalence in northern latitude populations with limited solar exposure.
- Omega-3:EPA/DHA fatty acid delivery through emulsified matrices encounters stability challenges that elevate antioxidant packaging requirements.
Multivitamin sits at the top of the volume ranking, with sugar-free variants climbing the fastest across diabetic and ketogenic-adherent populations.
Formulation:
Cost tier differentiation in formulation chemistry separates premium clean-label positioning from conventional mass-market alternatives.
- Organic:USDA Organic or EU Organic certified inputs command 40-60% raw material premiums over conventional alternatives. Supply scarcity of certified organic micronutrient isolates limits production scale and extends lead times for contract manufacturers.
- Non-GMO:Project Verified or equivalent certification eliminates genetically modified corn-derived maltodextrin carriers and soy-based lecithin emulsifiers. United States consumer willingness-to-pay premiums sustain price positioning 15-25% above standard formulations.
- Sugar-Free:Polyol-sweetened matrices using erythritol, xylitol, or allulose replace sucrose for glycemic control adherence.
- Gelatin-Based:Porcine and bovine collagen-derived gelling agents retain cost advantages but face clean-label displacement in premium segments.
Gelatin-based formulations retain volume dominance in emerging markets, with organic certification gaining share fastest in United States and German premium channels.
End User:
Customer type segmentation aligns product development with distinct usage occasions, compliance barriers, and price sensitivity thresholds.
- Health-Conscious Consumers:Preventive wellness orientation drives multivitamin and adaptogenic ingredient demand with subscription replenishment preference. United States urban markets exhibit highest direct-to-consumer penetration and same-day delivery adoption.
- Fitness Enthusiasts:Performance-oriented micronutrient stacking elevates single-nutrient formats with timing-specific dosing protocols. Protein co-positioning and gym channel distribution create distinct procurement pathways from pharmacy-centric alternatives.
- Seniors:Swallowing difficulty prevalence and polypharmacy fatigue create compliance advantages for chewable formats over tablet alternatives.
- Busy Professionals:Convenience prioritization and travel-friendly packaging drive single-serve sachet and resealable pouch demand.
Health-conscious consumers anchor volume demand, with fitness enthusiasts expanding most quickly through gym channel penetration and performance marketing.
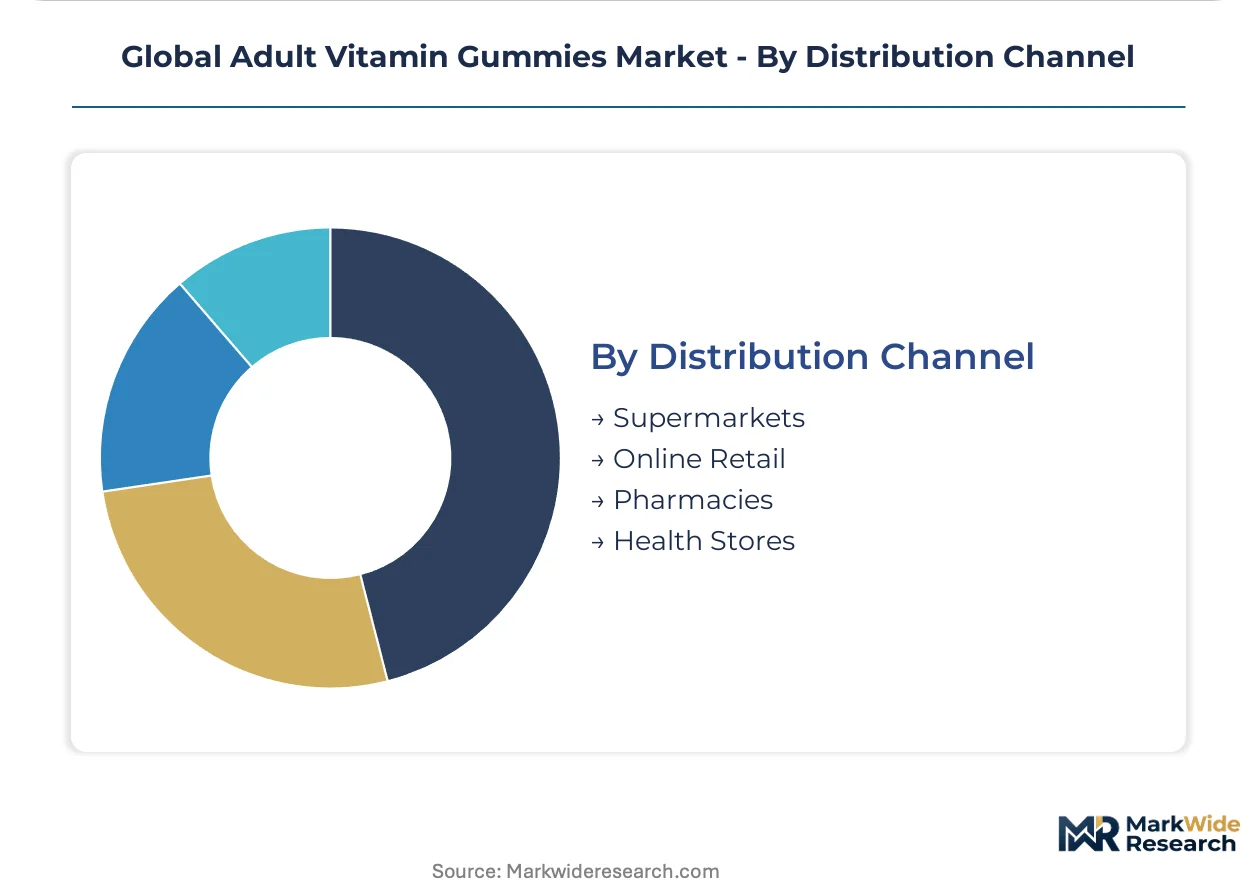
Distribution Channel:
Channel economics determine margin capture, compliance burden, and consumer data access across divergent intermediation structures.
- Supermarkets:Mass-market shelf placement demands slotting fee investments and promotional discounting that compress net margins. United States and German retail consolidation limits supplier negotiation leverage against Walmart, Kroger, and Rewe purchasing power.
- Online Retail:Direct-to-consumer and marketplace platforms eliminate wholesale markups while enabling subscription algorithms and first-party consumption data capture. Amazon, iHerb, and brand-owned storefronts concentrate United States digital volume.
- Pharmacies:Pharmacist recommendation liability and EFSA health claims verification create elevated compliance thresholds for immune and cognitive benefit assertions.
- Health Stores:Specialty retail positioning around clean-label curation supports premium pricing but limits geographic reach compared to mass-market alternatives.
Supermarkets retain volume leadership through impulse purchase visibility, with online retail climbing fastest through subscription model adoption and same-day delivery infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmacy-centric distribution model contrasts with the United States' direct-to-consumer acceleration, revealing how regulatory architecture shapes divergent growth trajectories across mature markets.
United States
Millennial wellness expenditure and subscription replenishment algorithms drive channel migration toward Amazon and brand-owned storefronts. FDA cGMP enforcement filters undercapitalized entrants through laboratory accreditation requirements. New Jersey and California contract manufacturers retrofit starch molding lines for pectin-based clean-label production.
Germany
Pharmacist-recommended positioning in pharmacy channels sustains premium pricing for clinically positioned brands. EFSA health claims verification procedures mandate randomized controlled trial evidence for immune benefit assertions. Bavaria-based production facilities concentrate pectin process innovation expertise.
China
Urban middle-class consumers in Shanghai and Beijing adopt vitamin C and D formats for immune positioning. SAMR registration requirements for imported health foods create compliance timelines that favor domestic contract manufacturers. Yangtze River Delta gummy producers scale depositing capacity for export markets.
United Kingdom
Health-conscious consumers in London and Southeast England prioritize sugar-free variants for glycemic control adherence. MHRA borderline classification determinations shape marketing language for nutrient-dense formats. Midlands-based contract manufacturers serve European private-label demand.
India
Fitness enthusiasts in Maharashtra and Karnataka drive single-nutrient format adoption through gym channel penetration. FSSAI health supplement regulations require ingredient disclosure standards that elevate quality control investments. Mumbai and Bangalore startups pilot pectin-based formulations for export qualification.
Global Adult Vitamin Gummies Market Vendor Landscape
United States producers anchor one tier; German specialists hold pharmacy-distributed positioning. The vendor base separates into mass-market shelf presence, clinical credibility, and direct-to-consumer agility tiers. Three archetypes dominate: legacy CPG conglomerates with retail leverage, pure-play gummy specialists with formulation IP, and vertically integrated nutrition platforms. Capacity expansion and subscription algorithm development represent the dominant competitive vectors.
Within the mass-market tier, Church & Dwight Co Inc exemplifies retail shelf leverage across United States supermarkets. Bayer AG occupies pharmacist-recommended positioning in European pharmacy channels. Pharmavite LLC anchors third-party verification credibility through USP-validated potency claims. These three entities represent distinct strategic postures without implying specific market share or financial performance.
| Leading Market Players |
|---|
| Church & Dwight Co Inc |
| Hero Nutritionals LLC |
| Amway Corp |
| Nature's Way Products LLC |
| Herbaland Naturals Inc |
| Bayer AG |
| Pharmavite LLC |
| SmartyPants Vitamins |
| Haleon Plc |
| Others |
Supply Flow & Price Mechanics
Premium-mid-economy pricing differentiation across organic, non-GMO, and conventional certification tiers manifests in divergent raw material procurement strategies and contract manufacturer qualification requirements. Pectin-based clean-label formulations command 40-60% raw material premiums over gelatin alternatives, compressing margins for brands lacking direct-to-consumer subscription infrastructure while rewarding vertically integrated players with captive citrus peel supply arrangements.
Pricing Analysis
Distributor margin stacking through wholesale-pharmacy-retail intermediation elevates shelf prices 35-50% above direct-to-consumer equivalents. Three-tier pricing structure across premium, standard, and economy levels separates USP-verified potency brands from mass-market alternatives and private-label economy offerings. Pricing pressure stems from gelatin-pectin cost spread volatility as citrus peel supply fluctuations and porcine gelatin price instability squeeze formulation economics. Cost-sensitive demographics in emerging markets exhibit highest price sensitivity, while health-conscious consumers in United States urban markets demonstrate lowest elasticity for certified organic positioning.
Supply Chain Analysis
Dual-sourcing requirements for pectin matrices mandate multi-supplier qualification across citrus peel processors in Spain, Italy, and Mexico to mitigate crop failure exposure. Raw material dependencies center on citrus-derived hydrocolloids, non-GMO corn maltodextrin carriers, and soy-based lecithin emulsifiers. Supply chain risk concentrates in single-source vulnerability for certified organic micronutrient isolates where USDA and EU Organic certification scarcity limits production scale. Distribution runs through Amazon and brand-owned storefronts for subscription replenishment, with pharmacy channels retaining premium positioning in Germany and supermarket mass-market dominance in United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as Millennial and Gen Z wellness expenditure shifts toward USP-verified potency and clean-label pectin formulations that command sustained shelf price premiums.
For Market Incumbents: Deploy USP-verified potency claims as a trust anchor against private-label erosion. Deepen backward integration into pectin raw material sourcing through captive citrus peel processing partnerships in Spain and Mexico. Fortify subscription algorithm capabilities to capture first-party consumption data and reduce customer acquisition cost exposure to Amazon marketplace fees. For New Entrants and Emerging Players: The price-point gap between premium organic certification and economy gelatin-based alternatives creates white-space opportunity for mid-tier non-GMO positioning. Target fitness enthusiasts through gym channel distribution with single-nutrient Vitamin C and D formats timed to seasonal immune positioning. Pursue white-label contract manufacturing relationships with United States direct-to-consumer brands lacking in-house starch molding expertise. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 17025 laboratory accreditation timelines and moisture stability expertise scarcity strain quality control staffing for mid-cap producers. Long-term viability favors vertically integrated nutrition platforms with captive pectin supply and subscription infrastructure over pure-play gummy specialists dependent on third-party contract manufacturing. Watch EFSA health claims verification enforcement intensity as the inflection indicator for European pharmacy channel margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Pectin Process Capacity Expansion | Retrofit starch molding lines in New Jersey and Bavaria to capture clean-label contract manufacturing demand. |
| USP Verification Investment | Third-party potency validation commands shelf price premiums in United States retail channels. |
| Subscription Platform Development | Predictive manufacturing algorithms reduce safety stock requirements and deepen margin pools. |
| Organic Certification Pipeline | USDA and EU Organic input scarcity limits production scale for qualified contract manufacturers. |
| Direct-to-Consumer Launch | Brand-owned storefronts eliminate wholesale markups and enable first-party data capture. |
Methodological Framework
Coverage spans United States, Germany, China, United Kingdom, and India, with primary inputs from each market's contract manufacturing executives, brand managers at supplement companies, pharmacy procurement leads, and quality control directors. Secondary validation draws from FDA cGMP inspection records, EFSA health claims register, SAMR registration filings, and Nielsen retail audit data. Bottom-up capacity modeling and top-down expenditure elasticity estimates were triangulated against trade flow data.
Granularity-level modeling addressed product type, formulation certification tier, end-user psychographic segment, and distribution channel across the analysis window. CAGRs were derived from segment-level volume and value build-ups incorporating micronutrient calibration trends, pectin adoption curves, and channel migration patterns. Forecast inputs included EFSA health claims verification timelines, FDA cGMP enforcement intensity, and same-day delivery infrastructure penetration rates.
Caveats apply where EFSA randomized controlled trial requirements, FDA laboratory accreditation delays, or citrus peel supply disruptions could materially shift the outlook. Deviation in clean-label certification adoption velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Enriched Flour Market
Vitamin Fortified
Colecalciferol Market
Vitamin Fortified
Vitamin D Market
Vitamin Fortified
Natural Beta Carotene Market
Vitamin Fortified
Middle East Feed Vitamins Market
Vitamin Fortified
Natural Vitamins Market
Vitamin Fortified
Fortified Food Market
Vitamin Fortified
Calcium Fortified Juice Market
Vitamin Fortified
Fat Soluble Vitamins Market
Vitamin Fortified
Retinyl Linoleate Market
Vitamin Fortified
Food Grade Retinol (Retinene) Market
Vitamin Fortified
Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Delta-Tocopherol Market
Vitamin Fortified
Food Grade Vitamin B Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
Esterified Vitamins Market