
 Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market | 2026-2036
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market Foresight
Poland is rewriting the production map for fortified beverages through expanded contract manufacturing capacity and cross-border supply integration. Danone SA leverages its dairy fermentation expertise to dominate probiotic-fortified drink segments. Nestle SA anchors its position through backward integration into micronutrient premix production. Abbott Laboratories specializes in clinical-grade nutritional formulations that command premium pharmacy placement.
Europe vitamin fortified and mineral enriched food and beverage encompasses products where vitamins or minerals are added during processing to achieve nutritional claims, typically involving spray-drying, microencapsulation, or direct blending at 50-200% of reference intake values per serving. These products serve to address documented micronutrient gaps in population diets while supporting targeted physiological functions from bone density to immune response. Functional beverages capture the widest margin pools as liquid delivery formats justify higher price points and repeat purchase frequency. Breakfast cereals retain volume leadership but face structural pressure from sugar reduction mandates that complicate fortification matrices. Nutritional supplements for seniors represent the fastest-growing end-user segment as aging demographics expand across Southern and Eastern Europe.
EFSA health claims authorization under Regulation (EC) No 1924/2006 determines which fortification messages reach European consumers, creating a bottleneck where only substantiated nutrient-function relationships gain market access. EMA oversight of medical foods and borderline products adds compliance layers for products targeting disease-risk reduction. REACH chemical safety requirements govern mineral additive sourcing and purity thresholds. Stakeholders must monitor pending revisions to the EU Nutrition and Health Claims Regulation that could recast permissible fortification levels and reshape competitive differentiation across the value chain.
Market Dynamics
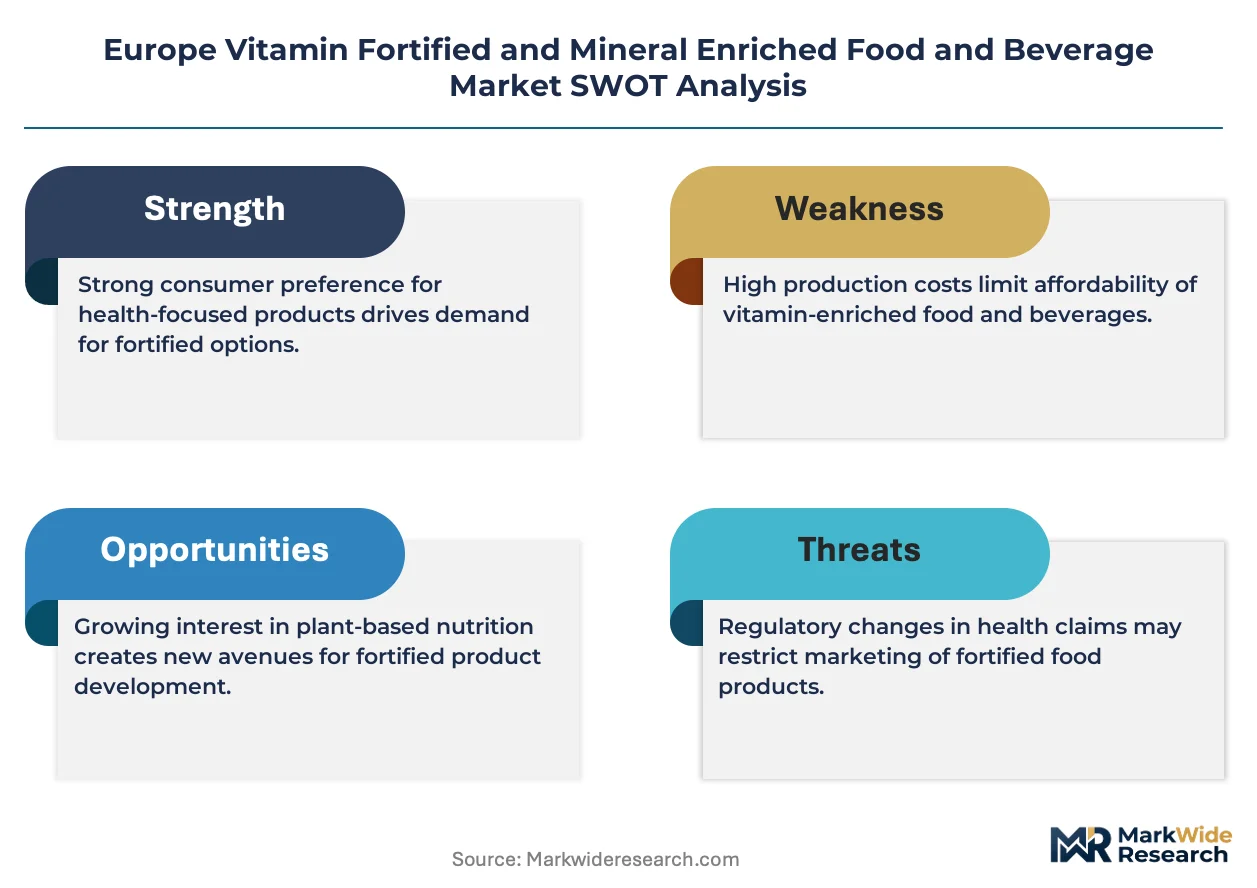
EFSA's tightening substantiation requirements under the EU Health Claims Regulation are compressing permissible marketing language for fortification claims, forcing reformulation investments and reshaping competitive differentiation across the value chain.
Growth Catalysts
- Sports nutrition adoption:Athletes and fitness enthusiasts in Germany, France, and Spain are expanding the consumer base for protein-fortified beverages and electrolyte-enriched hydration products, creating volume pull through specialty retail channels.
- REACH compliance integration:Mineral additive purity standards are elevating quality thresholds that favor established premix suppliers with certified supply chains, consolidating procurement relationships around verified sources.
- Aging demographics:Southern and Eastern European populations over 65 are driving clinical-grade nutritional supplement demand, with pharmacy channels capturing recurring prescription-adjacent purchases for bone density and immune support formulations.
Market Restraints
- Micronutrient input volatility:Supply concentration for selenium and zinc compounds in specific extraction geographies creates price instability that compresses margin predictability for mid-tier fortification suppliers.
- EFSA authorization bottlenecks:The nutrient-function substantiation process under Regulation (EC) No 1924/2006 delays claim approval timelines, freezing marketing investment until positive opinions issue.
- Sugar reduction mandate friction:Breakfast cereal fortification matrices face structural pressure from reformulation requirements that degrade vitamin stability during processing, complicating dual-claim product development.
Strategic Opportunities
- Poland contract manufacturing expansion:Cross-border supply integration into German and Nordic markets positions Polish production facilities as cost-competitive hubs for private-label fortified beverage manufacturing.
- Medical foods borderline positioning:EMA oversight frameworks for disease-risk reduction products create premium placement opportunities in pharmacy channels for formulations with clinical-grade micronutrient dosing.
- Microencapsulation-spray drying convergence:Hybrid processing technologies are enabling heat-sensitive vitamin incorporation into baked goods and retorted products previously excluded from fortification applications.
Industry Challenges
- Formulation chemist scarcity:Technical expertise in stability-matrix design for multi-nutrient premixes concentrates among aging specialists in Basel and Frankfurt, constraining R&D throughput for new market entrants.
- Dual certification timelines:Products targeting both food supplement and medical food classifications face sequential EFSA and EMA review processes that extend time-to-market by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market |
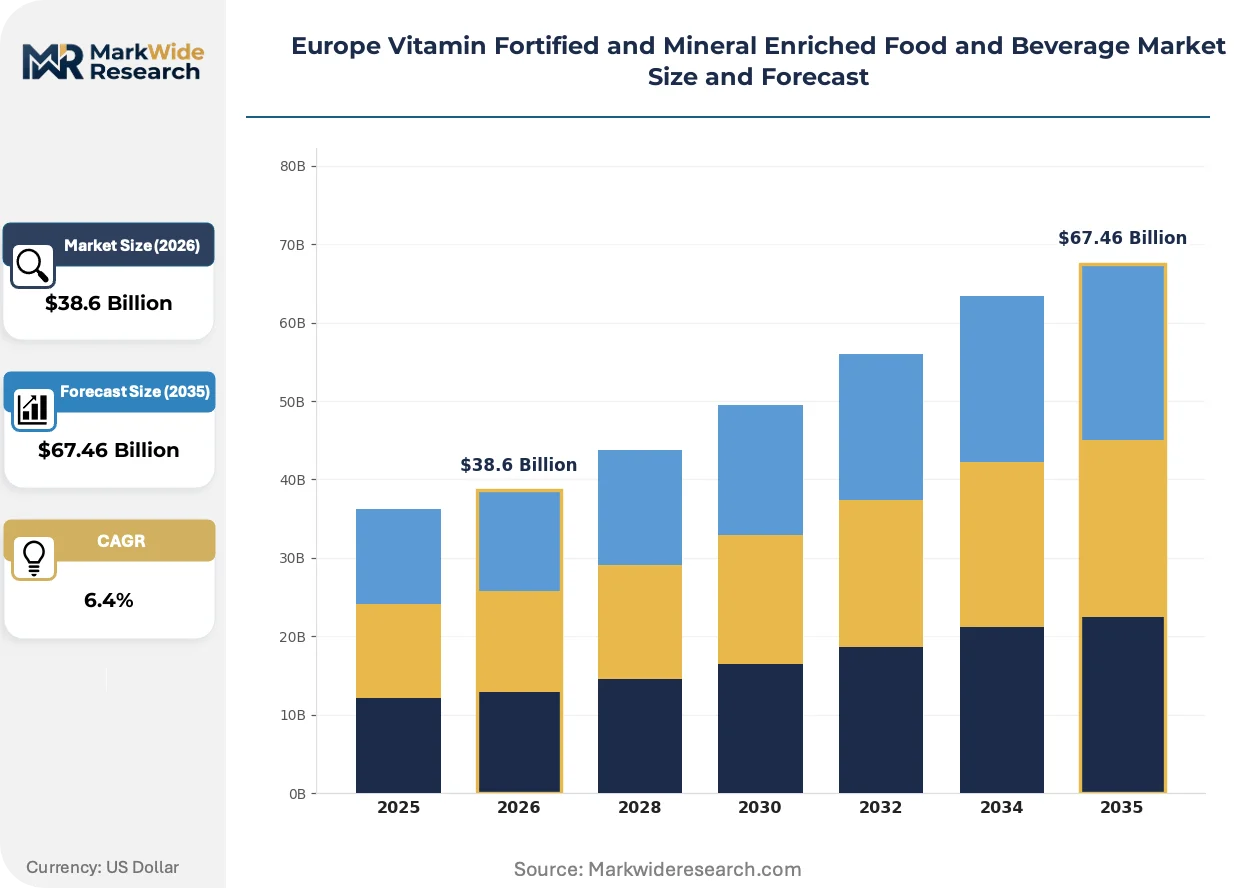
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $67.46 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Functional Beverages, Nutritional Supplements, Breakfast Cereals, Snack Bars Ingredient Type: Vitamin C, Vitamin D, Calcium, Iron End User: Athletes, Children, Pregnant Women, Seniors Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Pharmacies |
| Companies Covered | Nestle SA, Abbott Laboratories, PepsiCo Inc, Kellogg Company, Amway Corporation, Danone SA, The Coca-Cola Company, The Hain Celestial Group Inc, Marks and Spencer, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market Shifts & Advancements
Processing technology convergence and regulatory data requirements are digitizing quality assurance workflows while reformulation pressures accelerate ingredient innovation across the European fortified food and beverage sector.
Blockchain-enabled supply chain verification is digitizing mineral additive traceability from extraction through final product. German dairy processors and Dutch premix suppliers are deploying distributed ledger systems to satisfy EFSA audit requirements for health claim substantiation. This technology is digitizing compliance documentation, compressing third-party certification costs while creating defensible procurement relationships with retail chains.
REACH revisions governing chemical safety thresholds for food-contact mineral sources are elevating purity testing burdens. Industrial consequence includes mandatory third-party assay expansion for selenium yeast and chromium picolinate suppliers. The nutritional supplement segment faces the steepest compliance cost escalation, with pharmacy-channel products requiring batch-level certificate documentation that smaller premix blenders struggle to provision.
Direct-to-consumer subscription models are displacing traditional grocery replenishment for personalized micronutrient stacks. Nordic consumers lead adoption of algorithm-driven fortification regimens matched to biomarker data, with digital-native brands capturing recurring revenue previously held by retail private-label cereals. This behavioral shift concentrates most visibly in Sweden and Denmark, where pharmacy deregulation permits online clinical-grade nutritional sales.
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market Segmentation
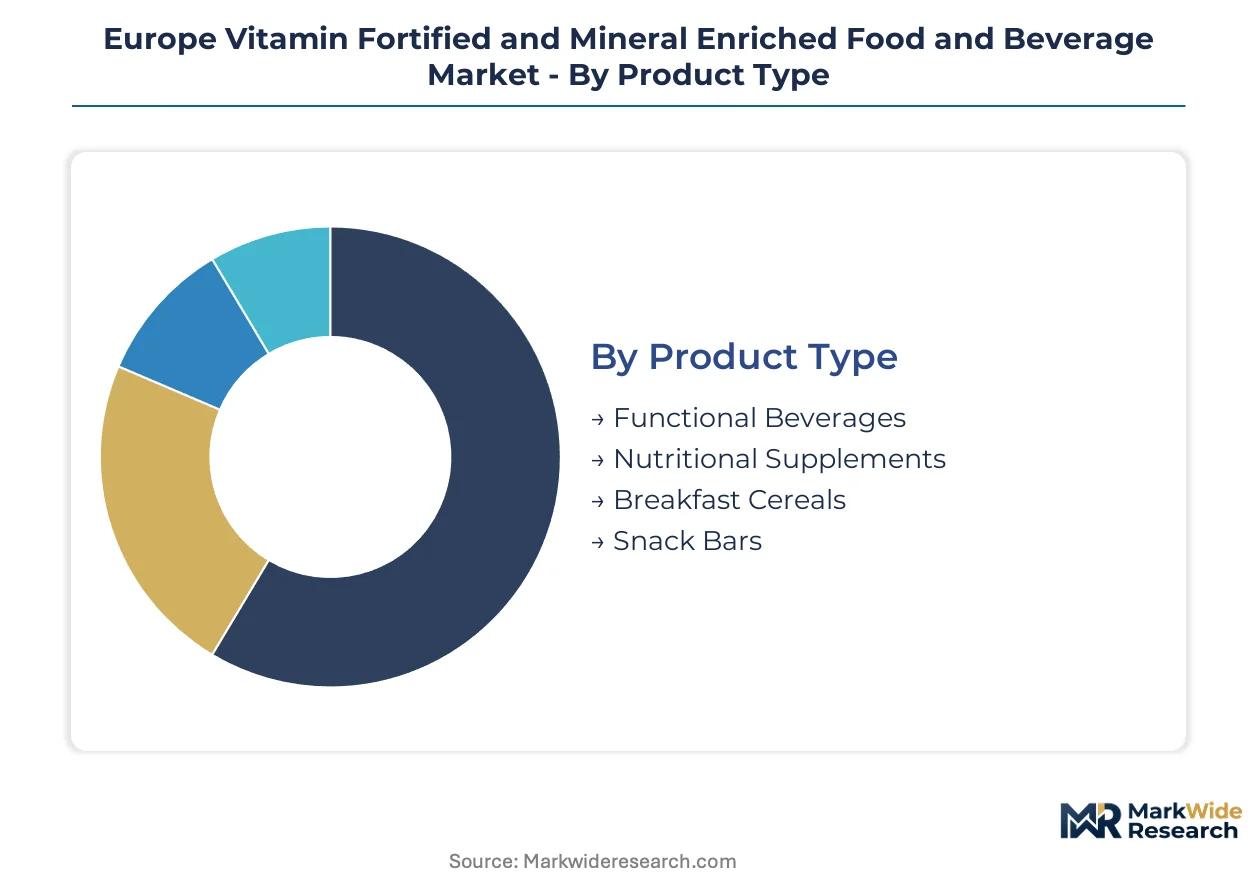
Segmentation in the European fortified food and beverage market reveals distinct margin profiles and replenishment rhythms across product formats. Cycle times vary dramatically from daily-consumed beverages to seasonal supplement purchases, reshaping inventory strategies and channel investments.
Product Type:
Functional beverages turn inventory fastest through refrigerated distribution networks, while nutritional supplements operate on extended purchase cycles with higher per-unit margins.
- Functional Beverages:Liquid delivery formats incorporate heat-sensitive vitamins via microencapsulation or cold-blending at 50-150% reference intake per serving. German and Nordic consumers drive repeat purchases through convenience retail, with sports hydration and probiotic dairy commanding premium shelf placement. EFSA health claim authorization bottlenecks slow new flavor variant launches.
- Nutritional Supplements:Clinical-grade tablets, capsules, and powders target bone density and immune support with precise micronutrient dosing. Pharmacy channels in Southern Europe capture recurring senior purchases, though dual EFSA-EMA certification timelines extend product development by 18-24 months.
- Breakfast Cereals:Spray-dried vitamin coatings face sugar reduction mandate friction that degrades fortification stability during extrusion processing.
- Snack Bars:Compressed formats with mineral-enriched coatings target on-the-go consumption in French and Spanish urban markets.
Breakfast cereals anchor the volume base while functional beverages gain share at the steepest rate.
Ingredient Type:
Cost tiers separate commodity-scale fortificants from specialty compounds requiring certified supply chains.
- Vitamin C:Ascorbic acid and mineral ascorbates provide antioxidant stability in aqueous systems. Polish contract manufacturers leverage bulk procurement for private-label beverage production serving German retail chains.
- Vitamin D:Cholecalciferol microencapsulation enables heat-stable incorporation into baked goods and UHT dairy previously excluded from fortification applications. Nordic biomarker-matched subscription services drive personalized dosing demand.
- Calcium:Carbonate and citrate salts target bone density claims in senior formulations, with REACH purity testing elevating supplier consolidation.
- Iron:Ferrous bisglycinate and encapsulated forms address bioavailability challenges in cereal matrices without metallic off-notes.
Vitamin C dominates by volume tonnage while Vitamin D expands most quickly through personalized nutrition platforms.
End User:
Application intensity varies from performance-driven athletic dosing to preventive maintenance in aging populations.
- Seniors:Clinical-grade formulations target documented calcium and Vitamin D deficiencies in Southern and Eastern European populations over 65. Pharmacy channel placement captures prescription-adjacent purchasing patterns with recurring revenue characteristics.
- Athletes:Protein-fortified recovery beverages and electrolyte-enriched hydration products pull volume through German, French, and Spanish specialty retail. EFSA-substantiated performance claims differentiate premium positioning from commodity sports drinks.
- Children:Iron and Vitamin D fortification addresses developmental requirements in breakfast cereals and growing-up milks.
- Pregnant Women:Folate and iron combinations serve prenatal nutritional requirements through medical food borderline positioning.
Seniors anchor the volume base while athletes gain share at the steepest rate.
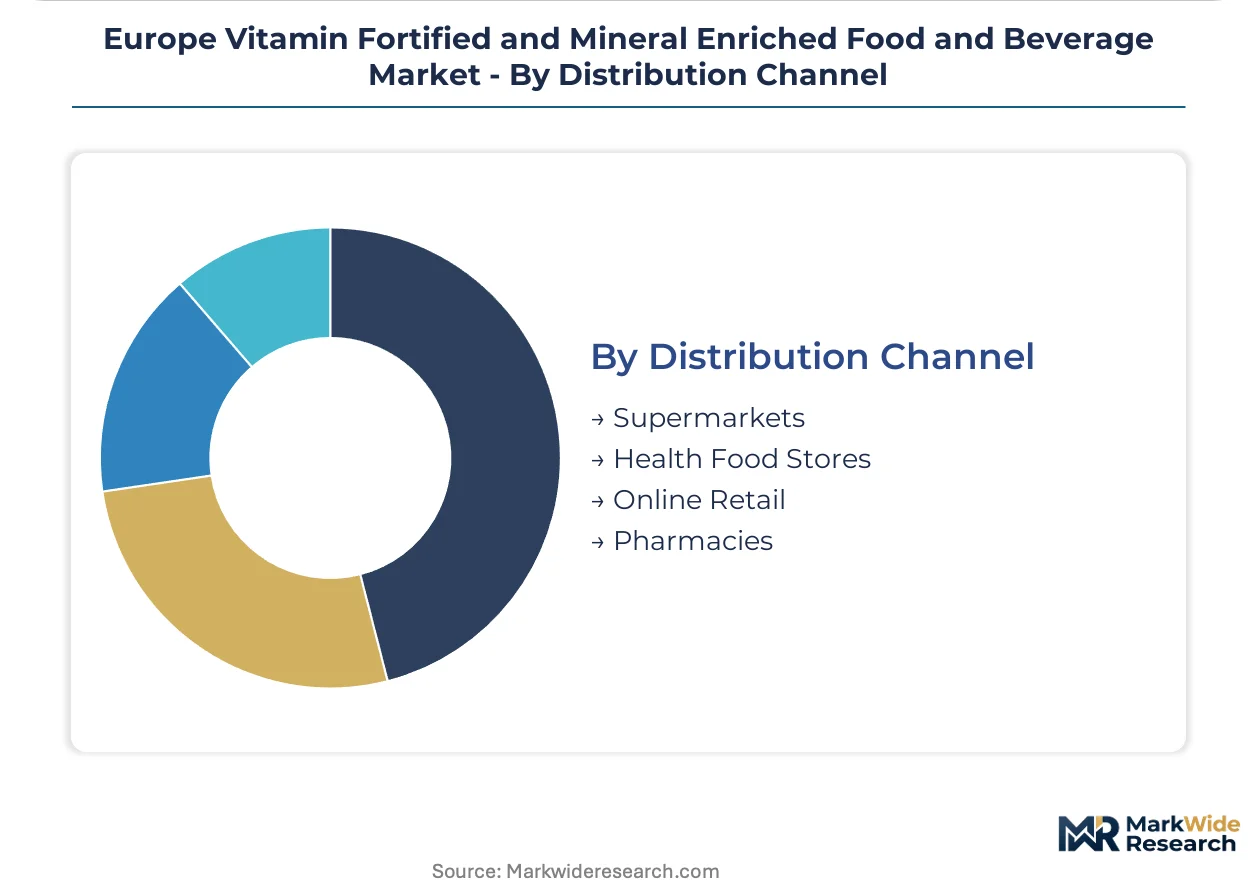
Distribution Channel:
Customer type concentration separates mass-market grocery replenishment from guided pharmacy consultations.
- Pharmacies:Clinical-grade supplements with EMA oversight for disease-risk reduction claims command premium pricing and trained staff recommendation. Southern European markets maintain stricter pharmacy channel control over medical food classifications.
- Online Retail:Direct-to-consumer subscription models displace traditional replenishment in Sweden and Denmark, where pharmacy deregulation permits algorithm-driven micronutrient stacking matched to biomarker data.
- Supermarkets:Mass-market cereals and beverages face private-label pressure with compressed margin pools.
- Health Food Stores:Specialist retailers capture organic and clean-label fortification demand in German and Austrian urban centers.
Supermarkets anchor the volume base while online retail gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fortified food and beverage manufacturing clusters concentrate in Germany's dairy belt and Poland's contract manufacturing corridor, with regulatory divergence between EFSA jurisdictions and national pharmacy controls fragmenting go-to-market pathways across the continent.
Germany
Sports nutrition demand from fitness enthusiasts and amateur athletes drives protein-fortified beverage consumption through convenience retail. EFSA health claims substantiation under Regulation (EC) No 1924/2006 governs permissible marketing language for functional positioning. Bavaria's dairy processing belt hosts spray-drying facilities supplying microencapsulated vitamin D for UHT milk fortification.
Poland
Cross-border supply integration into German and Nordic markets accelerates private-label contract manufacturing for functional beverages. REACH chemical safety requirements elevate purity testing burdens for mineral additive sourcing. Warsaw and Łódź production clusters specialize in cold-blended vitamin C fortification for export-oriented beverage brands.
France
Organic and clean-label fortification demand concentrates in Parisian and Lyonnais urban markets through specialist health food retail. ANSM oversight of borderline medical foods creates compliance pathways for clinical-grade nutritional supplements. Auvergne-Rhône-Alpes hosts premix formulation facilities serving pan-European bakery fortification.
Spain
Aging demographics in Mediterranean coastal regions expand pharmacy-channel demand for bone density and immune support formulations. EMA medical food classifications enable premium positioning for disease-risk reduction products. Barcelona's food technology cluster develops heat-stable vitamin matrices for retorted beverage applications.
Sweden
Algorithm-driven personalized nutrition subscriptions displace traditional grocery replenishment for biomarker-matched micronutrient stacks. Pharmacy deregulation permits direct-to-consumer online sales of clinical-grade supplements. Stockholm's digital health ecosystem anchors Nordic leadership in personalized fortification platform development.
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market Competitive Landscape
Diversified nutrition conglomerates and specialized clinical-formulation houses split the market into distinct capability tiers. Consolidation concentrates around dairy-derived probiotic platforms and pharmaceutical-grade supplement manufacturing. Strategic archetypes include backward-integrated premix producers, fermentation-technology specialists, and medical-food borderline navigators. Dominant competitive moves encompass cross-border manufacturing partnerships and dual EFSA-EMA certification investments.
Within the diversified conglomerate tier, Nestle SA and Danone SA exemplify scale-driven fortification platforms spanning beverage and dairy matrices. Abbott Laboratories occupies a specialized position in clinical-grade nutritional formulations commanding pharmacy-channel premium placement. These three anchors represent distinct strategic pathways: captive micronutrient supply, fermentation-derived probiotic integration, and disease-risk reduction positioning under EMA oversight.
| Leading Market Players |
|---|
| Nestle SA |
| Abbott Laboratories |
| PepsiCo Inc |
| Kellogg Company |
| Amway Corporation |
| Danone SA |
| The Coca-Cola Company |
| The Hain Celestial Group Inc |
| Marks and Spencer |
| Others |
Supply & Pricing Matrix
Polish contract manufacturing clusters for vitamin C fortification feed directly into German private-label beverage programs, concentrating margin capture among premix suppliers with REACH-certified mineral sourcing rather than finished goods assemblers.
Pricing Analysis
EFSA health claims authorization under Regulation (EC) No 1924/2006 dictates the pricing tier structure across functional beverages, nutritional supplements, and breakfast cereals. Premium-mid-economy pricing differentiation separates clinical-grade pharmacy-channel products from mass-market grocery placements, with certification grade and volume scale as primary price drivers. Cost compression in mid-tier fortification matrices is intensifying because REACH purity testing elevates supplier qualification burdens. Private-label cereal buyers exhibit highest price sensitivity, while pharmacy-channel senior formulations command lowest elasticity.
Supply Chain Analysis
Export-control regimes governing selenium yeast and chromium picolinate extraction technologies limit flows from concentrated geographies, elevating procurement risk for European formulators. Supply draws from German dairy processing belts, Polish beverage manufacturing corridors, and Dutch premix formulation hubs. Raw material dependencies center on vitamin D cholecalciferol microencapsulation inputs, ferrous bisglycinate bioavailability compounds, and calcium carbonate purity grades. Single-source vulnerability concentrates around selenium compound extraction geographies. Distribution runs through refrigerated networks for functional beverages and pharmacy-controlled channels for clinical-grade supplements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fresh food fortification and whole-food nutrition solutions threaten processed fortified product volumes, forcing incumbents to defend substitution erosion through clinical-grade differentiation and pharmacy-channel capture.
For Market Incumbents: Insulate core margin pools by deepening backward integration into micronutrient premix production and securing dual EFSA-EMA certification for medical food borderline positioning. Nestle SA's captive supply strategy and Abbott Laboratories' pharmacy-channel dominance demonstrate defensive archetypes against clean-label substitute encroachment. Prioritize R&D investment in microencapsulation-spray drying convergence to expand heat-sensitive vitamin applications. For New Entrants and Emerging Players: Build out algorithm-driven personalized nutrition platforms in Sweden and Denmark, where pharmacy deregulation permits direct-to-consumer clinical-grade sales and biomarker-matched subscription models displace traditional retail. Target senior populations in Southern and Eastern Europe with bone density and immune support formulations, leveraging Poland's contract manufacturing cost advantages for cross-border supply into German markets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across microencapsulation technology segments as REACH compliance and EFSA substantiation requirements elevate fixed cost barriers. Five-to-ten-year viability favors acquisition targets with certified mineral supply chains and established pharmacy-channel relationships. Monitor EFSA authorization timelines as inflection indicator for marketing investment release and premium pricing realization.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Simultaneous EFSA and EMA review processes compress time-to-market for disease-risk reduction products. |
| Backward Integration into Premix | Captive micronutrient supply secures margin capture and REACH compliance documentation for retail chains. |
| Microencapsulation Technology Acquisition | Heat-stable vitamin matrices unlock baked goods and retorted beverage applications previously excluded from fortification. |
| Pharmacy Channel Partnership | Trained staff recommendation and prescription-adjacent placement command premium pricing for senior formulations. |
| Poland Manufacturing Footprint Expansion | Cross-border supply integration into German and Nordic markets captures private-label contract manufacturing growth. |
Research Methodology
Desk research of EFSA health claims registers, REACH chemical safety filings, and EU trade flow databases preceded structured interviews with premix formulation chemists, pharmacy category managers, dairy processing technical directors, and retail private-label buyers. Secondary validation drew from industry association technical guidelines, customs mineral additive import records, and food technology patent filings. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Assumptions held fixed include EFSA authorization timelines, REACH purity threshold revisions, and pharmacy deregulation trajectories across Nordic markets; variables stress-tested encompass mineral input price volatility, sugar reduction mandate stringency, and sports nutrition adoption curves. The analytical framework modeled product type, ingredient category, end-user demographic, and distribution channel dimensions across the projection horizon. CAGRs derived from segment-level volume and value buildups incorporating biomarker-matched subscription adoption rates and clinical-grade supplement pharmacy-channel penetration.
Stress conditions across selenium and zinc compound supply concentration, EFSA substantiation backlog duration, and sugar reduction processing stability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory trajectory and demographic shift velocity. Material shifts in EU Health Claims Regulation revision scope or REACH chemical safety threshold timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Vitamin C Market
Vitamin Fortified
Pantothenic Acid Market
Vitamin Fortified
High Calcium Fortified Food Market
Vitamin Fortified
North America Vitamin D Market
Vitamin Fortified
North America Food Fortifying Agents Market
Vitamin Fortified
Riboflavin Market
Vitamin Fortified
Global Adult Vitamin Gummies Market
Vitamin Fortified
Global Fortified Edible Oils Market
Vitamin Fortified
Asia-Pacific Feed Vitamins Market
Vitamin Fortified
Food Grade Vitamin B1 Market
Vitamin Fortified
Feed Grade Vitamin D Market
Vitamin Fortified
Colecalciferol Market
Vitamin Fortified
Micronutrients Market
Vitamin Fortified
Vitamin D Market
Vitamin Fortified
Sodium Ascorbate Market
Vitamin Fortified
Vitamins Drink Market