
 Micronutrients Market | 2026-2036
Micronutrients Market Size, Share, and Industry Trends Forecast 2026-2036
Micronutrients Market Analysis
Subscription-based agronomic advisory services bundled with micronutrient prescriptions is pivoting how suppliers monetize crop nutrition. BASF SE leverages its digital farming platform to anchor premium chelated mineral sales in European row-crop markets. Nutrien Ltd. sustains North American distribution dominance through controlled retail networks and in-house agronomy staffing. Haifa Group specializes in water-soluble micronutrient formulations, competing on greenhouse and fertigation system compatibility.
Micronutrients are essential mineral elements required by organisms in minute quantities for metabolic and physiological functions, typically applied in concentrations below 100 parts per million in agricultural or nutritional formulations, with primary industrial purpose spanning crop yield optimization, livestock health maintenance, and human dietary supplementation. Vitamins and trace elements command the largest value pools in agricultural applications, where soil depletion and intensive farming practices sustain replacement demand. Functional foods represent the fastest-growing application channel, as food manufacturers fortify processed products with bioavailable mineral forms to meet evolving nutritional labeling requirements.
The EPA regulates micronutrient fertilizer registration and environmental release thresholds in the United States, while the EU Green Deal and REACH framework restrict heavy-metal contaminants in soil amendments sold across member states. India's FSSAI and BIS jointly enforce purity standards for nutritional-grade minerals entering food and supplement channels, shaping import compliance costs for foreign suppliers. Stakeholders must monitor evolving chelation technology patents and regional bioavailability testing protocols to defend product positioning against generic mineral salts.
Market Dynamics
Precision agriculture platforms are compressing the gap between soil diagnostics and micronutrient application rates, forcing suppliers to embed real-time agronomic algorithms into their distribution models or surrender margin to digital intermediaries.
Growth Catalysts
- Soil Health Card Scheme:India's government-mandated soil testing program is expanding micronutrient prescription access to 140 million farmland plots, creating institutional demand for zinc, boron, and iron formulations.
- EU Fertilizing Products Regulation:Standardized CE-marking requirements for chelated trace elements are consolidating quality tiers and accelerating premium product substitution of raw mineral salts across member states.
- Fertigation system penetration:Protected cultivation in Spain, Mexico, and Turkey is shifting water-soluble micronutrient demand toward greenhouse-compatible formulations with guaranteed dissolution rates.
Market Restraints
- Sulfuric acid feedstock volatility:Copper sulfate and zinc sulfate production costs track sulfuric acid spot prices, which fluctuate with phosphate fertilizer output and smelter byproduct availability.
- EDTA chelate supply concentration:Chinese manufacturers control 70% of global ethylenediaminetetraacetic acid supply, creating single-source vulnerability for European and North American formulators.
- Heavy-metal contamination thresholds:REACH Annex XVII restrictions on cadmium and nickel content in soil amendments force reformulation of legacy mineral sources.
Strategic Opportunities
- Sub-Saharan Africa underpenetration:Commercial farming expansion in Zambia, Kenya, and Ethiopia lacks established micronutrient distribution infrastructure, rewarding first-mover logistics investments.
- Functional food fortification mandates:India's FSSAI mandatory wheat flour fortification with iron, folic acid, and zinc is creating nutritional-grade mineral demand separate from agricultural channels.
- Biostimulant convergence:Integration of micronutrients with microbial inoculants and seaweed extracts is opening premium positioning in organic-certified crop segments.
Industry Challenges
- Agronomic data scientist scarcity:Suppliers struggle to staff precision agriculture platforms with personnel capable of translating satellite imagery and soil sensor data into prescriptive micronutrient recommendations.
- Chelate bioavailability validation timelines:OECD 106/107 testing protocols for trace element release rates extend product registration cycles by 18-24 months in EU and North American jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micronutrients Market |
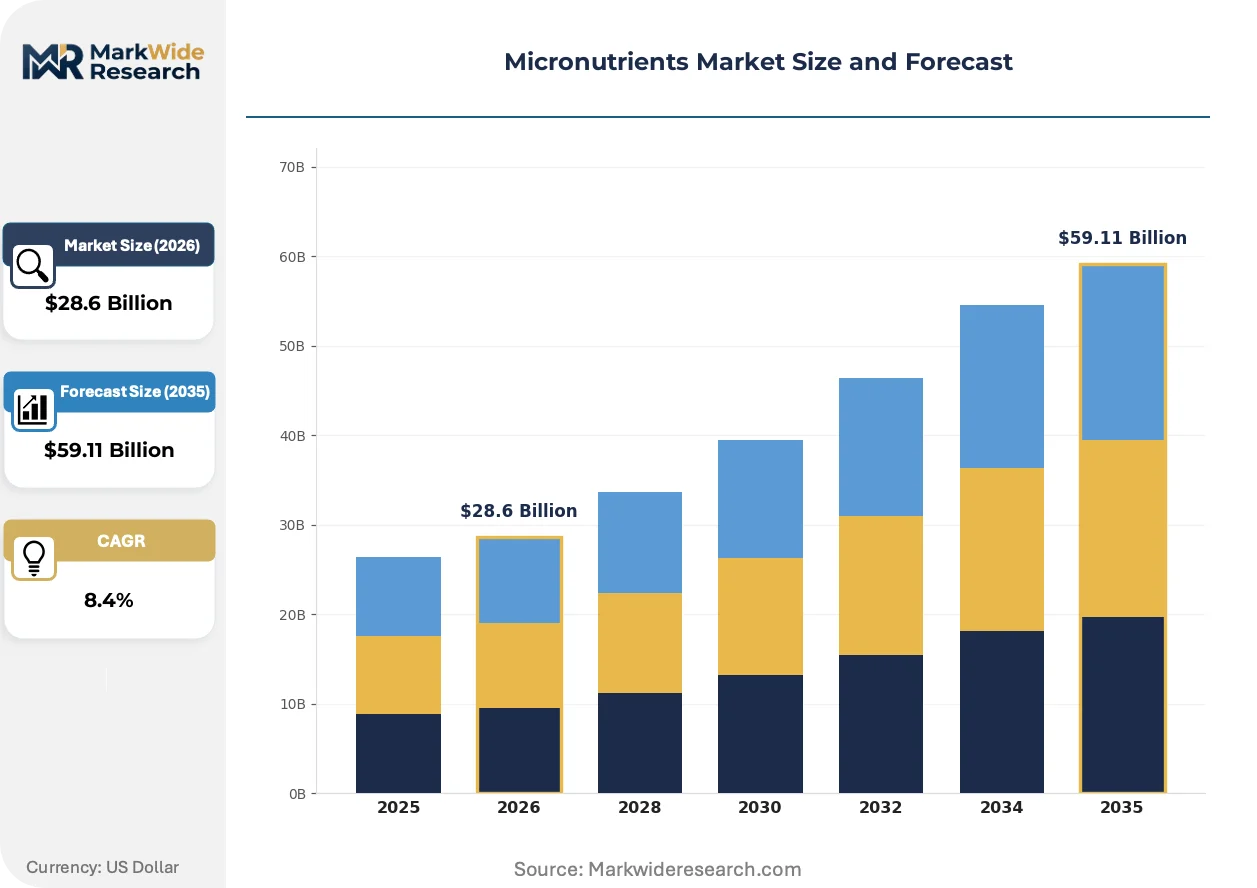
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Amino Acids, Trace Elements Application: Nutritional Supplements, Functional Foods, Animal Feed, Fertilizers Form: Powder, Liquid, Granule, Tablet End User: Healthcare, Food & Beverage, Agriculture, Pharmaceuticals |
| Companies Covered | Yara International ASA, The Mosaic Company, Nutrien Ltd., BASF SE, Haifa Group, Nouryon, ICL Specialty Fertilizers, Coromandel International Limited, Syngenta AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micronutrients Market Emerging Trajectories
Biostimulant-micronutrient hybrid formulations are compressing the boundary between mineral nutrition and plant physiology management, forcing traditional fertilizer suppliers to acquire or partner with biologicals specialists.
Nano-encapsulation technology is electrifying micronutrient delivery efficiency by protecting iron, zinc, and manganese ions from soil fixation until root-zone release. Large-scale row-crop operations in Brazil and the US Corn Belt are piloting these formulations to reduce application frequency from three to one per growing season. The technology is compressing per-hectare mineral input volumes while maintaining yield benchmarks, threatening bulk commodity micronutrient economics.
REACH authorization requirements for EDTA and DTPA chelating agents are compelling formulators to validate biodegradable alternatives such as IDHA and GLDA. The regulation is fragmenting product portfolios as suppliers maintain parallel formulations for EU-compliant and non-EU markets. Specialty crop sectors with organic certification requirements are accelerating adoption of natural chelate sources ahead of regulatory deadlines.
Subscription-based agronomic advisory is displacing transactional micronutrient sales in North American and European row-crop markets. Growers now procure mineral prescriptions bundled with soil monitoring and yield analytics rather than purchasing standalone products. This shift concentrates demand among suppliers with captive digital farming platforms and compresses margins for distributors without in-house agronomy capabilities.
Micronutrients Market Segmentation
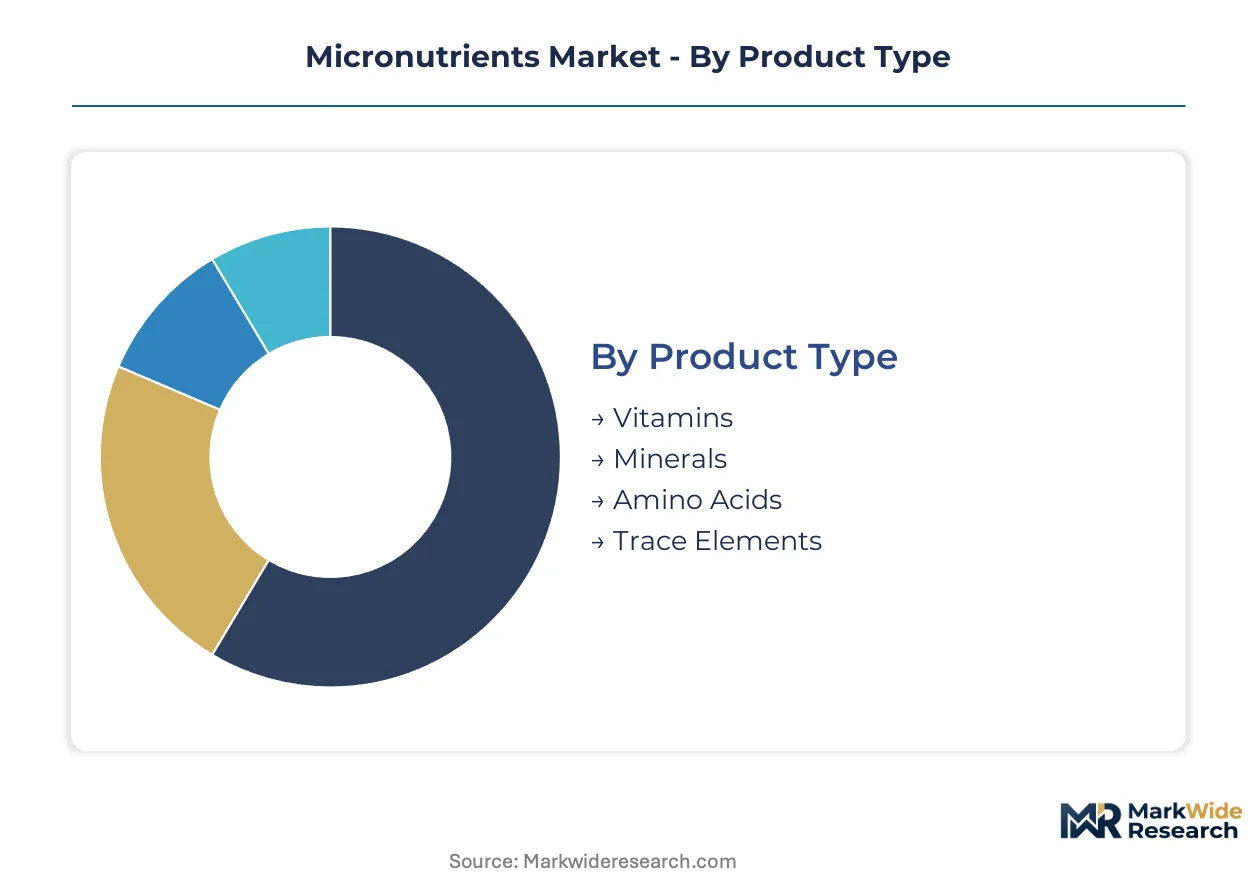
Micronutrient suppliers configure product portfolios around four intersecting dimensions: biochemical composition, downstream application, physical delivery format, and customer industry vertical. Each dimension carries distinct margin profiles and regulatory compliance burdens that reshape competitive positioning.
Product Type:
Vitamins and trace elements anchor volume throughput, while amino acids and mineral complexes command premium pricing in specialized formulations.
- Vitamins:Organic compounds essential for metabolic regulation, including fat-soluble and water-soluble variants. Demand concentrates in India's nutritional supplement manufacturing corridor, where FSSAI fortification mandates for wheat flour and edible oils sustain institutional procurement volumes.
- Minerals:Inorganic elements including macro-minerals and trace elements delivered as sulfates, oxides, or chelated complexes. Zinc and iron formulations dominate agricultural prescriptions under India's Soil Health Card Scheme, with 140 million farmland plots now requiring site-specific mineral replenishment.
- Amino Acids:Proteinogenic and non-proteinogenic compounds serving as metabolic intermediates and chelation agents. Animal feed premix manufacturers in Brazil and Mexico incorporate lysine and methionine blends to optimize livestock feed conversion ratios.
- Trace Elements:Boron, manganese, copper, and molybdenum applied at sub-100 ppm concentrations. Protected cultivation operators in Spain and Turkey specify water-soluble trace element formulations compatible with fertigation system dissolution requirements.
Today's leader: Minerals. Tomorrow's challenger: Amino acids.
Application:
Functional foods and nutritional supplements drive margin expansion, while fertilizers and animal feed sustain baseline throughput.
- Nutritional Supplements:Capsule, tablet, and powder formats for human dietary enhancement. India's FSSAI mandatory wheat flour fortification with iron, folic acid, and zinc is redirecting mineral volumes from agricultural channels into food-grade processing.
- Functional Foods:Processed products with bioavailable mineral fortification to meet nutritional labeling requirements. European food manufacturers under EU Green Deal sustainability frameworks are accelerating clean-label mineral sourcing to satisfy EFSA health claim substantiation protocols.
- Animal Feed:Premix and complete feed formulations for livestock productivity. Brazilian poultry and swine operations integrate precision-formulated trace minerals to reduce environmental excretion while maintaining growth performance benchmarks.
- Fertilizers:Soil amendments and foliar sprays for crop yield optimization. Precision agriculture platforms in the US Corn Belt are compressing application rates through soil sensor diagnostics, threatening bulk commodity micronutrient economics.
Functional foods are climbing the fastest as fortification mandates proliferate across processed food categories.
Form:
Liquid and powder formats dominate commercial throughput, while granules and tablets address specialized delivery requirements.
- Powder:Dry, free-flowing particulate suitable for bulk blending and encapsulation. Nutritional supplement manufacturers in India prefer powder intermediates for flexible formulation and cost-efficient packaging.
- Liquid:Aqueous or oil-based suspensions enabling precise dosing and rapid dispersion. Greenhouse operators in Mexico and Turkey specify liquid micronutrients for fertigation system compatibility and guaranteed dissolution rates.
- Granule:Compacted, slow-release particles for soil application. Row-crop farmers in Brazil deploy granular zinc and boron formulations to reduce leaching losses in tropical soil conditions.
- Tablet:Compressed solid dosage forms for direct human consumption. Pharmaceutical and supplement channels in regulated markets require tablet formats meeting USP dissolution and disintegration specifications.
Liquid formats are gaining share fastest in protected cultivation segments.
End User:
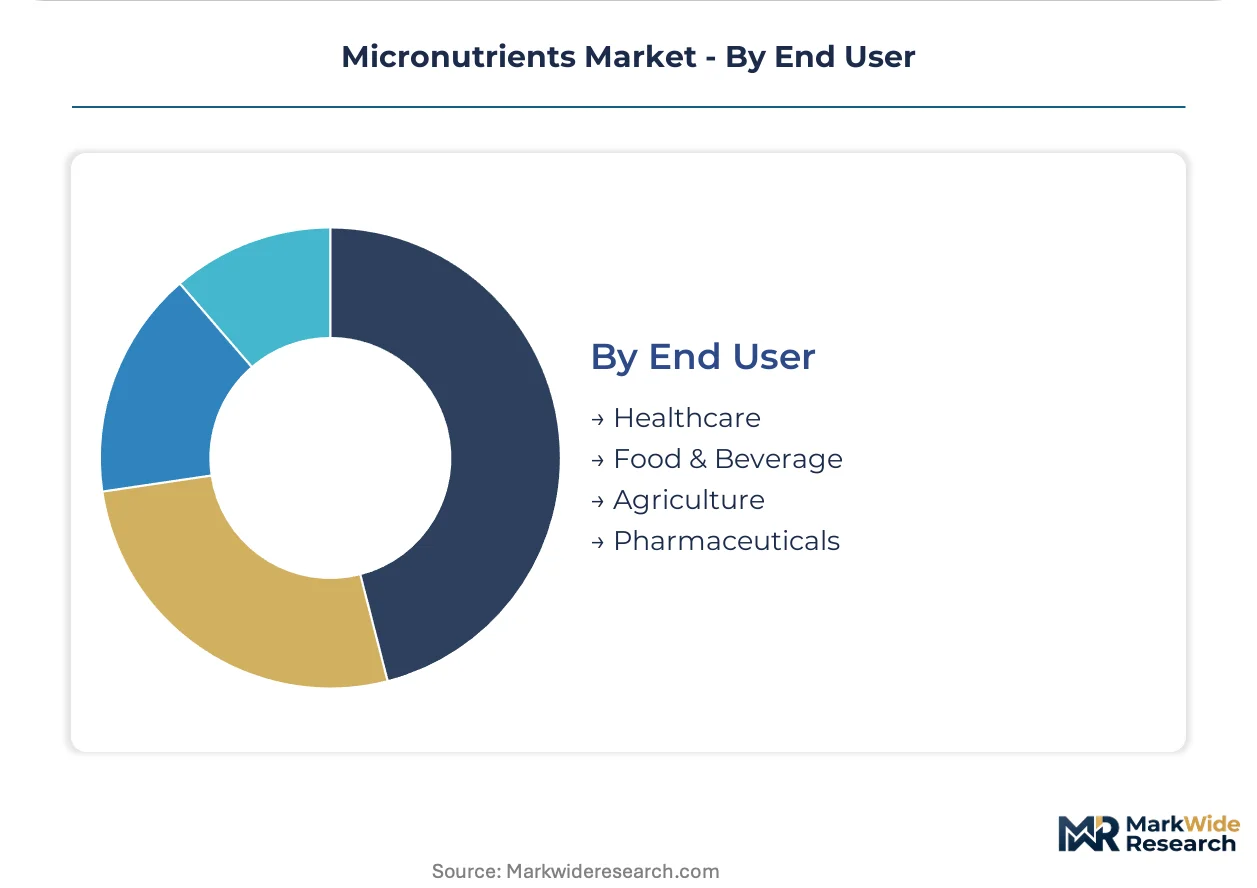
Agriculture and food manufacturing represent volume concentration, while healthcare and pharmaceuticals extract premium pricing through purity certification.
- Healthcare:Clinical nutrition and therapeutic supplementation under medical supervision. Hospital and long-term care facilities in Japan specify pharmaceutical-grade mineral injectables meeting PMDA manufacturing standards.
- Food & Beverage:Mass-market fortification of processed products. India's wheat flour millers now procure nutritional-grade iron and zinc under government-mandated fortification protocols separate from agricultural mineral channels.
- Agriculture:Crop and livestock productivity enhancement through soil, foliar, and feed applications. Brazil's precision agriculture adoption is forcing suppliers to embed real-time agronomic algorithms into distribution models or surrender margin to digital intermediaries.
- Pharmaceuticals:Active pharmaceutical ingredients and excipients requiring GMP certification. European formulators face REACH authorization requirements for EDTA chelating agents, compelling validation of biodegradable alternatives such as IDHA and GLDA.
Agriculture commands current volume leadership. Pharmaceuticals represent the steepest expansion trajectory through purity-premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's precision agriculture platforms outpace India's government-mandated soil testing programs in digital integration, yet both countries anchor agricultural micronutrient demand through fundamentally different procurement mechanisms.
United States
Row-crop operators in the Corn Belt deploy soil sensor diagnostics to compress application rates and threaten bulk commodity micronutrient economics. The EPA regulates fertilizer registration and environmental release thresholds, forcing suppliers to validate chelate formulations through extended testing protocols. Chicago-based distributors now bundle mineral prescriptions with satellite imagery analytics rather than selling standalone products.
Brazil
Commercial farming expansion in Mato Grosso and São Paulo drives demand for soil-specific micronutrient blends tailored to tropical conditions. ANVISA oversees agricultural input safety standards alongside MAPA's fertilizer quality regulations. Piracicaba's agritech cluster hosts precision agriculture platforms that embed real-time algorithms into distribution models, squeezing margin from traditional distributors without captive digital capabilities.
Germany
Specialty crop sectors accelerate biodegradable chelate adoption ahead of REACH authorization deadlines for EDTA and DTPA agents. ECHA restrictions on heavy-metal contaminants force reformulation of legacy mineral sources. Kassel's fertilizer formulation corridor concentrates water-soluble micronutrient R&D for greenhouse export markets across Southern Europe and the Middle East.
India
The Soil Health Card Scheme expands micronutrient prescription access to 140 million farmland plots, creating institutional demand for zinc, boron, and iron formulations. FSSAI and BIS jointly enforce purity standards for nutritional-grade minerals entering food and supplement channels. Gujarat's chemical processing belt redirects mineral volumes from agricultural channels into wheat flour fortification under government-mandated protocols.
Spain
Protected cultivation operators in Almería and Murcia specify water-soluble micronutrient formulations compatible with fertigation system dissolution requirements. EU Fertilizing Products Regulation standardizes CE-marking for chelated trace elements, consolidating quality tiers. Valencia's agricultural input distributors pivot toward subscription-based agronomic advisory bundled with mineral prescriptions for greenhouse vegetable exporters.
Micronutrients Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with agricultural channels favoring integrated suppliers and nutritional applications tolerating third-party formulators. The vendor base organizes around three tiers: multinational chemical conglomerates with captive mineral sourcing, regional fertilizer blenders with distribution density, and biostimulant specialists converging micronutrients with microbial inoculants. Consolidation pressure concentrates among mid-scale European formulators facing REACH compliance cost escalation. Dominant competitive moves include backward integration into sulfuric acid and phosphate byproduct streams, plus technology licensing agreements for nano-encapsulation delivery systems.
Within the multinational tier, Yara International ASA, BASF SE, and Nutrien Ltd. occupy positions that exemplify divergent strategic anchoring. Yara's Norwegian corporate structure reflects long-standing nitrogen fertilizer heritage extended into complete crop nutrition portfolios. BASF SE represents the German chemical conglomerate archetype leveraging digital farming platforms to anchor premium chelated mineral sales. Nutrien Ltd.'s Canadian corporate form sustains North American distribution dominance through controlled retail networks and in-house agronomy staffing. These three entities collectively illustrate how geographic origin and legacy business structure shape competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| Yara International ASA |
| The Mosaic Company |
| Nutrien Ltd. |
| BASF SE |
| Haifa Group |
| Nouryon |
| ICL Specialty Fertilizers |
| Coromandel International Limited |
| Syngenta AG |
| Others |
Supply Flow & Price Mechanics
Sulfuric acid spot price movements cascade through micronutrient manufacturing economics, compressing margins for sulfate-based formulations while amplifying pricing power for chelated alternatives. Chinese EDTA supply concentration forces European and North American formulators to absorb feedstock volatility or pivot toward biodegradable chelating agents at premium cost positions.
Pricing Analysis
Capacity additions in China's sulfuric acid and phosphate byproduct streams are reshaping price floors for copper sulfate and zinc sulfate formulations. Three-tier pricing structure across premium chelated, standard sulfate, and economy oxide grades stratifies according to bioavailability certification and dissolution performance. Pricing pressure stems from nano-encapsulation pilots in Brazil and the US Corn Belt reducing per-hectare mineral volumes. Smallholder cooperatives in India exhibit highest price sensitivity, while greenhouse operators in Spain and Mexico prioritize dissolution guarantees over unit cost.
Supply Chain Analysis
Return flows of spent chelating agents and packaging materials from European greenhouse operators are creating reverse-logistics cost centers for specialty formulators. Sulfuric acid supply concentrates in China, Morocco, and Russia, while EDTA manufacturing clusters in Shandong Province feed global mineral complex production. Raw material dependencies span phosphate rock byproducts, smelter-derived sulfuric acid, and synthetic chelating agents. Single-source vulnerability to Chinese EDTA supply disruptions constitutes the dominant structural risk. Distribution runs through controlled retail networks in North America, government-mandated soil health programs in India, and precision agriculture platforms in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Micronutrient procurement is shifting toward subscription-based agronomic advisory, rewarding suppliers with integrated digital farming platforms and compressing commodity mineral economics. This late-cycle quality story favors formulators with validated chelate bioavailability and captive precision agriculture capabilities.
For Market Incumbents: Extend backward integration into sulfuric acid and phosphate byproduct streams to defend margin against feedstock volatility. Acquire or partner with biostimulant specialists to compress the boundary between mineral nutrition and plant physiology management. Lock in long-term offtake agreements with Indian wheat flour millers under FSSAI fortification mandates to secure nutritional-grade mineral volumes.
For New Entrants and Emerging Players: Launch via subscription-based agronomic advisory bundled with micronutrient prescriptions to bypass established distribution bottlenecks. Target Sub-Saharan Africa commercial farming corridors in Zambia, Kenya, and Ethiopia where distribution infrastructure remains underdeveloped. Prioritize water-soluble formulations compatible with fertigation systems in Mexico and Turkey's protected cultivation expansion.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale European formulators holding biodegradable chelate validation ahead of REACH authorization deadlines. Long-term viability hinges on regulatory compliance cost absorption capacity and digital platform integration depth. Monitor EU Fertilizing Products Regulation CE-marking enforcement intensity as inflection indicator for premium product substitution rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfuric Acid Supply | Captive phosphate byproduct access insulates margin from smelter output volatility. |
| Biostimulant Partnership or Acquisition | Microbial inoculant convergence opens organic-certified crop segment positioning. |
| Biodegradable Chelate Validation | IDHA and GLDA certification ahead of EDTA REACH deadlines secures EU market access. |
| Precision Agriculture Platform Development | Real-time agronomic algorithms displace transactional sales in North American row-crop markets. |
| Sub-Saharan Africa Distribution Buildout | First-mover logistics investments capture commercial farming expansion in Zambia and Ethiopia. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct segment-level demand estimates. Primary fieldwork engaged fertilizer formulation plant managers, agronomic advisory platform engineers, procurement leads at Brazilian commercial farming cooperatives, and regulatory affairs specialists at European chelating agent manufacturers. Secondary validation drew from EPA fertilizer registration databases, EU Fertilizing Products Regulation CE-marking records, India Soil Health Card Scheme implementation reports, and customs trade data for sulfuric acid and mineral sulfate flows. Bottom-up product-level volume estimates triangulated against top-down macroeconomic agricultural input demand models.
Segment-weighting approaches applied differential growth assumptions across biochemical composition, application channel, physical format, and end-user vertical. Modeled dimensions spanned mineral grade tier, delivery system compatibility, regional regulatory cluster, and precision agriculture adoption intensity. CAGRs derived from historical volume trajectories adjusted for policy intervention impacts and technology substitution elasticities. Forecast inputs incorporated fertigation system penetration curves in protected cultivation markets and nano-encapsulation formulation adoption timelines in large-scale row-crop operations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sulfuric acid supply disruptions or accelerated REACH authorization enforcement. Practitioners should monitor Chinese EDTA export policy shifts, Indian FSSAI fortification mandate expansion, and Brazilian precision agriculture platform consolidation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
Retinyl Linoleate Market
Vitamin Fortified
Prenatal Vitamin Preparation Market
Vitamin Fortified
Encapsulated Vitamin C Market
Vitamin Fortified
Middle East and Africa Food Fortifying Agents Market
Vitamin Fortified
Natural Vitamins Market
Vitamin Fortified
Food Grade Vitamin C Market
Vitamin Fortified
Ready-To-Use Therapeutic Food and Supplementary Food (RUTF and RUSF) Market
Vitamin Fortified
Food Grade Vitamin B Market
Vitamin Fortified
South America Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Calcium Fortified Juice Market
Vitamin Fortified
Vitamin D3 Oil Market
Vitamin Fortified
Fortified Yeast Market
Vitamin Fortified
Vitamin C Market
Vitamin Fortified
Multivitamin Gummies Market
Vitamin Fortified
Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market