
 Specialty Cultures Market | 2026-2036
Specialty Cultures Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Cultures Market Analytics
Pharmaceutical-grade culture specifications are redrawing competitive boundaries in specialty cultures. Chr. Hansen Holding A/S leverages decades of microbial strain development to dominate dairy and probiotic culture supply. DSM-Firmenich AG anchors its position through integrated biotechnology platforms spanning enzymes to precision fermentation. Novonesis A/S differentiates via recombinant protein expression systems optimized for industrial biomanufacturing scale.
Specialty cultures comprise live microorganisms, isolated cells, or defined cell lines cultivated under controlled conditions to achieve specific metabolic, enzymatic, or therapeutic outputs, with critical parameters including viability density, passage stability, and sterility assurance levels. These cultures serve as foundational inputs for fermented food matrices, biopharmaceutical production, and industrial biocatalysis. Bacterial cultures command the largest volume share in food production applications where strain-specific acidification profiles determine product identity. Cell cultures generate the fastest value expansion within pharmaceutical biotechnology, driven by perfusion bioreactor adoption and serum-free media formulation advances. Yeast cultures occupy a mature margin pool in brewing and bioethanol, though engineered strains now penetrate recombinant protein markets.
FDA biologics license requirements and EMA good manufacturing practice standards for cell substrates enforce rigorous documentation of culture origin, genetic stability, and adventitious agent testing. ISO 20391-1 guidelines for cell counting and the International Council for Harmonisation Q5D document on cell substrate derivation further constrain supplier qualification pathways. Stakeholders must monitor emerging gene-edited culture classifications and evolving pharmacopeial standards for continuous bioprocessing substrates.
Market Dynamics
Serum-free media formulation is compressing production timelines across mammalian cell culture workflows while simultaneously raising technical qualification barriers for incumbent suppliers.
Growth Catalysts
- FDA-EMA Biosimilar Pathway Harmonization:Aligned approval frameworks accelerate culture-derived therapeutic commercialization timelines across transatlantic markets.
- Perfusion Bioreactor Adoption:Continuous processing architectures in biopharmaceutical manufacturing maximize viable cell density and volumetric productivity.
- Precision Fermentation Platforms:Industrial biotechnology firms deploy engineered microbial chassis for recombinant protein and bioactive compound synthesis.
Market Restraints
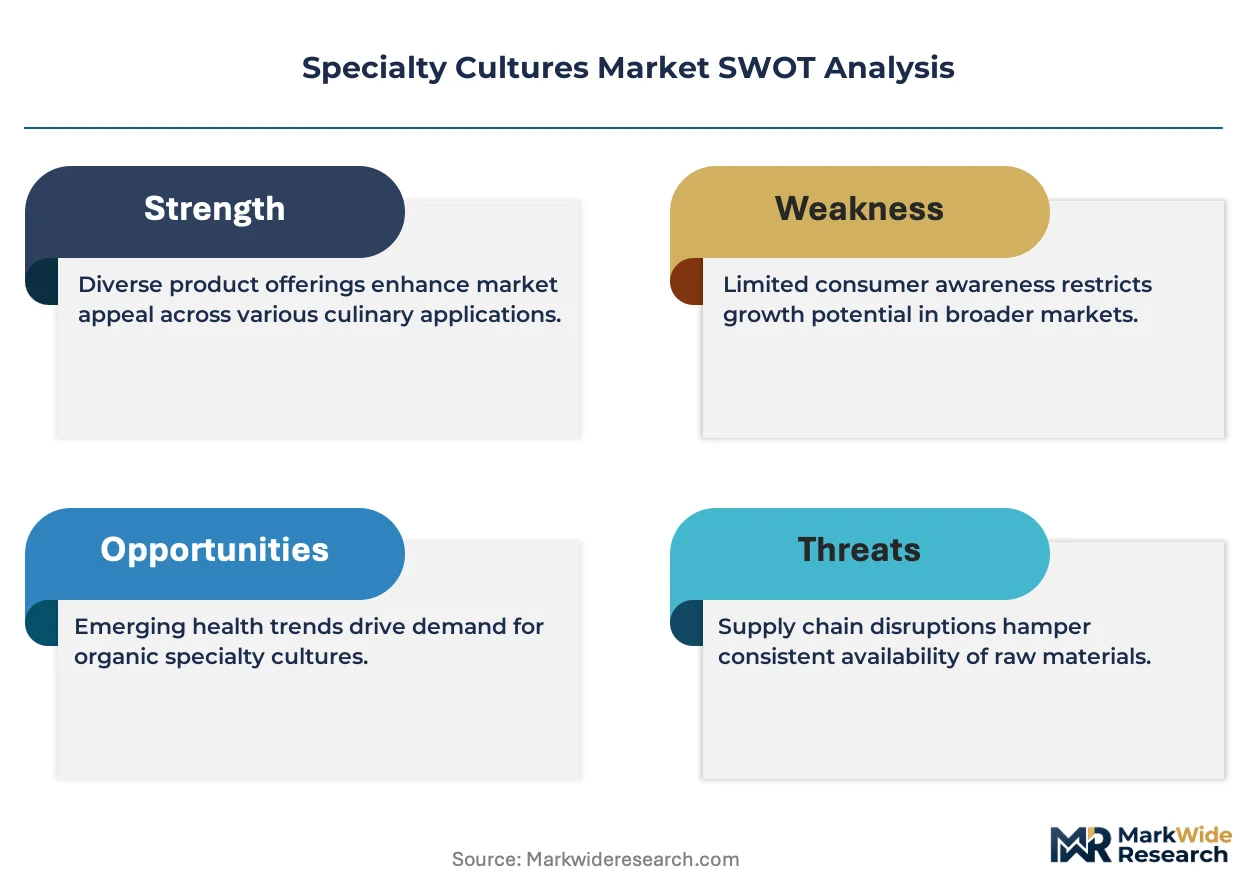
- Fetal Bovine Serum Price Volatility:Supply disruptions in South American abattoir sourcing destabilize cost structures for traditional serum-dependent culture workflows.
- Genetic Stability Documentation Burden:ICH Q5D compliance requirements for cell substrate characterization extend qualification timelines by 12-18 months.
- Chemically Defined Media Substitution:Fully synthetic formulations erode margins for serum-based product portfolios despite performance gaps in sensitive cell lines.
Strategic Opportunities
- Continuous Bioprocessing Substrate Standards:Pharmacopeial monograph development for perfusion-compatible culture systems creates first-mover certification advantages.
- Gene-Edited Culture Classifications:Emerging regulatory frameworks for CRISPR-modified cell lines open differentiated service offerings in contract development.
- Single-Use Bioreactor Integration:Disposable vessel technologies reduce cross-contamination risk and facility capital intensity for multi-product facilities.
Industry Challenges
- Cell Line Development Expertise Scarcity:Limited pools of scientists proficient in clonal selection and stability testing constrain expansion timelines.
- Adventitious Agent Testing Bottlenecks:Extended PCR and in-vitro assay queues delay batch release for GMP-grade culture products.
- Legacy Equipment Retrofit Complexity:Stainless steel infrastructure conversion to single-use architectures disrupts validated manufacturing processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Cultures Market |
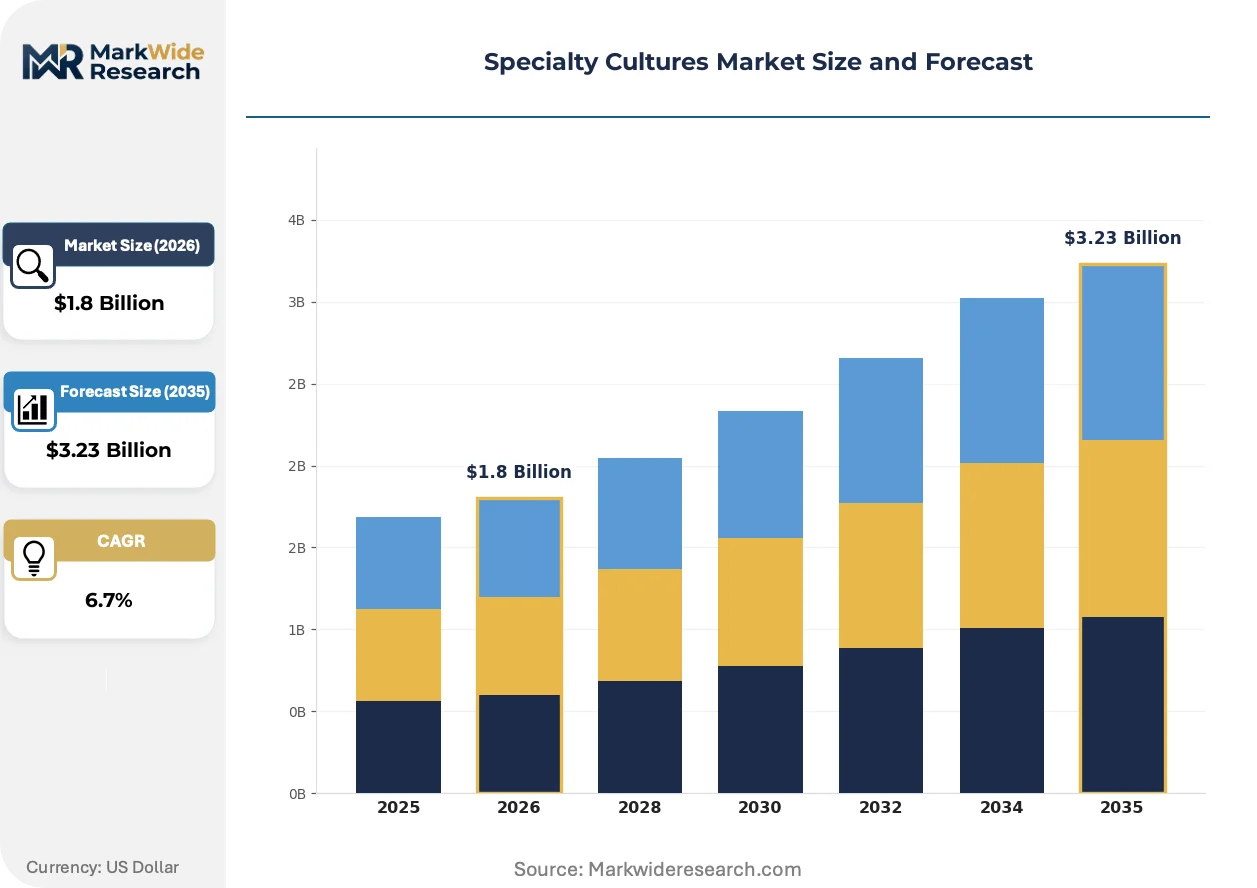
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial Cultures, Fungal Cultures, Cell Cultures, Yeast Cultures Application: Food Production, Biotechnology, Pharmaceuticals, Research End User: Laboratories, Healthcare Institutions, Academic Institutions, Agricultural Companies Distribution Channel: Online Sales, Direct Sales, Distributors, Retail |
| Companies Covered | Chr. Hansen Holding A/S, DuPont Nutrition & Health, DSM-Firmenich AG, Lallemand Inc., Kerry Group plc, Cargill, ADM, Novonesis A/S, Sacco System, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Cultures Market Evolving Landscape
Automation and artificial intelligence are penetrating culture process development, compressing experimental design cycles while demanding new data infrastructure investments from established suppliers.
Automated high-content screening platforms are displacing manual microscopy-based viability assessment in cell line development workflows. Biopharmaceutical process development groups at contract manufacturing organizations deploy these systems for 10,000-clone-per-week throughput. This capability compression is displacing mid-tier analytical service providers unable to amortize capital intensity across limited client bases.
EMA's revised Annex 1 guidelines on sterile manufacturing impose environmental monitoring requirements for open culture operations. The regulation mandates continuous viable particle detection in Grade A/B zones, forcing facility redesign investments. Aseptic processing suites in European biologics plants are responding through isolator technology adoption and restricted access barrier system upgrades.
Contract research organizations now bundle cell banking with downstream process development under unified master service agreements. This integration disintermediates discrete media suppliers and analytical testing houses. The consolidated procurement pattern is most visible among mid-cap biotech firms in Boston and San Diego clusters seeking single-source accountability for IND-enabling packages.
Specialty Cultures Market Segmentation
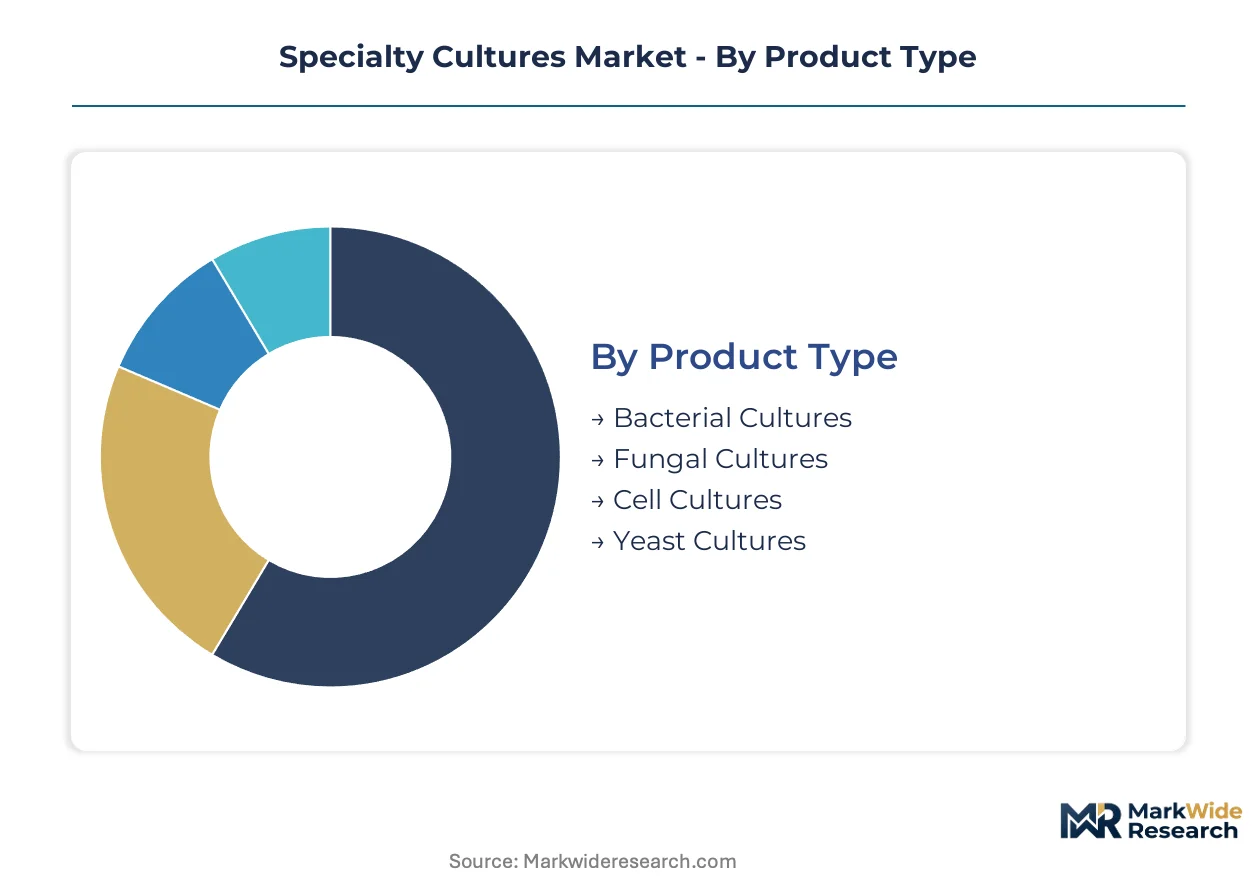
Specialty cultures traverse highly differentiated procurement pathways where technical specifications, regulatory burden, and volume scale determine channel economics. Segment boundaries in this market reflect competing pressures between standardized commodity supply and bespoke development services.
Product Type:
Bacterial cultures and cell cultures flow predominantly through direct technical sales channels requiring strain documentation, while yeast and fungal cultures move through distributor networks serving volume food and beverage accounts.
- Bacterial Cultures:Defined microbial strains selected for specific acidification, proteolytic, or bacteriocin production profiles. Demand concentrates in dairy fermentation facilities across Denmark and the Netherlands where PDO cheese specifications mandate strain traceability. Supply contracts increasingly bundle genomic stability testing with master cell banking services.
- Cell Cultures:Mammalian, insect, or stem cell lines maintained under serum-free or chemically defined conditions. Expansion concentrates in Boston and San Diego biotech clusters where perfusion bioreactor adoption drives custom media formulation demand. FDA master file documentation requirements extend qualification timelines for new suppliers.
- Fungal Cultures:Filamentous fungi and mushroom mycelia cultivated for enzyme production or food matrices. Agricultural biotechnology firms in the Netherlands deploy these chassis for biocontrol agent manufacturing.
- Yeast Cultures:Saccharomyces and non-conventional yeasts engineered for bioethanol, brewing, or recombinant protein expression. Industrial biotechnology accounts in Brazil and the United States absorb volume through long-term offtake agreements.
Bacterial cultures dominate installed base across fermented food applications. Cell cultures are where expansion concentrates as biopharmaceutical manufacturing scales toward continuous processing architectures.
Application:
Cost tier stratification separates premium pharmaceutical-grade specifications from commodity food fermentation requirements, with biotechnology and research occupying intermediate value bands.
- Food Production:Starter cultures for dairy, meat, and beverage fermentation where strain-specific metabolic fingerprints define product identity. European dairy cooperatives in France and Italy command specialized thermophilic and mesophilic blends with protected designation of origin compliance documentation.
- Pharmaceuticals:GMP-grade cell substrates and viral production systems subject to ICH Q5D genetic stability requirements. Contract development organizations in Singapore and Switzerland now bundle cell line development with downstream process optimization under unified service agreements.
- Biotechnology:Industrial enzyme production and biocatalysis applications employing engineered microbial chassis. Precision fermentation platforms in Denmark deploy fungal and yeast systems for recombinant protein manufacturing.
- Research:Non-GMP cell lines and reference strains for academic and contract research applications. Procurement concentrates through academic purchasing consortia with multi-year framework agreements.
Food production commands volume leadership. Pharmaceuticals is climbing the fastest as biosimilar pathway harmonization accelerates culture-derived therapeutic commercialization.
End User:
Customer type determines service intensity, with healthcare institutions demanding integrated quality systems and agricultural companies prioritizing cost-optimized bulk supply.
- Laboratories:Quality control and analytical testing facilities requiring certified reference strains with full traceability documentation. Clinical diagnostic laboratories in Germany and Japan absorb expanding volumes of molecular assay controls.
- Healthcare Institutions:Hospital-based cell therapy manufacturing and blood bank operations requiring GMP-compliant cell processing. Cell and gene therapy centers in the United Kingdom and Australia are investing in closed-system culture technologies.
- Academic Institutions:Research universities and teaching hospitals with fragmented procurement across departmental purchasing systems. Funding agency requirements for open-access strain deposition are reshaping supplier engagement models.
- Agricultural Companies:Seed treatment, silage inoculant, and biocontrol manufacturers seeking high-cell-density formulations with extended shelf stability. Brazilian and Argentinian agritech firms drive volume demand for rhizobial and silage-specific blends.
Healthcare institutions dominate value concentration. Agricultural companies are gaining share fastest as biological crop input substitution accelerates.
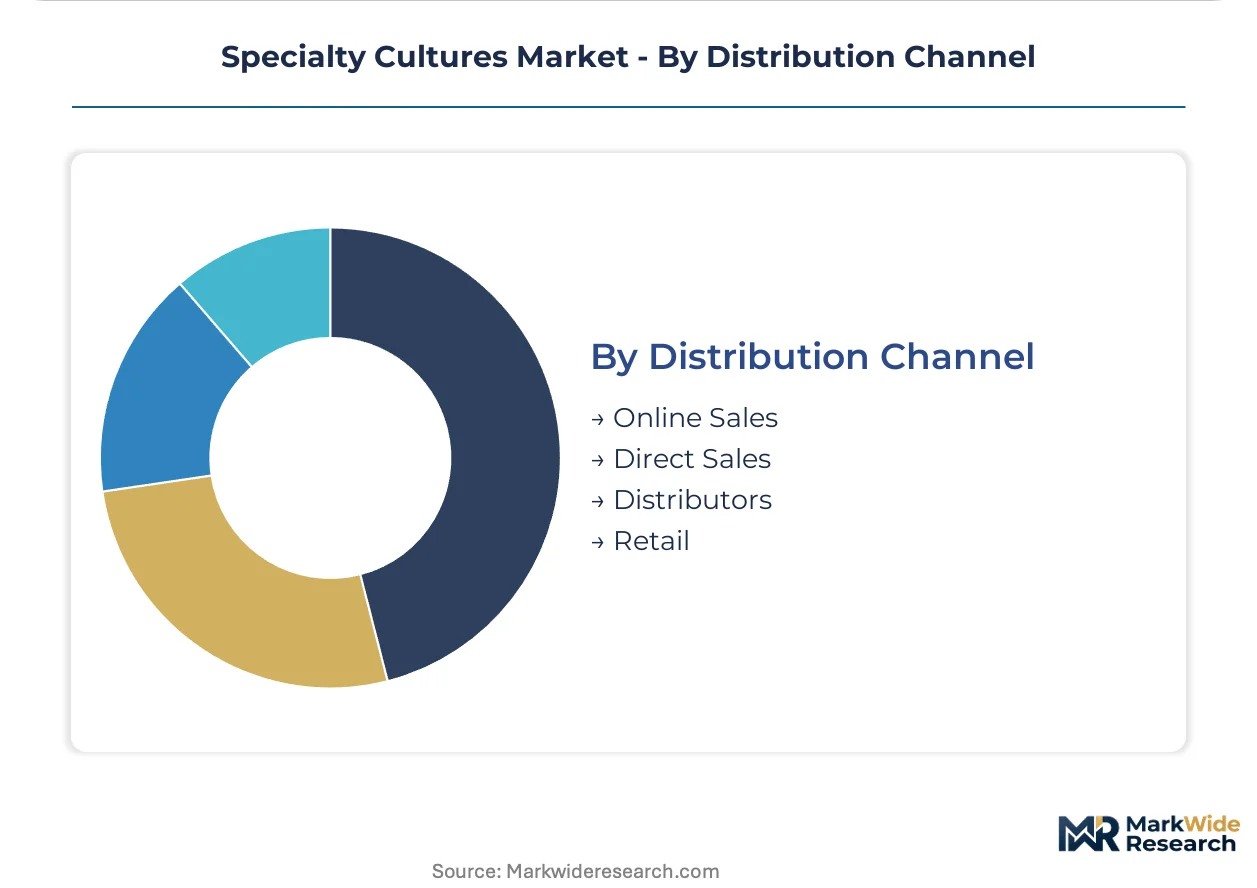
Distribution Channel:
Geography and margin structure shape channel selection, with direct sales penetrating high-specification accounts and online platforms capturing standardized research reagents.
- Direct Sales:Technical field teams engaging pharmaceutical and large food manufacturing accounts with custom formulation development. Chr. Hansen and DSM-Firmenich maintain dedicated technical service organizations for dairy and probiotic culture specification.
- Distributors:Regional inventory and logistics partners serving mid-tier food and agricultural accounts with consolidated product portfolios. European life science distributors have expanded cell culture media warehousing to support biotech cluster proximity.
- Online Sales:E-commerce platforms for catalog research reagents and standard bacterial strains with immediate availability requirements. Academic purchasing systems increasingly route routine procurement through punch-out catalog integration.
- Retail:Limited presence for home fermentation and artisanal production cultures through specialty food channels. Direct-to-consumer probiotic culture kits represent an emerging micro-segment.
Direct sales dominates pharmaceutical and large food account penetration. Online sales is expanding most quickly as research reagent procurement digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chr. Hansen maintains production facilities in Denmark that supply thermophilic cultures to European dairy cooperatives. DSM-Firmenich operates integrated biotechnology platforms across Switzerland and the Netherlands serving pharmaceutical and food fermentation accounts.
United States
Boston and San Diego biotech clusters command specialized media and custom culture services for monoclonal antibody production. FDA biosimilar pathway harmonization with EMA compresses approval timelines for culture-derived therapeutics. Perfusion bioreactor adoption in Massachusetts and California facilities drives demand for serum-free media formulations.
Germany
Clinical diagnostic laboratories in Munich and Heidelberg absorb expanding volumes of molecular assay controls and certified reference strains. EMA revised Annex 1 guidelines on sterile manufacturing impose environmental monitoring requirements for open culture operations. Bavarian biologics plants respond through isolator technology adoption and restricted access barrier system upgrades.
Denmark
PDO cheese specifications mandate strain traceability from dairy cooperatives across Jutland and Zealand. Precision fermentation platforms in Copenhagen deploy engineered microbial chassis for recombinant protein manufacturing. Chr. Hansen leverages decades of microbial strain development to dominate regional dairy and probiotic culture supply.
Switzerland
Contract development organizations in Basel and Zurich bundle cell banking with downstream process development under unified master service agreements. Swissmedic enforces rigorous documentation of culture origin, genetic stability, and adventitious agent testing for GMP-grade products. The country's pharmaceutical manufacturing base demands integrated quality systems from culture suppliers.
Singapore
Contract development organizations now bundle cell line development with downstream process optimization under unified service agreements. The country's national pharmaceutical regulator aligns with ICH Q5D compliance requirements for cell substrate characterization. Biopharmaceutical manufacturing investments in Tuas Biomedical Park create demand for perfusion-compatible culture systems.
Specialty Cultures Market Competitive Landscape
Concentration sits with integrated biotechnology conglomerates possessing decades of strain development expertise. The market structure reflects a tiered competitive environment where specialized culture suppliers compete against diversified life science platforms. Three archetypes dominate: heritage microbial culture houses, precision fermentation technology providers, and contract development service integrators. M&A activity consolidates strain portfolios while strategic partnerships accelerate access to gene-edited culture classifications.
Within the heritage culture tier, Chr. Hansen Holding A/S and Lallemand Inc. exemplify decades-long specialization in dairy and probiotic strain development. DSM-Firmenich AG occupies a position bridging food fermentation and pharmaceutical biotechnology through integrated enzyme and precision fermentation capabilities. Novonesis A/S represents the industrial biotechnology vector with recombinant protein expression systems optimized for biomanufacturing scale.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| DuPont Nutrition & Health |
| DSM-Firmenich AG |
| Lallemand Inc. |
| Kerry Group plc |
| Cargill |
| ADM |
| Novonesis A/S |
| Sacco System |
| Others |
Value Network & Pricing Analysis
FDA biologics license requirements and EMA good manufacturing practice standards simultaneously gate supply qualification and stratify price tiers across pharmaceutical-grade culture markets. These regulatory frameworks enforce documentation burdens that compress margins for non-compliant suppliers while enabling certified incumbents to command sustained premiums.
Pricing Analysis
ICH Q5D compliance requirements dictate the pricing tier structure across cell substrate markets. Three-tier pricing separates GMP-grade certified cultures from research-grade and food-grade alternatives. Price differentiation rests on genetic stability documentation depth and serum-free formulation complexity. Cost compression in research-grade segments is intensifying because academic consortia consolidate procurement through framework agreements. Agricultural buyers exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize qualification reliability over unit cost.
Supply Chain Analysis
Fetal bovine serum sourcing from South American abattoirs constitutes a critical chokepoint for traditional culture workflows. Manufacturing gravity centers on Denmark, Switzerland, and the United States for heritage strain development and precision fermentation platforms. Raw material dependencies span defined media components, recombinant growth factors, and cryopreservation agents. Single-source vulnerability concentrates in South American serum supply chains subject to veterinary health restrictions. Distribution runs through direct technical sales for pharmaceutical accounts and regional distributors for agricultural volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities proliferate as continuous bioprocessing substrate standards fragment procurement specifications across perfusion-compatible and batch-compatible culture systems. This demand-side shift creates specialized niches beyond incumbent conglomerate coverage.
For Market Incumbents: Shield master cell banking margins through backward integration into genetic stability testing services. Incumbents should deepen serum-free media formulation capabilities to offset fetal bovine serum price volatility. The priority lever centers on certification investment for emerging pharmacopeial monographs on perfusion-compatible substrates. For New Entrants and Emerging Players: Gene-edited culture classification services represent a service-layer gap where incumbents under-serve contract development demand. New entrants should penetrate mid-cap biotech clusters in Boston and San Diego with bundled cell banking and analytical testing offerings. The most penetrable angle combines rapid master file documentation with flexible batch sizing for IND-enabling packages. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across single-use bioreactor-integrated culture facilities. Long-term viability favors contract research organizations possessing integrated cell line development and downstream process capabilities. Acquisition targets should demonstrate proficiency in CRISPR-modified cell line characterization. The signal to watch is EMA pharmacopeial monograph publication timelines for continuous bioprocessing substrates.| Strategic Initiative | Industry Significance |
|---|---|
| Master Cell Banking Service Expansion | Captures recurring revenue from FDA biologics license documentation requirements. |
| Serum-Free Media Formulation Investment | Insulates margins from South American abattoir supply disruptions. |
| Precision Fermentation Platform Deployment | Enables recombinant protein manufacturing scale at DSM-Firmenich Copenhagen facilities. |
| Single-Use Bioreactor Integration | Reduces cross-contamination risk for multi-product facilities in Tuas Biomedical Park. |
| Gene-Edited Culture Classification Development | Opens differentiated service offerings as CRISPR regulatory frameworks mature. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with bioprocess development directors, regulatory affairs specialists, and cell line development scientists; and secondary validation through FDA master file databases, EMA submission records, and ISO 20391-1 technical documentation. Primary fieldwork encompassed contract manufacturing organizations in Singapore and Switzerland, heritage culture suppliers in Denmark, and biotech clusters in Massachusetts and California. Secondary sources included customs trade data for culture media imports, SEC filings for publicly traded biotechnology conglomerates, and pharmacopeial draft monographs. Bottom-up segment sizing triangulated against top-down market consolidation estimates.
Across the projection horizon, the analytical framework modeled value and volume trajectories through disaggregated segmentation across product type, application tier, end-user category, and distribution channel. Segmentation dimensions incorporated pharmaceutical-grade certification status, food-grade PDO compliance requirements, and research-grade academic purchasing patterns. CAGRs derived from historical growth rate analysis adjusted for regulatory harmonization impacts and technology substitution curves. Industry-specific inputs comprised perfusion bioreactor adoption rates, serum-free media penetration by cell line sensitivity, and gene-edited culture regulatory classification timelines.
Forecasts assume regulatory continuity in FDA and EMA biosimilar pathway harmonization; material policy shifts would require re-modeling across transatlantic approval frameworks. Specific risk factors include adventitious agent testing protocol changes, pharmacopeial standard revisions for continuous processing, and gene-edited organism classification regime updates. Practitioners should keep alternative scenarios live as ICH Q5D interpretation evolves across national competent authorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Molecular Microbiology Market
Industrial Microbiology
Microbial Lipase Market
Industrial Microbiology
Salinomycin Market
Industrial Microbiology
Global Microbial Testing Market
Industrial Microbiology
Lactobacillus Strains Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Global Starter Culture Market
Industrial Microbiology
Global Microbial Identification Market
Industrial Microbiology
Microbial Biosurfactants Market
Industrial Microbiology
Benzoate-Free Enzymes Market
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Global Bacterial Cell Culture Market
Industrial Microbiology
Global Microbiome Therapeutics Market
Industrial Microbiology
Automated Microbial Detection Systems Market
Industrial Microbiology
Freeze-Dried Microbial Food Culture Market
Industrial Microbiology
Mycoplasma Plate Antigens Market