
 Azotobacter Based Biofertilizer Market | 2026-2036
Azotobacter Based Biofertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Azotobacter Based Biofertilizer Market Outlook
A capital-intensity divergence between integrated fermentation facilities and toll-manufacturing dependent operators is reorganizing competitive tiers in the Azotobacter based biofertilizer sector. Novozymes leverages proprietary strain libraries and in-house fermentation capacity to command premium positioning across European agricultural markets. IFFCO anchors its presence through India's cooperative distribution network, sustaining volume throughput across liquid and granular formulations. Gujarat State Fertilizers & Chemicals competes on backward integration into ammonia-adjacent infrastructure, occupying a cost-advantaged position in western Indian supply corridors.
Azotobacter based biofertilizer comprises live cultures of nitrogen-fixing Azotobacter species, typically formulated at minimum viable counts between 10^7 and 10^8 CFU per gram or milliliter, with cell protectants such as peat, lignite, or polymer carriers ensuring shelf stability across ambient storage conditions. Its primary commercial purpose is biological nitrogen fixation in non-leguminous crops, reducing dependency on urea application while improving soil microbial biomass carbon. Liquid biofertilizer leads volume share due to compatibility with drip irrigation and foliar spraying systems, though granular formats retain margin advantages in subsurface application for deep-rooted cereals. The horticulture end use segment represents the fastest-expanding demand pool, driven by organic certification requirements in protected cultivation across Mediterranean and East Asian clusters. Wholesale distributors still control the dominant share of value realization, but agricultural supply stores are deepening their role in last-mile technical advisory.
India's Fertilizer Control Order mandates minimum viable count standards and registration through state agricultural departments, creating compliance barriers for unregistered imports. The EU Fertilizing Products Regulation establishes CE-marking requirements for biostimulant and microbiological fertilizer categories, shaping product development priorities for exporters targeting European horticulture. The USDA BioPreferred program and state-level organic certification frameworks in California and Iowa influence procurement specifications among large-scale row-crop operators. Stakeholders must monitor evolving strain registration protocols and carbon credit eligibility rules for biological inputs, as these mechanisms will determine which product formats achieve scalable adoption in subsidy-dependent markets.
Market Dynamics
Strain registration protocols and carbon credit eligibility rules are reconfiguring which product formats achieve scalable adoption in subsidy-dependent agricultural markets, forcing manufacturers to prioritize compliance infrastructure over pure production scale.
Growth Catalysts
- USDA BioPreferred program:Federal procurement preference for certified bio-based products accelerates farmer transition from synthetic nitrogen in US row-crop operations.
- Drip irrigation compatibility:Liquid formulation advances align with precision agriculture expansion across Mediterranean horticulture clusters.
- EU Fertilizing Products Regulation:CE-marking requirements for microbiological fertilizers create formal demand channels for registered Azotobacter inoculants.
Market Restraints
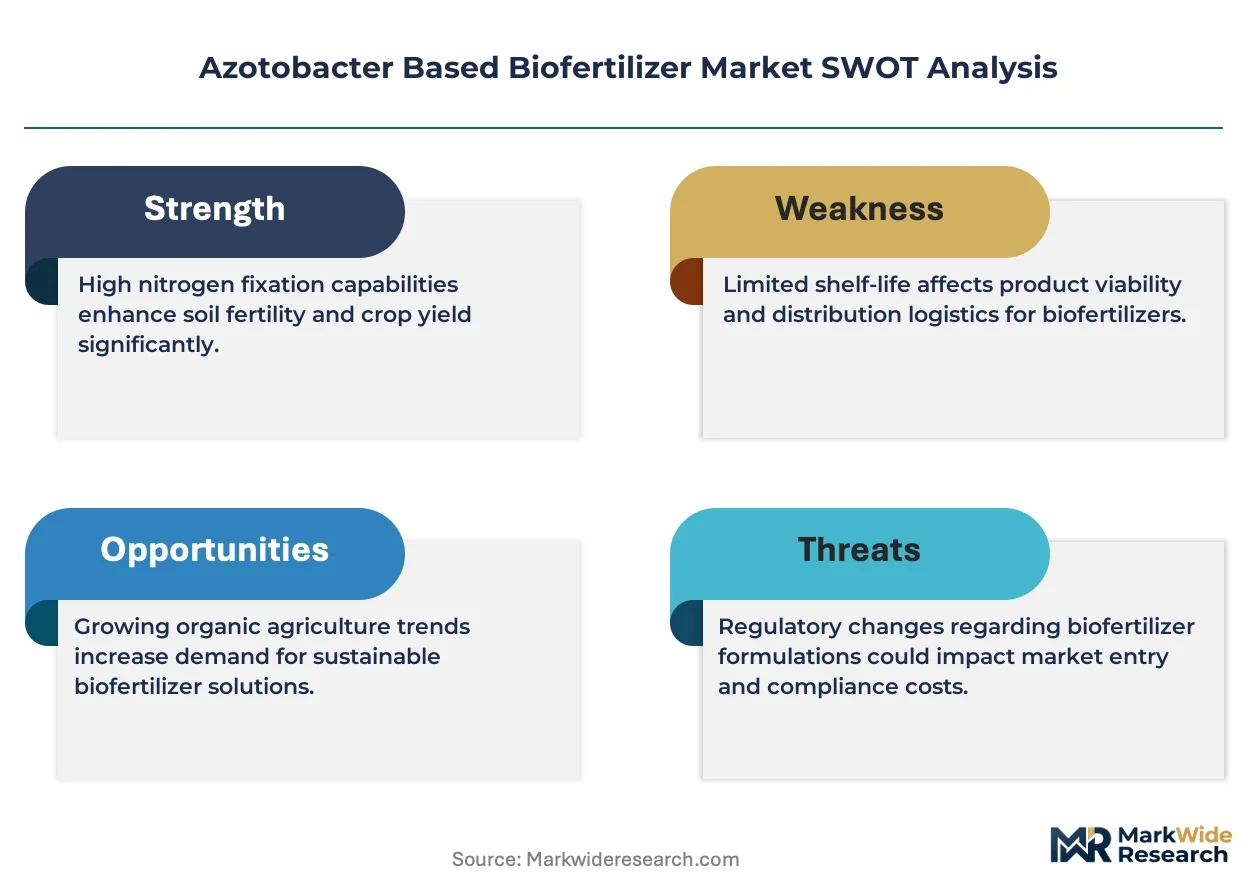
- Peat and lignite carrier costs:Cell protectant input volatility compresses margins for formulations requiring extended ambient shelf stability.
- State-level registration fragmentation:India's Fertilizer Control Order mandates separate state agricultural department approvals, multiplying compliance overhead.
- Synthetic nitrogen price cycles:Urea subsidy fluctuations in major wheat-rice systems create unpredictable substitution economics for biological alternatives.
Strategic Opportunities
- Protected cultivation in East Asia:Organic certification requirements in greenhouse vegetable systems open dedicated procurement channels for granular Azotobacter formulations.
- Carbon credit stacking:Biological input eligibility under emerging soil carbon protocols offers revenue layer beyond product sales.
- Agricultural supply store networks:Last-mile technical advisory capacity deepens as wholesale distributor dominance erodes in advisory-intensive horticulture segments.
Industry Challenges
- Strain viability certification timelines:Minimum viable count validation protocols delay product launch cycles by 8-14 months in regulated markets.
- Fermentation capacity scaling:Captive bioreactor investment requirements favor integrated operators over toll-manufacturing dependent entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Azotobacter Based Biofertilizer Market |
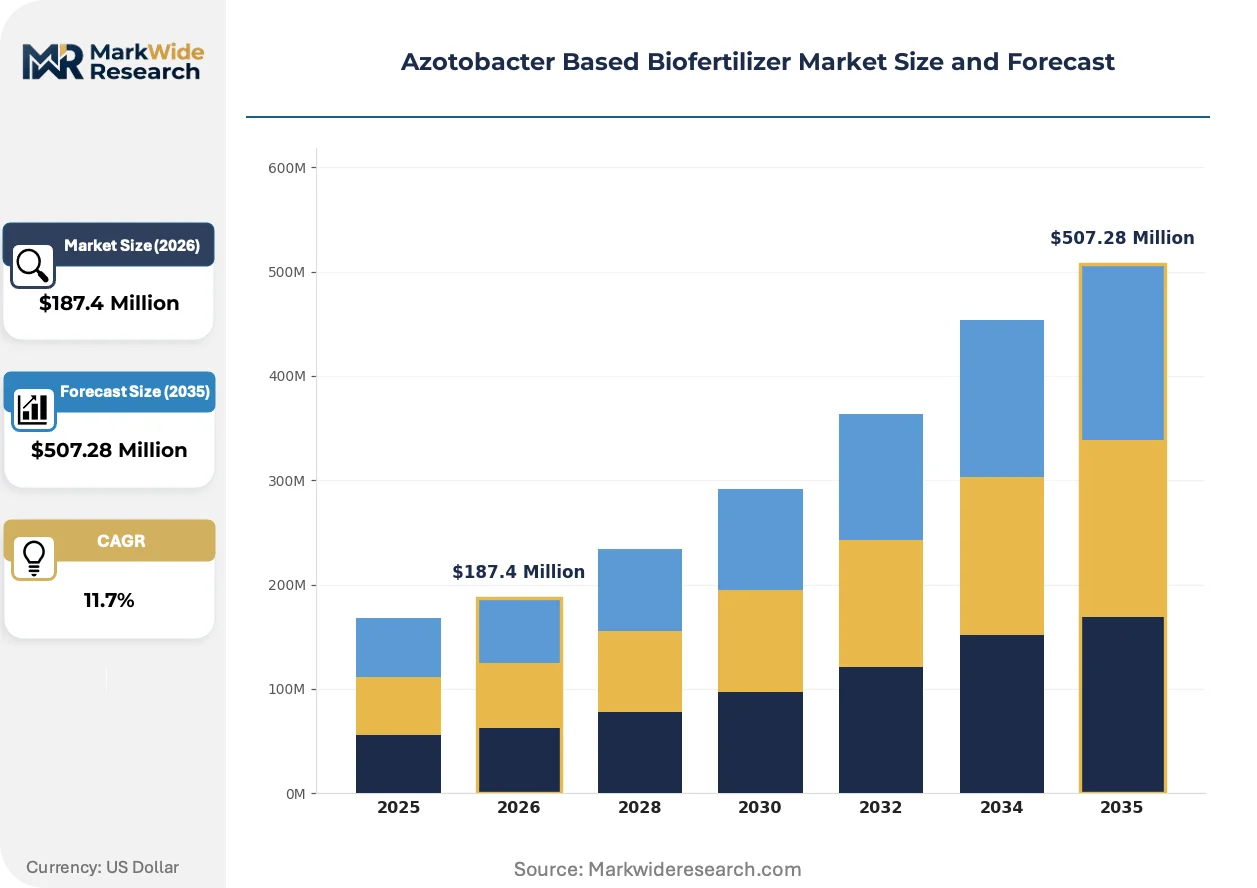
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Biofertilizer, Granular Biofertilizer, Powder Biofertilizer, Pelleted Biofertilizer End Use Industry: Agriculture, Horticulture, Forestry, Landscaping Distribution Channel: Online Sales, Retail Stores, Agricultural Supply Stores, Wholesale Distributors Application: Crops, Vegetables, Fruits, Turf |
| Companies Covered | Rizobacter, National Fertilizers Limited, Gujarat State Fertilizers & Chemicals, Madras Fertilizers Ltd., Rashtriya Chemicals and Fertilizers Ltd., IFFCO, Unisun Agro, Novozymes, Biotech International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Azotobacter Based Biofertilizer Market Strategic Shifts
Product format evolution and regulatory alignment are compressing traditional competitive advantages while opening technical differentiation pathways for manufacturers with integrated strain development capabilities.
Encapsulation technology is bifurcating shelf-stable formulation development. Polymer-based cell immobilization systems extend viable count retention from months to years. European horticulture exporters are adopting these formats for intercontinental shipment. The technology is compressing margin structures for conventional peat-carrier products while enabling premium positioning for climate-stress tolerant strains.
REACH compliance pathways for microbial inoculants are tightening substance characterization requirements. Strain-level toxicological dossier preparation now consumes 18-24 months for EU market entry. Exporters targeting Dutch and Spanish greenhouse clusters are prioritizing pre-registration data generation. This regulatory friction favors established strain libraries with existing characterization assets.
Farmer buying committees in India's cooperative distribution networks are consolidating procurement authority. IFFCO's member societies now negotiate directly with manufacturers for liquid formulation supply. Technical advisory unbundling from product sales is visible across Maharashtra and Gujarat procurement corridors. This channel compression reduces wholesale distributor value capture while elevating manufacturer-direct relationship requirements.
Azotobacter Based Biofertilizer Market Segmentation
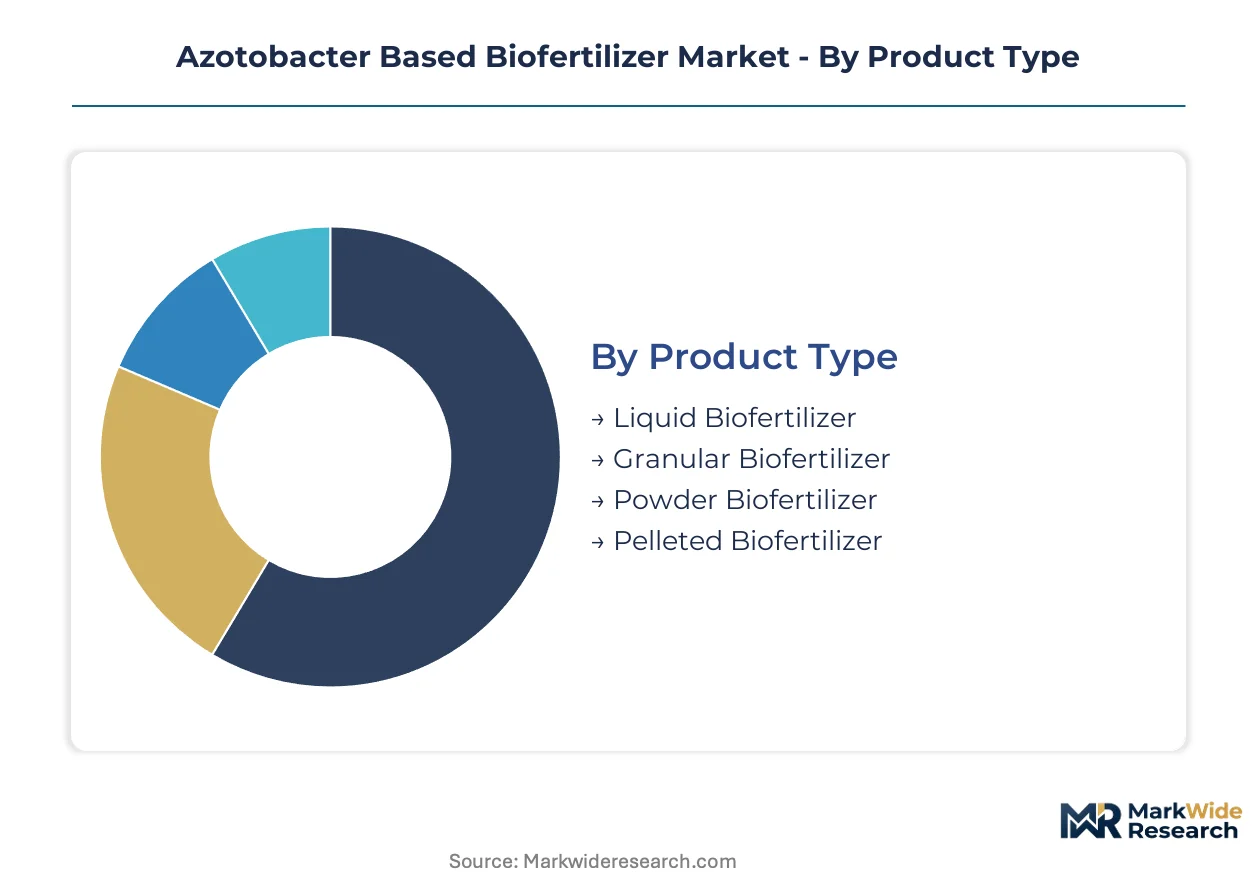
Azotobacter biofertilizer procurement channels reward distinct product formats with divergent margin structures. Manufacturers align formulation development with irrigation infrastructure and certification requirements across end-use segments.
Product Type:
Liquid and granular formulations flow through contrasting channel mixes, with drip-irrigation compatibility driving liquid volumes and subsurface application sustaining granular premiums.
- Liquid Biofertilizer:Suspended cell cultures at 10^7–10^8 CFU/ml enable direct injection into fertigation systems. Demand concentrates in India's wheat-rice belt where state subsidy programs prioritize tank-mixable formats for flood irrigation.
- Granular Biofertilizer:Peat or polymer-encapsulated cells deliver extended shelf stability for deep-rooted cereals. European horticulture clusters absorb premium-priced granular formats for organic greenhouse certification compliance.
- Powder Biofertilizer:Lyophilized preparations suit smallholder seed-treatment applications across Maharashtra and Gujarat cooperative networks.
- Pelleted Biofertilizer:Compressed formulations with synthetic binder systems target mechanized planting equipment in US Great Plains row-crop operations.
Liquid biofertilizer dominates installed base. Granular formats are where expansion concentrates.
End Use Industry:
Margin tiers separate commodity agriculture from certified organic systems, with regulatory intensity determining price realization per hectare treated.
- Agriculture:Broadacre cereal and oilseed production absorbs volume throughput at compressed margins. India's Fertilizer Control Order registration requirements filter supplier participation in state procurement channels.
- Horticulture:Protected cultivation in Mediterranean and East Asian clusters commands premium positioning. EU Fertilizing Products Regulation CE-marking creates formal demand gates for registered inoculants.
- Forestry:Nursery stock and reforestation programs generate episodic demand through government tender mechanisms.
- Landscaping:Municipal and commercial turf maintenance represents emerging demand with sustainability procurement mandates.
Agriculture anchors volume throughput. Horticulture is climbing the fastest.
Distribution Channel:
Channel power is shifting from wholesale aggregation toward last-mile technical advisory, compressing intermediary value capture.
- Wholesale Distributors:Bulk aggregation and logistics optimization serve large-scale cooperative procurement in India and corporate farming operations in the US. Volume concentration enables formulation standardization at reduced unit economics.
- Agricultural Supply Stores:Technical advisory bundling with product sales deepens in horticulture-intensive regions. Maharashtra farmer buying committees now negotiate manufacturer-direct relationships, eroding distributor margins.
- Retail Stores:General agricultural merchandise channels serve smallholder segments with limited technical support requirements.
- Online Sales:Direct-to-farmer platforms emerge for specialty formulations and repeat purchases in digitally penetrated markets.
Wholesale distributors retain installed base dominance. Agricultural supply stores are gaining share fastest.
Application:
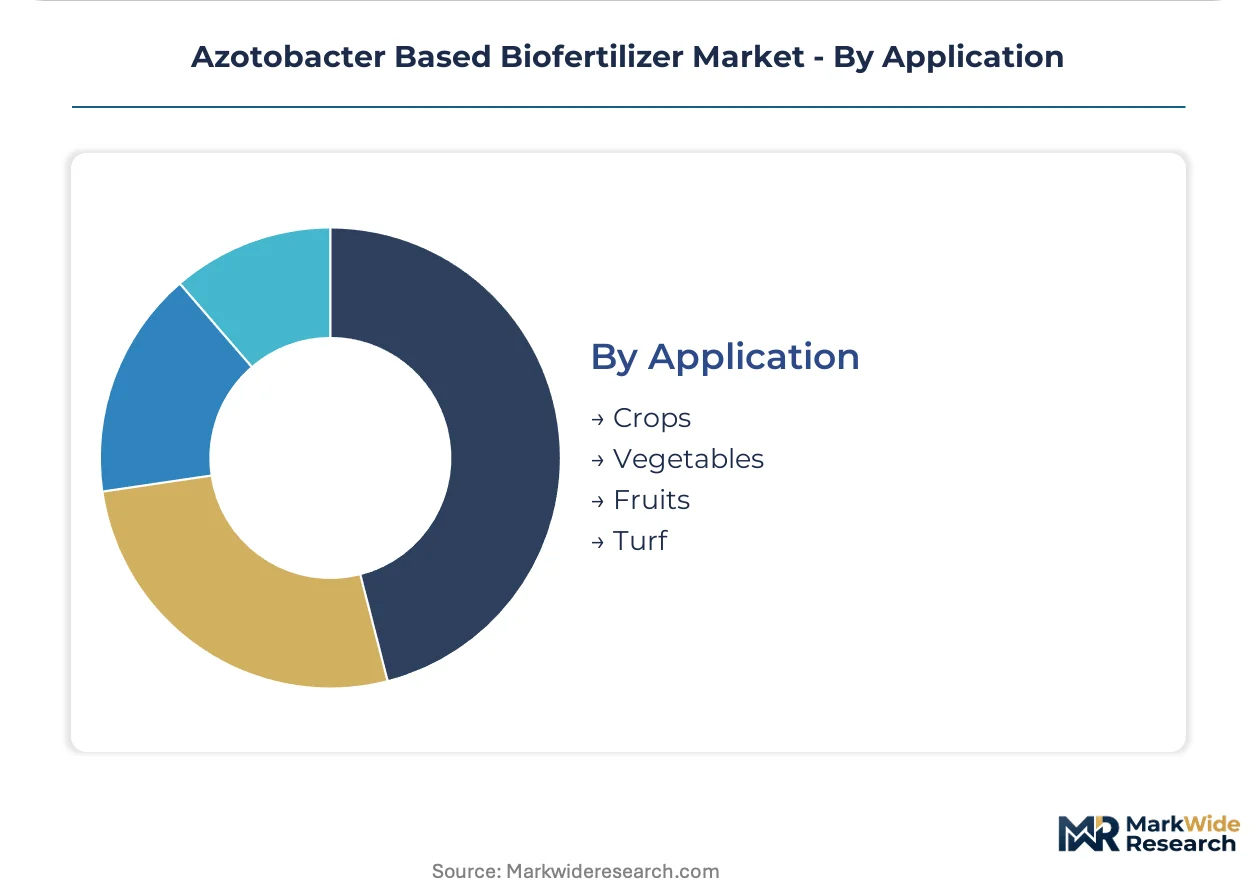
Application specificity determines strain selection and carrier formulation, with root-zone targeting versus foliar delivery creating product-line bifurcation.
- Crops:Cereal grain systems in the US Great Plains and India's Indo-Gangetic plain absorb nitrogen-fixing inoculants as urea substitution. USDA BioPreferred program procurement preferences accelerate farmer transition in certified operations.
- Vegetables:Greenhouse and open-field vegetable production in Spain and the Netherlands drives demand for shelf-stable formats compatible with precision irrigation. Organic certification requirements mandate biological input documentation.
- Fruits:Orchard and vineyard systems in Mediterranean climates apply Azotobacter for soil microbial biomass carbon enhancement.
- Turf:Sports field and golf course maintenance generates specialized demand for rapid-establishment formulations.
Crop applications dominate installed base. Vegetable systems are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of Azotobacter inoculants track regulatory divergence between subsidy-dependent import markets and technology-exporting manufacturing hubs. India's cooperative procurement networks absorb volume throughput while European horticulture clusters command premium positioning through CE-marking compliance.
United States
The USDA BioPreferred program accelerates farmer transition from synthetic nitrogen across Great Plains cereal operations. State-level organic certification frameworks in California and Iowa influence procurement specifications among large-scale row-crop operators. Chicago-area distributors aggregate liquid formulation volumes for flood-irrigation deployment.
India
State subsidy programs for biofertilizer distribution have created dedicated procurement channels in wheat-rice cropping systems. The Fertilizer Control Order mandates minimum viable count standards and registration through state agricultural departments. Maharashtra farmer buying committees now negotiate manufacturer-direct relationships, eroding wholesale distributor margins.
Germany
REACH compliance pathways for microbial inoculants tighten substance characterization requirements for EU market entry. Strain-level toxicological dossier preparation consumes 18-24 months, favoring established strain libraries. Bavarian greenhouse clusters absorb premium-priced granular formats for organic certification compliance.
Spain
Mediterranean horticulture exporters adopt polymer-based cell immobilization systems for intercontinental shipment. The EU Fertilizing Products Regulation establishes formal demand gates for registered Azotobacter inoculants. Almería greenhouse operations drive demand for shelf-stable formats compatible with precision irrigation.
Netherlands
Dutch greenhouse clusters prioritize pre-registration data generation for strain-level toxicological dossiers. CE-marking requirements for microbiological fertilizers shape product development priorities for exporters. Wageningen-area research corridors anchor technical advisory capacity for protected cultivation systems.
Azotobacter Based Biofertilizer Market Competitive Environment
Concentration sits with integrated fermentation operators possessing proprietary strain libraries and captive bioreactor capacity. The vendor base organizes around three strategic archetypes: multinational enzyme specialists with in-house fermentation infrastructure, state-affiliated fertilizer cooperatives leveraging distribution networks, and regional toll-manufacturing dependent formulators. Dominant competitive moves include backward integration into ammonia-adjacent infrastructure and direct-to-farmer relationship building through agricultural supply store networks.
Within the state-affiliated tier, National Fertilizers Limited and Rashtriya Chemicals and Fertilizers Ltd. exemplify cooperative distribution anchoring. Novozymes occupies a position representing multinational enzyme specialists with integrated strain development capabilities. These archetypes illustrate how compliance infrastructure and captive fermentation capacity separate scalable operators from toll-dependent entrants.
| Leading Market Players |
|---|
| Rizobacter |
| National Fertilizers Limited |
| Gujarat State Fertilizers & Chemicals |
| Madras Fertilizers Ltd. |
| Rashtriya Chemicals and Fertilizers Ltd. |
| IFFCO |
| Unisun Agro |
| Novozymes |
| Biotech International |
| Others |
Value Chain & Pricing Dynamics
Fermentation capacity utilization rates above 80 percent in integrated facilities create scale economies that compress unit costs for liquid formulations while elevating price floors for toll-dependent operators. This scale concentration shapes procurement negotiations across India's state subsidy channels and European horticulture clusters, with captive bioreactor operators commanding premium positioning against margin-stressed formulators.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Azotobacter biofertilizer market. Premium tiers attach to CE-marked granular formats with polymer encapsulation for European greenhouse exporters, while standard liquid formulations serve India's cooperative procurement at compressed margins. Cost compression in the economy tier is intensifying because peat and lignite carrier input volatility squeezes toll-manufacturing dependent operators. Smallholder seed-treatment segments in Maharashtra and Gujarat exhibit the highest price sensitivity, whereas Dutch and Spanish protected cultivation operators demonstrate the lowest.
Supply Chain Analysis
Container availability constraints on the Asia-Europe trade lane elevate inbound logistics costs for lyophilized powder shipments to European horticulture clusters. Manufacturing concentration rests on India, Denmark, and Spain, with Indian integrated fermentation facilities feeding domestic subsidy channels and Novozymes' Danish bioreactor network supplying premium European demand. Raw material dependencies center on molasses feedstock for fermentation, peat and lignite carriers for cell protection, and polymer resins for encapsulation systems. Single-source vulnerability in strain library access poses structural risk for toll-manufacturing entrants lacking proprietary development capabilities. Distribution runs through wholesale aggregators in India and agricultural supply store networks in Mediterranean horticulture corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Azotobacter biofertilizer market is emerging from a cyclical trough driven by urea subsidy volatility in wheat-rice systems, with recovery momentum tethered to carbon credit eligibility rules for biological nitrogen fixation.
For Market Incumbents: Secure strain registration dossiers ahead of EU Fertilizing Products Regulation enforcement timelines to defend against REACH-compliant European entrants. Backward integration into ammonia-adjacent infrastructure in western India preserves cost position against Gujarat State Fertilizers & Chemicals' integrated operations. Channel control through direct farmer buying committee relationships in Maharashtra erodes wholesale distributor value capture and locks in volume throughput. For New Entrants and Emerging Players: Differentiate on carbon credit stacking capabilities for soil carbon protocols, creating revenue layers beyond product sales that incumbent formulators lack. Protected cultivation in East Asian greenhouse vegetable systems represents the most penetrable geography, with organic certification requirements opening dedicated procurement channels. A go-to-market angle through agricultural supply store technical advisory partnerships bypasses wholesale distributor concentration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated fermentation operators with proprietary strain libraries and captive bioreactor capacity over toll-manufacturing dependent formulators. Long-term viability over a multi-year horizon rests on compliance infrastructure scale rather than pure production volume. The acquisition target archetype is regional formulators with state-level registration assets in India's Fertilizer Control Order system. The signal to watch is strain viability certification timeline compression as regulatory bodies streamline minimum viable count validation protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Molasses procurement control secures fermentation input cost stability for Indian integrated operators. |
| CE Marking Pathway Investment | REACH-compliant toxicological dossiers unlock Dutch and Spanish greenhouse cluster premium positioning. |
| Direct-to-Farmer Channel Development | Maharashtra buying committee relationships compress wholesale distributor margins and elevate manufacturer value capture. |
| Polymer Encapsulation Scale-Up | Shelf-stable formulation capacity enables intercontinental shipment to Mediterranean horticulture exporters. |
| Carbon Credit Protocol Registration | Soil carbon eligibility creates revenue stacking opportunity beyond product sales in subsidy-dependent markets. |
Study Parameters
A spread of perspectives from fermentation plant managers, state agricultural department registration officials, cooperative procurement leads, and greenhouse technical directors converged on the working assumptions for Azotobacter biofertilizer demand modeling. Primary interviews with these stakeholders combined with secondary validation from India's Fertilizer Control Order registration databases, EU Fertilizing Products Regulation CE-marking records, USDA BioPreferred program certifications, and customs trade data for microbial inoculant flows. Bottom-up strain-level production estimates and top-down subsidy program allocation analysis provided triangulation across the analysis window.
Segmentation dimensions modeled include product format tier, end-use crop system, distribution channel structure, and regional regulatory cluster throughout the forecast period. CAGRs were derived from installed base penetration curves and substitution elasticity estimates for biological nitrogen fixation against synthetic urea. Industry-specific forecast inputs incorporated state subsidy disbursement trajectories in India's wheat-rice belt and organic certification growth rates in Mediterranean protected cultivation.
The analysis sits within stated boundaries; outcomes outside sustained subsidy program continuity, stable strain viability certification timelines, and carbon credit protocol adoption would require recalibration. Forecasts reflect documented assumptions about farmer transition economics and regulatory enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Biochar Machine Market
Bio-Agriculture
West Africa Biostimulants Market
Bio-Agriculture
North America Bio Succinic Acid Market
Bio-Agriculture
India Biomass Market
Bio-Agriculture
Latin America Biostimulants Market
Bio-Agriculture
Biofuel Enzymes Market
Bio-Agriculture
North America Biofertilizer Market
Bio-Agriculture
Fish Vaccines Market
Bio-Agriculture
Europe Biological Organic Fertilizer Market
Bio-Agriculture
United States Biocontrol Agents Market
Bio-Agriculture
Biological Control Market
Bio-Agriculture
Global Biofungicides Market
Bio-Agriculture
South America Biopesticides Market
Bio-Agriculture
Bovine Tuberculosis Diagnosis Market
Bio-Agriculture
Indonesia Biopesticides Market
Bio-Agriculture
Mycelium Market