
 Global Escherichia Coli Testing Market | 2026-2036
Global Escherichia Coli Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Escherichia Coli Testing Market Foresight
The EU Green Deal's farm-to-fork strategy is shifting testing obligations across European food supply chains. bioMérieux SA leverages its chromogenic media portfolio to anchor quality control workflows in dairy processing facilities. Thermo Fisher Scientific Inc. dominates molecular diagnostics through integrated PCR platforms that extend laboratory throughput. IDEXX Laboratories, Inc. specializes in water safety applications where regulatory monitoring frequencies have intensified.
Escherichia coli testing encompasses laboratory and point-of-need analytical methods designed to detect, enumerate, and characterize pathogenic strains of this gram-negative bacterium, typically employing culture-based isolation on selective media, nucleic acid amplification with species-specific primer sets, or immunological capture with labeled antibodies against surface antigens such as O157:H7 lipopolysaccharide. Polymerase chain reaction methods lead the test method segment due to their analytical sensitivity and specificity for virulence gene targets, while biosensor technology within the technology segment represents the fastest-expanding margin pool as semiconductor-based detection platforms reduce time-to-result from days to hours. Clinical specimens and food products concentrate volume demand, though environmental surfaces are gaining share as hospitality and healthcare sectors institutionalize hygiene verification programs.
The FDA enforces zero-tolerance policies for E. coli O157:H7 in ground beef and leafy greens under the Food Safety Modernization Act, compelling processors to validate preventive controls with documented testing protocols. EFSA coordinates harmonized baseline surveys across member states that standardize method performance criteria and reference materials. ISO 16654 provides the internationally recognized reference method for E. coli O157 detection, shaping product development roadmaps for assay manufacturers seeking multi-jurisdictional regulatory acceptance. Stakeholders must monitor evolving whole-genome sequencing requirements from public health agencies that could displace legacy phenotypic confirmation workflows.
Market Dynamics
Whole-genome sequencing mandates from public health agencies are compressing confirmation timelines and forcing assay manufacturers to revalidate legacy phenotypic workflows against genomic benchmarks.
Growth Catalysts
- FSMA Preventive Controls:The FDA's zero-tolerance enforcement for O157:H7 in ground beef and leafy greens compels processors to document pathogen testing within hazard analysis frameworks.
- ISO 16654 Harmonization:International reference method standardization reduces regulatory friction for assay manufacturers seeking multi-jurisdictional product registrations.
- Point-of-Need Biosensors:Semiconductor-based detection platforms reduce time-to-result from days to hours, expanding deployment in dairy processing and water utilities.
Market Restraints
- Reagent Supply Concentration:Polymerase chain reaction primer synthesis depends on concentrated specialty chemical suppliers in Germany and Switzerland, creating single-source vulnerability.
- Capital Intensity of Validation:Clinical laboratories face extended timelines for analytical specificity studies required under FDA 510(k) and IVDR pathways.
- Technical Specificity Limits:Immunological capture assays struggle with serogroup cross-reactivity, necessitating confirmatory culture steps that extend total workflow duration.
Strategic Opportunities
- EU Green Deal Farm-to-Fork:Expanded testing obligations across European dairy and produce supply chains create volume expansion for chromogenic media and molecular platforms.
- Environmental Surface Monitoring:Hospitality and healthcare hygiene verification programs are institutionalizing rapid detection protocols for non-food matrices.
- Multiplex Convergence:Integration of virulence gene screening with Salmonella and Listeria detection on single PCR panels reduces per-sample operational cost.
Industry Challenges
- Genomic Data Integration:Public health laboratories lack standardized pipelines for comparing isolate sequences against PulseNet databases, delaying outbreak attribution.
- Cross-Training Requirements:Point-of-need deployment demands personnel competent in both microbiological technique and instrument maintenance, constraining workforce scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Escherichia Coli Testing Market |
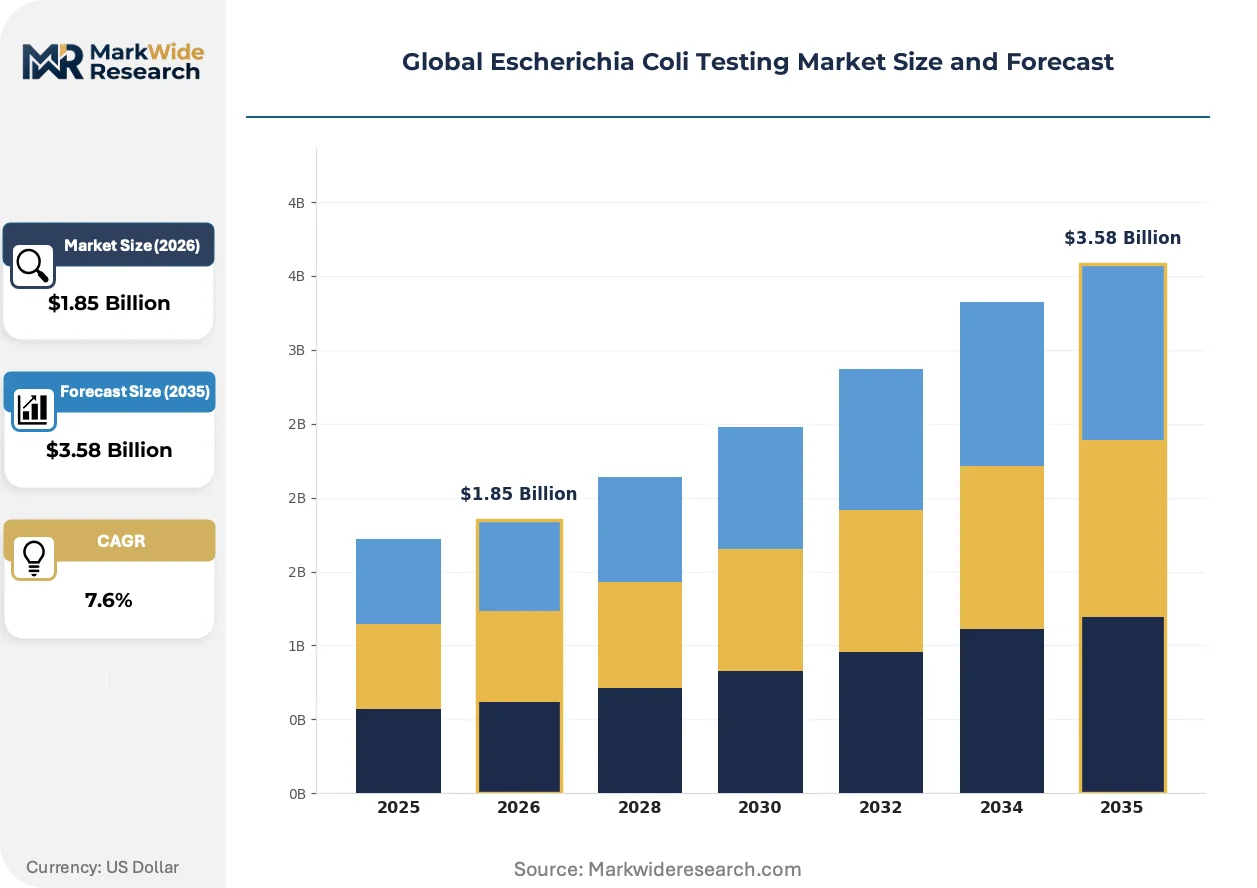
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.58 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Method: Polymerase Chain Reaction, Enzyme-Linked Immunosorbent Assay, Chromogenic Media, Fluorescence In Situ Hybridization, Membrane Filtration Sample Type: Water, Food Products, Clinical Specimens, Environmental Surfaces, Dairy Samples End User: Diagnostic Laboratories, Food Safety Agencies, Research Institutes, Quality Control Units, Public Health Departments Technology: Immunoassays, Biosensors, Microarray, Chromatography, Molecular Diagnostics |
| Companies Covered | bioMérieux SA, Thermo Fisher Scientific Inc., IDEXX Laboratories, Inc., QIAGEN N.V., Bio-Rad Laboratories, Inc., Becton, Dickinson and Company, Neogen Corporation, Meridian Bioscience Inc., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Escherichia Coli Testing Market Shifts & Advancements
Detection platforms are converging around reduced time-to-result as the primary competitive vector, with semiconductor biosensors and automated nucleic acid extraction systems compressing laboratory workflows.
Digital microfluidic cartridges are unifying sample preparation, amplification, and detection within single-use consumables. Regional hospital laboratories in Japan and Germany are adopting these systems to reduce dependence on centralized reference facilities. This integration is unifying previously fragmented workflow steps into continuous processing that eliminates manual transfer errors.
EFSA baseline survey harmonization is standardizing method performance criteria across member states. Assay manufacturers must now demonstrate equivalent sensitivity to ISO 16654 reference methods for product registration acceptance. Dairy processors in France and the Netherlands are responding by consolidating supplier relationships with vendors holding multi-country validation packages.
Buyers in the United States are compressing vendor qualification cycles as FSMA enforcement intensifies. Third-party certification from AOAC International is displacing in-house validation studies for many mid-sized food processors. This preference shift is most visible in the ready-to-eat salad sector, where private label brands demand documented testing protocols from contract manufacturers.
Global Escherichia Coli Testing Market Segmentation
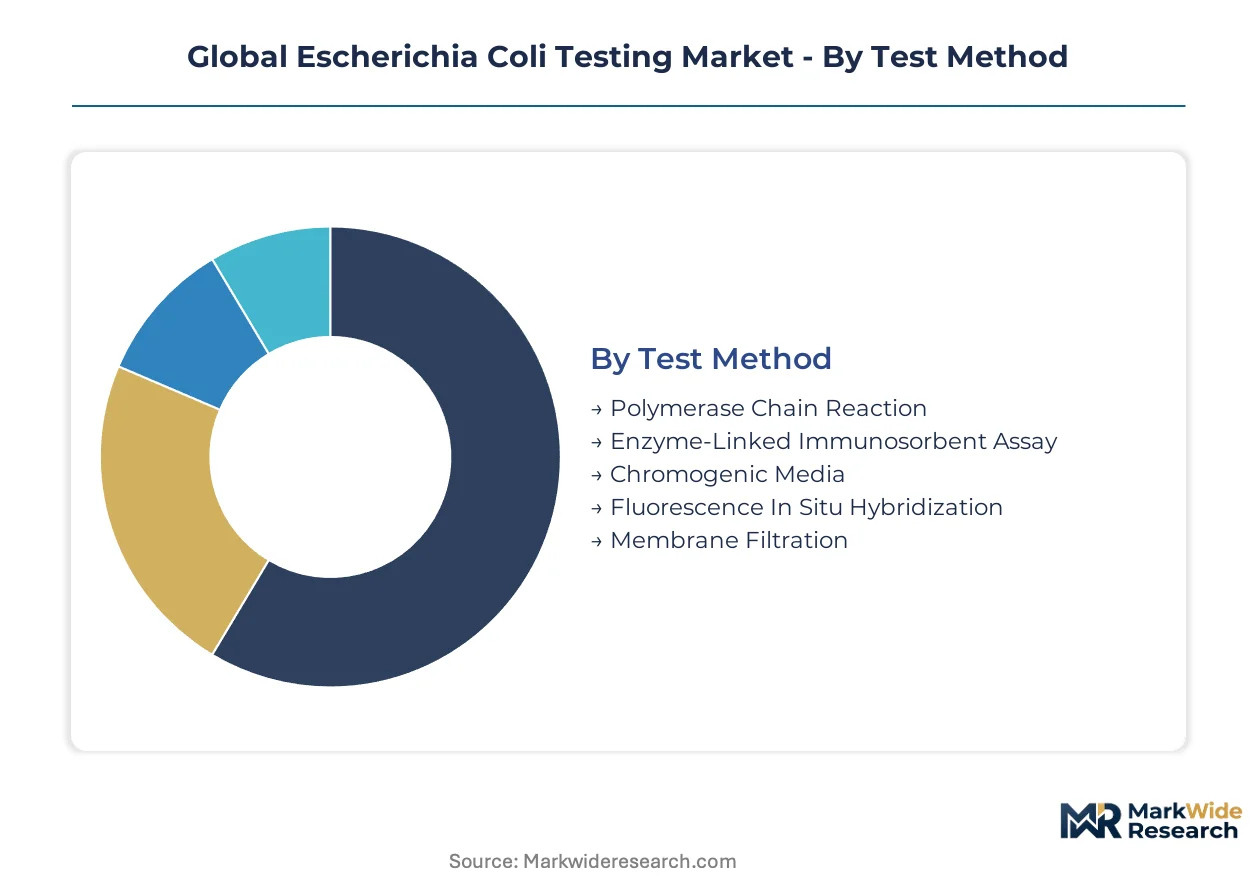
Segmentation in E. coli testing reflects divergent technical requirements across regulatory environments and operational settings. Assay selection depends on confirmation speed mandates, specimen matrix complexity, and capital availability for platform installation.
Test Method:
Standalone molecular platforms dominate high-throughput reference laboratories, while embedded immunoassays serve point-of-need environments where infrastructure constraints limit equipment footprint.
- Polymerase Chain Reaction:Nucleic acid amplification targeting virulence genes delivers analytical specificity exceeding culture-based alternatives. Demand concentrates in United States commercial diagnostic laboratories where FSMA documentation requirements favor traceable molecular confirmation workflows.
- Enzyme-Linked Immunosorbent Assay:Antibody capture against O157:H7 lipopolysaccharide enables rapid screening without thermal cycling infrastructure. Food processors in Germany deploy these assays within hazard analysis frameworks where speed-to-release outweighs genomic characterization needs.
- Chromogenic Media:Selective agar formulations exploit beta-glucuronidase activity for visual colony identification.
- Fluorescence In Situ Hybridization:Oligonucleotide probe binding enables cellular localization of target sequences.
- Membrane Filtration:Physical concentration methods precede cultural detection in water quality monitoring.
Polymerase Chain Reaction leads volumes today; Biosensors within the technology category is gaining share fastest.
Sample Type:
Matrix complexity drives preprocessing protocol selection, with liquid samples enabling direct amplification and solid matrices requiring enrichment homogenization steps that extend total workflow duration.
- Water:Municipal and recreational water monitoring employs membrane filtration followed by cultural confirmation. Japanese water utilities have intensified monitoring frequencies following revised drinking water quality standards.
- Food Products:Ground beef and leafy greens carry zero-tolerance regulatory status under FDA enforcement protocols. United States processors validate preventive controls with documented testing across slaughter and fresh-cut operations.
- Clinical Specimens:Stool and blood cultures from symptomatic patients require rapid pathogen identification.
- Environmental Surfaces:Hospitality and healthcare hygiene verification programs institutionalize rapid swab-based detection.
- Dairy Samples:Raw milk and cheese production lines in France and the Netherlands apply chromogenic media for quality control.
Food Products anchors revenue concentration today; Environmental Surfaces demonstrates the steepest expansion trajectory.
End User:
Procurement authority varies sharply across customer types, with regulatory agencies mandating method standards while commercial laboratories optimize for throughput economics.
- Diagnostic Laboratories:High-volume reference facilities in Japan and Germany consolidate testing for hospital networks and private practitioners. These operators prioritize automated nucleic acid extraction systems that compress technician hands-on time.
- Food Safety Agencies:Government enforcement laboratories in the United States coordinate PulseNet surveillance networks. Whole-genome sequencing mandates from CDC and FDA are compressing confirmation timelines and forcing revalidation of legacy phenotypic workflows.
- Research Institutes:Academic and government research programs investigate virulence mechanisms and resistance patterns.
- Quality Control Units:In-house testing at dairy processors and meatpacking facilities supports release decisions.
- Public Health Departments:Local health authorities conduct outbreak investigation and source attribution.
Diagnostic Laboratories command the largest installed base; Food Safety Agencies are expanding procurement most aggressively.
Technology:
Platform architecture determines capital intensity and consumable economics, with semiconductor-based systems requiring higher upfront investment but lower per-test operational cost at scale.
- Molecular Diagnostics:PCR and isothermal amplification platforms deliver definitive genomic characterization. Integrated systems from Thermo Fisher Scientific dominate United States reference laboratory procurement through combined hardware-reagent contracting.
- Biosensors:Semiconductor and electrochemical detection platforms reduce time-to-result from days to hours. Water utilities in Japan are adopting these systems for continuous monitoring applications where centralized laboratory access is geographically constrained.
- Immunoassays:Lateral flow and microwell formats serve resource-limited settings.
- Microarray:Multiplexed probe arrays enable simultaneous virulence gene screening.
- Chromatography:Separation-based methods support metabolite and toxin characterization.
Molecular Diagnostics generates the largest revenue pool; Biosensors climbs the fastest as point-of-need deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized microbiologists and molecular biologists concentrate in United States, Germany, and Japan, anchoring the geographic distribution of E. coli testing demand. These talent pools support regulatory enforcement laboratories and commercial diagnostic facilities that validate preventive controls across food supply chains.
United States
Ground beef processors and leafy greens packers drive volume demand as FDA enforces zero-tolerance policies under FSMA preventive controls. The CDC coordinates PulseNet surveillance networks that mandate whole-genome sequencing confirmation timelines. Diagnostic laboratories in Chicago and Atlanta consolidate testing for hospital networks and private practitioners.
Germany
Dairy processors in Bavaria and Baden-Württemberg deploy chromogenic media within hazard analysis frameworks where speed-to-release outweighs genomic characterization. EFSA baseline survey harmonization standardizes method performance criteria across member states. Reference laboratories in Berlin validate multi-country assay packages for cross-border product registration.
Japan
Water utilities intensify monitoring frequencies following revised drinking water quality standards from METI. Regional hospital laboratories in Tokyo and Osaka adopt digital microfluidic cartridges to reduce dependence on centralized reference facilities. Semiconductor biosensor manufacturers target continuous monitoring applications where laboratory access is geographically constrained.
France
Raw milk and cheese production lines apply chromogenic media for quality control under EU Green Deal farm-to-fork obligations. The country's national food safety agency enforces expanded testing protocols across dairy and produce supply chains. Processing clusters in Normandy and the Loire Valley consolidate supplier relationships with vendors holding multi-country validation packages.
Netherlands
Ready-to-eat salad contract manufacturers face compressed vendor qualification cycles as private label brands demand documented testing protocols. Third-party certification from AOAC International displaces in-house validation studies for mid-sized food processors. Quality control units in Rotterdam and Utrecht integrate virulence gene screening with Salmonella detection on single PCR panels.
Global Escherichia Coli Testing Market Competitive Landscape
Capital-heavy diagnostic platform manufacturers compete with asset-light assay designers for procurement contracts across reference laboratories and point-of-need environments. The vendor base separates into three strategic archetypes: integrated hardware-reagent contractors, chromogenic media specialists, and semiconductor biosensor developers. Consolidation pressures intensify as food safety agencies mandate genomic confirmation workflows that displace legacy phenotypic methods. Competitive positioning depends on multi-jurisdictional regulatory acceptance and automated throughput economics.
Among integrated molecular diagnostic providers, Thermo Fisher Scientific Inc. and QIAGEN N.V. occupy positions anchored by combined hardware-reagent contracting models. Chromogenic media specialists exemplified by bioMérieux SA represent quality control workflows in dairy processing facilities. Water safety application developers including IDEXX Laboratories, Inc. sit within the point-of-need deployment segment where regulatory monitoring frequencies have intensified. These three archetypes capture divergent procurement authority across diagnostic laboratories, food safety agencies, and quality control units.
| Leading Market Players |
|---|
| bioMérieux SA |
| Thermo Fisher Scientific Inc. |
| IDEXX Laboratories, Inc. |
| QIAGEN N.V. |
| Bio-Rad Laboratories, Inc. |
| Becton, Dickinson and Company |
| Neogen Corporation |
| Meridian Bioscience Inc. |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
Specialty chemical inputs for PCR primer synthesis flow from concentrated German and Swiss suppliers through tiered pricing structures that stratify assay manufacturers by validation depth and regulatory certification breadth. Reagent costs cascade downstream into bundled hardware-reagent contracts for reference laboratories and unbundled consumable sales for point-of-need deployers, with ISO 16654 compliance tiers separating premium molecular platforms from standard chromogenic media.
Pricing Analysis
Bundled hardware-reagent contracts dominate high-throughput reference laboratories while unbundled consumable sales serve point-of-need environments where capital constraints limit platform investment. Pricing stratifies across premium, standard, and economy tiers based on ISO 16654 validation depth and multi-jurisdictional regulatory acceptance breadth. Cost compression in the standard tier is intensifying as mid-sized food processors shift from in-house validation to third-party AOAC certification. Diagnostic laboratories exhibit lowest price sensitivity due to throughput economics, while quality control units at dairy processors demonstrate highest sensitivity to per-test operational costs.
Supply Chain Analysis
ISO 16654 and FDA 510(k) qualification gating concentrates reagent supply in Germany, Switzerland, and the United States where specialty chemical manufacturers maintain validated synthesis protocols. Primer synthesis draws from phosphoramidite chemistry feedstocks and fluorophore conjugation reagents sourced from concentrated chemical suppliers. Single-source vulnerability in oligonucleotide precursor supply creates structural risk for assay manufacturers dependent on just-in-time delivery. Distribution runs through authorized distributors for clinical diagnostics and direct sales forces for food safety agencies with consolidated procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where regulatory enforcement intensity in the United States and EU generates pricing premiums that subsidize platform development costs against lower-margin volume sales in enforcement-lagging jurisdictions.
For Market Incumbents: Deploy automated nucleic acid extraction systems as the primary lever against emerging biosensor substitutes. Backward integration into primer synthesis capabilities reduces exposure to German and Swiss single-source suppliers. Consolidate multi-country validation packages to defend reference laboratory contracts against regional challengers with narrower regulatory footprints. For New Entrants and Emerging Players: Launch via water utility direct sales channels where geographic constraints on centralized laboratory access create deployable white space. Environmental surface monitoring in hospitality and healthcare hygiene verification programs offers the most penetrable segment given institutionalization tailwinds. Target semiconductor biosensor platforms for continuous monitoring applications where time-to-result compression commands premium positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where whole-genome sequencing mandates from CDC and FDA compress confirmation timelines and obsolete legacy phenotypic workflows. Long-term viability across the analysis window favors integrated hardware-reagent contractors with multi-jurisdictional regulatory acceptance over asset-light assay designers. The signal to watch is EFSA harmonization progress that could accelerate cross-border validation package consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdictional Validation Investment | ISO 16654 and FDA 510(k) dual certification opens EU and US procurement channels simultaneously. |
| Semiconductor Biosensor Platform Launch | Digital microfluidic cartridges reduce time-to-result from days to hours for water utilities. |
| Backward Integration into Primer Synthesis | In-house phosphoramidite chemistry production mitigates German and Swiss supplier concentration risk. |
| Environmental Surface Application Expansion | Hygiene verification programs in healthcare and hospitality institutionalize rapid swab-based detection protocols. |
| Multiplex PCR Panel Development | Single-panel Salmonella and Listeria integration reduces per-sample operational cost for dairy processors. |
Research Methodology
Coverage spans the United States, Germany, Japan, France, and the Netherlands, with primary inputs from each market cluster. The analysis combines structured interviews with diagnostic laboratory directors, food safety agency procurement officers, quality control unit managers at dairy processors, and water utility monitoring specialists with secondary validation from FDA 510(k) filings, EFSA baseline survey reports, ISO 16654 documentation, and AOAC International certification records. Bottom-up demand modeling from installed platform bases triangulates against top-down market sizing from reagent consumption patterns.
Rate-of-change decomposition separates volume expansion from pricing trajectory across the projection horizon. The analytical framework models segmentation dimensions including test method, sample type, end user, and technology platform architecture. CAGRs derive from regression analysis of historical regulatory enforcement intensity against platform adoption curves. Industry-specific forecast inputs incorporate FSMA preventive control documentation mandates and EU Green Deal farm-to-fork testing obligation expansion.
Forecast precision tightens around the base case; tail outcomes carry wider variance under whole-genome sequencing mandate acceleration or reagent supply disruption scenarios. Forecasts reflect assumptions regarding regulatory enforcement continuity and platform technology transition rates. A model refresh is warranted upon material change in CDC or EFSA sequencing confirmation timeline requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Freeze-Dried Microbial Food Culture Market
Industrial Microbiology
Microbiomes Market
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Microbial Seed Treatment Market
Industrial Microbiology
Microbial Biosurfactants Market
Industrial Microbiology
Microbial Bioreactors Market
Industrial Microbiology
Microbial-Derived Fiber Market
Industrial Microbiology
Microbial Cell Banking Market
Industrial Microbiology
Eubiotics Market
Industrial Microbiology
Microbiome Sample Preparation Technology Market
Industrial Microbiology
Benzoate-Free Enzymes Market
Industrial Microbiology
Global Bacterial Cell Culture Market
Industrial Microbiology
Global Microbial Protein Market
Industrial Microbiology
Molecular Microbiology Market
Industrial Microbiology
Bacterial Amylase Market
Industrial Microbiology
Lactic Acid Bacteria Market