
 Freeze-Dried Microbial Food Culture Market | 2026-2036
Freeze-Dried Microbial Food Culture Market Size, Share, and Industry Trends Forecast 2026-2036
Freeze-Dried Microbial Food Culture Market Foresight
Buyer concentration across artisan producers and specialty food manufacturers is rebalancing toward mid-scale regional dairies and plant-based startups seeking standardized fermentation inputs. Lesaffre leverages its European yeast heritage to dominate bakery and dairy culture supply chains. Chr. Hansen Holding A/S specializes in lactic acid bacteria strains for cheese applications, while Lallemand Inc. extends its geographic footprint through beverage fermentation cultures.
Freeze-dried microbial food culture denotes viable microorganisms preserved through sublimation dehydration, typically achieving moisture content below 5% and shelf stability exceeding 12 months at ambient temperatures, employed to inoculate and standardize industrial fermentation processes. Lactic acid bacteria occupy the largest product category due to entrenched dairy demand, while probiotic cultures represent the fastest-expanding segment as nutraceutical manufacturers integrate live cultures into functional foods. Dairy fermentation commands the dominant application share, though plant-based fermentation accelerates as oat, almond, and pea protein substrates require tailored microbial solutions.
EFSA novel food assessments and EU MDR traceability requirements shape strain approval timelines and labeling obligations for culture suppliers targeting European food processors. FDA GRAS self-affirmation and USDA organic certification create parallel compliance pathways for US market entry. Stakeholders must monitor evolving strain patent landscapes and refrigeration energy regulations that directly influence the cost advantage of freeze-dried formats over frozen alternatives.
Market Dynamics
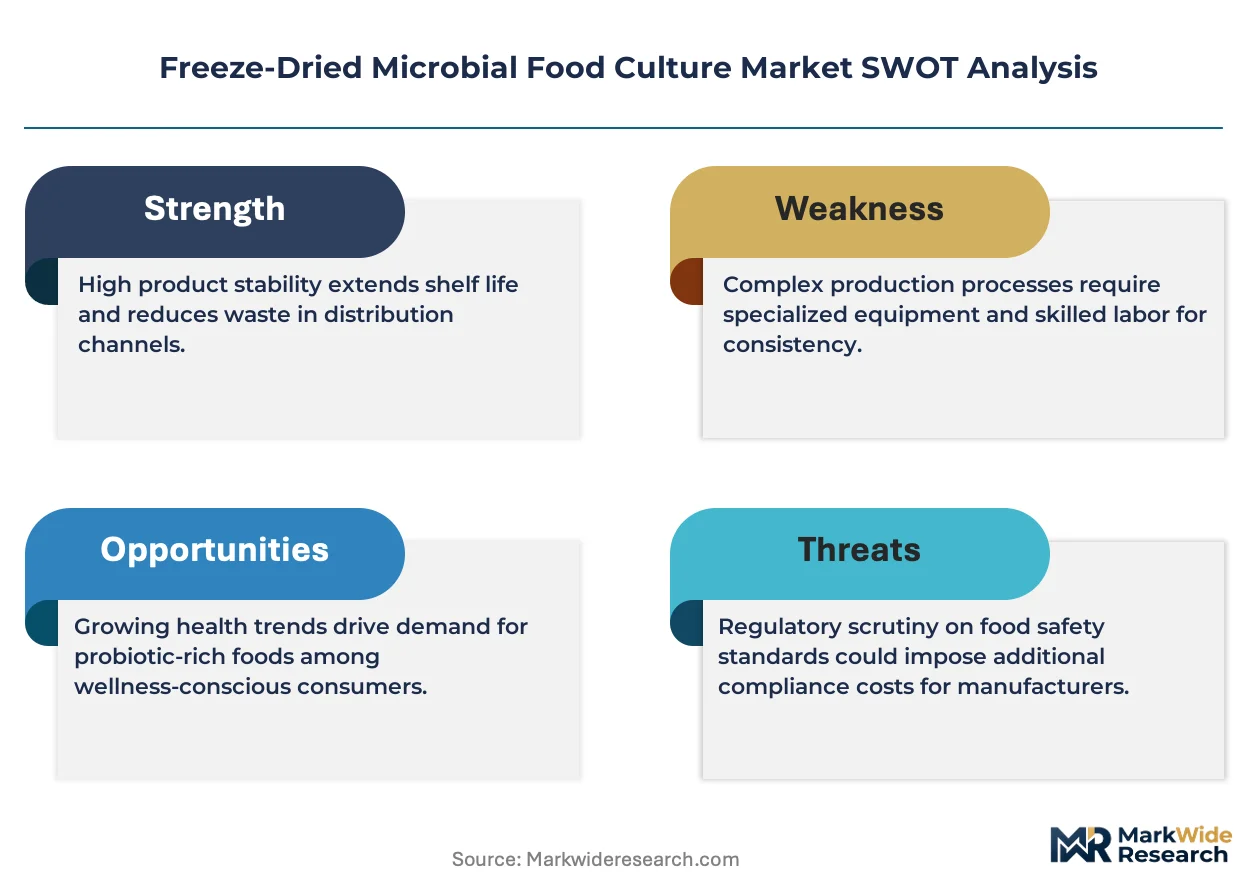
The EU F-Gas Regulation and refrigeration energy standards are compressing frozen culture economics, tilting procurement toward ambient-stable freeze-dried formats that eliminate cold-chain dependency and cut operational expenditure.
Growth Catalysts
- Refrigeration energy standards:The EU's tightening efficiency mandates raise frozen culture storage costs, accelerating processor migration to shelf-stable alternatives that bypass refrigeration entirely.
- Artisan dairy clusters:France's traditional cheese-producing regions and Italy's Emilia-Romagna belt standardize on freeze-dried inputs to achieve batch-to-batch consistency in protected designation products.
- Plant-based fermentation:Oat, almond, and pea protein substrate developers require tailored microbial solutions that deliver reliable acidification without dairy-derived culture backgrounds.
Market Restraints
- Strain patent thickets:Proprietary lactic acid bacteria and probiotic strain portfolios held by established culture houses create licensing friction for new entrants developing competitive alternatives.
- EFSA novel food timelines:European strain approval assessments extend 18-24 months, freezing commercialization schedules for innovators targeting EU dairy and nutraceutical processors.
- Input cost volatility:Fermentation media components and specialized cryoprotectants expose producers to agricultural commodity price swings that compress margin stability.
Strategic Opportunities
- Kombucha and water kefir channels:Beverage fermentation startups in North American and European urban markets seek standardized culture inputs that reduce variability in small-batch production.
- Clean-label positioning:Freeze-dried formats enable "no artificial preservatives" claims that resonate with European retailers enforcing stricter ingredient disclosure standards.
- Precision fermentation convergence:Integration of CRISPR-edited strain development with lyophilization protocols promises enhanced viability retention and targeted metabolic performance.
Industry Challenges
- Lyophilization technician scarcity:Specialized expertise in sublimation dehydration parameters and residual moisture control remains concentrated among veteran operators, constraining capacity expansion.
- Legacy frozen culture infrastructure:Dairy processors with sunk investments in -80°C storage systems face transition friction when evaluating ambient-stable format switches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freeze-Dried Microbial Food Culture Market |
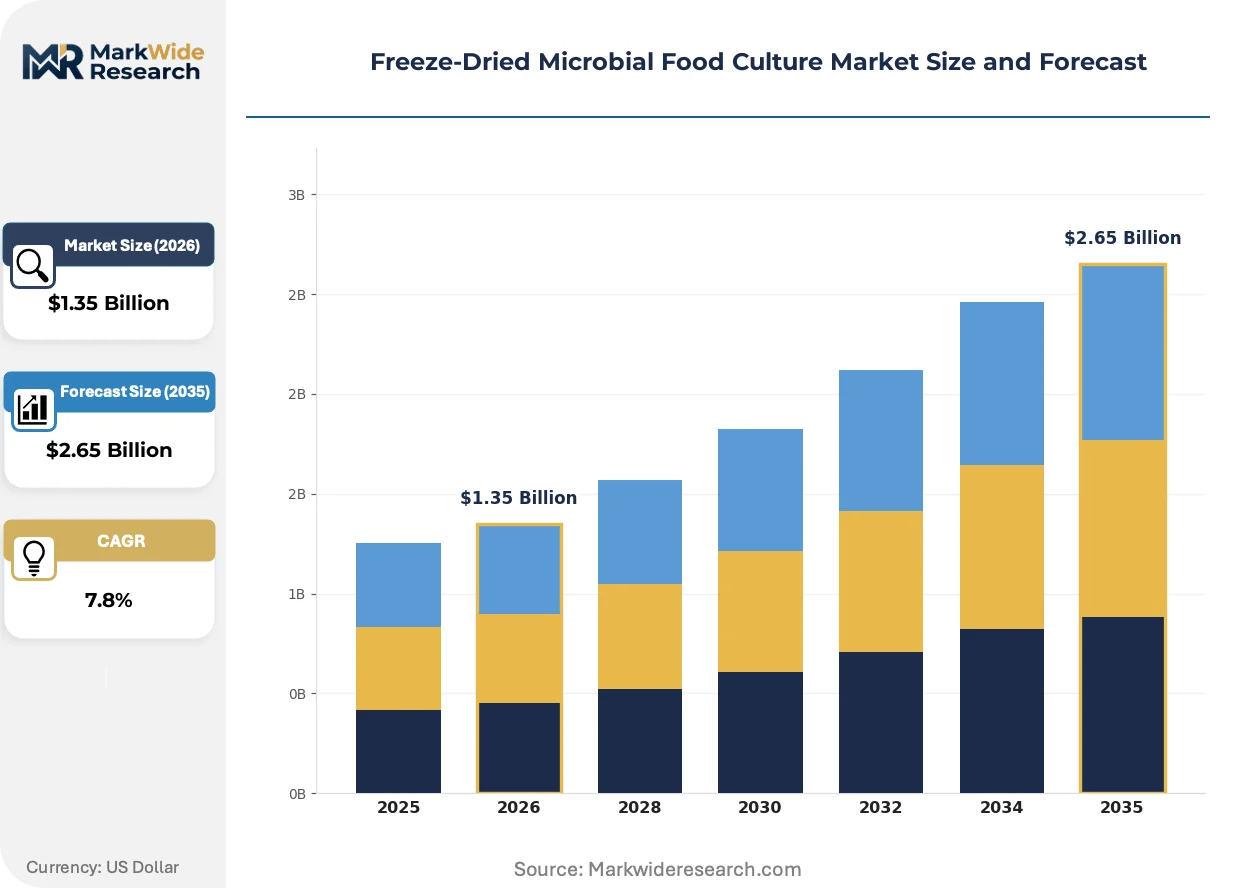
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.65 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lactic Acid Bacteria, Yeast Cultures, Mold Cultures, Acetic Acid Bacteria, Probiotic Cultures Application: Dairy Fermentation, Bakery Fermentation, Beverage Fermentation, Meat Fermentation, Plant-Based Fermentation End User: Food Processing Units, Specialty Food Manufacturers, Artisan Producers, Nutraceutical Manufacturers, Functional Food Producers Packaging Type: Vacuum Sealed Bags, Aluminum Foil Pouches, Glass Vials, Plastic Containers, Sachets |
| Companies Covered | Lesaffre, Lyo-San Inc., DuPont, Bioprox, Sacco System, Chr. Hansen Holding A/S, Lallemand Inc., NPSelection, Koninklijke DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freeze-Dried Microbial Food Culture Market Shifts & Advancements
Single-use sachet formats and strain-specific cryoprotectant formulations are compressing the technical barrier between industrial-scale culture production and small-batch artisan adoption.
Lyophilization with trehalose-based cryoprotectants is overtaking traditional skim-milk-based preservation for thermosensitive probiotic strains. Nutraceutical manufacturers in Germany and the Netherlands are adopting these formulations at accelerating pace. The shift is overtaking frozen concentrate dominance in high-value functional food applications where viability retention determines premium positioning.
The EU Medical Device Regulation traceability requirements now extend to probiotic cultures making structure-function claims, forcing suppliers to implement batch-level digital tracking. This industrial consequence raises compliance costs for smaller culture houses while favoring integrated producers with existing quality management systems. Dairy and supplement segments targeting European export markets are responding by consolidating supplier relationships toward MDR-ready partners.
Direct-to-artisan distribution via specialized ingredient marketplaces is fragmenting traditional distributor control over culture supply. Small-scale creameries and plant-based startups in Denmark and California now procure strains through vertically focused platforms that displace conventional food-ingredient middlemen. This channel rotation is most visible in specialty fermentation circles where technical support and strain education outweigh volume-based pricing in purchase decisions.
Freeze-Dried Microbial Food Culture Market Segmentation
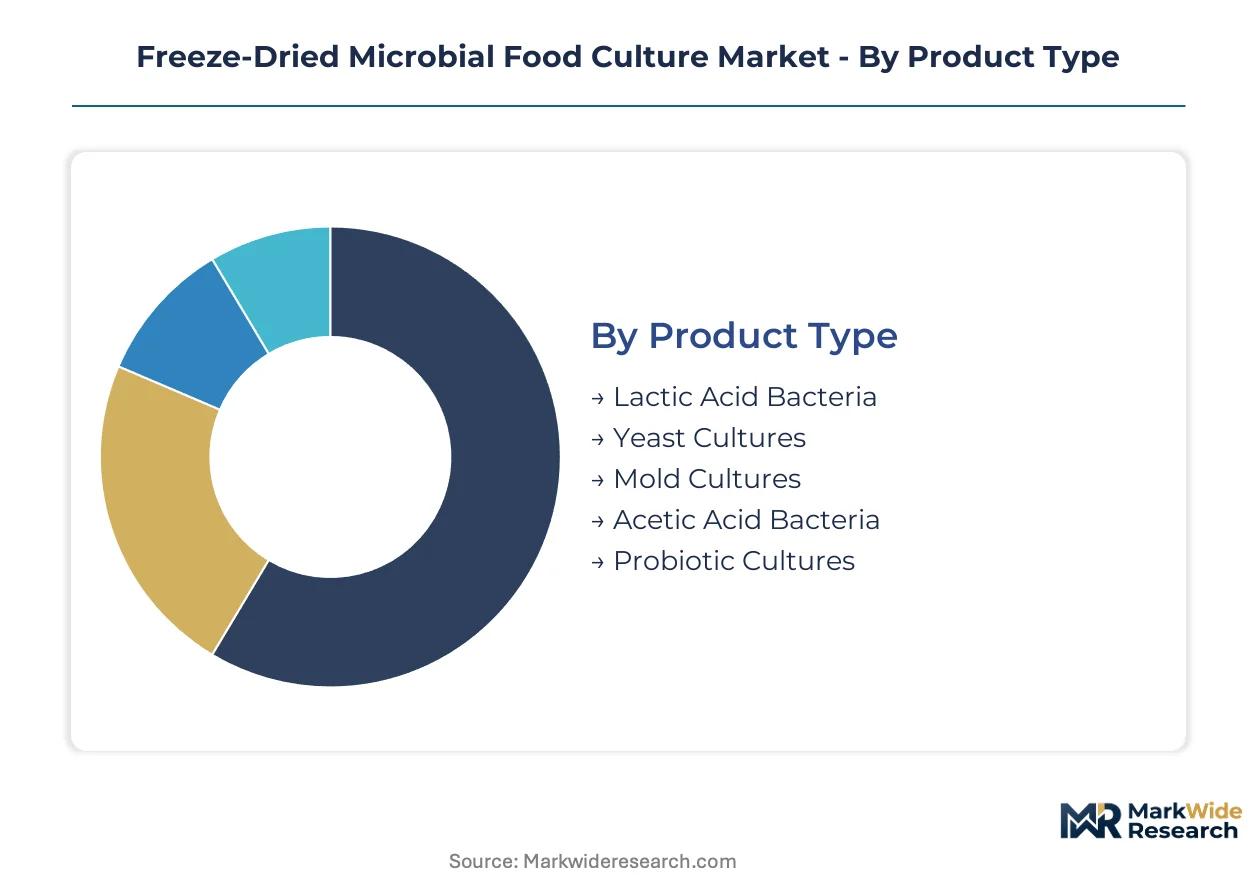
Freeze-dried microbial food culture segmentation reveals how strain specificity, application environment, and end-user scale determine procurement patterns. Each dimension carries distinct technical requirements that shape supplier relationships and format preferences.
Product Type:
Standalone single-strain cultures dominate commodity dairy applications, while multi-strain blends embed into specialized fermentation systems requiring precise metabolic coordination.
- Lactic Acid Bacteria:These mesophilic and thermophilic strains—Lactococcus, Lactobacillus, Streptococcus—deliver controlled acidification in cheese and yogurt production. French PDO creameries and Italian Grana Padano consortia standardize on defined-strain cultures to protect terroir consistency.
- Probiotic Cultures:Live microorganisms conferring documented health benefits when administered in adequate doses, typically Bifidobacterium and Lactobacillus rhamnosus strains. German and Dutch nutraceutical manufacturers drive demand as EFSA health claim assessments tighten strain documentation requirements.
- Yeast Cultures:Saccharomyces cerevisiae and Kluyveromyces marxianus strains for bread leavening and alcoholic fermentation.
- Mold Cultures:Penicillium roqueforti and Penicillium camemberti for blue and soft-ripened cheese surface development.
- Acetic Acid Bacteria:Komagataeibacter and Gluconacetobacter strains for vinegar production and kombucha SCOBY starter cultures.
Volume placements concentrate in Lactic Acid Bacteria; the faster expansion belongs to Probiotic Cultures.
Application:
Cost tier separation emerges clearly: high-volume dairy and bakery applications absorb standardized bulk formats, while beverage and plant-based segments absorb premium-priced specialized strains.
- Dairy Fermentation:Milk inoculation for cheese, yogurt, kefir, and fermented butter production. France's Lesaffre and Italy's Sacco System supply chains anchor this segment through heritage strain collections optimized for PDO compliance.
- Plant-Based Fermentation:Microbial solutions tailored to oat, almond, pea, and soy protein substrates lacking dairy's natural buffering capacity. Danish oat-milk innovators and California almond-yogurt startups require acidification strains free from dairy-derived culture backgrounds to maintain vegan certification.
- Bakery Fermentation:Sourdough starter cultures and commercial yeast formulations for bread and pastry applications.
- Beverage Fermentation:Kombucha SCOBYs, water kefir grains, and alcoholic fermentation cultures for craft producers.
- Meat Fermentation:Starter cultures for dry-cured sausages and fermented meat products, particularly salami and chorizo traditions.
Revenue concentration sits with Dairy Fermentation; Plant-Based Fermentation is climbing the fastest as substrate diversification accelerates.
End User:
Customer type determines technical support intensity: commodity food processors prioritize volume pricing, while artisan producers and nutraceutical manufacturers demand strain education and regulatory documentation.
- Food Processing Units:Large-scale dairy, bakery, and meat operations with automated inoculation systems and quality control laboratories.
- Artisan Producers:Small-batch creameries, farmhouse cheesemakers, and traditional bakeries requiring batch-to-batch consistency in protected designation products.
- Specialty Food Manufacturers:Mid-scale operations producing ethnic fermented foods, craft beverages, and premium dairy alternatives.
- Nutraceutical Manufacturers:Dietary supplement and functional food producers requiring EFSA novel food compliance and MDR traceability for structure-function claims.
- Functional Food Producers:Brands integrating live cultures into positioned health products such as probiotic-enriched yogurts and fermented beverages.
Procurement volume aggregates at Food Processing Units; the steepest expansion trajectory belongs to Nutraceutical Manufacturers as regulatory documentation requirements intensify.
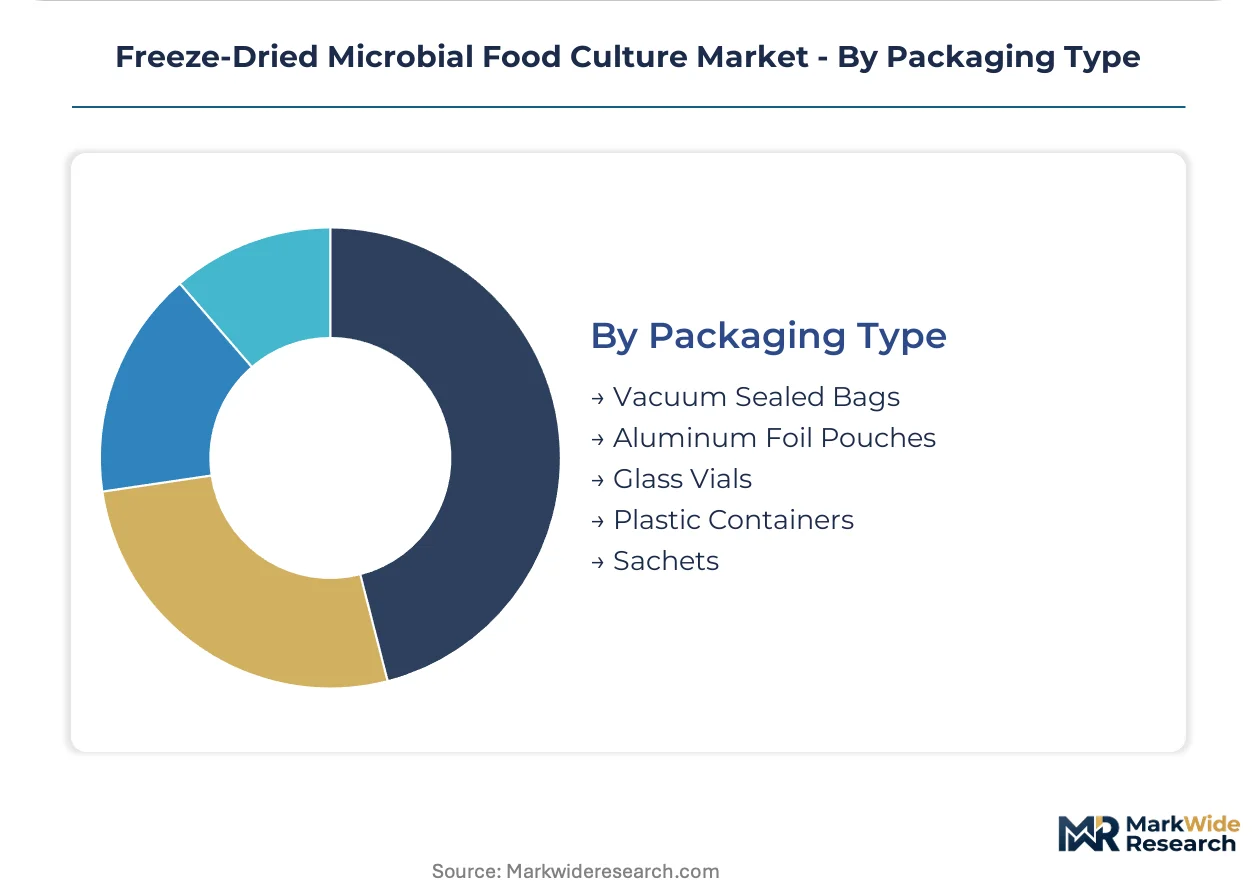
Packaging Type:
Margin structure differentiates formats: industrial bulk containers serve high-throughput processors, while unit-dose sachets and vials capture premium positioning in artisan and laboratory segments.
- Vacuum Sealed Bags:Multi-kilogram formats for industrial dairy and bakery operations with controlled-atmosphere storage capabilities.
- Sachets:Single-use portions enabling precise inoculation rates for small-batch producers without laboratory weighing equipment.
- Aluminum Foil Pouches:Intermediate formats balancing moisture protection with cost efficiency for mid-scale processors.
- Glass Vials:Premium hermetic sealing for high-value probiotic strains requiring maximum viability retention.
- Plastic Containers:Cost-optimized bulk storage for non-thermosensitive yeast and mold cultures with shorter distribution cycles.
Shipment tonnage clusters in Vacuum Sealed Bags; Sachets are gaining share fastest as direct-to-artisan distribution channels fragment traditional supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France concentrates the highest procurement volume for freeze-dried microbial cultures, driven by its heritage dairy infrastructure and protected designation cheese production. Artisan creameries across Normandy and the Alps standardize on defined-strain inputs to maintain terroir consistency in export-grade products.
France
Traditional cheese-producing regions anchor demand for lactic acid bacteria strains in Comté and Roquefort manufacturing. The EU F-Gas Regulation accelerates processor migration from frozen to ambient-stable culture formats. Lesaffre maintains production facilities in northern France serving bakery and dairy supply chains across the continent.
Italy
The Emilia-Romagna dairy belt generates concentrated demand for PDO-compliant starter cultures in Parmigiano-Reggiano and Grana Padano production. EFSA novel food assessments extend strain approval timelines for innovators targeting Italian processors. Sacco System operates from the Lombardy region supplying heritage strain collections to protected designation consortia.
Germany
Nutraceutical manufacturers in Bavaria and Baden-Württemberg drive probiotic culture demand for functional food applications. EU Medical Device Regulation traceability requirements force batch-level digital tracking implementation. Berlin-area ingredient distributors consolidate supplier relationships toward MDR-ready culture houses.
United States
Plant-based fermentation startups in California and craft beverage producers in the Pacific Northwest seek standardized culture inputs for oat-milk and kombucha applications. FDA GRAS self-affirmation creates a parallel compliance pathway distinct from European strain approval processes. Denver and Austin fermentation hubs attract direct-to-artisan distribution platforms displacing conventional ingredient middlemen.
Denmark
Oat-milk innovators in Copenhagen and Aarhus require dairy-free microbial solutions for vegan-certified alternative dairy production. REACH compliance for cryoprotectant formulations shapes import sourcing decisions. Danish food technology clusters partner with specialized culture suppliers for tailored acidification strains.
Freeze-Dried Microbial Food Culture Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and direct-to-artisan distribution channels. The supplier base stratifies between integrated culture houses with heritage strain collections and specialized entrants targeting plant-based and nutraceutical segments. Three archetypes dominate: European heritage suppliers with PDO-optimized portfolios, North American precision fermentation specialists, and Asian contract manufacturers scaling bulk production. Capacity expansion and strategic partnerships constitute the primary competitive vectors as cold-chain economics shift procurement preferences.
Among European heritage suppliers, Lesaffre and Chr. Hansen Holding A/S exemplify the integrated archetype with extensive strain documentation capabilities. Lallemand Inc. represents the geographic diversification strategy through its multi-regional production footprint. Sacco System occupies a specialist position within Italian dairy culture supply chains.
| Leading Market Players |
|---|
| Lesaffre |
| Lyo-San Inc. |
| DuPont |
| Bioprox |
| Sacco System |
| Chr. Hansen Holding A/S |
| Lallemand Inc. |
| NPSelection |
| Koninklijke DSM N.V. |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists across France and Italy anchor production clusters, translating heritage strain ownership into pricing discipline that resists commodity erosion while cold-chain economics shift procurement toward their ambient-stable formats.
Pricing Analysis
High-volume dairy processors absorb standardized bulk cultures at compressed margins, while artisan creameries and nutraceutical manufacturers pay premiums for strain documentation and regulatory compliance. Three-tier pricing structure across premium, standard, and economy levels separates EFSA MDR-traceable probiotic strains from commodity lactic acid bacteria and generic yeast formulations. Cost compression in standard-tier dairy cultures is intensifying because EU F-Gas Regulation compliance raises frozen storage costs and pushes buyers toward freeze-dried alternatives. Food processing units exhibit highest price sensitivity due to automated inoculation scale, whereas nutraceutical manufacturers prioritize regulatory documentation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with trehalose cryoprotectant suppliers concentrated in Germany and the Netherlands, where REACH compliance constraints limit alternative sourcing. Production gravity centers on France, Italy, and Denmark, with fermentation media components drawing from agricultural suppliers across the EU and specialized freeze-drying equipment anchored in Swiss and German manufacturing clusters. Tariff exposure on imported cryoprotectants and fermentation substrates presents structural risk as REACH documentation requirements tighten. Distribution runs through vertically focused ingredient marketplaces displacing conventional food-ingredient middlemen, particularly for direct-to-artisan channels in Denmark and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Upstream control over heritage strain collections and downstream direct-to-artisan channels constitute the vertical-integration race, with EFSA MDR traceability requirements forcing consolidation toward integrated producers with existing quality management systems.
For Market Incumbents: Extend strain documentation capabilities to capture EFSA MDR-ready positioning as EU traceability requirements raise compliance costs for smaller culture houses. Consolidate supplier relationships with oat-milk innovators and plant-based startups seeking dairy-free microbial solutions, leveraging existing cryoprotectant formulation expertise to defend against precision fermentation specialists entering with CRISPR-edited alternatives. For New Entrants and Emerging Players: Begin with kombucha and water kefir channels in North American urban markets, where beverage fermentation startups seek standardized culture inputs that reduce batch variability. Target direct-to-artisan distribution platforms displacing conventional middlemen, offering technical support and strain education that outweighs volume-based pricing in specialty fermentation purchase decisions. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision fermentation specialists with CRISPR-edited strain development capabilities in Denmark and California, where plant-based fermentation accelerates and regulatory pathways remain more permissive than EU novel food assessments. Watch for inflection signals in EFSA strain approval timelines, as compressed 12-month assessments would unlock commercialization schedules for innovators targeting European dairy and nutraceutical processors.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Strain Collection Acquisition | Secures PDO-compliant portfolios for Italian Grana Padano and French Comté supply chains. |
| Direct-to-Artisan Platform Launch | Displaces conventional distributors by offering technical support to Danish creameries. |
| Trehalose Cryoprotectant Formulation Scale-Up | Captures German nutraceutical demand as viability retention determines premium positioning. |
| EFSA MDR Traceability System Implementation | Raises compliance barriers that consolidate procurement toward integrated culture houses. |
| Precision Fermentation R&D Partnership | Integrates CRISPR-edited strain development with lyophilization protocols for enhanced performance. |
Research Methodology
Multi-period observation of strain approval timelines, cold-chain economics, and artisan procurement patterns anchored the trend analysis, supplemented by interviews with culture house R&D directors, dairy processor quality managers, nutraceutical regulatory affairs leads, and ingredient marketplace operators. Secondary validation drew from EFSA novel food assessment databases, EU F-Gas Regulation implementation records, FDA GRAS self-affirmation filings, and customs trade data on fermentation media imports. Bottom-up volume estimates from individual culture suppliers were triangulated against top-down demand projections from end-use segment analysis.
Segment-weighting across product type, application environment, end-user scale, and packaging format determined value distribution throughout the forecast period. CAGRs were derived from fitted growth curves applied to each segment's baseline penetration and projected expansion trajectory, with lactic acid bacteria volume and probiotic culture value treated as separate modeling dimensions. Industry-specific inputs included EFSA approval pipeline velocity, EU refrigeration energy standard implementation schedules, and plant-based substrate diversification rates.
Underlying measurement precision varies by segment; lactic acid bacteria dairy applications carry tighter precision than emerging plant-based fermentation categories where substrate-specific strain development remains iterative. Forecasts reflect assumptions about regulatory pathway efficiency, cold-chain cost trajectories, and cryoprotectant supply stability that could shift with agricultural commodity volatility or REACH compliance revisions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Molecular Microbiology Market
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Microbial Protein Used in Feed Market
Industrial Microbiology
Global Microbial Identification Market
Industrial Microbiology
Global Bacterial Cell Culture Market
Industrial Microbiology
Mesophilic Bacteria Market
Industrial Microbiology
Global Escherichia Coli Testing Market
Industrial Microbiology
Microbial Culture Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
North America Microbial Protein Market
Industrial Microbiology
Real Time Continuous Microbiological Monitoring Systems Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Microbial Identification Panels Market
Industrial Microbiology
Microbial Therapeutic Products Market
Industrial Microbiology
Industrial Bioprocessing Market
Industrial Microbiology
Anti-Microbial Anti-Fungal Test Market