
 Global Starter Culture Market | 2026-2036
Global Starter Culture Market Size, Share, and Industry Trends Forecast 2026-2036
Global Starter Culture Market Outlook
Starter culture as a service, where suppliers bundle strain maintenance, viability monitoring, and shelf-life guarantees into recurring contracts, is repositioning how buyers procure microbial inputs. Lesaffre leverages its global fermentation infrastructure to anchor long-term supply relationships with industrial dairy processors. Novonesis A/S sustains competitive distance through specialized enzyme-culture combinations that reduce formulation complexity for beverage manufacturers. Lallemand Inc. dominates North American yeast culture channels through integrated production and distribution control.
Starter cultures consist of defined microbial strains, typically bacteria such as Lactococcus lactis or Lactobacillus delbrueckii, selected for acidification rate, phage resistance, and flavor compound generation in controlled fermentation environments. These live, active preparations serve as the biological engine that initiates and steers biochemical transformations in food matrices, converting sugars to organic acids, alcohols, or carbon dioxide to achieve targeted shelf stability, texture, and sensory profiles. Bacteria-based cultures command the largest share of current value given their indispensability in cheese and yogurt manufacture, while custom blends represent the fastest-expanding category as processors seek strain cocktails optimized for specific phage environments and flavor targets. Probiotic applications within the application dimension concentrate margin pools, since clinical validation requirements create barriers that commodity fermentation starters cannot easily cross.
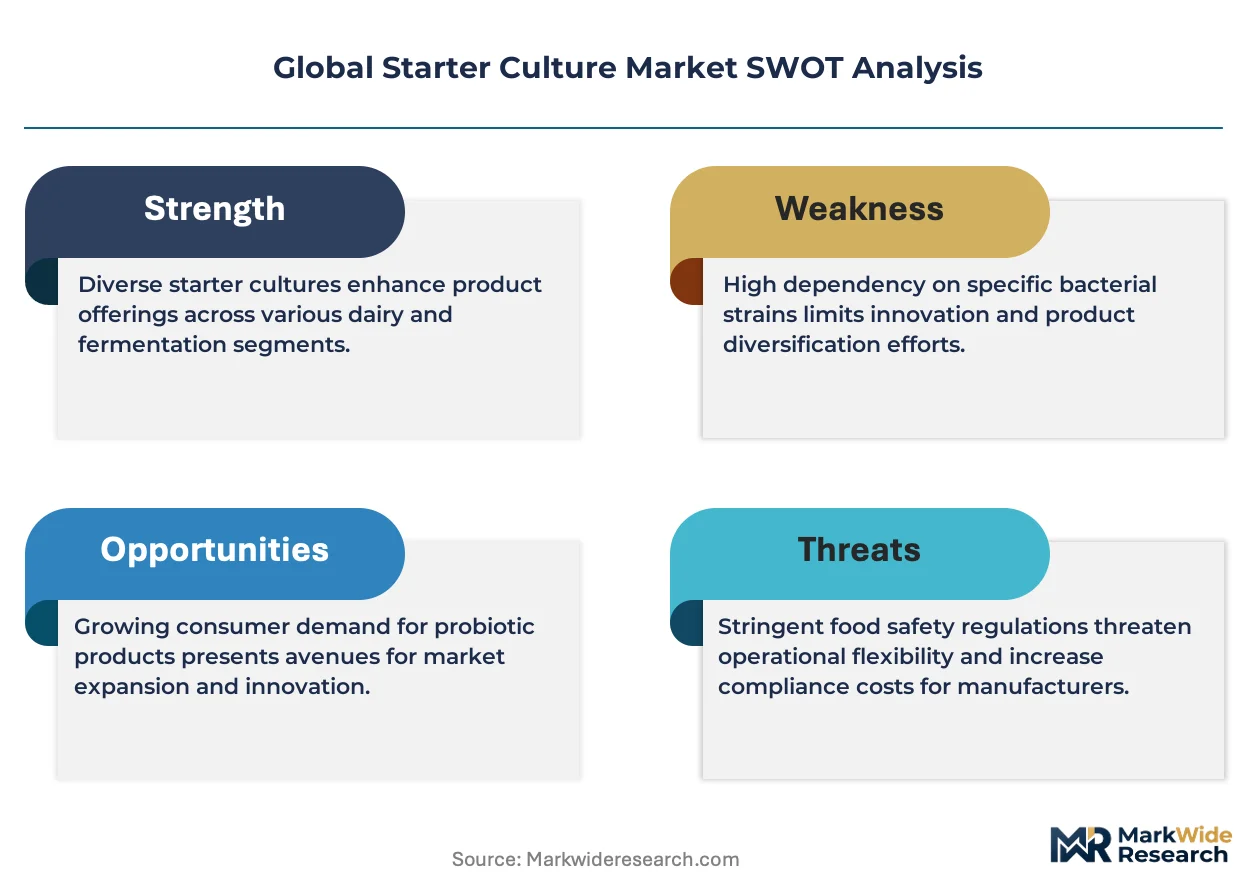
EFSA maintains stringent qualified presumption of safety assessments for novel strains entering European food channels, while the FDA exercises oversight through its GRAS notification framework for cultures marketed in the United States. EMA and national regulators in Germany and France scrutinize health claim linkages when cultures bridge into pharmaceutical or supplement classifications, compressing development timelines for cross-category players. ISO standards for strain identification and purity provide the baseline technical grammar that shapes procurement specifications across multinational food manufacturers. Stakeholders must track how evolving genome-editing regulatory classifications in major jurisdictions will redraw the boundary between traditional strain selection and engineered microbial inputs.
Market Dynamics
Starter culture supply chains are consolidating around integrated fermentation infrastructure, with suppliers bundling strain maintenance, viability monitoring, and shelf-life guarantees into recurring service contracts that lock in industrial dairy processors.
Growth Catalysts
- EU REACH and EFSA frameworks:Tightened strain safety requirements accelerate replacement of legacy cultures with validated alternatives, creating upgrade cycles across European dairy manufacturing.
- Probiotic dairy applications:Clinical validation requirements for health-positioned yogurt and fermented beverages expand demand for specialized strain portfolios with documented efficacy.
- Phage-resistant strain development:Advances in CRISPR-guided selection and directed evolution reduce production losses in cheese plants, improving process economics for culture-dependent operations.
Market Restraints
- Raw material concentration:Whey permeate and yeast extract supplies concentrate in specific geographic clusters, exposing culture manufacturers to input cost volatility and logistics disruption.
- Freeze-drying energy intensity:Lyophilization consumes substantial electricity, compressing margins where regional power costs spike and carbon pricing mechanisms expand.
- Regulatory fragmentation:Divergent genome-editing classifications between FDA GRAS and EFSA qualified presumption of safety assessments complicate strain registration for cross-Atlantic suppliers.
Strategic Opportunities
- Plant-based fermentation:Dairy-alternative yogurt and cheese analogs require tailored acidification profiles, opening white space for culture suppliers beyond traditional animal milk matrices.
- Precision fermentation feedstocks:Convergence of synthetic biology and food-grade strain engineering enables production of high-value metabolites through engineered starter derivatives.
- Indian FSSAI modernization:Updated food safety standards and import substitution policies create entry pathways for domestic culture manufacturing serving South Asian dairy cooperatives.
Industry Challenges
- Phage monitoring expertise:Industrial microbiology talent capable of rapid phage identification and rotation protocol design remains scarce, constraining plant-level operational resilience.
- ISO 17025 accreditation timelines:Strain identification and purity certification requirements extend validation cycles, delaying new product commercialization for culture developers.
- Legacy system integration:Automated culture dosing and fermentation control systems require retrofitting to interface with existing dairy plant SCADA architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Starter Culture Market |
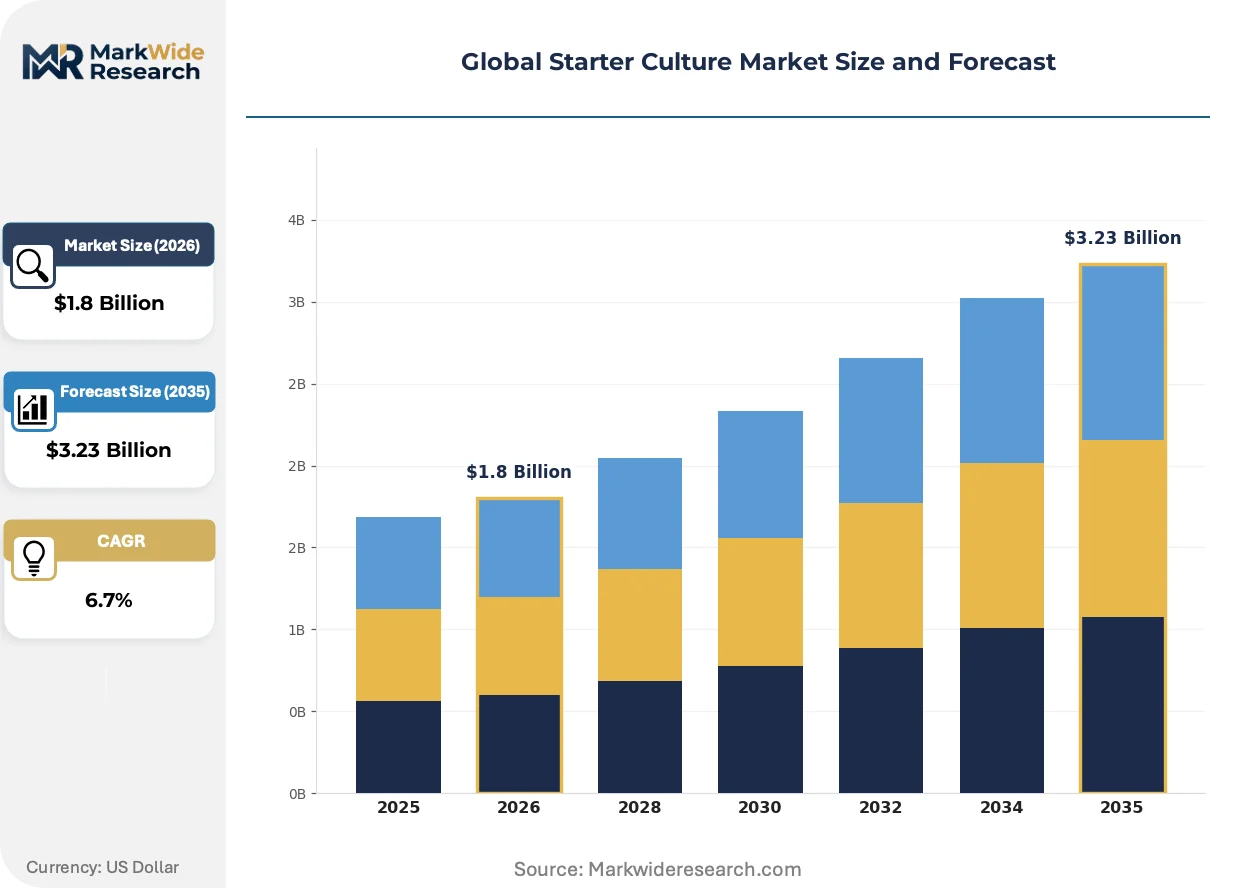
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacteria, Yeast, Mold, Custom Blends End User: Dairy, Beverages, Bakery, Confectionery Technology: Fermentation, Freeze-drying, Spray-drying, Liquid Culture Application: Food Preservation, Flavor Development, Nutritional Enhancement, Probiotic Products |
| Companies Covered | Lesaffre, International Flavors & Fragrances, Novonesis A/S, CSK Food Enrichment B.V., Sacco S.R.L, DSM-Firmenich AG, Lallemand Inc., THT S.A., Chr. Hansen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Starter Culture Market Strategic Shifts
Bioprocess automation and strain-level digital traceability are compressing quality assurance cycles while expanding the addressable market for precision-cultured ingredients beyond conventional dairy.
Genome-edited phage resistance is absorbing development resources across leading culture suppliers, with CRISPR-Cas systems enabling targeted modification of Lactococcus lactis phage receptor sites. Artisan and industrial cheese manufacturers in France and the Netherlands are piloting these strains under controlled regulatory exemptions. The technology is absorbing regulatory uncertainty as EFSA and FDA deliberate on edited-organism classifications, freezing some commercialization timelines.
EFSA's evolving qualified presumption of safety assessment criteria for novel strains is extending documentation requirements for whole-genome sequencing and toxicological screening. This compresses development pipelines for culture innovators while elevating compliance costs. Probiotic-positioned cultures bridging into supplement classifications face the steepest scrutiny, with ANSM in France and BfArM in Germany adding pharmaceutical-grade oversight layers.
Service-based contracting is displacing spot purchasing for industrial-scale culture procurement, with dairy processors favoring suppliers guaranteeing viability through shelf life. This concentrates procurement relationships around fermentation infrastructure owners capable of real-time quality monitoring. The shift is most visible in Germany and the United States, where large cooperatives and private-label manufacturers negotiate multi-year supply agreements bundling technical support with strain supply.
Global Starter Culture Market Segmentation
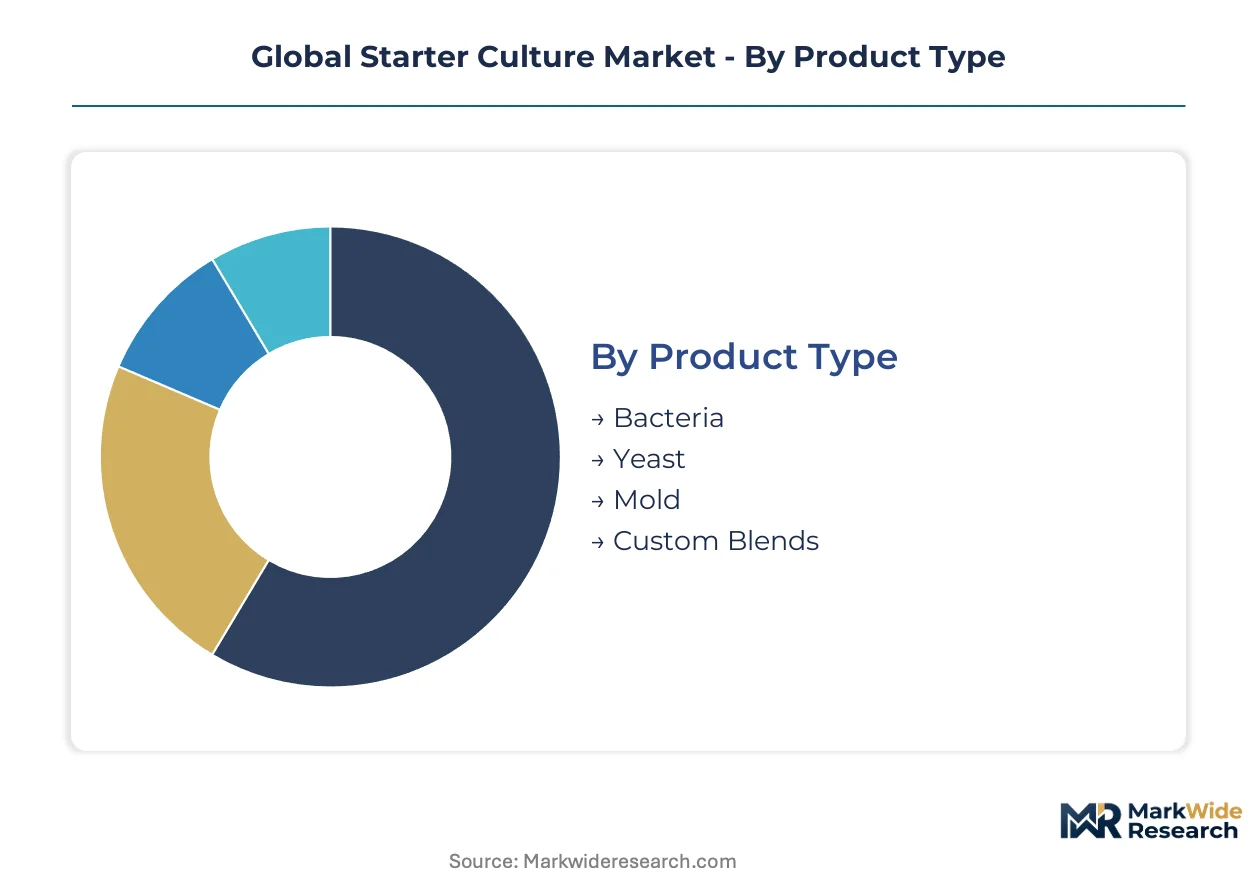
Starter culture procurement decisions hinge on matching microbial functionality to processing constraints. Dairy manufacturers prioritize phage resistance and acidification kinetics, while beverage formulators optimize for flavor compound generation under shortened fermentation windows.
Product Type:
Upgrade cycles accelerate as EFSA qualified presumption of safety assessments force replacement of legacy strains with validated alternatives, compressing development timelines for culture developers.
- Bacteria:Defined strains of Lactococcus lactis, Lactobacillus delbrueckii, and Streptococcus thermophilus dominate cheese and yogurt manufacture. German and French dairy cooperatives concentrate procurement here, driven by EFSA strain safety requirements that elevate documentation burdens for novel entries.
- Custom Blends:Processor-specific cocktails combine multiple strains optimized for local phage environments and targeted flavor profiles. United States industrial cheese plants are expanding adoption fastest, seeking rotation protocols that reduce production interruption risks.
- Yeast:Saccharomyces cerevisiae and Kluyveromyces marxianus preparations serve alcoholic fermentation and specific dairy applications like kefir.
- Mold:Penicillium roqueforti and Penicillium camemberti strains enable surface-ripened and blue-veined cheese categories.
Bacteria sits at the top of the volume ranking, with custom blends climbing the fastest.
End User:
Cost tier differentiation separates commodity fermentation inputs from clinically validated probiotic strains commanding formulation premiums.
- Dairy:Cheese, yogurt, and fermented milk production consumes the majority of industrial culture volumes. German manufacturers anchor European demand, while United States cooperatives drive North American procurement through multi-year service contracts bundling technical support with strain supply.
- Beverages:Kefir, kombucha, and functional fermented drinks require tailored acidification profiles and carbonation control. French and Dutch beverage manufacturers are piloting genome-edited phage-resistant strains under controlled regulatory exemptions, though EFSA deliberations freeze some commercialization timelines.
- Bakery:Sourdough fermentation relies on defined lactobacilli-yeast consortia for consistent rise and flavor development.
- Confectionery:Limited applications center on cocoa fermentation and specific flavor biogenesis requirements.
Dairy commands the steepest margin pools, with beverages gaining share fastest as functional positioning expands.
Technology:
Application requirements dictate preservation method selection, balancing viability maintenance against handling convenience and storage economics.
- Freeze-drying:Lyophilization delivers extended shelf stability and ambient storage logistics, though electricity intensity compresses margins where regional power costs spike. German and United States culture suppliers favor this method for industrial-scale dairy contracts.
- Liquid Culture:Fresh, high-viability preparations enable direct vat inoculation with minimal rehydration protocols. French artisan cheese manufacturers concentrate demand here, prioritizing flavor complexity over extended distribution reach.
- Fermentation:Bulk propagation systems serve large integrated dairy processors with captive culture production capabilities.
- Spray-drying:Lower-cost preservation suits applications where immediate viability is less critical than powder handling convenience.
Freeze-drying dominates value capture, with liquid culture expanding most quickly among premium positioning strategies.
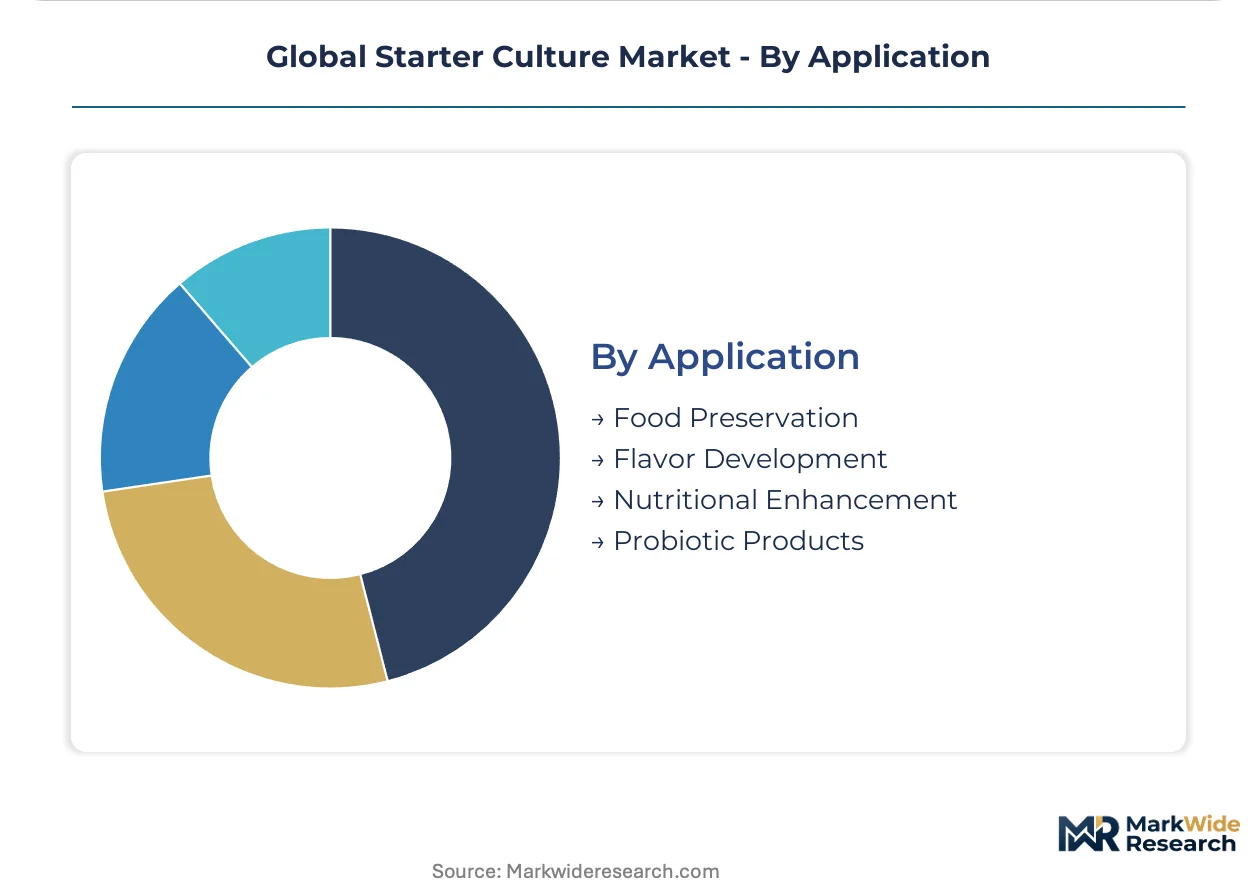
Application:
Margin structure stratifies sharply between commodity preservation functions and health-claim-supported positioning requiring clinical validation.
- Probiotic Products:Strains with documented efficacy in digestive or immune health support command formulation premiums and face pharmaceutical-grade oversight when bridging into supplements. ANSM in France and BfArM in Germany add regulatory layers that extend development cycles.
- Flavor Development:Diacetyl, acetoin, and ester-producing strains enable differentiated sensory profiles in cheese and fermented beverages. United States private-label manufacturers are concentrating procurement here as they compete with established brands.
- Food Preservation:Acidification for shelf stability and pathogen inhibition remains the foundational use case across dairy categories.
- Nutritional Enhancement:Vitamin-producing strains and bioavailability-improving fermentation processes serve fortified product positioning.
Food preservation anchors volume throughput, with probiotic products exhibiting the steepest expansion trajectory as clinical validation barriers protect margin structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's dairy cooperative infrastructure generates denser culture procurement volumes than France's fragmented artisan base, while the United States industrial cheese sector drives North American contract structuring toward multi-year service bundles.
Germany
Dairy cooperatives in Bavaria and Lower Saxony anchor European demand for phage-resistant bacterial strains. EFSA's qualified presumption of safety assessments force processors to document whole-genome sequencing for every novel culture introduction. The Münsterland cheese cluster concentrates industrial-scale yogurt and fresh cheese manufacturing, driving adoption of automated dosing systems integrated with supplier viability monitoring.
United States
Industrial cheese plants in Wisconsin and California prioritize rotation protocols combining multiple strain cocktails against persistent phage pressure. FDA GRAS notifications govern culture introductions, though divergence from EFSA genome-editing classifications complicates cross-Atlantic product registration. The Upper Midwest dairy belt generates concentrated demand for freeze-dried preparations suited to extended distribution networks.
France
Artisan cheese manufacturers in Auvergne-Rhône-Alpes and Normandy favor liquid culture formats preserving flavor complexity over shelf stability. ANSM oversight tightens when cultures bridge into probiotic supplement classifications, extending pharmaceutical-grade validation timelines. Roquefort-sur-Soulzon maintains specialized Penicillium roqueforti propagation traditions that resist full industrial standardization.
India
Dairy cooperatives in Gujarat and Maharashtra expand culture adoption as FSSAI modernization streamlines strain import and domestic manufacturing pathways. Updated food safety standards create regulatory clarity previously absent in South Asian microbial input markets. The Anand milk federation cluster experiments with tailored thermophilic cultures suited to buffalo milk fermentation profiles.
Netherlands
Beverage manufacturers in Noord-Brabant pilot genome-edited phage-resistant strains under controlled regulatory exemptions for functional fermented drinks. ECHA REACH frameworks govern chemical safety in culture production inputs, while EFSA deliberations on edited-organism classifications freeze some commercialization timelines. The Eindhoven-Tilburg corridor concentrates precision fermentation infrastructure development.
Global Starter Culture Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated fermentation infrastructure owners capturing recurring service contracts while smaller blenders serve spot-market artisan demand. The supplier base concentrates around three strategic archetypes: global yeast and bacteria conglomerates with captive distribution networks, mid-scale custom blenders optimizing regional phage environments, and precision fermentation technology licensors enabling metabolite production. Consolidation pressure intensifies through backward integration into strain maintenance capabilities and geographic expansion via acquisition of national distribution licenses.
Within the integrated infrastructure tier, Lesaffre anchors long-term supply relationships through global fermentation assets, while Novonesis A/S occupies a position combining specialized enzyme-culture combinations. Lallemand Inc. exemplifies North American channel control through integrated production and distribution reach. These three represent distinct competitive vectors: geographic coverage breadth, formulation complexity reduction, and regional channel dominance.
| Leading Market Players |
|---|
| Lesaffre |
| International Flavors & Fragrances |
| Novonesis A/S |
| CSK Food Enrichment B.V. |
| Sacco S.R.L |
| DSM-Firmenich AG |
| Lallemand Inc. |
| THT S.A. |
| Chr. Hansen |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon pricing mechanisms gate qualified supply and premium-tier pricing access for starter culture manufacturers, compressing margins for freeze-drying operations in high-electricity-cost zones while rewarding suppliers with renewable energy certificates. Buyers in Germany and France face tiered access costs based on strain documentation depth, with EFSA-qualified presumption of safety certifications commanding substantial formulation premiums over commodity fermentation inputs.
Pricing Analysis
Capacity additions in India are reshaping price floors for thermophilic cultures serving buffalo milk fermentation, pressuring legacy European suppliers. Three-tier pricing structure across premium, standard, and economy levels separates clinically validated probiotic strains from industrial preservation cultures and commodity spot-market blends. Price differentiation hinges on EFSA documentation completeness and phage resistance certification tier. Cost compression in standard-tier freeze-dried preparations is intensifying because regional electricity markets expose lyophilization operations to carbon pricing pass-through. Small-scale artisan dairy processors in France exhibit highest price sensitivity, while German cooperatives negotiating multi-year service contracts demonstrate lowest sensitivity due to bundled technical support value.
Supply Chain Analysis
ISO 17025 accreditation requirements gate supply chain participation, extending validation timelines for new culture developers. Manufacturing concentrates in Germany, France, and the United States, with each hub serving distinct regulatory filing pathways. Raw material sourcing draws from whey permeate suppliers in the Netherlands, yeast extract producers in Germany, and specialized growth media formulators in the United States. Single-source vulnerability in CRISPR-edited strain propagation creates concentration risk as EFSA and FDA deliberations freeze commercialization timelines for genome-edited lines. Distribution runs through integrated fermentation infrastructure owners bundling viability monitoring with strain supply, displacing spot-market procurement for industrial-scale dairy processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU regulatory compliance costs and Indian FSSAI modernization pathways, with strain documentation burdens in Germany and France creating 18-24 month entry delays that domestic Indian manufacturers can compress through updated food safety standards.
For Market Incumbents: Hedge phage resistance obsolescence risk by acquiring CRISPR-edited strain portfolios before EFSA classification clarity emerges. Backward integration into captive whey permeate processing insulates margin structures from agricultural commodity volatility. Lesaffre and Novonesis A/S demonstrate this through fermentation infrastructure ownership that locks in multi-year service contracts with industrial dairy processors. For New Entrants and Emerging Players: Genome-edited phage resistance platforms offer technology-first wedge positioning for beverage manufacturers in the Netherlands piloting controlled regulatory exemptions. Plant-based fermentation applications for dairy-alternative yogurt present the most penetrable white space, with acidification profile tailoring requirements unmet by incumbent strain portfolios. Direct technical support bundling with strain supply mimics incumbent service-contract structures without requiring captive fermentation assets. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale custom blenders because phage environment specialization creates local moats that resist commoditization. Long-term viability over a 5-10 year horizon favors targets with ISO 17025 accreditation and established rotation protocol design capabilities. The signal to watch is EFSA's final genome-edited organism classification, which would unlock commercialization timelines and revalue edited-strain portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Growth Media Production | Captive whey permeate and yeast extract supply insulates German manufacturers from agricultural input volatility. |
| Multi-Year Service Contract Expansion | Bundled viability monitoring and technical support locks in United States dairy cooperative procurement relationships. |
| Genome-Edited Strain Portfolio Acquisition | CRISPR-edited phage resistance capabilities position suppliers for post-EFSA-classification demand acceleration. |
| Plant-Based Fermentation Application Development | Tailored acidification profiles for dairy-alternative matrices open white space beyond traditional animal milk channels. |
| FSSAI Compliance Infrastructure Buildout | Domestic Indian manufacturing capabilities capture import substitution policy tailwinds in Gujarat and Maharashtra cooperatives. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dairy plant microbiologists, culture supplier technical directors, EFSA regulatory affairs specialists, and Indian FSSAI compliance officers with secondary validation. Bottom-up and top-down triangulation anchored market sizing, drawing from EFSA qualified presumption of safety filings, FSSAI strain import registrations, German dairy cooperative procurement disclosures, and United States FDA GRAS notification databases.
Historical reference periods established baseline strain adoption rates and pricing trajectories across the projection horizon. Segmentation modeling incorporated product type, application, preservation technology, and regional regulatory cluster dimensions. CAGRs were derived from strain volume throughput analysis and value-per-unit progression tied to documentation tier. Forecast inputs included phage pressure incidence rates in industrial cheese plants and electricity cost differentials affecting freeze-drying economics.
The model holds under stable EFSA and FDA regulatory classification frameworks; deviation in genome-edited organism policy triggers would shift commercialization timelines and strain portfolio valuations. Forecasts reflect documented assumptions regarding phage resistance adoption curves and service-contract penetration rates. A model refresh is warranted upon material change in EU carbon pricing mechanism scope or FSSAI enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Bacterial Antigens Market
Industrial Microbiology
Microbial Identification Panels Market
Industrial Microbiology
Industrial Microbiology Market
Industrial Microbiology
Microbial Coagulants Market
Industrial Microbiology
Microbial Therapeutic Products Market
Industrial Microbiology
Microbial Rennet Market
Industrial Microbiology
Galactosidase Market
Industrial Microbiology
Molecular Microbiology Market
Industrial Microbiology
Middle East Feed Probiotics Market
Industrial Microbiology
Freeze-Dried Microbial Food Culture Market
Industrial Microbiology
Global Microbial Testing Market
Industrial Microbiology
Europe Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Global Microbial Identification Market
Industrial Microbiology
Lactic Acid Bacteria Market
Industrial Microbiology
Benzoate-Free Enzymes Market
Industrial Microbiology
Microbiomes Market