
 China Feed Probiotics Market | 2026-2036
China Feed Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
China Feed Probiotics Market Analysis
Hebei Province is reconfiguring its feed additive manufacturing base with dedicated probiotic fermentation capacity. Cargill Inc anchors its North China operations through backward integration into microbial culture production. Chr Hansen A/S differentiates via thermotolerant strain libraries engineered for pelleted feed thermal stress. Lallemand Inc specializes in yeast-based direct-fed microbials calibrated for swine gut flora modulation.
Feed probiotics comprise live beneficial microorganisms—primarily lactic acid bacteria, Bacillus subtilis, and Saccharomyces cerevisiae—formulated at minimum viable counts of 10^6 to 10^9 CFU per gram to colonize the gastrointestinal tract and suppress pathogenic colonization in production animals. Multi-strain formulations command premium positioning due to synergistic colonization resistance and broader pH tolerance across ruminant foregut and monogastric environments. Aquaculture applications represent the fastest-expanding segment as shrimp and finfish producers replace antibiotic growth promoters with water-stable Bacillus blends. Synbiotics pairing probiotics with prebiotic substrates are capturing margin pools through differentiated efficacy claims in weaning piglet diets.
SAMR enforces feed additive registration under the Feed and Feed Additive Regulation, requiring strain-level safety documentation and shelf-stability validation for market authorization. BIS-equivalent national standards for viable count testing and contamination limits shape product quality benchmarks for domestic and imported formulations. China's dual carbon goals are pressuring fermentation facilities toward energy-efficient bioprocess design, altering capital allocation for new capacity. Stakeholders must monitor strain patent landscapes and regional feed mill consolidation patterns to anticipate distribution chokepoints and partnership requirements.
Market Dynamics
China's Ministry of Agriculture and Rural Affairs antibiotic reduction mandates are compressing feed formulation timelines and redirecting capital toward live microbial alternatives across Shandong and Guangdong poultry corridors.
Growth Catalysts
- Antibiotic Growth Promoter Bans:SAMR enforcement of feed additive registration requirements under the Feed and Feed Additive Regulation is compelling commercial layer and broiler operations to reformulate diets with Bacillus subtilis and lactic acid bacteria alternatives.
- Yangtze River Delta Manufacturing Concentration:Feed mill clustering across Jiangsu and Zhejiang provinces generates localized demand density that reduces probiotic distribution costs and accelerates technical service response times.
- Aquaculture Segment Expansion:Shrimp and finfish producers in Guangdong and Hainan are displacing antibiotic growth promoters with water-stable Bacillus blends, creating new viable count specifications for pelleted aquafeed applications.
Market Restraints
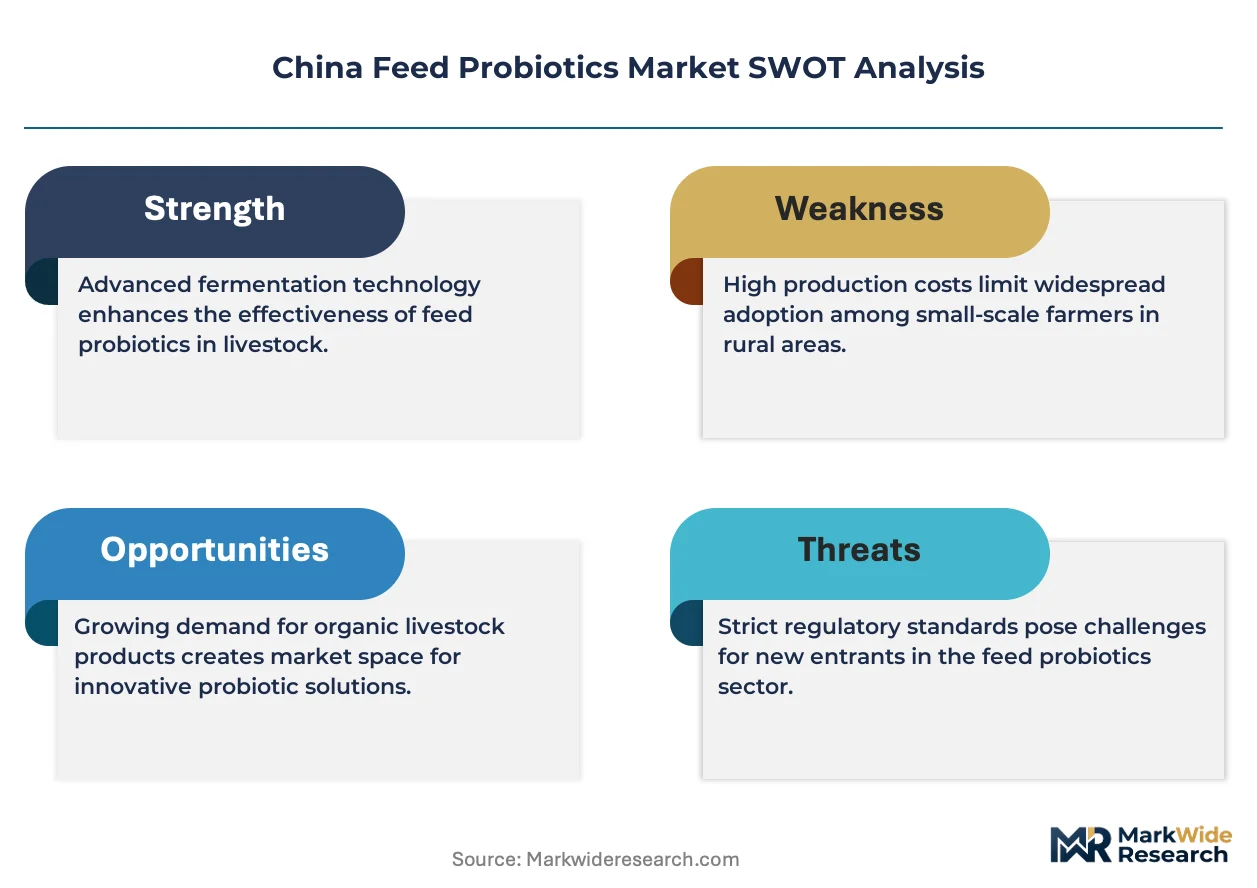
- Strain Patent Concentration:International microbial culture suppliers control thermotolerant strain libraries, limiting domestic fermentation facilities' access to pelleted feed-compatible formulations without licensing costs.
- Fermentation Energy Intensity:China's dual carbon goals are pressuring probiotic production facilities toward bioprocess redesign, elevating capital requirements for new capacity in Hebei and Shandong provinces.
- Shelf-Stability Validation Burden:SAMR requires strain-level safety documentation and extended viable count verification, extending product registration timelines for multi-strain formulations.
Strategic Opportunities
- Synbiotic Formulation White Space:Pairing probiotics with prebiotic substrates in weaning piglet diets commands differentiated positioning as sow farms in Sichuan and Hunan seek gut flora modulation beyond single-ingredient alternatives.
- North China Backward Integration:Dedicated probiotic fermentation capacity expansion in Hebei Province enables feed additive manufacturers to capture margin pools previously allocated to imported microbial cultures.
- Aquaculture Water Stability Standards:Emerging technical specifications for Bacillus viability in brackish water environments create first-mover positioning for strain developers serving South China shrimp producers.
Industry Challenges
- Multi-Strain Compatibility Expertise:Formulation chemists capable of optimizing synergistic colonization resistance across lactic acid bacteria and Bacillus combinations remain concentrated with international suppliers.
- Regional Feed Mill Consolidation Friction:Distribution partnerships require renegotiation as Yangtze River Delta manufacturing corridors consolidate, altering technical service coverage models for probiotic vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Feed Probiotics Market |
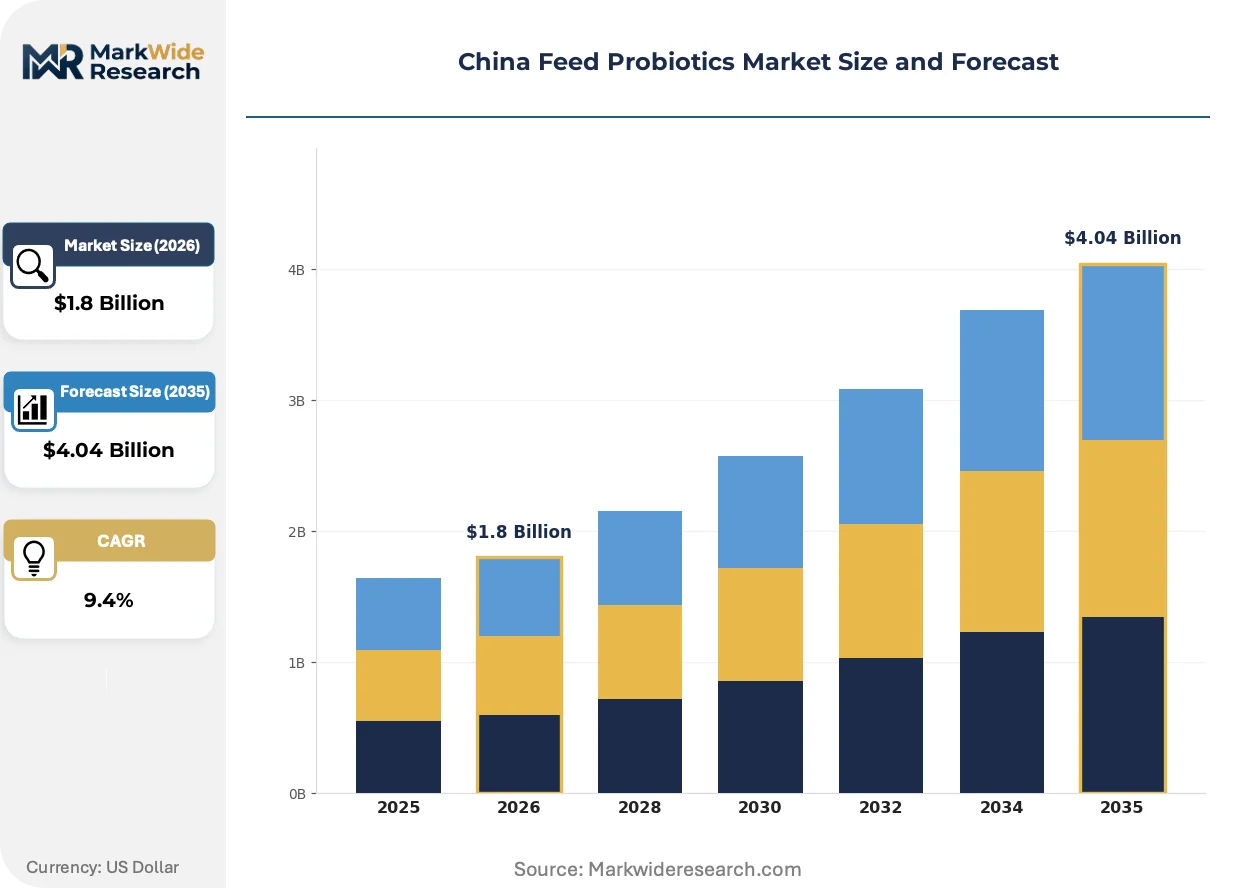
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Strain, Multi-Strain, Liquid Form, Powder Form Application: Poultry, Swine, Ruminants, Aquaculture Formulation: Probiotics Premix, Synbiotics, Direct-Fed Microbials, Feed Additives Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | DSM Nutritional Products AG, Cargill Inc, Evonik Industries AG, Chr Hansen A/S, Lallemand Inc, Adisseo, IFF (Danisco Animal Nutrition), Kemin Industries, Kerry Group PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Feed Probiotics Market Emerging Trajectories
Live microbial formulation science is advancing through strain engineering, regulatory compliance automation, and procurement model restructuring across China's animal production value chain.
Encapsulation technology for thermotolerant probiotic delivery is hybridizing conventional feed pelleting processes with microbial viability preservation. Commercial poultry operations in Guangdong are adopting lipid-matrix Bacillus formulations at accelerated rates. This hybridization is compressing the performance gap between antibiotic growth promoters and live microbial alternatives in high-temperature feed processing environments.
SAMR's GB standards for viable count testing and contamination limits are reshaping quality assurance protocols across domestic and imported formulation categories. Feed additive manufacturers must now implement strain-level traceability systems to satisfy registration renewal requirements. Multi-strain synbiotic products face the most intensive documentation burdens, driving consolidation among smaller fermentation facilities unable to absorb compliance costs.
Direct contracting between probiotic suppliers and integrated poultry operations is displacing traditional distributor-mediated procurement in Shandong Province. Large layer and broiler producers are unbundling technical service from product supply, selecting microbial culture vendors based on strain performance data rather than historical relationships. This behavioral shift is most visible among vertically integrated operations with captive feed milling capacity.
China Feed Probiotics Market Segmentation
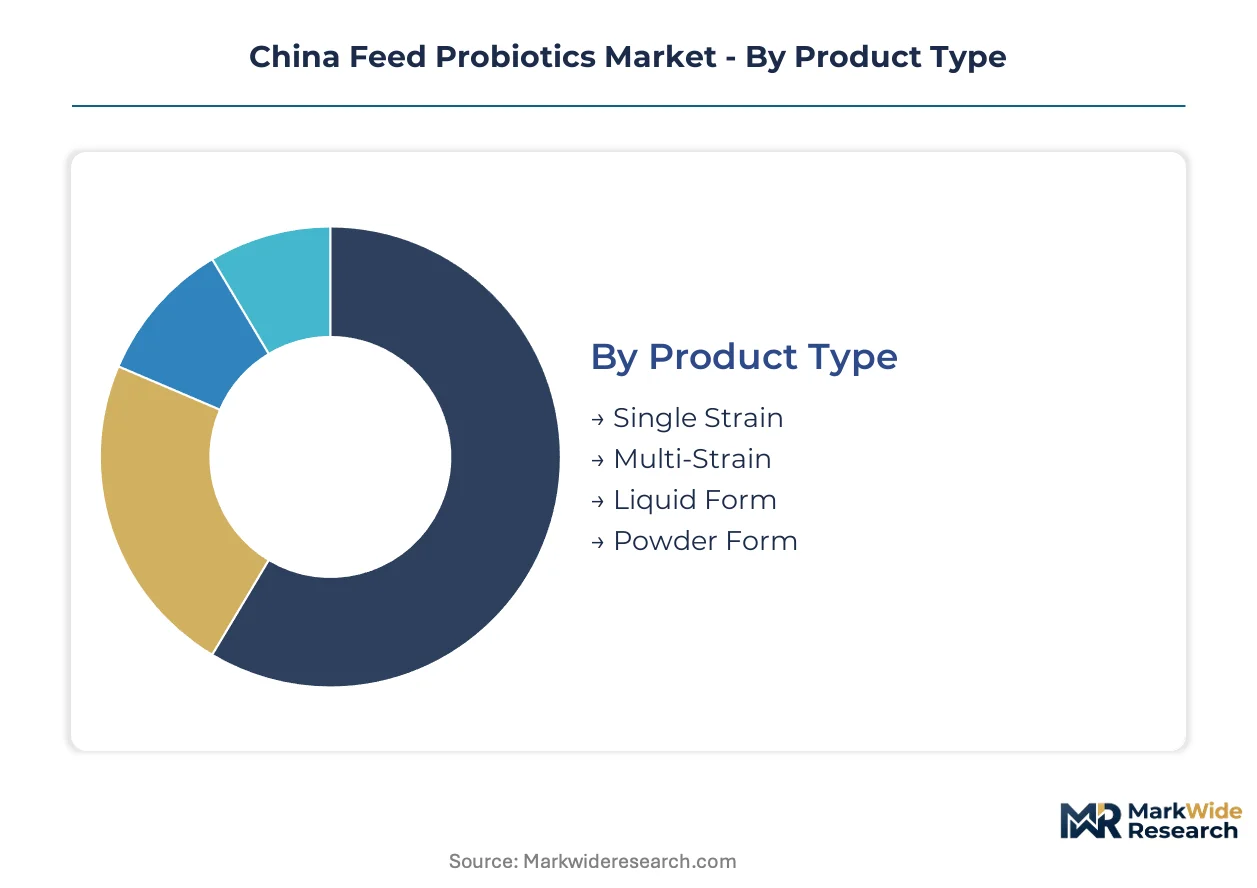
Feed probiotic suppliers in China calibrate technical service intensity and strain customization depth based on segment-specific viability requirements and formulation complexity. Segmentation reveals where margin pools concentrate and which customer relationships demand captive fermentation capacity.
Product Type:
After-sales service intensity escalates with viable count stability demands, as thermal stress during pelleting and extended shelf storage create performance failure modes requiring technical intervention.
- Single Strain:Comprises isolated Bacillus subtilis or lactic acid bacteria cultures standardized at 10^6 to 10^9 CFU per gram with defined colonization kinetics. Layer operations across Shandong prefer single-strain Bacillus for cost-predictable gut flora modulation in high-volume broiler diets. SAMR registration requirements for strain-level documentation compress margins for undifferentiated offerings.
- Multi-Strain:Combines complementary genera—typically lactic acid bacteria with Bacillus spores—to exploit synergistic colonization resistance across pH gradients. Guangdong poultry integrators specify multi-strain cocktails for antibiotic-free transition programs, accepting premium positioning for broader gastrointestinal coverage. Formulation chemists capable of optimizing strain compatibility remain concentrated with international suppliers, elevating technical service costs.
- Liquid Form:Aqueous suspensions requiring refrigerated distribution chains and shorter shelf windows.
- Powder Form:Lyophilized or spray-dried preparations with extended stability for ambient storage.
Multi-Strain holds the largest share; momentum sits with Powder Form as thermal tolerance engineering improves.
Application:
Customer procurement sophistication varies dramatically across animal species, with aquaculture operations demanding water-stability specifications absent from terrestrial applications.
- Poultry:Broiler and layer diets constitute the volume anchor, with Guangdong and Shandong integrators driving Bacillus adoption for coccidiosis management alternatives. Direct contracting between probiotic suppliers and vertically integrated operations is displacing distributor-mediated procurement.
- Aquaculture:Shrimp and finfish producers in Hainan and Guangdong specify water-stable Bacillus blends with brackish environment viability, creating first-mover positioning for strain developers. This segment expands most quickly as antibiotic growth promoter displacement accelerates in marine hatcheries.
- Swine:Sow farms in Sichuan and Hunan prioritize gut flora modulation during weaning stress windows.
- Ruminants:Dairy and beef operations in Inner Mongolia apply probiotics for foregut pH stabilization.
Poultry dominates volume; aquaculture climbs the fastest on regulatory displacement of antibiotics.
Formulation:
Margin structure stratifies by ingredient complexity, with synbiotics commanding premium positioning through differentiated efficacy claims.
- Synbiotics:Pair live microorganisms with prebiotic substrates—typically fructooligosaccharides or mannanoligosaccharides—to enhance colonization persistence. Weaning piglet diets in Hunan represent the primary demand concentration, as producers seek performance differentiation beyond single-ingredient alternatives.
- Direct-Fed Microbials:Live cultures administered without carrier premix, requiring precise dosing equipment and handler training.
- Probiotics Premix:Concentrated formulations diluted into complete feeds at manufacturing stage.
- Feed Additives:Broad regulatory category encompassing probiotics alongside enzymes and acidifiers.
Synbiotics capture premium positioning; Direct-Fed Microbials gain share among operations with captive feed milling.
Distribution Channel:
Channel selection reflects customer scale and technical service requirements, with large integrators bypassing traditional intermediaries.
- Direct Sales:Probiotic suppliers contract directly with integrated poultry and swine operations, unbundling technical service from product supply. Shandong layer producers now select vendors based on strain performance data rather than historical distributor relationships.
- Distributors:Regional feed additive specialists maintain coverage of fragmented sow farms and independent aquaculture operations.
- Online Retail:Emerging channel for smaller livestock operations purchasing standardized single-strain products.
- Offline Retail:Agricultural supply cooperatives serving backyard and semi-commercial producers.
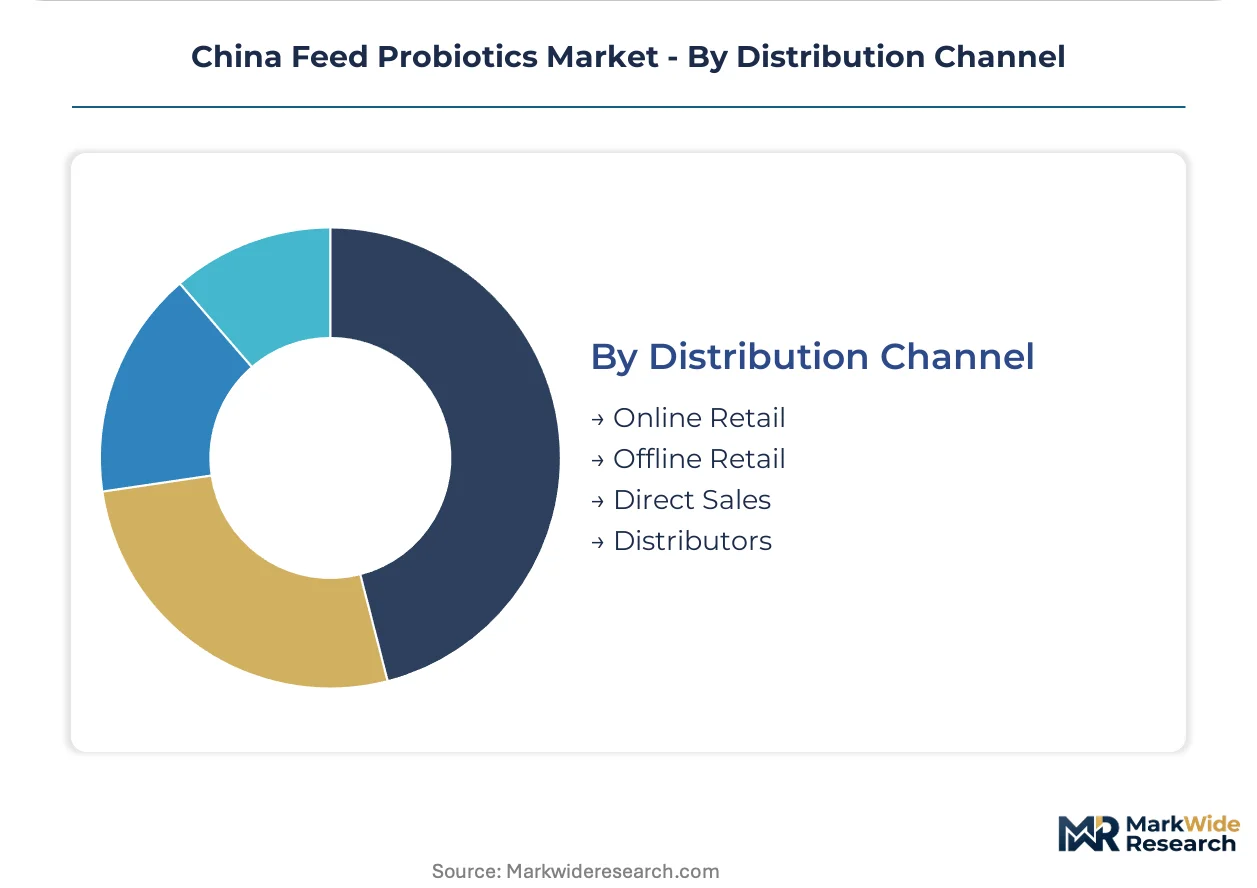
Direct Sales holds the largest share; momentum sits with Distributors as Yangtze River Delta feed mill consolidation reshapes partnership requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed probiotic manufacturing concentrates in provincial corridors where antibiotic reduction mandates intersect with dense livestock production. SAMR registration requirements and dual carbon goals are reshaping capacity placement decisions across major feed manufacturing zones.
Shandong Province
Commercial layer and broiler operations drive Bacillus subtilis adoption at scale. The Ministry of Agriculture and Rural Affairs antibiotic reduction mandates compress formulation timelines for integrators. Cargill Inc anchors North China operations through backward integration into microbial culture production in dedicated fermentation facilities.
Guangdong Province
Poultry integrators specify multi-strain cocktails for antibiotic-free transition programs in broiler and layer diets. SAMR enforces feed additive registration under the Feed and Feed Additive Regulation with strain-level documentation requirements. Pearl River Delta manufacturing clusters generate localized demand density that reduces distribution costs.
Jiangsu Province
Yangtze River Delta feed mill clustering creates technical service intensity around viable count stability. GB standards for viable count testing reshape quality assurance protocols across domestic formulations. Nanjing and Suzhou manufacturing corridors consolidate, altering partnership requirements for probiotic vendors.
Sichuan Province
Sow farms prioritize gut flora modulation during weaning stress windows with synbiotic formulations. Provincial agricultural policies support antibiotic growth promoter displacement in swine operations. Chengdu-Chongqing economic circle hosts specialized technical service teams for piglet diet optimization.
Hainan Province
Shrimp and finfish producers displace antibiotic growth promoters with water-stable Bacillus blends in marine hatcheries. SAMR registration requirements extend to aquaculture-specific viable count specifications. Sanya and Haikou processing zones drive fastest-expanding segment growth in feed probiotic applications.
China Feed Probiotics Market Vendor Landscape
Multinational culture suppliers and domestic fermentation specialists split the market across strain licensing and captive manufacturing vectors. The structure tilts toward tiered consolidation where thermotolerant strain libraries command premium positioning. Three archetypes dominate: international microbial culture houses with patent-protected strain banks, domestic feed additive manufacturers building backward-integrated fermentation capacity, and aquaculture-focused specialists engineering water-stable formulations. Competitive moves concentrate on M&A for strain portfolio expansion and greenfield fermentation capacity in Hebei and Shandong provinces.
Among international culture houses, Chr Hansen A/S and Lallemand Inc exemplify the premium-tier archetype built on proprietary strain libraries. Cargill Inc anchors the integrated processor segment with captive fermentation investments. These three occupy positions spanning thermotolerant Bacillus engineering, yeast-based direct-fed microbials, and North China manufacturing scale respectively.
| Leading Market Players |
|---|
| DSM Nutritional Products AG |
| Cargill Inc |
| Evonik Industries AG |
| Chr Hansen A/S |
| Lallemand Inc |
| Adisseo |
| IFF (Danisco Animal Nutrition) |
| Kemin Industries |
| Kerry Group PLC |
| Others |
Supply Flow & Price Mechanics
Hebei Province's dedicated probiotic fermentation capacity anchors upstream supply concentration, directing margin pools toward strain-level technical service and SAMR compliance documentation downstream. SAMR's Feed and Feed Additive Regulation dictates the pricing tier structure across China's feed probiotic market, separating multi-strain synbiotic formulations with strain-level safety documentation from commodity single-strain Bacillus alternatives. Price differentiation hinges on thermotolerance certification for pelleted feed applications and after-sales technical intensity for viable count stability. Cost compression in standard-tier single-strain products is intensifying as domestic fermentation facilities expand capacity. Sow farms in Sichuan and Hunan exhibit highest price sensitivity due to fragmented procurement scale, while Guangdong poultry integrators show lowest sensitivity given antibiotic-free transition program premiums.
Pricing Analysis
SAMR's Feed and Feed Additive Regulation dictates the pricing tier structure across China's feed probiotic market, separating multi-strain synbiotic formulations with strain-level safety documentation from commodity single-strain Bacillus alternatives. Price differentiation hinges on thermotolerance certification for pelleted feed applications and after-sales technical intensity for viable count stability. Cost compression in standard-tier single-strain products is intensifying as domestic fermentation facilities expand capacity. Sow farms in Sichuan and Hunan exhibit highest price sensitivity due to fragmented procurement scale, while Guangdong poultry integrators show lowest sensitivity given antibiotic-free transition program premiums.
Supply Chain Analysis
Chr Hansen A/S and Lallemand Inc hold core thermotolerant strain library capacity through proprietary microbial culture collections. Supply draws from Denmark, Canada, and domestic Hebei fermentation corridors for Bacillus subtilis, lactic acid bacteria, and Saccharomyces cerevisiae seed stocks. Single-source vulnerability concentrates in international strain licensing for pelleted feed-compatible formulations. Distribution runs through direct contracting with integrated poultry operations in Shandong and Yangtze River Delta feed mill clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for viable count stability monitoring represent a service-attach opportunity expanding faster than base probiotic product sales as SAMR registration requirements intensify.
For Market Incumbents: Harden strain patent defenses against domestic fermentation facilities seeking thermotolerant Bacillus licensing alternatives. Expand captive fermentation capacity in Hebei Province to capture margin pools from imported microbial cultures. Prioritize multi-strain compatibility expertise retention as formulation chemist talent concentrates with international suppliers. For New Entrants and Emerging Players: Hainan Province's shrimp hatchery corridor offers underpenetrated white space for water-stable Bacillus blends with brackish environment viability specifications. Target weaning piglet synbiotic formulations in Hunan sow farms seeking gut flora modulation beyond single-ingredient alternatives. Lead with aquaculture-specific technical service teams rather than terrestrial feed mill coverage. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed domestic fermentation specialists building backward-integrated capacity in North China. Five-to-ten-year viability favors strain library acquisitions over undifferentiated manufacturing scale. Watch for SAMR registration renewal waves as consolidation pressure mounts on smaller facilities unable to absorb compliance documentation costs.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Acquisition | Secures thermotolerant Bacillus IP for pelleted feed thermal stress environments. |
| Hebei Fermentation Capacity Expansion | Captures margin pools from imported microbial cultures in North China corridor. |
| SAMR Registration Automation | Compresses strain-level safety documentation timelines for multi-strain formulations. |
| Aquaculture Technical Service Buildout | Addresses water-stability specifications for Hainan shrimp hatchery demand. |
| Direct Contracting with Integrators | Displaces distributor-mediated procurement in Shandong poultry operations. |
Methodological Framework
A spread of perspectives from feed formulation chemists, SAMR regulatory affairs specialists, Yangtze River Delta feed mill procurement managers, and Guangdong poultry integrator nutritionists converged on the working assumptions. Secondary validation drew from SAMR feed additive registration databases, Ministry of Agriculture and Rural Affairs policy circulars, customs import records for microbial cultures, and GB standards documentation. Bottom-up strain-level demand modeling triangulated against top-down fermentation capacity assessments.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling poultry, aquaculture, swine, and ruminant application segments alongside single-strain, multi-strain, and synbiotic product categories. CAGRs derived from segment-level viable count demand trajectories and fermentation capacity expansion pipelines. Key inputs included antibiotic growth promoter displacement timelines and dual carbon goals pressure on bioprocess energy intensity.
The forecast holds incumbent behavior within observed patterns; aggressive strain patent litigation or accelerated SAMR enforcement tightening would shift outcomes. Quarterly review of SAMR registration approval velocities and Hebei Province fermentation capacity utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Mycorrhiza-Based Biofertilizer Market
Bio-Agriculture
Plant Based Biosurfactants Market
Bio-Agriculture
Hydroponics Market
Bio-Agriculture
Italy Biopesticides Market
Bio-Agriculture
United States Bio-Fungicide Market
Bio-Agriculture
China Biocontrol Agents Market
Bio-Agriculture
United States Biofertilizer Market
Bio-Agriculture
China Biofertilizer Market
Bio-Agriculture
Africa Biofertilizer Market
Bio-Agriculture
Canada Biofertilizers Market
Bio-Agriculture
Rhizobium-Based Biofertilizer Market
Bio-Agriculture
Europe Feed Probiotics Market
Bio-Agriculture
Middle East and Africa Biofertilizers Market
Bio-Agriculture
North America Bioherbicides Market
Bio-Agriculture
Bio-Seeds Market
Bio-Agriculture
Indonesia Biopesticides Market