
 Microbial Rennet Market | 2026-2036
Microbial Rennet Market Size, Share, and Industry Trends Forecast 2026-2036
Microbial Rennet Market Outlook
Multi-source enzyme procurement is broadening across dairy ingredient supply chains. Novozymes leverages its fermentation platform to deliver consistent recombinant chymosin batches at industrial scale. Chr. Hansen anchors European supply through specialized cultures and coagulant portfolios tailored to protected designation of origin requirements. Kerry Group competes by extending its enzyme distribution network across food processing customers in North America and Asia-Pacific.
Microbial rennet comprises coagulating enzymes—primarily chymosin produced via fermentation of genetically modified microorganisms such as Aspergillus niger or Kluyveromyces lactis—that replace traditional animal-derived calf rennet in curd formation. The enzyme typically achieves 90-95% protein specificity toward kappa-casein, enabling controlled milk clotting at temperatures between 30-35°C for cheese manufacturing. Liquid rennet dominates commercial volumes due to its ease of dosing integration in automated cheese vats, while powdered rennet occupies niche artisanal segments where extended shelf stability matters. Tablet rennet sustains hobbyist and small-batch producer demand through precise unit dosing, though this channel generates thinner margin pools compared to bulk liquid supply contracts.
FDA oversight of food enzyme GRAS determinations shapes microbial rennet market access in the United States, while EFSA evaluations under EU food additive regulations govern European commercialization pathways. ISO 11298 certification requirements for enzyme purity and absence of antibiotic residues influence supplier qualification standards across export-oriented dairy processors. Stakeholders must monitor evolving vegetarian certification protocols from private labels and retail chains, as these specifications increasingly override baseline regulatory compliance in contract negotiations.
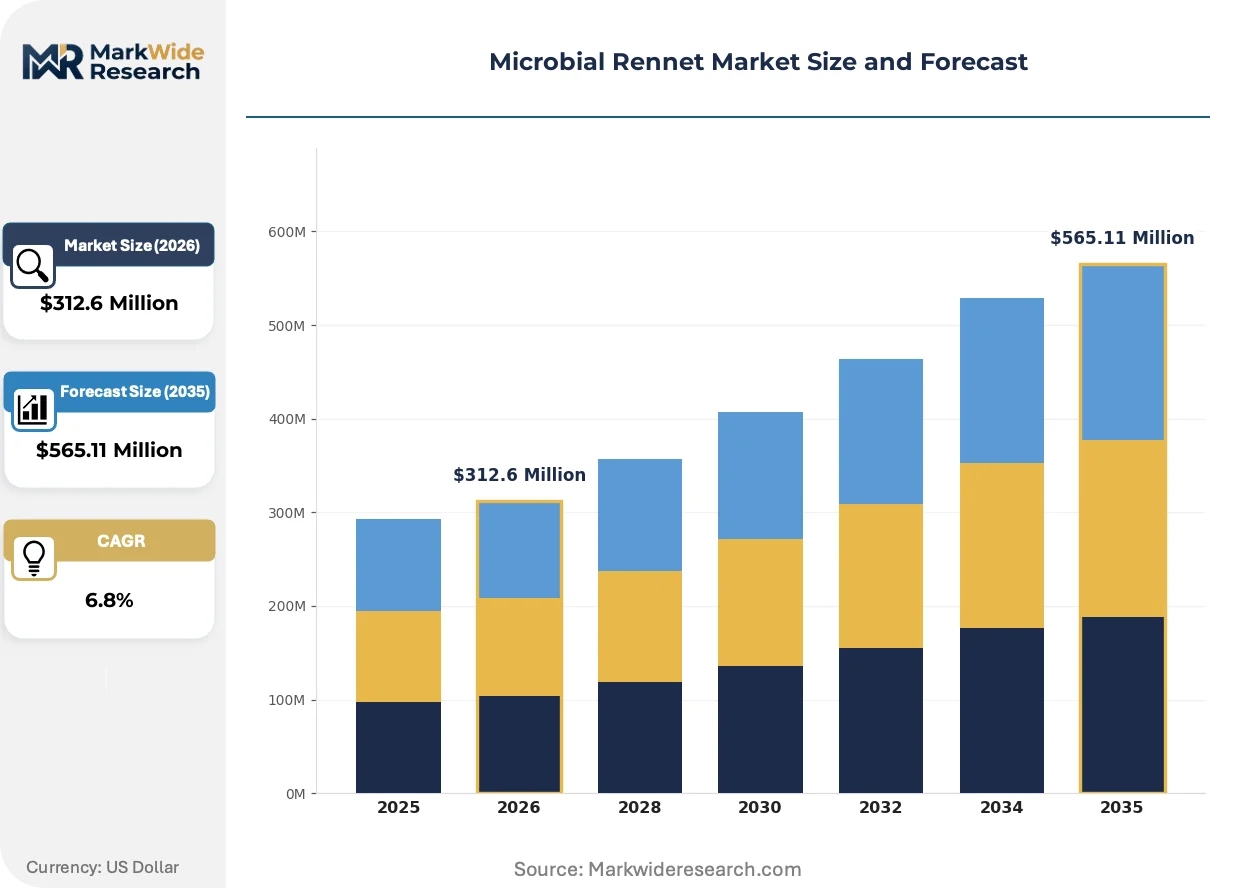
Market Dynamics
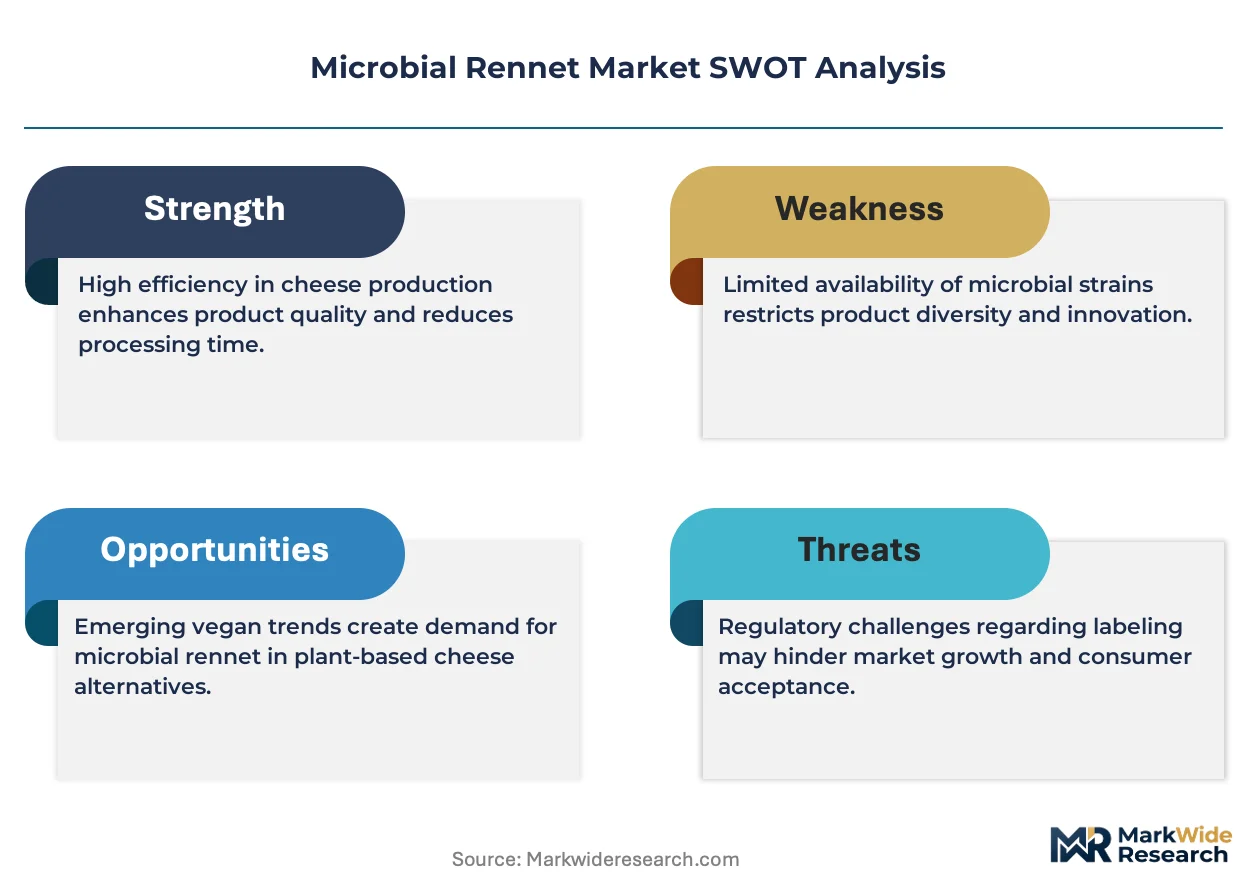
Fermentation-derived chymosin engineering is compressing the performance gap between microbial and animal rennet, forcing traditional calf rennet suppliers to defend their position in protected designation of origin cheese segments.
Growth Catalysts
- Vegetarian Label Mandates:Retail chains across Germany and France now require vegetarian certification for shelf placement, pulling microbial rennet into premium cheese lines.
- EFSA Additive Evaluations:Streamlined enzyme approval pathways under EU food additive regulations accelerate commercialization timelines for new fermentation-derived coagulants.
- Kluyveromyces lactis Platforms:Improved recombinant chymosin yields from this yeast host reduce production costs and enable consistent industrial-scale batching.
Market Restraints
- Feedstock Volatility:Glucose and yeast extract prices fluctuate with agricultural commodity cycles, squeezing margins for fermentation-based enzyme producers.
- PDO Cheese Barriers:Traditional protected designation of origin specifications in Italy and Spain explicitly require animal rennet, blocking microbial alternatives from heritage product categories.
- Enzyme Purity Certification:ISO 11298 antibiotic residue testing adds qualification costs that disadvantage smaller fermentation operators against established suppliers.
Strategic Opportunities
- Plant-Based Dairy Expansion:Precision fermentation chymosin enables clean-label vegan cheese curd formation, opening supply relationships with oat and almond milk processors.
- India FSSAI Enzyme Framework:Formalized food enzyme regulations create first-mover positioning for microbial rennet in a market historically dependent on imported animal rennet.
- Tablet-to-Liquid Conversion:Artisanal producers in the United States upgrade from hobbyist tablet dosing to automated liquid systems, expanding contract volumes for bulk suppliers.
Industry Challenges
- Fermentation Scale-Up Expertise:Qualified bioprocess engineers command premium compensation, constraining capacity expansion timelines for mid-tier enzyme manufacturers.
- GRAS Determination Delays:FDA notification timelines for novel recombinant strains extend market entry schedules, freezing investment decisions for developers targeting US dairy processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbial Rennet Market |
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Rennet, Powdered Rennet, Granular Rennet, Tablet Rennet Application: Cheese Production, Yogurt Manufacturing, Dietary Supplements, Confectionery End User: Dairy Industry, Food Processing, Restaurants, Retail Chains Distribution Channel: Online Retail, Supermarkets, Direct Sales, Wholesale |
| Companies Covered | International Flavors & Fragrances Inc., Novozymes, Koninklijke DSM, Sacco SRL, Fonterra Co-operative Group, Chr. Hansen, Kerry Group, Ginkgo BioWorks, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbial Rennet Market Strategic Shifts
Bioprocess intensification and regulatory harmonization are compressing the innovation cycle for fermentation-derived enzymes, while demand-side certification requirements reshape procurement specifications across dairy supply chains.
Precision fermentation is converging with continuous bioprocessing to enable real-time chymosin titer optimization. Industrial dairy enzyme manufacturers deploy perfusion bioreactors to achieve higher cell densities than traditional batch methods. This technology convergence is compressing capital requirements for new market entrants and eroding the scale advantages of legacy batch fermentation facilities.
EU Green Deal sustainability reporting obligations now capture enzyme manufacturing supply chains. EFSA evaluations increasingly weigh carbon intensity data in food additive approval processes, pressuring fermentation operators to document renewable energy sourcing. Protected designation of origin cheese producers in France face dual compliance pressure between heritage specifications and new environmental disclosure mandates.
Certification-driven procurement now dominates contract negotiations between enzyme suppliers and retail-aligned dairy processors. Private vegetarian labeling schemes from German and Dutch supermarket chains override baseline regulatory compliance as the primary qualification filter. Artisanal cheese producers in Wisconsin and Vermont accelerate microbial rennet adoption to secure shelf placement in these certification-conscious retail channels.
Microbial Rennet Market Segmentation
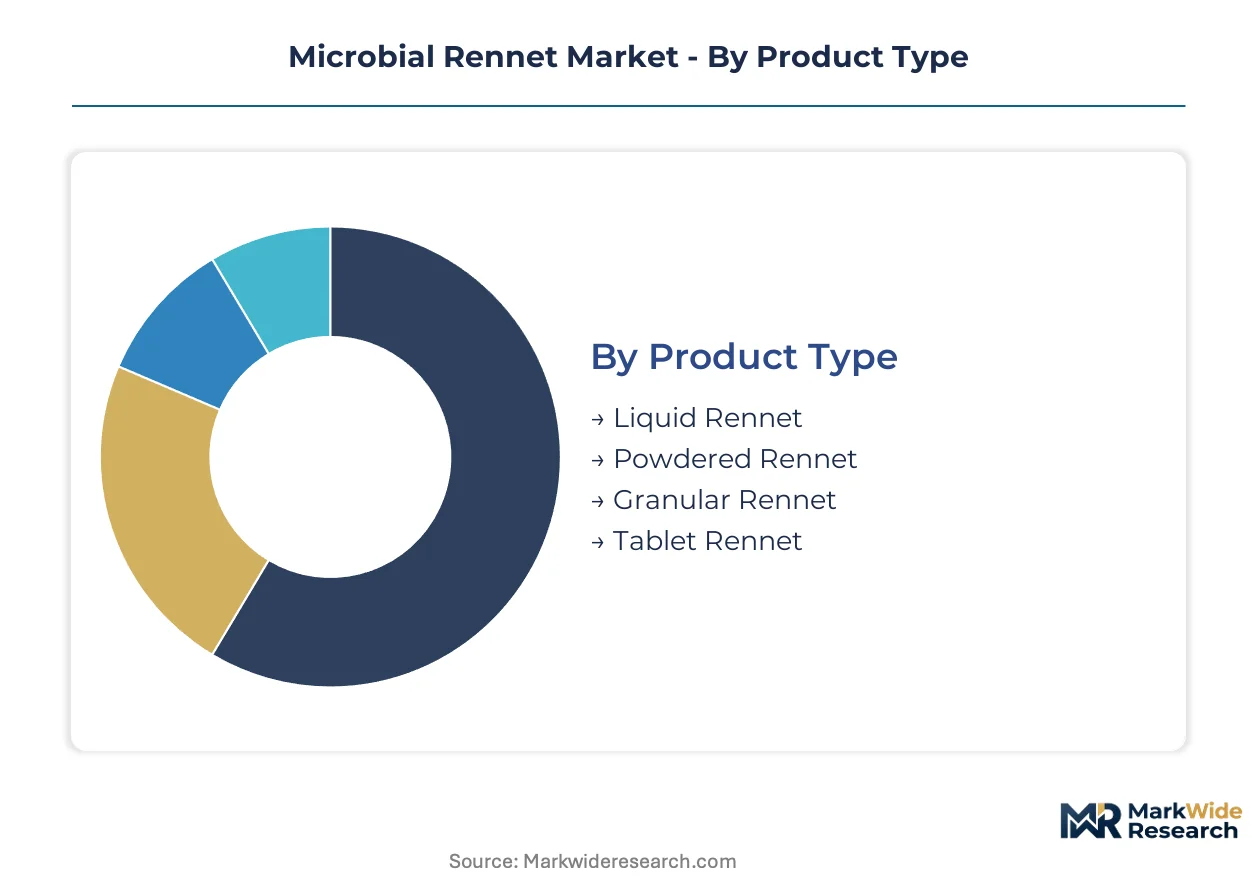
Microbial rennet procurement patterns diverge sharply between industrial-scale dairy operations and artisanal producers, with form factor and channel access determining supplier relationships. Segmentation reveals how fermentation-derived coagulants penetrate distinct value chains through differentiated technical specifications and certification requirements.
Product Type:
Liquid and powdered formats serve fundamentally different integration depths—liquid rennet embeds directly into automated cheese vat systems, while powdered variants support standalone artisanal workflows requiring extended shelf stability.
- Liquid Rennet:Standardized enzyme solutions at 200-400 MCU/mL concentration enable precise dosing through automated injection systems. German and French industrial cheesemakers specify liquid formats for continuous production lines where batch consistency overrides shelf-life concerns. EFSA additive compliance documentation accompanies bulk tanker deliveries to satisfy retail chain vegetarian certification audits.
- Powdered Rennet:Spray-dried chymosin preparations achieve 24-month stability in ambient storage, suiting distributed supply chains with irregular replenishment cycles. Small-batch producers in Vermont and Wisconsin favor powdered rennet for seasonal production schedules where liquid inventory turnover risks spoilage. The format commands premium unit pricing against liquid equivalents due to processing energy inputs.
- Granular Rennet:Intermediate moisture format bridging liquid dosing precision with powder stability, finding niche adoption in mid-scale Italian pasta filata operations.
- Tablet Rennet:Unit-dosed hobbyist format sustaining craft cheese education supply channels and home production segments with precise 1/4-tablet measurement scales.
Liquid rennet leads volumes today; tablet rennet is gaining share fastest through hobbyist channel expansion.
Application:
Cheese production absorbs the dominant fermentation capacity, while adjacent applications impose divergent purity and regulatory specifications that reshape supplier qualification requirements.
- Cheese Production:Curd-setting applications demand 90-95% kappa-casein specificity at 30-35°C coagulation temperatures. PDO-protected producers in Italy and Spain face specification conflicts between heritage animal rennet mandates and retail vegetarian labeling requirements. EFSA evaluations for novel recombinant strains concentrate approval resources on cheese-grade chymosin variants.
- Yogurt Manufacturing:Fermentation-stabilized enzyme preparations accelerate protein network formation in strained yogurt textures. Greek yogurt processors in the United States specify microbial rennet to avoid gelatin in clean-label positioning.
- Dietary Supplements:Pharmaceutical-grade chymosin isolates support digestive enzyme formulations with USP monograph compliance requirements.
- Confectionery:Limited adoption in caramel and fudge applications where milk protein stabilization replaces traditional acid coagulation methods.
Cheese production anchors fermentation output; yogurt manufacturing shows steepest expansion trajectory.
End User:
Dairy industry procurement concentrates in multinational processors with captive enzyme qualification teams, while restaurant and retail channels fragment across distributor-managed specifications.
- Dairy Industry:Integrated cheese manufacturers negotiate multi-year supply agreements with fermentation operators, embedding ISO 11298 certification into master service contracts. German dairy cooperatives specify renewable energy documentation under EU Green Deal supply chain reporting.
- Food Processing:Ingredient suppliers to prepared meal and sauce categories require chymosin with extended thermal stability for UHT processing lines.
- Restaurants:Farm-to-table establishments in France and the United States source microbial rennet for house-made cheese programs, channeling through specialty food distributors.
- Retail Chains:Private label vegetarian certification schemes from Dutch and German supermarkets override baseline regulatory compliance in enzyme procurement specifications.
Dairy industry captures bulk fermentation capacity; retail chains are driving specification tightening fastest.
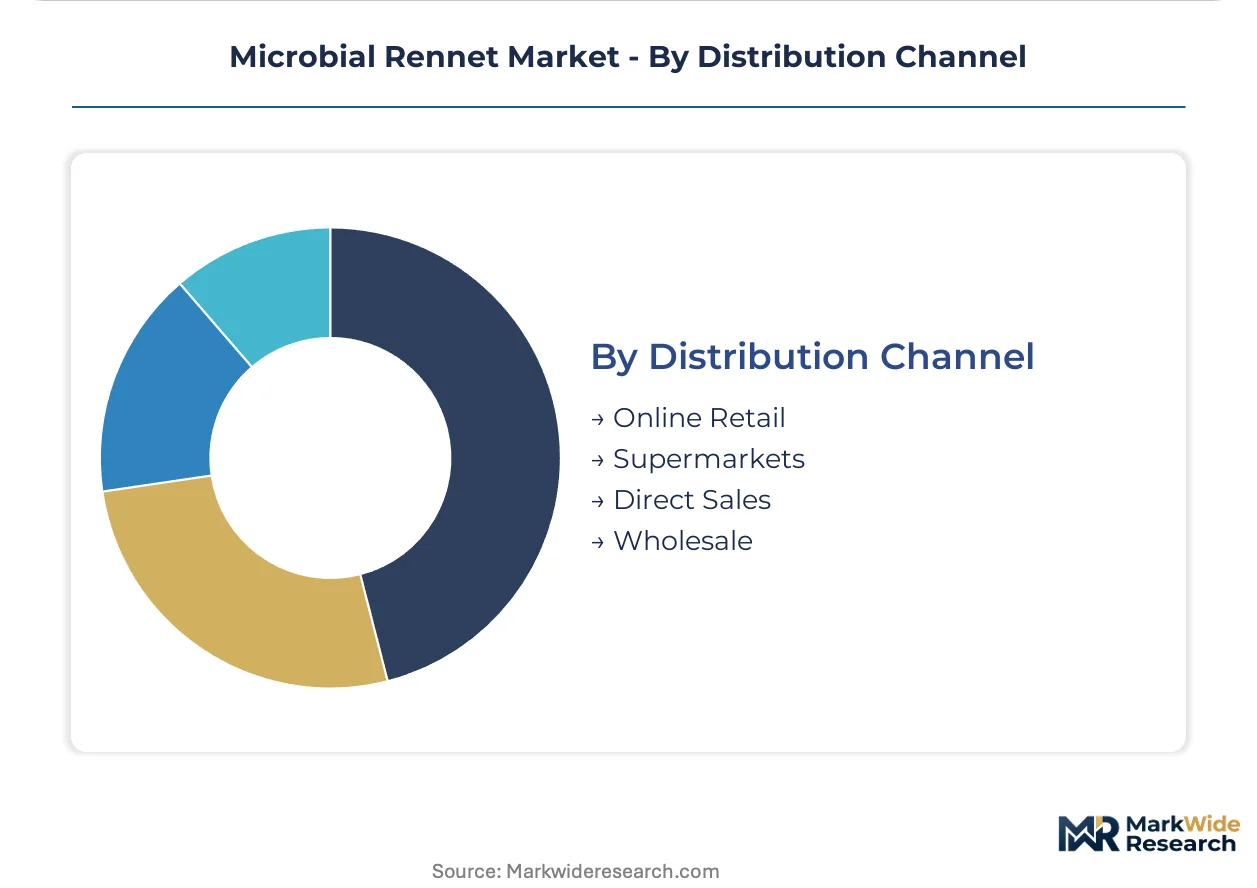
Distribution Channel:
Channel selection correlates with scale—direct sales lock in industrial volumes while online retail fragments into hobbyist and small-producer segments with divergent service requirements.
- Direct Sales:Fermentation operators maintain technical service teams for dairy industry accounts, embedding application engineers at major cheese manufacturing facilities. Contract structures include minimum volume commitments and price adjustment clauses tied to glucose feedstock indices.
- Wholesale:Regional dairy ingredient distributors carry liquid rennet inventory for mid-tier processors lacking tanker-receiving infrastructure.
- Supermarkets:Limited retail shelf presence for tablet rennet in specialty food aisles, predominantly hobbyist-oriented SKUs.
- Online Retail:Amazon and specialty enzyme suppliers serve dispersed artisanal producers with small-format liquid and powdered packaging.
Direct sales dominate value concentration; online retail expands access breadth most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzyme manufacturers exploit regulatory-arbitrage opportunities as FDA GRAS timelines stretch against EFSA's streamlined additive pathways, redirecting pilot-scale investments toward European qualification while maintaining US distribution through established strain clearances.
United States
Wisconsin and Vermont artisanal producers drive microbial rennet uptake to secure vegetarian certification from Kroger and Whole Foods. FDA GRAS notifications for novel recombinant chymosin strains extend 18-24 months, freezing capacity commitments from mid-tier fermentation operators. The Madison dairy corridor anchors domestic enzyme blending operations serving Great Lakes cheese cooperatives.
Germany
Retail chains including REWE and Edeka mandate vegetarian labeling for private-label cheese placement, pulling industrial volumes toward fermentation-derived coagulants. EU Green Deal supply chain reporting requires renewable energy documentation from enzyme suppliers under EFSA evaluation frameworks. The Bavarian dairy belt concentrates contract manufacturing for recombinant chymosin destined for Alpine cheese production.
France
PDO Comté and Roquefort producers face specification conflicts between heritage animal rennet mandates and retailer vegetarian certification requirements. ANSM oversight of food enzyme safety assessments runs parallel to EFSA additive evaluations, creating dual compliance layers for imported fermentation batches. The Rhône-Alpes cluster houses specialty cheese innovation centers testing microbial rennet in controlled terroir applications.
India
FSSAI's formalized food enzyme regulations open first-mover positioning as domestic dairy processors shift from imported calf rennet. Gujarat and Maharashtra cheese manufacturers pilot fermentation-derived chymosin for paneer and processed cheese lines. The Anand dairy cooperative network trials microbial rennet integration to reduce import dependency and capture vegetarian market positioning.
Italy
PDO Parmigiano-Reggiano and Pecorino Romano specifications explicitly block microbial rennet, preserving calf rennet demand for heritage production. EFSA evaluations for novel fermentation strains concentrate on non-PDO applications where regulatory barriers do not apply. The Emilia-Romagna cheese corridor maintains traditional coagulant supply chains while adjacent regions test microbial alternatives for industrial mozzarella production.
Microbial Rennet Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue precision fermentation platforms and plant-based dairy adjacencies. The market structures around three tiers: multinational enzyme houses with captive fermentation capacity, regional dairy ingredient distributors with blending operations, and biotechnology developers engineering novel recombinant strains. Consolidation pressure intensifies as GRAS determination timelines extend and EFSA pathways compress, favoring players with dual-continent regulatory expertise. Dominant competitive moves include backward integration into yeast host strain development and strategic partnerships with retail chains for vegetarian certification co-development.
Among Danish biotechnology specialists, Novozymes and Chr. Hansen exemplify the fermentation-platform archetype, leveraging decades of recombinant enzyme production expertise to anchor European supply security. Kerry Group occupies a position bridging ingredient distribution and application-specific formulation services across North American dairy processors. These three entities represent distinct strategic postures: pure-play enzyme engineering, culture-and-coagulant integration, and downstream formulation reach.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc. |
| Novozymes |
| Koninklijke DSM |
| Sacco SRL |
| Fonterra Co-operative Group |
| Chr. Hansen |
| Kerry Group |
| Ginkgo BioWorks |
| DuPont |
| Others |
Value Chain & Pricing Dynamics
Captive fermentation capacity in Denmark and the Netherlands anchors supply security for European enzyme houses while simultaneously locking in pricing power through controlled batch consistency. This integration pattern insulates dominant suppliers from glucose feedstock volatility that squeezes mid-tier operators dependent on toll manufacturing arrangements.
Pricing Analysis
Distributor margins of 15-25% separate bulk fermentation operators from artisanal end-users purchasing through regional dairy ingredient channels. Contract-based long-term offtake dominates industrial volumes, with price differentiation driven by ISO 11298 certification grade and volume scale commitments. Pricing pressure stems from Kluyveromyces lactis platform yield improvements compressing production costs at the premium tier. Small-batch producers in Vermont and Wisconsin show highest price sensitivity, while German dairy cooperatives prioritize renewable energy documentation over unit cost.
Supply Chain Analysis
Glucose and yeast extract supply rests on agricultural commodity producers in Brazil, the United States, and the European Union, with fermentation operators hedging through multi-source feedstock procurement. Chymosin titer optimization, downstream purification resins, and cold-chain logistics constitute critical input dependencies. Single-source vulnerability concentrates in specialized filtration membrane suppliers for pharmaceutical-grade isolates. Distribution runs through direct technical service teams for dairy industry accounts, with regional wholesalers bridging mid-tier processors lacking tanker-receiving infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microbial rennet market compounds steadily as vegetarian certification mandates tighten across European retail chains, embedding fermentation-derived coagulants into premium cheese supply chains with durable replacement demand.
For Market Incumbents: Acquire precision fermentation platforms to secure recombinant chymosin yield advantages against emerging biotechnology developers. Defend against PDO specification barriers in Italy and Spain by cultivating regulatory relationships with EFSA for novel strain approvals. Expand captive capacity in the Bavarian dairy belt to anchor Alpine cheese production contracts. For New Entrants and Emerging Players: The gap between premium-certified and economy-grade enzyme tiers creates entry space for mid-market positioning. Target India's FSSAI-regulated market as calf rennet import dependency creates white-space for domestic fermentation supply. Pursue co-development partnerships with Dutch supermarket chains on private-label vegetarian certification schemes. For Investors and Strategic Acquirers: Consolidation pressure builds where GRAS determination timelines extend and EFSA pathways compress, favoring players with dual-continent regulatory expertise. Long-term viability frames around 5-10 year compound growth anchored by clean-label dairy expansion. Target acquisition archetype: regional distributors with blending operations and established dairy processor relationships. Watch for FSSAI enforcement acceleration in India as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yeast Host Strain Development | Novozymes and Chr. Hansen reduce dependency on external biotechnology licensors for recombinant chymosin production. |
| Vegetarian Certification Co-Development with Retail Chains | German REWE and Edeka specifications now override baseline regulatory compliance in enzyme procurement negotiations. |
| Precision Fermentation Platform Investment | Perfusion bioreactor deployment compresses capital requirements for new market entrants versus legacy batch facilities. |
| India FSSAI Regulatory First-Mover Positioning | Gujarat and Maharashtra cheese manufacturers pilot domestic chymosin to reduce calf rennet import dependency. |
| Tablet-to-Liquid Format Conversion Programs | Artisanal producers in Wisconsin upgrade dosing systems, expanding contract volumes for bulk liquid suppliers. |
Study Parameters
Bottom-up cheese production modeling reconciled against top-down fermentation capacity tracking forms the analytical core of this study. Primary interviews with dairy processing executives, enzyme procurement leads at multinational cooperatives, EFSA regulatory affairs specialists, and specialty cheese distributors combined with secondary validation from FDA GRAS notifications, EFSA additive evaluations, customs trade data, and ISO 11298 certification registries. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Input-output matrices map chymosin titer yields to end-use absorption across cheese production, yogurt manufacturing, and dietary supplement applications. Segmentation dimensions span product format, application category, end-user archetype, and distribution channel, with CAGRs derived from growth driver elasticity modeling against vegetarian certification adoption curves. Forecast inputs include EFSA evaluation pipeline velocity, FSSAI regulatory formalization progress, and retail chain procurement specification tightening.
Caveats apply where EFSA additive approval delays, glucose feedstock price spikes, or PDO specification rigidities in Italy and Spain could materially shift the outlook. Forecasts reflect documented assumptions on regulatory pathway efficiency and clean-label dairy demand persistence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Bacterial Antigens Market
Industrial Microbiology
Cultured Dextrose Market
Industrial Microbiology
Microbial Culture Market
Industrial Microbiology
Microbial-Derived Fiber Market
Industrial Microbiology
Global Microbial Protein Market
Industrial Microbiology
Microbiology Testing Market
Industrial Microbiology
Microbial API Market
Industrial Microbiology
Real Time Continuous Microbiological Monitoring Systems Market
Industrial Microbiology
Bacterial Amylase Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
Global Microbial Products Market
Industrial Microbiology
Industrial Microbiology Market
Industrial Microbiology
Microbial Seed Treatment Market
Industrial Microbiology
B-Glucuronidase Enzymes Market
Industrial Microbiology
Freeze-Dried Microbial Food Culture Market
Industrial Microbiology
Benzoate-Free Enzymes Market