
 Microbial Lipase Market | 2026-2036
Microbial Lipase Market Size, Share, and Industry Trends Forecast 2026-2036
Microbial Lipase Market Analysis
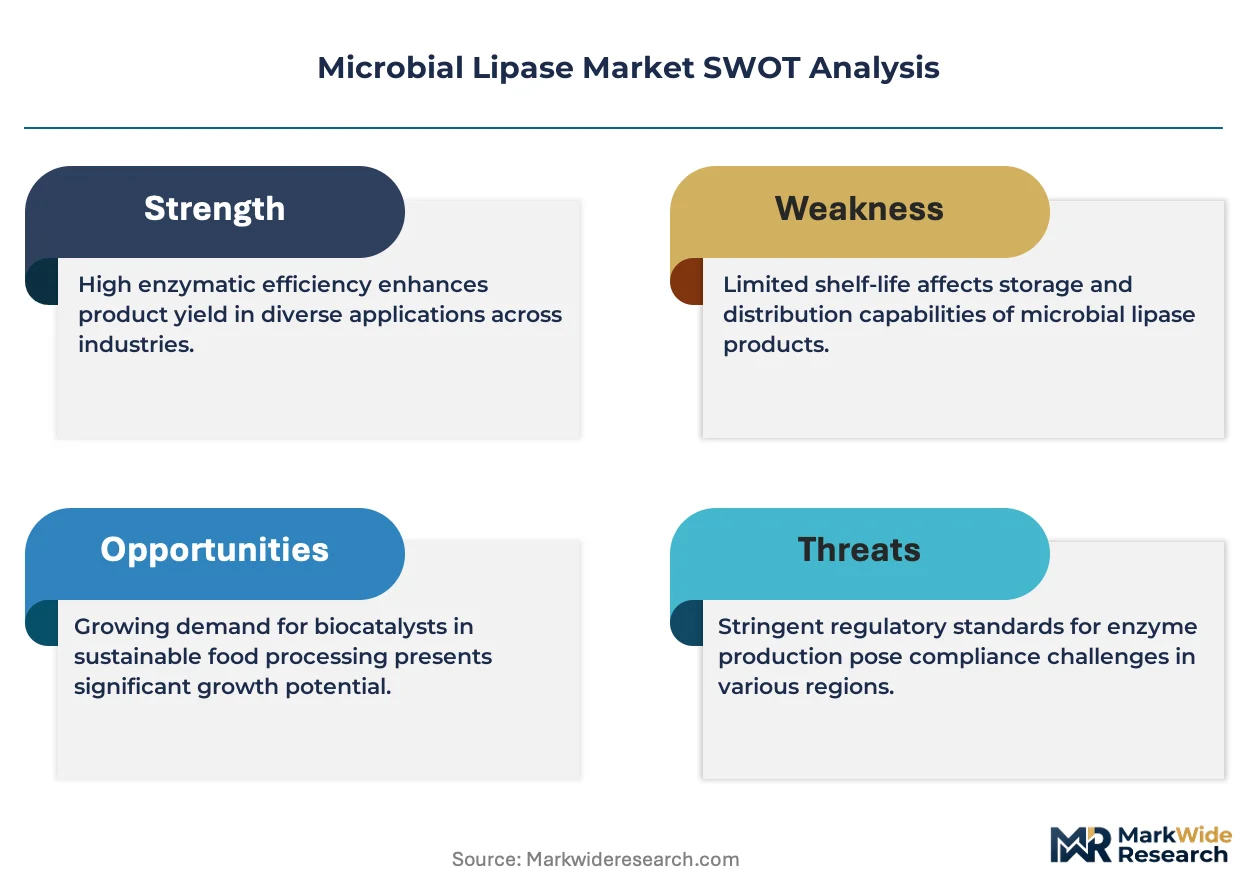
Technical service and formulation support is shifting from a cost center to a revenue stream for enzyme suppliers. Novozymes A/S leverages its application laboratories in Denmark and China to lock in multi-year detergent partnerships. Amano Enzyme Inc. anchors its competitive stance through proprietary fungal strain libraries optimized for pharmaceutical ester synthesis. Advanced Enzyme Technologies dominates India's domestic edible oil sector with thermostable lipase blends tailored to local processing temperatures.
Microbial lipases are extracellular enzymes produced by filamentous fungi, yeasts, and bacteria, typically operating at pH ranges from 4.0 to 10.0 and temperatures between 30°C and 60°C depending on the source organism; these biocatalysts hydrolyze triglycerides into fatty acids and glycerol for industrial transesterification, interesterification, and degumming operations. Thermostable lipases command premium positioning in food processing and biofuel applications where thermal stability reduces enzyme replacement frequency. Powder form lipases retain logistical advantages in detergent formulation where shelf stability and bulk freight economics outweigh liquid handling convenience. Lyophilized variants occupy niche margin pools in research laboratories and clinical diagnostics where activity preservation justifies higher unit costs.
REACH registration requirements in Europe and China's GB 1886.174 food additive standard constrain which microbial strains and production residues enter commercial channels, directly filtering supplier qualification pools. India's BIS certification for industrial enzymes and FSSAI approvals for food-grade lipase create parallel compliance tracks that shape domestic manufacturing investments. Stakeholders must monitor how tightening purity specifications in pharmaceutical applications redirect R&D spending toward GMP-compliant fermentation infrastructure.
Market Dynamics
Enzyme suppliers now bundle technical service contracts with bulk biocatalyst supply, converting formulation support from overhead into recurring revenue and locking processors into multi-year partnerships.
Growth Catalysts
- REACH registration thresholds:ECHA's tightening purity benchmarks filter out marginal fermentation operators, consolidating qualified supplier pools and redirecting procurement toward certified European producers.
- India's BIS certification pipeline:Domestic edible oil processors now specify BIS-certified lipase grades for interesterification, creating captive demand for thermostable fungal strains.
- Thermostable enzyme engineering:Protein stabilization protocols extend operational half-life above 60°C, reducing replacement frequency in continuous biodiesel transesterification systems.
Market Restraints
- Fermentation substrate volatility:Corn steep liquor and soy peptone prices fluctuate with agricultural commodity cycles, compressing gross margins for bulk lipase manufacturers.
- Strain IP concentration:Proprietary fungal libraries remain concentrated among three legacy suppliers, blocking new entrants from pharmaceutical-grade ester synthesis markets.
- GB 1886.174 residue limits:China's food additive standard restricts permissible production impurities, forcing fermentation infrastructure upgrades that extend qualification timelines.
Strategic Opportunities
- Underpenetrated detergent markets:Latin American household care formulators still source commodity proteases; lipase blends for cold-water washing remain below 15% formulation penetration.
- Carbon credit monetization:EU Green Deal carbon border adjustments reward enzymatic interesterification over chemical catalysis, creating regulatory arbitrage for European processors.
- Lyophilized clinical diagnostics:Molecular diagnostic manufacturers seek shelf-stable lipase reagents for point-of-care cholesterol assays, commanding 8-12x bulk food-grade pricing.
Industry Challenges
- Fermentation scale-up talent scarcity:GMP-compliant bioreactor operation requires hybrid skill sets spanning microbial physiology and pharmaceutical quality systems; training pipelines lag demand.
- Dual certification timelines:FSSAI food-grade and BIS industrial approvals for Indian manufacturers run parallel rather than sequential, extending market entry by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbial Lipase Market |
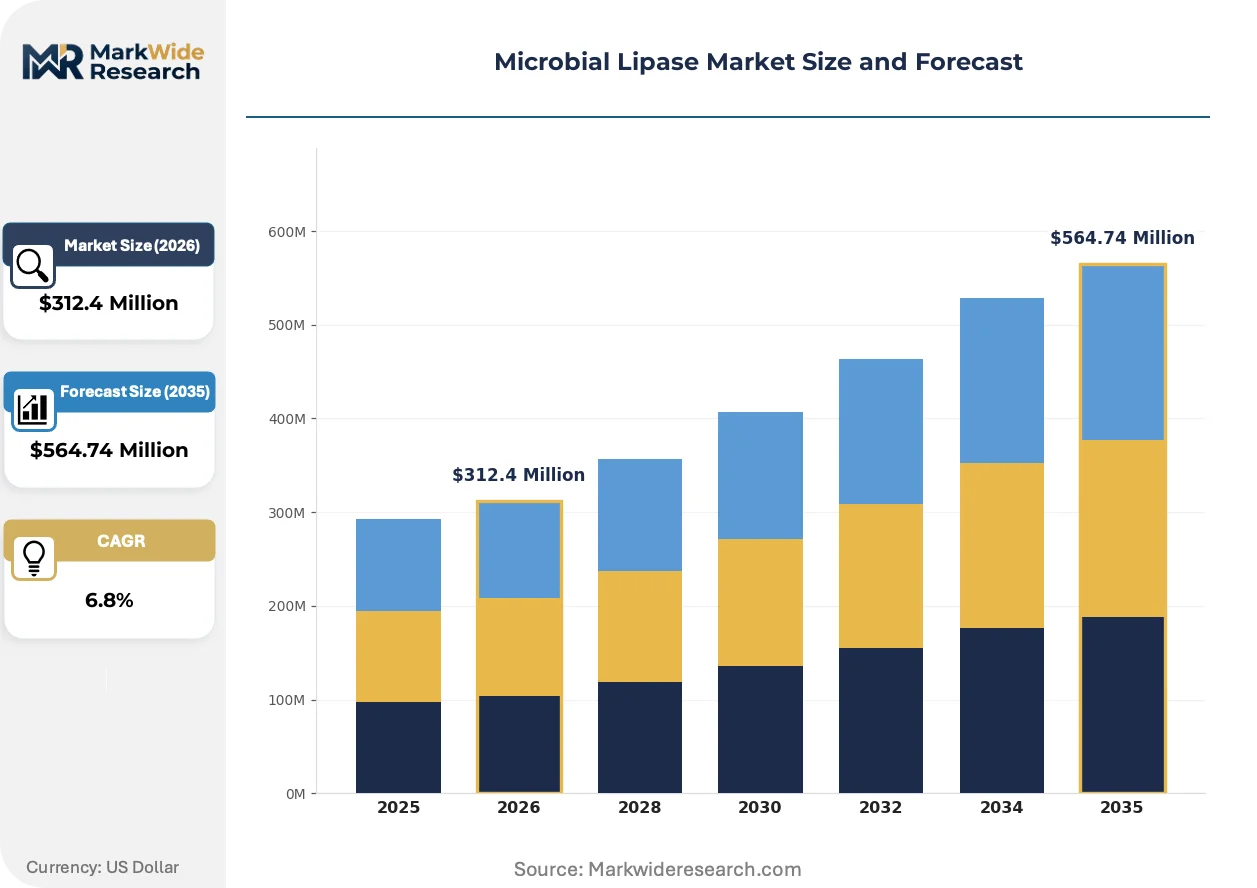
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermostable Lipases, Acidic Lipases, Neutral Lipases, Alkaline Lipases Application: Food Processing, Detergent Formulation, Biofuel Production, Pharmaceuticals End User: Food Industry, Textile Industry, Healthcare Sector, Research Laboratories Form: Liquid Form, Powder Form, Granular Form, Lyophilized Form |
| Companies Covered | Novozymes A/S, Amano Enzyme Inc., Advanced Enzyme Technologies, Koninklijke DSM N.V., Chr. Hansen Holding A/S, DuPont de Nemours, Inc., Biocatalysts, BASF SE, Aumgene Bioscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbial Lipase Market Emerging Trajectories
Biocatalysis is migrating from batch hydrolysis toward continuous-flow reactor architectures, with enzyme immobilization and process analytical technology rewriting unit economics across food and fuel applications.
Protein engineering via directed evolution is rewriting lipase thermal stability benchmarks. Novozymes A/S and academic consortia screen mutant libraries for 70°C operational tolerance. Detergent formulators in Germany and Brazil adopt these variants for cold-water efficacy claims. The technology is compressing replacement cycles and enabling single-enzyme formulations that previously required three-strain cocktails.
REACH Article 33 disclosure obligations now extend to enzyme production residues. ECHA's 2023 guidance requires full supply chain substance registration for industrial biocatalysts. Food-grade lipase imports into Rotterdam and Hamburg face enhanced documentation checks. European processors are qualifying domestic fermentation sources to eliminate import uncertainty.
Technical service unbundling is separating enzyme supply from application engineering. Detergent and edible oil processors previously received formulation support as a bundled cost; suppliers now invoice separately for pilot-scale optimization and regulatory dossier preparation. This shift is most visible in India, where Advanced Enzyme Technologies and multinational rivals compete on service contract scope rather than unit price alone.
Microbial Lipase Market Segmentation
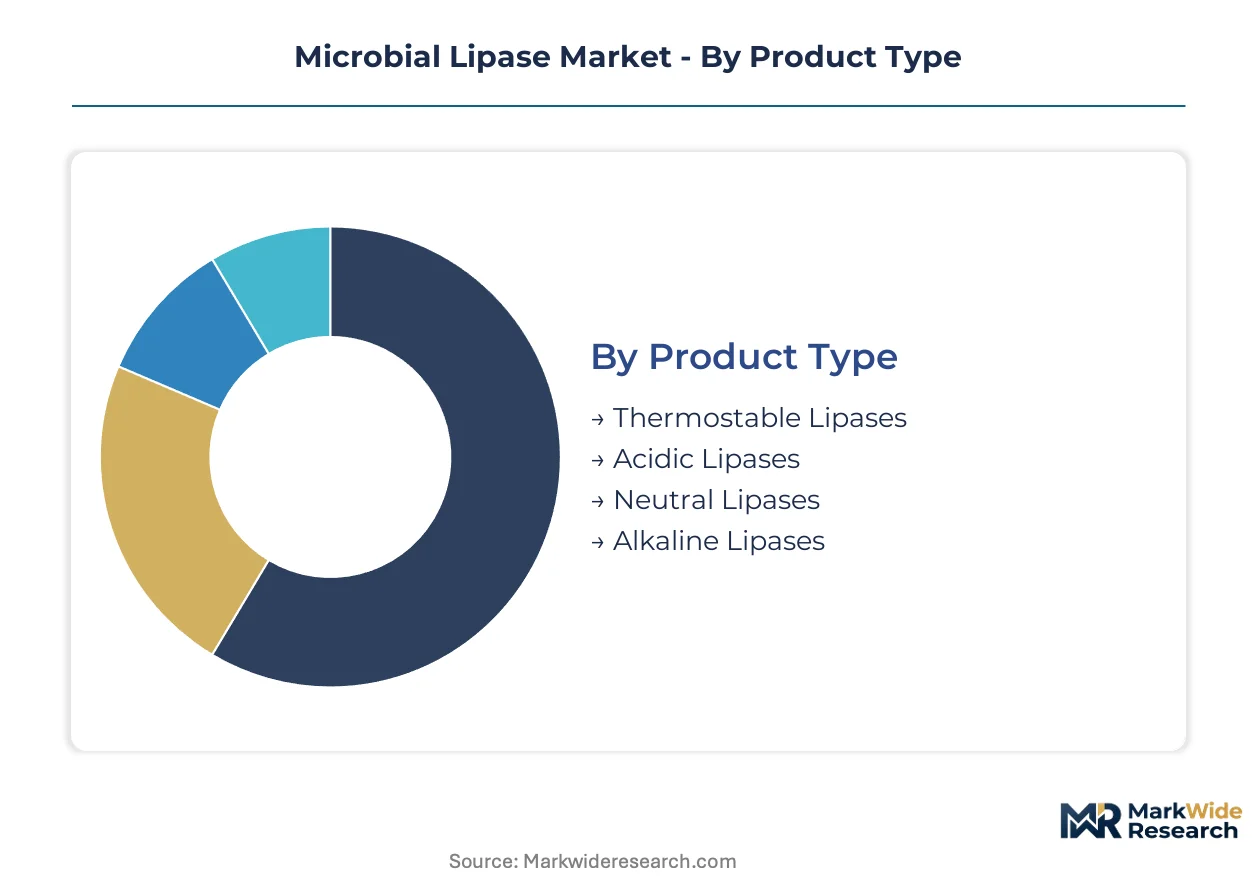
Enzyme buyers select microbial lipase grades based on thermal tolerance, pH stability, and formulation compatibility rather than commodity pricing. Segmentation reflects divergent technical requirements across food safety regulations, detergent performance claims, and pharmaceutical purity standards.
Product Type:
Procurement decisions hinge on operational temperature windows and pH compatibility with existing process infrastructure.
- Thermostable Lipases:Engineered protein variants retain catalytic activity above 60°C through disulfide bond stabilization and proline substitution. India's edible oil refiners specify these grades for continuous interesterification reactors running at elevated temperatures.
- Alkaline Lipases:These enzymes demonstrate optimal activity at pH 9.0-11.0, making them indispensable for detergent formulations targeting cold-water efficacy. German and Brazilian household care manufacturers now require variants with 70°C tolerance for premium positioning.
- Acidic Lipases:Active at pH 4.0-6.0 for fruit juice clarification and dairy flavor development.
- Neutral Lipases:Versatile pH 6.0-8.0 range suits general food processing where pH adjustment adds cost.
Volume sits with thermostable variants; growth tilts toward alkaline grades.
Application:
End-use concentration follows regulatory arbitrage opportunities and carbon credit monetization pathways.
- Food Processing:Interesterification of palm oil and butterfat replacers drives bulk demand, with EU Green Deal carbon border adjustments rewarding enzymatic over chemical catalysis. REACH-compliant producers in Denmark and the Netherlands capture premium positioning.
- Detergent Formulation:Lipase blends for cold-water washing remain underpenetrated in Latin American markets, offering expansion headroom as formulators replace three-strain cocktails with single-enzyme solutions.
- Biofuel Production:Biodiesel transesterification using immobilized lipases reduces caustic waste streams.
- Pharmaceuticals:Ester synthesis for active pharmaceutical ingredients requires GMP-compliant fermentation with residue documentation.
Revenue concentrates in food processing; pharmaceutical applications command the steepest expansion trajectory.
End User:
Customer type determines certification burden and service contract complexity.
- Food Industry:Edible oil processors in India and Europe specify BIS-certified or REACH-registered grades, locking suppliers into multi-year technical service agreements covering pilot-scale optimization.
- Healthcare Sector:Diagnostic manufacturers seek lyophilized lipases for point-of-care cholesterol assays, tolerating 8-12x bulk pricing for shelf stability and lot-to-lot consistency.
- Textile Industry:Desizing and bioscouring applications favor cost-optimized liquid concentrates.
- Research Laboratories:Small-batch requirements sustain niche suppliers with flexible minimum order quantities.
Contract value peaks with healthcare sector; transaction volume dominates food industry procurement.
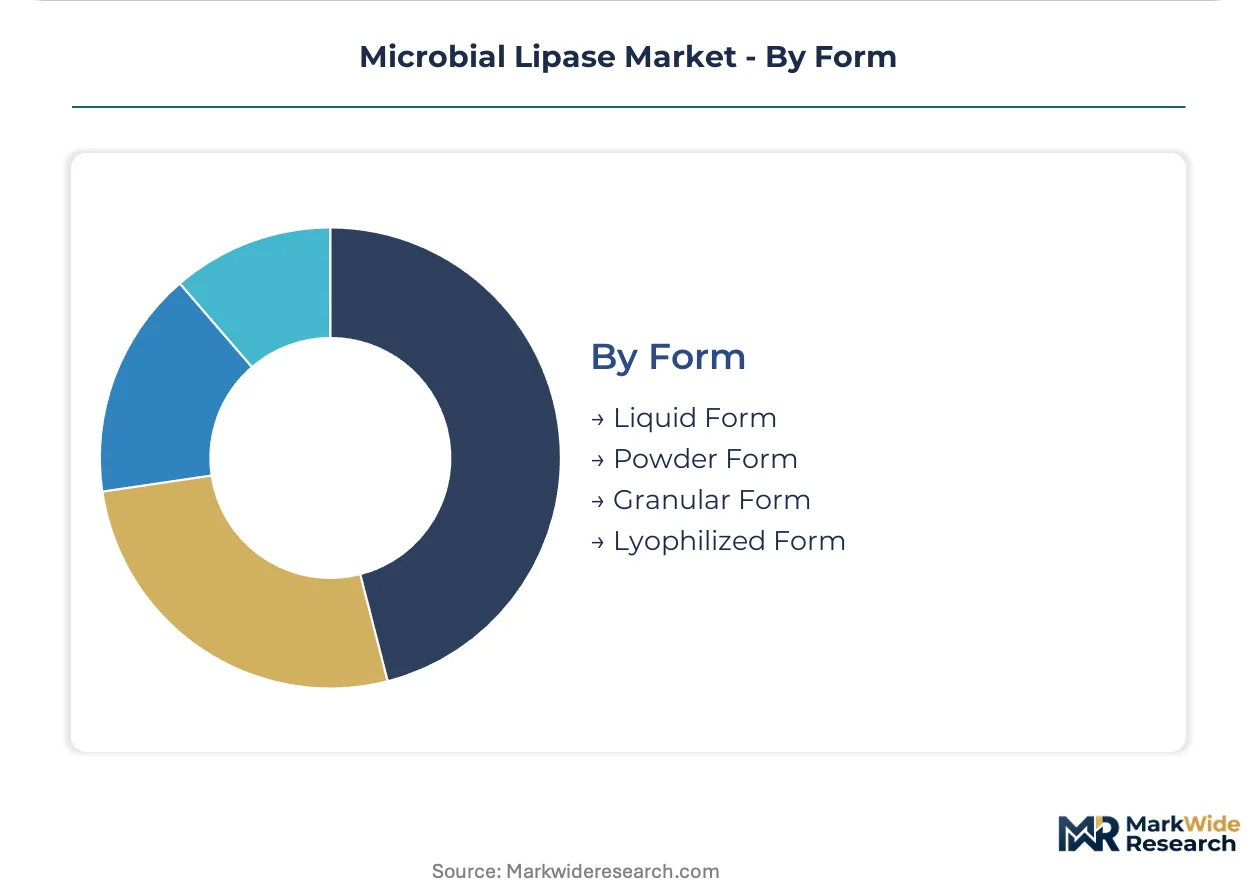
Form:
Logistics economics and shelf stability requirements partition the supply base.
- Powder Form:Spray-dried preparations dominate detergent manufacturing, where bulk freight efficiency and extended ambient storage outweigh reconstitution inconvenience. Brazilian formulators prefer this format for regional distribution.
- Lyophilized Form:Freeze-dried variants preserve activity for clinical diagnostics and molecular biology reagents, justifying premium positioning through validated stability protocols.
- Liquid Form:Ready-to-use concentrates reduce handling steps in continuous food processing lines.
- Granular Form:Dust-free handling characteristics suit pharmaceutical tableting operations.
Shipment tonnage favors powder; margin expansion concentrates in lyophilized formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Denmark, Japan, and India where fermentation infrastructure serves export markets, while consumption clusters in Germany, Brazil, and China where food processing and detergent formulation drive procurement.
Denmark
Novozymes A/S anchors European enzyme supply through Copenhagen-region fermentation complexes serving REACH-registered grades to Rotterdam and Hamburg processors. ECHA's 2023 Article 33 guidance on production residue disclosure tightens import documentation for non-EU biocatalysts. Danish suppliers capture premium positioning in EU Green Deal carbon credit arbitrage for edible oil interesterification.
Germany
Detergent formulators in Düsseldorf and Frankfurt specify alkaline lipases with 70°C thermal tolerance for cold-water efficacy marketing claims. ECHA's REACH registration thresholds filter marginal suppliers, consolidating procurement toward certified domestic distributors. The Ruhr industrial cluster hosts application laboratories where technical service contracts lock processors into multi-year partnerships.
India
Maharashtra and Gujarat edible oil refiners specify BIS-certified thermostable lipases for continuous interesterification reactors. FSSAI food-grade and BIS industrial approvals run parallel rather than sequential, extending qualification timelines for new entrants. Advanced Enzyme Technologies dominates domestic supply through Thane-region production tailored to local processing temperatures.
Brazil
São Paulo household care formulators source commodity proteases while lipase penetration for cold-water washing remains below 15 percent. ANVISA's biocatalyst import regulations align with Mercosur technical standards, creating compliance complexity for extra-regional suppliers. The São Paulo-Porto Alegre corridor represents primary expansion headroom for single-enzyme detergent formulations.
China
GB 1886.174 residue limits restrict permissible production impurities in food-grade lipases, forcing fermentation infrastructure upgrades. Yangtze River Delta processors qualify domestic strains to eliminate import uncertainty from enhanced Rotterdam and Hamburg documentation checks. MIIT's industrial enzyme standards create parallel compliance tracks shaping local manufacturing investments.
Microbial Lipase Market Vendor Landscape
Top-tier vendors anchor premium certification tiers, while mid-scale specialists compete on regional technical service contracts. The supplier base concentrates around three legacy players with proprietary fungal strain libraries, blocking new entrants from pharmaceutical-grade markets. Strategic archetypes include fermentation-scale generalists, application-focused technical service providers, and lyophilized niche specialists. Competitive moves center on multi-year partnership locking and GMP-compliant capacity expansion.
Among Denmark-based enzyme suppliers, Novozymes A/S exemplifies the technical-service-anchored archetype through application laboratory networks. Amano Enzyme Inc. occupies a position within the proprietary-strain specialist tier, with its company structure suggesting Japanese-origin fermentation expertise. Advanced Enzyme Technologies represents the emerging-market scale player, sitting within India's domestic supply consolidation. These three entities collectively illustrate how geographic fermentation advantages translate into certification-tier market segmentation.
| Leading Market Players |
|---|
| Novozymes A/S |
| Amano Enzyme Inc. |
| Advanced Enzyme Technologies |
| Koninklijke DSM N.V. |
| Chr. Hansen Holding A/S |
| DuPont de Nemours, Inc. |
| Biocatalysts |
| BASF SE |
| Aumgene Bioscience |
| Others |
Supply Flow & Price Mechanics
Thermostable certification tiers split microbial lipase procurement into parallel cost structures, with REACH-registered Danish supply commanding premium positioning against commodity Indian bulk grades while freight economics and cold-chain requirements reshape downstream distribution architectures across detergent and edible oil channels.
Pricing Analysis
Margin tightening in pharmaceutical-grade lyophilized lipases reflects GMP fermentation infrastructure costs and residue documentation burdens. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified clinical diagnostic supply from BIS-certified food processing grades and commodity detergent powder. Pricing pressure stems from corn steep liquor and soy peptone agricultural volatility squeezing bulk manufacturers. Detergent formulators exhibit highest price sensitivity; diagnostic manufacturers tolerate 8-12x premiums for shelf stability.
Supply Chain Analysis
Freight cost differentials between freeze-dried clinical reagents and spray-dried detergent powders determine regional sourcing strategies. Supply concentrates in Denmark, Japan, and India where fermentation infrastructure serves export markets. Corn steep liquor, soy peptone, and specialized fungal strain libraries constitute critical input dependencies. Single-source vulnerability concentrates in proprietary fungal libraries held by legacy suppliers. Distribution runs through technical service contracts that bundle formulation support with bulk supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microbial lipase supply is becoming a vertical-integration race as processors seek backward control over strain development and GMP fermentation capacity to escape certification bottlenecks and margin compression.
For Market Incumbents: Anticipate regulatory arbitrage erosion as REACH Article 33 disclosure obligations extend to production residues, forcing European processors to qualify domestic fermentation sources. Lock multi-year technical service contracts with Indian edible oil refiners before BIS certification pipelines mature. Prioritize thermostable strain R&D to defend premium positioning against protein engineering consortia.
For New Entrants and Emerging Players: Contract research organizations represent the most accessible channel partner type for penetrating pharmaceutical ester synthesis markets without proprietary fungal libraries. Target lyophilized clinical diagnostics where 8-12x pricing premiums offset GMP infrastructure investments. Pursue carbon credit monetization pathways under EU Green Deal border adjustments as the primary go-to-market angle for European food processors.
For Investors and Strategic Acquirers: Exit pathways concentrate in technical service-anchored fermentation specialists with captive strain libraries and regional certification tier access. Long-term viability hinges on GMP-compliant capacity expansion and multi-year partnership locking. Watch ECHA guidance evolution on production residue disclosure as the inflection signal for import substitution investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | Captive fungal libraries bypass IP concentration blocking pharmaceutical-grade market entry. |
| GMP Fermentation Capacity Expansion | EU Green Deal carbon credit arbitrage rewards certified European producers in edible oil interesterification. |
| Technical Service Contract Unbundling | Separate formulation support invoicing converts overhead into recurring revenue streams. |
| Long-term Supply Agreement with Detergent Formulators | Multi-year partnerships lock Brazilian and German household care manufacturers into cold-water lipase blends. |
| Joint Venture with Indian Edible Oil Processors | BIS certification pipelines create captive demand for thermostable fungal strains in Maharashtra and Gujarat. |
Methodological Framework
Independent corroboration across fermentation plant managers, procurement leads at detergent and edible oil processors, technical R&D directors, and distribution channel partners underwrites the qualitative findings. Secondary validation draws from ECHA REACH registration databases, FSSAI and BIS certification records, customs and trade data for biocatalyst imports, and SEC filings of publicly traded enzyme manufacturers. Bottom-up strain-level production estimates triangulate against top-down application segment demand assessments.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by thermal stability tier, pH compatibility class, end-use application, certification grade, and geographic production hub. CAGRs derive from elasticity modeling of substitution between enzymatic and chemical catalysis in interesterification, coupled with detergent formulation penetration curves for cold-water lipase blends. Forecast inputs include BIS certification pipeline velocity and ECHA guidance evolution on production residue disclosure.
Caveats apply where REACH Article 33 enforcement intensity, GB 1886.174 residue limit revisions, or agricultural commodity price spikes could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Lactic Acid Bacteria Market
Industrial Microbiology
Cultured Dextrose Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
Global Microbial Testing Market
Industrial Microbiology
Automated Microbial Detection Systems Market
Industrial Microbiology
Automated Microbiology Market
Industrial Microbiology
Microbial Protein Used in Feed Market
Industrial Microbiology
Mesophilic Bacteria Market
Industrial Microbiology
Bacillus Coagulans Market
Industrial Microbiology
Salinomycin Market
Industrial Microbiology
Mineral Yeast Market
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Microbial Therapeutic Products Market
Industrial Microbiology
Microbial Bioreactors Market
Industrial Microbiology
Molecular Microbiology Market
Industrial Microbiology
Global Microbial Fermentation Technology Market