
 Microbial Culture Market | 2026-2036
Microbial Culture Market Size, Share, and Industry Trends Forecast 2026-2036
Microbial Culture Market Outlook
Chinese fermentation capacity is broadening as domestic biomanufacturing infrastructure scales to serve pharmaceutical and food-grade culture demand. Thermo Fisher Scientific leverages its global distribution network to sustain leadership in research-grade bacterial and yeast cultures. Merck KGaA anchors European supply through specialized media formulations for bioprocessing applications. HiMedia Laboratories competes aggressively on cost-optimized culture media for emerging-market laboratories.
Microbial cultures comprise defined or complex nutrient formulations supporting the propagation of bacteria, yeast, algae, or fungi under controlled temperature, pH, and oxygen conditions, typically containing peptones, extracts, salts, and growth factors at precise concentrations. These cultures enable industrial fermentation, diagnostic assay development, and recombinant protein production across regulated manufacturing environments. Bacterial cultures dominate pharmaceutical applications where sterility assurance and traceability requirements command premium pricing. Yeast cultures expand fastest in food and beverage fermentation as clean-label ingredient trends reshape manufacturer sourcing. Liquid culture technology captures growing share from traditional agar plate methods as automated bioprocessing systems reduce contamination risk and batch-to-batch variability.
FDA enforces current Good Manufacturing Practice standards for culture media used in therapeutic manufacturing, while EMA's Annex 1 revisions tighten contamination control expectations for sterile culture processes. China's NMPA accelerates local inspection capacity for imported culture products, reshaping market access timelines for foreign suppliers. Stakeholders must monitor evolving pharmacopoeial harmonization between USP, EP, and Chinese standards as divergence in endotoxin and sterility testing protocols threatens to fragment quality requirements across major demand centers.
Market Dynamics
Single-use bioreactor technology is compressing facility build-out timelines from years to months, forcing incumbent suppliers to reconfigure their liquid culture media portfolios for disposable formats or cede share to specialized entrants.
Growth Catalysts
- Cell therapy manufacturing scale-up:Autologous and allogeneic cell therapy pipelines require GMP-grade bacterial and yeast culture substrates at volumes tenfold above research-grade norms. FDA's accelerated approval pathways for regenerative medicines compress supplier qualification timelines.
- EMA Annex 1 revision:The 2022 contamination control overhaul mandates continuous viable monitoring in aseptic processing zones, driving replacement of legacy agar-based environmental monitoring with automated liquid culture systems.
- Fermentation infrastructure clustering:Contract development and manufacturing organizations in Germany, China, and the United States are consolidating multi-thousand-liter capacity, concentrating demand for high-volume, traceable culture media supply.
Market Restraints
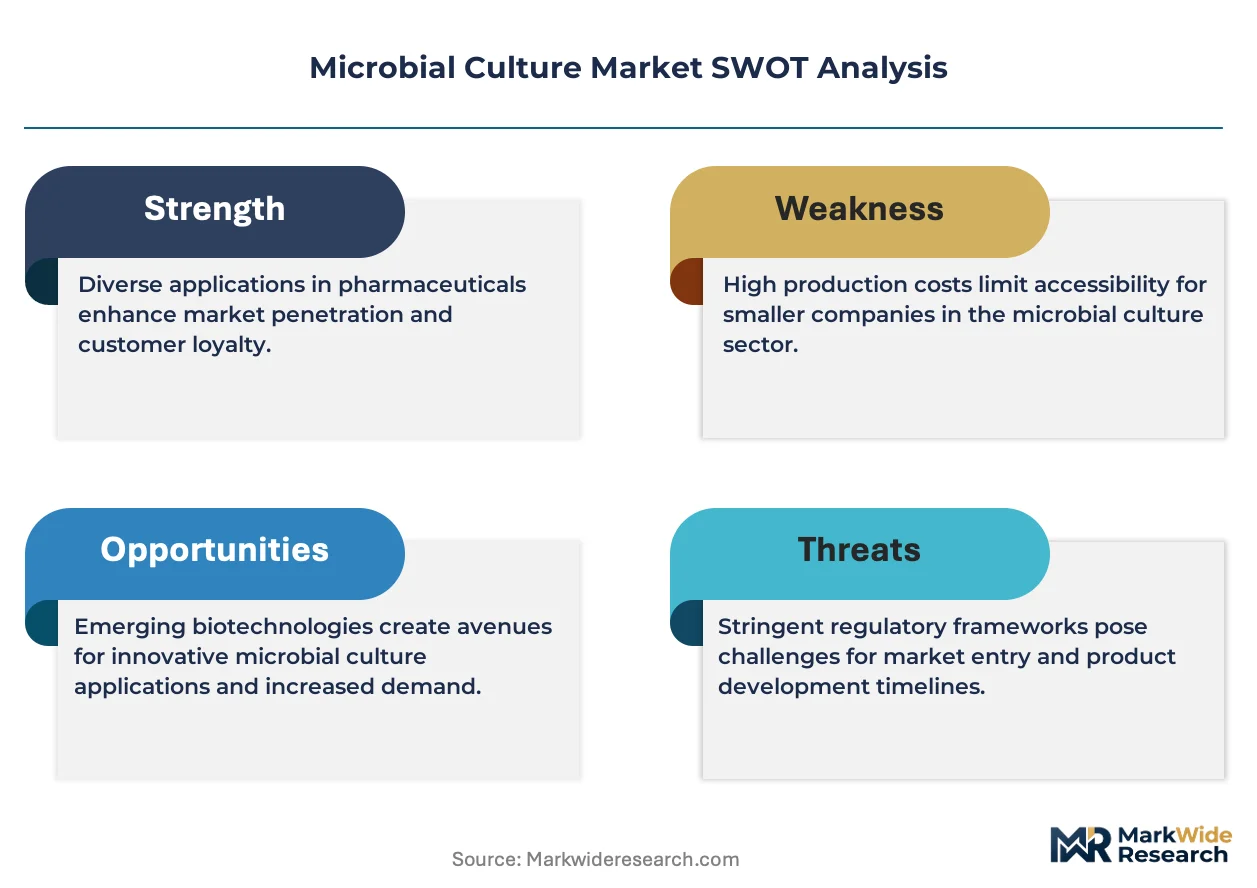
- Peptone supply concentration:Bovine and porcine-derived peptones face sourcing constraints from BSE/TSE regulatory zones, with European suppliers dependent on South American meat processing byproduct streams subject to export quota volatility.
- Specialized cold chain requirements:Lyophilized culture media demand controlled-atmosphere storage and validated shipping containers, elevating landed costs for inland laboratories distant from major logistics hubs.
- Endotoxin testing divergence:USP, EP, and Chinese pharmacopoeial methods for Limulus amebocyte lysate testing yield non-equivalent results, forcing manufacturers to maintain three validation protocols for multi-jurisdictional products.
Strategic Opportunities
- Plant-based peptone substitution:Soy, wheat gluten, and yeast-derived nitrogen sources bypass TSE/BSE certification burdens and appeal to vegan-certified fermentation end-uses in food and cosmetic applications.
- India's biomanufacturing expansion:CDSCO's streamlined import licensing for research-grade cultures and state-level biotechnology parks in Telangana and Karnataka create first-mover positioning for media suppliers establishing local formulation facilities.
- Continuous manufacturing integration:Perfusion bioreactor systems require real-time nutrient feed strategies, opening demand for concentrated, customizable culture media concentrates versus traditional batch formulations.
Industry Challenges
- Contamination investigation complexity:Rapid sterility test failures in pharmaceutical production trigger multi-week facility shutdowns; suppliers face liability exposure when root cause analysis implicates media-borne slow-growing contaminants.
- Qualification timeline compression:Cell therapy sponsors demand culture media supplier audits and validation documentation within 90-day windows, straining quality assurance bandwidth at mid-tier media manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbial Culture Market |
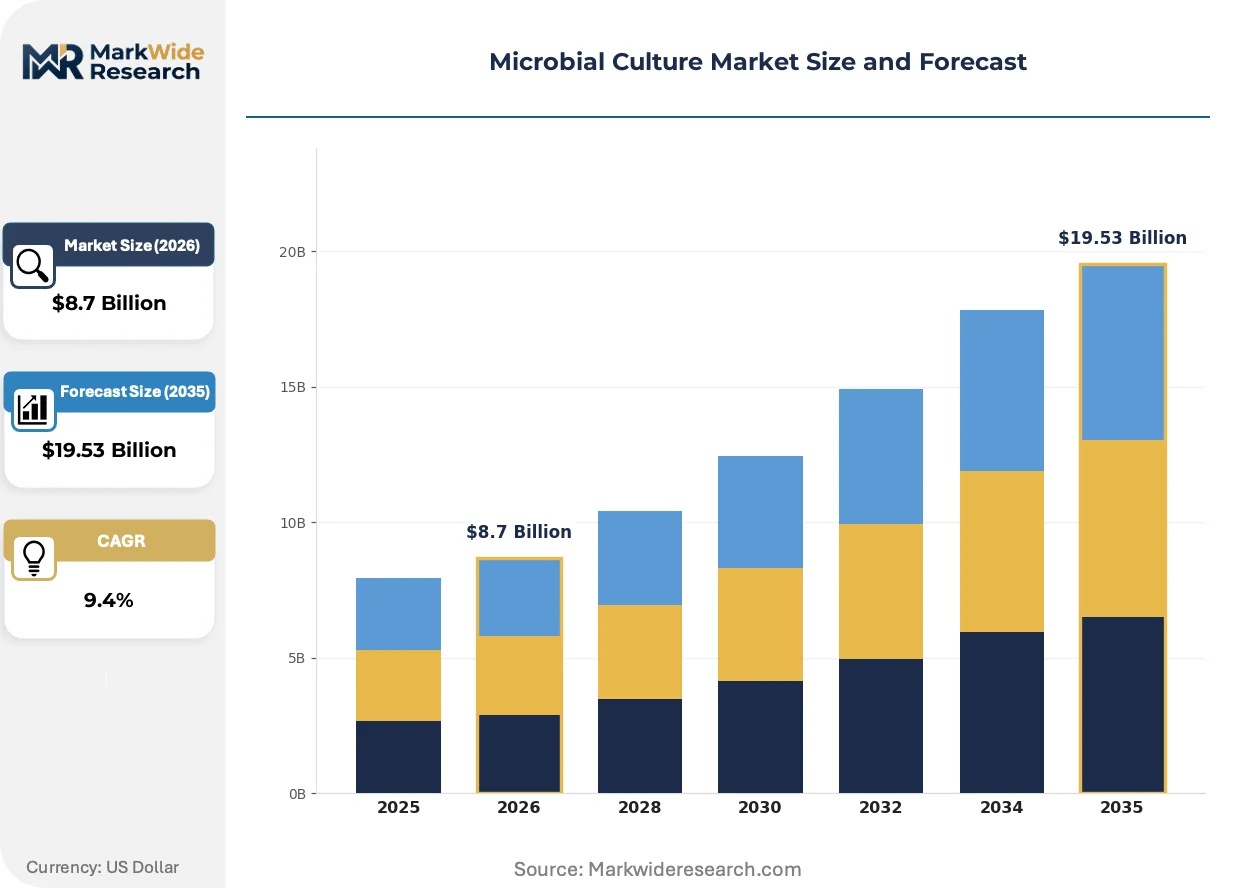
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial Cultures, Yeast Cultures, Algal Cultures, Fungal Cultures Application: Food & Beverage, Pharmaceuticals, Agriculture, Environmental End User: Research Laboratories, Biotech Companies, Food Manufacturers, Academic Institutions Technology: Agar Plate, Broth Culture, Liquid Culture, Freeze-Drying |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Becton, Dickinson and Company, bioMérieux SA, Bio-Rad Laboratories, Neogen Corporation, Sartorius AG, HiMedia Laboratories, Eiken Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbial Culture Market Strategic Shifts
Automation and closed-system architecture are displacing open-handling protocols across culture preparation and inoculation workflows, compressing contamination rates and labor intensity simultaneously.
Modular, skid-mounted bioreactor platforms is decentralizing microbial culture production from centralized multi-product facilities toward distributed, product-dedicated manufacturing nodes. Specialty chemical and enzyme manufacturers in Denmark and the Netherlands are deploying these systems for 500-2,000 liter campaigns. This architecture is decentralizing supply chain risk and enabling rapid product changeover without cross-contamination protocols.
REACH Annex XIV authorization requirements for nickel catalyst residues in peptone manufacturing are forcing European suppliers to document alternative protein hydrolysis chemistries or secure downstream user exemptions. The regulatory burden falls heaviest on complex media formulations containing multiple animal-derived components. German and Swiss manufacturers are responding by vertically integrating into controlled hydrolysis processes using food-grade acid and enzyme treatments.
Consolidated procurement through group purchasing organizations is concentrating buyer power among the largest pharmaceutical and contract manufacturing accounts, squeezing spot-market pricing for standard-grade culture media. Regional distributors in France and Italy are losing share to direct manufacturer relationships with top-twenty biotechnology sponsors. The shift is most visible in the United States, where three GPOs now control over half of hospital-affiliated research laboratory spend.
Microbial Culture Market Segmentation
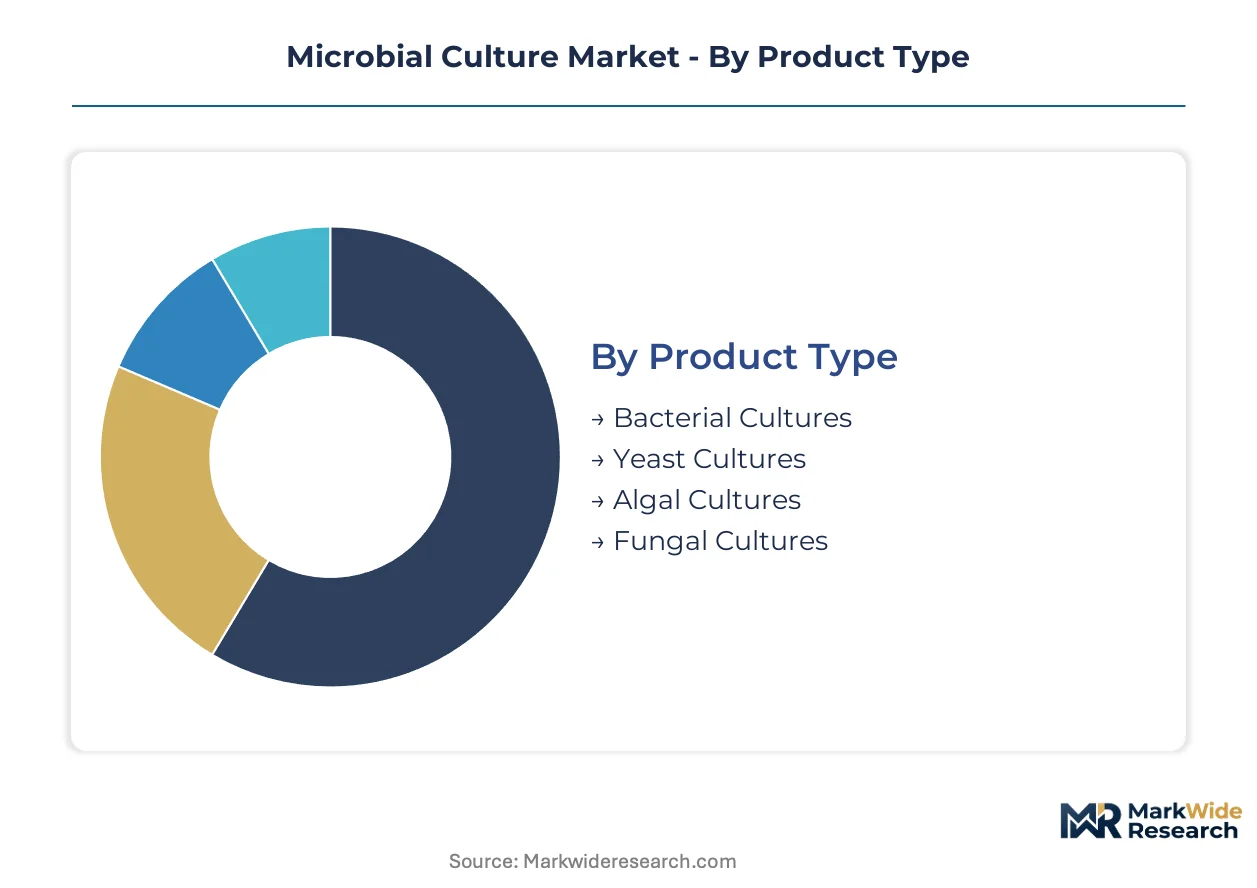
Microbial culture segmentation reflects divergent purity requirements across therapeutic manufacturing versus commodity fermentation. Product type determines raw material sourcing constraints, while application dictates regulatory validation burdens and pricing tiers.
Product Type:
Bacterial and yeast cultures command premium positioning through GMP certification tiers, while algal and fungal alternatives compete on specialized functional attributes.
- Bacterial Cultures:Defined media formulations supporting Gram-positive and Gram-negative propagation with precise peptone, yeast extract, and salt concentrations. Pharmaceutical manufacturers in Germany and the United States concentrate demand here, driven by FDA's cell substrate validation requirements for recombinant protein production.
- Yeast Cultures:Complex nutrient blends optimized for Saccharomyces and Pichia species with tailored carbon sources and trace mineral profiles. Food and beverage manufacturers across Denmark and the Netherlands are expanding procurement volumes fastest as clean-label fermentation ingredient demand reshapes sourcing priorities.
- Algal Cultures:Specialized seawater-based and synthetic formulations supporting photosynthetic microalgae propagation for nutraceutical and biofuel applications.
- Fungal Cultures:Malt extract and potato dextrose-based media designed for filamentous fungi and mushroom spawn production in agricultural and enzyme manufacturing settings.
Today's leader: Bacterial Cultures. Tomorrow's challenger: Yeast Cultures.
Application:
End-use fragmentation splits the market between regulated therapeutic environments and cost-sensitive industrial fermentation.
- Pharmaceuticals:GMP-grade culture media with full traceability documentation, sterility assurance, and endotoxin certification for biologics and cell therapy manufacturing. FDA and EMA inspection protocols drive supplier consolidation toward audit-ready manufacturers with dedicated quality systems.
- Food & Beverage:Fermentation substrates for dairy, brewing, and probiotic applications where clean-label positioning and vegan certification increasingly influence procurement decisions among European and North American manufacturers.
- Agriculture:Biofertilizer and biocontrol agent propagation media serving microbial inoculant producers with less stringent purity requirements than pharmaceutical grades.
- Environmental:Diagnostic and bioremediation culture formulations for wastewater testing and pollutant-degrading microorganism cultivation.
Pharmaceuticals capture margin concentration. Food & Beverage is expanding most quickly.
End User:
Customer type stratification separates high-volume contract manufacturers from fragmented research procurement.
- Biotech Companies:GMP-grade culture media at production scales with dedicated supplier relationships, audit requirements, and long-term contractual frameworks.
- Food Manufacturers:Industrial fermentation media procurement concentrated among multi-national dairy, brewing, and ingredient suppliers with sustainability and certification mandates.
- Research Laboratories:Research-grade bacterial and yeast cultures with flexible formulation requirements and spot-market purchasing patterns.
- Academic Institutions:Cost-optimized culture media for educational and fundamental research applications with limited validation documentation needs.
Biotech Companies anchor revenue stability. Food Manufacturers are gaining share fastest.
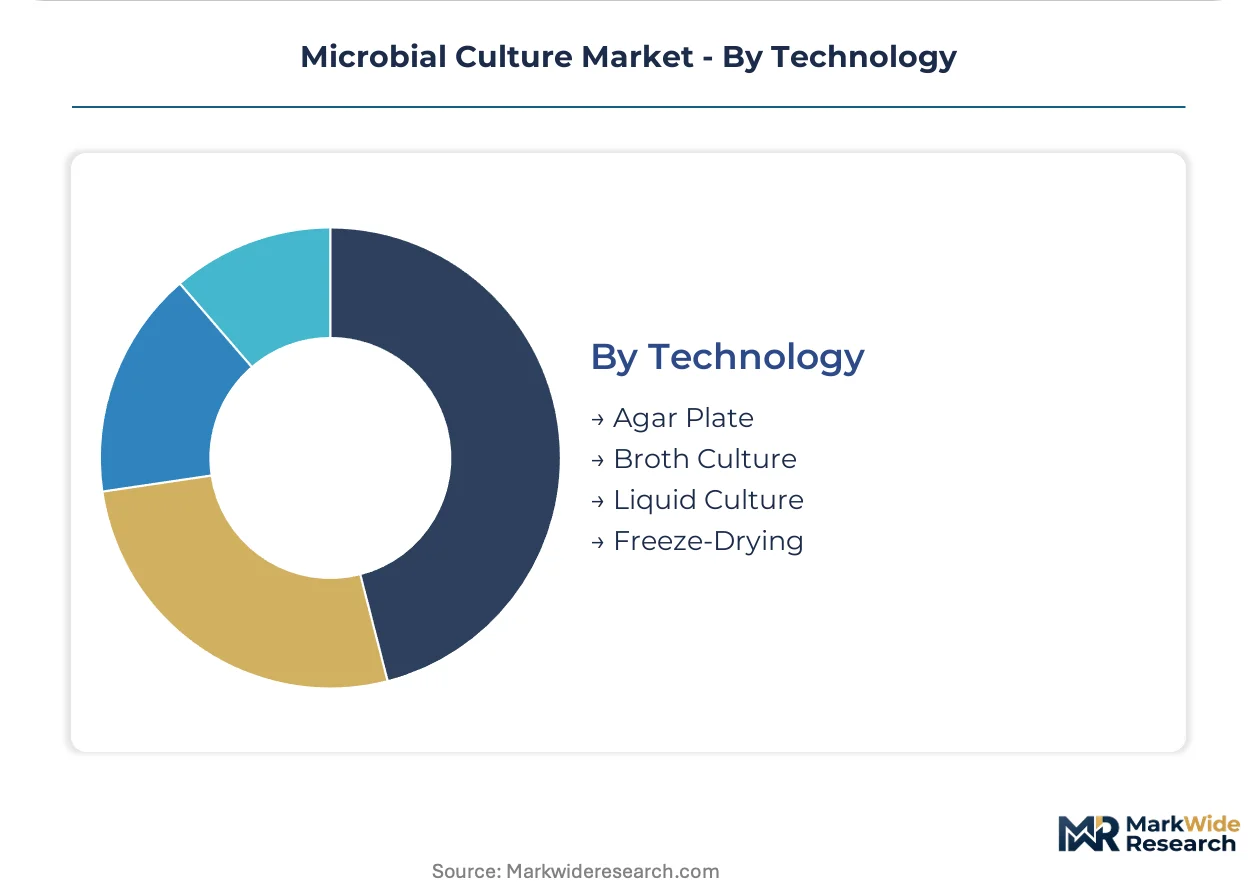
Technology:
Format selection determines contamination risk profiles and automation compatibility across manufacturing scales.
- Liquid Culture:Ready-to-use broth media and concentrates compatible with single-use bioreactor systems and automated filling lines. CDMOs in China and Germany are displacing traditional agar methods fastest as closed-system architecture reduces batch-to-batch variability.
- Freeze-Drying:Lyophilized culture media with extended shelf stability for remote laboratories and field applications where cold chain infrastructure remains limited.
- Agar Plate:Solidified media in pre-poured plates for diagnostic and environmental monitoring applications facing displacement from automated liquid alternatives.
- Broth Culture:Dehydrated powder formulations requiring on-site reconstitution, common in cost-sensitive research and educational settings.
Liquid Culture dominates new facility design. Freeze-Drying defends niche positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States biomanufacturing clusters outpace German fermentation capacity expansion in absolute volume terms, though Bavarian CDMOs maintain tighter GMP certification density per facility. Chinese infrastructure buildout in Jiangsu and Zhejiang provinces is compressing lead times for pharmaceutical-grade culture media procurement.
United States
Massachusetts and North Carolina biotech corridors concentrate cell therapy manufacturing demand for GMP-grade bacterial cultures. FDA's accelerated approval pathways for regenerative medicines compress supplier qualification timelines to ninety-day windows. Boston-Cambridge and Research Triangle Park host the densest clusters of autologous therapy production facilities.
Germany
Baden-Württemberg and Bavaria anchor European demand for specialized yeast culture media in industrial enzyme manufacturing. EMA's Annex 1 contamination control revisions mandate continuous viable monitoring, driving replacement of legacy agar systems. Frankfurt-Rhine-Main CDMOs are consolidating multi-thousand-liter fermentation capacity.
China
Jiangsu and Zhejiang provinces scale pharmaceutical fermentation infrastructure to serve domestic biologics production. NMPA accelerates local inspection capacity for imported culture products, reshaping market access timelines. Suzhou and Hangzhou biomanufacturing parks attract contract manufacturers seeking integrated media supply.
India
Telangana and Karnataka biotechnology parks create first-mover positioning for media suppliers establishing local formulation facilities. CDSCO's streamlined import licensing for research-grade cultures reduces procurement friction. Hyderabad and Bengaluru clusters concentrate vaccine and biosimilar manufacturing demand.
Japan
Kanto and Kansai regions maintain specialized demand for diagnostic culture media in environmental monitoring applications. PMDA enforces stringent endotoxin testing protocols for therapeutic manufacturing substrates. Osaka-Tokyo industrial corridors concentrate fermentation capacity for amino acid and nucleotide production.
Microbial Culture Market Competitive Environment
United States producers anchor one tier; German specialists hold certification-intensive positioning in GMP-grade formulations. The vendor base separates into three functional strata: diversified life science conglomerates with global distribution networks, regional specialists with formulation customization capabilities, and cost-optimized suppliers serving emerging-market laboratories. Consolidation pressure intensifies as group purchasing organizations concentrate buyer power among top-twenty pharmaceutical accounts. Strategic moves center on backward integration into peptone hydrolysis processes and geographic expansion into Indian and Chinese formulation facilities.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Merck KGaA exemplify scale-driven positioning through global distribution infrastructure and specialized media portfolios. HiMedia Laboratories occupies a distinct archetype as a cost-optimized regional specialist targeting emerging-market procurement patterns. These three anchors illustrate the competitive spectrum from premium-certified GMP supply through standardized research-grade formulations.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Becton, Dickinson and Company |
| bioMérieux SA |
| Bio-Rad Laboratories |
| Neogen Corporation |
| Sartorius AG |
| HiMedia Laboratories |
| Eiken Chemical |
| Others |
Value Chain & Pricing Dynamics
Skilled fermentation technologists concentrated in Bavaria and Jiangsu provinces create labor-cost differentials that widen spreads between GMP-certified premium tiers and research-grade economy formulations. EMA's Annex 1 contamination control mandates compress qualification timelines for European suppliers, while Chinese infrastructure buildout enables cost-optimized domestic sourcing that pressures import-dependent spot markets.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade bacterial culture media as domestic biomanufacturing parks achieve GMP certification density previously concentrated in Germany and the United States. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated therapeutic substrates from research-grade formulations and bulk industrial fermentation blends. Price differentiation hinges on endotoxin certification tiers and traceability documentation depth. Cost compression in the economy tier is intensifying because Indian suppliers are capturing emerging-market laboratory procurement with cost-optimized peptone formulations. Academic institutions and small research laboratories exhibit highest price sensitivity; cell therapy sponsors demonstrate lowest sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Dual-sourcing requirements mandated by FDA and EMA for therapeutic manufacturing substrates force buyers to qualify redundant suppliers across at least two regulatory jurisdictions, fragmenting procurement concentration. Geographic supply concentration centers on Germany, China, and the United States for GMP-grade formulations, with India emerging for research-grade production. Raw material dependencies draw from South American meat processing byproducts for animal-derived peptones, soy and wheat gluten for plant-based alternatives, and specialized yeast extracts for nitrogen sourcing. Single-source vulnerability persists in bovine-derived peptone streams subject to BSE/TSE zone restrictions. Distribution runs through direct manufacturer relationships with top-twenty pharmaceutical accounts and group purchasing organizations, displacing regional distributors in France and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EMA's 2022 Annex 1 revision and FDA's accelerated approval pathways for regenerative medicines continuously tighten quality requirements and compress supplier qualification timelines.
For Market Incumbents: Anticipate margin compression from single-use bioreactor technology adoption by reconfiguring liquid culture portfolios for disposable formats and securing backward integration into controlled peptone hydrolysis processes. Plant-based nitrogen source substitution represents a critical R&D lever to bypass TSE/BSE certification burdens and capture vegan-certified fermentation demand in food and cosmetic applications. For New Entrants and Emerging Players: Enter via India's biomanufacturing expansion where CDSCO's streamlined import licensing and state-level biotechnology parks in Telangana and Karnataka create first-mover positioning for local formulation facilities. Continuous manufacturing integration for perfusion bioreactor systems offers the most penetrable white-space, with real-time nutrient feed strategies opening demand for concentrated, customizable culture media concentrates versus traditional batch formulations. For Investors and Strategic Acquirers: Life science conglomerates with global distribution infrastructure are the most active acquirer in this space, seeking regional specialists with formulation customization capabilities to fill portfolio gaps. Acquisition target archetype: mid-tier manufacturers with GMP certification density and established supplier audit documentation capable of serving 90-day qualification windows. Signal to watch: pharmacopoeial harmonization progress between USP, EP, and Chinese standards as divergence in endotoxin testing protocols threatens to fragment quality requirements and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Peptone Hydrolysis | German and Swiss manufacturers secure captive supply of food-grade protein hydrolysis chemistries bypassing REACH Annex XIV nickel catalyst restrictions. |
| Geographic Expansion into Indian Formulation Facilities | Media suppliers establish local production in Hyderabad and Bengaluru to capture CDSCO-streamlined procurement and vaccine manufacturing demand. |
| Plant-Based Peptone Portfolio Development | Soy, wheat gluten, and yeast-derived nitrogen sources bypass TSE/BSE certification burdens and unlock vegan-certified fermentation end-uses. |
| Single-Use Bioreactor Format Reconfiguration | Suppliers adapt liquid culture media portfolios for disposable formats to defend share against specialized entrants targeting compressed facility build-out timelines. |
| Continuous Manufacturing Nutrient Feed Systems | Concentrated, customizable culture media concentrates enable real-time perfusion bioreactor strategies versus traditional batch formulations. |
Study Parameters
Multiple input streams — structured interviews with fermentation technologists and quality assurance directors, regulatory filing analysis from FDA and EMA databases, and customs trade data on peptone and yeast extract imports — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged bioprocess engineers at CDMOs in Germany and China, procurement leads at pharmaceutical manufacturers, and regulatory affairs specialists navigating multi-jurisdictional pharmacopoeial requirements. Secondary validation drew from USP and EP documentary standards, NMPA inspection disclosure records, and SEC filings of diversified life science conglomerates.
Data-stream reconciliation across supply-side capacity assessments and demand-side procurement pattern analysis anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and technology format alongside regional regulatory cluster differentiation. CAGRs were derived from volume-demand buildups by segment cross-referenced against supplier capacity expansion announcements. Forecast inputs incorporated single-use bioreactor adoption curves and EMA Annex 1 compliance investment timelines.
Inputs from regulatory agency disclosure databases and supplier qualification documentation were available through the study window; gaps in real-time procurement pricing from group purchasing organization contracts introduce uncertainty bands around spot-market tier estimates. Deviation in pharmacopoeial harmonization progress or BSE/TSE zone designation changes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Microbiology Testing Market
Industrial Microbiology
Global Escherichia Coli Testing Market
Industrial Microbiology
Microbial API Market
Industrial Microbiology
Salinomycin Market
Industrial Microbiology
Mineral Yeast Market
Industrial Microbiology
Microbial Identification Panels Market
Industrial Microbiology
Microbial Coagulants Market
Industrial Microbiology
Global Starter Culture Market
Industrial Microbiology
Global Microbiome Therapeutics Market
Industrial Microbiology
North America Microbial Protein Market
Industrial Microbiology
Global Microbial Products Market
Industrial Microbiology
Bacillus Subtilis Market
Industrial Microbiology
Automated Microbial Detection Systems Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Global Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Microbial Rennet Market