
 Microbiology Testing Market | 2026-2036
Microbiology Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Microbiology Testing Market Outlook
Hospital procurement channels is rewriting how microbiology testing platforms reach end users, with group purchasing organizations consolidating vendor selection around automated workflow integration. bioMérieux SA leverages its FilmArray syndromic panel architecture to sustain installed-base loyalty across integrated delivery networks. Danaher Corporation anchors its position through Beckman Coulter's clinical microbiology automation line, while Thermo Fisher Scientific Inc. competes on reagent consumables pull-through tied to its QuantStudio PCR instrumentation.
Microbiology testing encompasses the detection, identification, and quantification of microorganisms in clinical, environmental, and industrial specimens through culture-based, molecular, and immunological methods, typically requiring incubation periods of 18-48 hours for traditional methods and 1-6 hours for rapid molecular alternatives. Its primary purpose centers on diagnosing infectious diseases, ensuring pharmaceutical sterility, verifying food safety, and monitoring environmental contamination against established colony-forming unit thresholds. PCR technology leads the test type landscape for bloodstream infection diagnosis due to its sensitivity and turnaround speed, while next-generation sequencing represents the fastest-expanding technology segment as clinical laboratories adopt whole-genome sequencing for outbreak surveillance and antimicrobial resistance profiling. Culturing methods retain substantial volume in pharmaceutical quality control where regulatory validation requirements create high switching costs and stable margin pools.
The FDA enforces sterility testing standards under 21 CFR 211 for pharmaceutical manufacturing, while the EPA regulates drinking water microbial compliance through the Total Coliform Rule, and ISO 15189 accreditation shapes clinical laboratory quality management systems across multiple jurisdictions. These frameworks elevate capital requirements for market entry and drive recurring demand for proficiency testing materials and compliance documentation. Stakeholders must monitor how antimicrobial stewardship mandates and decentralized diagnostic deployment models reshape capital allocation between centralized reference laboratories and near-patient testing locations.
Market Dynamics
Automated workflow integration is compressing turnaround times for microbial identification while simultaneously raising capital barriers for laboratory infrastructure upgrades. Pharmaceutical manufacturers and clinical diagnostics laboratories now face a binary choice between full automation suites and modular point-of-care platforms.
Growth Catalysts
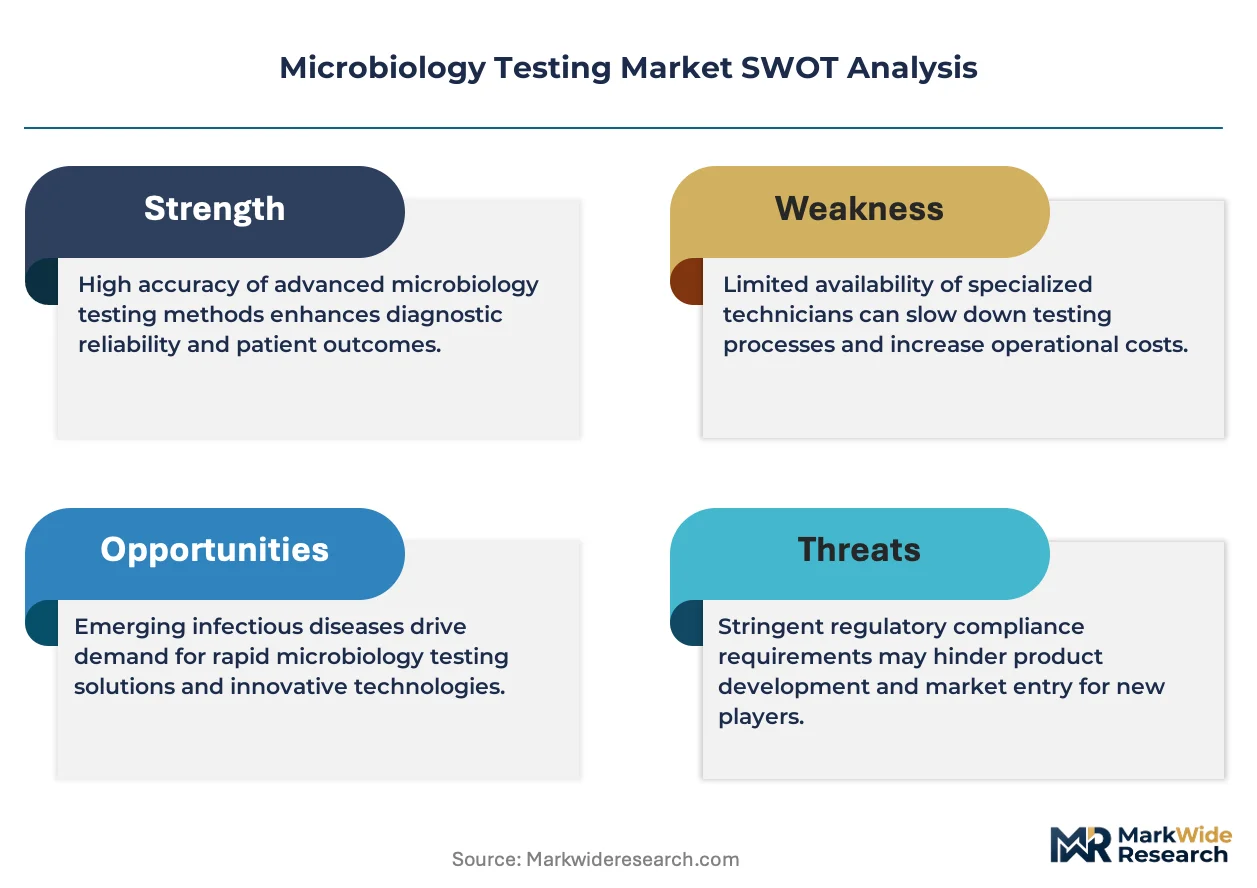
- FDA sterility guidance updates:The FDA's revised 21 CFR 211 sterility testing requirements are mandating rapid microbial detection methods in pharmaceutical manufacturing, accelerating replacement of compendial growth-based assays.
- Antimicrobial resistance surveillance:Whole-genome sequencing for outbreak tracing and resistance profiling is expanding demand in hospital infection control departments and public health reference laboratories.
- Germany's manufacturing cluster:Concentrated R&D infrastructure for automated microbial identification systems in Baden-Württemberg and Bavaria is sustaining regional supply chain density for European distribution.
Market Restraints
- Capital intensity of automation:Full laboratory automation platforms require seven-figure capital commitments, restricting adoption to health systems with consolidated procurement budgets.
- Regulatory validation inertia:Pharmaceutical quality control methods locked under FDA 21 CFR 211 and EU GMP Annex 1 create switching costs that extend replacement cycles beyond technological obsolescence.
- Reagent consumables dependency:Closed-system architectures tie laboratories to single-source consumables, exposing operations to supply concentration risk and price volatility.
Strategic Opportunities
- Decentralized diagnostic deployment:Near-patient molecular testing platforms are penetrating urgent care networks and pharmacy clinics, bypassing centralized laboratory bottlenecks.
- EU Green Deal alignment:Sustainability mandates for reduced laboratory waste and energy consumption are creating specification advantages for cartridge-based systems over traditional culture methods.
- Food safety molecular adoption:Pathogen detection in meat and dairy processing is shifting from enrichment culture to PCR-based screening, opening industrial microbiology applications beyond clinical settings.
Industry Challenges
- Cross-trained technician scarcity:Molecular diagnostics and bioinformatics competencies are outpacing laboratory workforce development programs, constraining operational scaling for mid-sized facilities.
- Legacy LIS integration complexity:Automated microbial identification platforms require middleware development to interface with existing laboratory information systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbiology Testing Market |
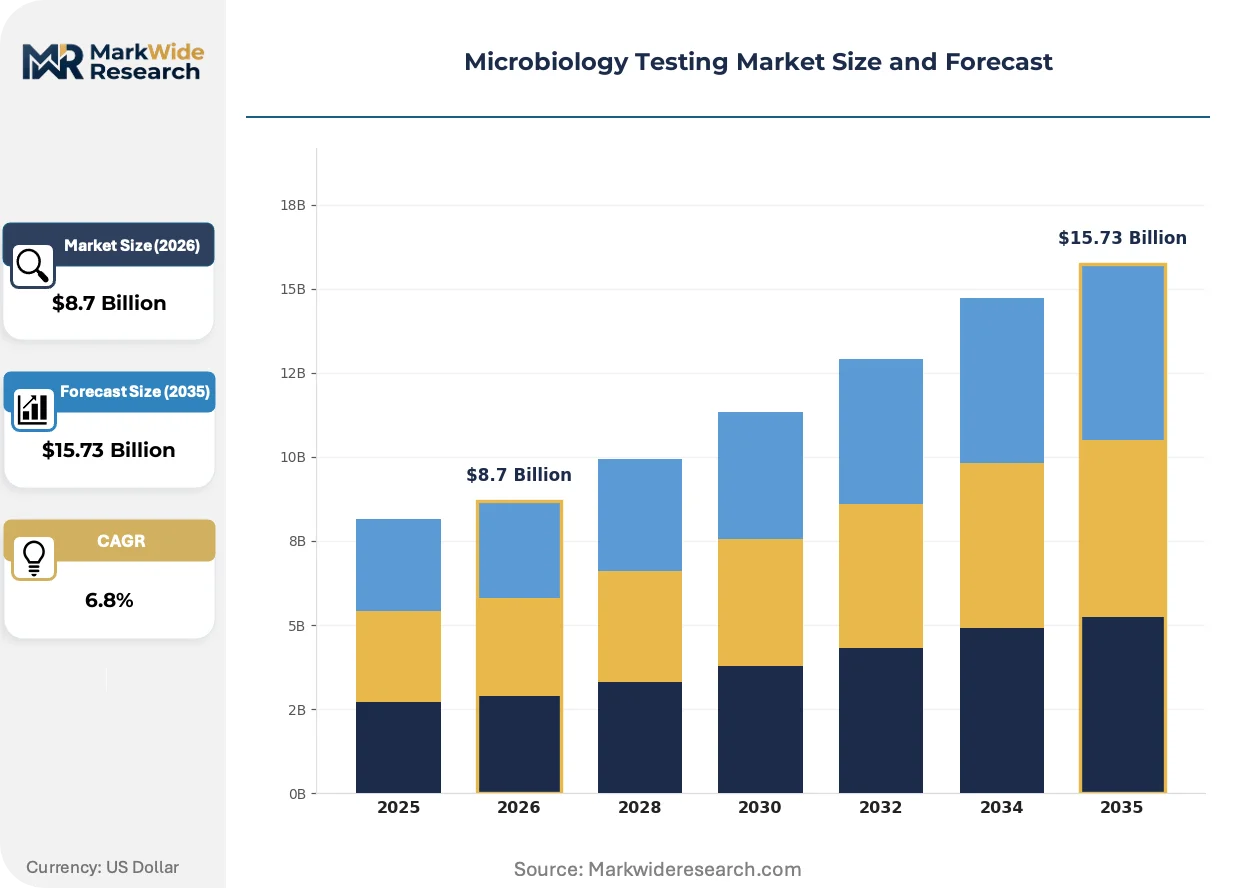
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Culturing, PCR, Serology, Microscopy Sample Type: Blood, Urine, Swab, Tissue End User: Clinical Laboratories, Research Institutions, Pharmaceutical Companies, Hospitals Technology: Flow Cytometry, Mass Spectrometry, Immunoassays, Next-Generation Sequencing |
| Companies Covered | Abbott Laboratories, bioMérieux SA, Thermo Fisher Scientific Inc., Sartorius AG, Bruker Corporation, Danaher Corporation, Becton Dickinson and Company, Eurofins Scientific SE, Bio-Rad Laboratories Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbiology Testing Market Strategic Shifts
Digital microbiology is collapsing the distinction between phenotypic and genotypic identification methods. Laboratories are converging on platforms that combine automated imaging with nucleic acid detection in unified workflows.
Mass spectrometry-based microbial identification is hybridizing with antimicrobial susceptibility testing in single-instrument configurations. Academic medical centers in the United States are deploying these integrated platforms to compress diagnostic turnaround from days to hours. The technology is hybridizing previously separate capital equipment categories, forcing vendors to defend installed bases through workflow consolidation rather than instrument replacement cycles.
EU MDR and IVDR implementation timelines are reclassifying microbiology diagnostics as higher-risk devices, triggering enhanced clinical evidence requirements. Manufacturers are restructuring quality management systems and post-market surveillance protocols to maintain CE marking access. In vitro diagnostic reagent producers serving European markets are absorbing compliance costs through portfolio rationalization, discontinuing lower-volume SKUs that cannot support regulatory filing investments.
Group purchasing organizations are consolidating vendor selection criteria around total cost of ownership metrics rather than capital expenditure alone. Hospital procurement committees now weight reagent pricing, service contract terms, and interoperability specifications in multi-year agreements. This behavioral shift is most pronounced in United States integrated delivery networks, where standardized instrument platforms across dozens of sites generate volume leverage unavailable to standalone laboratories.
Microbiology Testing Market Segmentation
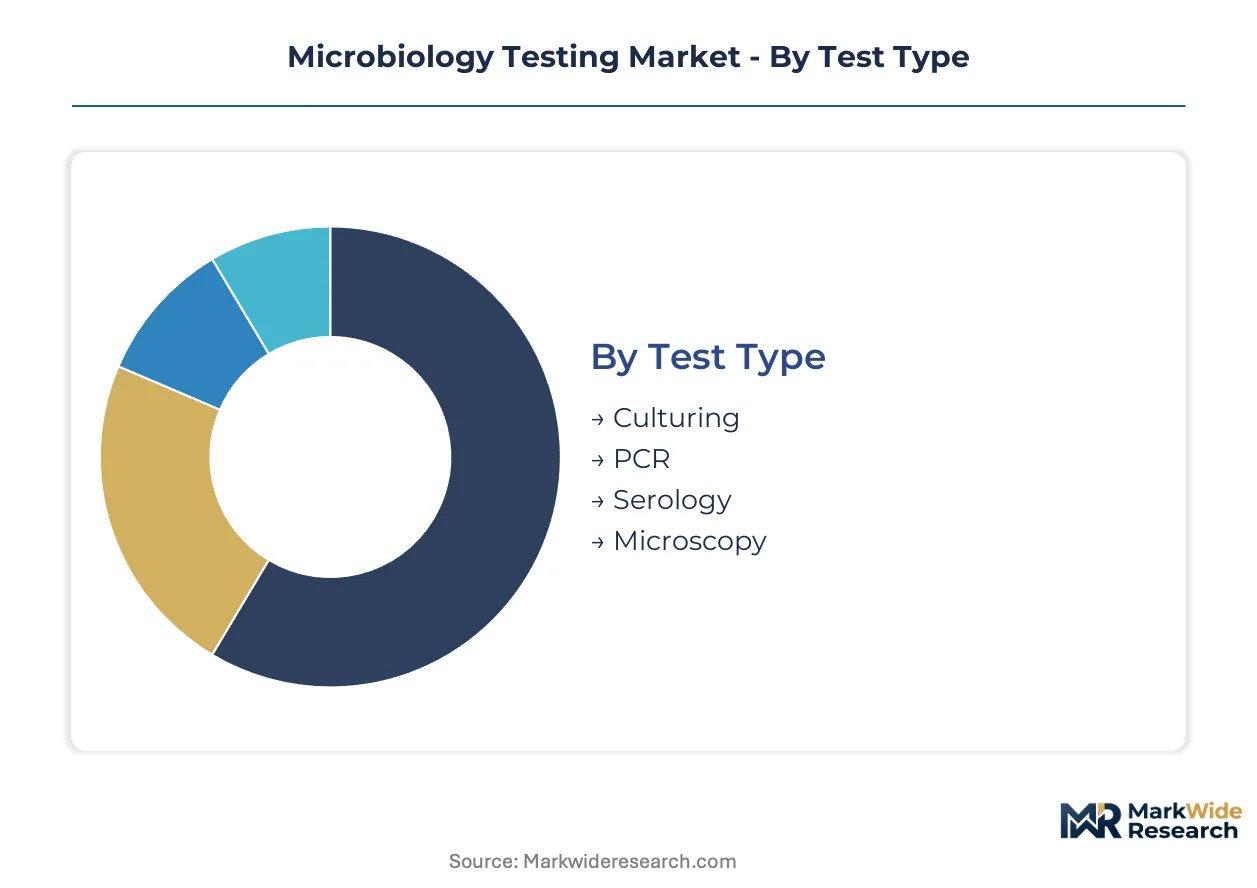
Segmentation in microbiology testing reveals divergent technology lifecycles and procurement patterns across clinical, pharmaceutical, and research environments. Laboratories allocate capital differently based on regulatory validation requirements, sample throughput demands, and integration complexity with existing infrastructure.
Test Type:
Mature growth-based methods coexist with emerging molecular platforms, creating a bifurcated investment landscape where regulatory inertia and speed imperatives pull procurement in opposite directions.
- Culturing:Growth-based detection on selective and differential media remains the regulatory gold standard for pharmaceutical sterility testing under FDA 21 CFR 211 and EU GMP Annex 1. Pharmaceutical quality control laboratories in Germany and Switzerland maintain substantial installed bases due to compendial validation requirements that extend replacement cycles beyond technological obsolescence.
- PCR:Nucleic acid amplification delivers pathogen identification in 1-6 hours versus 18-48 hours for traditional methods. Hospital laboratories in the United States prioritize syndromic respiratory and bloodstream infection panels to compress antimicrobial stewardship decision timelines.
- Serology:Antibody detection methods retain relevance in blood bank screening and epidemiological surveillance where pathogen exposure history matters more than active infection status.
- Microscopy:Gram staining and direct fluorescent antibody techniques persist in resource-limited settings and rapid presumptive diagnostics where capital constraints preclude molecular infrastructure.
Culturing retains volume leadership in pharmaceutical applications; PCR holds the steepest expansion curve in clinical diagnostics.
Sample Type:
Sample matrix complexity drives platform selection, with liquid specimens enabling automation and solid tissues demanding specialized preparation workflows.
- Blood:Bloodstream infection diagnosis concentrates demand for rapid molecular platforms, with academic medical centers deploying PCR and mass spectrometry to reduce time-to-effective-therapy. Sepsis mortality pressure makes this the highest-priority specimen type for automation investment.
- Urine:High-volume screening for urinary tract infections sustains automated culture systems in centralized laboratories, though rapid dipstick and PCR alternatives are penetrating urgent care settings.
- Swab:Respiratory and wound specimens flow through syndromic panel architectures, with integrated delivery networks standardizing platforms across outpatient and inpatient sites.
- Tissue:Surgical specimen analysis requires specialized processing for anaerobic and fastidious organisms, concentrating demand in reference laboratories with dedicated microbiology pathologists.
Blood specimens command the highest per-test reimbursement; tissue analysis expands most quickly as surgical site infection surveillance intensifies.
End User:
Customer type determines capital scale and procurement channel, with consolidated health systems leveraging volume against standalone laboratories prioritizing flexibility.
- Clinical Laboratories:High-throughput processors face binary automation choices—full laboratory automation suites versus modular point-of-care platforms—based on health system consolidation status.
- Research Institutions:Academic medical centers deploy whole-genome sequencing for outbreak surveillance and antimicrobial resistance profiling, absorbing higher per-sample costs for epidemiological granularity.
- Pharmaceutical Companies:Quality control budgets expand for microbial contamination detection, with sterility testing and environmental monitoring locked under FDA and EMA validation requirements that create stable consumables demand.
- Hospitals:Near-patient molecular testing penetrates urgent care networks and pharmacy clinics, bypassing centralized laboratory bottlenecks for rapid infectious disease triage.
Clinical laboratories retain volume leadership; hospital-based decentralized testing climbs the fastest as bedside diagnostics gain reimbursement traction.
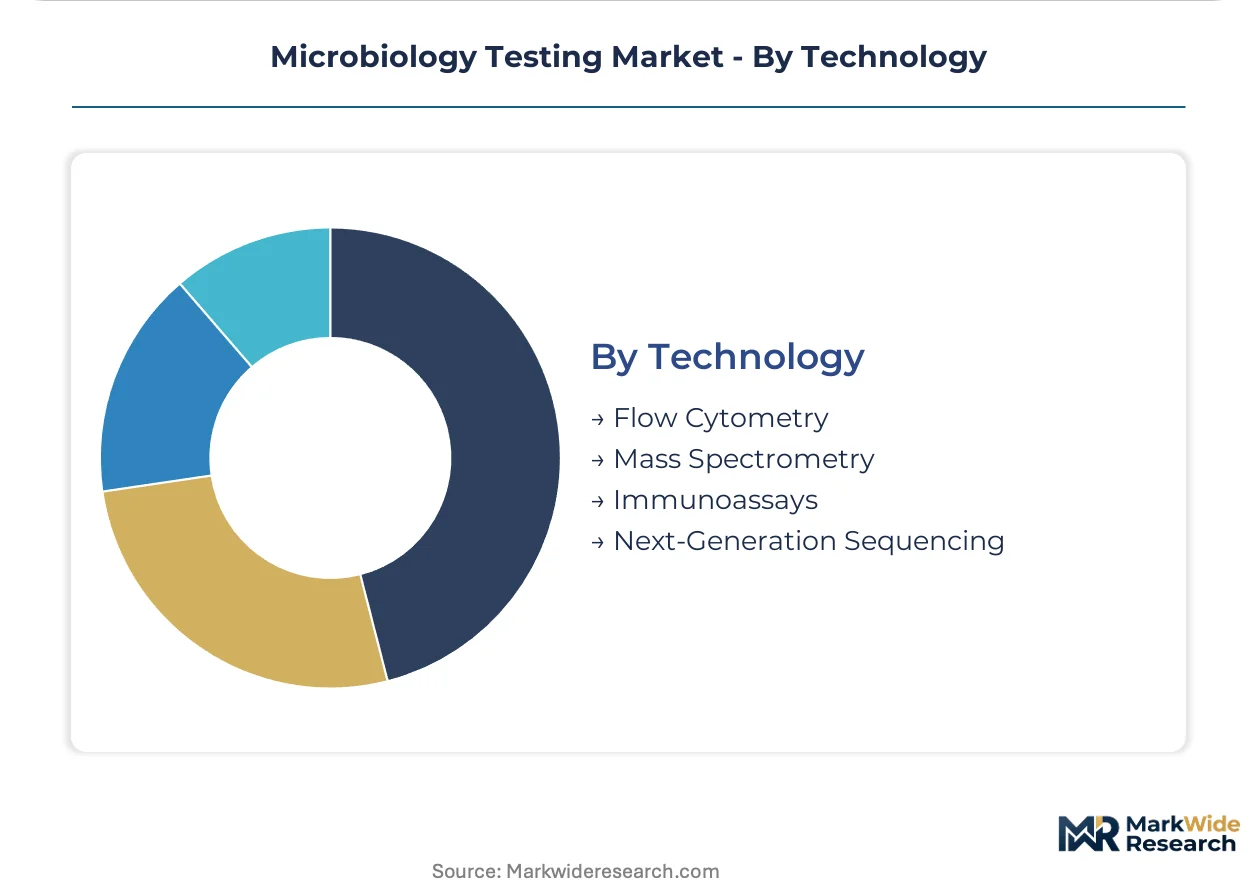
Technology:
Technology platforms hybridize previously separate detection modalities, forcing vendors to defend installed bases through workflow consolidation rather than instrument replacement cycles.
- Flow Cytometry:Cell counting and viability assessment integrate into automated microbial identification workflows, with pharmaceutical applications driving precision requirements for bioburden testing.
- Mass Spectrometry:MALDI-TOF platforms collapse identification timelines from days to hours by analyzing ribosomal protein spectra. United States academic medical centers deploy hybrid configurations combining identification with antimicrobial susceptibility testing.
- Immunoassays:Enzyme-linked and chemiluminescent methods retain cost advantages for high-volume screening where pathogen identity is known and antigen detection suffices.
- Next-Generation Sequencing:Whole-genome sequencing represents the fastest-expanding technology segment, with public health reference laboratories adopting platforms for outbreak tracing and resistance gene profiling.
Mass spectrometry anchors clinical identification volume; next-generation sequencing gains share fastest as bioinformatics pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites the Netherlands' distribution role for temperature-sensitive reagents across Western Europe. Germany's Rhine-Main corridor links pharmaceutical manufacturing clusters to centralized testing laboratories. The US Interstate 95 pharmaceutical corridor connects API producers to quality control facilities from New Jersey through North Carolina.
United States
Academic medical centers in Boston and Baltimore deploy whole-genome sequencing platforms for outbreak surveillance. FDA's 21 CFR 211 sterility testing updates mandate rapid microbial detection in pharmaceutical manufacturing. The Research Triangle Park in North Carolina concentrates contract testing organizations serving generic drug manufacturers.
Germany
Baden-Württemberg's automation engineering base supplies robotic liquid handling systems to clinical laboratories. EU GMP Annex 1 revisions for sterile medicinal products tighten environmental monitoring requirements. Munich's biotechnology cluster anchors R&D for mass spectrometry-based microbial identification systems.
China
Domestic pharmaceutical producers in Jiangsu and Zhejiang provinces expand quality control capacity for export-oriented manufacturing. NMPA's alignment with ICH Q5A guidelines elevates viral safety testing standards for biologics. The Suzhou Industrial Park hosts joint ventures between multinational diagnostics firms and local automation suppliers.
India
Contract research organizations in Hyderabad and Bangalore absorb microbiology testing demand from European pharmaceutical clients. CDSCO's revised Schedule M requirements for Good Manufacturing Practices intensify contamination control protocols. Gujarat's pharmaceutical manufacturing zone concentrates environmental monitoring laboratories serving API exporters.
United Kingdom
London's academic hospital networks pilot rapid molecular platforms for antimicrobial stewardship programs. MHRA's post-Brexit recognition of EU-issued CE marks maintains device market access while diverging on software-as-medical-device classifications. The Cambridge life sciences cluster develops bioinformatics pipelines for resistance gene profiling.
Microbiology Testing Market Competitive Environment
On the supply side, the industry is consolidating around integrated platform vendors capable of spanning identification, susceptibility testing, and workflow automation. Full-system providers compete against modular specialists through installed-base lock-in and consumables pull-through. Three archetypes dominate: diversified life science conglomerates with diagnostics divisions, pure-play microbiology automation specialists, and contract testing organizations with captive instrument development. Consolidation through acquisition of niche technology targets and exclusive distribution partnerships for regional market penetration represent the dominant competitive moves.
Among diversified conglomerates, Danaher Corporation and Thermo Fisher Scientific Inc. exemplify scale-driven platform bundling, while bioMérieux SA occupies a position as the dedicated microbiology pure-play. These three anchors represent contrasting strategic postures—horizontal life science breadth versus vertical infectious disease specialization—each defending margin pools through different combinations of instrument placement and reagent dependency.
| Leading Market Players |
|---|
| Abbott Laboratories |
| bioMérieux SA |
| Thermo Fisher Scientific Inc. |
| Sartorius AG |
| Bruker Corporation |
| Danaher Corporation |
| Becton Dickinson and Company |
| Eurofins Scientific SE |
| Bio-Rad Laboratories Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in automated liquid handling systems across Baden-Württemberg is compressing capital equipment margins while simultaneously elevating reagent consumables pricing power for closed-system vendors. This utilization asymmetry forces mid-sized clinical laboratories into long-term consumables contracts that lock in total cost of ownership premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates fully automated identification platforms from modular PCR systems and manual culture methods. Price differentiation hinges on FDA 510(k) clearance tier and ISO 15189 accreditation bundling. Cost compression in the economy tier is intensifying because group purchasing organizations are consolidating vendor selection around reagent pricing transparency. Standalone reference laboratories exhibit the highest price sensitivity, while integrated delivery networks prioritize workflow interoperability over per-test economics.
Supply Chain Analysis
Contract manufacturing for disposable cartridges concentrates among German precision molding specialists and Swiss medical device foundries with cleanroom certification. Geographic supply concentration spans Germany, Switzerland, and the United States for instrumentation assembly, with plastic resin and optical components feeding from specialized chemical suppliers. Single-source vulnerability runs through lyophilized reagent formulations held by captive production facilities. Distribution runs through cold-chain logistics networks anchored at the Port of Rotterdam for temperature-sensitive European distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as antimicrobial stewardship mandates splinter procurement authority between centralized laboratories and hospital infection control departments, creating niche entry points for specialized workflow vendors.
For Market Incumbents: Harden installed-base defenses through backward integration into reagent manufacturing and exclusive service contracting with integrated delivery networks. Molecular diagnostics startups threaten margin pools in syndromic panels; vertical integration into consumables production anchors switching costs. For New Entrants and Emerging Players: Mid-tier hospital laboratories in India and Southeast Asia represent the most penetrable entry point for cartridge-based molecular platforms bypassing legacy LIS infrastructure. Direct sales partnerships with regional distributors circumvent GPO consolidation barriers in mature markets. For Investors and Strategic Acquirers: Capital is best deployed toward bioinformatics pipeline specialists with regulatory-grade resistance profiling algorithms. Long-term viability favors platforms spanning identification-to-susceptibility testing in unified workflows. Watch FDA guidance alignment on rapid sterility methods as inflection signal for pharmaceutical QC automation demand.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU IVDR compliance investment preserves European market access for IVD reagent portfolios. |
| Hospital System Partnership | Multi-site standardization agreements generate volume leverage against standalone laboratory competitors. |
| Software Companion Development | LIS middleware integration compresses implementation timelines for automated platform deployment. |
| Reimbursement Strategy | AMR surveillance coding alignment secures favorable coverage for whole-genome sequencing panels. |
| Acquisition of Specialist Firm | Mass spectrometry susceptibility testing targets consolidate identification and AST into single-instrument workflows. |
Study Parameters
The analysis maps automated identification platforms, molecular diagnostics, and traditional culture systems, each validated through laboratory directors, GPO contracts managers, regulatory affairs leads, and pharmaceutical QC officers. Primary interviews combined with FDA 510(k) filings, EMA CE marking databases, hospital procurement records, and ISO accreditation registries. Bottom-up instrument placement counts and top-down reagent consumables demand triangulate market sizing across the analysis window.
Assumptions held regulatory validation timelines and antimicrobial stewardship mandate intensity fixed, while pharmaceutical R&D spending and hospital consolidation rates varied across sensitivity scenarios. Segmentation dimensions modeled include test type, sample matrix, end-user category, technology platform, and regional regulatory cluster. CAGRs derived from instrument replacement cycle analysis and reagent pull-through coefficients calibrated against proficiency testing volume trends.
Practitioners should monitor FDA sterility guidance implementation pace and EU MDR transition enforcement for early signals of platform replacement acceleration. Forecasts reflect assumptions regarding regulatory harmonization and GPO procurement consolidation trajectories. Quarterly review of hospital capital expenditure commitments and pharmaceutical QC budget disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Mycoplasma Plate Antigens Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Anti-Microbial Anti-Fungal Test Market
Industrial Microbiology
Global Microbiome Therapeutics Market
Industrial Microbiology
Industrial Bioprocessing Market
Industrial Microbiology
Global Microbial Protein Market
Industrial Microbiology
Lipase Market
Industrial Microbiology
Microbial Biosurfactants Market
Industrial Microbiology
Microbial Culture Market
Industrial Microbiology
Microbial Therapeutic Products Market
Industrial Microbiology
Microbial Seed Treatment Market
Industrial Microbiology
Middle East Feed Probiotics Market
Industrial Microbiology
Mesophilic Bacteria Market
Industrial Microbiology
Microbial Cell Banking Market
Industrial Microbiology
Industrial Microbiology Market
Industrial Microbiology
Global Microbial Testing Market