
 South America Biopesticides Market | 2026-2036
South America Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
South America Biopesticides Market Analytics
Buyer concentration across South American row-crop agriculture is broadening as cooperatives and large-scale farming enterprises in Brazil and Argentina consolidate procurement decisions while smaller specialty-crop operations fragment demand across niche biological suppliers. Koppert Biological Systems leverages its greenhouse and protected-crop expertise to anchor service contracts with high-value vegetable producers in São Paulo state. Certis Biologicals competes through specialized Bacillus-based formulations tailored to tropical fungal pressure. BASF SE extends its conventional crop protection distribution infrastructure into biological adjacencies, capturing channel economics that pure-play biopesticide firms cannot replicate alone.
Biopesticides comprise naturally derived or live-organism formulations—primarily bacterial, fungal, viral, or botanical extracts—engineered to suppress agricultural pests through biological antagonism, behavioral disruption, or growth inhibition rather than direct chemical toxicity, with active ingredient concentrations typically measured in colony-forming units or spore counts per milliliter. Their primary commercial purpose centers on integrated pest management rotations that preserve beneficial insect populations and delay resistance evolution in target pest populations. Microbial biopesticides dominate current revenue pools due to established manufacturing fermentation infrastructure and reproducible quality standards, while plant extracts command premium positioning in organic-certified supply chains where synthetic residue tolerances approach zero. Liquid formulations lead volume throughput because of compatibility with existing aerial and ground spray equipment, though granular seed-treatment formats are gaining structural importance as precision-planting technology penetrates Argentine wheat and Brazilian corn systems.
ANVISA in Brazil and SENASA in Argentina enforce divergent registration pathways for biological crop protection agents, with Brazil's streamlined provisional approval mechanism accelerating market entry for novel microbial strains while Argentine toxicity data requirements create longer validation timelines. Brazil's Law 7.802 and subsequent decrees explicitly differentiate biological from synthetic chemical registration, reducing compliance costs for domestic biopesticide manufacturers. Stakeholders must monitor how MERCOSUR harmonization negotiations reshape cross-border product equivalence recognition, as regulatory misalignment currently fragments scale economics for firms operating across the Southern Cone.
Market Dynamics
ANVISA's reclassification protocols and Brazil's Law 7.802 are compressing synthetic chemical registration timelines while accelerating provisional approvals for microbial strains, forcing incumbent agrochemical distributors to rebuild portfolios around biological rotation cycles.
Growth Catalysts
- Soybean IPM mandates:Brazil's Mato Grosso state now requires biological rotation in integrated pest management programs, institutionalizing procurement of Bacillus thuringiensis and Beauveria bassiana formulations for fall armyworm suppression.
- ANVISA residue tolerance evolution:Brazil's national health surveillance agency has tightened maximum residue limits for synthetic insecticides on fresh produce exports, redirecting vegetable grower procurement toward botanical extracts and viral bioinsecticides.
- Seed-treatment format expansion:Precision planting technology penetration across Argentine wheat and Brazilian corn systems is creating attach-rate opportunities for granular Trichoderma and Pseudomonas inoculants at planting.
Market Restraints
- Fermentation input cost volatility:Molasses and soybean meal price swings directly compress margins for domestic microbial biopesticide manufacturers in Brazil's São Paulo industrial corridor.
- SENASA validation timelines:Argentina's national food safety and quality service requires extended toxicity dossiers for novel microbial strains, fragmenting scale economics for firms attempting cross-border product equivalence.
- Synthetic pyrethroid substitution:Low-cost generic chemical insecticides retain price-positioning dominance in Paraguayan and Bolivian row-crop markets where IPM compliance remains voluntary.
Strategic Opportunities
- Uruguay organic export corridor:The country's zero-residue berry and citrus supply chains to European retailers are creating premium positioning for viral bioinsecticides and plant extract formulations.
- MERCOSUR harmonization tailwind:Pending mutual recognition protocols for biological crop protection agents would collapse duplicate registration costs for manufacturers operating across Brazil, Argentina, Paraguay, and Uruguay.
- Drone application convergence:Compatibility between liquid microbial formulations and aerial spray platforms is opening service-contract models for soybean and cotton pest suppression in Brazil's Cerrado expansion zones.
Industry Challenges
- Strain preservation expertise gap:Cold-chain maintenance and viability monitoring for live-organism formulations requires specialized technical staff scarce outside Brazil's southeastern research clusters.
- Legacy equipment incompatibility:Existing ground spray rigs calibrated for synthetic chemical droplet sizes require nozzle and pressure reconfiguration to prevent shear damage to fungal spore suspensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Biopesticides Market |
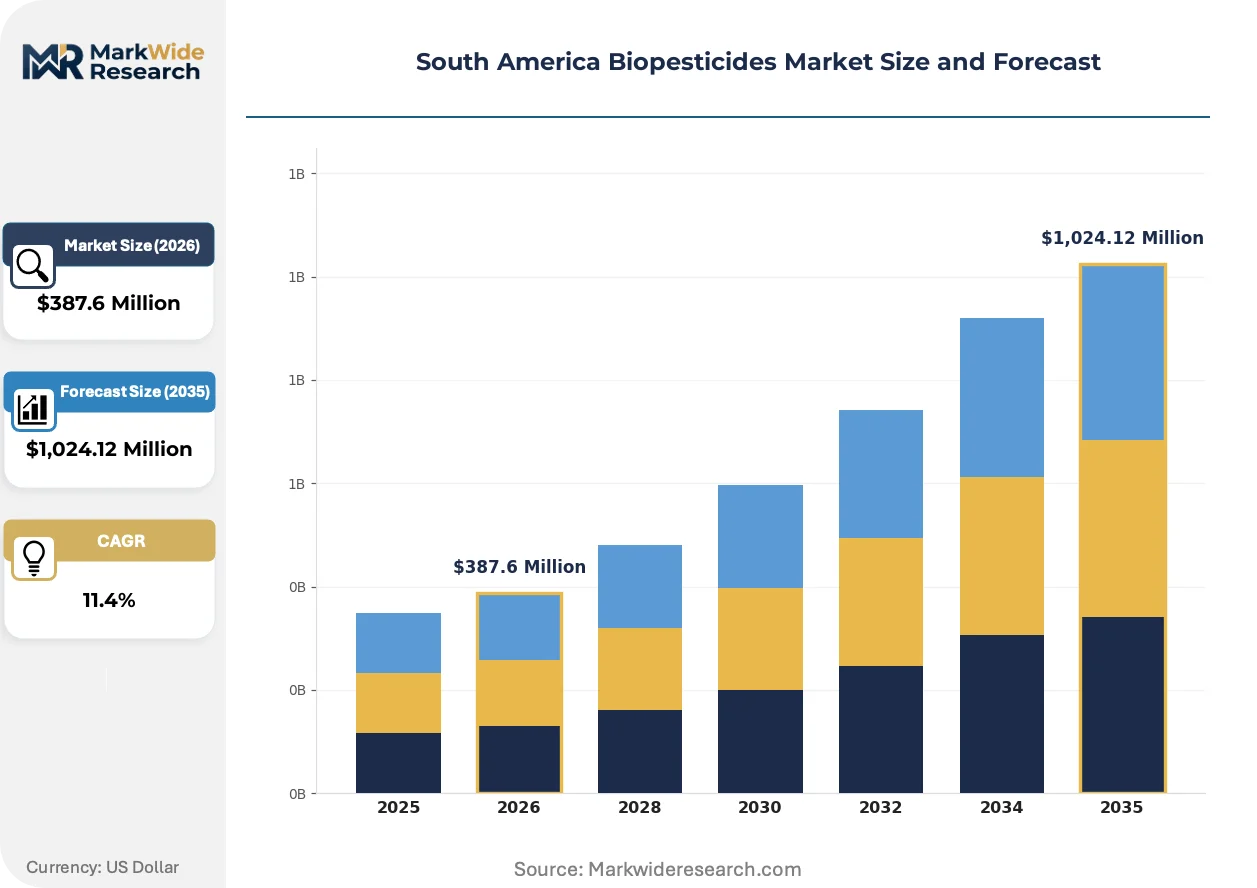
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial, Plant Extracts, Biochemical, Others Target Pest: Insects, Weeds, Fungi, Nematodes Formulation Type: Liquid, Powder, Granular, Others Application Method: Folioar Spray, Soil Application, Seed Treatment, Others |
| Companies Covered | Certis Biologicals, Coromandel International Limited, Vittia S.A., Koppert Biological Systems, Valent BioSciences LLC, Corteva Agriscience, IPL Biologicals Limited, Atlántica Agrícola, BASF SE, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Biopesticides Market Evolving Landscape
Biological formulation science and digital agriculture tools are converging to reshape how South American growers deploy pest suppression, with precision application technologies and regulatory data systems compressing the gap between laboratory strain development and field efficacy validation.
RNA interference biopesticides are overtaking conventional microbial sprays in specialty crop segments. These nucleic acid-based formulations silence essential pest genes through topical application. Strawberry and tomato producers in São Paulo's protected agriculture zones are piloting RNAi sprays against whitefly and thrips at commercial scale. The technology is overtaking slower-acting bacterial alternatives where speed-to-kill determines harvest window compliance.
Brazil's Law 7.802 implementing decrees have established distinct biological product categories with reduced data requirements versus synthetic chemicals. This regulatory architecture is diverting domestic R&D investment toward indigenous microbial strain discovery. Argentine manufacturers without Brazilian subsidiary registration are losing access to the region's largest addressable market as provisional approval pathways favor locally incorporated entities.
Cooperative procurement consolidation is compressing supplier negotiation cycles. Large-scale farming enterprises and agricultural cooperatives in Argentina's Pampas and Brazil's Center-West are centralizing biopesticide tender decisions under specialized technical managers. Direct manufacturer relationships are displacing traditional distributor intermediaries in soybean and corn pest management programs, with Mato Grosso cooperatives leading contract restructuring toward volume-based biological rotation commitments.
South America Biopesticides Market Segmentation
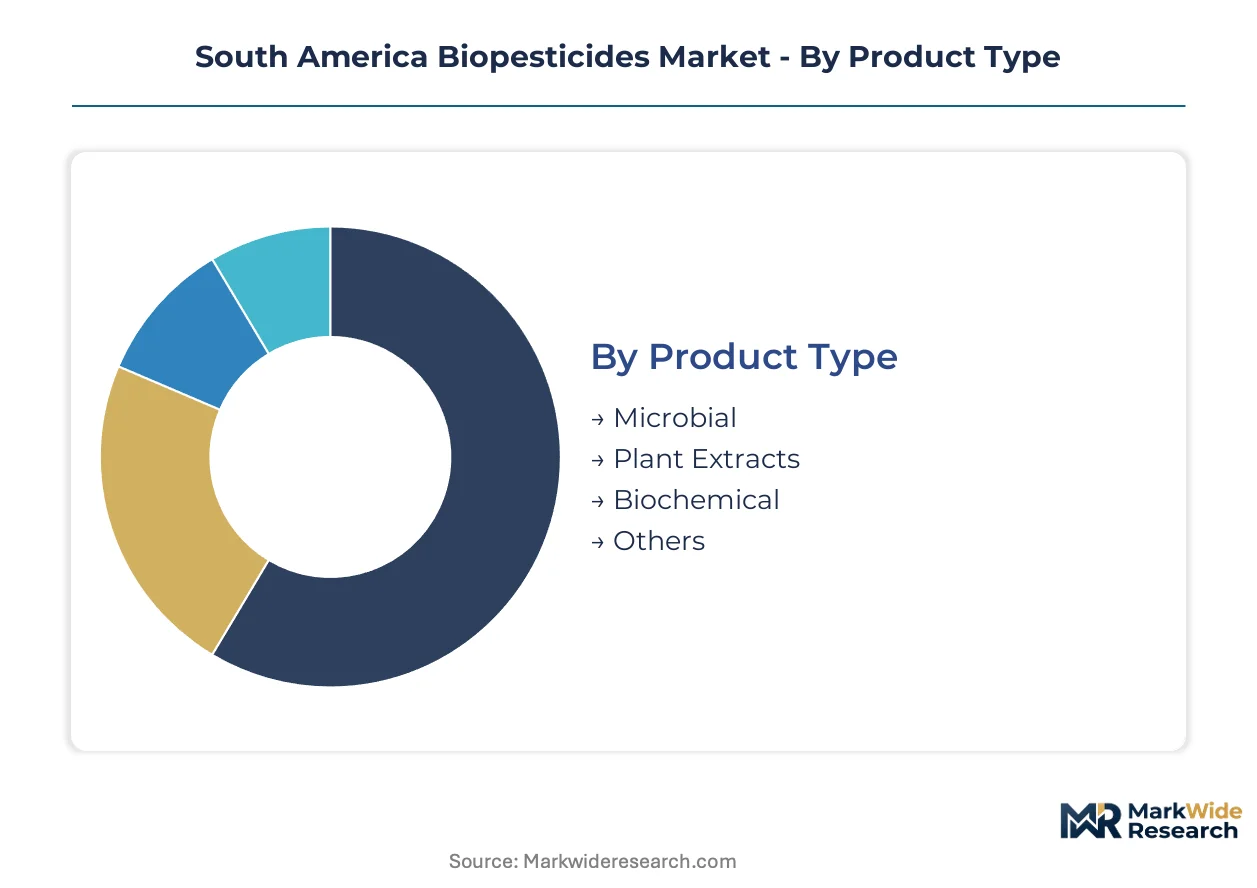
South American biopesticide procurement diverges sharply across product chemistry, target pest ecology, and application infrastructure. Segmentation reveals where capital deployment concentrates and which technical formats unlock new acreage.
Product Type:
Capital intensity peaks with fermentation infrastructure for live-organism manufacturing, while extraction facilities for botanical compounds require less upfront equipment but secure premium pricing through certification.
- Microbial:Bacterial, fungal, and viral formulations dominate commercial volumes through established fermentation protocols. Brazilian manufacturers in São Paulo's industrial corridor anchor supply for soybean IPM programs in Mato Grosso, where Beauveria bassiana and Bacillus thuringiensis rotations suppress fall armyworm resistance. ANVISA's streamlined provisional approval pathways favor domestic strain registration, accelerating pipeline access for locally incorporated entities.
- Plant Extracts:Botanical insecticides and fungicides command positioning in zero-residue export supply chains. Uruguayan berry and citrus producers procure neem, pyrethrin, and essential oil formulations for European retail compliance, with premium pricing reflecting organic certification requirements.
- Biochemical:Semiochemicals and plant growth regulators disrupt pest behavior without direct toxicity. Argentine viticulture and protected vegetable operations deploy pheromone mating disruption for Lepidoptera management.
- Others:Mineral-based and protein-based formulations occupy niche positions in specialty crop segments with restrictive residue protocols.
Most installed capacity flows through Microbial. Expansion is steepest in Plant Extracts.
Target Pest:
Application economics vary dramatically by pest biology—chewing insects permit contact-acting sprays while soil-dwelling nematodes demand delivery system reinvestment.
- Insects:Lepidoptera, Hemiptera, and Coleoptera suppression drives the largest addressable acreage. Brazil's Cerrado soybean belt and Argentina's Pampas corn systems deploy Bacillus thuringiensis and viral bioinsecticides against fall armyworm and stink bug complexes, with drone application services expanding in Mato Grosso and Goiás.
- Fungi:Fungal pathogens threaten humid-climate row crops and protected vegetables. São Paulo greenhouse operators and Argentine wheat systems prioritize Trichoderma and Bacillus subtilis formulations for soil-borne and foliar disease suppression.
- Weeds:Bioherbicides remain technically constrained by narrow host ranges and environmental persistence requirements. Adoption concentrates in organic-certified specialty systems with manual labor cost pressures.
- Nematodes:Soil-dwelling parasitic roundworms damage root systems in Brazilian soybean and vegetable rotations. Pasteuria and Purpureocillium formulations require precision placement equipment, limiting penetration outside large-scale farming enterprises with technical management capacity.
Volume concentrates in Insects. Technical innovation is accelerating most quickly in Fungi.
Formulation Type:
Equipment compatibility determines formulation economics—liquid formats leverage existing spray infrastructure while granular and powder systems demand planting technology upgrades.
- Liquid:Aqueous suspensions and emulsifiable concentrates dominate throughput through compatibility with aerial and ground spray rigs. Brazilian cotton and soybean operations in the Cerrado rely on liquid Beauveria bassiana and Bacillus thuringiensis for foliar pest suppression, though nozzle reconfiguration prevents shear damage to fungal spore viability.
- Granular:Precision planting technology penetration across Argentine wheat and Brazilian corn creates attach-rate opportunities for Trichoderma and Pseudomonas inoculants applied at planting. Seed-treatment equipment upgrades in Mato Grosso and Rio Grande do Sul cooperatives are expanding granular format adoption.
- Powder:Wettable powders and dust formulations serve protected agriculture and smallholder segments with limited water access or mechanization. São Paulo vegetable cooperatives deploy powder Bacillus formulations in greenhouse ventilation systems.
- Others:Gel, tablet, and encapsulated formats occupy experimental positions in drone delivery and precision release applications.
Manufacturing investment clusters in Liquid. Format conversion is climbing the fastest in Granular.
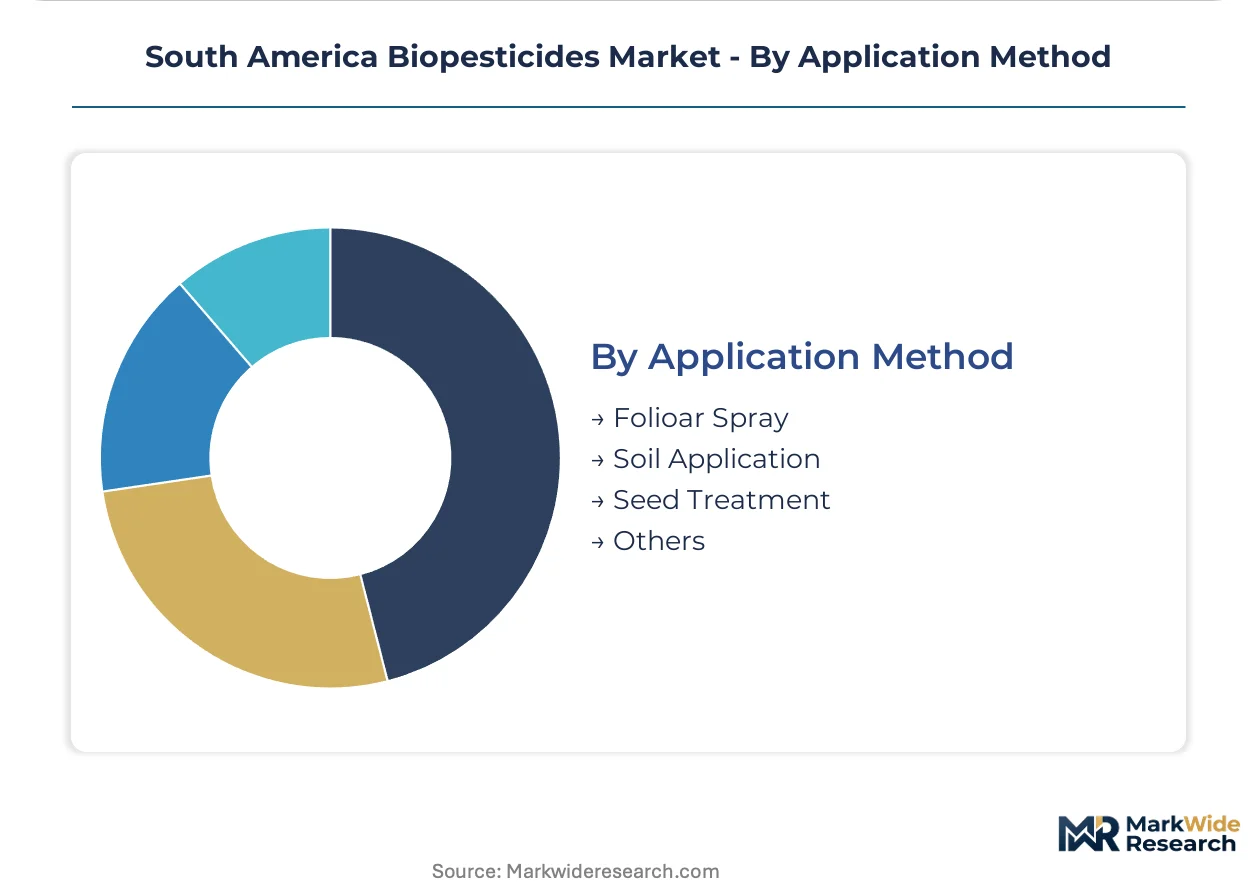
Application Method:
Service infrastructure availability shapes method selection—foliar spraying leverages existing contractor networks while seed treatment requires upstream supply chain integration.
- Foliar Spray:Aerial and ground application of microbial suspensions and botanical extracts dominates commercial deployment. Brazil's Mato Grosso soybean belt contracts helicopter and fixed-wing operators for Bacillus thuringiensis and Beauveria bassiana coverage, with spray timing synchronized to pest pressure monitoring.
- Seed Treatment:On-seed inoculation of Trichoderma and Pseudomonas expands with precision planting technology. Argentine wheat systems and Brazilian corn operations in Rio Grande do Sul centralize treatment at cooperative processing facilities, capturing scale economics in biological rotation programs.
- Soil Application:Drench, in-furrow, and broadcast delivery of nematode suppressants and fungal biocontrol agents targets soil-borne pest complexes. Strawberry and tomato producers in São Paulo's protected zones deploy soil-directed Purpureocillium for root-knot nematode management.
- Others:Trunk injection, dip treatments, and post-harvest applications serve perennial crop and storage pest segments with specialized equipment requirements.
Service capacity concentrates in Foliar Spray. Infrastructure buildout is gaining share fastest in Seed Treatment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil captures the dominant share of regional biopesticide procurement while Argentina's regulatory complexity fragments cross-border product equivalence. Uruguay's zero-residue export corridors command premium pricing for botanical formulations. Paraguay and Bolivia remain price-sensitive markets where synthetic generics retain volume leadership.
Brazil
Mato Grosso's soybean belt mandates biological rotation cycles under state-level integrated pest management protocols. ANVISA's provisional approval pathways for novel microbial strains compress registration timelines versus synthetic chemical equivalents. São Paulo's industrial corridor hosts domestic fermentation capacity serving Beauveria bassiana and Bacillus thuringiensis demand.
Argentina
Pampas-region corn and wheat systems drive seed-treatment attach rates for Trichoderma inoculants. SENASA requires extended toxicity dossiers for microbial strain validation, delaying market entry versus Brazilian timelines. Buenos Aires province cooperatives centralize procurement decisions under technical managers displacing traditional distributor networks.
Uruguay
Berry and citrus export supply chains to European retailers enforce near-zero synthetic residue tolerances. The national agricultural ministry prioritizes organic certification infrastructure for high-value horticulture. Colonia and Canelones departments concentrate protected agriculture operations deploying viral bioinsecticides.
Paraguay
Soybean expansion in the Oriental region proceeds without mandatory IPM compliance. Low-cost generic pyrethroids dominate fall armyworm suppression due to price positioning. Asunción-based distributors serve as transshipment nodes for Brazilian biological products.
Bolivia
Santa Cruz department's mechanized soy and corn operations lack technical management capacity for live-organism formulation handling. The national crop protection registry maintains no distinct biological product category. Chilean and Argentine suppliers capture limited premium segment share through direct farm relationships.
South America Biopesticides Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South American biopesticide channels. Incumbent agrochemical distributors leverage existing field relationships and spray service infrastructure to capture biological adjacencies. Three archetypes dominate: fermentation-based microbial manufacturers, botanical extraction specialists, and integrated crop protection conglomerates. Strategic moves concentrate on cooperative procurement consolidation and seed-treatment equipment integration.
Within the microbial formulation tier, Certis Biologicals and Valent BioSciences LLC exemplify specialized bacterial and viral product development. BASF SE represents diversified conglomerate positioning through conventional distribution infrastructure extension. Koppert Biological Systems anchors the greenhouse and protected-crop service contract segment. Vittia S.A. occupies a position among Brazil-based domestic manufacturers benefiting from ANVISA's streamlined provisional approval pathways.
| Leading Market Players |
|---|
| Certis Biologicals |
| Coromandel International Limited |
| Vittia S.A. |
| Koppert Biological Systems |
| Valent BioSciences LLC |
| Corteva Agriscience |
| IPL Biologicals Limited |
| Atlántica Agrícola |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Fermentation microbiologist clusters in São Paulo's industrial corridor anchor South American biopesticide manufacturing, with labor-cost differentials between Brazil's southeastern research hubs and Argentine technical centers widening pricing-tier spreads across microbial formulations.
Pricing Analysis
Capacity additions in Brazil's Mato Grosso soybean belt are reshaping price floors for liquid Beauveria bassiana and Bacillus thuringiensis formulations. Three-tier pricing structure across premium certified-organic, standard IPM-compliant, and economy conventional-adjacent levels separates Uruguayan berry exporters from Argentine wheat cooperatives from Paraguayan price-sensitive growers. Pricing pressure stems from molasses and soybean meal input volatility squeezing domestic fermentation margins. Smallholder vegetable operations in Bolivia's Santa Cruz department exhibit highest price sensitivity, while São Paulo protected-crop enterprises absorb premium positioning for RNAi and viral bioinsecticides.
Supply Chain Analysis
Brazil's Law 7.802 domestic-content provisions for microbial strain registration are reshaping sourcing patterns toward locally incorporated entities. Geographic supply concentration centers on Brazil, Argentina, and Uruguay, with Paraguay and Bolivia dependent on transshipment from Brazilian distributors. Raw material dependencies include molasses feedstock, soybean meal nitrogen sources, and proprietary culture media formulations. Single-source vulnerability runs through cold-chain logistics networks for live-organism viability preservation. Distribution runs through agricultural cooperative procurement committees displacing traditional distributor intermediaries in Mato Grosso and Argentina's Pampas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ANVISA's residue tolerance tightening and Brazil's Law 7.802 biological registration differentiation institutionalize procurement shifts toward microbial and botanical alternatives.
For Market Incumbents: Acquire fermentation capacity and cold-chain logistics assets in Brazil's southeastern industrial corridor before provisional approval pathways favor domestic entities exclusively. Consolidate cooperative procurement relationships through volume-based biological rotation contracts. Counter synthetic pyrethroid substitution threats in Paraguay and Bolivia via seed-treatment equipment bundling with granular Trichoderma inoculants.
For New Entrants and Emerging Players: Begin with Uruguay's zero-residue berry and citrus export corridors where European retail compliance mandates command premium positioning for viral bioinsecticides and plant extract formulations. Penetrate Brazil's Cerrado drone application service market through liquid microbial formulation compatibility with aerial spray platforms. Deploy direct technical service teams to overcome strain preservation expertise gaps outside established research clusters.
For Investors and Strategic Acquirers: Diversified agrochemical conglomerates with existing distribution infrastructure represent the most active acquirer category in this space, capturing channel economics pure-play biopesticide firms cannot replicate independently. Target domestic Brazilian manufacturers holding ANVISA provisional approvals for novel microbial strains. Monitor MERCOSUR harmonization negotiation progress as the signal indicating cross-border scale economics collapse or perpetuation.
| Strategic Initiative | Industry Significance |
|---|---|
| Seed-Treatment Equipment Integration | Captures attach-rate opportunities for granular Trichoderma inoculants at Argentine wheat and Brazilian corn planting. |
| Domestic Strain Registration Investment | Secures ANVISA provisional approval pathway access before biological-synthetic registration divergence hardens. |
| Cold-Chain Logistics Partnership | Addresses viability monitoring expertise gaps for live-organism formulations outside Brazil's southeastern clusters. |
| Cooperative Procurement Consolidation | Displaces distributor intermediaries through direct manufacturer relationships with Mato Grosso technical managers. |
| Drone Application Service Launch | Exploits liquid microbial formulation compatibility with aerial platforms in Brazil's Cerrado expansion zones. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with biopesticide manufacturing executives, agricultural cooperative procurement managers, ANVISA regulatory affairs specialists, fermentation plant engineers, and greenhouse technical directors with secondary validation against ANVISA registration databases, SENASA toxicity dossier filings, MERCOSUR trade harmonization protocols, and agricultural customs records. Bottom-up strain-level production estimates and top-down regional demand aggregation provided triangulation anchors.
Segment-weighting approaches modeled microbial, plant extract, biochemical, and mineral formulation categories alongside target pest ecology, application infrastructure compatibility, and regulatory pathway differentiation across the projection horizon. CAGRs derived from acreage expansion trajectories, IPM mandate enforcement timelines, and seed-treatment technology penetration curves. Industry-specific forecast inputs incorporated fall armyworm resistance evolution patterns and precision planting equipment deployment rates.
Caveats apply where MERCOSUR harmonization delays, molasses price volatility spikes, or synthetic chemical generic price wars could materially shift the outlook. Forecasts reflect documented assumptions about regulatory enforcement consistency and cooperative procurement centralization momentum. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
India Biopesticides Market
Bio-Agriculture
West Africa Biostimulants Market
Bio-Agriculture
North America Bio Succinic Acid Market
Bio-Agriculture
Bio-Insecticide Market
Bio-Agriculture
Brazil Biopesticides Market
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
Europe Biopesticides Market
Bio-Agriculture
Transgenic Animals Market
Bio-Agriculture
China Biostimulants Market
Bio-Agriculture
GCC Biofertilizer Market
Bio-Agriculture
Biopesticides Market
Bio-Agriculture
Bio-Based Levulinic Acid Market
Bio-Agriculture
Brazil Biofertilizers Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market
Bio-Agriculture
Asia-Pacific Biofertilizers Market