
 Ball Grid Array (BGA) Packaging Market | 2026-2036
Ball Grid Array (BGA) Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Ball Grid Array (BGA) Packaging Market Analysis
Buyer concentration among fabless semiconductor designers and automotive tier-one module suppliers is hardening, reducing the supplier base for mid-tier OSATs. Samsung Electronics leverages captive memory and logic demand to anchor internal BGA capacity in Suwon and Hwaseong. ASE Technology Holding Co. Ltd. sustains its position through geographic diversification across Kaohsiung, Chungli, and Shanghai facilities. Amkor Technology competes aggressively in advanced SiP and flip-chip BGA configurations for mobile AP and baseband markets.
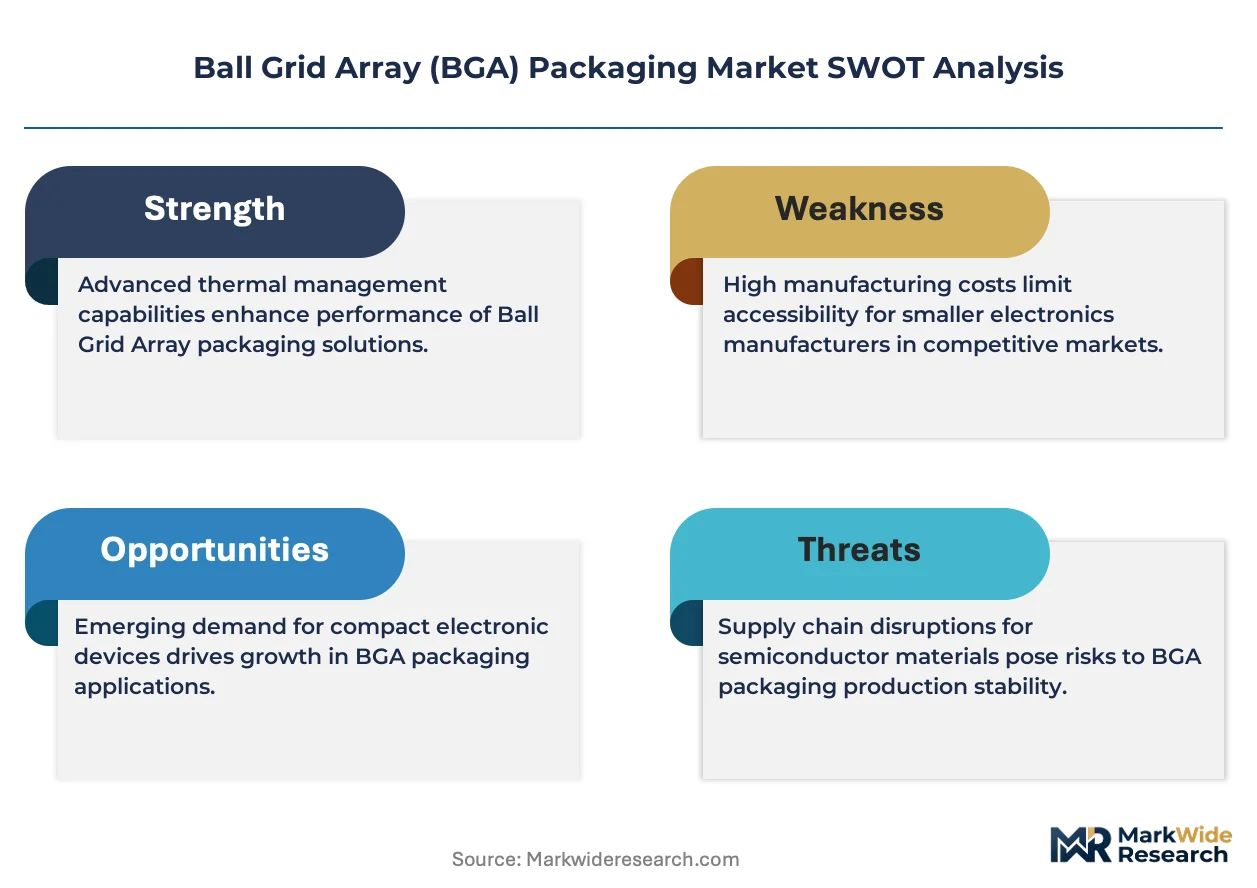
Ball Grid Array (BGA) packaging arranges solder balls in a grid pattern on the package underside, enabling pitch densities below 0.5mm and thermal resistance characteristics critical for high-pin-count processors and memory stacks. The architecture replaces peripheral lead frames with area-array interconnects, permitting higher I/O counts within equivalent or smaller footprints than quad flat packages. Flip Chip BGA and Micro BGA segments command premium positioning as smartphone SoCs and automotive radar modules drive finer-pitch requirements. Organic substrate materials dominate volume production, though ceramic substrates retain margin concentration in aerospace and high-reliability telecommunications applications.
REACH restrictions on lead-bearing solders and RoHS substance limits compel substrate and bumping material transitions across European-bound electronics supply chains. China's GB standards and MIIT regulations on hazardous substance control in electronic products shape local manufacturing compliance requirements for both domestic and export-oriented OSATs. Japan's METI energy-efficiency directives for industrial equipment indirectly influence BGA thermal performance specifications in precision automation controllers. Stakeholders must monitor evolving solder alloy compositions and substrate warpage specifications as heterogeneous integration and chiplet architectures redefine package-level interconnect demands.
Market Dynamics
Heterogeneous integration architectures are compressing interconnect pitch requirements below 0.35mm, forcing substrate suppliers and OSATs to coordinate warpage control across thermal cycling profiles previously unnecessary for monolithic die packaging.
Growth Catalysts
- ADAS module proliferation:Automotive radar and lidar systems require fine-pitch BGA configurations for signal integrity at millimeter-wave frequencies. Tier-one module suppliers in Germany and Japan are qualifying 0.4mm pitch packages for next-generation sensor fusion.
- China MIIT dual carbon mandates:Substrate material suppliers must transition to lower-temperature solder alternatives and halogen-free laminates for domestic EV electronics production. GB standards on hazardous substance control are accelerating qualification timelines for compliant interconnect materials.
- Flip-chip BGA adoption:Smartphone SoC designers are migrating from wirebond to flip-chip configurations for power delivery efficiency. Apple and Qualcomm procurement specifications now prioritize thermal resistance characteristics achievable only through area-array bumping.
Market Restraints
- ABF substrate supply concentration:Ajinomoto Build-up Film capacity is concentrated among three Japanese chemical suppliers, creating input bottlenecks for high-layer-count organic substrates used in advanced BGA stacks.
- RoHS substance friction:REACH restrictions on lead-bearing solders compel European-bound supply chains to qualify SAC305 and other tin-silver-copper alloys with inferior drop-test performance for automotive applications.
- Organic substrate warpage limits:Coefficient of thermal expansion mismatches between silicon die and bismaleimide-triazine laminates constrain maximum package sizes for high-pin-count server processors.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor packaging are attracting OSAT investment in Gujarat and Karnataka, creating captive demand for standard BGA configurations in domestic mobile and appliance production.
- Chiplet interconnect standards:UCIe and other die-to-die protocols are creating white space for interposer-based BGA variants that integrate multiple chiplets within a single package footprint for data center accelerators.
- Low-temperature solder transition:Bismuth-tin and indium-based alloys enable warpage reduction for large body-size packages, opening qualification pathways with Japan METI energy-efficiency directives for industrial automation controllers.
Industry Challenges
- Substrate warpage metrology:Measurement repeatability across thermal profiles requires capital investment in shadow moiré and digital image correlation systems that mid-tier OSATs struggle to justify.
- Cleanroom technician scarcity:Flip-chip bonding and underfill dispense operations demand operators trained in Class 1000 contamination protocols, with Taiwan and South Korea packaging hubs reporting 15-20% vacancy rates in critical technician roles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ball Grid Array (BGA) Packaging Market |
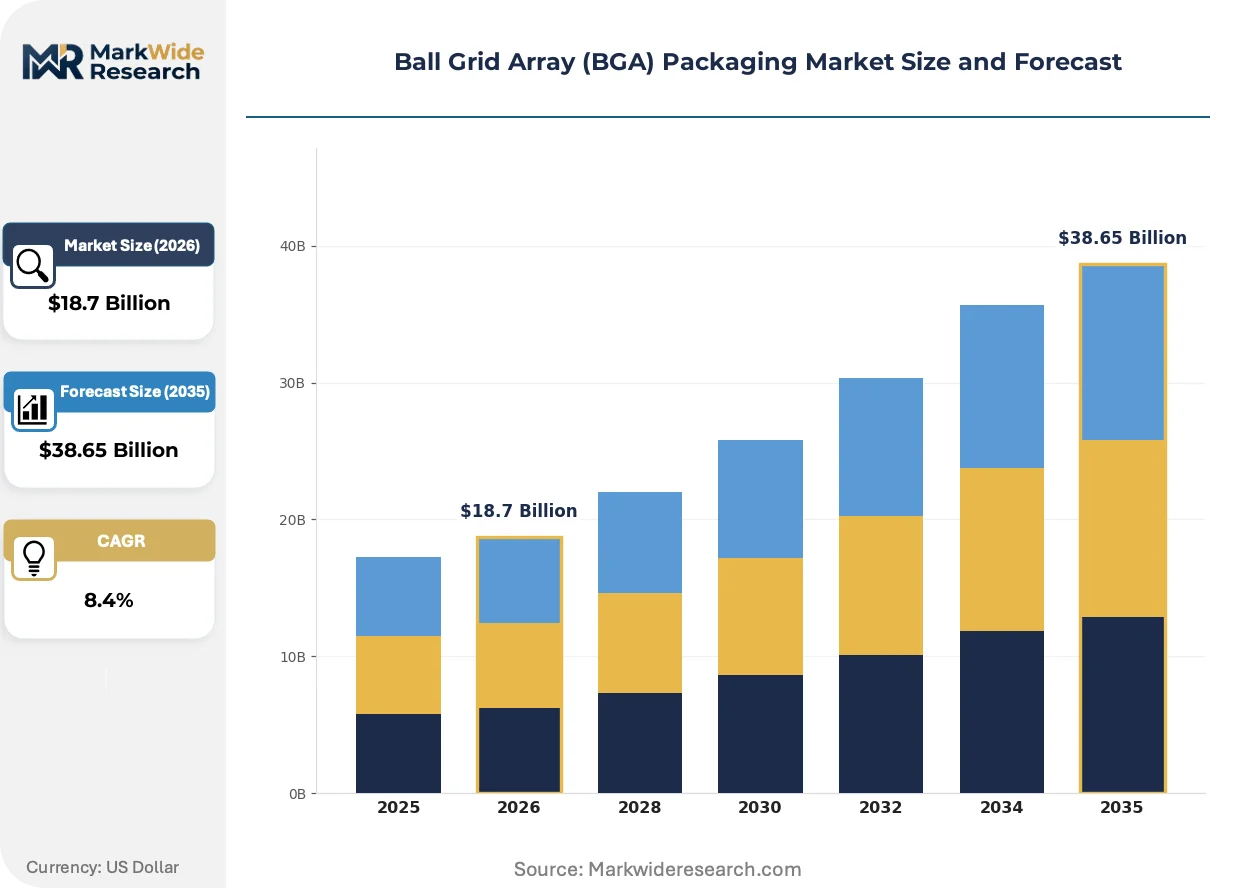
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard BGA, Micro BGA, Flip Chip BGA, Controlled Collapse Chip Connection Material: Epoxy Solder, Conductive Adhesive, Organic Substrate, Ceramic End User: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Equipment Manufacturing Stage: Assembly, Testing, Packaging, Inspection |
| Companies Covered | Samsung Electronics, JCET Group Co. Ltd., ASE Technology Holding Co. Ltd., Infineon Technologies AG, ChipMOS Technologies Inc., Amkor Technology, Intel Corporation, STATS ChipPAC, Powertech Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ball Grid Array (BGA) Packaging Market Emerging Trajectories
Packaging architectures are converging around thermal-mechanical co-design methodologies that treat substrate, die, and interconnect as a unified system rather than sequential manufacturing steps.
Embedded die packaging is automating the integration of passive components and silicon bridges within substrate cores, eliminating surface-mount placements for decoupling capacitors. Smartphone AP suppliers in Taiwan are adopting this for 5G mmWave modules where trace length minimization determines RF performance. The approach is compressing traditional PCB assembly steps into substrate fabrication, blurring historical boundaries between package and board-level manufacturing.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are accelerating transitions to nitrogen-based reflow atmospheres for BGA solder ball attach operations. European OSAT facilities in Germany and the Netherlands are retrofitting convection ovens to eliminate sulfur hexafluoride process gases previously used for oxidation control. Automotive module suppliers serving EU OEMs must document atmospheric emissions across substrate fabrication and final package assembly to maintain CE marking eligibility.
Consolidated procurement consortia among fabless semiconductor designers are displacing fragmented spot-market purchasing for BGA substrates and bumping services. Apple, Qualcomm, and MediaTek have established multi-year capacity reservations with ABF laminate suppliers, forcing second-tier AP vendors into residual allocation queues. The concentration is most visible in Taiwan, where substrate suppliers now prioritize direct relationships with top-five fabless customers over OSAT-mediated orders.
Ball Grid Array (BGA) Packaging Market Segmentation
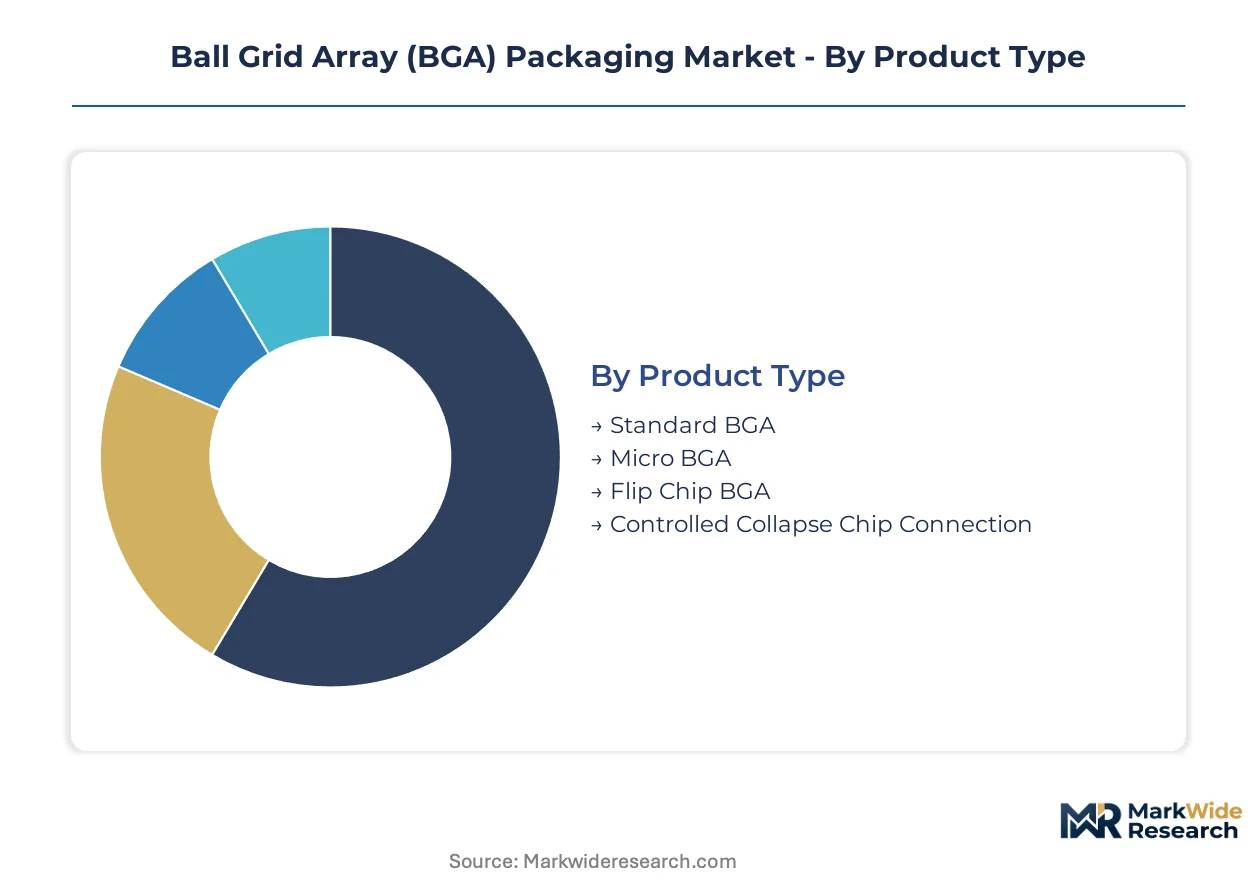
BGA packaging configurations diverge sharply in capital requirements and process complexity. Substrate material selection and interconnect architecture determine which segments absorb the majority of cleanroom investment and which remain accessible to mid-tier assembly houses.
Product Type:
Flip Chip BGA and Micro BGA demand the steepest upfront capital, with die bumping and underfill dispense equipment consuming 60-70% of greenfield facility budgets.
- Flip Chip BGA:Area-array interconnects place solder bumps directly on die pads, eliminating wirebond loops. Apple and Qualcomm procurement specifications for smartphone SoCs concentrate demand in Taiwan and South Korea packaging hubs where thermal resistance below 0.5°C/W is mandatory.
- Micro BGA:Body sizes below 10mm² with pitch densities reaching 0.3mm serve 5G mmWave modules and wearable sensors. Assembly houses in Kaohsiung report capacity constraints as fabless designers qualify finer-pitch variants for RF front-end integration.
- Standard BGA:Peripheral and area-array configurations with 0.8-1.0mm pitch dominate consumer appliance and legacy computing applications.
- Controlled Collapse Chip Connection:IBM-developed high-lead solder bumping retains niche positioning in aerospace and military-grade reliability specifications.
Most installed capacity flows through Standard BGA. Expansion is steepest in Flip Chip BGA.
Material:
Substrate material selection separates premium-margin applications from commodity volume, with ceramic and advanced organic laminates commanding 3-4x the unit economics of standard epoxy configurations.
- Organic Substrate:Bismaleimide-triazine and ABF laminates enable high-layer-count routing for server processors and network switches. Coefficient of thermal expansion mismatches with silicon constrain maximum package sizes, pushing substrate suppliers toward low-CTE glass fiber reinforcements.
- Ceramic:Alumina and aluminum nitride substrates deliver thermal conductivity above 150 W/mK for aerospace radar modules and base station power amplifiers. Japanese suppliers in Nagoya maintain tight allocation for telecommunications infrastructure builds.
- Epoxy Solder:Standard no-clean flux formulations dominate consumer electronics with cost-optimized reliability profiles.
- Conductive Adhesive:Isotropic and anisotropic pastes enable flex circuit attachments where solder reflow risks substrate damage.
Volume concentrates in Organic Substrate. Margin expansion is sharpest in Ceramic.
End User:
Automotive qualification timelines stretch 18-24 months versus 6-9 months for consumer electronics, segmenting the customer base by risk tolerance and design-in persistence.
- Automotive Electronics:ADAS radar and EV powertrain modules require AEC-Q100 Grade 0 thermal cycling performance. Tier-one suppliers in Germany and Japan are qualifying 0.4mm pitch packages for sensor fusion architectures where signal integrity at 77GHz is non-negotiable.
- Consumer Electronics:Smartphone AP and tablet processor demand concentrates procurement power among five fabless designers, compressing margins for OSATs without direct customer relationships.
- Telecommunications:Base station and optical transceiver applications favor ceramic substrates for thermal management in outdoor deployments.
- Industrial Equipment:Japan METI energy-efficiency directives drive thermal performance specifications for precision automation controllers.
Revenue pools deepest in Consumer Electronics. Qualification velocity is fastest in Automotive Electronics.
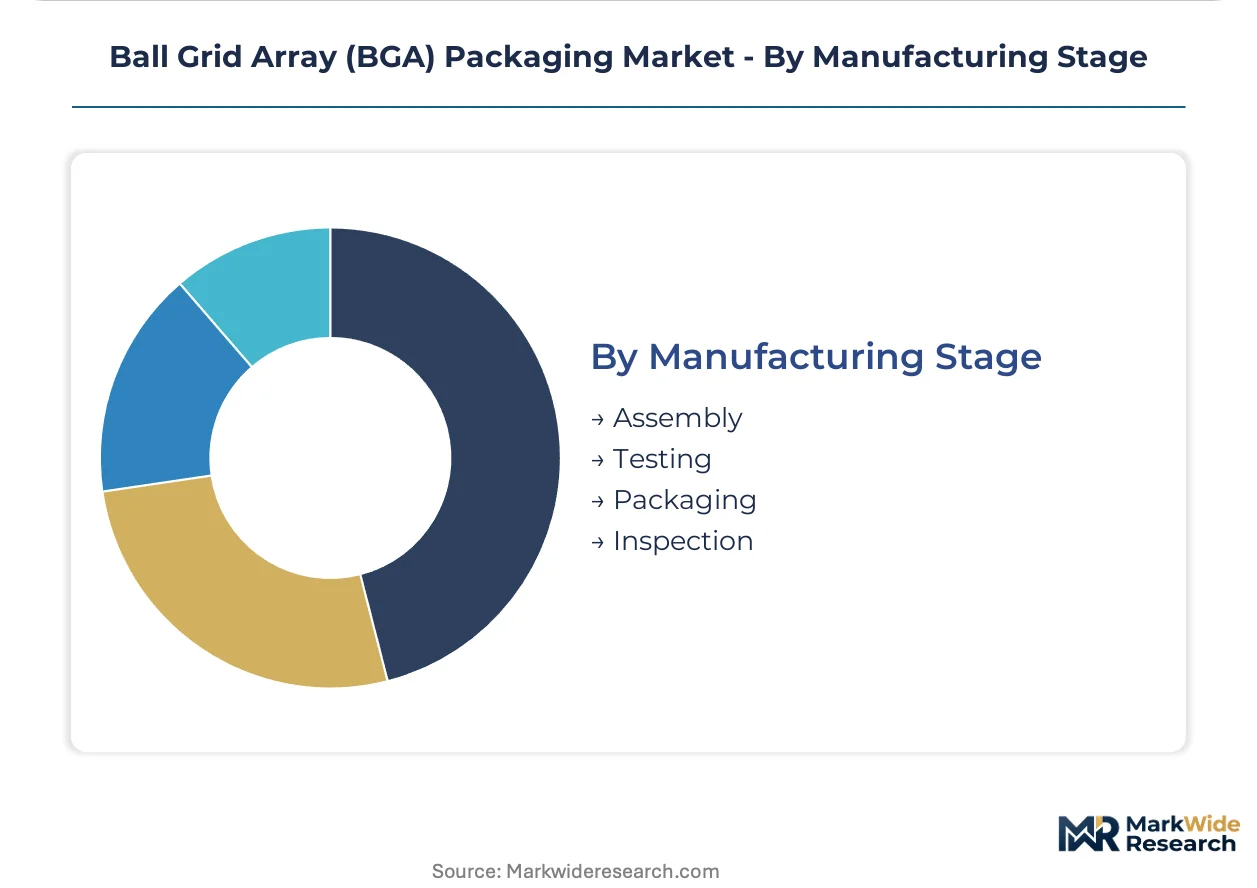
Manufacturing Stage:
Testing and inspection absorb disproportionate capital relative to their headcount share, with automated optical inspection and X-ray systems required for void detection in solder ball arrays.
- Assembly:Die attach, wirebond or flip-chip bonding, and solder ball placement constitute the core value-add operations.
- Testing:Burn-in and final test sequences for automotive-grade packages extend cycle times 40% versus commercial temperature variants.
- Packaging:Tape-and-reel and tray configurations align with customer pick-and-place line requirements.
- Inspection:Shadow moiré warpage measurement and 3D X-ray for ball void detection are becoming mandatory for 0.4mm pitch qualifications.
Headcount concentrates in Assembly. Capital intensity peaks in Testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan concentrates OSAT capacity for advanced flip-chip configurations while South Korea anchors captive memory packaging, yet substrate supply bottlenecks in Japan constrain expansion timelines across both hubs.
Taiwan
ASE Technology Holding and ChipMOS Technologies drive capacity expansion in Kaohsiung and Hsinchu for smartphone SoC and 5G mmWave modules. The island's EPA enforces hazardous substance controls that align with REACH-equivalent standards for export-bound electronics. Kaohsiung packaging hubs report cleanroom technician vacancy rates above 15% as flip-chip bonding operations scale.
South Korea
Samsung Electronics leverages captive demand for DRAM and logic devices to anchor internal BGA capacity in Suwon and Hwaseong. The MFDS regulates hazardous substances in electronic products through standards parallel to RoHS directives. Pyeongtaek semiconductor clusters are attracting substrate material suppliers for co-location with advanced packaging lines.
China
JCET Group and domestic OSATs are expanding Shanghai and Jiangsu facilities to serve EV powertrain and ADAS module demand from local automotive OEMs. MIIT dual carbon mandates accelerate transitions to lower-temperature solder alternatives and halogen-free laminates. Suzhou packaging parks are qualifying 0.4mm pitch configurations for domestic radar sensor production.
Japan
Ajinomoto and substrate chemical suppliers in Nagoya maintain tight allocation of build-up film capacity for high-layer-count organic laminates. METI energy-efficiency directives for industrial equipment indirectly shape thermal performance specifications in precision automation controllers. Kyoto-area material suppliers are prioritizing telecommunications infrastructure builds over consumer electronics allocations.
Germany
Bosch and Continental tier-one module suppliers are qualifying 0.4mm pitch BGA packages for 77GHz automotive radar and sensor fusion architectures. ECHA REACH restrictions on lead-bearing solders compel qualification of SAC305 alloys with documented drop-test performance trade-offs. Dresden semiconductor clusters are attracting OSAT investment for European-bound automotive electronics production.
Ball Grid Array (BGA) Packaging Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Captive packaging divisions of integrated device manufacturers anchor demand for internal logic and memory products, while independent OSATs compete for fabless semiconductor procurement contracts. Three archetypes dominate: diversified electronics conglomerates with captive packaging, pure-play packaging specialists with geographic diversification, and memory-focused fabricators with vertical integration into assembly. Capacity reservation agreements and multi-year substrate supply contracts represent the dominant competitive moves, displacing spot-market purchasing for advanced configurations.
Within the diversified conglomerate tier, Samsung Electronics exemplifies captive integration across memory and logic packaging. Among pure-play specialists, ASE Technology Holding Co. Ltd. and Amkor Technology occupy positions defined by geographic facility networks rather than single-site concentration. JCET Group Co. Ltd. represents the China-based specialist archetype serving domestic EV electronics demand. Infineon Technologies AG anchors European semiconductor packaging with internal capacity for automotive-grade reliability specifications.
| Leading Market Players |
|---|
| Samsung Electronics |
| JCET Group Co. Ltd. |
| ASE Technology Holding Co. Ltd. |
| Infineon Technologies AG |
| ChipMOS Technologies Inc. |
| Amkor Technology |
| Intel Corporation |
| STATS ChipPAC |
| Powertech Technology Inc. |
| Others |
Supply Flow & Price Mechanics
Fabless semiconductor designers in Taiwan and South Korea concentrate procurement power through multi-year capacity reservations, locking in contract-based long-term offtake agreements that displace spot-market purchasing for advanced BGA configurations. This buyer consolidation forces mid-tier OSATs into residual allocation queues while premium pricing accrues to substrate suppliers with direct relationships.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard BGA configurations as domestic OSATs expand to serve EV electronics demand. Three-tier pricing structure across premium, standard, and economy levels separates ceramic substrate aerospace applications from organic laminate consumer electronics and commodity epoxy configurations. Cost compression in standard BGA runs through aggressive capacity expansion by JCET Group and domestic competitors. Tier-one automotive module suppliers exhibit lowest price sensitivity due to AEC-Q100 qualification requirements, while appliance manufacturers drive hard volume negotiations.
Supply Chain Analysis
Regional distribution centers in Kaohsiung, Suwon, and Shanghai operate hub-and-spoke patterns for substrate materials and finished packages. Supply concentrates in Taiwan, South Korea, and China for assembly operations, while Japan anchors ABF laminate and build-up film production. Raw material dependencies include bismaleimide-triazine resins, Ajinomoto Build-up Film, and SAC305 solder alloys. Single-source vulnerability in Japanese chemical suppliers creates input bottlenecks for high-layer-count organic substrates. Distribution runs through direct OSAT-to-OEM relationships for automotive qualifications and consolidated procurement consortia for consumer electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The BGA packaging market represents a late-cycle quality story as ADAS module proliferation and chiplet architectures shift demand toward premium flip-chip configurations with stringent thermal resistance specifications.
For Market Incumbents: Anticipate margin compression from captive memory packaging divisions at Samsung Electronics and domestic Chinese OSATs expanding under MIIT dual carbon mandates. Defensive consolidation moves should prioritize backward integration into ABF substrate supply through joint ventures with Japanese chemical suppliers, and certification investment in AEC-Q100 Grade 0 automotive qualifications to lock in 18-24 month design-in cycles before second-tier competitors qualify. For New Entrants and Emerging Players: Enter via India's PLI scheme incentives for semiconductor packaging, where Gujarat and Karnataka facilities offer white-space access with lower competitive density than East Asian hubs. The most penetrable segment is standard BGA for domestic mobile and appliance production, avoiding direct confrontation with ASE Technology and Amkor Technology in advanced flip-chip configurations. Go-to-market angle should emphasize halogen-free laminate compliance and lower-temperature solder alternatives aligned with MIIT regulations for export-oriented supply chains. For Investors and Strategic Acquirers: Automotive tier-one module suppliers are the most active acquirer in this space, seeking captive packaging capacity for 77GHz radar and sensor fusion architectures. Long-term viability centers on substrate material suppliers with low-CTE glass fiber reinforcement capabilities and cleanroom technician training pipelines. Acquisition target archetype: mid-tier OSATs with existing AEC-Q100 qualifications and underutilized capacity in secondary geographies. Signal to watch: vacancy rates in Taiwan and South Korea packaging hubs, which indicate labor cost inflection and automation ROI thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| ABF Substrate Joint Venture | Japanese chemical suppliers in Nagoya secure allocation priority for high-layer-count organic laminates used in server processors. |
| AEC-Q100 Grade 0 Qualification | German tier-one suppliers at Bosch and Continental mandate thermal cycling performance for 77GHz automotive radar modules. |
| Low-Temperature Solder Transition | China's MIIT dual carbon goals accelerate bismuth-tin alloy adoption for warpage reduction in large body-size packages. |
| India PLI Scheme Participation | Gujarat and Karnataka facilities attract OSAT investment for captive demand in domestic mobile and appliance production. |
| Chiplet Interposer Integration | UCIe protocol adoption creates white space for interposer-based BGA variants in data center accelerator applications. |
Methodological Framework
Multiple input streams — OSAT operations executives, substrate material procurement leads, automotive tier-one module suppliers, and fabless semiconductor packaging directors — were reconciled against customs data, SEMI equipment forecasts, SEC 10-K filings, and EPA hazardous substance disclosure records. Primary interviews with cleanroom operations managers and flip-chip bonding technicians in Kaohsiung and Hsinchu provided ground-level capacity utilization color. Secondary validation drew from MIIT regulatory filings, METI energy-efficiency directive documentation, and ECHA REACH restriction updates. Bottom-up triangulation across facility-level capacity announcements and top-down reconciliation against semiconductor unit demand models anchored value estimates.
Historical shipment patterns were cross-referenced against panel input from substrate suppliers and OSAT planning departments to construct projection trajectories across the analysis window. Segmentation dimensions modeled include interconnect architecture, substrate material grade, end-use vertical, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized adoption curves for flip-chip versus wirebond configurations, with specific inputs from smartphone SoC procurement specifications and EV powertrain module ramp schedules.
Inputs from Japanese ABF laminate suppliers and Taiwan packaging hubs were available through the study window; gaps in mid-tier OSAT financial disclosure introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions regarding heterogeneous integration adoption rates and cleanroom technician labor pool expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Global Semiconductor Equipment Packaging and Test Market
Semiconductor Packaging
Embedded Die Packaging Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Test Services (OSAT) Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
System-On-Package Market
Semiconductor Packaging
3D IC Packaging Market
Semiconductor Packaging
Global High-End Semiconductor Packaging Market
Semiconductor Packaging
2.5D and 3D Semiconductor Packaging Market
Semiconductor Packaging
Global MEMS Packaging Market
Semiconductor Packaging
Bonding Wire Packaging Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Testing Market
Semiconductor Packaging
Global Semiconductor Seals Market
Semiconductor Packaging
IC Packaging and Testing Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
Semiconductor Packaging Market
Semiconductor Packaging
Multichip Package Market