
 Outsourced Semiconductor Assembly and Test Services (OSAT) Market | 2026-2036
Outsourced Semiconductor Assembly and Test Services (OSAT) Market Size, Share, and Industry Trends Forecast 2026-2036
Outsourced Semiconductor Assembly and Test Services (OSAT) Market Analytics
Aftermarket service revenue from legacy wirebond testing is narrowing as capital migrates toward advanced packaging lines. ASE Technology Holding leverages its Taiwan-based footprint to dominate fan-out wafer-level packaging for high-performance computing. Amkor Technology anchors North American automotive certification pipelines with its Arizona and Colorado operations. JCET sustains cost-competitive flip-chip scale through its Jiangsu manufacturing complex.
Outsourced Semiconductor Assembly and Test Services (OSAT) encompasses third-party provision of die attachment, wire bonding, flip chip interconnection, wafer-level packaging, and final electrical testing for semiconductor devices, typically performed on silicon wafers ranging from 200mm to 300mm diameter before singulation into individual chips. These services enable fabless semiconductor companies and integrated device manufacturers to access advanced packaging capabilities without capital-intensive in-house fabrication investments. Wafer Level Package and System-In-Package segments capture expanding margin pools as heterogeneous integration replaces monolithic scaling in AI and 5G applications. Flip Chip technology leads volume in mobile processors while Ball Grid Array maintains maturity in automotive microcontroller modules where reliability standards exceed consumer thresholds.
REACH chemical restrictions and RoHS substance limits in Europe constrain solder material selection and flux chemistry across OSAT supply chains, while FDA quality system regulations govern medical device semiconductor packaging for implantable applications. Taiwan's NMI metrology standards and China's GB/T reliability protocols shape cross-border qualification requirements for automotive-grade packages. Stakeholders must monitor how export control classifications on advanced packaging equipment reshape geographic capacity allocation decisions.
Market Dynamics
Capital migration from wirebond infrastructure toward heterogeneous integration platforms is compressing traditional margin structures while elevating technical barriers to market entry. Taiwan's NMI metrology standards and China's GB/T certification protocols are forcing simultaneous compliance investments across multiple qualification pipelines.
Growth Catalysts
- Heterogeneous Integration Demand:AI accelerators and 5G baseband processors require fan-out wafer-level packaging and system-in-package architectures that monolithic scaling cannot deliver. Fabless semiconductor firms outsource these capabilities to avoid billion-dollar cleanroom investments.
- Automotive Certification Mandates:Taiwan's NMI standards and China's GB/T reliability protocols for automotive-grade packages create captive demand for qualified OSAT capacity as electric vehicle production scales.
- Flip Chip Technology Maturation:Mobile processor manufacturers now specify copper pillar bumping and thermal compression bonding as baseline requirements, pulling volume from wirebond alternatives.
Market Restraints
- Equipment Import Concentration:Advanced packaging lithography and die-bonding systems concentrate among Japanese and Dutch suppliers, creating lead-time vulnerability for capacity expansion.
- REACH Chemical Constraints:ECHA restrictions on lead-free solder alternatives and flux chemistry limit material selection flexibility for European-bound shipments.
- Substrate Supply Bottlenecks:Ajinomoto Build-up Film and bismaleimide-triazine resin shortages constrain flip-chip package substrate availability.
Strategic Opportunities
- Malaysia Capacity Expansion:Penang and Kulim industrial zones offer cost-competitive real estate and established electronics manufacturing clusters for heterogeneous integration facilities.
- Medical Device Packaging:FDA quality system regulations for implantable applications create premium pricing tiers for hermetic ceramic packages and biocompatible encapsulation.
- Chiplets and 3D Stacking Convergence:Hybrid bonding of memory-on-logic stacks opens new service revenue pools as DRAM manufacturers seek outsourced assembly partners.
Industry Challenges
- Process Engineer Scarcity:Thermal compression bonding and hybrid bonding expertise concentrates among Taiwan and South Korea talent pools, constraining global capacity scaling.
- Multi-Site Qualification Burden:Automotive OEMs require simultaneous AEC-Q100 and GB/T 28046 compliance, extending new product introduction timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outsourced Semiconductor Assembly and Test Services (OSAT) Market |
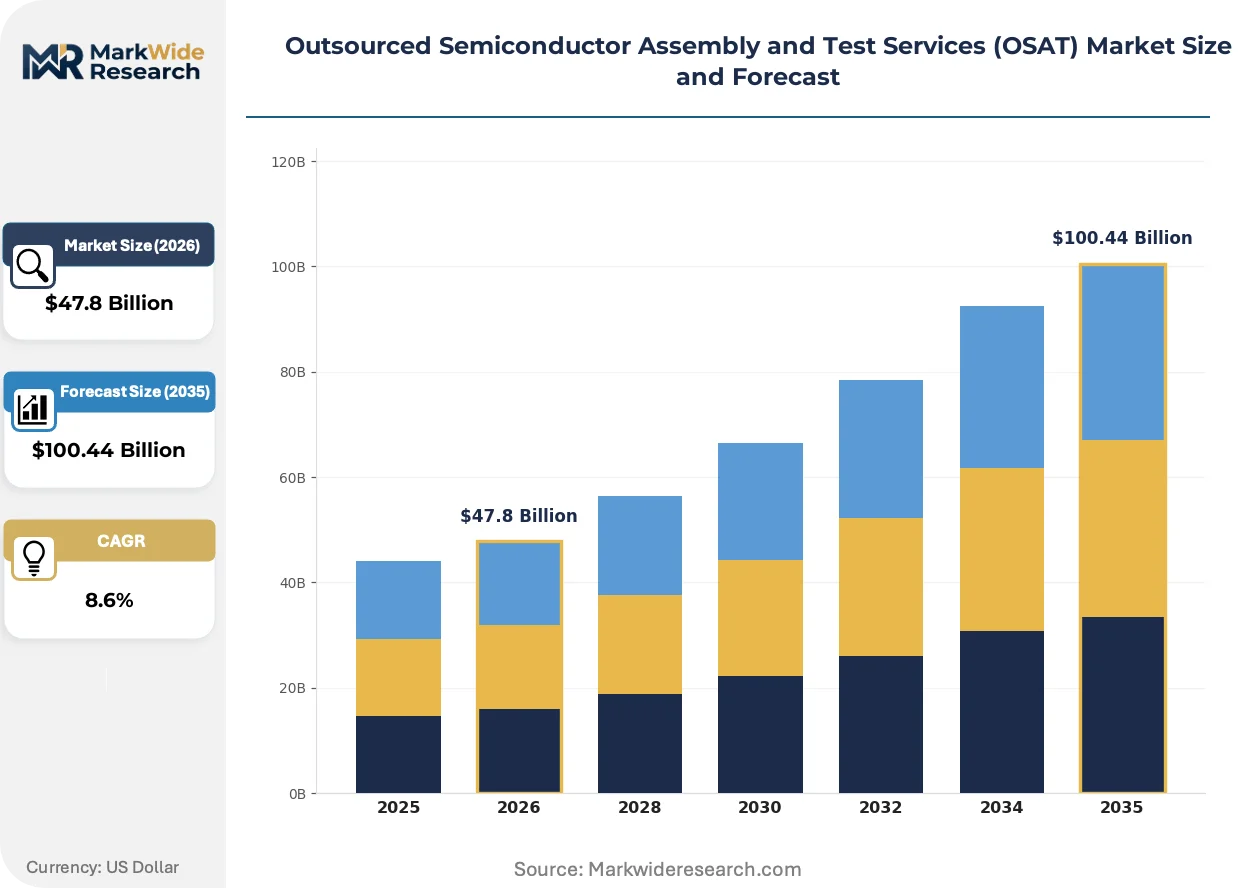
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $100.44 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Wafer Level Package, Flip Chip, Ball Grid Array, Chip-On-Board End User: Consumer Electronics, Automotive, Telecommunication, Industrial Electronics Technology: Advanced Packaging, Standard Packaging, 3D Packaging, System-In-Package Product Type: Microcontrollers, Memory Chips, Power Devices, RF Devices |
| Companies Covered | Tongfu Microelectronics, HT-Tech, ASE Technology Holding, Hana Micron, WiseRoad, Amkor Technology, Powertech Technology, ChipMOS Technologies, JCET, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outsourced Semiconductor Assembly and Test Services (OSAT) Market Evolving Landscape
Heterogeneous integration architectures are forcing OSAT providers to reconfigure cleanroom layouts and equipment mixes around wafer-level processes rather than traditional die-level assembly lines. Three developments are compressing competitive differentiation timelines.
Hybrid bonding is collapsing the physical separation between memory and logic die stacking by eliminating solder microbumps entirely. AI accelerator designers at NVIDIA and AMD now specify this technology for high-bandwidth memory attachment. The elimination of underfill materials and reduced z-height profiles is collapsing package form factor constraints that previously limited mobile device design freedom.
REACH substance restrictions are constraining solder alloy selection across European-bound production lines. ECHA's candidate list expansion for Substances of Very High Concern is forcing reformulation of flux chemistries and surface finishes. Automotive microcontroller suppliers are responding by dual-qualifying tin-silver-copper and bismuth-doped alternatives to maintain shipment flexibility.
Contract structures are unbundling test services from assembly in high-volume mobile processor relationships. Fabless firms now source wafer probe and final test separately from packaging, compressing traditional OSAT bundle economics. This pattern is most visible in Taiwan, where dedicated test houses capture margin that integrated providers previously retained.
Outsourced Semiconductor Assembly and Test Services (OSAT) Market Segmentation
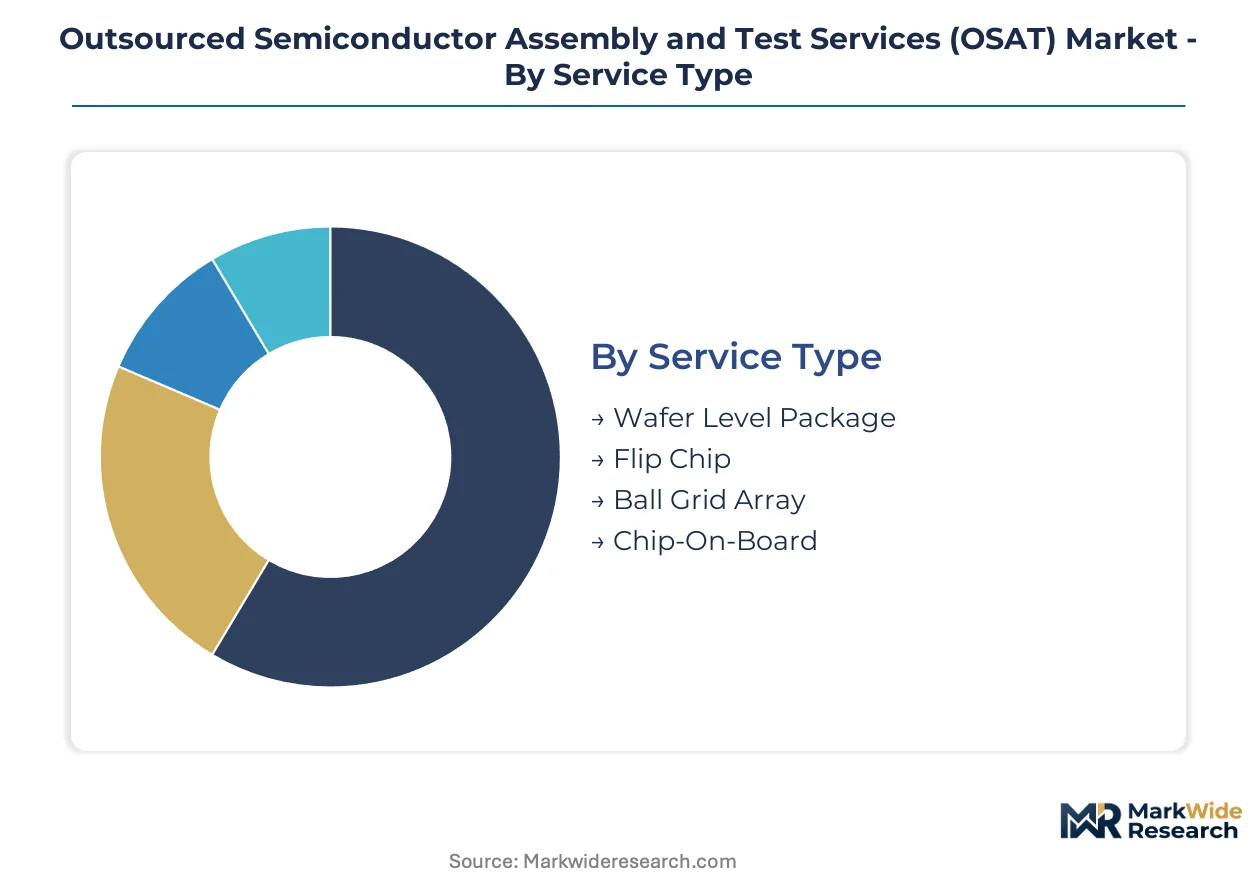
OSAT providers configure equipment mixes and cleanroom layouts around distinct service architectures, each demanding specialized lithography, bonding, and testing protocols. Segment boundaries determine capital allocation priorities and qualification pipeline investments across heterogeneous integration platforms.
Service Type:
Cost tier differentiation separates legacy wirebond infrastructure from advanced packaging platforms requiring billion-dollar cleanroom investments.
- Wafer Level Package:Fan-out and fan-in architectures process redistribution layers on intact wafers before singulation, eliminating substrate costs. AI accelerator designers at NVIDIA and AMD specify this technology for high-bandwidth memory integration, compressing form factors in data center deployments.
- Flip Chip:Copper pillar bumping and thermal compression bonding attach die face-down to organic substrates with superior electrical performance. Mobile processor manufacturers specify this as baseline for 5nm and below nodes, pulling volume from wirebond alternatives in Taiwan and South Korea packaging houses.
- Ball Grid Array:Traditional organic substrate packages maintain dominance in automotive microcontroller modules where AEC-Q100 reliability standards exceed consumer thresholds.
- Chip-On-Board:Direct die attachment to printed circuit boards serves cost-sensitive LED lighting and simple controller applications with minimal I/O requirements.
Flip Chip commands the established base. The steepest expansion runs through Wafer Level Package.
End User:
Application-specific certification requirements fragment qualification timelines and pricing structures across customer verticals.
- Consumer Electronics:Smartphones, tablets, and wearables drive highest volume with compressed product cycles and aggressive cost targets. Taiwan's NMI metrology standards and China's GB/T protocols shape cross-border shipments for premium mobile devices.
- Automotive:Electric vehicle powertrains and advanced driver-assistance systems demand zero-defect reliability with 15-year operational lifespans. Taiwan's NMI standards and China's GB/T 28046 certification create captive demand for qualified OSAT capacity as EV production scales.
- Telecommunication:5G baseband processors and network infrastructure require enhanced thermal management for outdoor deployment conditions.
- Industrial Electronics:Factory automation controllers and power conversion systems prioritize long-term supply continuity over leading-edge miniaturization.
Consumer Electronics anchors current volume. Automotive is expanding most quickly.
Technology:
Technology maturity determines whether providers compete on yield optimization or frontier process development.
- Advanced Packaging:Fan-out wafer-level packaging, embedded die, and silicon interposers enable heterogeneous integration of logic, memory, and photonics. Fabless semiconductor firms outsource these capabilities to avoid cleanroom investments exceeding internal fabrication costs.
- System-In-Package:Multi-die integration of processors, memory, and RF components in single molded bodies serves space-constrained mobile and wearable designs.
- Standard Packaging:Wirebond and leadframe technologies maintain cost competitiveness for discrete power devices and legacy analog circuits.
- 3D Packaging:Hybrid bonding and through-silicon via stacking collapse z-height for memory-on-logic configurations in AI accelerators.
Standard Packaging retains the volume base. System-In-Package is gaining share fastest.
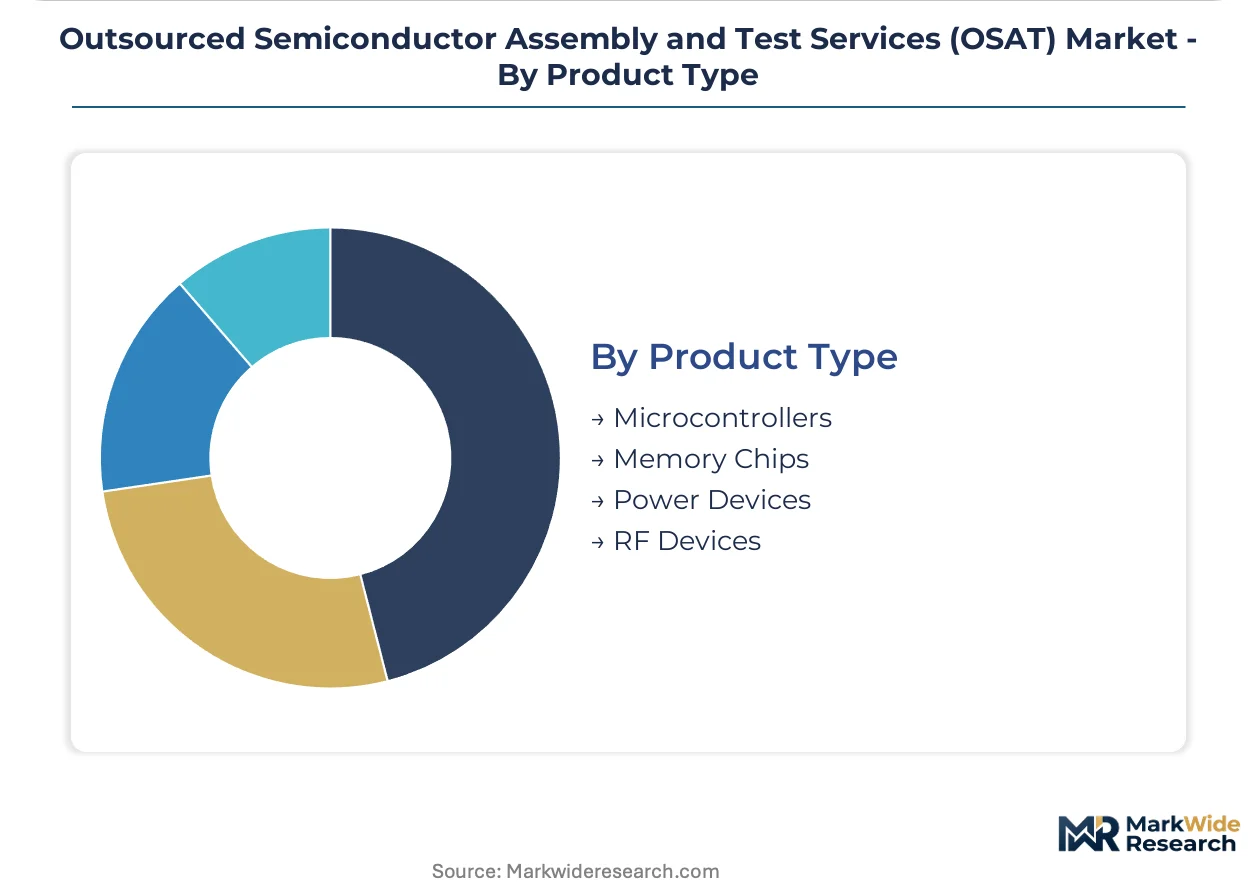
Product Type:
Device physics and I/O density requirements dictate substrate selection, encapsulation methods, and thermal management approaches.
- Microcontrollers:Automotive-grade 32-bit and 64-bit controllers require extended temperature range validation and AEC-Q100 qualification. Malaysia's Penang cluster and China's Jiangsu province concentrate capacity for automotive microcontroller packaging serving European and domestic OEMs.
- Memory Chips:DRAM and NAND flash demand precise wirebond pitch control and advanced mold compound formulations for stacked configurations. High-bandwidth memory attachment to AI accelerators is pulling investment toward hybrid bonding expertise in Taiwan and South Korea.
- Power Devices:Silicon carbide and gallium nitride discretes need specialized thermal interface materials and copper clip interconnects for electric vehicle inverters.
- RF Devices:5G millimeter-wave front-end modules require low-loss substrate materials and precision passive component integration.
Microcontrollers command the established base. Memory Chips show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Taiwan and South Korea exhibit lowest price elasticity for advanced packaging capacity, while Southeast Asian procurement teams negotiate aggressively on legacy wirebond services. Europe's automotive OEMs absorb premium pricing for zero-defect reliability. Chinese fabless firms prioritize cost-competitive flip-chip scale over frontier hybrid bonding.
Taiwan
AI accelerator designers at NVIDIA and AMD source fan-out wafer-level packaging from Taiwan-based providers, driving capital migration from wirebond infrastructure. The National Measurement Institute enforces NMI metrology standards that shape cross-border qualification requirements. The Hsinchu Science Park anchors heterogeneous integration capacity expansion as ASE Technology Holding scales thermal compression bonding lines.
China
Domestic electric vehicle production scales demand for automotive-grade microcontroller packaging with 15-year operational lifespans. The State Administration for Market Regulation enforces GB/T 28046 certification protocols that create captive demand for qualified capacity. JCET's Jiangsu manufacturing complex sustains cost-competitive flip-chip scale serving European and domestic OEMs.
South Korea
DRAM manufacturers seek outsourced assembly partners for memory-on-logic hybrid bonding stacks in AI accelerators. The Ministry of Food and Drug Safety governs medical device semiconductor packaging through quality system regulations. Seoul's Pangyo cluster concentrates thermal compression bonding expertise that constrains global capacity scaling.
Malaysia
Penang and Kulim industrial zones attract heterogeneous integration facility investments from cost-sensitive fabless firms. The country's national investment promotion agency coordinates electronics manufacturing cluster development. Penang's established semiconductor ecosystem supports flip-chip package substrate availability amid Ajinomoto Build-up Film shortages.
United States
North American automotive certification pipelines require AEC-Q100 qualified capacity for electric vehicle powertrains. The Environmental Protection Agency enforces REACH-aligned chemical restrictions on solder material selection. Amkor Technology's Arizona and Colorado operations anchor FDA-governed medical device packaging for implantable applications.
Outsourced Semiconductor Assembly and Test Services (OSAT) Market Competitive Landscape
Integrated technology holding companies and specialized packaging houses split the market along capability-depth versus scale-efficiency lines. Taiwan-based incumbents leverage NMI-standard compliance and cleanroom infrastructure to dominate premium heterogeneous integration. Chinese state-linked enterprises compete on cost-competitive legacy packaging with government-backed capacity expansion. Strategic moves concentrate on Malaysia real estate acquisition and multi-site automotive qualification investments.
Within the integrated technology holding tier, ASE Technology Holding exemplifies Taiwan-based dominance in fan-out wafer-level packaging, while JCET occupies a position as a Chinese state-linked cost leader in flip-chip scale. Amkor Technology anchors the North American automotive certification pipeline. These three entities represent the geographic and capability archetypes that structure competitive positioning: Taiwan's NMI-compliant premium tier, China's GB/T-aligned volume tier, and US-based FDA-governed medical specialization.
| Leading Market Players |
|---|
| Tongfu Microelectronics |
| HT-Tech |
| ASE Technology Holding |
| Hana Micron |
| WiseRoad |
| Amkor Technology |
| Powertech Technology |
| ChipMOS Technologies |
| JCET |
| Others |
Value Network & Pricing Analysis
Overcapacity in legacy wirebond lines across Malaysia and Thailand compresses spot pricing for commodity packages while tightening margins force suppliers toward advanced packaging commitments. Taiwan's NMI-certified facilities command 40-60 point utilization premiums that translate directly into pricing power for heterogeneous integration services.
Pricing Analysis
Aftermarket testing service contracts generate lifetime value multiples exceeding initial assembly revenue by 2.5-3x for automotive-qualified packages. Three-tier pricing structure across AEC-Q100 premium, industrial-grade standard, and consumer-economy levels separates qualification-intensive automotive microcontrollers from cost-sensitive LED drivers. Cost compression in wirebond tiers intensifies because Chinese state-linked providers absorb negative margins to maintain volume. Fabless AI accelerator designers exhibit lowest price sensitivity, while Southeast Asian procurement teams for consumer electronics negotiate most aggressively on legacy services.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize equipment procurement from Japanese and Dutch lithography suppliers, straining OSAT balance sheets during capacity expansion cycles. Taiwan, South Korea, and Japan anchor supply for advanced packaging equipment, while Ajinomoto Build-up Film and bismaleimide-triazine resin feed from specialized chemical producers in Japan and South Korea. Single-source vulnerability concentrates in die-bonding systems from two dominant equipment makers. Distribution runs through direct OEM partnerships for high-volume mobile processors and distributor-mediated spot markets for legacy wirebond capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as chiplets interoperability standards collapse traditional package-level differentiation into ecosystem battles. UCIe and other die-to-die interconnect specifications are reshaping how OSAT providers capture value from heterogeneous integration.
For Market Incumbents: Build hybrid bonding process libraries as a technical moat against commoditization of fan-out wafer-level packaging. ASE Technology Holding and Amkor Technology should deepen backward integration into substrate materials to offset Ajinomoto Build-up Film shortages. Taiwan-based leaders must defend NMI-certified capacity against Chinese state-subsidized expansion in Jiangsu province by accelerating thermal compression bonding yield improvements. For New Entrants and Emerging Players: Establish a beachhead in medical device packaging for implantable applications where FDA quality system regulations create certification barriers. Malaysia's Penang industrial zone offers the most penetrable geography for cost-competitive heterogeneous integration facilities serving European automotive OEMs. A go-to-market angle targeting hermetic ceramic packages for neuromodulation devices captures premium pricing tiers absent from consumer electronics. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among OSAT providers with automotive certification pipelines that lock in 10-15 year supply agreements. Target acquisition archetypes are mid-cap specialists with GB/T 28046 and AEC-Q100 dual qualification capabilities that large incumbents lack. The signal to watch is hybrid bonding yield rates at sub-10 micron pitch as inflection indicator for which providers can service NVIDIA and AMD next-generation AI accelerators.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Process Development | Enables memory-on-logic stacking for NVIDIA and AMD AI accelerators. |
| Malaysia Capacity Expansion | Penang and Kulim zones attract cost-sensitive fabless heterogeneous integration demand. |
| Dual Automotive Certification Investment | GB/T 28046 and AEC-Q100 compliance captures electric vehicle powertrain packaging. |
| Medical Device Packaging Specialization | FDA quality system regulations create premium tiers for hermetic ceramic packages. |
| Substrate Material Backward Integration | In-house production of ABF and BT resin reduces flip-chip substrate bottlenecks. |
Research Methodology
A standing panel of OSAT operations directors, fabless semiconductor procurement executives, automotive Tier 1 supplier packaging engineers, and equipment vendor sales leads provided ongoing calibration throughout data collection. Primary interviews combined with secondary validation against SEMI equipment forecasts, Taiwan NMI metrology bulletins, China GB/T standard filings, and SEC 10-K disclosures from ASE Technology Holding, Amkor Technology, and JCET. Bottom-up capacity utilization models triangulated against top-down semiconductor assembly spend estimates.
Scenario-bracketing framed low, base, and high cases across the projection horizon without specifying discrete year markers. Segmentation dimensions modeled include service architecture, end-user vertical, technology maturity tier, and regional regulatory cluster. CAGRs derived from equipment shipment trajectories and cleanroom investment pipelines rather than extrapolated historical growth. Industry-specific forecast inputs encompassed thermal compression bonding yield learning curves and automotive qualification timeline distributions.
Sensitivities concentrate around export control classifications on advanced packaging equipment and REACH substance list expansions affecting solder chemistry. Forecasts reflect assumptions about heterogeneous integration adoption rates in AI accelerators and electric vehicle production scaling. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Semiconductor Wafer Tape Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
Global High-End Semiconductor Packaging Market
Semiconductor Packaging
Global Semiconductor Equipment Packaging and Test Market
Semiconductor Packaging
Semiconductor Packaging Material Market
Semiconductor Packaging
Ball Grid Array (BGA) Packaging Market
Semiconductor Packaging
Bonding Wire Packaging Market
Semiconductor Packaging
Wafer Carrier Boxes Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market
Semiconductor Packaging
Global Semiconductor Seals Market
Semiconductor Packaging
Flip-Chip COB Technology Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
Microtube Box Market
Semiconductor Packaging
Wafer Level Packaging (WPL) Market
Semiconductor Packaging
Through Silicon via (TSV) Packaging Market
Semiconductor Packaging
Epoxy Potting Market