
 Global Bare Die Shipping and Handling and Processing and Storage Market | 2026-2036
Global Bare Die Shipping and Handling and Processing and Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bare Die Shipping and Handling and Processing and Storage Market Foresight
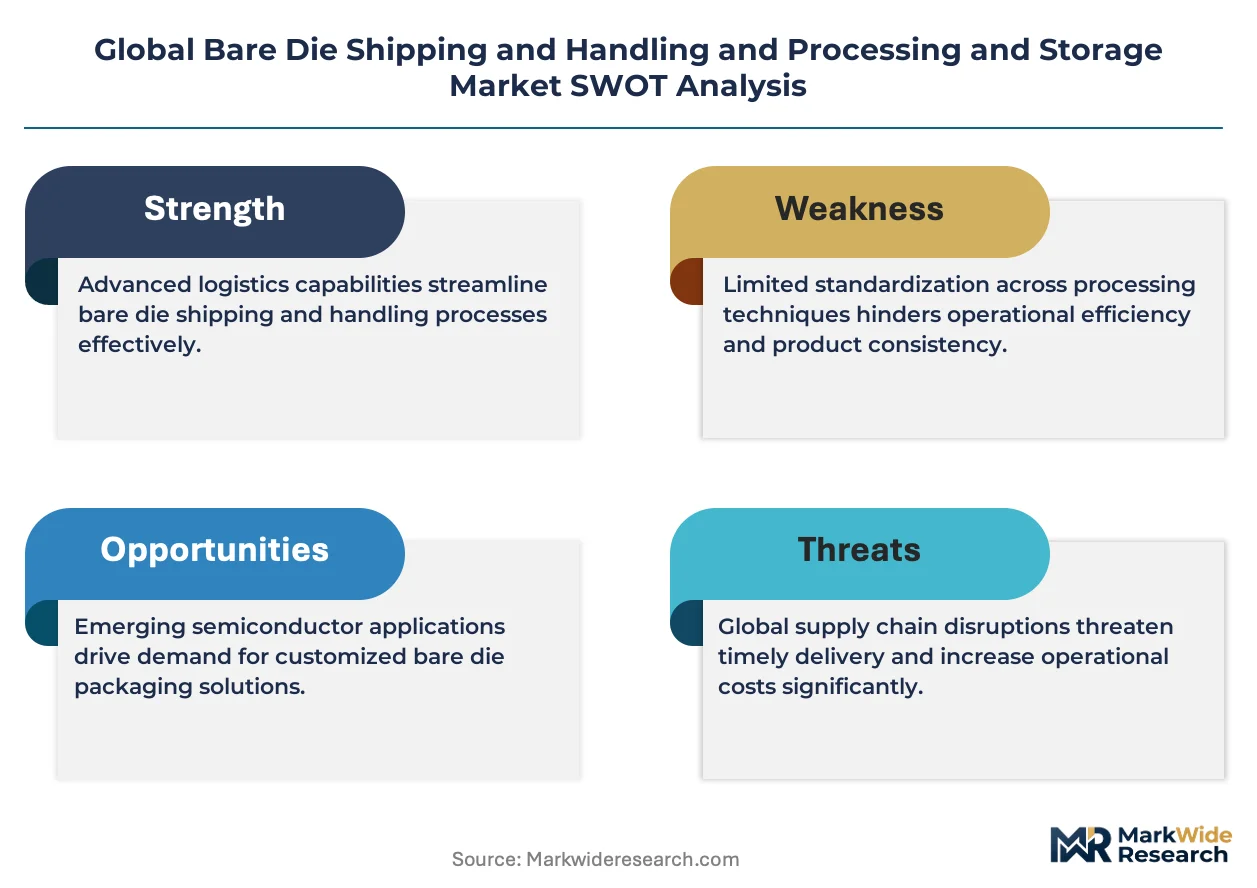
IDM-led captive logistics is collapsing as fabless semiconductor designers and outsourced assembly houses capture a growing share of bare die handling volume. Entegris leverages its materials science heritage to dominate contamination-controlled shipping media for advanced node dies. Brooks Automation sustains leadership in automated storage and retrieval systems for high-mix die inventories. Advantek specializes in substrate tray architectures that accommodate shrinking die form factors.
Bare die shipping and handling and processing and storage encompasses the engineered systems, materials, and protocols that protect unpackaged semiconductor dies from fabrication through final assembly, requiring particulate control below Class 1000 standards and electrostatic discharge protection below 100 volts. The primary purpose is to preserve die yield and electrical performance across multi-step global supply chains where thermal cycling and mechanical shock threaten functional integrity. Wire bonding and flip chip processing methods lead current volume but plasma etching and laser trimming represent the fastest-growing segments as heterogeneous integration demands finer die preparation. Climate-controlled cabinets and electrostatic discharge bags anchor existing infrastructure while vacuum-sealed containers capture margin pools in photonics and RF component handling where moisture sensitivity levels drive premium pricing.
The EPA enforces hazardous substance reporting for semiconductor transport packaging under TSCA, while ISO 14644 cleanroom standards govern die exposure limits during handling operations. REACH compliance in Europe restricts certain polymer additives in shipping trays, forcing material reformulation across supplier bases. Stakeholders must monitor how dual-use export control expansions affect cross-border die shipments to defense contractor end users.
Market Dynamics
IDM-led captive logistics is collapsing as fabless semiconductor designers and outsourced assembly houses capture handling volume, forcing established suppliers to restructure service portfolios around contamination control and traceability mandates.
Growth Catalysts
- Heterogeneous integration architectures:Chiplet-based designs multiply die touchpoints between fabrication and final assembly, expanding addressable logistics scope for specialized handlers.
- EU Chips Act traceability mandates:Cross-border semiconductor shipments now require documented chain-of-custody records, generating compliance-driven demand for integrated tracking systems.
- Taiwan's Hsinchu Science Park cluster concentration:Foundry output density creates natural aggregation points for high-throughput automated handling infrastructure.
Market Restraints
- Fluoropolymer supply concentration:REACH restrictions on perfluorinated compound formulations limit tray and carrier material sourcing flexibility across European supply chains.
- Cleanroom infrastructure capex thresholds:Class 1000 and below particulate control requires facility investments that exclude mid-tier logistics providers from advanced node contracts.
- Moisture sensitivity level classification complexity:JEDEC MSL ratings above 3 demand nitrogen-purged shipping environments that standard freight operators cannot provision.
Strategic Opportunities
- India's semiconductor assembly and test ecosystem:PLI scheme incentives for OSAT investments create greenfield demand for bare die handling infrastructure in Gujarat and Karnataka.
- Photonics component logistics:Indium phosphide and silicon photonics dies require vacuum-sealed containers with thermal stabilization, commanding premium service tiers.
- Dual-use export control expansion:Defense contractor end-user screening requirements favor handlers with established ITAR compliance frameworks and secure facility certifications.
Industry Challenges
- Electrostatic discharge technician certification:ANSI/ESD S20.20-qualified personnel scarcity constrains facility expansion timelines for high-volume handlers.
- Legacy tray format incompatibility:Shrinking die form factors below 1mm edge length render existing substrate carrier inventories obsolete, forcing capital-intensive retooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bare Die Shipping and Handling and Processing and Storage Market |
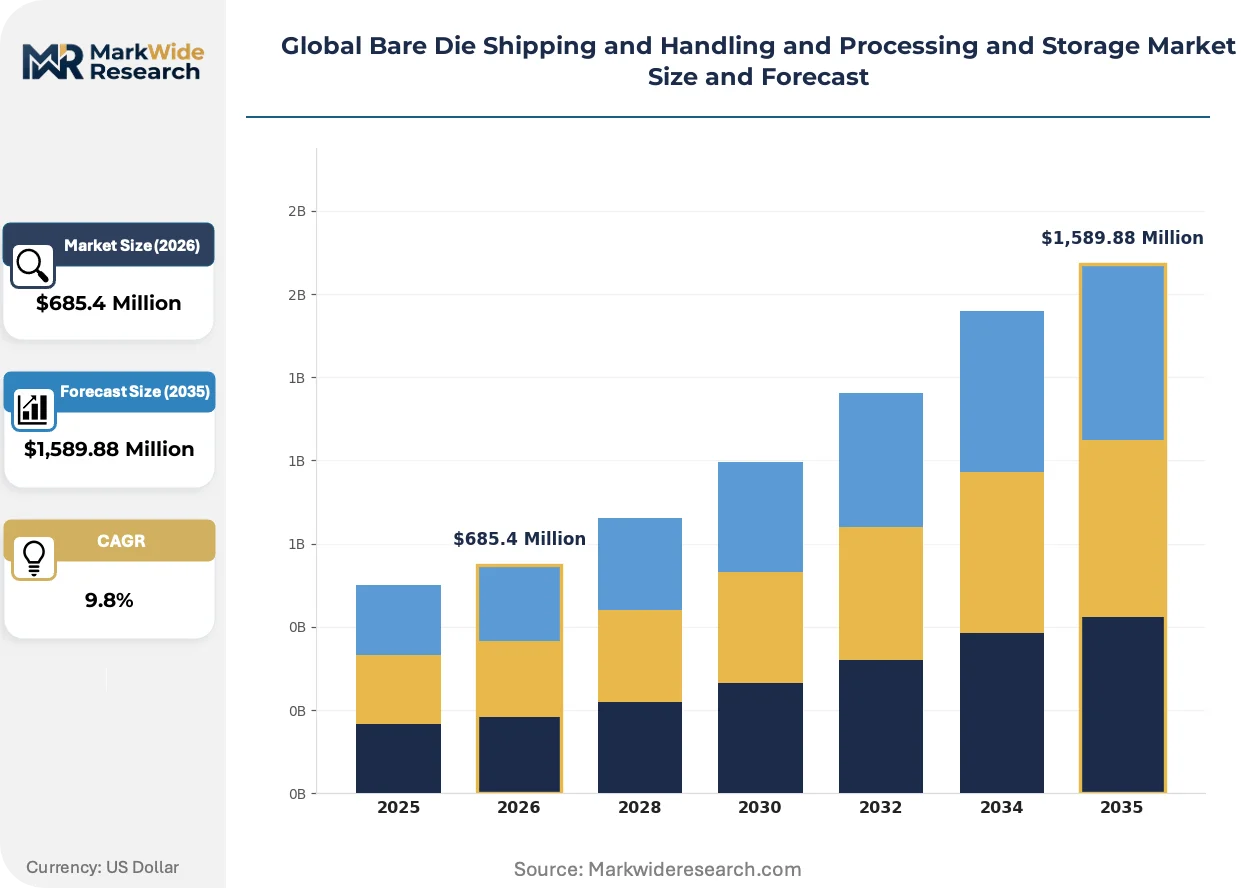
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,589.88 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bare Die Shipments, Wafers, Silicon Chips, Embedded Circuits, Photonics Components Processing Method: Wire Bonding, Flip Chip, Die Attach, Encapsulation, Plasma Etching, Laser Trimming Storage Technology: Climate-Controlled Cabinets, Electrostatic Discharge Bags, Vacuum-Sealed Containers, Substrate Trays, Refrigerated Units End User Industry: Semiconductor Fabricators, Consumer Electronics Manufacturers, Aerospace Suppliers, Defense Contractors, Telecommunications Providers |
| Companies Covered | Entegris, 3M, Brooks Automation, Achilles USA, Kostat, ITW ECPS, Dalau, Daitron Incorporated, Advantek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bare Die Shipping and Handling and Processing and Storage Market Shifts & Advancements
Active materials science development is redefining contamination control boundaries, while regulatory traceability mandates and buyer consolidation reshape competitive requirements across the value chain.
Advanced polymer nanocomposites with embedded electrostatic dissipation properties are fragmenting traditional tray material categories. Fabless designers in RF and millimeter-wave segments now specify customized dielectric constants for shipping media, compressing standard product lifecycle timelines and forcing compounders to maintain parallel formulation pipelines.
REACH authorization procedures for perfluorinated substances are tightening material constraints on European-sourced shipping trays. Compounders are accelerating bio-based polymer development programs, with photonics handlers in Germany and the Netherlands piloting cellulose-derived alternatives for moisture barrier applications.
Consolidated procurement by top-five fabless designers is compressing supplier qualification cycles and unbundling after-sales service from hardware contracts. Taiwan-based OSATs now demand outcome-based die yield guarantees from logistics providers, transferring financial risk to handlers while securing preferential capacity allocation during supply crunches.
Global Bare Die Shipping and Handling and Processing and Storage Market Segmentation
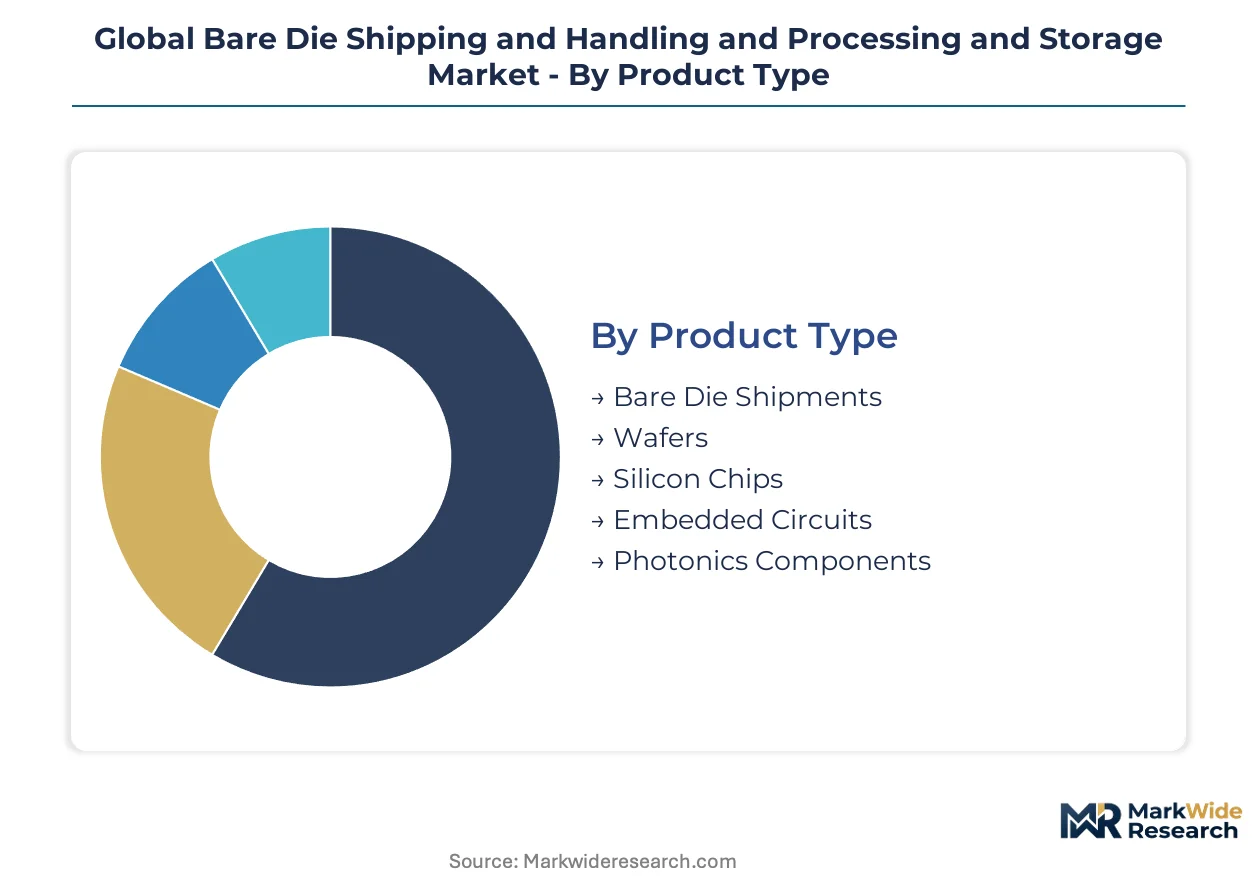
Segmentation in bare die logistics reveals how contamination sensitivity, form factor miniaturization, and regulatory traceability create divergent margin structures across handling modalities. Each dimension captures distinct capex requirements and certification barriers that reshape competitive positioning among specialized handlers.
Product Type:
Margin pools concentrate in photonics and advanced node silicon where moisture sensitivity and electrostatic discharge tolerances command premium service tiers.
- Bare Die Shipments:Unpackaged semiconductor dies transported in substrate trays or waffle packs with Class 1000 particulate control and sub-100-volt ESD protection. Taiwan's Hsinchu Science Park cluster generates the densest handling volume as foundry output aggregation creates natural throughput economies for automated infrastructure.
- Photonics Components:Indium phosphide and silicon photonics dies requiring vacuum-sealed containers with active thermal stabilization to prevent wavelength drift. Defense contractor end-users in the US and Germany drive specification stringency through ITAR and dual-use export control compliance mandates.
- Wafers:Full-diameter silicon substrates handled in FOUPs and specialized shippers with edge-grip automation.
- Silicon Chips:Singulated dies with intermediate processing completion staged for downstream assembly.
- Embedded Circuits:Partially integrated multi-die subsystems requiring traceable chain-of-custody documentation under EU Chips Act requirements.
The dominant share belongs to bare die shipments, while photonics components are closing the gap fastest.
Processing Method:
Volume distribution tracks the shift from wire-intensive interconnect toward flip chip and precision etching as heterogeneous integration architectures proliferate.
- Wire Bonding:Thermosonic and thermocompression attachment of gold or copper wires between die pads and leadframes. Consumer electronics manufacturers in Vietnam and Mexico sustain high throughput demand for mature node logic and memory products.
- Plasma Etching:Reactive ion processing for die surface preparation and undercut control in 3D stacking applications. Advanced packaging facilities in South Korea and Japan specify this method for high-bandwidth memory and logic-on-logic integration.
- Flip Chip:Solder bump or copper pillar interconnect with direct die-to-substrate attachment.
- Die Attach:Adhesive and eutectic bonding processes for thermal and mechanical die fixation.
- Encapsulation:Molding compound application for environmental and mechanical protection of bonded assemblies.
- Laser Trimming:Precision ablation for resistor adjustment and die singulation in RF component preparation.
Wire bonding retains the largest installed base, though plasma etching is expanding most quickly as chiplets multiply die touchpoints.
Storage Technology:
Cost tier stratification separates commodity electrostatic protection from nitrogen-purged and vacuum-sealed systems required by JEDEC MSL 3+ classifications.
- Vacuum-Sealed Containers:Hermetic barrier packaging with desiccant integration and humidity indicator cards for moisture-sensitive devices. Photonics handlers in Germany and the Netherlands pilot cellulose-derived alternatives as REACH restrictions constrain fluoropolymer sourcing.
- Substrate Trays:Injection-molded carriers with pocket geometries matched to shrinking die form factors below 1mm edge length. Taiwan-based OSATs now demand outcome-based die yield guarantees tied to tray specification compliance.
- Climate-Controlled Cabinets:Ambient temperature stabilization with particulate filtration for short-duration die staging.
- Electrostatic Discharge Bags:Metallized polymer barriers for standard semiconductor products with MSL ratings below 3.
- Refrigerated Units:Sub-ambient storage for specialized compound semiconductor materials with temperature-dependent degradation kinetics.
Substrate trays command the highest shipment volumes, while vacuum-sealed containers are gaining share fastest in RF and photonics segments.
End User Industry:
Procurement concentration among top-five fabless designers compresses supplier qualification cycles and unbundles service contracts from hardware sales.
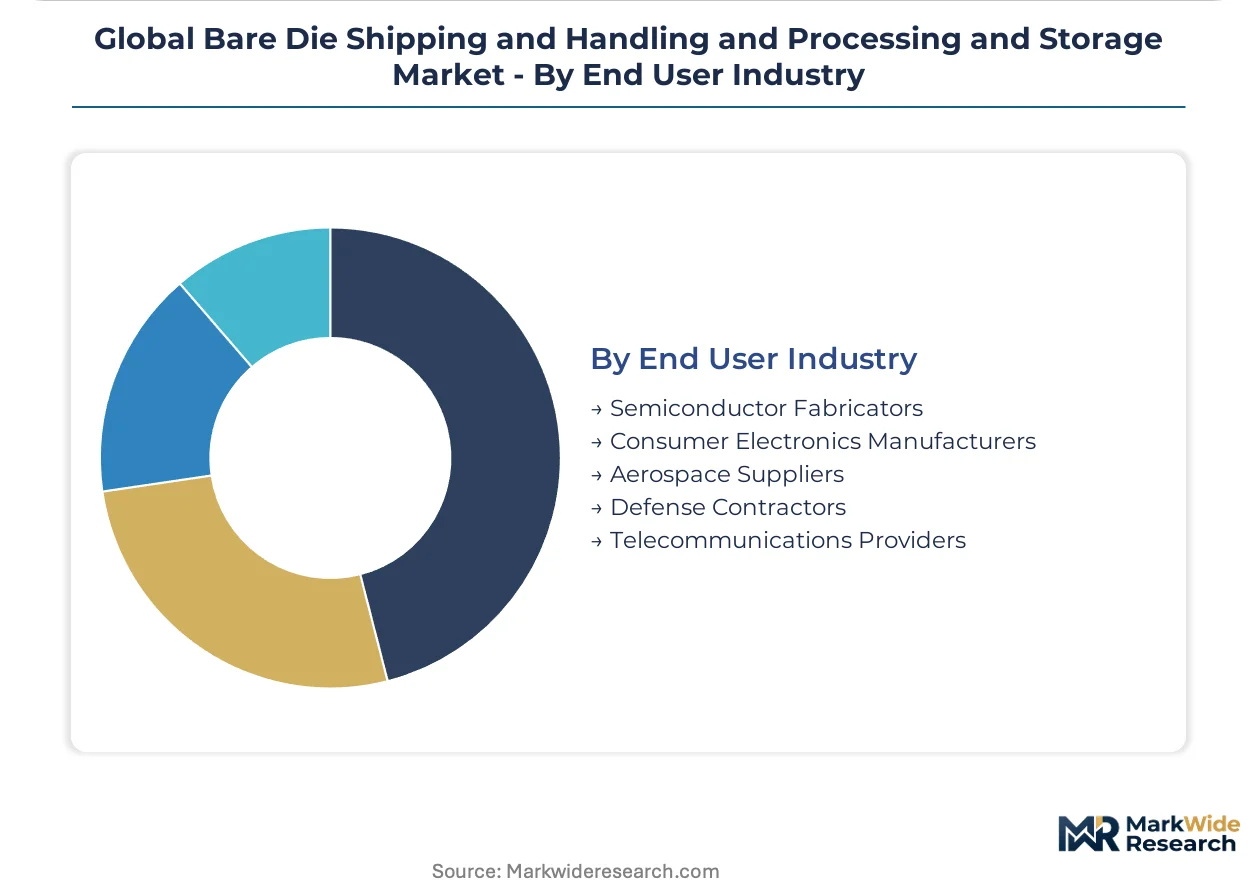
- Semiconductor Fabricators:Foundry and IDM facilities managing die output from wafer singulation through outsourced assembly handoff. India's PLI scheme incentives for OSAT investments in Gujarat and Karnataka create greenfield demand for automated handling infrastructure.
- Defense Contractors:End-users subject to expanded dual-use export controls requiring handlers with established ITAR compliance frameworks and secure facility certifications. US and European procurement offices now mandate documented chain-of-custody records for cross-border shipments.
- Consumer Electronics Manufacturers:High-volume assembly operations with cost-optimized handling specifications for mature node products.
- Aerospace Suppliers:Radiation-hardened and high-reliability component handlers with extended qualification protocols.
- Telecommunications Providers:5G infrastructure and optical network equipment manufacturers driving millimeter-wave die specifications.
Semiconductor fabricators anchor current demand, while defense contractors are expanding their specification influence fastest through security-driven procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's Kaohsiung Port expansion underwrites the densest bare die handling throughput globally, with automated container terminals processing wafer-level shipments bound for OSAT facilities. Germany's Rhine-Main corridor anchors European photonics logistics through Frankfurt Airport's temperature-controlled cargo infrastructure. India's Mundra Port connectivity supports emerging assembly investments in Gujarat.
Taiwan
Hsinchu Science Park foundry aggregation drives automated handling infrastructure deployment. The National Development Council enforces semiconductor supply chain security protocols under the Industrial Innovation Act. Taichung's precision machinery corridor hosts tray and carrier manufacturing clusters serving die form factors below 1mm edge length.
United States
Defense contractor procurement mandates expand ITAR-compliant handling capacity for secure die shipments. The EPA enforces hazardous substance reporting for semiconductor transport packaging under TSCA. Arizona's Phoenix metro attracts captive logistics investments from IDMs transitioning to fabless outsourcing models.
Germany
Photonics component handlers pilot cellulose-derived moisture barriers as REACH restrictions constrain fluoropolymer sourcing. ECHA authorization procedures for perfluorinated substances tighten material constraints on shipping tray formulations. Dresden's silicon Saxony cluster concentrates vacuum-sealed container demand for indium phosphide dies.
India
PLI scheme incentives for OSAT investments create greenfield demand for bare die handling infrastructure. BIS certification requirements govern electrostatic discharge protection standards for imported shipping media. Gujarat's Dholera Special Investment Region anchors semiconductor assembly and test ecosystem development with dedicated logistics zones.
South Korea
Advanced packaging facilities specify plasma etching preparation for high-bandwidth memory integration. The Ministry of Trade, Industry and Energy administers export control frameworks affecting dual-use die shipments. Pyeongtaek's semiconductor cluster proximity to Incheon Airport enables rapid-turn nitrogen-purged cargo handling.
Global Bare Die Shipping and Handling and Processing and Storage Market Competitive Landscape
Concentration sits with materials science specialists and automation system providers that control contamination-critical shipping media. The vendor base spans three tiers: integrated materials-automation conglomerates, specialized substrate tray fabricators, and regional logistics service operators. Two strategic archetypes dominate—heritage cleanroom materials suppliers extending into die handling protocols, and robotic storage system vendors capturing high-mix inventory automation. Competitive moves center on capacity expansion in Taiwan and India, plus strategic partnerships with top-five fabless designers seeking outcome-based yield guarantees.
Among US-based materials specialists, Entegris and 3M exemplify the heritage contamination control archetype, leveraging polymer science capabilities into shipping media specifications. Brooks Automation anchors the automated storage and retrieval segment, occupying a position in high-throughput die inventory management systems. Advantek represents the specialized substrate architecture tier, with tray design expertise aligned to shrinking form factor requirements. These three players collectively illustrate how technical specialization in particulate control, robotics integration, or pocket geometry engineering creates defensible positioning against generalized logistics competitors.
| Leading Market Players |
|---|
| Entegris |
| 3M |
| Brooks Automation |
| Achilles USA |
| Kostat |
| ITW ECPS |
| Dalau |
| Daitron Incorporated |
| Advantek |
| Others |
Supply & Pricing Matrix
Cellulose-derived moisture barriers displacing fluoropolymer trays in European-sourced shipping media simultaneously redraw raw material procurement maps and compress margin structures for legacy compounders facing REACH authorization deadlines.
Pricing Analysis
Volume-discount tiering structures separate bare die shipments from photonics components and vacuum-sealed containers, with JEDEC MSL 3+ classifications commanding premium service tiers. Price differentiation hinges on contamination control certification levels and after-sales service bundling, particularly for Taiwan-based OSATs demanding outcome-based die yield guarantees. Cost compression in standard substrate trays intensifies as shrinking die form factors below 1mm edge length force capital-intensive retooling. Consumer electronics manufacturers in Vietnam and Mexico exhibit highest price sensitivity, while defense contractors accept premium pricing for ITAR-compliant secure handling protocols.
Supply Chain Analysis
Inventory lead times for advanced polymer nanocomposites stretch 8-14 weeks as bio-based formulation pipelines compete with legacy fluoropolymer stockpiles. Supply concentrates in Taiwan, Germany, and the United States, with tray fabrication drawing from indium phosphide substrates, desiccant-integrated films, and electrostatic-dissipative compounds. Single-source vulnerability in perfluorinated compound formulations threatens European logistics providers under REACH restrictions. Distribution runs through foundry-adjacent automated container terminals, nitrogen-purged cargo handlers, and secure defense contractor facilities with documented chain-of-custody protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to fabless semiconductor design house capital expenditure cycles, with heterogeneous integration architectures multiplying die touchpoints between fabrication and final assembly.
For Market Incumbents: Compound contamination control capabilities through backward integration into polymer compounding operations, securing supply of electrostatic-dissipative nanocomposites amid REACH-driven material constraints. Expand automated storage and retrieval capacity in Taiwan's Hsinchu Science Park cluster to capture foundry output aggregation economies. Prioritize ITAR compliance framework investments as defense contractor procurement mandates harden secure facility certification requirements.
For New Entrants and Emerging Players: Outcome-based die yield guarantee services represent a service-layer gap where incumbents under-serve mid-tier fabless designers seeking risk transfer from logistics providers. Target India's Gujarat and Karnataka OSAT greenfield investments under PLI scheme incentives, where bare die handling infrastructure demand outpaces established supplier qualification cycles. Lead with cellulose-derived moisture barrier pilot programs as REACH restrictions accelerate bio-based polymer adoption in Germany and the Netherlands.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialized substrate tray fabricators holding pocket geometry engineering expertise aligned to sub-1mm die form factors. Five-to-ten year viability hinges on consolidation plays capturing Taiwan-India corridor automation demand and photonics logistics premium service tiers. Monitor EU Chips Act traceability mandate enforcement intensity as inflection indicator for integrated tracking system valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Secures electrostatic-dissipative material supply amid REACH-driven fluoropolymer constraints. |
| Capacity Expansion in Taiwan Science Park Corridor | Captures foundry output aggregation economies for high-throughput automated handling infrastructure. |
| ITAR Compliance Framework Certification | Unlocks defense contractor procurement mandates requiring secure facility chain-of-custody protocols. |
| Bio-Based Moisture Barrier Development | Positions suppliers ahead of ECHA authorization deadlines for perfluorinated compound restrictions. |
| Outcome-Based Yield Guarantee Service Launch | Transfers financial risk from fabless designers while securing preferential capacity allocation. |
Research Methodology
Cross-validation between primary interviews with contamination control engineers, OSAT procurement directors, and polymer compounding R&D leads and secondary validation through SEC filings, customs trade data, and ISO cleanroom certification registries anchors the qualitative findings. Bottom-up triangulation aggregates substrate tray shipment volumes, vacuum-sealed container deployment rates, and automated storage system installations across foundry and OSAT facilities. Top-down validation cross-references fabless designer capital expenditure disclosures with EU Chips Act implementation timelines and REACH authorization procedure schedules.
Sensitivity analysis tests forecast robustness across heterogeneous integration adoption rates, JEDEC MSL classification stringency evolution, and dual-use export control expansion scenarios. The analytical framework models product type segmentation by contamination sensitivity tier, processing method by interconnect architecture, storage technology by moisture sensitivity classification, and end-user industry by procurement concentration patterns. CAGRs derive from installed base replacement cycles, greenfield capacity absorption rates, and premium service tier penetration trajectories. Industry-specific inputs include wafer-level packaging adoption curves and photonics component wavelength stabilization requirements.
Underlying assumptions cover sustained fabless outsourcing momentum, REACH authorization timeline adherence, and Taiwan-India logistics corridor development, with deviation risk concentrated in fluoropolymer supply disruption, cleanroom infrastructure capex threshold escalation, and ANSI/ESD S20.20 technician certification scarcity constraining facility expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Semiconductor Chip Handler Market
Semiconductor Packaging
Semiconductor Wafer Tape Market
Semiconductor Packaging
Semiconductor Solder Flux Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Test Services (OSAT) Market
Semiconductor Packaging
ESD Stackable Boxes Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
Wafer Level Packaging (WPL) Market
Semiconductor Packaging
Microtube Box Market
Semiconductor Packaging
Global Semiconductor Seals Market
Semiconductor Packaging
Antenna-In-Package Technology Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Testing Market
Semiconductor Packaging
Embedded Die Packaging Market
Semiconductor Packaging
Global Semiconductor Packaging and Assembly Equipment Market
Semiconductor Packaging
System-On-Package Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
Asia-Pacific Quad-Flat-No-Lead Packaging Market