
 Wafer Level Packaging (WPL) Market | 2026-2036
Wafer Level Packaging (WPL) Market Size, Share, and Industry Trends Forecast 2026-2036
Wafer Level Packaging (WPL) Market Analytics
The EU Green Deal and associated supply-chain due diligence rules are consolidating purchasing power among buyers who now mandate lower-carbon packaging processes. Taiwan Semiconductor Manufacturing Company Limited leverages its captive advanced packaging capacity to bind leading fabless customers. ASE Technology Holding Co., Ltd. anchors its competitive position through massive OSAT scale across multiple geographies. Samsung Electronics Co., Ltd. dominates by integrating memory and logic packaging within its captive semiconductor operations.
Wafer Level Packaging refers to the complete integration of die protection, electrical connection, and thermal management functions while the semiconductor die remains on the original wafer substrate, typically achieving interconnect pitches below 40 micrometers and enabling die footprints nearly identical to the original chip size. This technology serves the primary industrial purpose of miniaturizing electronic systems without sacrificing electrical performance or thermal dissipation capability. Fan-Out packaging leads in structural importance because it liberates I/O constraints beyond die boundaries, while Through-Silicon Via technology captures the fastest expansion trajectory as heterogeneous integration demands multiply. Wafer-Level Chip Scale packaging retains mature, high-volume status in cost-sensitive consumer applications where margin pools remain thin but stable.
The EPA regulates hazardous substance reporting from semiconductor packaging facilities in the United States, while REACH restricts specific chemicals in European packaging materials and processes. Taiwan's environmental regulators enforce wastewater and air emission standards that shape foundry location decisions for advanced packaging expansion. Stakeholders must monitor how divergent chemical compliance regimes across these jurisdictions reshape total cost of ownership for multi-site packaging strategies.
Market Dynamics
Advanced packaging capacity concentration in Taiwan, South Korea, and the United States is reshaping competitive access as sovereign semiconductor initiatives redirect capital flows and fragment equipment procurement pools.
Growth Catalysts
- Fan-Out Wafer-Level Packaging:Smartphone manufacturers accelerate adoption for thinner, higher-performance devices, compressing die footprints while maintaining electrical integrity.
- EU Chips Act:Sovereign semiconductor initiatives redirect capital toward advanced packaging capacity, expanding regional manufacturing footprints.
- Heterogeneous Integration Demands:Through-Silicon Via technology captures fastest expansion trajectory as chiplet architectures multiply interconnection requirements.
Market Restraints
- Equipment Supply Concentration:Lithography and bonding tool vendors cluster in Japan and the Netherlands, creating single-source vulnerability for advanced packaging lines.
- REACH Chemical Restrictions:European regulations constrain specific packaging materials and processes, forcing formulation changes that extend qualification timelines.
- High-Purity Copper Price Volatility:Through-Silicon Via manufacturing depends on sputtering targets and plating chemistry exposed to commodity metal swings.
Strategic Opportunities
- United States OSAT Expansion:CHIPS Act incentives attract advanced packaging investment to Arizona and Texas, creating captive supply options for defense and aerospace buyers.
- Automotive Heterogeneous Integration:ADAS and power module applications demand fan-out packaging for sensor fusion and wide-bandgap semiconductors.
- EU Green Deal Supply-Chain Mandates:Carbon disclosure requirements consolidate purchasing power among buyers who now mandate lower-carbon packaging processes.
Industry Challenges
- Advanced Substrate Interposer Shortage:Glass and organic interposer capacity lags behind CoWoS and EMIB demand, creating allocation bottlenecks for AI accelerators.
- Cross-Jurisdictional Chemical Compliance:Divergent EPA, REACH, and Taiwan environmental regulator regimes reshape total cost of ownership for multi-site packaging strategies.
- Warpage Control at 300mm:Thin-wafer handling and die-shift management in fan-out processes require process engineers with specialized metrology expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wafer Level Packaging (WPL) Market |
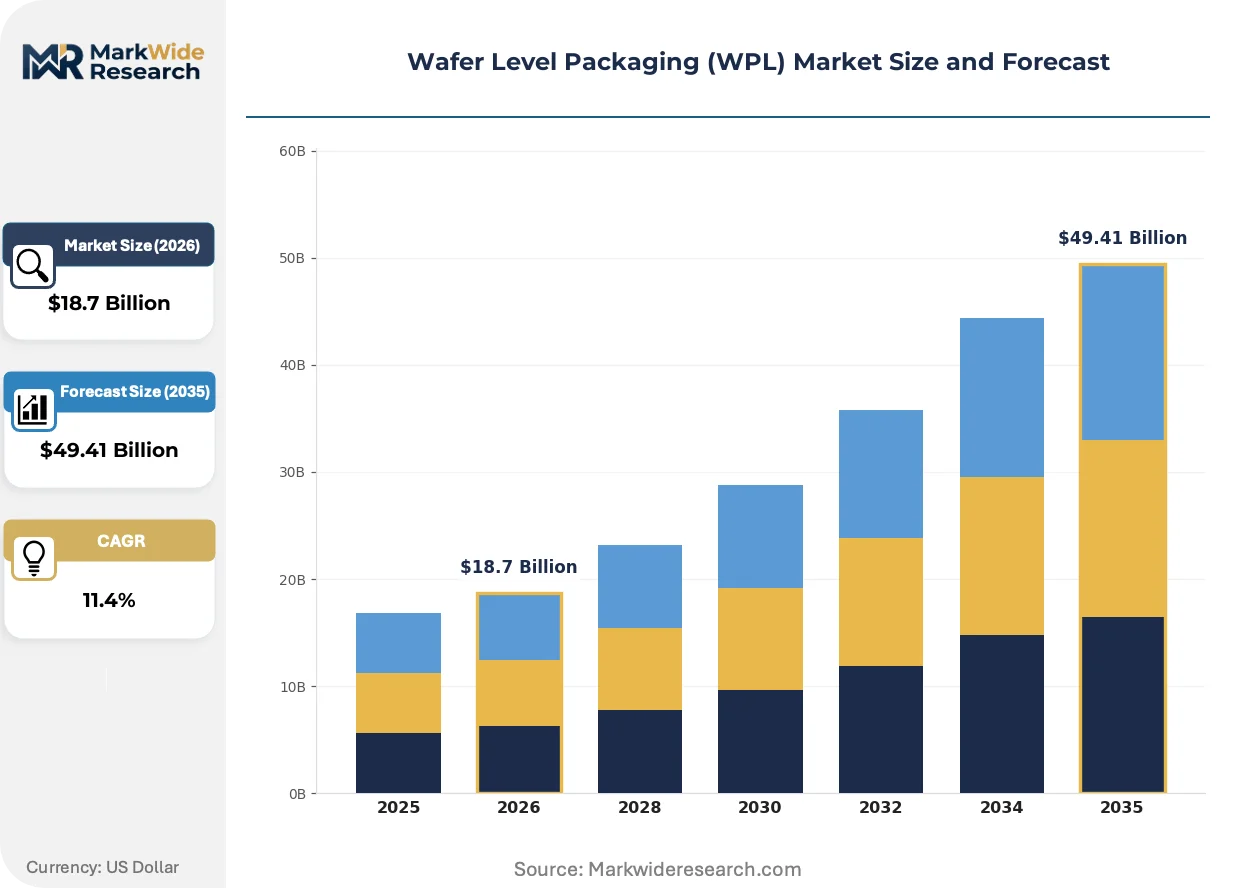
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fan-Out, Fan-In, Through-Silicon Via, Wafer-Level Chip Scale Application: Consumer Electronics, Automotive Electronics, Telecommunications, Medical Devices Technology: 3D Packaging, Embedded Die Technology, Advanced Bonding, High-Density Interconnect End User: Semiconductor Manufacturers, OEMs, Contract Manufacturers, System Integrators |
| Companies Covered | Taiwan Semiconductor Manufacturing Company Limited, ASE Technology Holding Co., Ltd., Amkor Technology, Inc., JCET Group, Intel Corporation, Samsung Electronics Co., Ltd., ChipMOS TECHNOLOGIES INC., China Wafer Level CSP Co. Ltd., Deca Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wafer Level Packaging (WPL) Market Evolving Landscape
Wafer-level packaging technology is fragmenting into specialized process branches as heterogeneous integration demands outpace homogeneous scaling economics.
Hybrid bonding is expanding into 3D memory-on-logic stacks by eliminating microbump pitch limitations. SK Hynix and Samsung deploy this for high-bandwidth memory attachment to AI accelerators at sub-10 micrometer pitches. The technology is compressing traditional flip-chip and wire-bond margins in high-performance computing segments.
REACH chemical restrictions are forcing substitution of lead-based solders and certain epoxy mold compounds in European-bound packaging. Formulation changes extend qualification timelines by 6-18 months for automotive and medical device tiers. OSATs serving EU automotive OEMs are establishing segregated production lines to isolate compliant material flows.
Consolidated buyer procurement is displacing spot-market substrate purchasing as hyperscalers and smartphone OEMs negotiate multi-year advanced packaging capacity reservations. Direct foundry-to-OEM contracts are replacing traditional OSAT-mediated relationships in leading-edge nodes. Taiwan and South Korea show earliest concentration of this behavior among AI chip designers.
Wafer Level Packaging (WPL) Market Segmentation
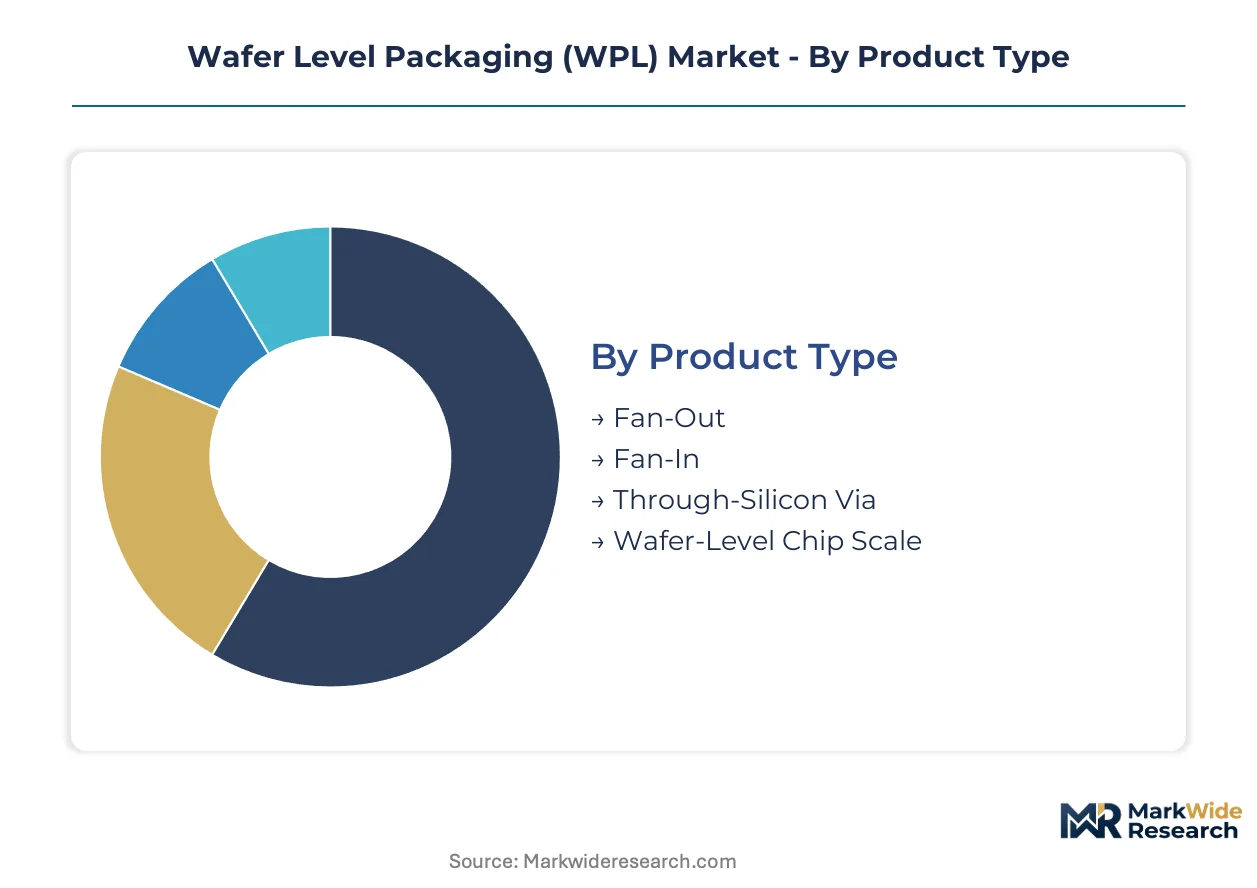
Wafer Level Packaging technology fragments into distinct process branches, each demanding specialized equipment sets and cleanroom configurations. Capital allocation decisions across these segments determine competitive positioning for foundries and OSATs.
Product Type:
Fan-Out and Through-Silicon Via technologies command the heaviest upfront investment, requiring lithography, bonding, and metrology equipment clusters that strain balance sheets.
- Fan-Out:Redistribution layers extend interconnect beyond die boundaries using epoxy mold compound reconstitution. Smartphone OEMs in Taiwan and South Korea drive volume for thinner handset architectures where z-height constraints dominate design.
- Through-Silicon Via:Vertical copper interconnects pierce silicon substrates to stack memory and logic dies. AI accelerator designers concentrate demand here as heterogeneous integration multiplies bandwidth requirements between chiplets.
- Fan-In:Die-sized packaging with perimeter I/O pads suits cost-sensitive consumer applications. Legacy wire-bond conversion continues in Southeast Asian OSAT facilities serving mid-tier smartphone markets.
- Wafer-Level Chip Scale:Mature redistribution layer processes achieve near-die-size footprints. Automotive sensor modules and wearable devices sustain stable demand with thinner margin pools.
Fan-Out absorbs the bulk of installed capacity; Through-Silicon Via is expanding most quickly.
Application:
Automotive Electronics and Consumer Electronics sit at opposite ends of the qualification spectrum, with divergent reliability requirements reshaping process flow design.
- Automotive Electronics:ADAS sensor fusion and power module packaging demand AEC-Q100 thermal cycling performance. German and Japanese OEMs mandate fan-out processes for radar and LiDAR modules where wide-bandgap semiconductors generate concentrated heat loads.
- Consumer Electronics:Smartphones, tablets, and wearables prioritize z-height reduction over thermal extremes. Apple and Samsung procurement teams reserve capacity at TSMC and ASE for flagship device launches.
- Telecommunications:5G baseband and RF front-end modules require tight impedance control. Network equipment vendors in Finland and Sweden specify wafer-level packaging for millimeter-wave antenna-in-package solutions.
- Medical Devices:Implantable and diagnostic instruments impose biocompatibility and hermeticity standards. FDA 510(k) pathways extend qualification timelines for cardiac monitor and hearing aid packaging.
Consumer Electronics retains the deepest capacity absorption; Automotive Electronics climbs the fastest as electrification multiplies semiconductor content per vehicle.
Technology:
3D Packaging and Advanced Bonding concentrate proprietary process knowledge, creating capability moats that equipment vendors exploit through long-term service contracts.
- 3D Packaging:Stacked memory and logic dies interconnect through hybrid bonding or microbumps. SK Hynix and Samsung deploy this for high-bandwidth memory attachment to AI accelerators at sub-10 micrometer pitches.
- Advanced Bonding:Thermocompression and laser-assisted bonding achieve fine-pitch die attachment. OSATs in Taiwan and Malaysia compete for smartphone AP and modem packaging where thermal budget constraints dominate.
- Embedded Die Technology:Active components integrate within printed circuit board substrates. Power module suppliers favor this for silicon carbide MOSFET packaging in electric vehicle inverters.
- High-Density Interconnect:Fine-line lithography and sequential build-up create multilayer redistribution. Network processors and FPGA devices drive demand where I/O count exceeds peripheral pad limitations.
3D Packaging captures the steepest expansion trajectory; High-Density Interconnect maintains the broadest installed base across mature product generations.
End User:
Semiconductor Manufacturers and Contract Manufacturers operate distinct procurement models, with captive foundries favoring in-house packaging while fabless designers outsource to OSATs.
- Semiconductor Manufacturers:IDMs and foundries integrate packaging with front-end fabrication. TSMC binds leading fabless customers through captive CoWoS capacity for AI training chips.
- Contract Manufacturers:OSATs and EMS providers assemble packaged dies into finished systems. Foxconn and Jabil negotiate volume commitments with ASE and Amkor for smartphone and server motherboard integration.
- OEMs:Apple, Tesla, and defense primes increasingly contract directly with foundries for advanced packaging. CHIPS Act incentives accelerate this bypass of traditional OSAT mediation for Arizona-based capacity.
- System Integrators:Hyperscalers and telecom equipment vendors specify packaging requirements for custom silicon. Google and Amazon procurement teams reserve fan-out capacity for TPU and Trainium accelerators.
Semiconductor Manufacturers deploy the majority of captive capacity; OEM direct contracting gains share fastest as sovereign semiconductor initiatives reshape procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors the densest concentration of advanced packaging capacity worldwide, with foundry and OSAT operations clustering along this corridor to exploit proximity to front-end fabrication and specialized talent pools.
United States
CHIPS Act incentives attract advanced packaging investment to Arizona and Texas, where defense and aerospace buyers seek captive supply options. EPA hazardous substance reporting requirements shape facility siting decisions for multi-site operators. Phoenix and Austin metropolitan areas host the fastest-expanding cleanroom construction for fan-out and 3D packaging lines.
Taiwan
Environmental regulators enforce wastewater and air emission standards that constrain foundry expansion timing for advanced packaging capacity. Taiwan's environmental regulator mandates shape total cost calculations for multi-site strategies. Hsinchu and Tainan Science Industrial Parks concentrate CoWoS and InFO operations serving AI accelerator designers.
South Korea
Memory-logic integration demands multiply heterogeneous packaging requirements for high-bandwidth memory attachment. MFDS medical device regulations extend qualification timelines for biocompatible packaging tiers. Pyeongtaek and Yongin host the densest hybrid bonding capacity for sub-10 micrometer pitch 3D stacks.
Japan
Equipment vendor concentration in lithography and bonding tools creates procurement vulnerability for advanced packaging lines. METI industrial policy directs subsidy flows toward domestic packaging autonomy initiatives. Hiroshima and Kyoto prefectures anchor precision tool manufacturing clusters supplying global OSAT tool procurement pools.
Germany
Automotive OEMs mandate AEC-Q100 thermal cycling performance for ADAS sensor fusion modules. REACH chemical restrictions constrain lead-based solder and epoxy mold compound formulations in European-bound packaging. Dresden and Bavaria concentrate automotive electronics design centers specifying fan-out processes for radar and LiDAR.
Wafer Level Packaging (WPL) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and captive capacity access, with foundry-integrated operations commanding pricing power over pure-play OSATs. The vendor base stratifies into three tiers: integrated device manufacturers with captive packaging, foundry-affiliated advanced packaging units, and independent OSATs serving cost-optimized segments. Two archetypes dominate competitive positioning: technology licensors extracting rents from proprietary bonding and lithography processes, and scale operators amortizing equipment clusters across high-volume consumer electronics programs. Capacity reservation contracts and direct foundry-to-OEM procurement relationships represent the dominant competitive moves displacing traditional OSAT mediation.
Within the foundry-affiliated tier, Taiwan Semiconductor Manufacturing Company Limited anchors captive advanced packaging capacity binding leading fabless customers through CoWoS reservation structures. ASE Technology Holding Co., Ltd. exemplifies the massive OSAT archetype spanning multiple geographies with scale-driven unit economics. Samsung Electronics Co., Ltd. occupies a position integrating memory and logic packaging within semiconductor operations, representing the IDM-captive archetype with heterogeneous integration capabilities.
| Leading Market Players |
|---|
| Taiwan Semiconductor Manufacturing Company Limited |
| ASE Technology Holding Co., Ltd. |
| Amkor Technology, Inc. |
| JCET Group |
| Intel Corporation |
| Samsung Electronics Co., Ltd. |
| ChipMOS TECHNOLOGIES INC. |
| China Wafer Level CSP Co. Ltd. |
| Deca Technologies Inc. |
| Others |
Value Network & Pricing Analysis
High-purity copper price volatility cascades through wafer-level packaging supply chains, compressing margins in Through-Silicon Via manufacturing while amplifying pricing power for integrated foundries with captive sputtering target supply. Tiered pricing separates CoWoS reservation structures from spot-market fan-out capacity, with AI accelerator designers absorbing premium tiers and mid-tier smartphone OEMs clustering in economy segments.
Pricing Analysis
Yield-guaranteed throughput anchors value-based pricing for advanced packaging lines, with CoWoS capacity commanding reservation premiums tied to silicon interposer yield rates rather than per-wafer processing fees. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence—AEC-Q100 automotive qualification extends timelines and inflates standard-tier spreads, while consumer electronics volumes compress economy-tier margins. Pricing pressure stems from REACH chemical reformulation costs passing through to European-bound packaging tiers. Fabless AI chip designers show least price sensitivity; Southeast Asian OSATs serving mid-tier smartphone markets absorb maximum margin compression.
Supply Chain Analysis
Dual-sourcing mandates from defense and aerospace buyers force lithography and bonding tool procurement across Japanese and Dutch vendor bases, isolating single-source vulnerability in advanced packaging lines. Taiwan, South Korea, and the United States concentrate front-end fabrication and advanced packaging capacity, drawing from Japanese equipment clusters and German chemical precursor supply. High-purity copper sputtering targets, epoxy mold compounds, and glass interposer substrates anchor raw material dependencies. Single-source vulnerability in EUV lithography tools for sub-10 micrometer hybrid bonding creates procurement risk. Distribution runs through direct foundry-to-OEM contracts displacing traditional OSAT mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical restrictions erect a cost-of-compliance barrier that consolidates margin pools among European-qualified packaging tiers, with reformulation timelines extending 6-18 months for automotive and medical device segments.
For Market Incumbents: To counter sovereign semiconductor initiatives fragmenting equipment procurement pools, TSMC and Samsung deepen backward integration into captive interposer manufacturing while ASE expands Malaysia and Vietnam cleanroom footprints to isolate REACH-compliant production lines. Capacity reservation structures bind fabless AI customers through multi-year CoWoS commitments. For New Entrants and Emerging Players: CHIPS Act incentives in the United States open a window for Arizona-based fan-out specialists serving defense primes seeking captive supply options. White-space concentrates in automotive heterogeneous integration for silicon carbide power modules and medical device biocompatible packaging tiers. Go-to-market leverage rests on AEC-Q100 qualification acceleration and FDA 510(k) pathway expertise. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision metrology specialists in Japan and Taiwan with warpage control IP for 300mm thin-wafer handling. Long-term viability centers on hybrid bonding equipment vendors and glass interposer substrate capacity. The signal to watch is AI accelerator designer procurement shifting from OSAT mediation to direct foundry contracting.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Capacity Expansion | SK Hynix and Samsung deploy sub-10 micrometer pitch stacks for high-bandwidth memory attachment. |
| Backward Integration into Interposer Manufacturing | TSMC captive CoWoS silicon interposer supply binds leading fabless AI accelerator designers. |
| REACH-Compliant Production Line Segregation | ASE establishes isolated European-bound packaging flows to satisfy German automotive OEM mandates. |
| Direct Foundry-to-OEM Capacity Reservation | Apple and Google procurement teams bypass traditional OSAT mediation for Arizona-based advanced packaging. |
| Automotive AEC-Q100 Qualification Acceleration | Fan-out specialists capture ADAS sensor fusion demand from German and Japanese electrification programs. |
Research Methodology
Independent corroboration across packaging equipment vendor shipment data, foundry capital expenditure disclosures, and OSAT utilization surveys underwrites the qualitative findings in this study. Primary interviews with advanced packaging process engineers, semiconductor procurement directors, and cleanroom construction contractors combined with secondary validation from EPA hazardous substance filings, ECHA REACH registration databases, and Taiwan environmental regulator emission permits. Bottom-up capacity build-up across Hsinchu, Pyeongtaek, and Phoenix metropolitan clusters triangulates against top-down semiconductor content-per-device estimates.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon, modeling technology transition from wire-bond to fan-out to Through-Silicon Via penetration curves. Segmentation dimensions span packaging architecture, application thermal qualification tier, bonding pitch class, and regional regulatory cluster. CAGRs derive from equipment procurement pipeline analysis and foundry disclosed capacity ramps. Forecast inputs incorporate AI accelerator shipment trajectories and electric vehicle semiconductor content curves.
The model assumes a particular technology adoption path; alternative pathways for hybrid bonding displacing microbump architectures would alter the outlook. Forecasts reflect assumptions on sovereign incentive program disbursement timing and chemical compliance regime convergence. Deviation in high-purity copper commodity cycles or glass interposer substrate availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Chip Carrier Socket Market
Semiconductor Packaging
Global High-End Semiconductor Packaging Market
Semiconductor Packaging
IC Packaging and Testing Market
Semiconductor Packaging
3D IC and 2.5D IC Packaging Market
Semiconductor Packaging
Electronic Board Level Underfill and Encapsulation Material Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Testing Market
Semiconductor Packaging
NOR-Based Multi-Chip Packages Market
Semiconductor Packaging
Asia-Pacific Quad-Flat-No-Lead Packaging Market
Semiconductor Packaging
Ball Grid Array (BGA) Packaging Market
Semiconductor Packaging
2.5D and 3D Semiconductor Packaging Market
Semiconductor Packaging
Through-Silicon via (TSV) IC Packaging Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market
Semiconductor Packaging
Semiconductor Wafer Tape Market
Semiconductor Packaging
3D IC Packaging Market
Semiconductor Packaging
2.5D IC Packaging Market
Semiconductor Packaging
System in Package (SIP) Die Market