
 Antenna-In-Package Technology Market | 2026-2036
Antenna-In-Package Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Antenna-In-Package Technology Market Outlook
Multi-source procurement of advanced packaging services is expanding as fabless RF designers diversify away from captive assembly. Qualcomm leverages its modem-antenna co-design expertise to sustain leadership in 5G mmWave modules. Murata Manufacturing anchors Japanese supply through proprietary LTCC-based AiP architectures. ASE Technology competes aggressively on fan-out wafer-level packaging scale for Wi-Fi 6E and 7 chipsets.
Antenna-in-Package technology embeds radiating elements, feed networks, and electromagnetic shielding within semiconductor-grade laminate or wafer-level enclosures, typically operating from sub-6 GHz through 71 GHz for 5G NR and automotive radar. The primary purpose is to miniaturize RF front-ends while preserving gain, efficiency, and thermal performance in space-constrained devices. Passive antennas still occupy the largest volume share in Bluetooth and RFID tags, but active antenna segments with integrated beamforming ICs are capturing the fastest value growth in telecommunications infrastructure. Integrated antenna solutions command premium positioning where medical devices and industrial automation demand hermetic, biocompatible packaging with precise impedance control.
The FCC governs mmWave device certification and spectrum licensing in the United States, while ETSI harmonizes cross-border RF exposure limits across Europe; both frameworks directly shape AiP power-density specifications and test protocols. China's MIIT enforces domestic GB standards for 5G terminal radiation performance, creating a dual-compliance burden for multinational module suppliers. Stakeholders must monitor evolving national spectrum auctions and packaging material restrictions, as regulatory divergence between jurisdictions will determine which AiP architectures achieve scale economics.
Market Dynamics
Millimeter-wave spectrum commercialization is compressing development cycles for multi-band AiP architectures as automotive and telecommunications OEMs demand chip-scale RF integration. This structural pressure forces packaging houses to bridge electromagnetic simulation with semiconductor fabrication workflows.
Growth Catalysts
- Automotive radar mandates:NHTSA testing protocols for 77-81 GHz collision-avoidance systems compel Tier-1 suppliers to source compact AiP modules for bumper-integrated sensors.
- ETSI harmonization:Cross-border RF exposure limit alignment accelerates single-SKU certification for European 5G infrastructure deployments.
- Fan-out wafer-level packaging:Taiwan-based OSAT capacity expansion reduces unit costs for Wi-Fi 6E/7 chipsets targeting consumer electronics.
Market Restraints
- EMI shielding material costs:Silver-filled epoxy and sputtered copper prices fluctuate with precious metals markets, squeezing laminate-based AiP margins.
- Advanced substrate concentration:Ajinomoto Build-up Film supply remains captive to Japanese chemical conglomerates, creating single-source vulnerability.
- Thermal dissipation limits:Power amplifiers above 28 GHz generate heat densities that standard mold compounds cannot manage without expensive diamond-filled underfills.
Strategic Opportunities
- India PLI scheme:Domestic handset manufacturing incentives create captive demand for sub-6 GHz AiP modules in locally assembled smartphones.
- Satellite terminal integration:Low-earth-orbit user equipment requires Ka-band phased arrays that merge antenna and transceiver silicon in hermetic packages.
- Biocompatible packaging:Implantable medical devices seek hermetic LTCC enclosures with precise impedance control for wireless vital-sign monitoring.
Industry Challenges
- Multi-physics simulation talent:RF engineers capable of co-optimizing electromagnetic, thermal, and mechanical performance in single-package designs command premium compensation.
- mmWave test infrastructure:Over-the-air validation chambers for 71 GHz operation require capital outlays that strain mid-tier packaging houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antenna-In-Package Technology Market |
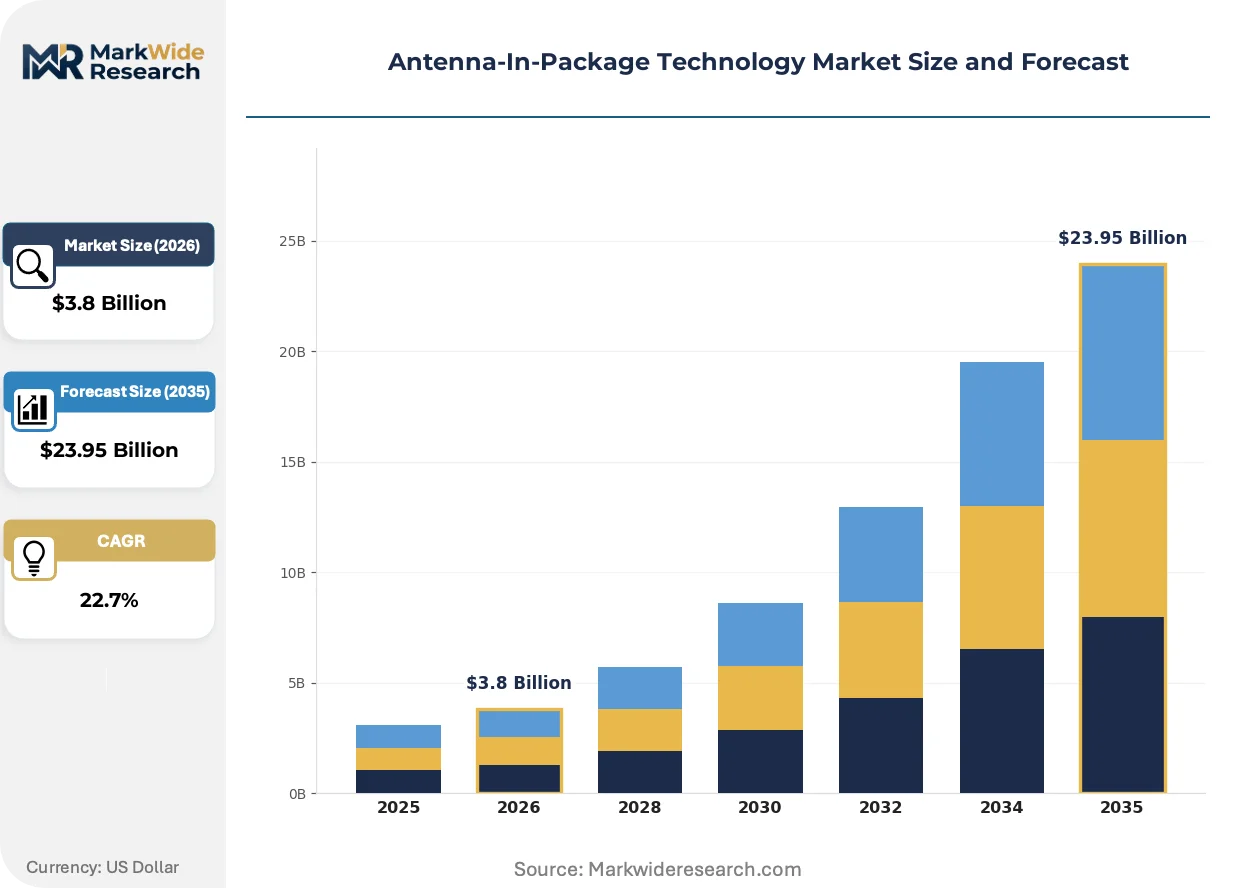
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.95 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Antennas, Active Antennas, Dual-Function Antennas, Integrated Antenna Solutions End User: Consumer Electronics, Telecommunications, Automotive, IoT Devices Technology: 5G, Wi-Fi, Bluetooth, RFID Application: Wireless Communication, Smart Home, Industrial Automation, Medical Devices |
| Companies Covered | Qualcomm, Intel, Broadcom, Texas Instruments, NXP Semiconductors, Murata Manufacturing, Amkor Technology, ASE Technology, Skyworks Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antenna-In-Package Technology Market Strategic Shifts
Antenna-in-package design workflows are converging with semiconductor front-end processes as electromagnetic co-simulation becomes standard. This integration is compressing prototype cycles and reshaping supplier qualification criteria.
Glass-core substrate technology is overtaking organic laminates for mmWave applications above 39 GHz. Automotive radar suppliers in Germany and Japan are qualifying 50-micron glass interposers for 77 GHz modules. This material shift is overtaking traditional low-loss dielectrics by enabling finer line widths and tighter via pitches without moisture absorption degradation.
China's MIIT GB standards for 5G terminal radiation performance are tightening test-protocol specificity for AiP modules entering the domestic market. Module suppliers must duplicate certification workflows to satisfy both MIIT and FCC/ETSI requirements. Smartphone OEMs are responding by pre-qualifying dual-compliant antenna designs during chipset co-development phases.
Direct procurement from packaging houses is displacing traditional distributor channels for high-volume RF module buyers. Tier-1 telecommunications equipment manufacturers in South Korea now negotiate wafer-start agreements directly with fan-out foundries. This channel compression is most visible in 5G small-cell deployments where buyers consolidate purchase authority to secure capacity allocation.
Antenna-In-Package Technology Market Segmentation
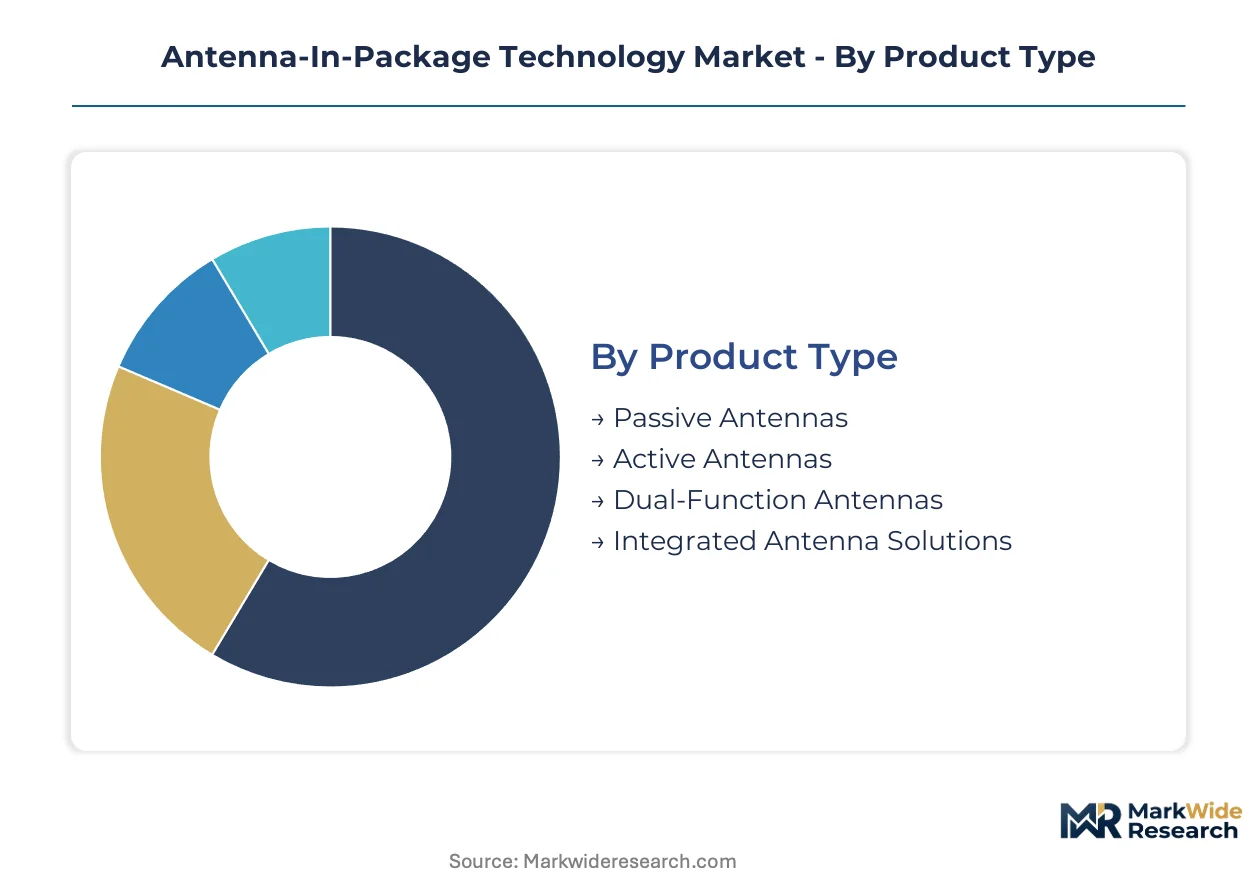
Antenna-in-package architectures fragment across four orthogonal dimensions that determine electromagnetic performance, thermal budgets, and regulatory compliance pathways. Each segmentation axis carries distinct margin profiles and qualification barriers that reshape supplier selection criteria for module buyers.
Product Type:
Passive antennas dominate unit volumes through cost-optimized laminate substrates, while active architectures with integrated beamforming ICs capture disproportionate value in telecommunications infrastructure.
- Passive Antennas:Radiating elements and feed networks fabricated on organic laminates or LTCC substrates without active semiconductor integration. Bluetooth and RFID tag manufacturers in Shenzhen and Dongguan source these for sub-dollar module targets where range requirements stay below 10 meters.
- Active Antennas:Beamforming ICs, power amplifiers, and phase shifters co-packaged with radiating elements in hermetic enclosures. 5G base station deployments in South Korea and Germany concentrate procurement here, driven by massive MIMO channel density requirements that passive architectures cannot satisfy.
- Dual-Function Antennas:Hybrid designs merging sub-6 GHz and mmWave bands in single packages. Automotive radar suppliers qualify these for 77-81 GHz collision-avoidance modules where bumper space constraints prohibit separate antennas.
- Integrated Antenna Solutions:Complete RF front-ends with transceiver silicon, filters, and antennas in single molded packages. Medical device OEMs specify these for implantable cardiac monitors requiring biocompatible hermetic seals and precise impedance control.
Today's leader: Passive Antennas. Tomorrow's challenger: Active Antennas.
End User:
Automotive applications command the steepest price premiums for thermal cycling reliability, while consumer electronics absorb the highest absolute volumes through smartphone refresh cycles.
- Consumer Electronics:Smartphones, tablets, and wearables drive sub-6 GHz AiP consumption through annual flagship release schedules. Apple and Samsung negotiate directly with fan-out foundries in Taiwan to secure capacity for mmWave modules.
- Telecommunications:Base stations, small cells, and repeaters require phased-array architectures with beam-steering precision. European infrastructure vendors under ETSI harmonization pressure favor single-SKU designs certifiable across member states.
- Automotive:Radar and telematics modules for ADAS and V2X connectivity. NHTSA testing protocols for 77 GHz collision-avoidance systems compel Tier-1 suppliers to source automotive-qualified AiP with -40°C to 150°C thermal envelopes.
- IoT Devices:Low-power wide-area network endpoints and industrial sensors. Cost pressure here pushes designers toward chip antennas and PCB-integrated solutions rather than discrete AiP modules.
Procurement concentrates in automotive for margin, telecommunications for technology validation, and consumer electronics for volume scale.
Technology:
5G mmWave implementations absorb the most advanced packaging investment, while Bluetooth and RFID sustain legacy laminate technologies with minimal process innovation.
- 5G:Sub-6 GHz and mmWave bands through 71 GHz demanding low-loss dielectrics and precision impedance matching. FCC Part 30 licensing and MIIT GB standards create dual-certification burdens for modules targeting both US and Chinese markets.
- Wi-Fi:6E and 7 protocols at 6 GHz and 7 GHz with 320 MHz channel bonding. Fan-out wafer-level packaging from Taiwan-based OSATs reduces unit costs for router and smartphone applications.
- Bluetooth:2.4 GHz ISM band with minimal performance differentiation. Passive chip antennas on standard FR-4 substrates satisfy most use cases without AiP premium pricing.
- RFID:UHF and NFC frequencies for inventory tracking and contactless payment. Tag inlay manufacturers prioritize lowest-cost laminate solutions with printed silver antennas.
5G claims the steepest expansion trajectory as spectrum auctions accelerate mmWave infrastructure deployment.
Application:
Wireless communication infrastructure commands the most complex multi-band requirements, while medical devices impose the strictest hermeticity and biocompatibility standards.
- Wireless Communication:Cellular base stations, satellite terminals, and backhaul links. Ka-band phased arrays for low-earth-orbit user equipment merge antenna and transceiver silicon in packages qualified for space-grade thermal cycling.
- Smart Home:Mesh Wi-Fi systems, voice assistants, and security cameras. Amazon and Google negotiate volume commitments for Wi-Fi 6E modules with integrated antennas to reduce board space in compact enclosures.
- Industrial Automation:Wireless sensor networks and AGV navigation systems. Harsh factory environments demand extended temperature range specifications and EMI shielding that standard consumer-grade AiP cannot provide.
- Medical Devices:Implantable monitors, wireless endoscopy capsules, and wearable diagnostics. FDA Class III and EMA MDR compliance pathways require hermetic LTCC enclosures with documented biocompatibility per ISO 10993.
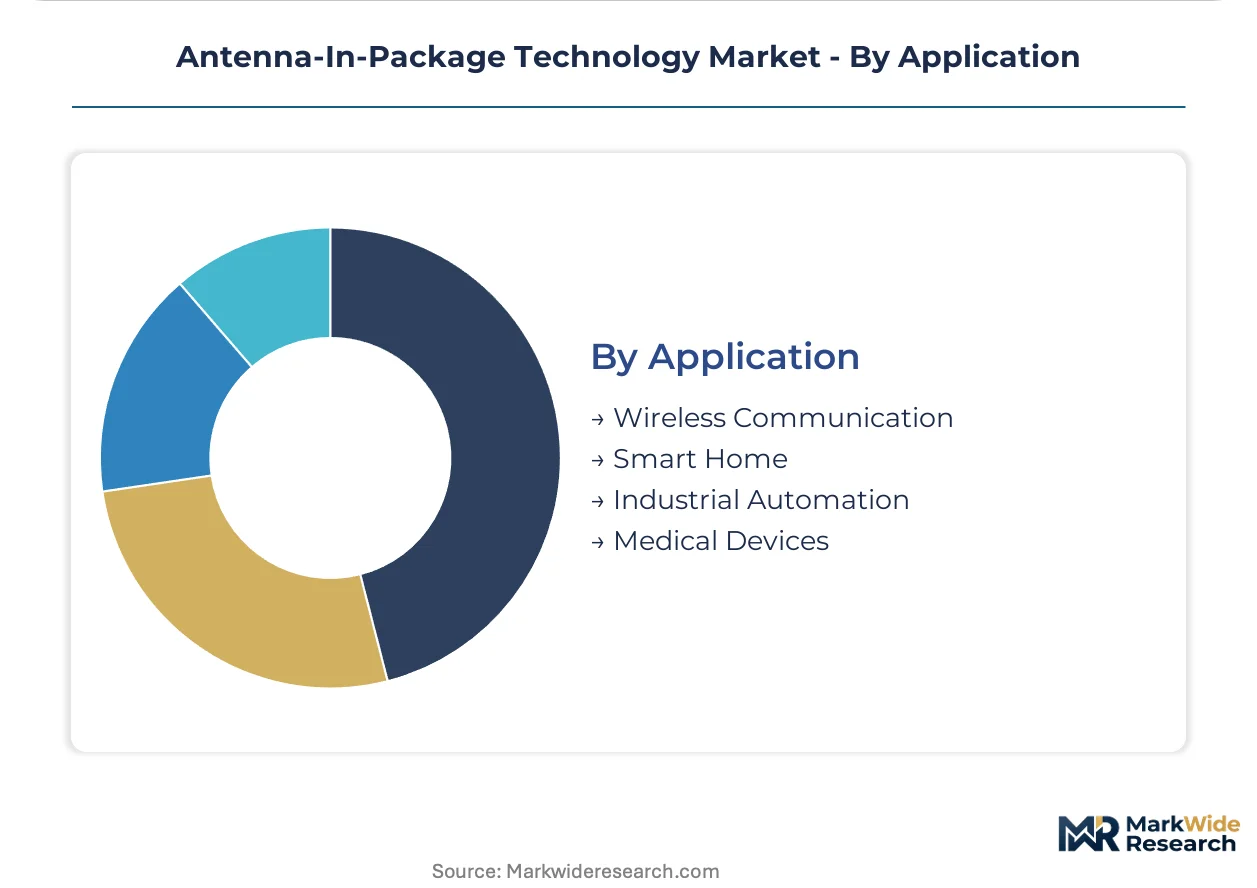
Medical devices sustain the highest pricing tiers through regulatory barriers, while wireless communication delivers the largest addressable revenue pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's Hsinchu Science Park anchors advanced packaging capacity for millimeter-wave AiP modules. Foundry clusters in Tainan and Taichung process fan-out wafer-level substrates for 5G and Wi-Fi 7 chipsets. ASE Technology and other OSATs operate multi-fab networks serving fabless RF designers across three continents.
United States
Automotive radar mandates from NHTSA and FCC Part 30 mmWave licensing drive collision-avoidance module procurement. Tier-1 suppliers in Michigan and California qualify 77-81 GHz AiP for bumper-integrated sensors. Qualcomm anchors San Diego's modem-antenna co-design ecosystem for 5G infrastructure.
China
MIIT GB standards for 5G terminal radiation performance create dual-certification burdens for module suppliers. Domestic handset manufacturing incentives under the national technology self-sufficiency program concentrate demand in Shenzhen and Dongguan. OSATs in Suzhou and Wuxi expand laminate-based AiP capacity for sub-6 GHz applications.
Germany
ETSI harmonization of cross-border RF exposure limits accelerates single-SKU certification for European 5G deployments. Automotive OEMs in Stuttgart and Munich specify 77 GHz radar modules with -40°C to 150°C thermal envelopes. Glass-core substrate qualification for 39 GHz+ applications centers on Bavarian packaging research consortia.
South Korea
Telecommunications equipment manufacturers negotiate wafer-start agreements directly with Taiwan-based fan-out foundries. Seoul-based base station vendors under ETSI pressure favor designs certifiable across EU member states. Samsung's Suwon operations integrate mmWave AiP into flagship smartphone refresh cycles.
Japan
METI industrial technology roadmaps prioritize hermetic LTCC enclosures for automotive and medical applications. Murata Manufacturing's proprietary AiP architectures anchor domestic supply through Kyoto and Nagaoka facilities. Ajinomoto Build-up Film supply concentration creates single-source vulnerability for advanced substrate procurement.
Antenna-In-Package Technology Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue satellite terminal and biocompatible medical packaging niches. The vendor base stratifies across three tiers: integrated device manufacturers with captive packaging, specialized OSATs with fan-out scale, and fabless RF designers outsourcing assembly. Two dominant competitive moves define current positioning: direct procurement agreements between OEMs and packaging houses bypassing traditional distributors, and backward integration by modem suppliers into antenna co-design workflows.
Among US-based semiconductor designers, Qualcomm and Intel exemplify the integrated-architecture archetype, while Broadcom occupies a position within the connectivity-focused tier. Taiwan's ASE Technology represents the scale-driven OSAT model for advanced fan-out wafer-level packaging. These three anchors illustrate how competitive positioning fragments across geographic and capability dimensions rather than consolidating around unified technology platforms.
| Leading Market Players |
|---|
| Qualcomm |
| Intel |
| Broadcom |
| Texas Instruments |
| NXP Semiconductors |
| Murata Manufacturing |
| Amkor Technology |
| ASE Technology |
| Skyworks Solutions |
| Others |
Value Chain & Pricing Dynamics
Family-owned Japanese chemical conglomerates controlling advanced substrate supply exercise outsized pricing discipline through captive Ajinomoto Build-up Film distribution. Their concentrated ownership structure limits spot-market liquidity and forces packaging houses into long-term offtake commitments that insulate raw material costs from short-term volatility.
Pricing Analysis
Silver-filled epoxy and sputtered copper input costs pass through directly to laminate-based AiP module pricing with minimal lag. Three-tier pricing structure across automotive-qualified, telecommunications-grade, and consumer electronics tiers separates thermal cycling certification levels. Cost compression in consumer Wi-Fi modules intensifies because Taiwan OSATs compete aggressively on fan-out wafer-level packaging scale. Smartphone OEMs exhibit the sharpest price sensitivity, while medical device manufacturers absorb premiums for hermetic LTCC biocompatibility.
Supply Chain Analysis
Reverse-logistics flows for failed automotive radar modules create refurbishment channels that recover gold bonding wire and reclaim LTCC substrates for non-critical applications. Manufacturing concentrates in Taiwan, South Korea, and Japan where foundry clusters process fan-out wafers and laminate substrates. Supply draws from silver-filled epoxies, low-loss dielectrics, and Ajinomoto Build-up Film. Single-source vulnerability in advanced substrate procurement poses structural risk. Distribution runs through direct procurement agreements between Tier-1 OEMs and packaging houses, bypassing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Antenna-in-Package Technology Market reads as a late-cycle quality story where automotive radar mandates and medical device hermeticity requirements shift procurement toward premium thermal-cycling specifications. Buyers now prioritize reliability certification over unit cost minimization.
For Market Incumbents: Cement leadership through backward integration into antenna-modem co-design workflows and captive qualification of dual-compliant architectures satisfying both FCC Part 30 and MIIT GB standards. Threats from fabless RF designers with direct foundry access require defensive capacity reservations at Taiwan-based fan-out facilities. Prioritize R&D investment in glass-core substrate processes for 77 GHz automotive modules.
For New Entrants and Emerging Players: Capture white-space in satellite terminal Ka-band phased arrays and biocompatible LTCC enclosures for implantable cardiac monitors. The most penetrable segment sits in Indian domestic handset assembly where PLI scheme incentives concentrate sub-6 GHz module demand. Pursue qualification partnerships with European telecommunications equipment vendors seeking ETSI-harmonized single-SKU designs.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized OSATs lacking fan-out wafer-level scale but possessing automotive radar qualification heritage. Long-term viability hinges on 5G mmWave infrastructure deployment cadence and low-earth-orbit satellite constellation buildouts. Monitor FCC spectrum auction schedules and MIIT GB standard revision timelines as inflection indicators for certification workflow duplication costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Antenna-Modem Co-Design Integration | Qualcomm's San Diego ecosystem demonstrates competitive moat through RF front-end consolidation. |
| Fan-Out Wafer-Level Capacity Expansion | ASE Technology's multi-fab network secures allocation for Wi-Fi 7 smartphone refresh cycles. |
| Dual-Compliance Certification Investment | Murata Manufacturing's LTCC architectures satisfy both FCC and MIIT radiation performance protocols. |
| Glass-Core Substrate Qualification | Bavarian research consortia validate 50-micron interposers for 77 GHz automotive radar. |
| Direct Procurement Channel Development | South Korean base station vendors negotiate wafer-start agreements bypassing distributors. |
Study Parameters
Direct dialogue with packaging house executives, RF front-end designers at fabless semiconductor firms, Tier-1 automotive radar procurement managers, and telecommunications infrastructure equipment vendors grounded qualitative assessment. Secondary validation drew from FCC equipment authorization databases, ETSI harmonized standards publications, MIIT GB certification filings, and Taiwan Stock Exchange OSAT capacity disclosures. Bottom-up module shipment estimates triangulated against top-down RF front-end value chain analysis.
Bottom-up modeling aggregated unit economics across passive antenna, active beamforming, dual-function, and integrated solution architectures. Segmentation dimensions included product type, end-user industry, operating frequency band, and substrate material technology. CAGRs derived from curve-fitting historical packaging capacity expansion against spectrum auction timelines and automotive ADAS mandate schedules. Forecast inputs incorporated thermal dissipation limits for power amplifiers above 28 GHz and diamond-filled underfill adoption curves.
Underlying measurement precision varies by segment; automotive radar and medical device categories carry tighter precision than consumer Bluetooth modules due to mandatory certification documentation. Forecasts reflect assumptions regarding millimeter-wave spectrum commercialization velocity and packaging material regulatory restrictions. Practitioners should monitor NHTSA testing protocol revisions and national spectrum auction outcomes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
Semiconductor Chip Handler Market
Semiconductor Packaging
Flip-Chip COB Technology Market
Semiconductor Packaging
ESD Stackable Boxes Market
Semiconductor Packaging
Global MEMS Packaging Market
Semiconductor Packaging
Embedded Die Packaging Technology Market
Semiconductor Packaging
Global Semiconductor Packaging and Assembly Equipment Market
Semiconductor Packaging
3D Semiconductor Packaging Market
Semiconductor Packaging
NOR-Based Multi-Chip Packages Market
Semiconductor Packaging
Global Semiconductor Seals Market
Semiconductor Packaging
Global High-End Semiconductor Packaging Market
Semiconductor Packaging
System in Package (Sip) Technology Market
Semiconductor Packaging
2.5D IC Packaging Market
Semiconductor Packaging
Asia-Pacific Quad-Flat-No-Lead Packaging Market