
 Bonding Wire Packaging Market | 2026-2036
Bonding Wire Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Bonding Wire Packaging Market Outlook
Aftermarket wire reclamation and precious metal recovery is reconfiguring margin distribution across the bonding wire value chain. Heraeus leverages its vertically integrated precious metals refining to sustain captive supply security for high-purity gold bonding wire. Tanaka anchors its position through specialized alloy development for fine-pitch semiconductor applications. MK Electron competes aggressively on copper wire purity grades for memory and power device packaging.
Bonding wire packaging encompasses the engineered containment and transport systems for ultrafine metallic wires used in electrical interconnection of semiconductor dies to package substrates, typically involving spools or reels wound to precise tension tolerances to prevent wire deformation during automated bonding operations. The primary commercial purpose centers on preserving wire surface integrity and dimensional consistency from manufacture through high-speed wire bonding equipment deployment. Copper wire continues displacing gold in cost-optimized consumer electronics and memory packaging, while gold wire maintains structural dominance in high-reliability automotive and aerospace applications where corrosion resistance and bond stability under thermal cycling remain critical. Reel-based packaging formats lead volume throughput for mass-production OSAT environments, though tape-and-foil configurations are gaining traction for specialized fine-pitch and stacked-die configurations requiring reduced wire loop profiles.
REACH compliance across Europe mandates full material disclosure for precious metal content and restricts certain alloy additives, compelling suppliers to requalify wire compositions and packaging substrates. The EPA oversees hazardous material transport classifications for spooled wire shipments within the United States, while China's GB standards govern dimensional tolerances and surface cleanliness for imported bonding wire used in domestic semiconductor packaging. Japan's METI coordinates national semiconductor packaging initiatives that influence bonding wire procurement specifications for domestic IDM and OSAT customers. Stakeholders must monitor evolving dual-use export control classifications for advanced packaging materials and assess qualification timelines for copper wire migration in automotive-grade reliability programs.
Market Dynamics
Copper wire substitution for gold is compressing material costs across consumer electronics packaging while simultaneously fragmenting supplier qualification pathways. This material transition, combined with REACH-mandated alloy requalification in Europe and China's tightening GB standards for imported wire, is forcing packaging houses to maintain dual-material inventory strategies.
Growth Catalysts
- Automotive reliability programs:High-temperature power modules and ADAS sensor packages require gold wire for thermal cycling stability. Tier-1 automotive suppliers are expanding wire bonding capacity for electrification platforms.
- REACH material disclosure mandates:European ECHA enforcement drives premium pricing for fully documented precious metal supply chains. Suppliers with captive refining capabilities capture margin from compliance-heavy buyers.
- Memory packaging expansion:DDR5 and HBM3 production ramps in South Korea and Taiwan concentrate demand for ultra-fine copper wire. OSATs are qualifying new purity grades for high-density stacked die configurations.
Market Restraints
- Gold price volatility:Precious metal cost swings compress margins for bonding wire distributors holding inventory. Hedging costs add 3-5% to working capital requirements for non-integrated suppliers.
- China supply concentration:Over 60% of copper wire drawing capacity sits in Jiangsu and Guangdong provinces. Regional lockdowns or power rationing disrupt just-in-time delivery to OSAT facilities.
- Fine-pitch physical limits:Sub-15-micron wire diameter introduces necking failures and loop height control challenges. Memory manufacturers face yield loss migrating to next-generation node geometries.
Strategic Opportunities
- India OSAT buildout:PLI scheme subsidies for semiconductor packaging attract bonding wire suppliers to establish local spooling operations. Gujarat and Karnataka clusters offer tariff advantages for imported wire rod.
- Tape-and-foil packaging formats:Stacked-die memory and fan-out wafer-level packages require reduced loop profiles. Equipment vendors are qualifying new feeding mechanisms for foil-based wire delivery.
- Copper wire automotive qualification:Power device packaging for EV inverters and charging modules is migrating from gold to palladium-coated copper. AEC-Q100 reliability testing creates first-mover advantage for qualified suppliers.
Industry Challenges
- Alloy metallurgist scarcity:Fine-pitch wire development requires expertise in dopant optimization for electrical conductivity and mechanical strength. Universities in Japan and Germany produce limited graduates with relevant semiconductor materials training.
- Dual-use export control alignment:Advanced packaging wire with specialized coating chemistries faces evolving BIS and EU dual-use classifications. Suppliers must maintain parallel documentation systems for defense-sensitive and commercial customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bonding Wire Packaging Market |
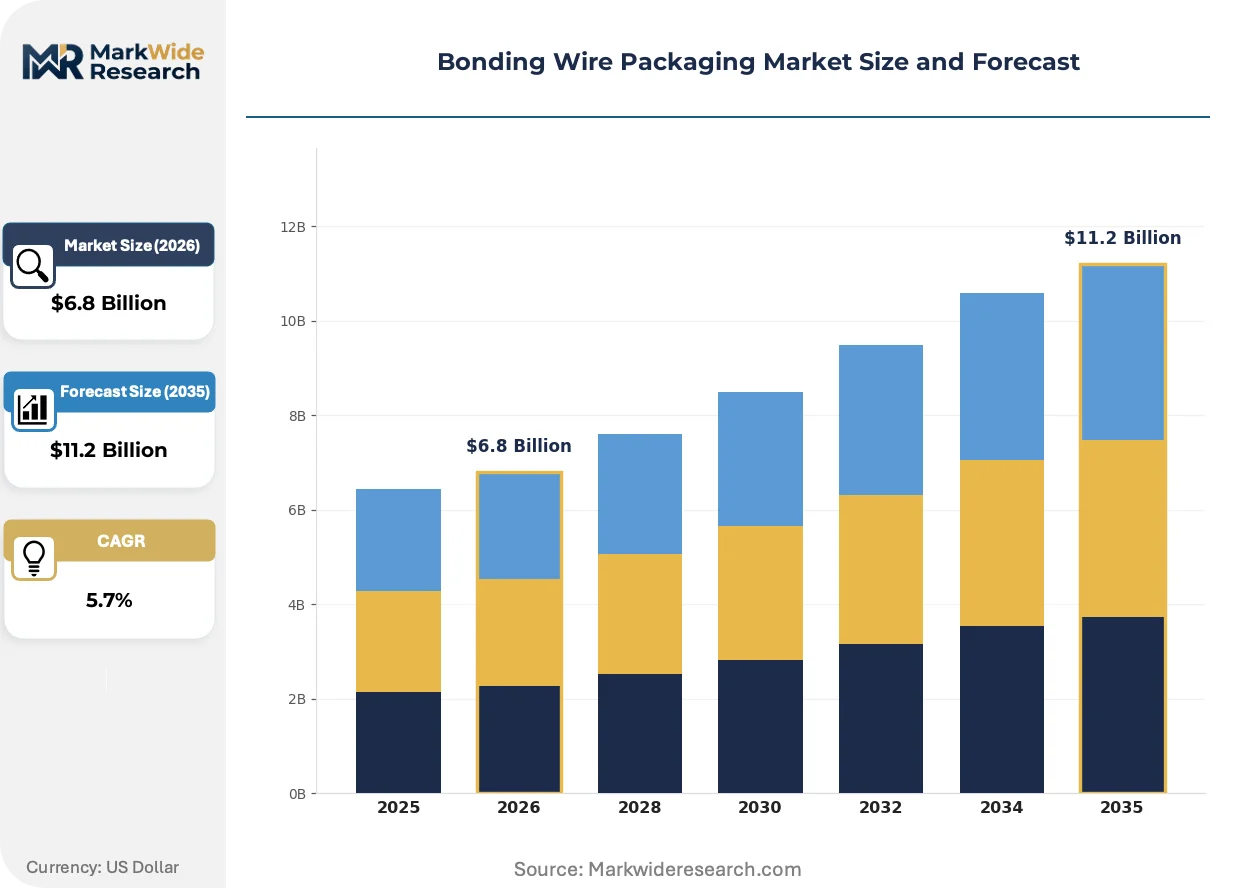
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gold Wire, Copper Wire, Aluminum Wire, Silver Wire Packaging Type: Reels, Tapes, Foils, Spools Application: Semiconductors, Aerospace, Automotive, Consumer Electronics End User: Manufacturers, Distributors, OEMs, Research Institutions |
| Companies Covered | Heraeus, Tanaka, MK Electron, Sumitomo Metal Mining, California Fine Wire, Ametek, Tatsuta Electric Wire & Cable, Nippon Micrometal, Custom Chip Connections, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bonding Wire Packaging Market Strategic Shifts
Automated bonding equipment intelligence and wire surface engineering are converging to enable finer pitch geometries while reducing process variation. These developments compress the traditional trade-off between material cost and reliability performance.
Palladium-coated copper wire is collapsing the cost-reliability gap for automotive and industrial applications. Power module manufacturers in Germany and Japan are adopting this hybrid construction for 175°C operating environments. The technology enables gold substitution in segments previously reserved for precious metal bonding due to corrosion resistance requirements.
REACH substance restrictions on certain alloy additives are compelling reformulation of high-purity gold bonding wire for European automotive customers. ECHA enforcement timelines pressure suppliers to complete requalification by 2026. Packaging houses in Slovakia and Romania are pre-qualifying alternative dopant compositions to avoid supply disruption.
OSAT procurement teams are consolidating supplier relationships around vertically integrated wire manufacturers with captive refining and spooling capabilities. Long-term supply agreements with fixed precious metal pass-through mechanisms displace spot-market purchasing for high-volume consumer electronics programs. This concentration is most visible in Taiwan, where three packaging houses control over half of regional wire consumption.
Bonding Wire Packaging Market Segmentation
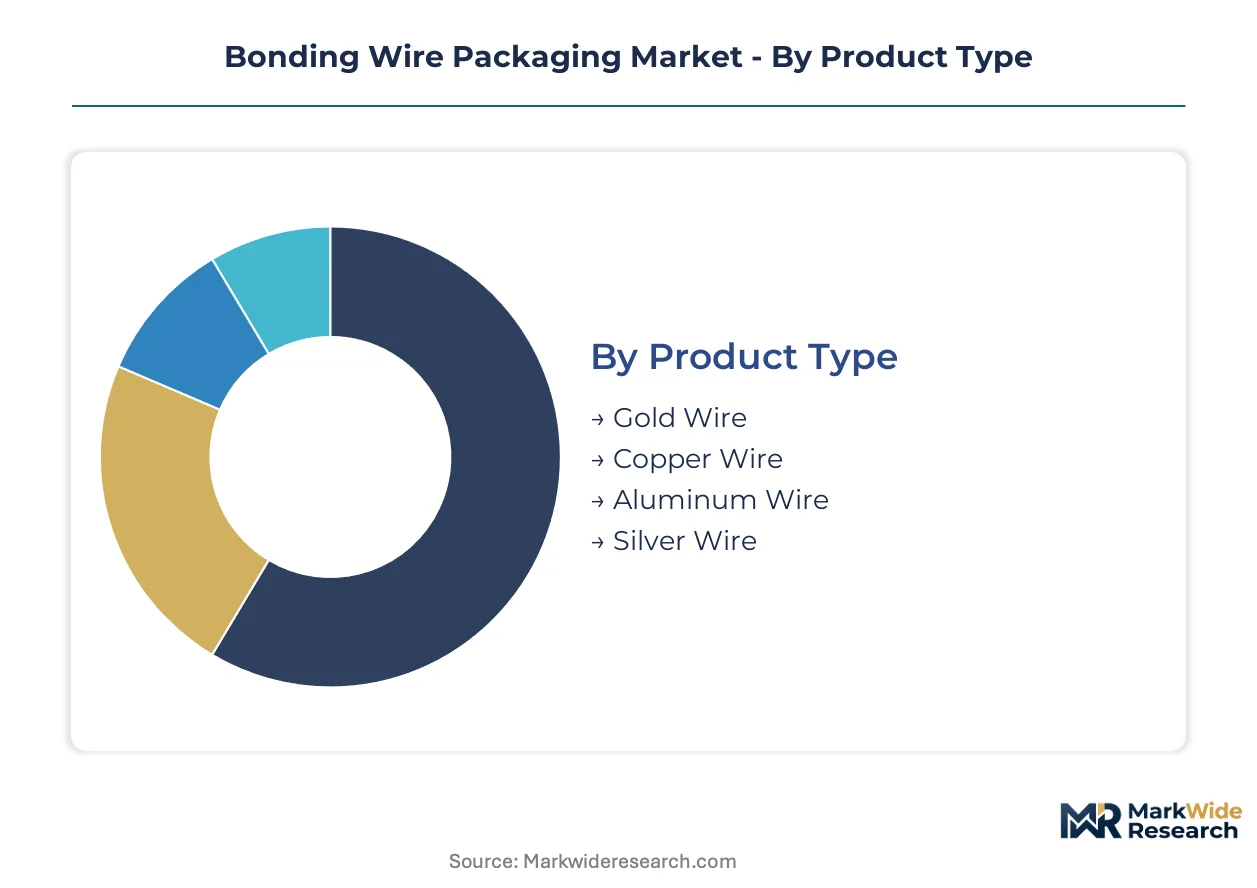
Segmentation in bonding wire packaging reveals how material composition, containment format, and end-use reliability requirements create distinct commercial pathways. Each dimension shapes procurement specifications, inventory strategies, and supplier qualification timelines differently.
Product Type:
After-sales service intensity varies sharply by wire chemistry — gold wire demands precious metal recovery programs and bond failure analysis support, while copper wire prioritizes purity certification and diameter consistency documentation.
- Gold Wire:High-purity precious metal wire maintains structural dominance in automotive and aerospace applications where thermal cycling stability and corrosion resistance are non-negotiable. Demand concentrates in German power module packaging and Japanese automotive sensor assemblies, driven by AEC-Q100 reliability mandates that resist material substitution.
- Copper Wire:Oxygen-free high-conductivity copper wire dominates memory packaging and cost-optimized consumer electronics, with palladium-coated variants penetrating automotive power devices previously reserved for gold. South Korean DDR5 and HBM3 production ramps in Suwon and Icheon concentrate demand for ultra-fine diameters below 20 microns.
- Aluminum Wire:Heavy-gauge aluminum wire serves power semiconductor and discrete device packaging where electrical conductivity requirements are moderate and cost sensitivity is acute.
- Silver Wire:Specialized silver alloy wire addresses niche LED and optoelectronic packaging applications requiring high thermal conductivity and reflectivity.
Gold wire holds the largest share; momentum sits with copper wire.
Packaging Type:
Containment format selection hinges on automated feeding compatibility and loop profile constraints — reel-based systems dominate high-volume OSAT throughput while tape-and-foil configurations command premium positioning for advanced packaging.
- Reels:Precision-wound plastic or metal reels constitute the workhorse format for mass-production wire bonding equipment, engineered to precise tension tolerances that prevent wire deformation during high-speed unwinding. Taiwan OSAT facilities in Taichung and Tainan consume the majority of regional reel throughput, with procurement consolidating around suppliers offering captive spooling and precious metal pass-through mechanisms.
- Tapes:Adhesive tape carriers enable reduced loop profiles for stacked-die memory and fan-out wafer-level packages where traditional reel feeding creates height interference. Equipment vendors in Yokohama and Seoul are qualifying new feeding mechanisms for tape-based wire delivery in HBM3 configurations.
- Foils:Metal foil substrates provide the flattest wire presentation for ultra-fine-pitch applications requiring sub-30-micron bond pad pitches.
- Spools:Cylindrical spools persist in laboratory and low-volume production environments where equipment compatibility with legacy feeding systems matters.
Reels command the highest volume; tape formats are climbing the fastest.
Application:
Reliability tier determines material specification rigidity — automotive and aerospace applications enforce fixed precious metal requirements while consumer electronics permit aggressive cost-driven substitution.
- Semiconductors:Logic and memory device packaging represents the core demand pool, spanning from mature node microcontrollers to advanced DDR5 and HBM3 stacks. China's Jiangsu and Guangdong provinces host over sixty percent of copper wire drawing capacity feeding this segment.
- Aerospace:Satellite and avionics systems mandate gold wire for radiation tolerance and bond integrity across extreme temperature swings. European Space Agency qualification protocols in Noordwijk and Toulouse enforce material traceability requirements that favor vertically integrated suppliers.
- Automotive:Power modules for EV inverters and ADAS sensor packages are migrating from gold to palladium-coated copper, with AEC-Q100 testing creating qualification bottlenecks for new material entrants.
- Consumer Electronics:Smartphone and wearable device packaging drives the most aggressive copper substitution, with OSATs maintaining minimal inventory buffers to capture spot metal price advantages.
Semiconductors hold the largest share; automotive is expanding most quickly.
End User:
Procurement sophistication divides end users — captive IDMs and large OSATs negotiate long-term supply agreements while distributors and research institutions operate on spot purchasing and small-lot fulfillment.
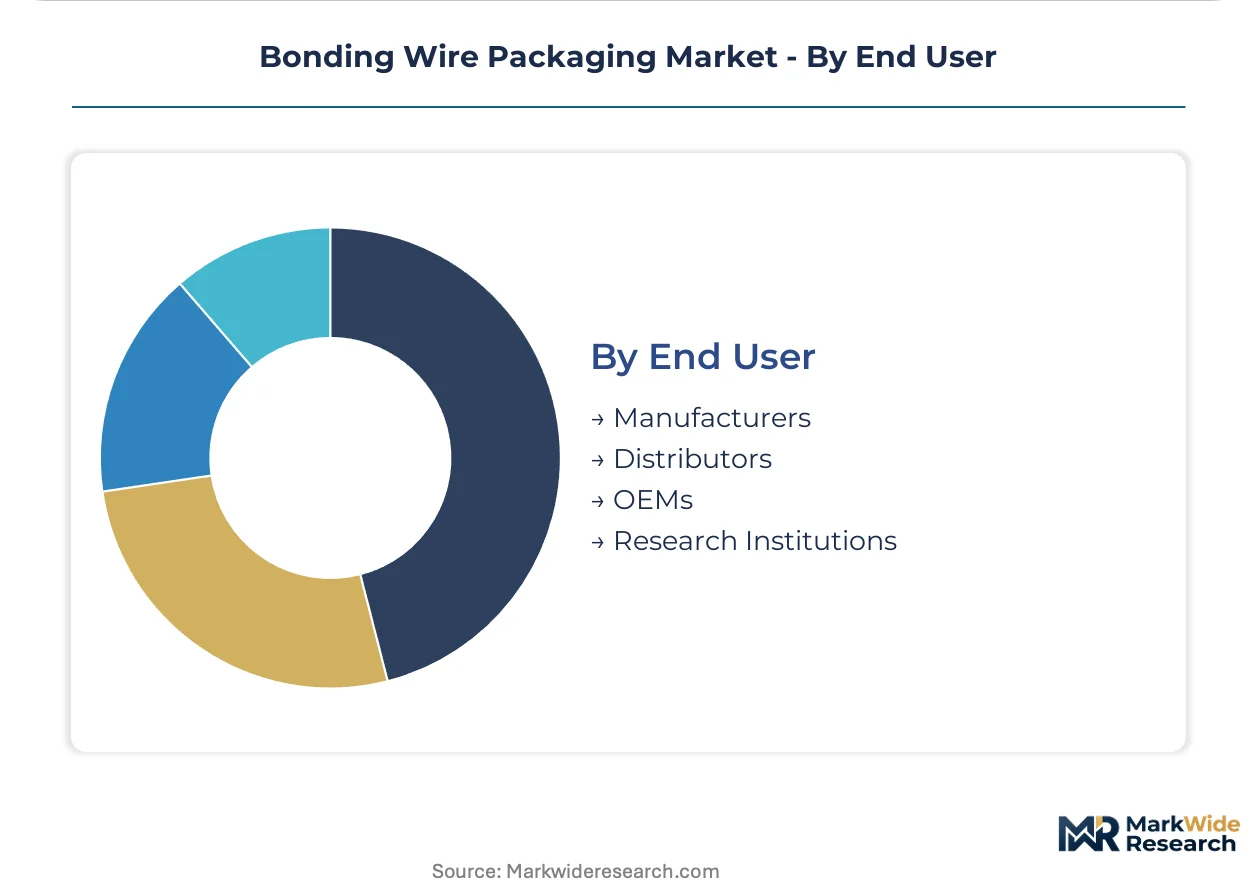
- Manufacturers:Captive semiconductor packaging houses and IDMs with in-house wire bonding operations constitute the price-setting demand tier, leveraging volume concentration to secure fixed precious metal pass-through mechanisms. Three Taiwan-based packaging houses control over half of regional wire consumption.
- Distributors:Regional stocking distributors serve mid-tier OSATs and specialty device manufacturers, absorbing gold price volatility through hedging programs that add working capital overhead.
- OEMs:Automotive and industrial equipment manufacturers with internal electronics assembly capabilities source bonding wire for module repair and limited captive production.
- Research Institutions:Universities and national laboratories purchase small-diameter specialty wires for advanced packaging research, with procurement cycles tied to grant funding rather than production schedules.
Manufacturers hold the largest share; momentum sits with distributors as OSAT consolidation continues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSAT procurement teams in Taiwan and South Korea exhibit minimal price elasticity for high-reliability gold wire, while Chinese packaging houses aggressively optimize for copper wire cost advantages. This demand bifurcation shapes regional supplier strategies and inventory positioning.
China
Jiangsu and Guangdong provinces concentrate over sixty percent of copper wire drawing capacity feeding memory and consumer electronics packaging. GB standards for dimensional tolerances and surface cleanliness tighten qualification requirements for imported bonding wire. Suzhou and Shenzhen clusters host captive spooling operations serving domestic OSAT expansion.
South Korea
DDR5 and HBM3 production ramps in Suwon and Icheon drive concentrated demand for ultra-fine copper wire below 20 microns. The national semiconductor initiative coordinates procurement specifications for domestic packaging houses. Samsung and SK Hynix captive operations in Gyeonggi Province anchor regional consumption patterns.
Taiwan
Three packaging houses in Taichung and Tainan control over half of regional wire consumption through long-term supply agreements. METI-influenced procurement standards from Japanese parent companies elevate quality specifications for automotive-grade wire. The island's OSAT consolidation accelerates supplier relationship concentration.
United States
EPA hazardous material transport classifications govern spooled wire shipments to domestic packaging facilities. California and Arizona host aerospace wire bonding operations for satellite and defense applications requiring gold wire traceability. Automotive power module packaging in Michigan and Ohio migrates toward palladium-coated copper for EV platforms.
Germany
REACH substance restrictions compel reformulation of high-purity gold bonding wire for European automotive customers. Power module manufacturers in Bavaria and Baden-Württemberg adopt palladium-coated copper for 175°C operating environments. ECHA enforcement timelines pressure suppliers to complete requalification by 2026.
Bonding Wire Packaging Market Competitive Environment
Vertically integrated precious metal refiners and specialized wire metallurgists split the market into distinct capability tiers. Supplier concentration is pronounced in East Asia, where captive refining and spooling operations create defensive moats. Three strategic archetypes dominate: integrated precious metal houses with backward refining control, specialized alloy developers for fine-pitch applications, and copper purity specialists competing on memory packaging specifications. Competitive moves center on dual-material inventory partnerships with OSATs and palladium-coated copper qualification for automotive reliability programs.
Among German and Japanese precious metal houses, Heraeus and Tanaka occupy positions reflecting deep metallurgical heritage and captive supply chain structures. MK Electron anchors the Korean competitive vector with scale-oriented positioning in copper wire segments. These three exemplify how regional industrial specialization maps onto distinct strategic archetypes without overlapping capability claims.
| Leading Market Players |
|---|
| Heraeus |
| Tanaka |
| MK Electron |
| Sumitomo Metal Mining |
| California Fine Wire |
| Ametek |
| Tatsuta Electric Wire & Cable |
| Nippon Micrometal |
| Custom Chip Connections |
| Others |
Value Chain & Pricing Dynamics
Jiangsu and Guangdong provinces concentrate over sixty percent of copper wire drawing capacity, anchoring margin capture at the raw material refining tier while downstream OSATs compete for fixed-price pass-through mechanisms. Precious metal volatility and REACH-mandated alloy requalification are compressing distributor margins and accelerating consolidation around vertically integrated suppliers with captive spooling operations.
Pricing Analysis
After-sales precious metal recovery programs and bond failure analysis support drive lifetime value for gold wire tiers, while copper wire emphasizes purity certification and diameter consistency documentation. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 automotive grades from consumer electronics specifications and laboratory small-lot fulfillment. Cost compression in copper wire segments is intensifying because memory manufacturers are qualifying ultra-fine diameters below 20 microns. Consumer electronics OSATs exhibit highest price sensitivity through minimal inventory buffers and spot metal purchasing, while aerospace satellite assemblers show lowest sensitivity due to ESA-mandated traceability requirements.
Supply Chain Analysis
Dual-use export control classifications for advanced packaging materials with specialized coating chemistries limit technology flows between defense-sensitive and commercial customers. Supply concentration rests in China, South Korea, and Taiwan for wire drawing and spooling capacity, with Germany and Japan hosting specialized alloy development. Raw material dependencies draw from high-purity gold bullion, oxygen-free copper rod, and palladium plating chemistries. Single-source vulnerability runs through Jiangsu province power rationing risks and regional lockdown disruptions to just-in-time OSAT delivery. Distribution runs through long-term supply agreements with fixed precious metal pass-through mechanisms for high-volume manufacturers, supplemented by regional stocking distributors absorbing hedging costs for mid-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as three Taiwan-based packaging houses control over half of regional wire consumption, forcing suppliers into captive spooling partnerships and fixed-price renegotiation cycles. OSAT consolidation is fragmenting distributor relevance and elevating vertically integrated refiners to price-setting positions.
For Market Incumbents: Harden palladium-coated copper qualification timelines for automotive power modules to preempt gold substitution threats in 175°C operating environments. Deepen backward integration into precious metal refining to capture REACH compliance premiums from European automotive customers. Expand captive spooling capacity in Gujarat and Karnataka clusters to defend against India PLI scheme entrants seeking tariff advantages for imported wire rod. For New Entrants and Emerging Players: India OSAT buildout under PLI scheme subsidies represents the most penetrable geographic white space, with local spooling operations offering tariff advantages for imported wire rod. Tape-and-foil packaging formats for HBM3 stacked-die memory present a technology entry angle where equipment vendors in Yokohama and Seoul are actively qualifying new feeding mechanisms. A qualification-first go-to-market approach targeting AEC-Q100 automotive reliability programs builds defensible positioning before scaling into consumer electronics volume. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated precious metal houses with captive refining and established OSAT long-term agreements, as these archetypes capture margin from compliance-heavy buyers and metal price volatility. The five-to-ten year viability window favors suppliers with dual-material inventory partnerships spanning gold and copper wire portfolios. The signal to watch is palladium-coated copper penetration rates in German and Japanese automotive power module qualifications, as this indicates whether cost-reliability gap closure accelerates gold displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Palladium-Coated Copper Qualification | AEC-Q100 testing in German power module packaging collapses the cost-reliability gap for automotive wire bonding. |
| Backward Integration into Precious Metal Refining | Heraeus-style captive supply security sustains margin capture from REACH-mandated alloy requalification pressures. |
| India Local Spooling Operations | Gujarat and Karnataka clusters under PLI scheme subsidies reduce tariff exposure for copper wire rod imports. |
| Tape-and-Foil Feeding Mechanism Development | Yokohama and Seoul equipment vendor partnerships enable reduced loop profiles for HBM3 memory configurations. |
| Dual-Material Inventory Partnerships | OSAT consolidation in Taiwan and South Korea demands suppliers with parallel gold and copper wire qualification pathways. |
Study Parameters
A spread of perspectives from wire bonding equipment engineers, OSAT procurement directors, precious metal refining specialists, and automotive power module packaging managers converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation from SEC filings of semiconductor packaging houses, ECHA substance restriction databases, and Japan METI semiconductor initiative documentation. Bottom-up triangulation across wire diameter specifications, purity grade demand, and packaging format adoption patterns was cross-checked against top-down precious metal consumption estimates and OSAT capacity expansion announcements.
Demand-supply balance framing anchored the analytical approach across the analysis window, with segmentation modeled across material composition tiers, containment format types, application reliability requirements, and end-user procurement sophistication levels. CAGRs were derived from wire bonding equipment deployment rates, memory packaging node transitions, and automotive electrification platform ramp schedules. Copper substitution velocity in consumer electronics and palladium-coated copper qualification timelines for automotive power modules served as industry-specific forecast inputs.
Practitioners should monitor dual-use export control reclassifications, ECHA enforcement timelines for alloy reformulation, and Jiangsu province power rationing patterns for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Semiconductor Packaging Material Market
Semiconductor Packaging
Epoxy Potting Market
Semiconductor Packaging
Wafer Level Packaging (WPL) Market
Semiconductor Packaging
Semiconductor Chip Handler Market
Semiconductor Packaging
Semiconductor Wafer Tape Market
Semiconductor Packaging
ESD Stackable Boxes Market
Semiconductor Packaging
3D TSV Packages Market
Semiconductor Packaging
3D IC Packaging Market
Semiconductor Packaging
Embedded Die Packaging Technology Market
Semiconductor Packaging
Through Silicon via (TSV) Packaging Market
Semiconductor Packaging
Wafer Carrier Boxes Market
Semiconductor Packaging
Global Semiconductor Packaging and Assembly Equipment Market
Semiconductor Packaging
Memory Packaging Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
Antenna-In-Package Technology Market
Semiconductor Packaging
2.5D IC Packaging Market