
 Barometer Market | 2026-2036
Barometer Market Size, Share, and Industry Trends Forecast 2026-2036
Barometer Market Analysis
Specialized instrumentation distribution is narrowing as direct OEM relationships replace traditional wholesale networks. Honeywell International Inc. leverages its aerospace certification depth to sustain long-term contracts with defense weather services. Vaisala Oyj anchors Nordic meteorological infrastructure through national agency partnerships. BOSCH Sensortec GmbH competes on MEMS miniaturization for consumer drone altimetry modules.
A barometer measures atmospheric pressure through liquid column displacement, aneroid cell deformation, or solid-state piezoresistive sensing, typically resolving pressure differentials to 0.1 hectopascal for meteorological-grade instruments. Digital barometers lead commercial volume due to microcontroller integration and data logging compatibility, while altimeter barometers capture premium margins in aviation safety systems where FAA TSO-C88b certification governs airworthiness. Capacitive MEMS technology displaces mechanical designs in portable applications, though mechanical aneroid mechanisms persist in marine environments where salt corrosion degrades electronic components.
EPA air quality monitoring protocols and FAA instrument flight rules shape domestic product specifications and calibration intervals for barometric altimeters. ISO 2533 standard atmospheric models and WMO instrument guidelines further constrain design parameters for international meteorological deployments. Stakeholders must weigh MEMS cost trajectories against mechanical reliability demands when configuring next-generation product portfolios.
Market Dynamics
MEMS piezoresistive sensing is compressing mechanical barometer supply chains as aviation and consumer drone manufacturers demand microcontroller-integrated pressure modules over discrete aneroid mechanisms.
Growth Catalysts
- Aviation Weather Station Modernization:Defense meteorological services are replacing legacy mechanical altimeters with solid-state pressure sensors to meet FAA TSO-C88b airworthiness mandates.
- EU Green Deal Monitoring Mandates:Environmental agencies across Germany, France, and the Netherlands are procuring precision barometric stations for climate tracking networks under tightened calibration standards.
- Consumer Drone Altimeter Modules:MEMS miniaturization enables sub-gram pressure sensors for recreational and commercial UAV navigation systems.
Market Restraints
- MEMS Foundry Concentration:Taiwan and South Korea dominate wafer fabrication for piezoresistive pressure dies, creating single-source vulnerability for sensor module assemblers.
- Marine Corrosion Limits:Salt degradation of electronic components forces commercial shipping and offshore platforms to retain mechanical aneroid barometers despite higher unit costs.
- Calibration Infrastructure Gaps:Developing meteorological services lack ISO 17025-accredited pressure laboratories, delaying digital instrument deployment.
Strategic Opportunities
- India Meteorological Department Expansion:The country's national weather service is tendering for 500+ automated weather stations requiring pressure sensors with local content requirements.
- Wearable Altimetry Convergence:Fitness device manufacturers are integrating barometric pressure with GPS and accelerometer data for elevation tracking.
- Outcome-Based Calibration Services:Instrument vendors are bundling sensor-as-a-service contracts with guaranteed accuracy maintenance for research institutions.
Industry Challenges
- FAA Certification Timeline Compression:Aviation safety system approvals for novel MEMS altimeter designs now require 18-24 months of flight testing.
- Legacy System Integration Friction:National meteorological networks running 1980s-era data protocols face middleware complexity when connecting digital barometers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barometer Market |
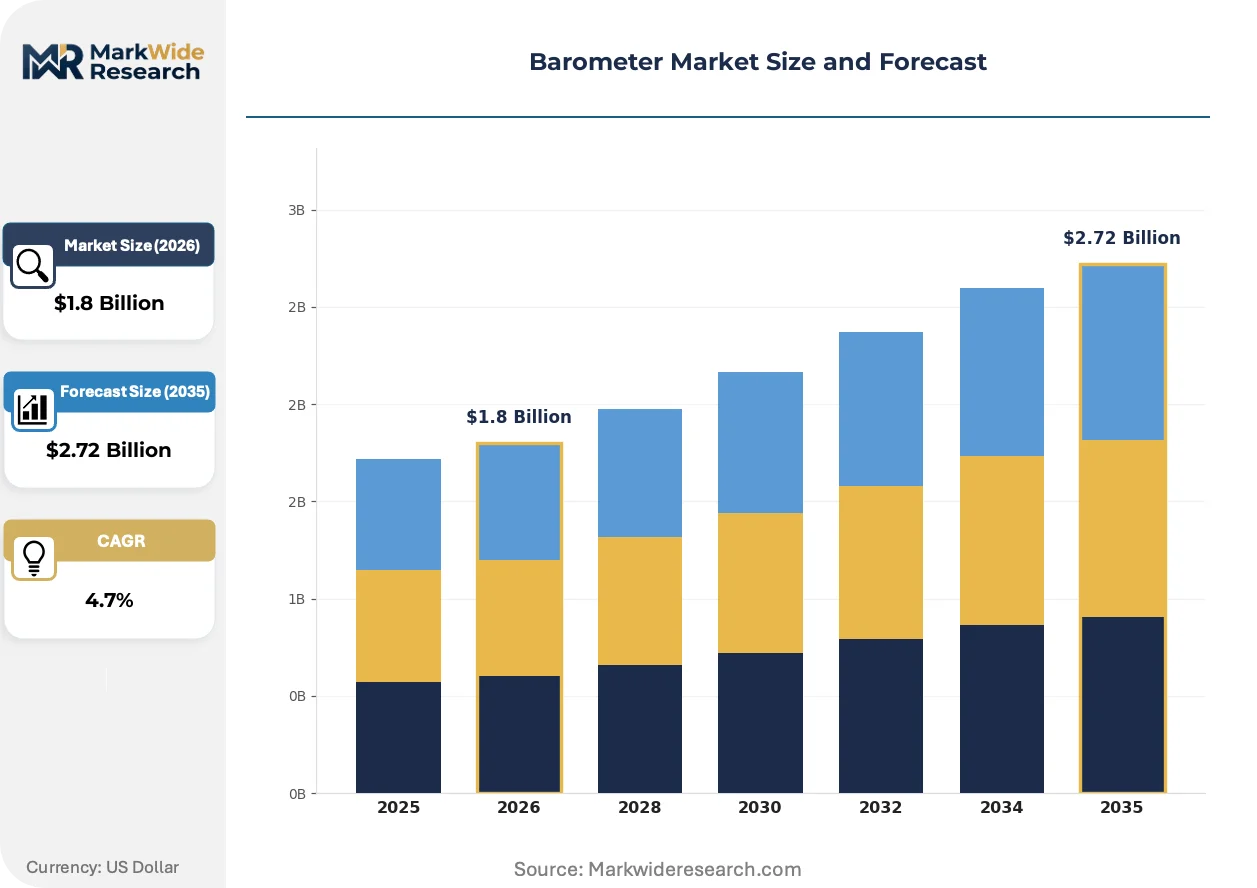
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Barometers, Analog Barometers, Wireless Barometers, Altimeter Barometers Measurement Range: High Pressure, Low Pressure, Medium Pressure, Absolute Pressure End User: Aerospace, Meteorology, Marine, Industrial Applications Technology: Capacitive, Piezoelectric, Microelectromechanical Systems, Mechanical |
| Companies Covered | Honeywell International Inc., Vaisala Oyj, BOSCH Sensortec GmbH, Dwyer Instruments Inc., Testo SE & Co. KGaA, Fortive Corporation, OMEGA Engineering Inc., WIKA Alexander Wiegand SE & Co. KG, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barometer Market Emerging Trajectories
Capacitive MEMS architectures are merging with traditional mechanical reliability engineering as vendors navigate divergent end-use requirements across aviation safety and consumer portability segments.
Silicon-on-insulator piezoresistive sensing is hybridizing with hermetic vacuum packaging to deliver 0.01 hectopascal resolution in temperature-cycled environments. Aviation altimeter manufacturers are qualifying these hybrid designs for FAA TSO-C88b certification timelines. The technology is hybridizing supply chains as MEMS foundries acquire legacy aneroid calibration expertise through specialist hiring.
REACH substance restrictions on mercury-containing instruments are accelerating phase-out of liquid-column barometers across European research institutions. National metrology institutes in Germany and the United Kingdom are reallocating capital toward solid-state primary standards. Laboratory-grade digital pressure transducers now dominate procurement for atmospheric physics departments.
Direct OEM contracting is displacing traditional instrumentation distributors in aviation and defense verticals. Tier-1 pressure sensor manufacturers are establishing captive application engineering teams at major airframe assembly sites. This channel compression is most visible in Germany's industrial instrumentation corridor where Honeywell and Vaisala maintain resident technical support.
Barometer Market Segmentation
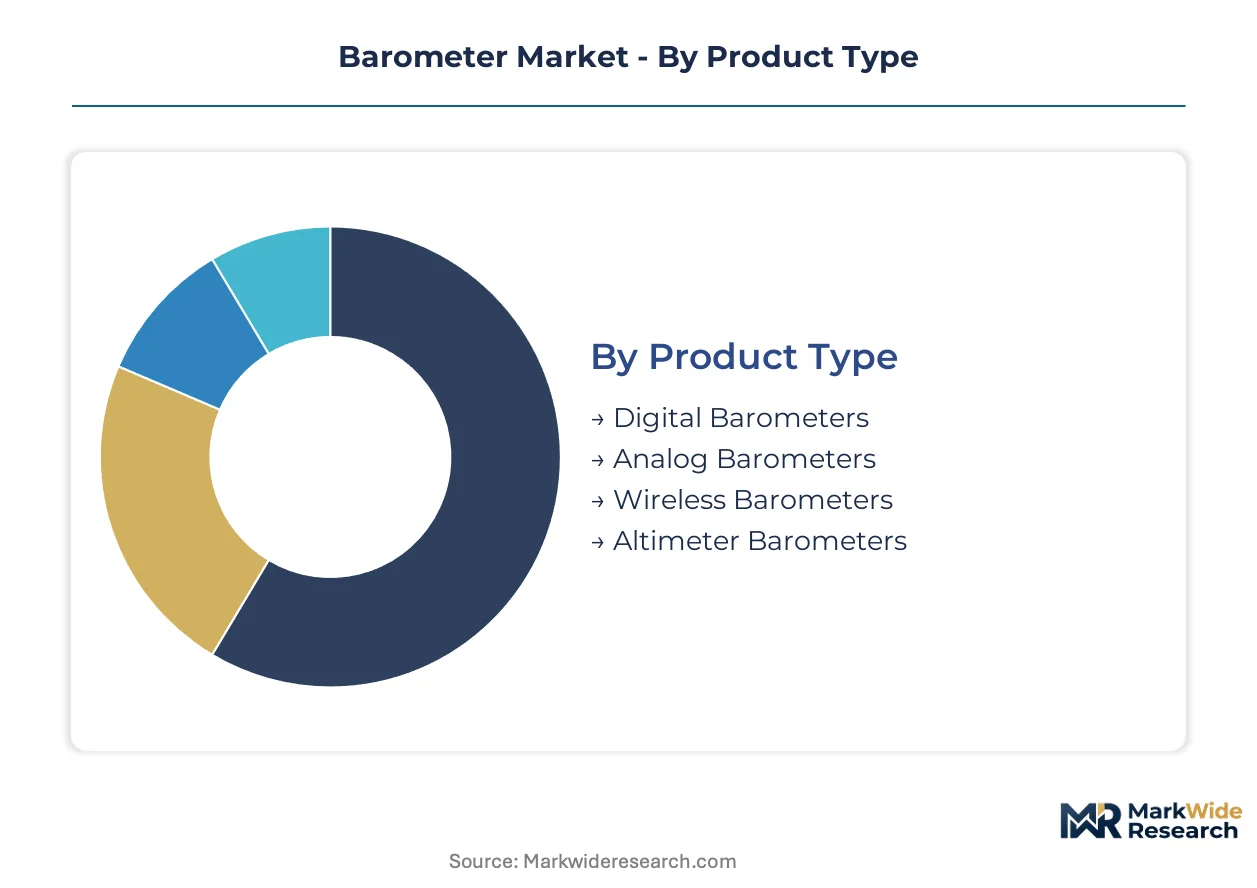
Barometer procurement cycles vary dramatically by application context, with consumer drone modules refreshing annually while aviation safety systems operate on decade-long certification timelines. Understanding these velocity differentials helps vendors align inventory, R&D pipelines, and service revenue models to specific segment economics.
Product Type:
Replacement frequency separates recreational instruments from certified aviation systems by an order of magnitude, creating distinct aftermarket architectures.
- Digital Barometers:Solid-state piezoresistive sensing with microcontroller integration enables 0.1 hectopascal resolution for automated weather stations. Germany's industrial instrumentation corridor concentrates procurement for climate monitoring networks under EU Green Deal mandates.
- Altimeter Barometers:FAA TSO-C88b-certified pressure sensors for aviation safety systems require 18-24 month flight testing protocols. Defense meteorological services sustain long-term supply agreements given airworthiness liability exposure.
- Analog Barometers:Mechanical aneroid mechanisms persist where electromagnetic interference or salt corrosion degrades electronic alternatives.
- Wireless Barometers:Bluetooth and LoRa-enabled units serve distributed agricultural and recreational monitoring with battery-operated autonomy.
Digital barometers anchor the volume base while altimeter barometers gain share at the steepest rate through aviation fleet modernization mandates.
Measurement Range:
Cost tier alignment follows precision requirements, with laboratory-grade absolute pressure transducers commanding multiples of industrial gauge sensors.
- Absolute Pressure:Hermetically sealed reference vacuum enables primary metrology applications. National institutes in Germany and the United Kingdom allocate capital toward solid-state standards as REACH restrictions phase out mercury instruments.
- High Pressure:Industrial process monitoring for compressed gas systems and hydraulic infrastructure requires robust diaphragm construction.
- Medium Pressure:General meteorological deployments balance resolution against calibration cost for regional weather services.
- Low Pressure:Vacuum system monitoring and altitude simulation chambers demand specialized sensor geometries.
Absolute pressure instruments command premium positioning while medium pressure sensors expand most quickly through automated weather station proliferation.
End User:
Customer type determines certification burden and contract structure, from outcome-based calibration services for research institutions to fixed-price component supply for OEM airframe assembly.
- Aerospace:FAA instrument flight rules and TSO-C88b certification govern altimeter specifications for commercial and defense aviation. Tier-1 manufacturers maintain resident application engineering at major assembly sites.
- Meteorology:WMO instrument guidelines and ISO 2533 atmospheric models constrain design parameters for national weather services. India Meteorological Department tenders for 500+ automated stations with local content requirements.
- Marine:Salt corrosion forces retention of mechanical aneroid designs despite higher unit costs and maintenance intervals.
- Industrial Applications:Process control and environmental monitoring drive demand for calibrated pressure transducers with ISO 17025 traceability.
Meteorology anchors the volume base while aerospace climbs the fastest through defense weather service modernization budgets.
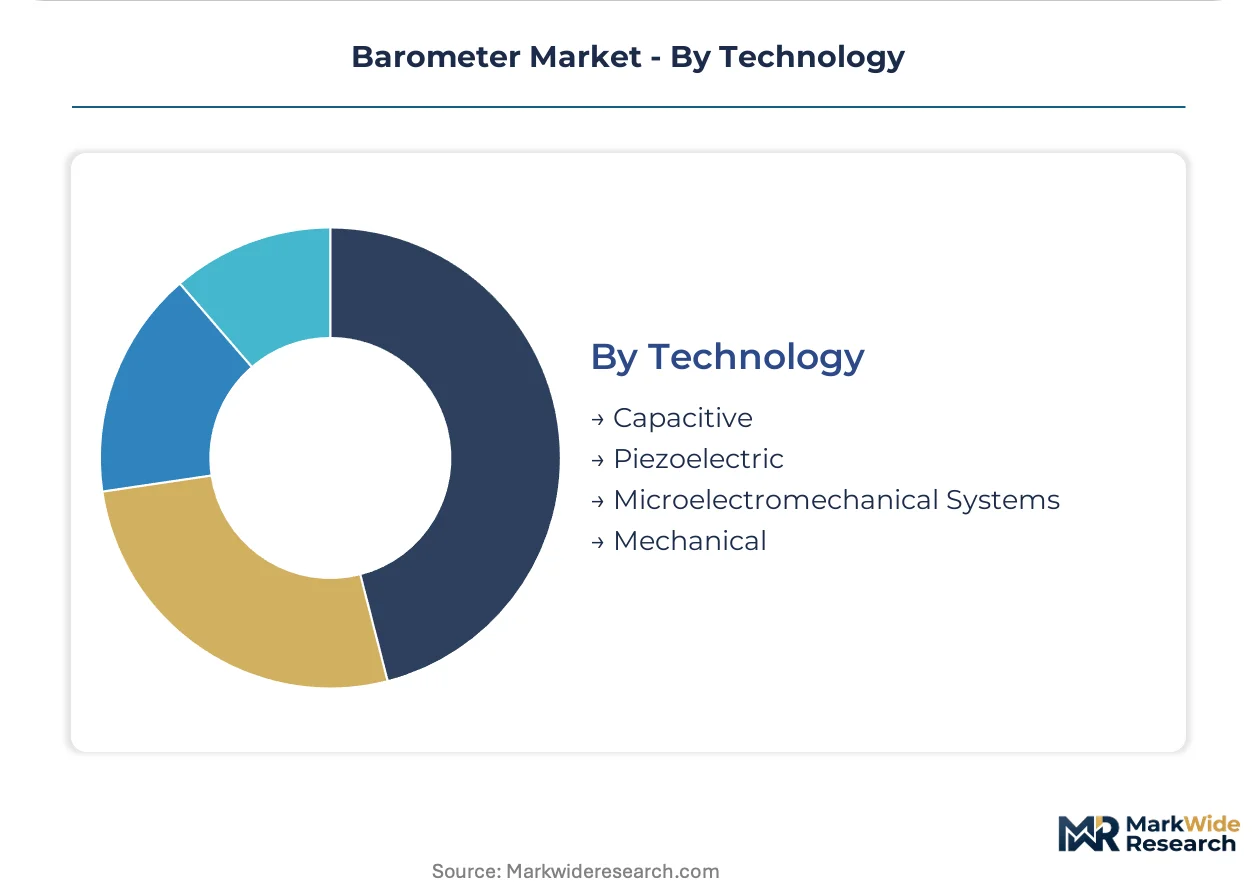
Technology:
Supply concentration creates vulnerability as MEMS foundry capacity concentrates in Taiwan and South Korea, while mechanical expertise remains geographically dispersed.
- Microelectromechanical Systems:Silicon-on-insulator piezoresistive sensing with hermetic vacuum packaging delivers 0.01 hectopascal resolution. Consumer drone manufacturers drive sub-gram miniaturization for altimetry modules.
- Mechanical:Aneroid cell deformation mechanisms persist in marine and backup aviation applications where electronic reliability remains unproven.
- Capacitive:MEMS architectures merging with reliability engineering target portable applications requiring low power consumption.
- Piezoelectric:Quartz crystal resonators serve niche high-frequency dynamic pressure measurement in wind tunnel and blast applications.
Mechanical technology retains installed base dominance while MEMS expands most quickly through consumer and aviation volume displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial instrumentation corridor commands premium pricing for calibration-grade pressure sensors, while India's meteorological procurement operates under strict local-content mandates that compress margins for foreign suppliers.
United States
Defense meteorological services drive solid-state altimeter procurement under FAA TSO-C88b certification timelines. EPA air quality monitoring protocols shape specifications for environmental pressure stations. Greater Boston's precision instrumentation cluster houses resident application engineering teams from major sensor manufacturers.
Germany
National metrology institutes reallocate capital toward solid-state primary standards as REACH substance restrictions phase out mercury barometers. EU Green Deal environmental monitoring mandates tighten calibration requirements for climate tracking networks. The industrial instrumentation corridor concentrates procurement for automated weather stations serving Central European meteorological infrastructure.
India
The national weather service tenders for 500-plus automated weather stations with domestic content requirements favoring local assembly. BIS standards govern instrument specifications for meteorological deployments. Maharashtra and Gujarat host emerging sensor module assembly operations targeting South Asian environmental monitoring demand.
Japan
METI industrial standards drive MEMS miniaturization for consumer drone altimetry modules with sub-gram weight targets. JIS certification requirements constrain design parameters for meteorological-grade instruments. The Kanto region's precision electronics manufacturing base supplies piezoresistive pressure dies to regional avionics integrators.
United Kingdom
National metrology laboratories redirect investment from liquid-column standards to digital pressure transducers under REACH compliance timelines. The country's meteorological service modernizes automated station networks with solid-state sensors. Southeast England's research instrumentation cluster concentrates climate monitoring procurement for North Atlantic atmospheric physics programs.
Barometer Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in MEMS wafer fabrication and mechanical aneroid calibration. The vendor base separates into three tiers: aerospace-certified system houses, industrial instrumentation conglomerates with meteorological agency relationships, and fabless MEMS designers serving consumer drone OEMs. Dominant competitive moves include backward integration into captive wafer fabrication and geographic co-location of application engineering at major airframe assembly sites.
Among diversified industrial technology conglomerates, Honeywell International Inc. and Fortive Corporation exemplify platform integrators with aerospace certification depth. Vaisala Oyj occupies a specialist position anchoring Nordic meteorological infrastructure through national agency partnerships. BOSCH Sensortec GmbH represents the component-tier archetype, supplying MEMS pressure modules for consumer and commercial UAV navigation systems.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Vaisala Oyj |
| BOSCH Sensortec GmbH |
| Dwyer Instruments Inc. |
| Testo SE & Co. KGaA |
| Fortive Corporation |
| OMEGA Engineering Inc. |
| WIKA Alexander Wiegand SE & Co. KG |
| NXP Semiconductors |
| Others |
Supply Flow & Price Mechanics
Taiwanese MEMS foundry overcapacity is compressing sensor module pricing while simultaneously incentivizing tier-1 vendors to secure captive wafer supply through long-term offtake agreements. This utilization dynamic creates divergent pricing postures between fabless designers facing margin erosion and integrated manufacturers extracting supply security premiums.
Pricing Analysis
Configured-to-order pricing for FAA TSO-C88b-certified altimeter modules commands substantial premiums over standard MEMS pressure sensor SKUs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and calibration traceability, with aviation safety systems showing minimal price sensitivity while consumer drone OEMs drive aggressive cost compression. Pricing pressure stems from MEMS commoditization in portable applications, though meteorological-grade instruments retain pricing power through ISO 17025-accredited calibration bundling.
Supply Chain Analysis
Export-control restrictions on advanced semiconductor manufacturing equipment constrain MEMS foundry expansion outside Taiwan and South Korea, concentrating piezoresistive pressure die supply. The supply chain draws from silicon wafer feedstock, hermetic packaging ceramics, and precision calibration equipment, with single-source vulnerability around 200mm MEMS fabrication capacity. Tariff exposure on Chinese-assembled sensor modules is reshaping final assembly location decisions. Distribution runs through direct OEM contracting that displaces traditional instrumentation wholesalers in aviation and defense verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
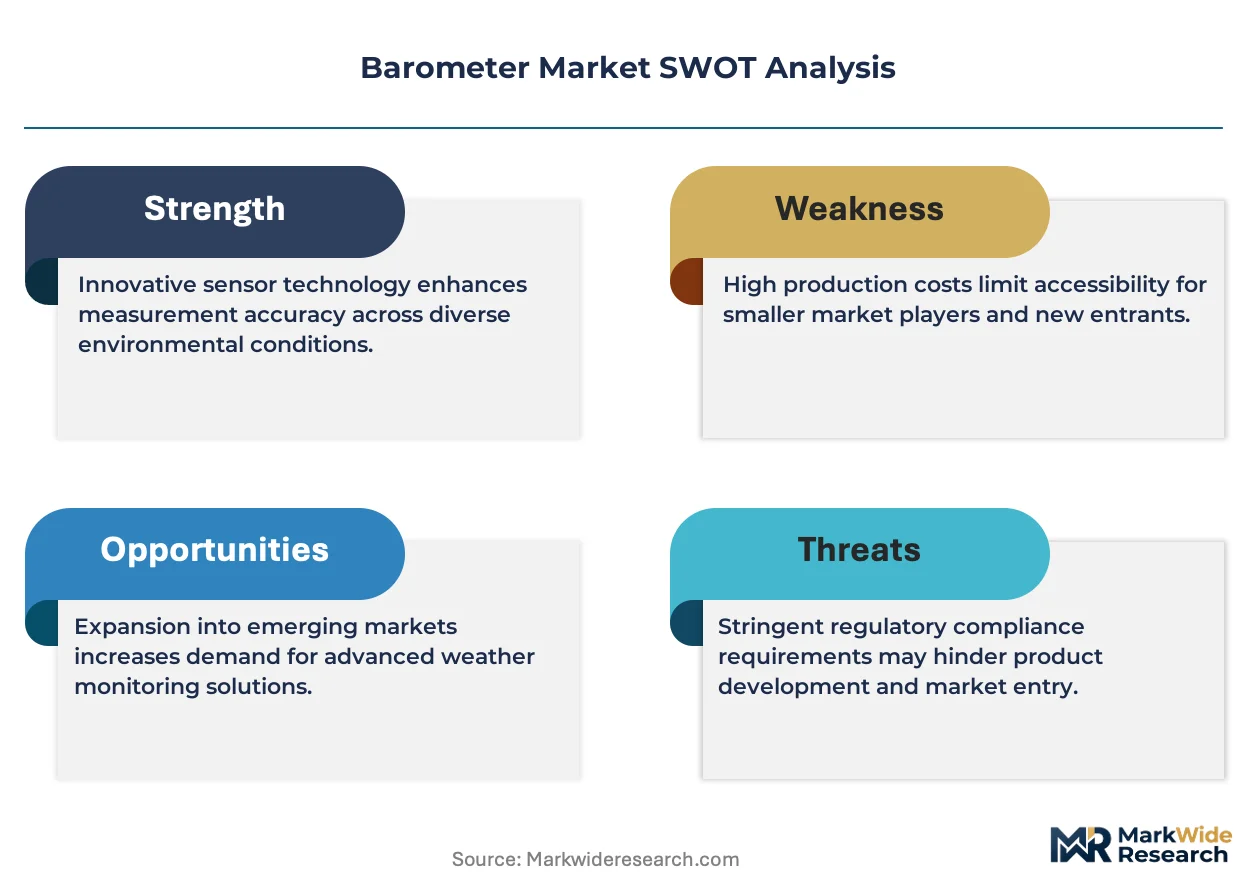
This market functions as a defensive-moat arena where regulatory entrenchment creates substantial switching costs for certified aviation and meteorological deployments. Incumbents benefit from decade-long approval timelines that freeze competitive dynamics.
For Market Incumbents: Harden certification depth as the primary defensive perimeter by accelerating FAA TSO-C88b qualification for next-generation MEMS architectures before emerging fabless competitors achieve airworthiness validation. Pursue backward integration into captive wafer fabrication to neutralize Taiwan and South Korea foundry concentration risk. Channel control through resident application engineering at German and US airframe assembly sites reinforces switching cost advantages against modular disruptors. For New Entrants and Emerging Players: Pursue white-space capture in India's meteorological procurement, where BIS-mandated local content requirements create protected demand corridors for domestic assembly operations. Target wearable altimetry convergence as the most penetrable segment, where fitness device OEMs prioritize rapid integration over legacy certification depth. A calibration-as-a-service go-to-market angle sidesteps capital-intensive certification barriers while capturing recurring revenue from research institutions. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among calibration-service bundlers serving national meteorological networks with multi-year accuracy maintenance contracts. Long-term viability across the projection horizon favors acquisition targets combining MEMS design capability with captive metrology laboratory assets. The signal to watch is India Meteorological Department tender awards, which indicate inflection in localized supply chain formation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Foundry Capacity | Captive wafer supply neutralizes Taiwan concentration risk for tier-1 sensor houses. |
| FAA TSO-C88b Certification Acceleration | Early qualification locks in defense meteorological service modernization procurement cycles. |
| Calibration-as-a-Service Platform Launch | Outcome-based contracts convert transactional sensor sales into recurring institutional revenue. |
| Resident Application Engineering Deployment | Co-location at German industrial corridor sites compresses OEM design-in timelines. |
| India Local Content Compliance Investment | Maharashtra and Gujarat assembly operations unlock IMD automated weather station tenders. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with MEMS design engineers, aviation certification specialists, meteorological procurement officers, and industrial instrumentation distributors; alongside secondary validation through FAA TSO certification databases, WMO instrument guidelines, EU Green Deal implementation reports, and customs trade data on pressure sensor module flows. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Forecast inputs considered technology displacement curves, regulatory compliance timeline shifts, and procurement cycle velocities by end-use segment. Modeled dimensions span product architecture, measurement precision tier, end-user certification burden, and geographic regulatory cluster. CAGRs were derived from segment-level unit economics and value-per-unit trajectories, with aviation safety system refresh rates and consumer drone shipment patterns serving as primary demand anchors.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or defense procurement budgets would shift the trajectory. Forecasts reflect documented assumptions regarding MEMS cost curves and certification timeline stability. Cross-checking against national meteorological service capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Digital Radiography Sensor Market
Sensors and Controls
Global Refrigeration Leak Detector Market
Sensors and Controls
GPS Tracking Device Market
Sensors and Controls
Smart Flow Meter Market
Sensors and Controls
North America Water Detection Sensors Market
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
Asia-Pacific Current Transducer Market
Sensors and Controls
Battery Monitor Market
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
Global Single Loop Controller Market
Sensors and Controls
Optical Chemical Sensor Market
Sensors and Controls
Asia Pacific Lidar Market
Sensors and Controls
Smart Thermometer Market
Sensors and Controls
France Digital Thermometer Market
Sensors and Controls
Digital Thermohygrometers Market
Sensors and Controls
Embedded Biometric Sensor Market